
 HSLA Steel Plate Market | 2026-2036
HSLA Steel Plate Market Size, Share, and Industry Trends Forecast 2026-2036
HSLA Steel Plate Market Insights
Advanced thermomechanical rolling is tilting HSLA plate production toward leaner alloy designs that retain strength at reduced carbon equivalents. ArcelorMittal leverages integrated R&D across European and North American melt shops to sustain leadership in ultra-high-strength grades above 700 MPa. POSCO anchors its position through captive supply of specialized slab feedstock optimized for offshore structural specifications.
HSLA steel plate denotes a class of low-alloy carbon steels engineered with micro-additions of niobium, vanadium, or titanium to achieve yield strengths between 275 MPa and 700 MPa while maintaining weldability and formability. Primary applications span load-bearing structures where weight reduction intersects with fatigue resistance, including ship hulls, crane booms, and pressure-boundary components. Hot rolled plate dominates volume shipments for heavy-gauge structural fabrication, where mill scale tolerance and as-rolled properties suffice for welded assemblies. Coated and galvanized variants command premium positioning in energy infrastructure exposed to corrosive offshore atmospheres, with margin pools concentrating in specialized zinc-aluminum-magnesium formulations.
Classification societies including Lloyd's Register, DNV, and the American Bureau of Shipping enforce notch-toughness and through-thickness ductility standards that filter mill qualification and lock out non-certified suppliers. The EU Green Deal's embodied-carbon benchmarking and the US Inflation Reduction Act's domestic content incentives reshape procurement criteria for infrastructure-grade plate. Stakeholders must monitor evolving alloy-recycling regulations and classification-society updates on hydrogen-embrittlement testing protocols for plates destined for emerging energy applications.
Market Dynamics
The EU Green Deal's embodied-carbon benchmarking is forcing European mills to reformulate HSLA chemistries for electric-arc-furnace compatibility while maintaining classification-society notch-toughness certifications.
Growth Catalysts
- IMO decarbonization mandates:Shipbuilders in South Korea and Japan specify 355+ MPa yield strength plates to reduce hull weight and meet EEDI Phase 3 efficiency targets for new container vessel programs.
- US Inflation Reduction Act domestic content incentives:Infrastructure procurement now prioritizes domestically melted and rolled plate for bridge and energy projects, redirecting mill capacity toward certified structural grades.
- Advanced thermomechanical rolling:Leaner niobium-vanadium micro-alloying achieves 700+ MPa strength at reduced carbon equivalents, cutting welding preheat requirements and fabrication cycle times.
Market Restraints
- Scrap quality volatility:Electric-arc-furnace operations depend on consistent residual element control in shredded automotive scrap, with copper and tin contamination degrading HSLA toughness properties.
- Classification-society qualification lock-in:Lloyd's Register, DNV, and ABS certification timelines of 18-24 months filter out non-integrated mills lacking in-house metallurgical testing capacity.
- Aluminum-lithium substitution in aerospace:Airframe manufacturers above 80-meter wingspans increasingly specify Al-Li alloys for weight-critical spar applications, compressing addressable plate demand in aviation.
Strategic Opportunities
- India's National Steel Policy capacity expansion:Greenfield integrated mills in Odisha and Jharkhand target 300 MT annual crude steel output by 2030, with dedicated HSLA plate lines for domestic infrastructure and export positioning.
- Hydrogen storage pressure vessel applications:700-bar Type III and IV composite-wrapped vessels require ultra-high-strength backing plates with hydrogen-embrittlement resistance protocols under development by ISO/TC 197.
- Direct-mill procurement platforms:Digital tendering systems connecting Ulsan and Nagasaki shipyards to qualified melt shops are compressing distributor margins and capturing 15-20% cost savings on long-term charter contracts.
Industry Challenges
- Weld procedure qualification bottlenecks:Each new HSLA grade requires requalification of WPS/PQR documentation under ASME Section IX and EN ISO 15614-1, extending project startup timelines by 4-6 months.
- Through-thickness ductility testing capacity:Z-direction tensile and reduction-of-area specimens demand specialized 500-tonne testing machines concentrated at a handful of European and Japanese laboratory facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | HSLA Steel Plate Market |
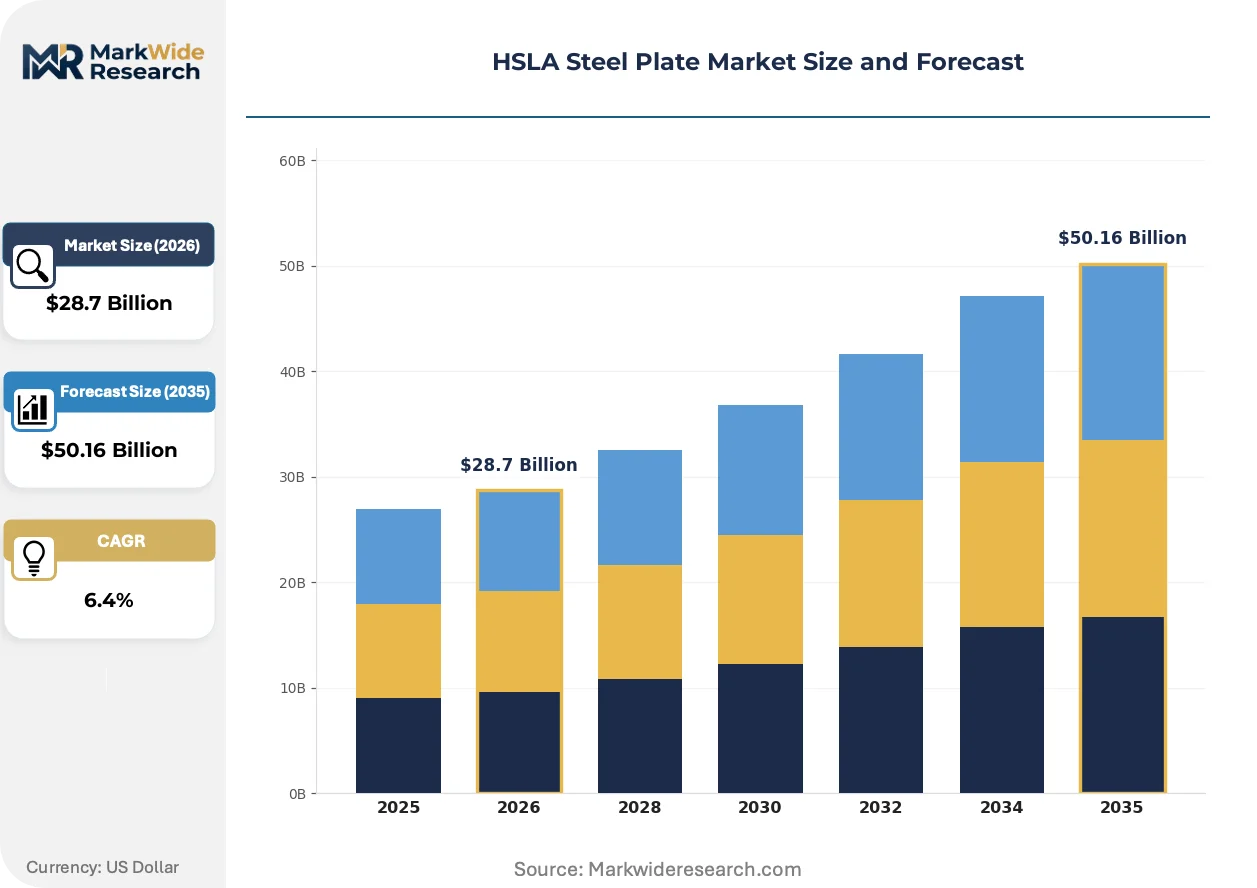
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $50.16 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hot Rolled, Cold Rolled, Coated, Galvanized, Annealed Application: Shipbuilding, Heavy Machinery, Structural Fabrication, Pressure Vessels, Petrochemical Equipment Thickness Range: 1-5 mm, 6-10 mm, 11-20 mm, 21-40 mm, Above 40 mm End User Industry: Construction, Defense Manufacturing, Energy Infrastructure, Transportation Equipment, Mining |
| Companies Covered | ArcelorMittal, POSCO, Nippon Steel Corporation, SSAB AB, Nucor Corporation, Tata Steel, thyssenkrupp AG, JFE Steel Corporation, Baosteel Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
HSLA Steel Plate Market Trends and Innovations
Thermomechanical processing advances and regulatory carbon accounting are converging to redefine alloy design priorities, with mills racing to decouple strength from carbon content while maintaining weldability certifications.
High-strength low-alloy plate production is migrating from conventional normalized rolling to direct-quench and temper (DQ-T) protocols that achieve equivalent mechanical properties at 30-40% lower carbon equivalents. Korean shipyards in Ulsan have adopted DQ-T 460 MPa grades for Panamax bulk carrier decks, eliminating post-weld heat treatment and compressing hull block assembly schedules by two weeks per vessel.
The EU Green Deal's Carbon Border Adjustment Mechanism is reshaping import competitiveness for non-European plate suppliers. Mills in Turkey and India face embedded-emissions reporting requirements from 2026, forcing investment in scrap-based electric-arc-furnace routes or green hydrogen direct-reduction pilots to maintain access to German and Dutch infrastructure tenders.
Shipyard procurement departments are consolidating supplier lists around mills with integrated slab casting and plate rolling capabilities. Buyers in Nagasaki now require single-source traceability from liquid steel to finished plate, disqualifying merchant slab processors and compressing qualified vendor pools to six integrated producers across East Asia and Europe.
HSLA Steel Plate Market Segmentation
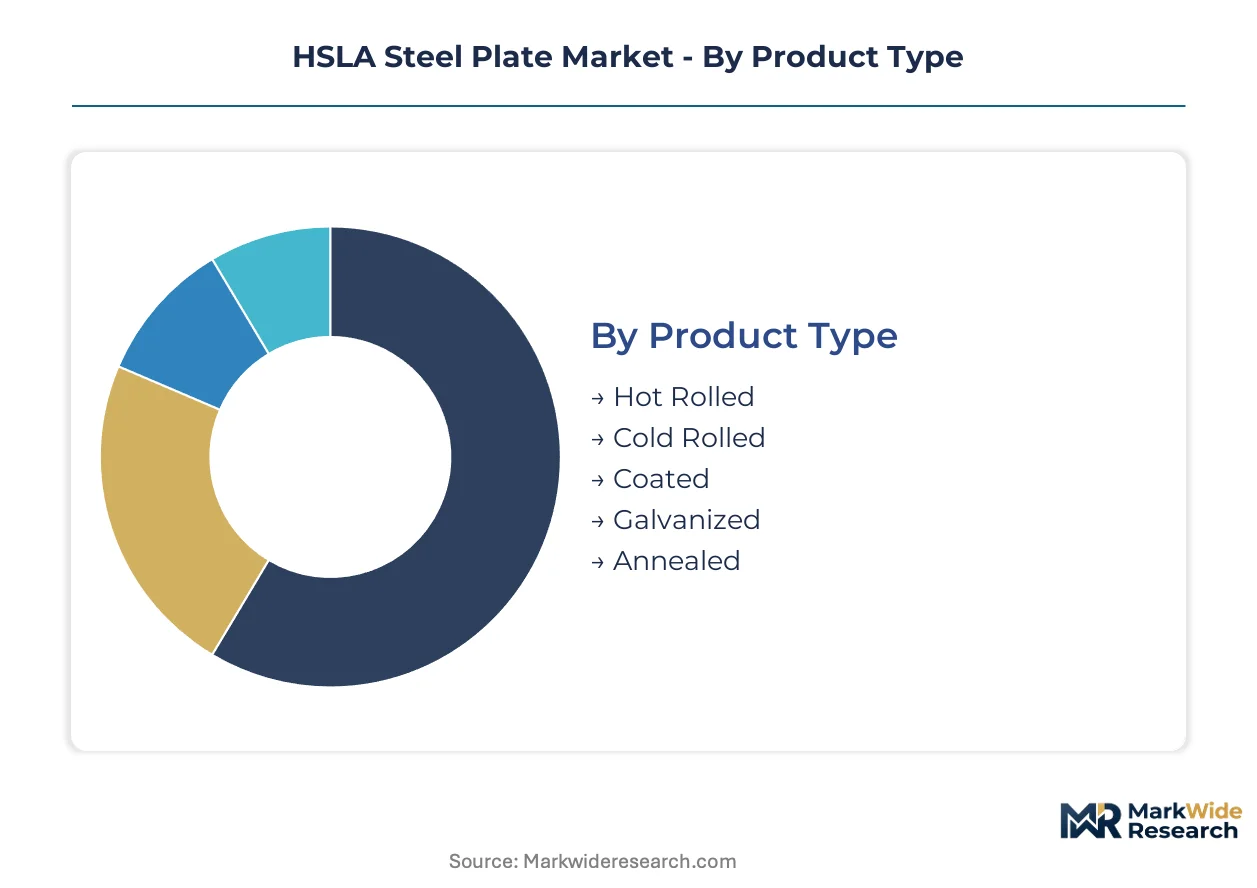
HSLA steel plate demand fragments across fabrication processes, end-use specifications, and dimensional requirements. Each segment carries distinct metallurgical constraints, certification burdens, and margin structures that shape procurement behavior.
Product Type:
After-sales service intensity varies sharply across product categories, with coated and galvanized plates demanding technical support for corrosion warranty claims and application engineering.
- Hot Rolled:As-rolled plates with mill scale tolerance dominate heavy-gauge structural fabrication. Shipyards in Ulsan specify hot rolled 355+ MPa grades for Panamax bulk carrier hull blocks, leveraging direct-quench protocols to eliminate post-weld heat treatment.
- Cold Rolled:Tighter dimensional tolerances and improved surface finish suit precision components. Japanese crane manufacturers specify cold rolled HSLA for telescopic boom sections where fatigue resistance intersects with weight reduction targets.
- Coated:Zinc-aluminum-magnesium formulations command premium positioning in offshore energy infrastructure exposed to corrosive North Sea atmospheres.
- Galvanized:Hot-dip zinc coatings extend service life for bridge girders and transmission towers in coastal environments.
- Annealed:Softened microstructures improve formability for complex press-brake fabrication in mining equipment manufacturing.
By volume, Hot Rolled leads. By growth pace, Coated is ahead.
Application:
Application segmentation maps directly to qualification barriers, with shipbuilding and pressure vessels imposing the most demanding certification timelines.
- Shipbuilding:Classification societies enforce notch-toughness and through-thickness ductility standards that filter mill qualification. South Korean yards specify plates above 355 MPa yield strength for new container vessel programs under IMO EEDI Phase 3 mandates.
- Heavy Machinery:Crane booms and excavator arms require high strength-to-weight ratios with weldability for field repair. German equipment manufacturers source 700+ MPa grades from ArcelorMittal's European melt shops.
- Structural Fabrication:Bridge and building frameworks consume standardized grades with less stringent Z-direction testing requirements.
- Pressure Vessels:ASME Section VIII and EN 13445 compliance drives procurement toward mills with integrated metallurgical testing capacity.
- Petrochemical Equipment:Sour service resistance specifications limit supplier pools for hydrogen sulfide-exposed reactor vessels.
Shipbuilding commands the largest revenue pool. Pressure Vessels is climbing the fastest on hydrogen storage demand.
Thickness Range:
Thickness determines rolling mill configuration requirements and shapes regional supply concentration.
- 21-40 mm:Heavy plate for ship hulls and offshore jackets demands specialized 5-meter wide rolling mills concentrated at integrated producers in Japan, South Korea, and Germany.
- Above 40 mm:Ultra-heavy gauges for pressure vessel shells and mining truck bodies require ingot casting or thick slab capabilities that lock out mini-mill competition.
- 1-5 mm:Thin gauges serve automotive and light structural applications with tighter flatness tolerances.
- 6-10 mm:Medium plate bridges construction and general fabrication with broader supplier availability.
- 11-20 mm:Standard structural thicknesses face commodity pricing pressure from Turkish and Indian export mills.
The 21-40 mm band generates the highest margin per tonne. Above 40 mm is gaining share fastest on energy infrastructure investment.
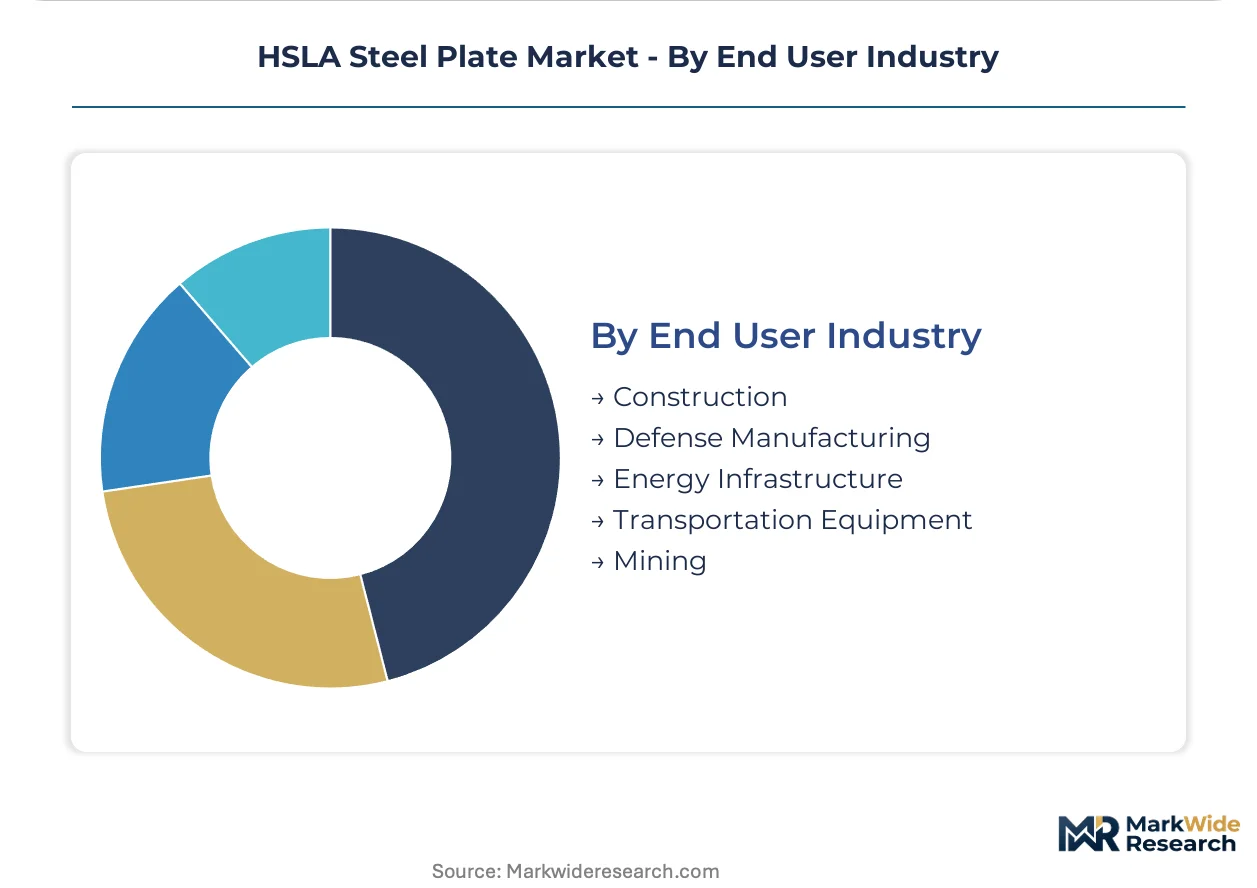
End User Industry:
End-use concentration varies by regional industrial structure, with energy infrastructure and defense manufacturing showing the most inelastic demand.
- Energy Infrastructure:Offshore wind transition pieces and hydrogen storage vessels require ultra-high-strength grades with emerging hydrogen-embrittlement testing protocols under ISO/TC 197 development.
- Defense Manufacturing:Naval vessel and armored vehicle programs impose domestic sourcing mandates that override cost optimization.
- Construction:Bridge and building frameworks consume standardized grades with price-sensitive procurement through distributor channels.
- Transportation Equipment:Rail car and truck chassis specifications balance weight reduction against fatigue life requirements.
- Mining:Haul truck bodies and shovel booms prioritize abrasion resistance through through-hardened alloy overlays on HSLA substrates.
Construction absorbs the greatest tonnage. Energy Infrastructure shows the steepest expansion trajectory on offshore wind and hydrogen storage investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shipyard procurement departments in South Korea and Japan anchor buyer concentration for high-yield grades, while European mills adapt formulations to EU Green Deal carbon benchmarks. Classification-society certification requirements filter supplier access across all major demand centers.
South Korea
Hyundai Heavy Industries and Samsung Heavy Industries drive specification of 355+ MPa yield strength plates for container vessel newbuilds under IMO EEDI Phase 3 mandates. The Ministry of Trade, Industry and Energy enforces domestic content thresholds for naval and commercial shipbuilding. Ulsan shipyard clusters source directly from POSCO's integrated Pohang works, eliminating merchant slab processors from qualified vendor lists.
Japan
Imabari Shipbuilding and Japan Marine United specify ultra-high-strength grades above 460 MPa for Panamax bulk carrier lightweight hull designs. METI's Green Innovation Fund subsidizes electric-arc-furnace conversion projects at coastal plate mills. Nagasaki yard complexes now require single-source traceability from liquid steel to finished plate, compressing qualified suppliers to integrated producers with captive slab casting.
United States
Nucor Corporation and domestic integrated mills capture infrastructure procurement redirected by Inflation Reduction Act domestic content incentives for bridge and energy projects. The Department of Transportation enforces Buy America provisions for federally funded steel fabrication. Gulf Coast plate consumers in Houston and New Orleans face extended lead times as mills prioritize certified structural grades over commodity shipments.
Germany
Thyssenkrupp Steel and Salzgitter AG reformulate HSLA chemistries for electric-arc-furnace compatibility while maintaining DNV and Lloyd's Register notch-toughness certifications. The EU Green Deal's Carbon Border Adjustment Mechanism from 2026 pressures embedded-emissions reporting for imported plate. Duisburg-Ruhrort port clusters serve as distribution hubs for offshore wind transition pieces requiring through-thickness ductility testing.
India
Tata Steel and JSW Steel expand dedicated HSLA plate lines at greenfield integrated mills in Odisha and Jharkhand targeting domestic infrastructure and export positioning. The Ministry of Steel's National Steel Policy mandates 300 MT annual crude steel output by 2030 with quality-grade emphasis. Visakhapatnam and Hazira port facilities concentrate plate finishing capacity for Southeast Asian shipyard contracts.
HSLA Steel Plate Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a market structure defined by integrated mill concentration and classification-society qualification barriers. The vendor base separates into three tiers: global integrated producers with captive mining and slab casting, regional merchant plate rollers dependent on external feedstock, and specialty alloy developers serving pressure-vessel and offshore niches. Dominant competitive moves include backward integration into specialized slab feedstock and strategic partnerships with shipyard procurement platforms.
Among East Asian integrated producers, POSCO and Nippon Steel Corporation occupy positions defined by captive supply chains and direct mill-to-yard relationships. ArcelorMittal anchors the European-North American axis through R&D integration across multiple melt shops. These three exemplify the channel-control archetype where qualification maintenance and carbon-transition investment determine competitive durability.
| Leading Market Players |
|---|
| ArcelorMittal |
| POSCO |
| Nippon Steel Corporation |
| SSAB AB |
| Nucor Corporation |
| Tata Steel |
| thyssenkrupp AG |
| JFE Steel Corporation |
| Baosteel Group |
| Others |
Pricing and Supply Chain Analysis
Freight corridors connecting Pohang to Ulsan and Nagasaki transmit slab-to-plate cost structures that amplify pricing power at integrated Korean and Japanese mills while compressing margins for merchant feedstock processors serving European fabricators.
Pricing Analysis
Cost-plus contracts with quarterly iron ore and scrap indexation dominate long-term charter agreements between East Asian shipyards and integrated mills. Price differentiation rests on classification-society certification grade and volume commitment scale, with Lloyd's Register-qualified 460 MPa grades commanding substantial premiums over standard structural specifications. Cost compression in commodity-grade plate intensifies as Turkish and Indian export mills expand capacity. Construction distributors exhibit the highest price sensitivity, while defense procurement officers accept premium positioning for domestic-melted certified grades.
Supply Chain Analysis
Export-control restrictions on advanced thermomechanical rolling technology limit equipment transfers to non-integrated producers, reinforcing supply concentration in South Korea, Japan, and Germany. Raw material flows draw from Brazilian iron ore fines, Australian metallurgical coal, and ferroalloy concentrates from South Africa and Kazakhstan. Single-source vulnerability concentrates at specialized 500-tonne Z-direction testing facilities in Duisburg and Tokyo. Distribution runs through direct-mill procurement platforms connecting Ulsan and Nagasaki shipyards to qualified melt shops, bypassing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The HSLA steel plate market sits in early-cycle expansion as hydrogen storage vessel specifications under ISO/TC 197 development create new demand pools for ultra-high-strength grades with hydrogen-embrittlement resistance protocols.
For Market Incumbents: Harden qualification moats by accelerating backward integration into specialized niobium-vanadium ferroalloy supply and expanding in-house 500-tonne through-thickness testing capacity before merchant laboratory bottlenecks worsen. Aluminum-lithium substitution in aerospace spar applications threatens adjacent plate demand, making shipyard direct-mill platform partnerships the priority lever for volume defense. For New Entrants and Emerging Players: India's greenfield integrated mill corridors in Odisha and Jharkhand offer the most penetrable white-space for domestic infrastructure-grade plate production targeting National Steel Policy capacity mandates. Secondary opportunities concentrate in hydrogen storage pressure vessel backing plates where ISO/TC 197 protocols remain under development and qualification timelines have not yet locked out new suppliers. A joint-venture route with established ferroalloy traders accelerates metallurgical credibility without captive mining investments. For Investors and Strategic Acquirers: Regional merchant plate rollers with established classification-society relationships but lacking captive slab casting represent the most attractive acquisition archetype for consolidation plays. Long-term viability hinges on electric-arc-furnace transition execution ahead of EU Carbon Border Adjustment Mechanism compliance deadlines. The signal to watch is shipyard procurement consolidation around single-source traceability requirements, which will force distressed divestitures from non-integrated processors unable to upgrade.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ferroalloy Supply | Captive niobium-vanadium sourcing insulates ArcelorMittal and POSCO from spot market volatility. |
| Direct-Mill Procurement Platform Deployment | Digital tendering systems connecting Ulsan shipyards to qualified melt shops capture 15-20% cost savings. |
| Electric-Arc-Furnace Conversion Investment | Salzgitter AG and Thyssenkrupp Steel reformulate chemistries to meet EU Green Deal carbon benchmarks. |
| Hydrogen-Embrittlement Testing Protocol Development | ISO/TC 197 standards for 700-bar vessel backing plates unlock new premium grade demand pools. |
| Classification-Society Qualification Expansion | DNV and Lloyd's Register certifications filter mill access and lock out non-integrated competitors. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with shipyard procurement directors, plate mill metallurgical engineers, classification-society surveyors, and offshore wind EPC contractors. Secondary validation drew from customs trade databases, SEC filings of listed steel producers, Lloyd's Register and DNV certification registries, and EU Carbon Border Adjustment Mechanism draft implementing acts. Bottom-up volume estimates from individual mill capacity announcements were triangulated against top-down demand projections from shipbuilding orderbook analysis.
Calibration against historical price spreads between commodity and certified grades anchored the analytical framework across the projection horizon. Segmentation dimensions modeled included product type, yield strength tier, thickness range, end-use application, and regional regulatory cluster. CAGRs were derived from regression analysis of capacity utilization rates against shipbuilding contract awards and infrastructure stimulus disbursements. Forecast inputs incorporated IMO EEDI Phase 3 compliance timelines and National Steel Policy capacity targets.
Macroeconomic conditions sit as an overlay; deviation in Chinese steel export policy or Baltic Dry Index volatility would shift the trajectory. Forecasts reflect documented assumptions on scrap quality consistency and classification-society qualification timelines. Material shifts in EU Carbon Border Adjustment Mechanism implementation scope or hydrogen storage vessel standard finalization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
High Purity Base Metals Market
Metals
Japan Aluminium Powder Market
Metals
Ferro Aluminum Market
Metals
Weathering Steel Market
Metals
Global Precious Metal Market
Metals
China Neodymium Iron Boron Magnet Market
Metals
Barium Market
Metals
Global Aluminum Market
Metals
GCC Metal Forging Market
Metals
Aluminum Ingots Market
Metals
Zirconium Market
Metals
India Metal Fabrication Market
Metals
Prebaked Anodes for Aluminum Market
Metals
Tantalum and Niobium Material Market
Metals
Recycled Metal Market
Metals
Europe Aluminium Powder Market