
 Metal Finishing Market | 2026-2036
Metal Finishing Market Size, Share, and Industry Trends Forecast 2026-2036
Metal Finishing Market Outlook
Surface treatment as a subscription-linked performance service is restructuring how finishing contracts get priced and renewed. Atotech Deutschland GmbH leverages its captive chemistry supply to anchor long-term plating line management agreements with tier-one automotive suppliers. PPG Industries competes through powder coating technology leadership in architectural and appliance segments. Quaker Houghton sustains its position in metalworking fluids that integrate with downstream finishing operations.
Metal finishing encompasses chemical and mechanical processes that modify surface properties—hardness, corrosion resistance, electrical conductivity, or aesthetic appearance—through controlled deposition, conversion, or coating layers typically measured in microns. Electroplating deposits metallic coatings via electrolytic reduction, while anodizing builds oxide layers on aluminum substrates for wear protection and dye adhesion. Electroplating remains the largest process category by installed base, though powder coating is displacing liquid finishes in automotive and appliance applications due to near-zero volatile organic compound emissions. Aluminum dominates material throughput in aerospace and electronics applications where weight reduction intersects with thermal management requirements.
EPA effluent guidelines and OSHA hexavalent chromium exposure limits shape process chemistry selection and capital equipment decisions across U.S. finishing operations. REACH authorization requirements in Europe are eliminating certain chromate conversion coatings, forcing substrate-level reformulation and alternative pretreatment adoption. China's MEE enforcement of wastewater discharge standards is consolidating fragmented electroplating shops around centralized treatment infrastructure. Stakeholders must monitor how dual regulatory pressure—chemical restriction plus carbon accounting—reshapes process economics and geographic sourcing decisions.
Market Dynamics
REACH authorization requirements and China's MEE wastewater enforcement are consolidating electroplating capacity around centralized treatment infrastructure, eliminating fragmented job-shop operations while concentrating volume among integrated suppliers with captive chemistry and effluent handling capabilities.
Growth Catalysts
- Electric drivetrain housing demand:Automotive OEMs are expanding surface treatment procurement for aluminum and magnesium housings requiring corrosion-resistant coatings with thermal conductivity specifications.
- REACH hexavalent chromium restrictions:European supply chains are accelerating substitution toward trivalent chrome and electroless nickel processes, creating equipment refresh cycles across plating operations.
- China eastern manufacturing corridor concentration:Ningbo and Suzhou clusters are serving as export finishing hubs for precision electronics and aerospace components, capturing scale efficiencies in high-mix, low-volume production.
Market Restraints
- Specialty chemical input volatility:Nickel sulfate and chromium compounds face price swings tied to mining output and energy-intensive refining economics, compressing job-shop margins.
- European plating capacity consolidation:REACH compliance costs and effluent treatment capital requirements are forcing small- and mid-scale operators to exit, reducing supplier diversity for tier-two manufacturers.
- Powder coating substitution ceiling:Liquid finishes retain adhesion advantages on complex geometries and internal passages, limiting complete displacement despite VOC advantages.
Strategic Opportunities
- India precision component manufacturing:BIS standards adoption and PLI scheme incentives for electronics and automotive are creating demand for export-grade finishing capacity in Pune and Chennai corridors.
- Surface treatment-as-a-service models:Chemistry suppliers are anchoring long-term plating line management agreements with performance-linked pricing, capturing recurring revenue beyond commodity chemical sales.
- Dual carbon goals alignment:China's MEE enforcement and provincial carbon intensity targets are favoring finishing operations with renewable energy procurement and closed-loop water systems.
Industry Challenges
- Hexavalent chromium remediation expertise:OSHA exposure limit compliance and worker safety protocols require specialized industrial hygiene capabilities that fragmented operators struggle to staff.
- Legacy equipment integration:Trivalent chrome and electroless nickel process conversions demand line reconfiguration, tank replacement, and power supply upgrades with extended commissioning timelines.
- Cross-border chemistry certification:Formulation approvals for aerospace and medical applications require synchronized documentation across EASA, FAA, and CAAC jurisdictions, delaying market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metal Finishing Market |
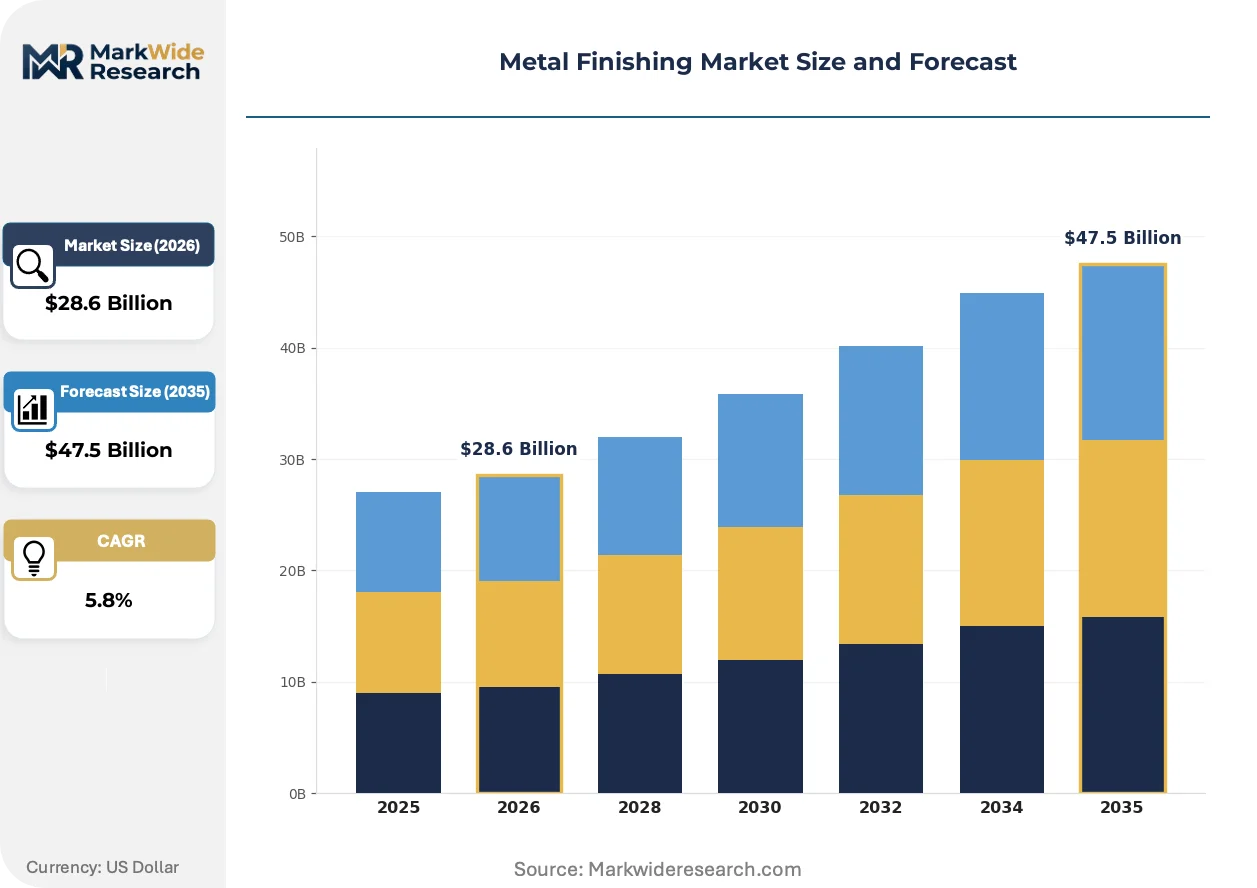
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $47.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Process Type: Electroplating, Galvanizing, Anodizing, Powder Coating Material: Aluminum, Steel, Copper, Zinc Application: Aerospace, Automotive, Electronics, Medical Devices Technology: Wet Processing, Dry Processing, Electroless Plating, Surface Treatment |
| Companies Covered | Honeywell International Inc., Atotech Deutschland GmbH, DuPont de Nemours, Inc., Henkel AG & Co. KGaA, BASF SE, PPG Industries, Inc., Quaker Houghton, OC Oerlikon Management AG, Axalta Coating Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metal Finishing Market Strategic Shifts
Process electrification and chemistry substitution are compressing the technology lifecycle for conventional plating lines, while regulatory pressure on hazardous substances is accelerating capital deployment toward closed-loop systems and alternative surface modification methods.
Pulse-reverse electroplating is electrifying deposition control for high-aspect-ratio through-holes and wafer-level packaging in semiconductor substrates. Advanced packaging manufacturers in Taiwan and South Korea are adopting these power supply architectures to achieve uniform thickness distribution below five microns. The technology is electrifying competition between captive semiconductor finishing operations and specialized outsourced suppliers.
REACH authorization sunset dates for chromate conversion coatings are forcing substrate-level reformulation across European aerospace and defense supply chains. Manufacturers are qualifying trivalent passivation layers and thin-film ceramic coatings for aluminum alloys previously protected by hexavalent chemistries. German and French tier-one suppliers are absorbing the longest qualification timelines due to OEM specification conservatism.
Subscription-linked performance contracts are restructuring how automotive and appliance OEMs source finishing operations. Buyers are shifting from chemical procurement to surface-quality guarantees with chemistry, equipment, and technical service bundled under unit-price or throughput-based arrangements. This model is most visible in Germany and China's eastern provinces, where integrated suppliers with captive formulation capabilities anchor multi-year agreements.
Metal Finishing Market Segmentation
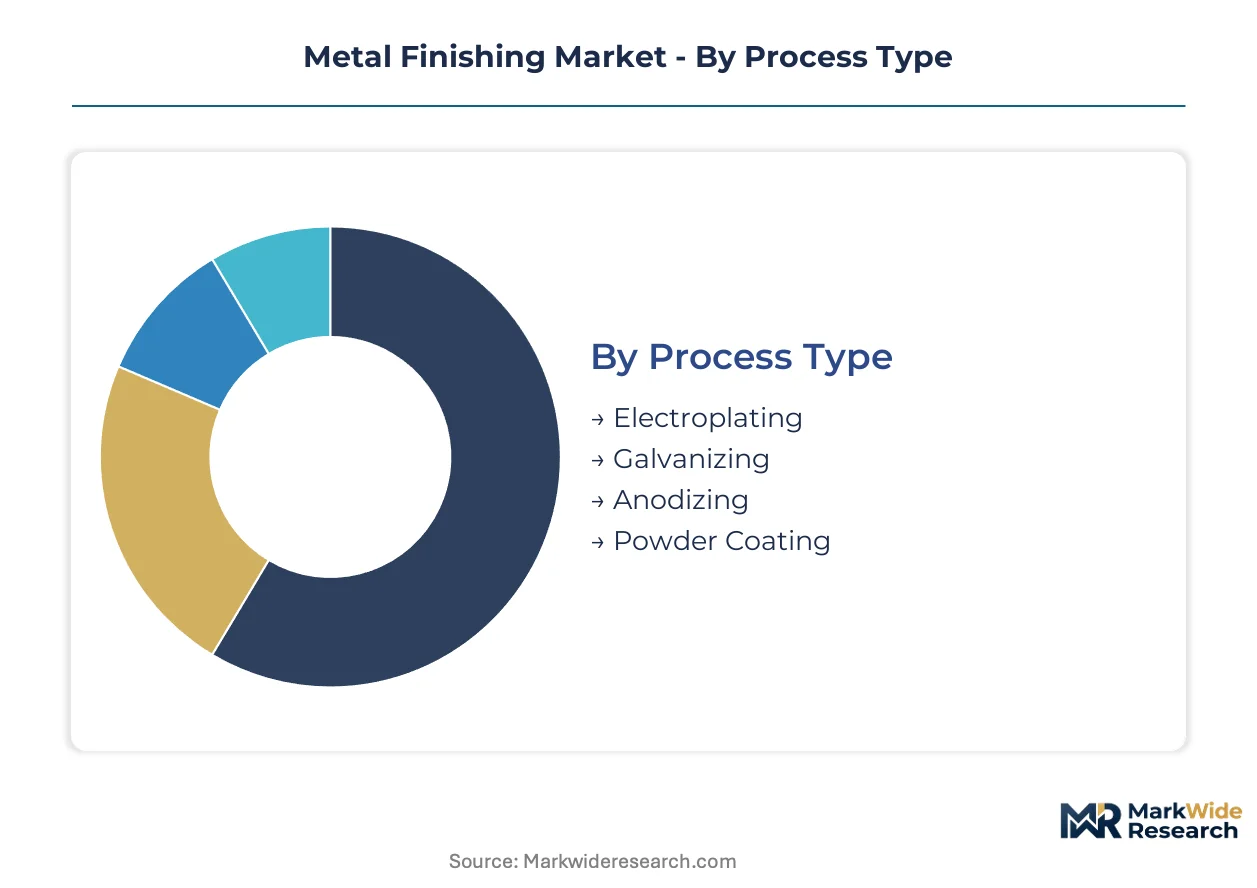
Process chemistry selection and substrate compatibility dictate equipment configuration and regulatory compliance pathways across metal finishing operations. Segmentation reveals how automotive electrification and REACH chemical restrictions are reallocating volume across traditional plating categories and emerging surface modification technologies.
Process Type:
Electroplating commands the largest installed base by throughput volume, while powder coating captures premium pricing in emission-sensitive applications.
- Electroplating:Electrolytic reduction deposits metallic coatings—nickel, chromium, zinc—onto conductive substrates with precise thickness control measured in microns. Demand concentrates in automotive connector and fastener manufacturing across China's eastern manufacturing corridor, where Ningbo job shops serve export-tier electronics and appliance supply chains. REACH hexavalent chromium restrictions are forcing line conversions to trivalent processes, extending equipment refresh cycles.
- Powder Coating:Thermoset or thermoplastic powders are electrostatically applied and cured, eliminating volatile organic compound emissions inherent to liquid finishes. Automotive OEMs in Germany and appliance manufacturers in Turkey are expanding procurement for exterior housing applications where color durability and environmental compliance intersect. Powder formulations with metallic flake effects are displacing liquid metallic paints in premium automotive segments.
- Galvanizing:Hot-dip or electrogalvanizing deposits zinc layers onto steel substrates for corrosion protection in infrastructure and construction applications.
- Anodizing:Electrochemical oxidation builds aluminum oxide layers for wear resistance, dielectric properties, and dye adhesion in aerospace and consumer electronics housings.
Mature deployment sits with electroplating. Newer deployment is concentrated in powder coating.
Material:
Aluminum and steel split the market by weight, with aluminum gaining share fastest in electric drivetrain and aerospace thermal management applications.
- Aluminum:Lightweight substrates with superior thermal conductivity dominate aerospace structural components and electronics heat dissipation solutions. Taiwan semiconductor packaging manufacturers specify sulfuric acid anodizing for aluminum carrier frames in advanced packaging operations. China's dual carbon goals are accelerating aluminum substitution for heavier steel components in NEV battery enclosures.
- Steel:Carbon and alloy steels remain the substrate of choice for high-strength fasteners, automotive chassis components, and construction hardware requiring zinc or nickel interlayers. European automotive tier-one suppliers in Germany and Czechia maintain captive steel finishing lines for powertrain and suspension components. REACH restrictions on hexavalent passivation are forcing chemistry reformulation for steel pretreatment sequences.
- Copper:High electrical conductivity substrates require precision plating for semiconductor lead frames and printed circuit board interconnects.
- Zinc:Die-cast zinc alloys serve as substrate and sacrificial coating material in decorative hardware and automotive interior trim.
Volume concentration favors steel. Premium expansion is anchored in aluminum.
Application:
Automotive applications generate the highest absolute demand, while medical devices command the steepest process certification premiums.
- Automotive:Surface treatment procurement spans exterior trim, underhood components, and electric drivetrain housings with thermal conductivity and dielectric specifications. OEMs in Germany, China, and the United States are qualifying electroless nickel and trivalent chrome finishes for aluminum motor housings and battery enclosures. Powder coating is displacing liquid primers in wheel and chassis applications.
- Electronics:Semiconductor packaging, connector plating, and shielding applications require sub-micron thickness control and high-aspect-ratio through-hole coverage. Taiwan and South Korean advanced packaging manufacturers are adopting pulse-reverse electroplating power supplies for wafer-level redistribution layers. REACH substance restrictions are complicating tin-lead solder finish qualifications.
- Aerospace:Airframe structures and landing gear components require chromic acid anodizing and cadmium plating replacements qualified to EASA and FAA specifications.
- Medical Devices:Implantable and surgical instrument finishing demands biocompatibility certification, passivation, and electropolishing to ISO and FDA standards.
Process standardization is deepest in automotive. Qualification complexity peaks in medical devices.
Technology:
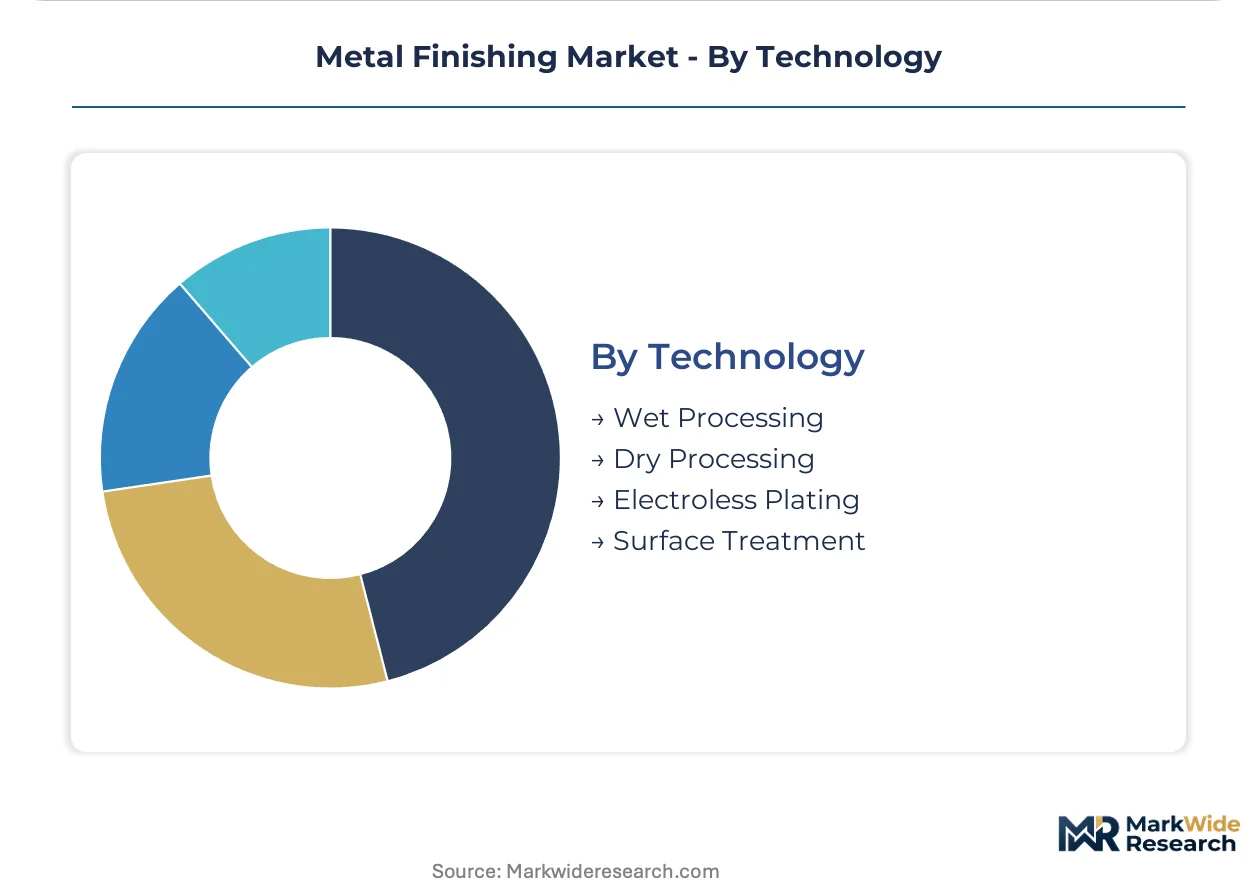
Wet processing retains volume leadership while dry processing and electroless plating expand in precision and emission-constrained niches.
- Wet Processing:Immersion-based chemical and electrolytic baths constitute the dominant technology architecture across job-shop and captive operations. China's MEE wastewater enforcement is consolidating wet line capacity around centralized treatment infrastructure in Suzhou and Dongguan clusters. Effluent handling capital requirements are eliminating fragmented operators without captive chemistry supply.
- Electroless Plating:Autocatalytic deposition eliminates external current requirements, achieving uniform coating thickness on complex geometries and internal passages. Automotive OEMs are specifying electroless nickel-phosphorus for aluminum transmission housings and electronic shielding enclosures. German tier-one suppliers are absorbing extended qualification timelines for high-phosphorus variants in fuel cell bipolar plate applications.
- Dry Processing:Physical vapor deposition and thermal spray technologies serve aerospace and tooling applications requiring ceramic or cermet surface layers.
- Surface Treatment:Conversion coatings, phosphating, and organic pretreatments prepare substrates for subsequent coating adhesion and corrosion protection.
Established capacity centers on wet processing. Capability investment is flowing toward electroless plating.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China processes the majority of global metal finishing throughput while Germany and the United States concentrate specialized high-value applications. Consumption patterns diverge between mass-market automotive and electronics manufacturing in Asia-Pacific and precision aerospace and medical finishing in Western Europe and North America.
China
Electric vehicle production and semiconductor packaging drive surface treatment demand across the eastern manufacturing corridor. MEE wastewater enforcement is consolidating fragmented electroplating shops around centralized treatment infrastructure in Ningbo and Suzhou. These clusters now serve as export finishing hubs for precision electronics and aerospace components.
Germany
Automotive OEMs are expanding procurement for aluminum drivetrain housings with thermal conductivity specifications. REACH authorization requirements are eliminating hexavalent chromium processes and forcing trivalent chrome conversions across Bavarian and Baden-Württemberg plating operations. German tier-one suppliers absorb extended qualification timelines due to OEM specification conservatism.
United States
Defense aerospace and medical device applications sustain demand for chromic acid anodizing and specialized passivation processes. EPA effluent guidelines and OSHA hexavalent chromium exposure limits shape capital equipment decisions across Midwest finishing corridors. Michigan and Ohio job shops face consolidation pressure from compliance cost burdens.
Japan
Advanced packaging manufacturers specify pulse-reverse electroplating for wafer-level redistribution layers with sub-micron thickness control. METI industrial standards and JIS certification requirements govern chemistry formulation approvals for semiconductor and automotive applications. Kyushu and Nagoya clusters concentrate captive finishing operations for electronics supply chains.
India
BIS standards adoption and PLI scheme incentives for electronics and automotive are creating demand for export-grade finishing capacity. CDSCO medical device regulations and DGFT export certification requirements are raising quality thresholds for Pune and Chennai corridor operations. Domestic plating capacity is scaling to reduce import dependency for precision components.
Metal Finishing Market Competitive Environment
Capital-heavy producers with captive chemistry supply compete with asset-light process technology licensors for long-term service contracts. The market structure consolidates around integrated suppliers with effluent handling capabilities while fragmenting among specialized job shops without treatment infrastructure. Three archetypes dominate: chemistry-integrated line managers, equipment-focused technology providers, and regional job-shop networks. M&A activity targets captive formulation capabilities, and strategic partnerships anchor subscription-linked performance contracts.
Among chemistry-integrated specialists, Atotech Deutschland GmbH exemplifies the line-management archetype through long-term plating agreements with automotive tier-ones. PPG Industries and Quaker Houghton occupy positions at the technology-licensing and fluid-integration poles respectively. These three anchors illustrate how competitive positioning depends on whether suppliers bundle chemicals, equipment, or technical service into recurring revenue structures.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Atotech Deutschland GmbH |
| DuPont de Nemours, Inc. |
| Henkel AG & Co. KGaA |
| BASF SE |
| PPG Industries, Inc. |
| Quaker Houghton |
| OC Oerlikon Management AG |
| Axalta Coating Systems |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between aerospace-qualified and commodity job-shop finishing creates distinct pricing bands that map directly onto supply chain tiering. Premium pricing for EASA and FAA-certified processes in Germany and the United States rests on captive chemistry supply and multi-year qualification timelines, while Ningbo and Suzhou clusters compete on throughput scale for automotive and electronics volume.
Pricing Analysis
Margin tightening in commodity electroplating reflects nickel sulfate and chromium compound volatility tied to mining output swings. Contract-based long-term offtake agreements dominate premium tiers, with pricing stratifying across aerospace-certified, automotive-qualified, and unstandardized job-shop levels. Certification level and volume scale drive differentiation, with tier-two manufacturers most price-sensitive and medical device OEMs least sensitive due to biocompatibility requirements.
Supply Chain Analysis
Dual-sourcing mandates from automotive OEMs in Germany and the United States require qualified backup suppliers for critical plating lines. Supply concentrates in China, Germany, and the United States, with raw material dependencies on nickel sulfate, chromium compounds, and proprietary organic additives. Single-source vulnerability around captive chemistry formulations from Atotech and Henkel creates consolidation risk. Distribution runs through tier-one automotive suppliers and direct OEM contracts for high-specification applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Trivalent chrome and electroless nickel processes are displacing hexavalent chromium across European and North American supply chains, compressing the technology lifecycle for legacy plating lines and forcing capital redeployment toward closed-loop systems.
For Market Incumbents: Cement market position by acquiring captive formulation capabilities in trivalent chrome chemistry to offset REACH-driven substitution pressure. Expand effluent treatment infrastructure in China's eastern corridor to capture MEE consolidation benefits and anchor multi-year line management agreements with automotive tier-ones. For New Entrants and Emerging Players: REACH authorization requirements in Europe open a window for specialized trivalent passivation and thin-film ceramic coating qualifications previously blocked by incumbents with legacy hexavalent approvals. Target German and French aerospace supply chains with EASA-compliant alternative chemistries, using qualification partnership models with tier-one suppliers as the primary go-to-market angle. For Investors and Strategic Acquirers: Re-rating potential sits with integrated suppliers possessing captive chemistry and centralized effluent handling given regulatory consolidation pressure. Long-term viability favors operations with renewable energy procurement and closed-loop water systems aligned with China's dual carbon goals. Monitor MEE enforcement intensity in Ningbo and Suzhou as the inflection indicator for geographic supply concentration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Chemistry | REACH compliance costs favor suppliers with in-house trivalent chrome formulation capabilities. |
| Centralized Effluent Infrastructure Buildout | China's MEE enforcement consolidates fragmented job shops around integrated treatment hubs in Suzhou. |
| Long-term Line Management Agreements | Automotive OEMs in Germany bundle chemistry, equipment, and technical service under throughput-based contracts. |
| EASA/FAA Qualification Partnership | Aerospace tier-ones in France and Germany absorb extended timelines for alternative coating approvals. |
| Renewable Energy Procurement | Provincial carbon intensity targets in China's eastern corridor favor finishing operations with clean power sourcing. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with plating line managers, automotive tier-one procurement leads, chemical formulation technical directors, and effluent treatment equipment suppliers combined with ECHA authorization databases, EPA effluent guideline documentation, and China MEE enforcement reports. Bottom-up facility capacity estimates and top-down chemical consumption data underwent triangulation across the analysis window.
Reconciliation of production volume data from Ningbo and Suzhou clusters with chemical shipment records established the baseline for segmentation modeling across process type, substrate material, end-use application, and regional regulatory cluster. CAGRs derived from installed base depreciation schedules and replacement demand cycles for trivalent chrome conversion. Semiconductor packaging demand for pulse-reverse electroplating and electric vehicle housing specifications for thermal conductivity coatings served as industry-specific forecast inputs.
The model assumes a particular technology adoption path for trivalent chrome and electroless nickel substitution; alternative pathways for thin-film ceramic coatings would alter the outlook for traditional plating demand. Deviation in REACH authorization sunset timelines or MEE enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Lanthanum Market
Metals
Industrial Silver Market
Metals
High Purity Base Metals Market
Metals
Crude Steel Market
Metals
Pump Casing Materials Market
Metals
Stainless Steel Panels Market
Metals
High Purity Aluminium Market
Metals
High Purity Iron Powder Market
Metals
Arc Ferrite Magnet Market
Metals
Stainless Steel Round Bar Market
Metals
Seamless Stainless Steel Products Market
Metals
Aluminum Flat Products Market
Metals
Beryllium Copper for Telecommunication Market
Metals
Metal Recycling Market
Metals
Global Vanadium Market
Metals
North America Metal Finishing Market