
 Beryllium Oxide Market | 2026-2036
Beryllium Oxide Market Size, Share, and Industry Trends Forecast 2026-2036
Beryllium Oxide Market Analysis
The EU Green Deal is repositioning beryllium oxide procurement standards across European electronics and nuclear supply chains. Materion Corporation leverages captive refining capacity in Utah to sustain its position in high-purity substrate supply. NGK Insulators anchors its competitive stance through ceramic processing expertise developed for thermal management applications. American Beryllia specializes in precision-machined components for defense and aerospace end users.
Beryllium oxide is a white crystalline compound with exceptional thermal conductivity reaching approximately 300 W/m·K and high electrical resistivity, produced through calcination of beryllium hydroxide followed by sintering or hot pressing into ceramic forms. Aerospace applications dominate volume consumption due to satellite and radar system requirements for heat-dissipating insulators, while thermal management segments in power electronics represent the fastest-expanding demand pool as wide-bandgap semiconductor deployment accelerates. High purity grades command premium positioning in nuclear and laser technology markets where trace contamination tolerance approaches parts-per-billion thresholds.
The EPA governs beryllium workplace exposure limits under 29 CFR 1910.1024, directly constraining domestic manufacturing economics and protective equipment investment requirements. OSHA enforcement of permissible exposure limits shapes facility location decisions and automation capital allocation for U.S.-based producers. ECHA REACH authorization procedures regulate import and use of beryllium compounds across European member states, creating divergent compliance pathways. Stakeholders must monitor evolving toxicity reclassification proceedings and alternative ceramic substitution timelines to calibrate long-term capacity commitments.
Market Dynamics
Wide-bandgap semiconductor deployment is compressing thermal management requirements across power electronics, pulling beryllium oxide substrates into high-frequency amplifier and radar module assemblies at volumes previously reserved for legacy alumina alternatives.
Growth Catalysts
- Defense electronics procurement:Pentagon modernization programs for phased-array radar systems are expanding qualified supplier pools for heat-dissipating ceramic substrates. Materion and American Beryllia have secured multi-year supply agreements.
- OSHA 29 CFR 1910.1024:Stricter permissible exposure limits are accelerating automation investments among domestic manufacturers, concentrating output among facilities with captive refining and precision-machining capabilities.
- REACH authorization pathways:ECHA registration requirements are filtering out non-compliant importers, tightening European supply chains and elevating pricing power for authorized producers with established downstream user networks.
Market Restraints
- Beryllium hydroxide feedstock concentration:Spor Mountain, Utah hosts the sole commercial beryllium ore mining operation in the United States, creating single-source dependency for domestic refined oxide output.
- Aluminum nitride substitution:Lower-cost ceramic alternatives with comparable thermal conductivity are capturing mid-tier power electronics applications where trace contamination tolerance exceeds parts-per-billion thresholds.
- Workplace exposure liability:Chronic beryllium disease risk elevates insurance premiums and protective equipment capex, compressing margins for manual processing stages that resist full automation.
Strategic Opportunities
- Laser technology purity grades:Parts-per-billion contamination specifications in solid-state laser cavities command 3-4x substrate premiums over standard electronics grades, opening specialty revenue pools.
- India defense indigenization:Make in India procurement mandates for radar and electronic warfare systems are creating first-mover advantages for substrate suppliers establishing local machining partnerships.
- EU Green Deal material passports:Digital traceability requirements for critical raw materials are favoring producers with vertically integrated mine-to-substrate documentation systems.
Industry Challenges
- Ceramic metallization expertise:Thin-film deposition and direct bond copper processes require specialized technicians whose training pipelines lag demand growth by 18-24 months.
- Dual-use export licensing:ITAR and EAR classifications for defense-grade substrates extend order-to-delivery cycles by 90-120 days, complicating just-in-time inventory coordination with semiconductor foundries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beryllium Oxide Market |
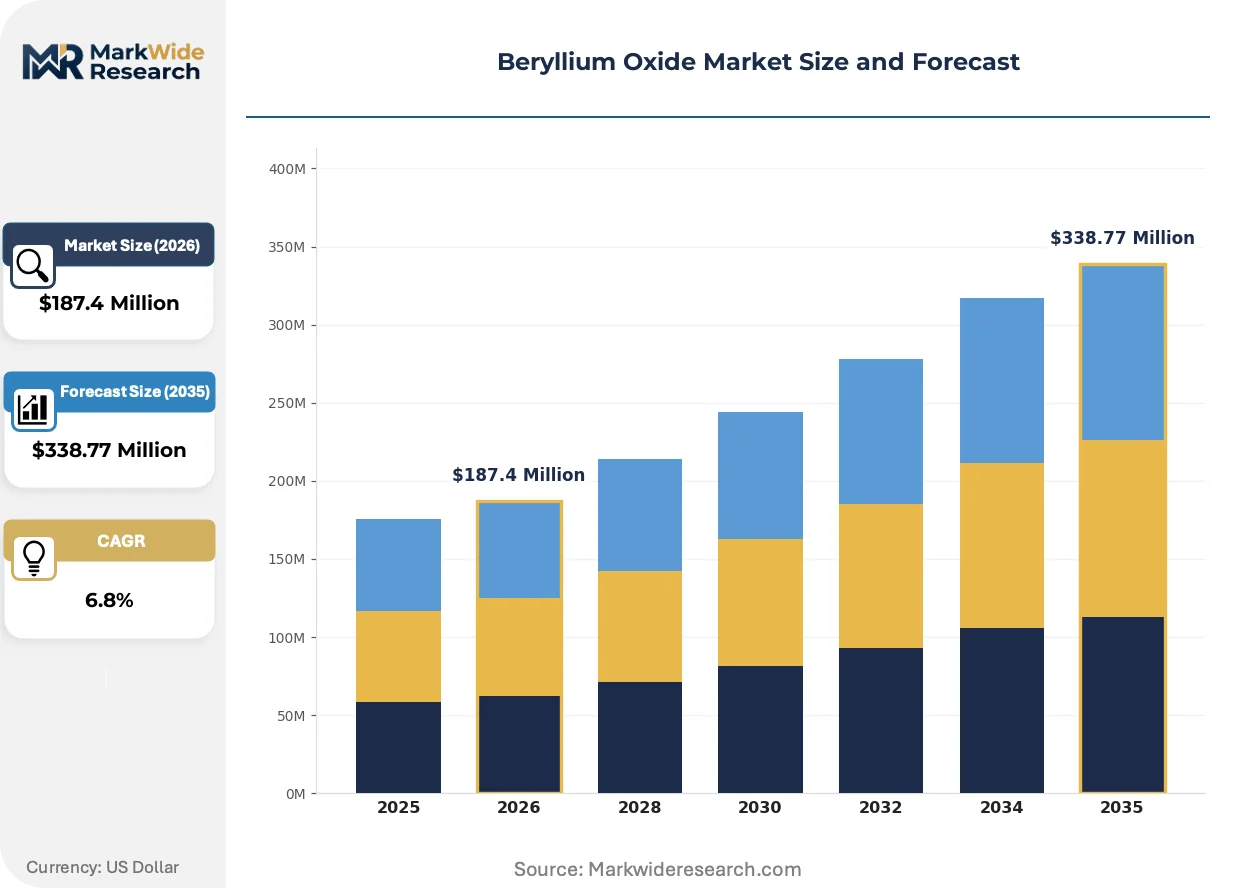
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High Purity, Low Purity, Coated, Uncoated End Use Industry: Aerospace, Electronics, Defense, Nuclear Form: Powder, Sintered, Ceramic, Composite Application: Thermal Management, Electrical Insulation, Pressure Vessels, Laser Technology |
| Companies Covered | Materion Corporation, NGK Insulators, Ltd., American Beryllia, Inc., IBC Advanced Alloys Corp., Kazatomprom, Hunan Shuikoushan Nonferrous Metals Group Co., Ltd., Texas Mineral Resources Corp., Belmont Metals, Xiamen Beryllium Copper Technologies Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beryllium Oxide Market Emerging Trajectories
Hot isostatic pressing is displacing conventional sintering as the dominant densification method for high-purity grades, while regulatory pressure on workplace exposure is reshaping facility automation roadmaps across producer networks.
Hot isostatic pressing is consolidating quality differentiation in substrate manufacturing. This process eliminates residual porosity in beryllium oxide ceramics, achieving thermal conductivity measurements approaching theoretical limits. Aerospace prime contractors and satellite integrators now specify HIP-processed material for all new heat-dissipating insulator designs. The technology is consolidating supplier tiers by compressing acceptable defect rates to sub-50 ppm levels that legacy sintering cannot reliably hit.
REACH authorization timelines are compressing European procurement flexibility. ECHA's 2023-2024 substance evaluation waves have extended lead times for beryllium compound import permits by 8-14 months. German and French electronics manufacturers are responding by dual-qualifying Utah-sourced material through Materion's direct distribution channels, bypassing intermediate traders lacking authorization documentation. Nuclear energy OEMs face the tightest constraints, as their traceability requirements intersect with both REACH and EURATOM safeguards protocols.
Direct supplier relationships are displacing distributor intermediaries in high-specification procurement. Defense contractors and satellite prime manufacturers now require technical service integration that commodity ceramic distributors cannot provide. American Beryllia and NGK Insulators have established field engineering teams co-located with major radar and power module assembly facilities in California, Texas, and Aichi Prefecture. This channel compression is most visible in United States military procurement, where DFARS compliance mandates eliminate non-domestic intermediaries from qualified supplier lists.
Beryllium Oxide Market Segmentation
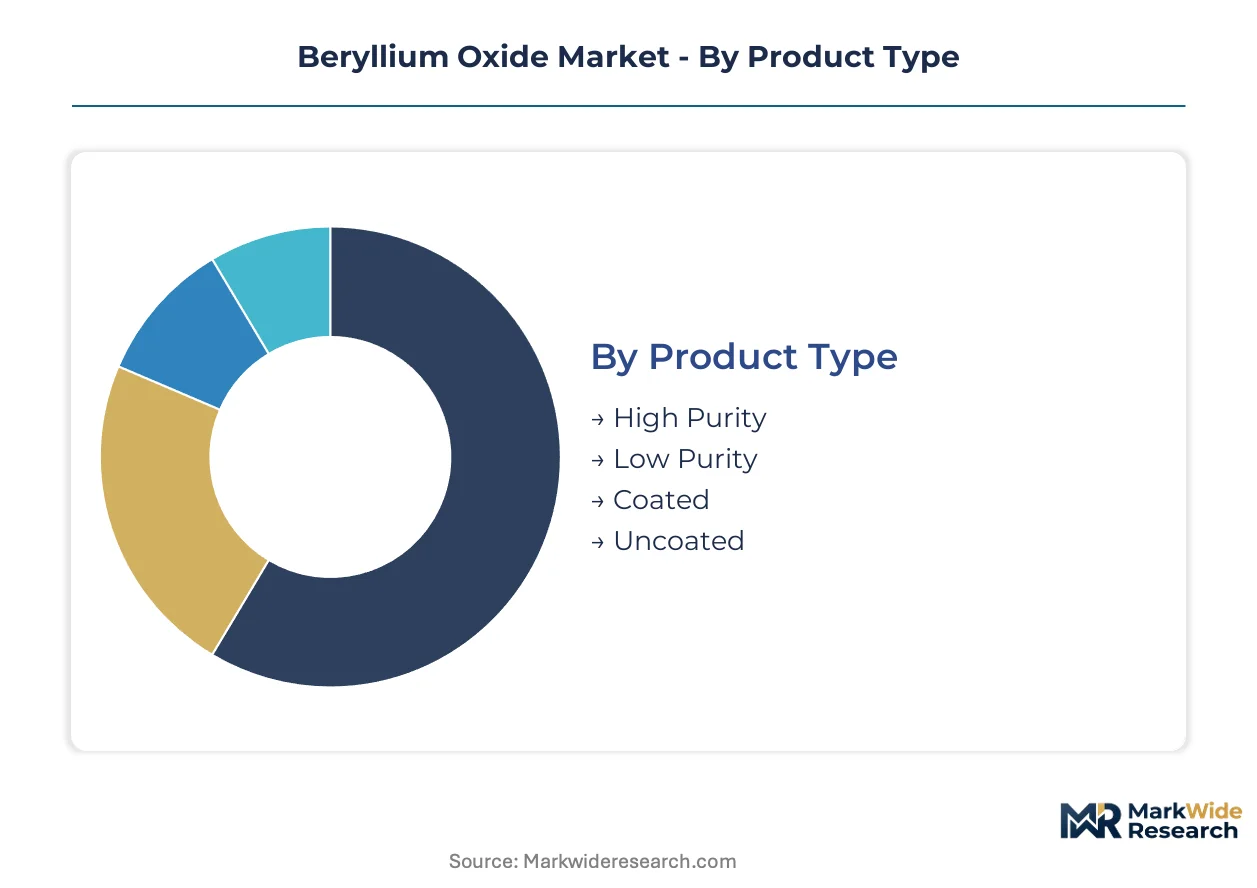
Beryllium oxide procurement patterns diverge sharply between standalone substrate applications and embedded ceramic systems, creating distinct specification requirements across each segment tier. Understanding these integration-depth differences enables suppliers to calibrate purity grades, machining tolerances, and metallization services to actual end-use constraints.
Product Type:
Integration depth separates standalone high-purity substrates from lower-grade materials embedded in composite assemblies where trace contamination tolerance relaxes.
- High Purity:Achieves parts-per-billion contamination thresholds through multiple calcination cycles and hot isostatic pressing, serving solid-state laser cavities and nuclear reactor neutron reflectors where thermal neutron absorption cross-section precision governs performance. Materion Corporation's Utah refining complex dominates supply for defense and energy OEMs requiring documented provenance.
- Low Purity:Standard electronics-grade material tolerates higher trace metal content, finding volume placement in commercial RF amplifiers and industrial heating elements where cost sensitivity outweighs extreme purity premiums. Chinese ceramic processors capture mid-tier thermal management demand through scaled powder metallurgy operations.
- Coated:Thin-film metallized surfaces enable direct bond copper attachment for power module substrates, with nickel-gold or titanium-tungsten coatings applied via sputtering or electroless deposition.
- Uncoated:Raw ceramic blanks serve precision-machining houses and captive component fabrication facilities with in-house metallization capabilities.
High Purity leads volumes today; Coated is gaining share fastest.
End Use Industry:
Customer procurement sophistication spans from commodity ceramics purchasing to mission-critical qualification programs with multi-year validation cycles.
- Aerospace:Satellite thermal control systems and radar heat sinks demand HIP-processed substrates with sub-50 ppm defect rates, with prime contractors Lockheed Martin and Northrop Grumman mandating direct supplier relationships bypassing distributors.
- Electronics:Wide-bandgap semiconductor packaging pulls beryllium oxide into GaN and SiC power modules, though aluminum nitride substitution pressures mid-tier applications where thermal conductivity requirements sit below 250 W/m·K.
- Defense:Phased-array radar and electronic warfare systems drive qualified supplier pool expansion, with Pentagon modernization programs extending multi-year supply agreements to Materion and American Beryllia.
- Nuclear:Neutron moderator and reflector applications in research reactors and fusion energy prototypes require EURATOM-safeguarded traceability documentation intersecting with REACH authorization constraints.
Defense procurement is expanding most quickly; Aerospace retains the largest installed base.
Form:
Processing stage determines supply chain positioning, with upstream powder producers capturing different margin pools than downstream precision machiners.
- Powder:Calcined beryllium oxide feedstock concentrates production at Spor Mountain, Utah, creating single-source dependency for domestic refined output that constrains global supply elasticity.
- Sintered:Near-net-shape ceramic blanks reduce machining waste for high-volume electronics applications, with Japanese and German ceramic houses dominating densification technology.
- Ceramic:Fully densified and finished substrates command premium positioning in laser and nuclear markets where dimensional tolerances approach micrometer precision.
- Composite:Beryllium oxide dispersed in metal or polymer matrices addresses applications requiring combined thermal conductivity and mechanical compliance, including avionics chassis and semiconductor tooling.
Ceramic forms dominate revenue today; Composite applications show the steepest expansion trajectory.
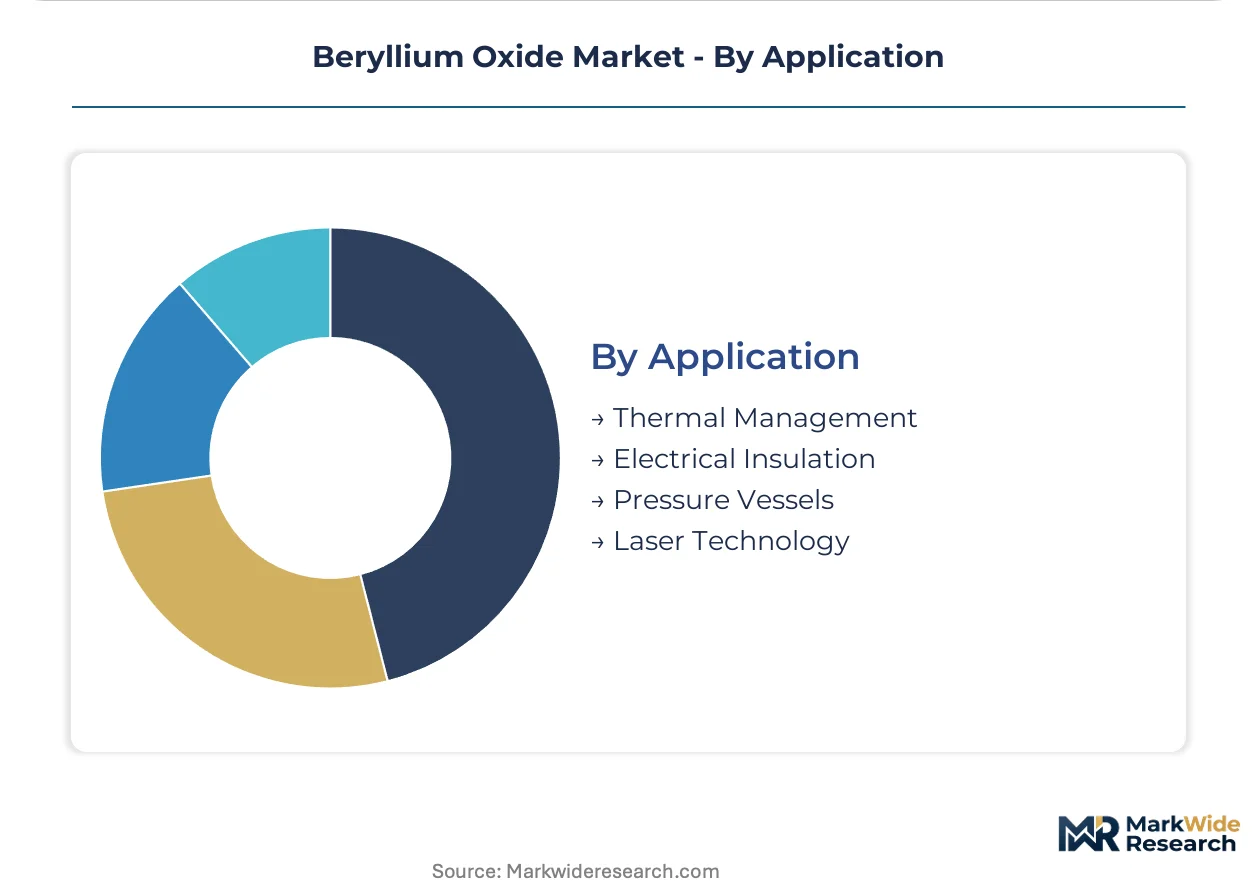
Application:
Functional performance requirements stratify pricing power, with thermal dissipation applications tolerating broader specification bands than optical or nuclear systems.
- Thermal Management:Heat-spreading substrates for RF power amplifiers and wide-bandgap semiconductor packages represent volume demand concentration, with power density escalation in 5G base stations and electric vehicle inverters pulling material substitution from alumina.
- Electrical Insulation:High-voltage standoff capabilities in compact geometries serve aerospace and defense systems where space constraints prohibit larger alumina or aluminum nitride alternatives.
- Pressure Vessels:Neutron-transparent structural ceramics for fusion energy research and specialized chemical processing equipment require custom fabrication cycles extending 12-18 months.
- Laser Technology:Solid-state laser cavities demand parts-per-billion purity with specialized dopant incorporation, commanding 3-4x substrate premiums over standard electronics grades.
Thermal Management leads volumes today; Laser Technology is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The beryllium oxide industry traces its commercial origins to Utah's Spor Mountain mining complex, where domestic refining capacity established supply chain foundations that persist today. This historical concentration shapes contemporary procurement patterns across defense, electronics, and nuclear energy sectors worldwide.
United States
Pentagon modernization programs for phased-array radar systems and satellite thermal control platforms drive procurement volumes. OSHA 29 CFR 1910.1024 governs workplace exposure limits, accelerating automation investments among domestic manufacturers. Utah's Spor Mountain remains the sole commercial beryllium ore source, anchoring Materion Corporation's captive refining and precision-machining operations.
Japan
Wide-bandgap semiconductor packaging for electric vehicle inverters and 5G base station amplifiers pulls substrate demand. METI industrial standards regulate ceramic processing emissions and worker safety protocols. Aichi Prefecture ceramic houses concentrate hot isostatic pressing expertise developed through decades of thermal management component supply to automotive and electronics OEMs.
Germany
Nuclear energy research reactors and fusion energy prototypes require EURATOM-safeguarded traceability documentation. ECHA REACH authorization procedures filter import permits, extending lead times by 8-14 months. Bavarian precision engineering clusters dual-qualify Utah-sourced material through direct distribution channels, bypassing intermediate traders lacking authorization.
China
Domestic RF amplifier and industrial heating element manufacturing scales powder metallurgy operations for mid-tier thermal management applications. GB standards and MIIT regulations govern workplace exposure and environmental discharge limits. Hunan Province nonferrous metals processing infrastructure supports calcined beryllium oxide feedstock production for electronics-grade ceramic manufacturing.
India
Make in India procurement mandates for radar and electronic warfare systems create first-mover opportunities for substrate suppliers establishing local machining partnerships. BIS certification requirements and DGFT import licensing shape supplier qualification timelines. Bangalore and Hyderabad defense electronics corridors concentrate demand for heat-dissipating ceramic components in indigenous aerospace programs.
Beryllium Oxide Market Vendor Landscape
Premium-margin players sit above commodity-margin players across purity-grade and metallization-capability dimensions. The supplier base consolidates into three tiers: vertically integrated miners with captive refining, specialized ceramic processors with hot isostatic pressing expertise, and precision-machining houses serving defense-qualified specifications. Two dominant competitive moves define current positioning: backward integration into beryllium hydroxide feedstock security, and field engineering co-location with prime contractor assembly facilities.
Within the vertically integrated tier, Materion Corporation and American Beryllia, Inc. exemplify archetypes combining Utah-sourced ore access with downstream substrate finishing capabilities. NGK Insulators, Ltd. occupies a distinct position as a ceramic processing specialist leveraging decades of thermal management expertise. Hunan Shuikoushan Nonferrous Metals Group Co., Ltd. represents the scale-driven Chinese contingent focused on powder and sintered blank production for mid-tier electronics applications. These three anchors illustrate how geographic proximity to ore sources, metallization technical depth, and defense qualification status stratify competitive positioning.
| Leading Market Players |
|---|
| Materion Corporation |
| NGK Insulators, Ltd. |
| American Beryllia, Inc. |
| IBC Advanced Alloys Corp. |
| Kazatomprom |
| Hunan Shuikoushan Nonferrous Metals Group Co., Ltd. |
| Texas Mineral Resources Corp. |
| Belmont Metals |
| Xiamen Beryllium Copper Technologies Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Captive refining integration at Utah's Spor Mountain complex anchors Materion Corporation's pricing power across high-purity substrate tiers while constraining supply elasticity for downstream competitors lacking equivalent upstream control. This concentration pattern compresses margin pools for non-integrated processors and elevates cost pass-through capabilities for authorized REACH suppliers serving European nuclear and defense OEMs.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies beryllium oxide procurement based on purity certification and metallization complexity. Premium HIP-processed grades command substantial markups over standard electronics material due to sub-50 ppm defect requirements and EURATOM traceability documentation. Cost compression in mid-tier thermal management applications intensifies as aluminum nitride substitution accelerates, with Chinese powder processors capturing volume-sensitive RF amplifier demand. Defense contractors exhibit lowest price sensitivity given ITAR qualification barriers and mission-critical performance specifications.
Supply Chain Analysis
Refurbishment and precision re-machining flows for high-value defense substrates create secondary supply channels extending component lifecycles in satellite and radar systems. Primary production concentrates in the United States, Japan, and China, with Utah's Spor Mountain hosting the sole commercial beryllium ore mining operation for Western supply. Feedstock dependency on beryllium hydroxide calcination and specialized ceramic densification equipment creates single-source vulnerability for non-integrated manufacturers. Distribution runs through direct supplier relationships with prime contractors, bypassing commodity ceramic distributors unable to provide technical service integration or DFARS compliance documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where OSHA 29 CFR 1910.1024 exposure limits and ECHA REACH authorization timelines continuously reshape qualified supplier pools and procurement flexibility. Pentagon modernization programs for phased-array radar systems provide durable demand anchors across the analysis window.
For Market Incumbents: Anticipate aluminum nitride substitution pressure in mid-tier power electronics by deepening hot isostatic pressing capabilities and securing captive beryllium hydroxide feedstock through Utah refining capacity expansion. Accelerate automation investments to compress workplace exposure liability costs and defend margin position against emerging ceramic processors in Aichi Prefecture. For New Entrants and Emerging Players: Direct-to-defense-prime digital qualification pathways offer lower barrier entry than distributor-dependent channels, particularly for precision-machining houses establishing ITAR-compliant facilities in Texas or California. Target India's Make in India radar indigenization programs through local machining partnerships in Bangalore and Hyderabad defense corridors, leveraging BIS certification timelines to build reference accounts before incumbent field engineering teams consolidate positioning. For Investors and Strategic Acquirers: Roll-up economics work for precision-ceramic-machining specialists because defense qualification cycles create sticky customer relationships and ITAR compliance barriers protect acquired revenue streams. Platform consolidation around HIP-processed substrate capabilities offers five-to-ten year viability given wide-bandgap semiconductor thermal management demand trajectories. Monitor ECHA substance evaluation proceedings for authorization timeline compression signals that would elevate authorized-producer valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Hot Isostatic Pressing Capacity Expansion | Eliminates residual porosity to achieve thermal conductivity approaching theoretical limits for satellite integrators. |
| Backward Integration into Beryllium Hydroxide Feedstock | Secures Utah-sourced ore access and constrains supply elasticity for non-integrated competitors. |
| REACH Authorization Documentation Investment | Filters European import permit access and elevates pricing power for authorized producers. |
| Field Engineering Co-location with Prime Contractors | Enables technical service integration that commodity ceramic distributors cannot replicate. |
| Automation Capital Allocation for OSHA Compliance | Compresses workplace exposure liability costs and protective equipment capex requirements. |
Methodological Framework
Coverage spans the United States, Japan, Germany, China, and India, with primary inputs from each region combining interviews with defense procurement officers, ceramic plant managers, nuclear energy OEM technical directors, and semiconductor packaging engineers. Secondary validation draws from EPA enforcement records, ECHA authorization databases, SEC 10-K filings, and customs trade data. Bottom-up substrate demand modeling triangulates against top-down market sizing across purity grades and end-use applications.
Granularity-level modeling extends to individual purity tiers, metallization capabilities, and defense qualification status for each geographic production cluster. Segmentation dimensions include product type, end-use industry, processing form, and thermal management application intensity. CAGRs derive from demand elasticity analysis against wide-bandgap semiconductor deployment curves and Pentagon modernization program procurement schedules. Forecast inputs incorporate OSHA automation investment trajectories and REACH authorization timeline assumptions.
Substitution acceleration, regulatory reclassification proceedings, and defense budget reallocation are the dominant revision risks to modeled outputs. Practitioners should monitor aluminum nitride thermal conductivity improvements, ECHA substance evaluation waves, and phased-array radar program funding authorizations for early signals warranting forecast adjustment.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
Global Insulation Coating Materials Market
Insulation Materials
Industrial Pipe Insulation Market
Insulation Materials
Global Insulation Materials Market
Insulation Materials
Carbon Foam Market
Insulation Materials
Syntactic Foam Market
Insulation Materials
Cold-Air Diffusion Market
Insulation Materials
Phase Change Thermal Interface Materials Market
Insulation Materials
Protective Building Materials Market
Insulation Materials
North America Expanded Polypropylene Foam Market
Insulation Materials
Active Insulation Market
Insulation Materials
EV Battery Thermal Insulation Materials Market
Insulation Materials
Extruded Polystyrene (XPS) Insulation Material Market
Insulation Materials
One-Component Foam Market
Insulation Materials
Thermal Conductive Polymer Materials Market
Insulation Materials
OEM Insulation Market
Insulation Materials
Global Advanced Insulation Material Market