
 North America Aluminum Casting Market | 2026-2036
North America Aluminum Casting Market Size, Share, and Industry Trends Forecast 2026-2036
North America Aluminum Casting Market Analytics
The EPA's tightened Corporate Average Fuel Economy standards is decoupling aluminum casting demand from steel-intensive vehicle architectures across North America. Alcoa Corporation leverages captive smelting and recycling infrastructure to sustain cost leadership in high-purity alloy supply. Nemak S.A.B. de C.V. anchors its North American footprint through dedicated powertrain casting complexes serving Detroit Three automakers. Gibbs Die Casting Corp differentiates via precision high-pressure die casting for transmission housings and structural nodes.
Aluminum casting encompasses the pouring of molten aluminum alloys into molds to produce near-net-shape components with typical wall thicknesses of two to ten millimeters and tensile strengths ranging from 150 to 400 MPa depending on alloy grade and heat treatment. Die casting dominates volume production for automotive transmission cases and engine blocks where dimensional repeatability and surface finish requirements are stringent. Sand casting occupies critical aerospace and industrial equipment niches where low tooling costs accommodate shorter production runs and complex geometries. Permanent mold casting captures growing demand from Tier-1 suppliers seeking balance between die-cast precision and sand-cast flexibility for medium-volume powertrain brackets and suspension knuckles.
The EPA and NHTSA jointly govern vehicle efficiency mandates that directly dictate aluminum content targets for OEM platforms, while OSHA standards shape foundry automation investments to reduce molten metal exposure risks. The US Department of Energy's manufacturing competitiveness programs are channeling R&D funding toward advanced vacuum-assisted casting and 3D-printed mold technologies that reduce porosity defects. Stakeholders must monitor how Tier-1 supplier consolidation and OEM in-house casting investments reshape contract manufacturing volumes across the Great Lakes and Southeastern production zones.
Market Dynamics
EPA Corporate Average Fuel Economy standards are decoupling aluminum casting demand from steel-intensive vehicle architectures across North America. OEM procurement of lightweight powertrain and structural components now concentrates in the US Midwest manufacturing corridor.
Growth Catalysts
- CAFE Standards:EPA tightened fuel economy mandates force aluminum substitution in vehicle platforms, accelerating OEM procurement of lightweight transmission housings and structural nodes.
- Recycling Infrastructure:Secondary aluminum recovery from automotive shredder residue reduces primary metal dependency across Great Lakes foundry clusters.
- Powertrain Electrification:Battery enclosure and motor housing casting demand from electric vehicle platforms is displacing traditional engine block volumes in Michigan and Ohio.
Market Restraints
- Primary Aluminum Volatility:LME price swings and Midwest premium spikes compress foundry margins, particularly for sand casting operations serving aerospace lots.
- China Supply Concentration:Smelter capacity and alumina refining gravity in Shandong and Guangxi create input cost vulnerability for North American alloy producers.
- Steel Cost Arbitrage:Hot-rolled coil price collapses periodically resurrect steel-intensive designs for non-structural brackets and mounts.
Strategic Opportunities
- Southeastern US Expansion:Greenfield casting investments in Tennessee and Alabama capture BMW, Mercedes-Benz, and Hyundai-Kia assembly plant proximity.
- 3D-Printed Sand Molds:Binder jetting and digital patternless molding compress prototype-to-production timelines for low-volume aerospace and defense castings.
- IRA Clean Energy Credits:Inflation Reduction Act domestic content provisions incentivize recycled aluminum sourcing for battery and renewable energy hardware.
Industry Challenges
- Die Maintenance Expertise:High-pressure die casting tool steel refurbishment and thermal fatigue management skills gap constrains uptime in aging US facilities.
- OSHA Compliance Burden:Molten metal exposure reduction mandates require foundry automation capex that mid-tier contract manufacturers struggle to fund.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Aluminum Casting Market |
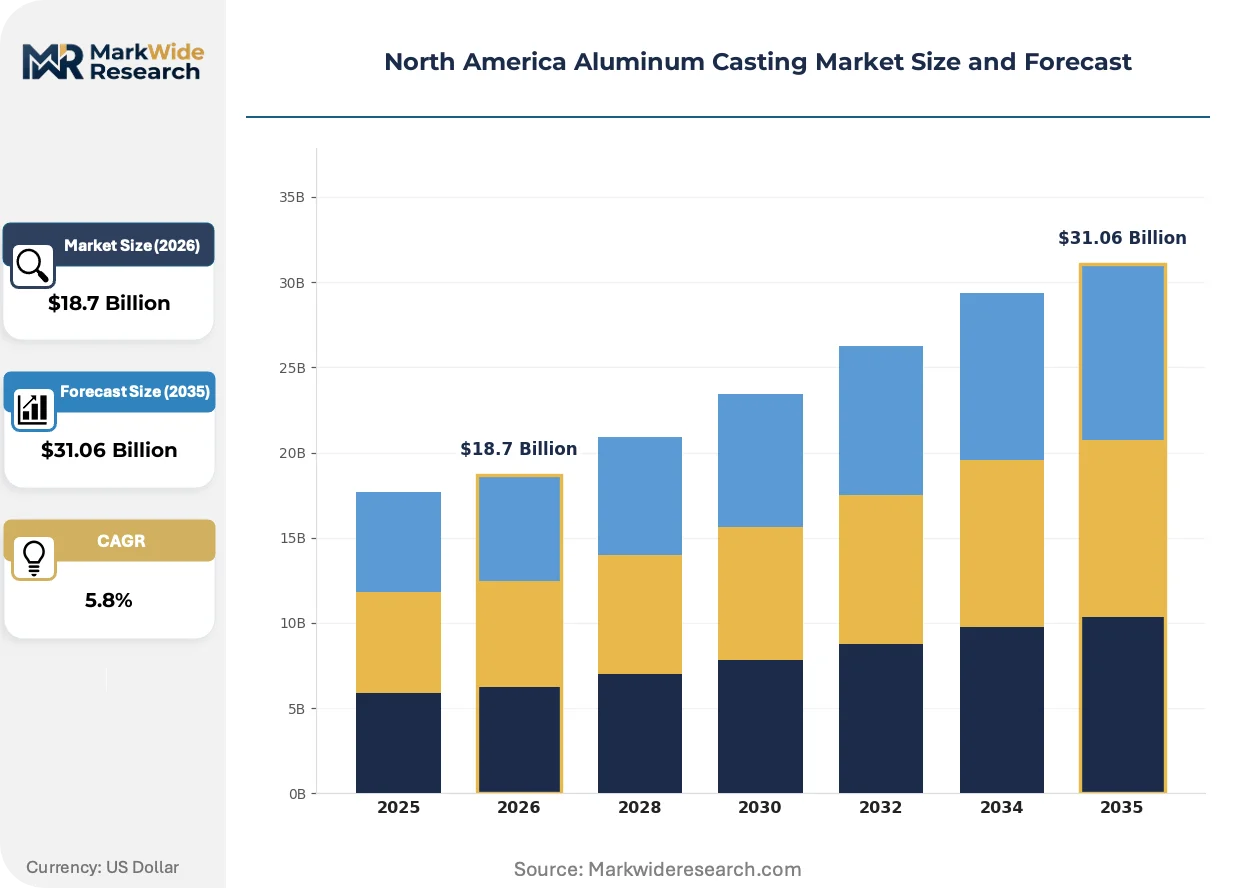
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Die Casting, Sand Casting, Permanent Mold Casting, Gravity Casting Application: Aerospace, Automotive, Consumer Electronics, Industrial Equipment End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Manufacturers Technology: High Pressure, Low Pressure, Vacuum, 3D Printing |
| Companies Covered | Alcoa Corporation, Nemak S.A.B. de C.V., Dynacast, Ryobi Limited, Consolidated Metco, Inc., DyCast Specialties Corporation, Alcast Technologies, Gibbs Die Casting Corp, Pace Industries, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Aluminum Casting Market Evolving Landscape
Vacuum-assisted and semi-solid metal casting processes are compressing porosity defect rates in critical automotive safety components. Digital thread integration from mold design to X-ray inspection is reshaping quality assurance protocols across Tier-1 supply chains.
Semi-solid rheocasting is consolidating process control advantages for thin-wall structural nodes requiring weldability and heat treat response. Detroit Three automakers specify these alloys for front and rear cradles on light truck platforms. The technology is consolidating specification authority among fewer qualified foundries capable of meeting OEM crash performance thresholds.
EPA and NHTSA joint rulemaking on vehicle greenhouse gas standards is hardening aluminum content minimums for model year fleets. Tier-1 suppliers must document recycled content percentages and carbon intensity scores under emerging supply chain disclosure requirements. Powertrain casting categories face the steepest compliance cost escalation as electrification timelines compress.
Fleet procurement of electric commercial vehicles is fragmenting traditional powertrain supply relationships. Municipal and logistics buyers now source battery enclosure castings directly from aluminum specialists, bypassing legacy engine component distributors. This pattern concentrates most visibly in California and Quebec zero-emission vehicle mandate jurisdictions.
North America Aluminum Casting Market Segmentation
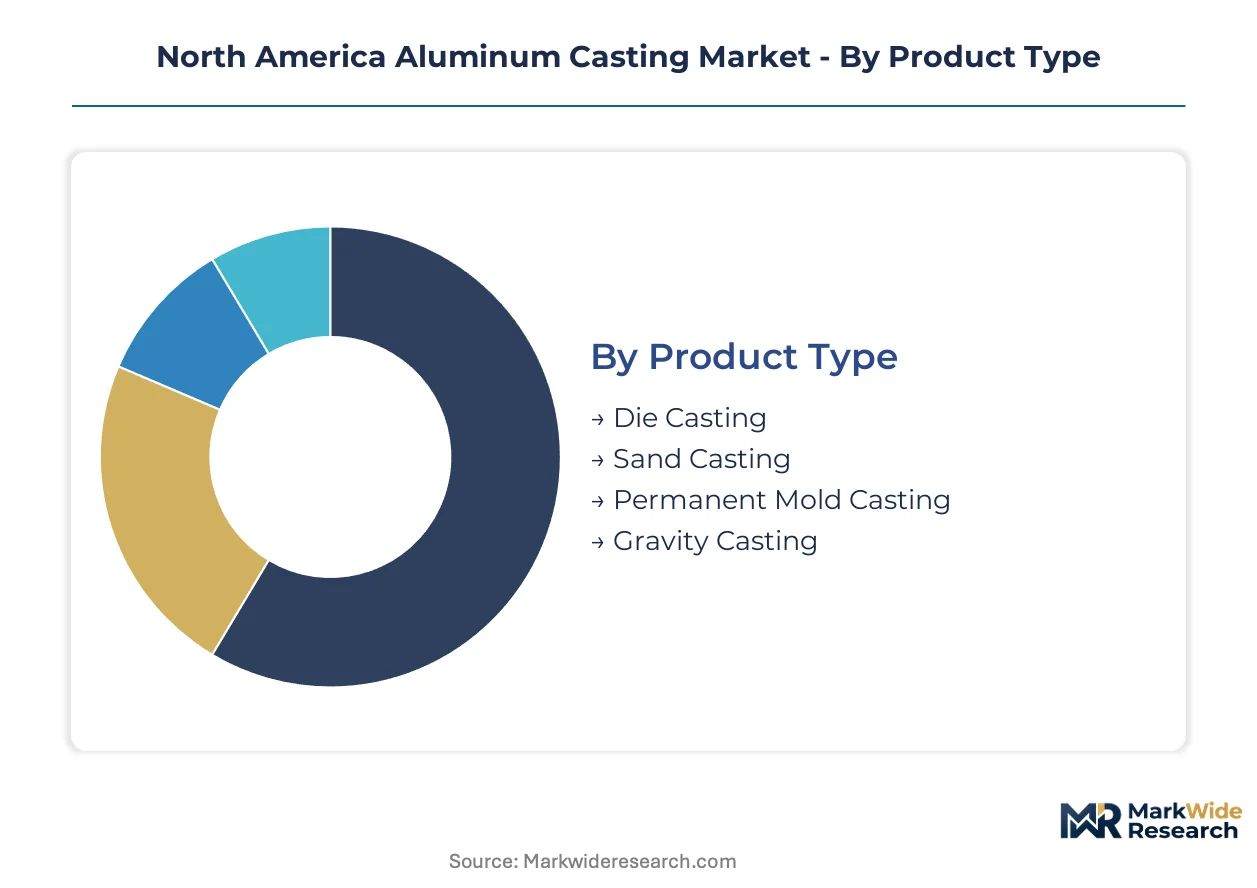
Process selection in aluminum casting directly determines achievable wall thickness, surface integrity, and production economics. OEMs match casting technology to component criticality, with powertrain safety parts demanding tighter process control than non-structural brackets.
Product Type:
Die casting commands volume leadership while sand casting retains premium positioning for aerospace lots and prototype runs.
- Die Casting:High-pressure injection of molten aluminum into hardened steel dies achieves dimensional tolerances of ±0.1 mm and cycle times under 60 seconds. Detroit Three automakers specify die-cast transmission housings and engine blocks for light truck platforms manufactured across Michigan and Ohio.
- Sand Casting:Bonded silica molds accommodate complex geometries and low tooling costs for production runs below 10,000 units annually. Aerospace OEMs in California and Washington source flight-critical structural castings through this process for its heat treat response and weldability.
- Permanent Mold Casting:Reusable metal molds balance surface finish precision with moderate volume flexibility for Tier-1 suspension component suppliers.
- Gravity Casting:Simple pour techniques serve industrial equipment manufacturers seeking thick-walled housings without pressure equipment capital expenditure.
Today's leader: Die Casting. Tomorrow's challenger: Permanent Mold Casting.
Application:
Automotive procurement volumes dwarf other segments while aerospace specifications command margin premiums.
- Automotive:EPA CAFE standards mandate aluminum substitution in vehicle platforms, concentrating demand for powertrain castings across the US Midwest manufacturing corridor spanning Michigan, Ohio, and Indiana.
- Aerospace:FAA-certified sand and investment castings for airframe structures and turbine housings require vacuum-assisted pouring and X-ray inspection protocols.
- Consumer Electronics:Thin-wall die-cast enclosures for laptops and smartphones source primarily from Mexican border maquiladoras serving US assembly operations.
- Industrial Equipment:Pump housings and valve bodies for oilfield and agricultural machinery favor permanent mold and gravity processes for corrosion resistance in harsh operating environments.
Automotive dominates present volumes. Aerospace maintains the steepest expansion trajectory as commercial aircraft production rates recover.
End User:
OEMs drive specification authority while Tier-1 suppliers capture contract manufacturing scale.
- OEMs:Ford, General Motors, and Stellantis maintain in-house casting capabilities for proprietary powertrain architectures, particularly engine blocks and transmission cases where design integration protects competitive position.
- Tier-1 Suppliers:Contract manufacturers like Nemak and Gibbs Die Casting operate dedicated facilities adjacent to Detroit Three assembly plants, managing die maintenance and thermal fatigue expertise that OEMs outsource.
- Aftermarket Providers:Independent distributors source sand-cast replacement components for vintage vehicle restoration and industrial equipment repair channels.
- Manufacturers:Industrial OEMs producing compressors, generators, and material handling equipment procure aluminum castings through direct foundry relationships.
Tier-1 Suppliers control current contract volumes. OEMs are reclaiming strategic casting categories through captive investments.
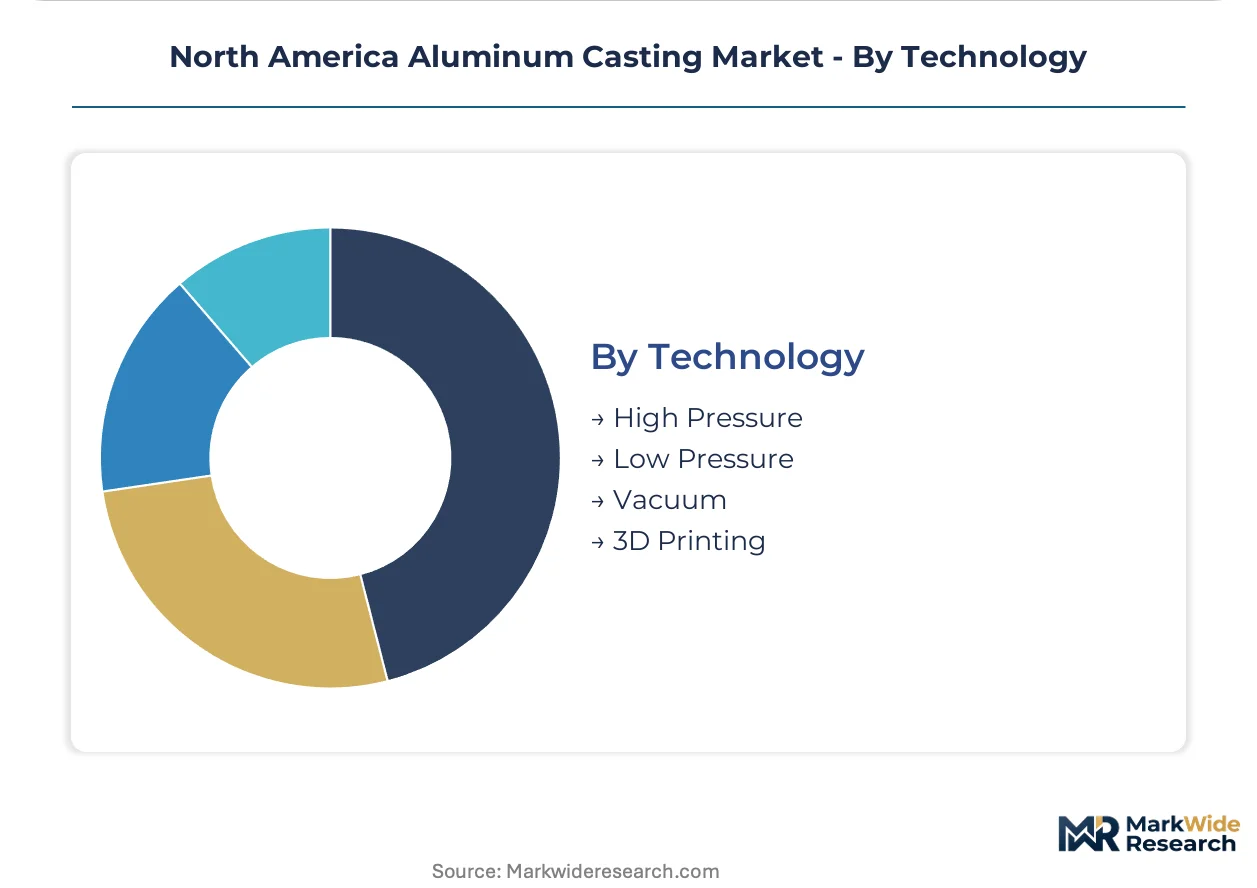
Technology:
High pressure dominates automotive throughput while vacuum and 3D printing capture specification premiums.
- High Pressure:Clamping forces exceeding 4,000 tons inject molten aluminum at 100 MPa into multi-cavity dies, achieving the surface finish and dimensional repeatability required for transmission housings and structural nodes.
- Vacuum:Evacuated mold cavities before metal entry reduce porosity defects below 0.5 percent, satisfying OEM crash performance thresholds for safety-critical suspension knuckles and steering components.
- Low Pressure:Controlled metal rise from pressurized crucibles produces directional solidification favorable for wheel castings and cylinder heads.
- 3D Printing:Binder-jetted sand molds eliminate pattern tooling for prototype-to-production transitions in aerospace and defense low-volume programs.
High Pressure anchors present automotive supply. Vacuum is climbing the fastest as safety component specifications tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aluminum casting scaled industrially across the Great Lakes region during the 20th century automotive build-out. Foundry infrastructure concentrated near Detroit, Cleveland, and Windsor to serve integrated OEM assembly. The EPA's CAFE standards now redirect investment toward Southeastern corridors and Mexican border zones.
United States
Michigan, Ohio, and Indiana anchor powertrain casting demand from Ford, General Motors, and Stellantis assembly operations. The EPA and NHTSA joint rulemaking on greenhouse gas standards hardens aluminum content minimums for light truck platforms. Detroit-area foundry clusters in Warren, Grand Rapids, and Cleveland supply die-cast transmission housings and structural nodes under tightened efficiency mandates.
Canada
Ontario's Windsor-to-Toronto corridor hosts casting operations serving cross-border automotive supply chains. Health Canada and Environment Canada coordinate emissions standards with US EPA benchmarks, eliminating regulatory arbitrage. Quebec's aluminum smelting infrastructure in Saguenay-Lac-Saint-Jean supplies primary metal to Great Lakes foundries through St. Lawrence Seaway logistics.
Mexico
Bajío Region and Nuevo León foundries capture OEM assembly plant proximity for GM, Ford, and BMW operations. Mexican environmental regulators enforce SEMARNAT standards aligning with US EPA thresholds for foundry emissions. Border maquiladoras in Tijuana and Ciudad Juárez specialize in thin-wall die-cast enclosures for consumer electronics serving US assembly.
North America Aluminum Casting Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across divergent cost structures in aluminum casting. The market exhibits tiered consolidation: integrated primary aluminum smelters control upstream alloy supply, specialized foundry groups dominate automotive contract manufacturing, and regional job shops serve aerospace prototype lots. Three archetypes define competitive positioning: captive OEM casting divisions, Tier-1 contract manufacturers with dedicated plant adjacency, and independent specialists in low-volume aerospace and defense programs. Dominant competitive moves include geographic consolidation through facility acquisitions and strategic partnerships for recycling infrastructure access.
Within the integrated primary metal tier, Alcoa Corporation anchors North American supply through captive smelting and recycling infrastructure. Among dedicated automotive contract manufacturers, Nemak S.A.B. de C.V. and Gibbs Die Casting Corp exemplify the plant-proximity model, operating facilities adjacent to Detroit Three assembly complexes. These three entities represent distinct competitive vectors: upstream alloy control, downstream OEM integration, and precision process specialization.
| Leading Market Players |
|---|
| Alcoa Corporation |
| Nemak S.A.B. de C.V. |
| Dynacast |
| Ryobi Limited |
| Consolidated Metco, Inc. |
| DyCast Specialties Corporation |
| Alcast Technologies |
| Gibbs Die Casting Corp |
| Pace Industries |
| Others |
Value Network & Pricing Analysis
EPA CAFE mandates forcing aluminum substitution in vehicle platforms are compressing procurement timelines and compelling foundries to absorb alloy volatility rather than pass through costs. This dynamic concentrates pricing power with OEMs while squeezing margins across Tier-1 contract manufacturers.
Pricing Analysis
Contract-based long-term offtake agreements dominate automotive procurement, with pricing stratifying across premium, standard, and economy tiers based on alloy purity grades and crash certification levels. Price differentiation hinges on vacuum-assisted process premiums versus conventional high-pressure die cast baseline rates. Cost compression in standard-tier transmission housings is intensifying because LME volatility and Midwest premium spikes outpace contract escalation clauses. Fleet procurement teams exhibit highest price sensitivity, while aerospace buyers prioritize defect rates over unit economics.
Supply Chain Analysis
The Inflation Reduction Act's domestic content provisions are reshaping sourcing patterns toward Great Lakes recycling clusters and away from Chinese primary metal dependency. Raw material flows draw from Quebec smelting infrastructure, Mexican border maquiladora recovery operations, and Ohio Valley automotive shredder residue. Supply chain risk centers on alumina refining concentration in Shandong and Guangxi provinces. Distribution runs through dedicated plant-proximity corridors adjacent to Detroit Three assembly complexes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
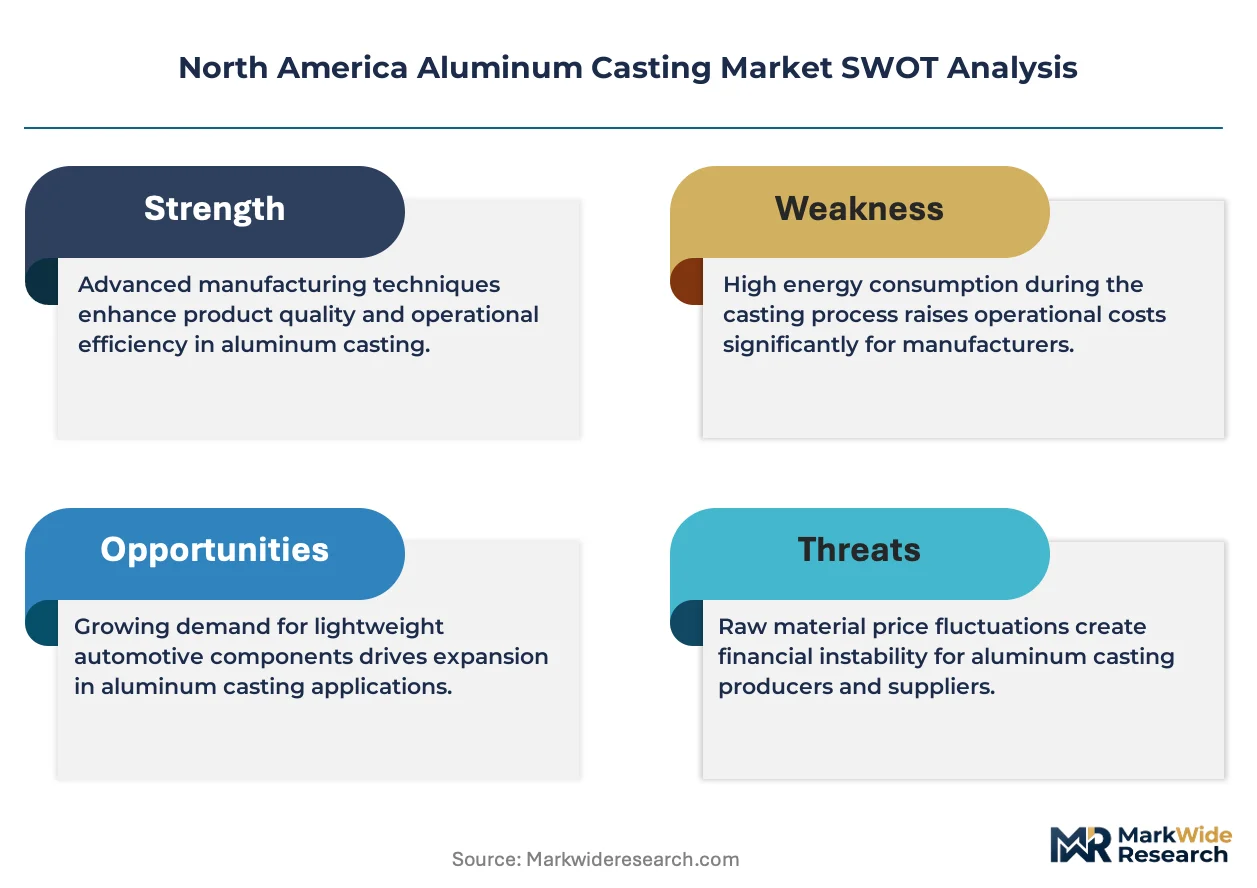
North America aluminum casting functions as a geographic-arbitrage play where Tennessee and Alabama labor cost differentials against Michigan and Ohio create margin expansion opportunities for greenfield investments.
For Market Incumbents: Anchor market position through captive recycling infrastructure investments in the Great Lakes corridor to offset primary aluminum volatility. Secure die maintenance expertise through apprenticeship partnerships with technical colleges before OSHA automation mandates accelerate. Defend against OEM in-house casting reclamation by locking long-term adjacency contracts with transmission housing specifications. For New Entrants and Emerging Players: The premium-to-economy tier price gap in aerospace sand casting offers white-space entry for digital patternless molding specialists. Target California and Washington defense prototyping programs where binder-jetted sand molds compress lead times. Pursue direct qualification pathways with FAA-certified airframe OEMs rather than Tier-1 distributor channels. For Investors and Strategic Acquirers: Asymmetric upside sits with permanent mold casting specialists serving EV battery enclosure demand. Five-to-ten-year viability favors operations with IRA clean energy credit eligibility and documented carbon intensity scores. Monitor EPA-NHTSA joint rulemaking timelines as the inflection signal for accelerated aluminum content minimums.| Strategic Initiative | Industry Significance |
|---|---|
| Recycling Infrastructure Expansion | Captive secondary aluminum recovery reduces LME price exposure across Great Lakes foundry clusters. |
| 3D-Printed Sand Mold Adoption | Binder jetting technology compresses prototype-to-production timelines for aerospace defense programs. |
| Southeastern US Greenfield Capacity | Tennessee and Alabama proximity captures BMW, Mercedes-Benz, and Hyundai-Kia assembly plant demand. |
| Vacuum-Assisted Process Investment | Evacuated mold cavities satisfy OEM crash performance thresholds for safety-critical suspension components. |
| OSHA Compliance Automation | Robotic molten metal handling reduces exposure risks while qualifying facilities for Tier-1 supplier contracts. |
Research Methodology
Direct dialogue with foundry operations managers, OEM platform engineers, Tier-1 procurement leads, and EPA regulatory affairs specialists grounded qualitative insights. Secondary validation drew from SEC 10-K filings, USGS mineral commodity summaries, NHTSA CAFE compliance databases, and automotive production registration data. Bottom-up capacity assessments and top-down demand modeling triangulated volume estimates.
Segment-level outputs across the projection horizon reflect process type, application category, and regional production cluster dimensions. CAGRs were derived from alloy substitution elasticity models tied to EPA fuel economy mandate stringency indices. Forecast inputs incorporated electric vehicle platform aluminum content trajectories and secondary recovery rate assumptions.
Caveats apply where LME price volatility, Chinese export restriction policy shifts, or accelerated OEM in-house casting investments could materially shift the outlook. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Silico Manganese Market
Metals
Asia-Pacific Metallurgical Grade Fluorspar Market
Metals
GCC Aluminium Powder Market
Metals
Steel Salvage Drums Market
Metals
High Purity Boron Market
Metals
Global Aluminium Wire Rod Market
Metals
US Ferrochrome Market
Metals
Global Aluminum Market
Metals
Flat-Rolled Stainless Steel Market
Metals
Welding Materials Market
Metals
Global Tin Market
Metals
Global Superconducting Wire Market
Metals
Powder Metallurgy Market
Metals
Aluminum Flat Products Market
Metals
TMCP Steel Market
Metals
Colloidal Metal Particles Market