
 Global Formulation Additives Market | 2026-2036
Global Formulation Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Global Formulation Additives Market Foresight
Subscription-based technical service and formulation support is expanding what additive suppliers monetize beyond physical product. BASF leverages its global technical centers to embed additive packages into customer co-development workflows. Evonik Industries AG anchors its competitiveness in specialty silica and silane chemistry for coatings and adhesives segments. Dow competes through backward integration into acrylic monomers that feed dispersant and emulsifier production.
Formulation additives are chemical substances incorporated at low loadings, typically below five percent by weight, to modify processing characteristics, end-use performance, or stability of host matrices such as polymers, coatings, or agrochemical preparations. These materials function through surface activity, radical scavenging, plasticization of polymer chains, or particle separation mechanisms to achieve targeted viscosity, durability, or compatibility outcomes. Dispersants and rheology modifiers within paints and coatings applications command the deepest margin pools due to formulation complexity and customer switching costs. Powder and liquid forms dominate volume throughput, though paste concentrates are gaining traction in high-solids industrial coating systems where precise incorporation and reduced solvent content matter.
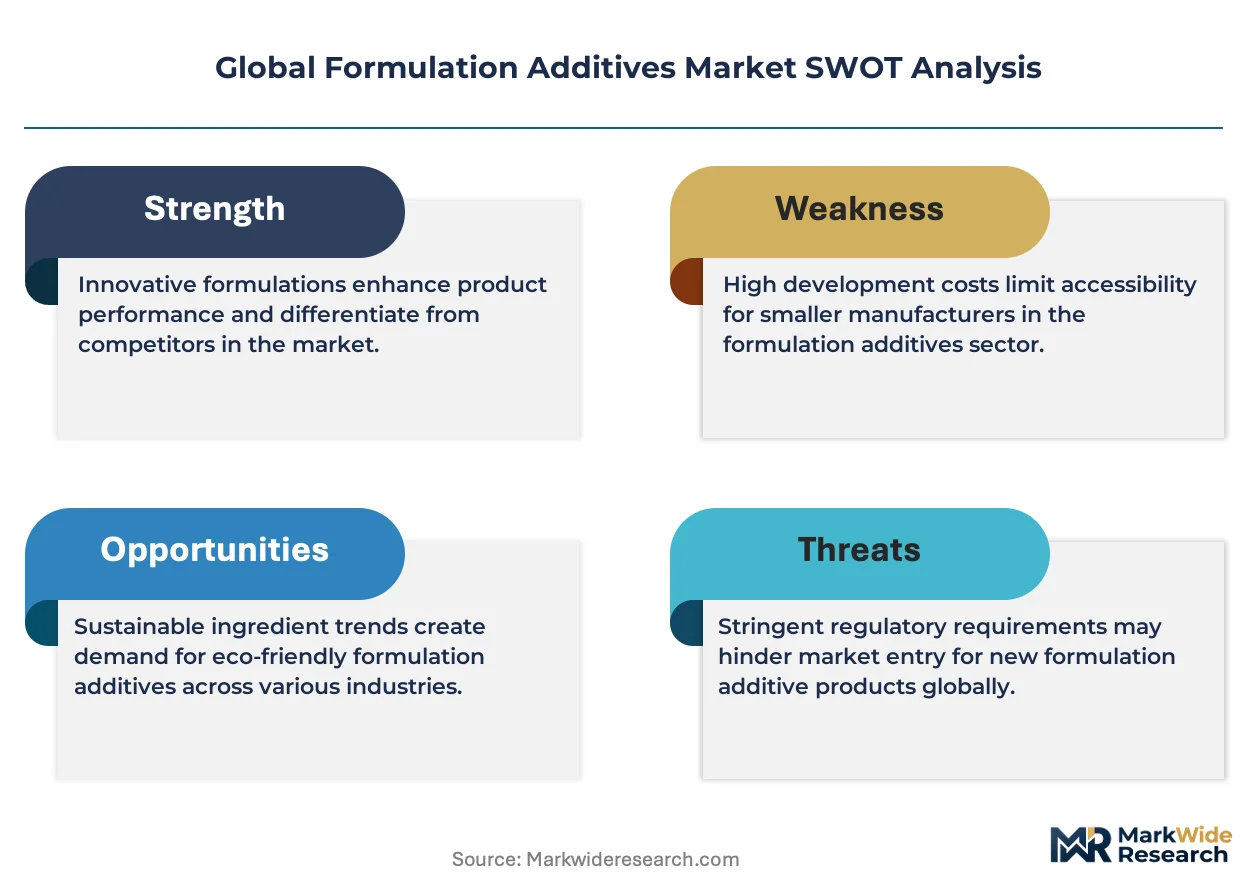
REACH in Europe, EPA chemical management rules in the United States, and China's MEE environmental compliance protocols are collectively elevating documentation burdens and restricting legacy chemistries across adhesive and coatings supply chains. BIS certification requirements in India and GB standard updates in China are further fragmenting market access conditions for imported additive formulations. Stakeholders must monitor regulatory divergence across these jurisdictions to determine where reformulation investments yield priority market access.
Market Dynamics
Additive suppliers face mounting pressure to decouple revenue from physical volume as REACH documentation costs and EPA chemical review timelines compress margins on legacy dispersant chemistries. Technical service bundling and formulation co-development contracts now determine competitive positioning.
Growth Catalysts
- Waterborne coating transitions:Architectural and automotive OEM formulators are substituting solvent-borne systems with high-solids waterborne alternatives, requiring specialized rheology modifiers and wetting agents to maintain film integrity.
- China MEE environmental protocols:Domestic coatings producers must reformulate to meet volatile organic compound thresholds, creating localized demand for compliant dispersant technologies.
- Agrochemical suspension concentrates:Precision agriculture expansion is driving procurement of polymeric dispersants that stabilize active ingredient loading in high-concentration formulations.
Market Restraints
- Petrochemical feedstock volatility:Acrylic acid and ethylene oxide derivatives constitute 40-60% of additive input costs, exposing margin structures to naphtha-cracker output swings.
- Specialty silica supply concentration:Fumed silica for rheology control originates from a narrow supplier base in Germany and Belgium, creating single-source vulnerability for coatings compounders.
- Substitution by bio-based alternatives:Lignin-derived dispersants and plant oil plasticizers are displacing synthetic chemistries in packaging and consumer goods applications.
Strategic Opportunities
- India BIS certification pathways:Imported additive formulations face fragmented compliance requirements across states, rewarding early investment in local testing infrastructure.
- 3D printing photopolymer additives:Photoinitiator synergists and oxygen inhibition suppressants represent unpenetrated white space as industrial resin printing scales.
- EU Green Deal sustainable chemistry mandates:Biodegradable dispersant chemistries qualify for preferential procurement in public infrastructure coatings.
Industry Challenges
- Formulation chemist scarcity:The intersection of polymer science, surface chemistry, and regulatory compliance requires specialized talent that outpaces university pipeline output.
- Multi-jurisdiction dossier management:Maintaining REACH, EPA TSCA, and China MEE registrations simultaneously consumes technical resources and extends product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Formulation Additives Market |
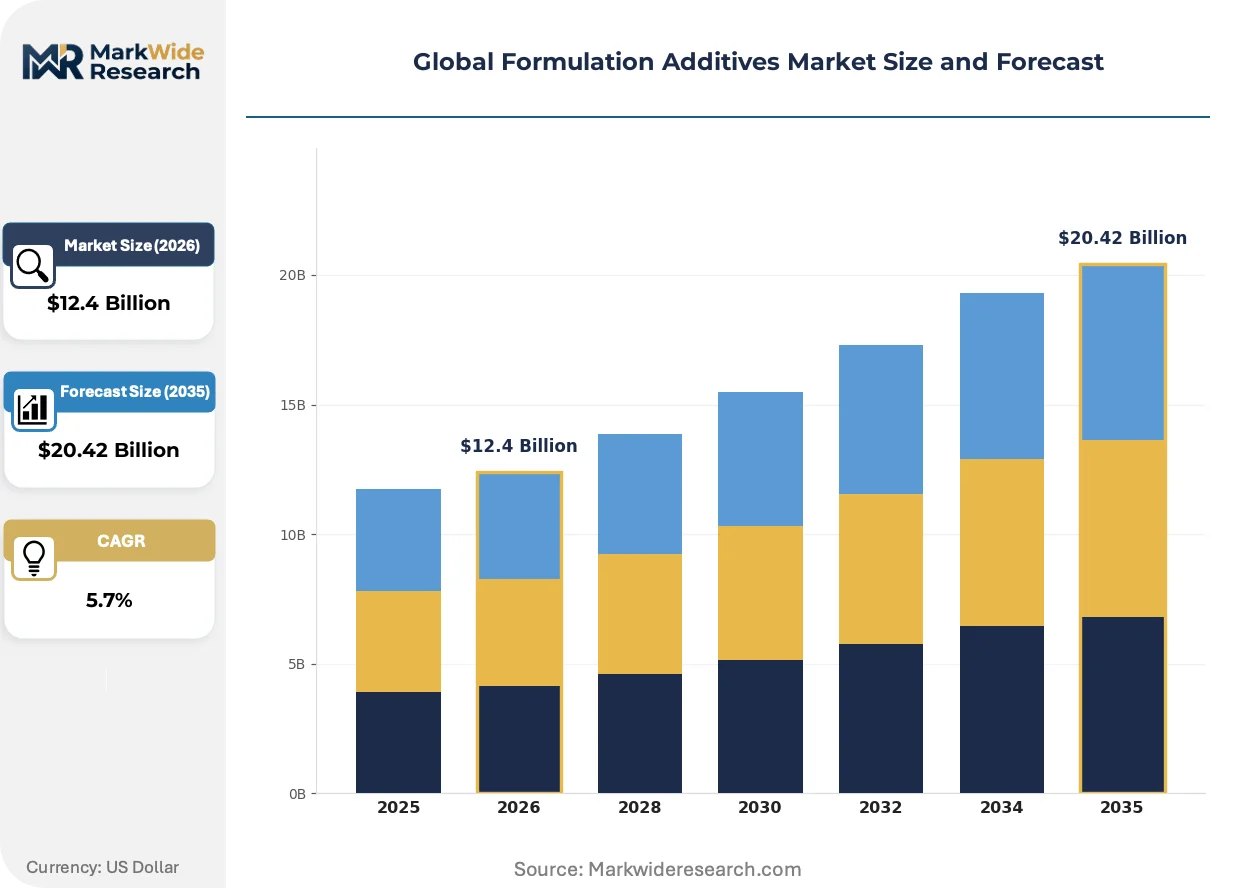
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $20.42 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plasticizers, Stabilizers, Dispersants, Emulsifiers, Antioxidants, Lubricants Form: Powder, Granules, Liquid, Paste, Flakes Application: Paints & Coatings, Adhesives & Sealants, Agrochemicals, Personal Care, Construction Materials End User Industry: Packaging Manufacturers, Textile Processing Units, Chemical Processors, Consumer Goods Producers |
| Companies Covered | BASF, Evonik Industries AG, Dow, Arkema, Eastman Chemical Company, Altana (BYK), Honeywell International, Clariant, Huntsman, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Formulation Additives Market Shifts & Advancements
Digital formulation platforms and predictive compatibility modeling are compressing development cycles, while regulatory chemistry restrictions force molecular redesign across dispersant and stabilizer portfolios.
Hybrid organic-inorganic dispersant architectures are converging with graphene oxide and carbon nanotube surface functionalization to enable stable incorporation of conductive fillers in EMI-shielding coatings. Aerospace and electronics manufacturers are piloting these systems at qualification scale. The technology is converging with automated high-throughput screening to collapse formulation iteration timelines from months to weeks.
REACH authorization requirements for microplastic additives are forcing phase-out of conventional polyethylene and polymethyl methacrylate matting agents in European decorative coatings. Manufacturers must reformulate with biodegradable alternatives or lose market access. The wood and furniture coating segment is absorbing the steepest compliance costs as decorative finish specifications resist performance trade-offs.
Coatings compounders are consolidating supplier relationships around integrated additive package providers who deliver pre-optimized rheology-surfactant-foam control combinations. Regional distributors and independent technical representatives are losing share to direct supplier technical service teams. This consolidation is most visible in China, where domestic coatings producers prefer single-source accountability for formulation performance failures.
Global Formulation Additives Market Segmentation
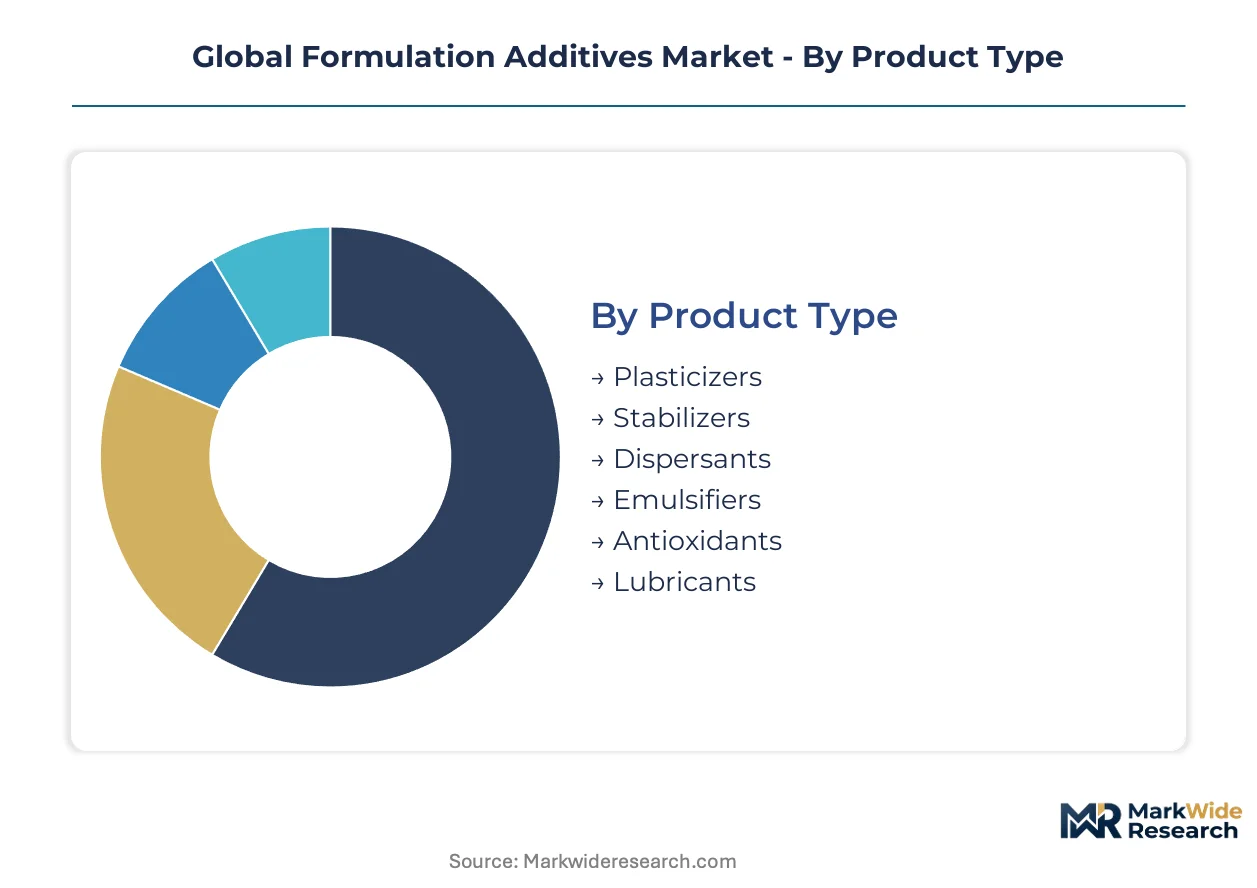
Formulation additive suppliers configure product portfolios around distinct technical specifications and incorporation methods. Each segmentation dimension carries implications for margin structure, regulatory exposure, and customer switching costs across coatings, adhesives, and agrochemical end-uses.
Product Type:
Supply concentration in specialty chemistries determines which product families command pricing power and technical differentiation.
- Dispersants:Polymeric and surfactant-based chemistries stabilize particle suspensions in high-solids coatings and agrochemical concentrates. Demand concentrates in China as domestic coatings producers reformulate under MEE environmental protocols to reduce VOC emissions. REACH documentation costs and EPA chemical review timelines compress margins on legacy acrylic dispersant chemistries.
- Rheology Modifiers:Organoclays, associative thickeners, and fumed silica architectures control viscosity profiles in waterborne architectural and automotive OEM coatings. Formulators in Germany and Belgium face single-source vulnerability for fumed silica feedstocks, elevating procurement risk premiums. Technical service bundling now determines competitive positioning more than commodity pricing.
- Plasticizers:Phthalate and non-phthalate esters modify polymer chain mobility in flexible packaging films and construction membranes.
- Stabilizers:Hindered amine light stabilizers and UV absorbers protect coating films from photodegradation in exterior architectural applications.
- Emulsifiers:Anionic and nonionic surfactants enable stable oil-in-water dispersions in personal care and agrochemical formulations.
- Antioxidants:Phenolic and phosphite chemistries interrupt radical oxidation chains in hot-melt adhesives and polyolefin packaging.
- Lubricants:Fatty acid amides and metallic stearates reduce friction in PVC processing and textile fiber manufacturing.
Today's leader: Dispersants. Tomorrow's challenger: Rheology modifiers.
Form:
Physical state selection trades off incorporation precision against handling economics and solvent content constraints.
- Liquid:Pumpable concentrates dominate high-volume coatings compounding where automated dosing systems require flowable consistency. Waterborne architectural formulators in the United States specify liquid rheology modifiers to maintain film integrity during high-humidity application windows. Paste concentrates are gaining traction in high-solids industrial coating systems where precise incorporation and reduced solvent content matter.
- Powder:Free-flowing particulates serve powder coating manufacturers and dry-mix construction material compounders seeking extended shelf stability. European decorative coatings producers face REACH authorization requirements forcing phase-out of conventional polyethylene matting agents, redirecting procurement toward biodegradable powder alternatives. Powder forms dominate volume throughput in cost-sensitive packaging applications.
- Granules:Dust-reduced agglomerates improve handling safety in large-scale polymer compounding operations.
- Paste:High-solids concentrates enable precise incorporation in solvent-restricted industrial coating formulations.
- Flakes:Low-dust solid forms suit hot-melt adhesive and textile lubricant applications requiring controlled melting profiles.
Liquid forms anchor current volume; paste formats are climbing the fastest as solids regulations tighten.
Application:
End-use performance specifications fragment demand across formulation complexity tiers and regulatory exposure levels.
- Paints & Coatings:Architectural, automotive OEM, and industrial protective segments command the deepest margin pools due to formulation complexity and customer switching costs. Waterborne coating transitions in the United States and Europe require specialized wetting agents and dispersants to maintain film integrity. BASF and Evonik embed additive packages into customer co-development workflows through global technical centers.
- Agrochemicals:Suspension concentrates and emulsifiable concentrates demand polymeric dispersants that stabilize active ingredient loading under variable storage conditions. Precision agriculture expansion in Brazil and Australia drives procurement of high-performance dispersant technologies. Multi-jurisdiction dossier management for REACH, EPA TSCA, and China MEE registrations extends product launch timelines.
- Adhesives & Sealants:Hot-melt, reactive, and waterborne systems require tailored stabilizer and rheology packages.
- Personal Care:Emulsifier and stabilizer specifications emphasize dermatological safety and sensory performance.
- Construction Materials:Cement and gypsum additives modify workability and curing characteristics in mortar and concrete applications.
Paints and coatings dominate value capture; agrochemicals represent the steepest expansion trajectory.
End User Industry:
Customer scale and technical sophistication determine service intensity and contract structuring.
- Packaging Manufacturers:Flexible film and rigid container producers specify plasticizers and stabilizers for food-contact compliance under FDA and EFSA frameworks. Lignin-derived dispersants and plant oil plasticizers are displacing synthetic chemistries in sustainable packaging mandates driven by EU Green Deal procurement preferences. India BIS certification requirements create fragmented compliance conditions for imported additive formulations.
- Chemical Processors:Toll manufacturers and specialty chemical producers procure dispersants and emulsifiers for intermediate formulation steps.
- Textile Processing Units:Dyeing and finishing operations consume lubricants and emulsifiers for fiber handling and color dispersion.
- Consumer Goods Producers:Household and personal care formulators specify cosmetic-grade emulsifiers and stabilizers.
Packaging manufacturers lead procurement scale; chemical processors are gaining share fastest through outsourcing trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's coatings production expansion contrasts with Germany's regulatory-driven reformulation costs, while the United States and India present divergent procurement patterns shaped by environmental enforcement intensity.
China
Domestic coatings manufacturers in the Yangtze River Delta are scaling procurement of compliant dispersant technologies to meet MEE volatile organic compound thresholds. GB standard updates for industrial coatings are tightening permissible additive chemistries in Shanghai and Jiangsu province production clusters. Local additive suppliers in Guangdong province are deepening technical capabilities to capture share from imported formulations.
United States
Architectural formulators specify liquid rheology modifiers to maintain film integrity during high-humidity application windows in the Southeast and Gulf Coast. EPA chemical management rules under TSCA are extending review timelines for legacy dispersant chemistries, compressing margins on established product lines. Coatings compounders in Ohio and Texas are consolidating supplier relationships around integrated additive package providers.
Germany
REACH authorization requirements are forcing phase-out of conventional polyethylene matting agents in decorative coatings manufactured in North Rhine-Westphalia. ECHA documentation burdens are elevating costs for acrylic dispersant chemistries produced in the BASF Ludwigshafen cluster. Specialty silica supply concentration from Belgian and domestic sources creates single-source vulnerability for rheology control in automotive OEM coatings.
India
Packaging manufacturers in Maharashtra and Gujarat face fragmented BIS certification requirements across states for imported additive formulations. FSSAI frameworks for food-contact compliance are redirecting procurement toward plasticizers meeting domestic safety specifications. Domestic coatings producers in Tamil Nadu are reformulating under state-level environmental directives that anticipate national MEE-style protocols.
Brazil
Precision agriculture expansion in São Paulo and Mato Grosso is driving procurement of polymeric dispersants for suspension concentrate formulations. ANVISA registration pathways for agrochemical additives are extending product launch timelines compared to regional benchmarks. Local toll manufacturers in Minas Gerais are absorbing technical service functions previously handled by direct supplier relationships.
Global Formulation Additives Market Competitive Landscape
Top-tier vendors anchor integrated additive package provision, while mid-scale specialists occupy niche chemistries and regional distribution roles. The vendor base stratifies across three tiers: multinational chemical conglomerates with backward integration into monomer feedstocks, specialty silica and silane chemistry houses, and regional formulators with localized regulatory expertise. Dominant competitive moves include technical service bundling into co-development contracts and capacity consolidation around pre-optimized rheology-surfactant combinations.
Within the specialty chemistry tier, Evonik Industries AG and BASF exemplify divergent strategic anchors. Evonik occupies a position centered on silane and silica architectures for coatings and adhesives applications, while BASF leverages global technical center networks to embed additive packages into customer workflows. Dow represents the backward-integrated archetype, with captive acrylic monomer production feeding dispersant and emulsifier manufacturing. These three entities collectively illustrate how feedstock control, technical service intensity, and molecular specialization define competitive positioning in this market.
| Leading Market Players |
|---|
| BASF |
| Evonik Industries AG |
| Dow |
| Arkema |
| Eastman Chemical Company |
| Altana (BYK) |
| Honeywell International |
| Clariant |
| Huntsman |
| Others |
Supply & Pricing Matrix
EU Green Deal sustainable chemistry mandates gate qualified supply and premium-tier pricing access for biodegradable dispersant formulations, forcing coatings compounders to absorb compliance premiums or surrender market access in European public infrastructure procurement.
Pricing Analysis
Capacity additions in China are reshaping price floors for standard-grade acrylic dispersants as domestic producers achieve technical parity with imported formulations. Three-tier pricing structure across REACH-compliant premium, standard industrial, and economy grades reflects certification burden and technical service bundling. Cost compression in legacy dispersant tiers is intensifying because EPA chemical review timelines extend product launch cycles. Small-scale agrochemical formulators exhibit highest price sensitivity; automotive OEM coatings buyers prioritize performance consistency over unit cost.
Supply Chain Analysis
Direct-to-coatings-compounder channels handle technical service-intensive demand while regional distributors serve price-sensitive packaging manufacturers. Feedstock supply concentrates in Germany, Belgium, and China for fumed silica and acrylic acid derivatives. Raw material dependencies rest on ethylene oxide, naphtha-cracker output, and organoclay feedstocks. Single-source vulnerability for specialty silica from German and Belgian producers elevates procurement risk premiums. Distribution runs through integrated additive package providers consolidating rheology-surfactant-foam control combinations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Formulation Additives Market functions as a stable compounder anchored by regulatory-driven reformulation cycles that perpetually refresh demand for compliant chemistries.
For Market Incumbents: Deepen technical service bundling into long-term co-development contracts to lock switching costs against emerging local suppliers in Guangdong province. Anchor backward integration into acrylic monomer production to defend margin position against feedstock volatility. Prioritize REACH pre-registration of biodegradable dispersant architectures ahead of polyethylene matting agent phase-outs. For New Entrants and Emerging Players: Enter via 3D printing photopolymer additive segments where photoinitiator synergists remain unpenetrated white space with minimal incumbent technical service coverage. Target India BIS certification pathways for plasticizer formulations serving Maharashtra packaging manufacturers. Pursue toll manufacturing partnerships to bypass direct multi-jurisdiction dossier management burdens. For Investors and Strategic Acquirers: Roll-up economics work for specialty silica and silane chemistry houses because supply concentration in Germany and Belgium creates scarcity value for qualified production assets. Five-to-ten year viability hinges on regulatory chemistry restriction trajectories across REACH, EPA TSCA, and China MEE frameworks. Monitor GB standard update announcements as inflection indicators for China domestic supplier capability maturation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Monomers | Dow's captive feedstock supply insulates margin structures from naphtha-cracker volatility. |
| Technical Service Center Expansion | BASF's global technical center network embeds additive packages into customer co-development workflows. |
| Biodegradable Dispersant R&D Investment | EU Green Deal procurement preferences reward early movers in polyethylene matting agent replacements. |
| India BIS Certification Infrastructure | Early local testing investment captures share as Maharashtra and Gujarat packaging manufacturers consolidate suppliers. |
| Specialty Silica Supply Agreement | Evonik's silane and silica architectures command scarcity premiums amid Belgian-German supply concentration. |
Research Methodology
Multiple input streams — primary interviews with coatings formulators, agrochemical R&D directors, and procurement leads at packaging manufacturers; secondary validation through ECHA registration databases, EPA TSCA filings, and customs/trade data; plus ACC and Cefic industry reports — were reconciled through bottom-up and top-down triangulation.
Historical volume trajectories were cross-referenced against expert panel inputs to construct analytical frameworks across product type, application, form, and regional production hub dimensions. CAGRs were derived from segmented growth rate reconciliation against macroeconomic drivers. Forecast inputs incorporated MEE environmental protocol enforcement intensity, REACH authorization timelines, and waterborne coating transition penetration curves.
The model holds under stable regulatory enforcement intensity; deviation in EPA chemical review acceleration or China MEE threshold tightening would shift trajectory. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Automotive Additives Market
Additives
Binder Excipients Market
Additives
Global Asphalt Additives Market
Additives
Feed Additive Nosiheptide Premix Market
Additives
Refinery Process Additives Market
Additives
Surface Modifiers Market
Additives
Organic Friction Modifier Additives Market
Additives
Maltitol Based on Corn Starch Market
Additives
Flux Injection System Market
Additives
Europe Fuel Additives Market
Additives
Dispersing Agents Market
Additives
Refining Additives Market
Additives
Global Peptone Market
Additives
Indonesia Feed Additives Market
Additives
United States Betaine Market
Additives
Global UV Stabilizers Market