
 Medical Ceramics Market | 2026-2036
Medical Ceramics Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Ceramics Market Intelligence
Implant surface treatment services is expanding as a distinct revenue layer beyond device sales, with manufacturers bundling bioactive coatings and patient-specific finishing into long-term supply contracts. CeramTec GmbH leverages its German production base to dominate medical-grade alumina supply for hip bearings. Stryker Corporation sustains R&D intensity across its ceramics portfolio through captive research facilities in Michigan and Ireland. Kyocera Corporation anchors Japanese supply of fine ceramic components for dental and orthopedic applications through vertically integrated manufacturing in Kyoto.
Medical ceramics are inorganic, non-metallic materials—principally alumina, zirconia, and hydroxyapatite—processed through high-temperature sintering to achieve biocompatibility, wear resistance, and osseointegration for permanent implantation in the human body. Advanced sintering protocols achieve sub-micron grain structures that reduce fracture risk under cyclic loading. Ceramic implants command premium positioning in orthopedics due to superior wear characteristics against polyethylene liners, while dental ceramics driven by CAD/CAM chairside milling are displacing metal-ceramic restorations in aesthetic applications. Bioceramics for bone graft substitutes represent the fastest-growing product category as synthetic hydroxyapatite formulations replace autograft harvesting.
The FDA's 510(k) premarket notification and the EU MDR's tightened clinical evidence requirements for Class III implantable devices are extending development timelines and consolidating regulatory expertise among larger manufacturers. ISO 13356 for surgical-grade zirconia and ASTM F603 for alumina ceramics establish material benchmarks that shape procurement specifications across hospitals and orthopedic centers. Stakeholders must monitor how the EU AI Act's risk classification framework applies to machine-learning-enabled CAD/CAM design tools that generate patient-specific ceramic implant geometries.
Market Dynamics
Orthopedic implant manufacturers are consolidating ceramic supply chains around German and Japanese production clusters as FDA 510(k) and EU MDR timelines extend, creating captive sourcing advantages for vertically integrated producers.
Growth Catalysts
- EU MDR clinical evidence mandates:Tightened biocompatibility documentation for Class III implants is accelerating hospital procurement of pre-certified ceramic components from established suppliers.
- Hydroxyapatite bone graft substitutes:Synthetic bioceramics are displacing autograft harvesting in spinal fusion and trauma reconstruction, reducing surgical morbidity and operating time.
- CAD/CAM chairside milling:Dental clinics are adopting same-day zirconia crown production, compressing laboratory turnaround from two weeks to under two hours.
Market Restraints
- Yttria-stabilized zirconia powder concentration:Five specialized chemical processors control global supply of medical-grade feedstock, creating input cost volatility and qualification barriers for new entrants.
- FDA 510(k) pathway friction:Predicate device requirements for ceramic-on-ceramic hip bearings are narrowing acceptable design modifications and extending premarket review cycles.
- 3D-printed titanium lattice structures:Additive manufacturing of porous metal implants is capturing patient-specific orthopedic applications where ceramics lack design flexibility.
Strategic Opportunities
- Brazil ANVISA accelerated pathway:Emerging market regulators are adopting abbreviated review frameworks for materials with established FDA or EMA clearance, opening Latin American hospital procurement.
- AI-enabled implant design tools:Machine learning algorithms for patient-specific geometry generation are converging with ceramic milling workflows, creating software-service revenue layers beyond device sales.
- Bioceramic-coated metal implants:Hybrid constructs combining titanium structural cores with hydroxyapatite surface layers are penetrating trauma and extremity applications previously closed to monolithic ceramics.
Industry Challenges
- ISO 13356 certification timelines:Surgical-grade zirconia qualification requires 18-24 months of biocompatibility and mechanical testing, compressing product launch windows against faster-evolving polymer alternatives.
- High-temperature sintering furnace capacity:Sub-micron grain structure production demands specialized thermal processing equipment with 36-month lead times, constraining volume scaling for mid-tier manufacturers.
- Legacy ERP integration with digital dentistry workflows:Dental laboratory management systems require costly middleware development to connect chairside scanners with centralized ceramic milling center scheduling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Ceramics Market |
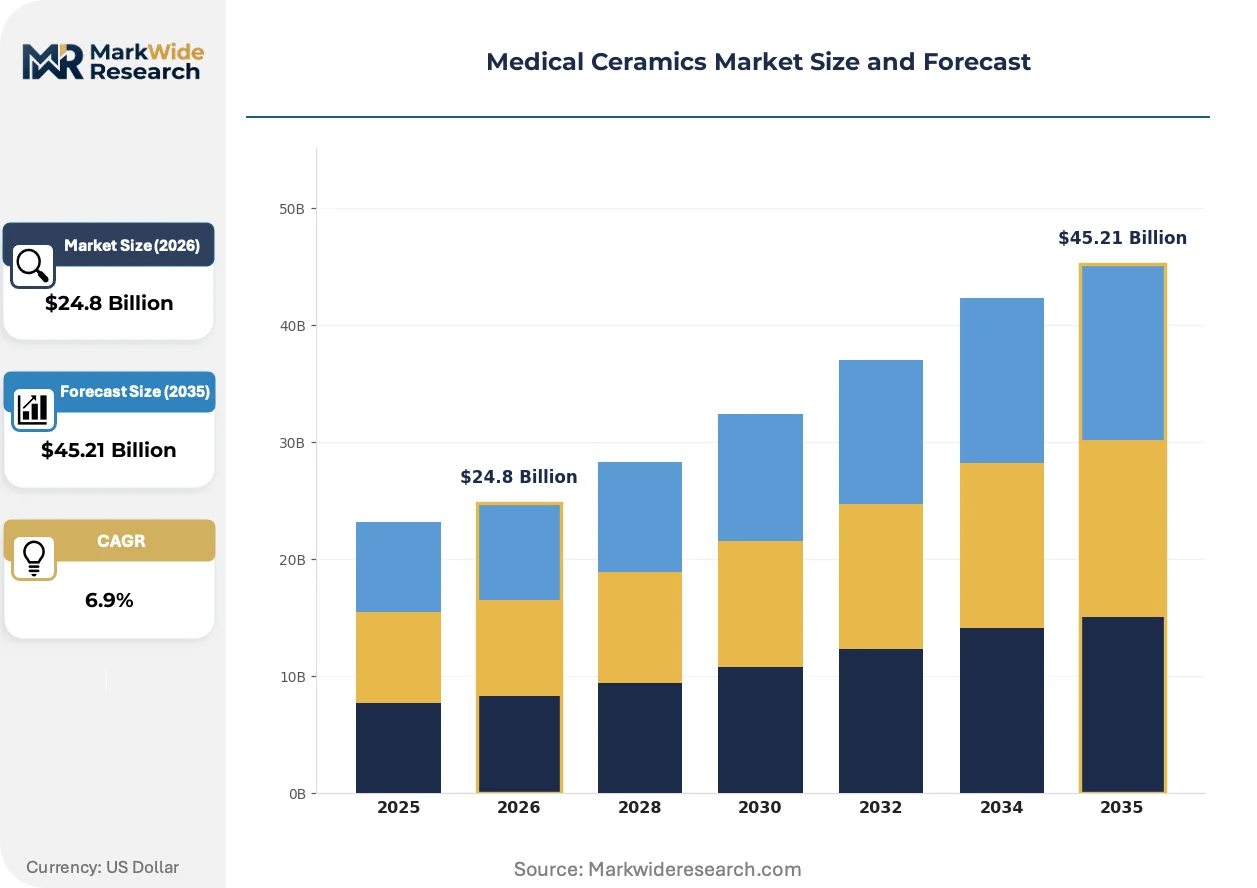
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $45.21 Billion |
| CAGR (2026 – 2036) | 6.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ceramic Implants, Bioceramics, Dental Ceramics, Zirconia Application: Orthopedics, Dentistry, Cardiovascular, Prosthetics End User: Hospitals, Dental Clinics, Orthopedic Centers, Research Labs Technology: CAD/CAM, 3D Printing, Advanced Sintering, Surface Treatments |
| Companies Covered | Morgan Advanced Materials, Zimmer Biomet Holdings, Inc., CeramTec GmbH, Stryker Corporation, DePuy Synthes, Kyocera Corporation, 3M, NGK Spark Plug Co., Ltd., CoorsTek, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Ceramics Market Strategic Shifts & Innovations
Medical ceramics manufacturing is fragmenting into modular, distributed production nodes as regulatory compliance costs and patient-specific demand reshape traditional centralized supply models.
Additive manufacturing of ceramic implants is modularizing production economics for complex geometries. Academic medical centers and specialized contract manufacturers are adopting lithography-based ceramic printing for craniofacial reconstruction and dental abutments. This technology is modularizing what were previously five-step machining and sintering sequences into single-build processes, compressing lead times and enabling batch-size-one economics without tooling changeover costs.
REACH authorization requirements for yttrium oxide nanoparticles are tightening traceability obligations across European ceramic supply chains. The industrial consequence is mandatory upstream documentation from powder processors through finished device sterilization. Hip and knee bearing manufacturers with German production bases are responding by consolidating yttria sourcing to two qualified suppliers with established ECHA dossier compliance.
Hospital procurement committees are consolidating orthopedic implant contracts around suppliers offering bundled ceramic bearing warranties and revision surgery cost guarantees. Group purchasing organizations are displacing individual surgeon preference contracts with standardized ceramic-on-polyethylene specifications across health system networks. This concentration is most visible in US integrated delivery networks where Medicare bundled payment programs align device selection with episode cost accountability.
Medical Ceramics Market Segmentation
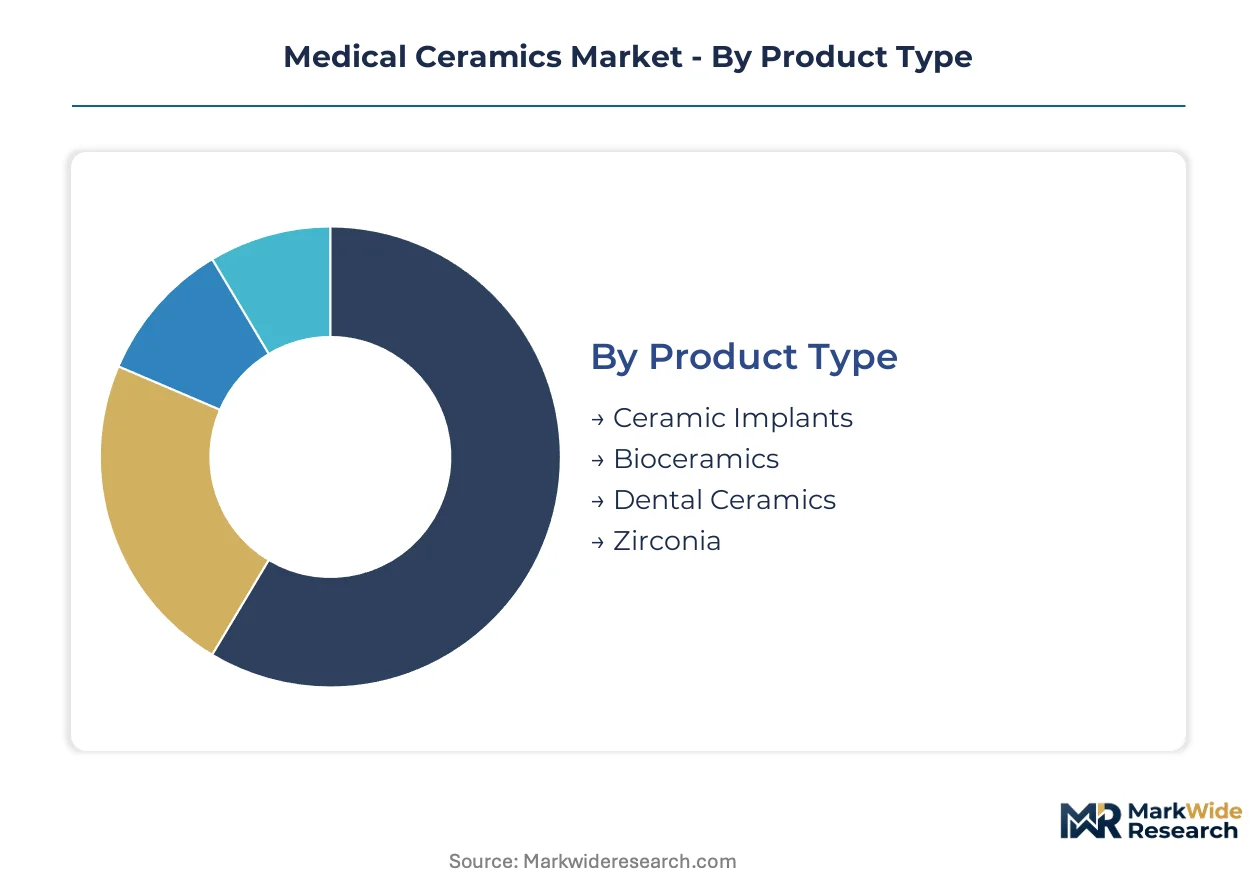
Medical ceramics segmentation reveals how supply chain concentration and regulatory pathways shape competitive positioning across product categories. Distinct technical specifications and end-use requirements create natural market boundaries that manufacturers navigate through specialized production investments.
Product Type:
Supply concentration around German and Japanese production clusters favors established categories with validated sintering protocols and ISO certification histories.
- Ceramic Implants:High-purity alumina and zirconia monoblock components for permanent skeletal replacement. Hip and knee bearing demand concentrates in US integrated delivery networks and German orthopedic centers where Medicare bundled payments and statutory health insurance reimbursement align procurement with wear-performance guarantees.
- Bioceramics:Synthetic hydroxyapatite and tricalcium phosphate formulations for bone graft substitutes. Spinal fusion applications in US hospital systems and trauma reconstruction in European university hospitals are displacing autograft harvesting as synthetic osseointegration performance improves.
- Dental Ceramics:Chairside-milled zirconia and lithium disilicate for crown and bridge restorations. Japanese and German dental laboratory networks dominate precision finishing capacity.
- Zirconia:Yttria-stabilized tetragonal polycrystal feedstock for bearing surfaces and dental frameworks. Five specialized chemical processors control medical-grade powder supply, creating qualification barriers for new device entrants.
Today's leader: Ceramic Implants. Tomorrow's challenger: Bioceramics.
Application:
Cost tier stratification separates premium permanent implants from consumable restorative materials, with reimbursement pathways determining viable price points.
- Orthopedics:Load-bearing hip and knee bearings, spinal spacers, and trauma fixation components. US Medicare bundled payment programs and German Diagnosis-Related Group reimbursement concentrate hospital procurement around ceramic-on-polyethylene and ceramic-on-ceramic bearing warranties.
- Dentistry:Aesthetic and functional restorations including crowns, bridges, veneers, and implant abutments. CAD/CAM chairside milling adoption in Japanese and US dental clinics compresses laboratory turnaround from weeks to hours.
- Cardiovascular:Pacemaker encapsulation and implantable sensor housings. Specialized alumina formulations serve niche demand from US and European device manufacturers with captive ceramic supply agreements.
- Prosthetics:Socket liners and limb component coatings. Hybrid ceramic-coated titanium structures penetrate applications where monolithic ceramics lack design flexibility for patient-specific geometry.
Orthopedics commands premium positioning. Dentistry delivers volume scale through CAD/CAM adoption curves.
End User:
Customer type determines specification stringency, with hospitals demanding full Class III implant documentation and dental clinics prioritizing chairside workflow integration.
- Hospitals:Acute care systems and specialty surgical centers performing joint replacement and spinal fusion. US integrated delivery networks and German university hospitals consolidate procurement through group purchasing organizations that standardize ceramic bearing specifications.
- Dental Clinics:Private practices and dental service organizations adopting in-house milling capabilities. Japanese and US markets lead intraoral scanner and chairside sintering furnace installation.
- Orthopedic Centers:Ambulatory surgery facilities focused on joint replacement and sports medicine. Outpatient migration in US markets creates demand for streamlined implant inventory with rapid revision surgery logistics.
- Research Labs:Academic medical centers and contract research organizations conducting biocompatibility studies and next-generation material development. EU MDR clinical evidence mandates expand toxicology and mechanical testing service demand.
Hospitals anchor revenue concentration. Dental clinics drive unit volume expansion through workflow automation.
Technology:
Manufacturing maturity separates established high-temperature sintering from emerging additive methods, with capital intensity and regulatory qualification timelines determining adoption pace.
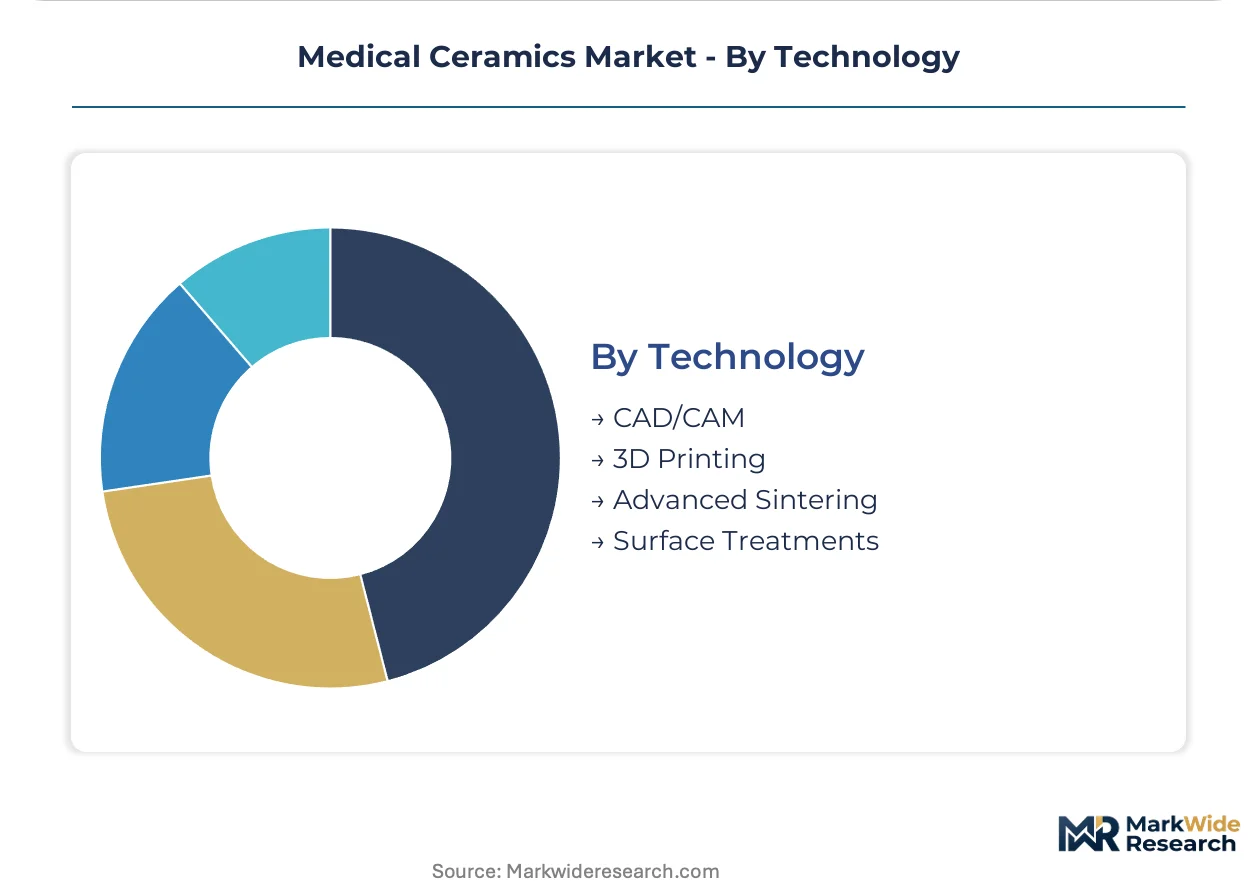
- CAD/CAM:Computer-aided design and manufacturing systems for patient-specific geometry generation and automated milling. Dental applications in German and Japanese markets achieve sub-24-hour crown production through integrated scanner-milling workflows.
- 3D Printing:Lithography-based ceramic manufacturing for complex geometries including craniofacial reconstruction and dental abutments. Academic medical centers and specialized contract manufacturers adopt single-build processes that eliminate multi-step machining sequences.
- Advanced Sintering:High-temperature thermal processing achieving sub-micron grain structures for mechanical reliability. Specialized furnace capacity with 36-month lead times constrains volume scaling for mid-tier manufacturers.
- Surface Treatments:Bioactive coating application including hydroxyapatite plasma spraying and ion beam-assisted deposition. Hybrid ceramic-coated metal implants penetrate trauma applications previously closed to monolithic ceramics.
Advanced Sintering retains process control. 3D Printing reshapes geometric possibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands denser medical-grade ceramics production infrastructure than the United States, though American hospital procurement volumes exceed European totals. Japanese manufacturers retain tighter vertical integration across dental ceramic workflows than competitors in either Western market.
United States
Medicare bundled payment programs for joint replacement episodes concentrate hospital procurement around ceramic bearing suppliers offering revision surgery cost guarantees. The FDA's 510(k) premarket notification pathway extends review cycles for ceramic-on-ceramic hip designs lacking suitable predicate devices. Michigan and Massachusetts host captive R&D facilities where major orthopedic manufacturers develop next-generation bearing surfaces.
Germany
Statutory health insurance reimbursement through Diagnosis-Related Group classifications aligns hospital procurement with wear-performance guarantees for ceramic implants. The EU Medical Device Regulation's tightened clinical evidence mandates for Class III devices accelerate demand for pre-certified components from established suppliers. Stuttgart and Cologne anchor concentrated production clusters for medical-grade zirconia and alumina feedstock processing.
Japan
PMDA marketing authorization pathways for permanent implantable devices favor manufacturers with established ISO 13356 certification histories for surgical-grade zirconia. METI industrial policy supports domestic production of fine ceramic components through targeted R&D subsidies. Kyoto-based manufacturers maintain vertically integrated production from powder synthesis through finished dental and orthopedic components.
China
NMPA regulatory reforms for imported Class III implants create qualification barriers for foreign ceramic bearing manufacturers while accelerating domestic substitution programs. Provincial healthcare procurement centralization in Jiangsu and Guangdong standardizes implant specifications across hospital networks. Yangtze River Delta manufacturing clusters expand hydroxyapatite bone graft substitute production for spinal fusion applications.
Brazil
ANVISA's accelerated review pathway for materials with established FDA or EMA clearance opens Latin American hospital procurement to pre-certified ceramic component suppliers. Private health insurance expansion in São Paulo and Rio de Janeiro drives demand for premium orthopedic implants with ceramic bearing surfaces. Regional distributors consolidate inventory positions for dental ceramics amid chairside milling adoption in major metropolitan clinics.
Medical Ceramics Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with consolidated supply chains around German and Japanese production clusters favoring established incumbents. The vendor base organizes into three strategic archetypes: vertically integrated material-to-device producers, specialized ceramic component suppliers, and diversified orthopedic conglomerates with captive ceramics divisions. Capacity expansion in high-temperature sintering furnaces and strategic partnerships for yttria-stabilized zirconia feedstock sourcing represent dominant competitive moves.
Among Germany-based specialists, CeramTec GmbH and Morgan Advanced Materials occupy positions reflecting deep ceramic processing heritage. Stryker Corporation exemplifies the diversified orthopedic conglomerate archetype with integrated ceramics capabilities. These three entities represent distinct strategic postures: specialized feedstock control, advanced material formulation, and end-to-end implant system integration.
| Leading Market Players |
|---|
| Morgan Advanced Materials |
| Zimmer Biomet Holdings, Inc. |
| CeramTec GmbH |
| Stryker Corporation |
| DePuy Synthes |
| Kyocera Corporation |
| 3M |
| NGK Spark Plug Co., Ltd. |
| CoorsTek, Inc. |
| Others |
Cost & Logistics Intelligence
Specialized sintering furnace operators in Germany's Stuttgart corridor command wage premiums that widen spreads between ISO-certified premium bearings and standard-grade hospital contract tiers.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for hydroxyapatite bone graft substitutes. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared ceramic-on-ceramic bearings from CE-marked standard implants and uncoated economy grades. Cost compression in dental zirconia blocks intensifies as chairside milling adoption accelerates in Japanese clinics. Group purchasing organizations demonstrate highest price sensitivity, while academic medical centers prioritize wear-performance guarantees over unit cost.
Supply Chain Analysis
Regional distribution centers in Cologne, Kyoto, and Michigan operate hub-and-spoke patterns for just-in-time hospital inventory. Supply concentrates in Germany, Japan, and the United States for medical-grade alumina and yttria-stabilized zirconia feedstock. Raw material dependencies rest on yttrium oxide nanoparticles, high-purity alumina powder, and synthetic hydroxyapatite precursors. Single-source vulnerability in yttria-stabilized tetragonal polycrystal powder creates qualification barriers for new device entrants. Distribution runs through orthopedic manufacturer direct sales forces and dental laboratory service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Medical ceramics offers margin-expansion potential as synthetic hydroxyapatite formulations displace autograft harvesting, compressing surgical morbidity costs into premium pricing power.
For Market Incumbents: Acquire high-temperature sintering furnace capacity with sub-micron grain structure certification to defend against additive manufacturing of porous titanium lattice structures. Consolidate yttria feedstock sourcing to qualified suppliers with established ECHA dossier compliance. Lock in long-term supply contracts with German and Japanese production clusters before EU MDR clinical evidence mandates extend qualification timelines.
For New Entrants and Emerging Players: AI-enabled patient-specific geometry generation offers technology-first wedge into dental CAD/CAM software services where incumbent device manufacturers lack computational expertise. Target bioceramic-coated metal hybrid constructs for trauma applications previously closed to monolithic ceramics. Pursue ANVISA accelerated pathway clearance for Brazilian private health insurance networks as the most penetrable geographic entry point.
For Investors and Strategic Acquirers: Diversified orthopedic conglomerates with captive ceramics divisions are the most active acquirer in this space, seeking specialized feedstock control and ISO 13356 certification histories. Mid-tier manufacturers with advanced sintering protocols but constrained furnace scaling capacity represent prime acquisition archetypes. Monitor REACH authorization timelines for yttrium oxide nanoparticles as the signal indicating consolidation pressure on European supply chains.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Yttria Feedstock | Secures supply of medical-grade powder from ECHA-compliant German chemical processors. |
| ISO 13356 Certification Investment | Accelerates PMDA marketing authorization for Japanese orthopedic center procurement. |
| CAD/CAM Software Companion Development | Captures recurring revenue from dental clinic chairside milling workflow integration. |
| Hospital System Partnership | Aligns ceramic bearing warranties with Medicare bundled payment episode accountability. |
| Bioceramic Surface Treatment Scale-Up | Enables hybrid titanium-ceramic constructs for trauma applications lacking monolithic flexibility. |
Research Approach
Multiple input streams — hospital procurement database analysis, GPO contract documentation, and regulatory filing review — were reconciled against primary interviews with orthopedic implant development executives, biomedical engineers at academic medical centers, dental laboratory operations managers, and ceramics R&D directors. Secondary validation drew from FDA 510(k) premarket notification databases, EU MDR technical documentation summaries, ISO 13356 certification registries, and hospital Diagnosis-Related Group reimbursement schedules. Bottom-up volume modeling and top-down market sizing were triangulated to constrain estimate variance.
Historical volume trajectories were cross-referenced against expert panel assessments of EU MDR implementation pace and CAD/CAM adoption curves across the projection horizon. Segmentation dimensions modeled include product type, application, end user, and technology with regional production hub differentiation. CAGRs were derived from slope analysis of validated data points rather than extrapolation. Industry-specific forecast inputs encompassed sintering furnace capacity expansion announcements and yttria powder processor qualification timelines.
The model holds under stable regulatory enforcement timelines; deviation in EU MDR clinical evidence mandate stringency or REACH authorization scope would shift volume trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Kaolin Market
Ceramics
Electronics Ceramics and Electrical Ceramics Market
Ceramics
Aluminium Nitride Market
Ceramics
Ceramic Binders Market
Ceramics
North America Barium Carbonate Market
Ceramics
Ceramic Substrate Market
Ceramics
East Africa Ceramic Tiles Market
Ceramics
Ceramic Injection Molding Market
Ceramics
Global Wollastonite Powder Market
Ceramics
Pottery Ceramics Market
Ceramics
Europe Ceramic Tiles Market
Ceramics
Polymer-Derived Ceramics Market
Ceramics
Colloidal Alumina Market
Ceramics
United Kingdom Ceramic Tiles Market
Ceramics
Global Zirconia Oxygen Sensors Market
Ceramics
Quartz Powder Market