
 South America Metal Finishing Market | 2026-2036
South America Metal Finishing Market Size, Share, and Industry Trends Forecast 2026-2036
South America Metal Finishing Market Analytics
Electrochemical coating automation is tilting process economics toward precision-controlled deposition lines. Chemetall GmbH leverages its pretreatment chemical portfolio to anchor automotive OEM relationships across Brazil. POSCO competes through integrated stainless supply chains that extend into finished coil products. Linde plc dominates industrial gas delivery for thermal spraying operations in the region.
Metal finishing encompasses surface modification processes—plating, coating, anodizing, and polishing—that alter substrate properties through electrochemical, thermal, mechanical, or chemical means, typically achieving thickness tolerances from 0.1 to 100 micrometers to enhance corrosion resistance, electrical conductivity, or aesthetic appearance. Plating retains the largest revenue share due to its entrenched role in electronics and automotive connector manufacturing, while thermal spraying technology captures expanding demand from aerospace maintenance operations seeking wear-resistant turbine coatings. Chemical processes command premium margins in medical device applications where biocompatibility certification constrains supplier pools.
Brazil's IBAMA enforcement and Argentina's Secretariat of Environment and Sustainable Development impose wastewater discharge limits that force process chemistry substitutions. ANVISA regulates surface treatments for medical device applications through Good Manufacturing Practice inspections. Stakeholders must monitor how evolving Mercosur environmental harmonization affects cross-border process standardization and supplier qualification requirements.
Market Dynamics
REACH-aligned chemical restrictions are forcing wholesale process chemistry substitutions across Brazilian and Argentinian plating operations, compressing profit margins for mid-tier job shops while advantaging integrated chemical suppliers with compliant formulations.
Growth Catalysts
- Automotive OEM demand:Brazil's vehicle manufacturers are mandating advanced coating systems for corrosion-resistant chassis components, pulling volume through São Paulo state's supplier network.
- IBAMA wastewater enforcement:Stricter discharge limits are accelerating capital deployment into closed-loop water treatment systems, creating pull for process equipment upgrades.
- Thermal spraying adoption:Aerospace maintenance operations in Argentina are specifying wear-resistant turbine coatings, expanding addressable market for high-velocity oxy-fuel application services.
Market Restraints
- Pretreatment chemical cost volatility:Chrome-free conversion coating feedstocks face supply concentration from German and US specialty chemical producers, exposing Brazilian finishers to currency-driven input cost spikes.
- Technical limitation in thin-film precision:Medical device applications requiring sub-5-micrometer tolerance plating remain constrained by limited local ionic liquid process expertise.
- Mercosur harmonization friction:Divergent national implementation timelines for cross-border environmental standards create qualification complexity for multi-country suppliers.
Strategic Opportunities
- Chilean mining equipment aftermarket:Copper and lithium extraction machinery in Antofagasta and Atacama regions generates unmet demand for hard chrome alternatives on hydraulic cylinder rods.
- ANVISA biocompatibility certification:Medical device surface treatment mandates create premium-margin service opportunities for ISO 13485-qualified job shops.
- Electropolishing-automation convergence:Robotic handling integration with precision electrolytic polishing is opening batch-size flexibility for orthopedic implant contract manufacturers.
Industry Challenges
- Electrochemist skill scarcity:Qualified bath chemistry technicians with plating process control expertise command wage premiums that compress job shop economics.
- Legacy ERP integration complexity:Process data historians from 1990s-vintage lines resist interoperability with modern environmental compliance reporting platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Metal Finishing Market |
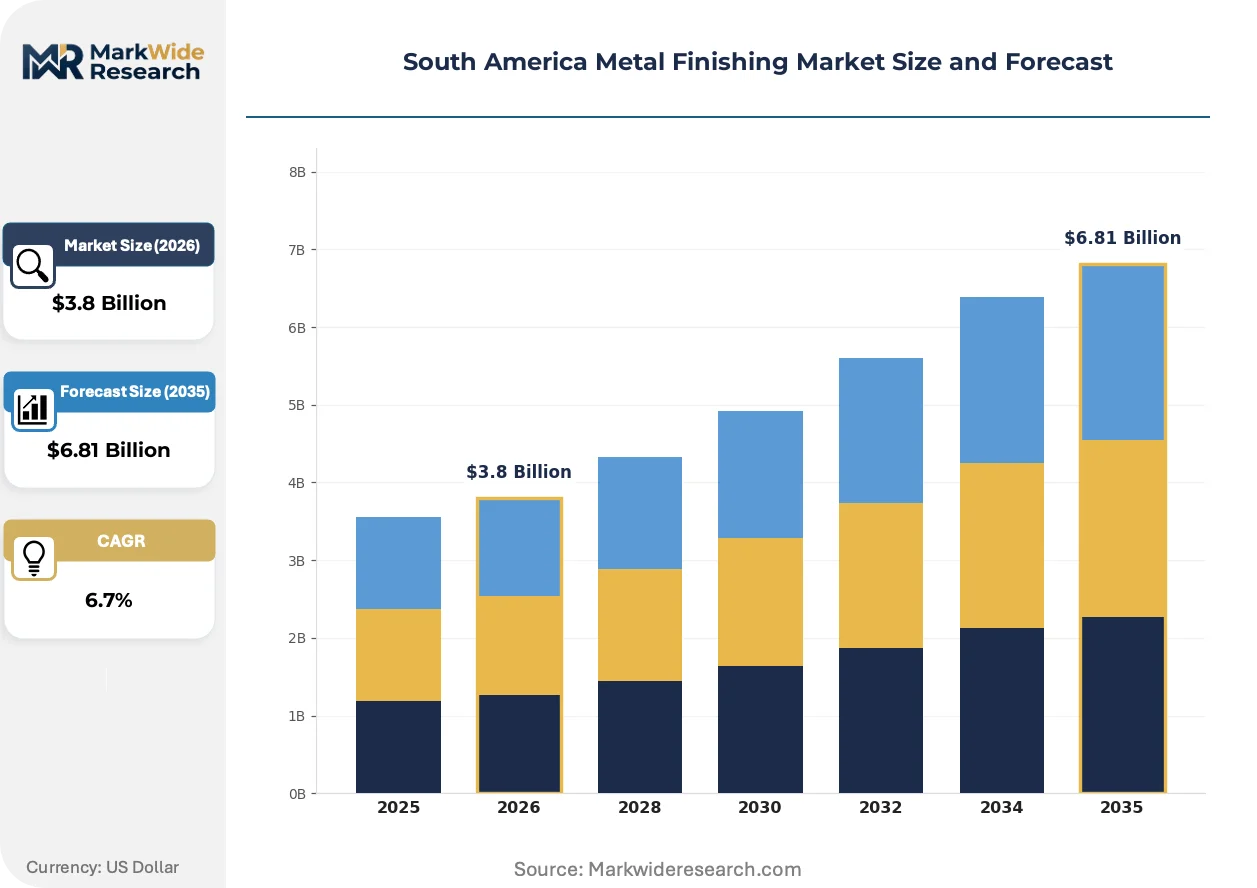
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plating, Coating, Anodizing, Polishing Technology: Electrochemical, Thermal Spraying, Mechanical, Chemical End User: Aerospace, Automotive, Electronics, Construction Application: Consumer Goods, Industrial Equipment, Medical Devices, Aerospace Components |
| Companies Covered | Chemetall GmbH, POSCO, Honeywell International Inc., Giant Finishing Inc., TIB Chemicals AG, Linde plc, ELEMENTIS PLC, ArcelorMittal, OC Oerlikon Management AG, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Metal Finishing Market Evolving Landscape
Automation and environmental compliance are converging to reshape competitive economics across South American surface treatment operations, favoring capital-intensive precision deposition over traditional manual batch processing.
Trivalent chromium conversion coatings are collapsing the process window for pretreatment applications previously dominated by hexavalent chemistries. Brazilian automotive tier-1 suppliers are adopting these systems at accelerated pace to preempt IBAMA enforcement actions. This transition is collapsing the viable supplier base to chemical houses with certified REACH-compliant portfolios.
Argentina's Secretariat of Environment and Sustainable Development is tightening hazardous waste manifesting requirements for spent plating baths. Industrial consequence includes mandatory third-party treatment contracts and serialized tracking documentation. Surface treatment operations in Buenos Aires province are most affected, responding through consolidation into shared-service recovery facilities.
Aftermarket procurement for aerospace component restoration is compressing qualification cycles for new coating applicators. Airlines and MRO providers in São Paulo and Rio de Janeiro are unbundling long-term service agreements into discrete work-order contracts. Chilean mining fleet operators are most visible in adopting this model, driving spot-market pricing for thermal spray reclamation services.
South America Metal Finishing Market Segmentation
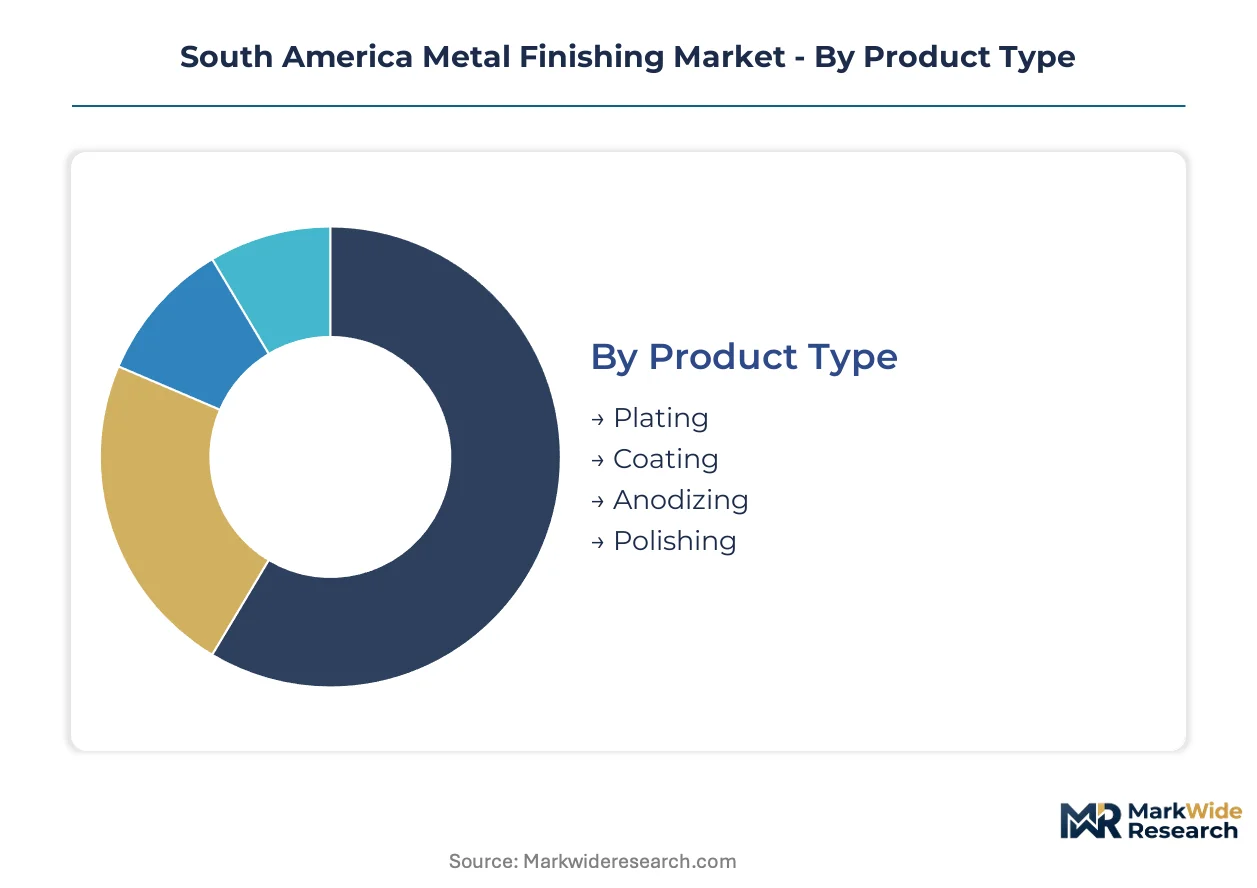
Process differentiation across South American metal finishing operations determines capital intensity, regulatory exposure, and margin capture. Segmentation reveals how coating chemistry choices and end-use specifications reshape competitive positioning across Brazil's industrial corridor and Andean mining regions.
Product Type:
Application requirements dictate coating thickness tolerances and corrosion resistance specifications across Brazil's automotive belt and Chilean mining equipment aftermarket.
- Plating:Electrochemical deposition of nickel, chromium, or zinc layers achieves thickness tolerances from 0.1 to 100 micrometers. São Paulo state's automotive connector manufacturers anchor regional demand, though IBAMA wastewater enforcement is forcing chemistry substitutions that compress job shop margins.
- Coating:Organic and inorganic film applications—powder, liquid, and conversion coatings—dominate chassis component protection. Brazilian OEMs are mandating advanced systems for corrosion-resistant underbody parts, pulling volume through tier-1 supplier networks around Campinas and Sorocaba.
- Anodizing:Electrochemical oxide layer formation on aluminum substrates delivers wear resistance and dielectric properties. Argentina's aerospace maintenance sector specifies hard anodized finishes for landing gear components.
- Polishing:Mechanical and electrolytic surface refinement achieves aesthetic and functional finishes. Medical device manufacturers in Brazil's Free Economic Zone of Manaus require electropolished stainless steel for surgical instrument biocompatibility.
Plating holds installed capacity. Coating is rotating up the share rankings.
Technology:
Process control sophistication separates precision deposition operations from commodity batch finishing across the region's regulatory environment.
- Electrochemical:Controlled current density deposition enables sub-micrometer thickness precision for electronics and medical applications. Brazilian finishers face technical constraints in sub-5-micrometer tolerance plating due to limited local ionic liquid process expertise.
- Thermal Spraying:High-velocity oxy-fuel and plasma spray systems deposit wear-resistant ceramic and metallic coatings. Aerospace MRO operations in Buenos Aires and São Paulo are expanding turbine blade reclamation contracts, compressing qualification cycles for new applicators.
- Mechanical:Abrasive blasting, grinding, and mass finishing modify surface topography without chemical alteration. Chilean copper mining equipment rebuilders in Antofagasta specify mechanical preparation before hard chrome alternative application.
- Chemical:Conversion coatings, passivation, and pickling modify surface chemistry through redox reactions. Trivalent chromium systems are displacing hexavalent pretreatment chemistries as Brazilian tier-1 suppliers accelerate IBAMA compliance timelines.
Electrochemical processes command premium margins. Thermal spraying is expanding most quickly in aerospace aftermarket procurement.
End User:
Customer concentration patterns concentrate demand in Brazil's manufacturing clusters while creating geographic pockets of specialized requirement.
- Automotive:Vehicle OEMs and tier suppliers specify corrosion-resistant chassis and powertrain coatings. Brazil's production corridor from São Paulo to Curitiba generates the dominant share of regional finishing volume, with OEMs unbundling long-term service agreements into discrete work orders.
- Aerospace:Airlines and MRO providers demand wear-resistant turbine coatings and component restoration services. São Paulo and Rio de Janeiro maintenance bases are driving spot-market pricing for thermal spray reclamation.
- Electronics:Connector and semiconductor packaging manufacturers require precision plating for conductivity and solderability. Argentina's limited electronics assembly base constrains local demand relative to import-dependent supply chains.
- Construction:Structural steel and architectural metal fabricators specify protective coatings for atmospheric exposure. Brazilian infrastructure project delays have softened near-term demand in this segment.
Automotive anchors volume concentration. Aerospace is climbing the fastest in margin contribution.
Application:
Functional performance requirements stratify pricing power and certification burden across South American finishing operations.
- Medical Devices:Orthopedic implants and surgical instruments demand biocompatibility-certified surface treatments. ANVISA Good Manufacturing Practice inspections constrain qualified supplier pools, creating premium-margin opportunities for ISO 13485-certified job shops in São Paulo state.
- Aerospace Components:Engine parts and airframe structures require FAA/EASA-qualified coating applicators with NADCAP accreditation. Argentine and Brazilian MRO providers are consolidating supplier bases to reduce qualification overhead.
- Industrial Equipment:Mining, agriculture, and energy sector machinery requires wear and corrosion protection. Chilean lithium extraction equipment in Atacama generates unmet demand for hydraulic cylinder rod reclamation services.
- Consumer Goods:Appliances, hardware, and decorative metal products specify aesthetic and functional finishes. Brazilian domestic appliance manufacturers are adopting automated deposition lines to reduce manual batch processing costs.
Medical Devices commands pricing premiums. Industrial Equipment is gaining share fastest on mining aftermarket expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil exports finished automotive components to Mercosur partners and North American OEMs, creating cross-border demand for corrosion-resistant coatings that comply with destination-market environmental standards.
Brazil
Automotive OEMs in São Paulo state mandate advanced coating systems for chassis components, pulling volume through Campinas and Sorocaba supplier networks. IBAMA enforcement actions are accelerating capital deployment into closed-loop water treatment systems. São Paulo's industrial corridor concentrates the dominant share of regional plating and coating capacity.
Argentina
Aerospace maintenance operations in Buenos Aires specify wear-resistant turbine coatings, expanding demand for high-velocity oxy-fuel application services. The Secretariat of Environment and Sustainable Development tightens hazardous waste manifesting requirements for spent plating baths. Buenos Aires province surface treatment operations are consolidating into shared-service recovery facilities to manage compliance costs.
Chile
Copper and lithium extraction machinery in Antofagasta and Atacama regions generates unmet demand for hard chrome alternatives on hydraulic cylinder rods. Mining fleet operators are adopting spot-market procurement models for thermal spray reclamation services. The northern mining belt is driving fastest segment growth in industrial equipment surface treatment.
Colombia
Petrochemical and energy infrastructure projects in Barrancabermeja and Cartagena specify protective coatings for atmospheric exposure. National environmental authority resolution 2086 establishes wastewater discharge parameters for metal finishing operations. The Magdalena River industrial corridor is emerging as a secondary concentration for anticorrosion coating demand.
South America Metal Finishing Market Competitive Landscape
On the supply side, the industry is structured around integrated chemical suppliers, diversified industrial conglomerates, and specialized coating applicators competing across distinct value chain positions. Three strategic archetypes dominate: formulation houses with REACH-compliant portfolios, integrated steel producers extending into finished coil products, and industrial gas suppliers anchoring thermal spray operations. Competitive moves concentrate on chemistry substitution partnerships and automated deposition line deployments.
Among German-headquartered chemical specialists, Chemetall GmbH and TIB Chemicals AG occupy positions within the pretreatment formulation tier, representing the archetype of regulatory-compliant chemistry suppliers. POSCO exemplifies integrated steel producers leveraging captive metal supply into downstream finishing. These three entities anchor distinct competitive vectors without overlapping core capabilities.
| Leading Market Players |
|---|
| Chemetall GmbH |
| POSCO |
| Honeywell International Inc. |
| Giant Finishing Inc. |
| TIB Chemicals AG |
| Linde plc |
| ELEMENTIS PLC |
| ArcelorMittal |
| OC Oerlikon Management AG |
| Others |
Value Network & Pricing Analysis
Chrome-free conversion coating feedstock concentration from German and US specialty chemical producers determines both the spread between REACH-compliant premium tiers and legacy-economy pricing, and the geographic shape of supplier networks around São Paulo state's industrial corridor.
Pricing Analysis
The prior-generation hexavalent chromium chemistry gap against next-generation trivalent systems defines pricing stratification across premium, standard, and economy tiers. Contract-based long-term offtake dominates, with price differentiation driven by certification level (REACH/IBAMA compliance tier) and volume scale. Cost compression in mid-tier job shops is intensifying because currency-driven input cost spikes from euro-denominated feedstock contracts erode margins. Automotive OEMs demonstrate least price sensitivity due to mandated coating specifications, while commodity construction finishers face acute pressure.
Supply Chain Analysis
Contract-manufacturing concentration rests with Chemetall GmbH and TIB Chemicals AG for pretreatment formulations, Linde plc for industrial gas delivery, and regional Brazilian job shops for application services. Geographic supply concentration centers on Germany, the United States, and Brazil. Raw material dependencies draw from chromium compounds, nickel sulfate, and specialty organic additives. Single-source vulnerability in German REACH-compliant chemistry imports creates structural exposure. Distribution runs through tier-1 automotive supplier networks anchored in Campinas and Sorocaba.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The South America metal finishing market rewards operators with certified electrochemist capabilities and IBAMA-aligned process chemistry portfolios, while punishing capital-light job shops lacking closed-loop water treatment infrastructure.
For Market Incumbents: Build regulatory compliance moats by securing ANVISA biocompatibility certification for medical device surface treatments and deepening backward integration into captive trivalent chromium chemistry production. Anchor automotive OEM relationships through co-located technical service teams in São Paulo state's manufacturing clusters. Preempt substitute technology threats from thermal spraying by embedding electrochemical precision deposition into long-term chassis component contracts.
For New Entrants and Emerging Players: Pursue white-space capture in Chilean mining equipment aftermarket reclamation services, where hard chrome alternative demand in Antofagasta and Atacama regions outpaces qualified applicator supply. Target ANVISA-certified medical device electropolishing for orthopedic implant contract manufacturers in Manaus Free Economic Zone. Penetrate through ISO 13485 qualification partnerships with established Brazilian surgical instrument distributors.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated chemical suppliers with REACH-compliant portfolios over fragmented job shop aggregations. Long-term viability hinges on automation-capital intensity and regulatory qualification durability. Acquisition target archetype: mid-cap Brazilian finishers with installed closed-loop water treatment and IBAMA enforcement preemption. Monitor Mercosur environmental harmonization implementation timelines as inflection indicator for cross-border supplier qualification complexity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Trivalent Chromium Chemistry | Captive REACH-compliant feedstock production insulates Brazilian finishers from euro-denominated import volatility. |
| ANVISA Biocompatibility Certification Investment | ISO 13485 qualification opens premium-margin medical device surface treatment contracts in São Paulo state. |
| Closed-Loop Water Treatment Deployment | IBAMA wastewater enforcement preemption transforms compliance cost center into competitive barrier. |
| Thermal Spray Capability Addition | High-velocity oxy-fuel systems capture aerospace MRO turbine blade reclamation demand in Buenos Aires. |
| Chilean Mining Aftermarket Service Expansion | Antofagasta hydraulic cylinder rod reclamation addresses unmet demand from copper and lithium extraction fleets. |
Research Methodology
Cross-validation between regulatory filing analysis and supply chain participant interviews anchors the qualitative findings. Primary fieldwork engaged plating process engineers, automotive tier-1 procurement managers, IBAMA compliance officers, medical device quality directors, and thermal spray applicators across São Paulo, Buenos Aires, and Santiago. Secondary sources drew from ANVISA GMP inspection records, IBAMA environmental enforcement bulletins, SEC filings of listed chemical suppliers, and Mercosur technical regulation harmonization documents. Bottom-up capacity estimates from individual finishing facilities were reconciled with top-down demand projections from automotive and aerospace OEM production schedules.
Calibration against historical chemistry substitution timelines and regulatory enforcement intensity shaped the analytical framework. Segmentation modeling spanned process type, coating chemistry generation, end-use industry, and regional regulatory cluster across the projection horizon. CAGRs were derived from installed capacity utilization trends and capital expenditure announcements by integrated chemical suppliers. Industry-specific forecast inputs incorporated trivalent chromium adoption curves and thermal spray aerospace qualification cycle compression.
Sensitivities concentrate around Mercosur environmental harmonization delays, electrochemist wage inflation, and German specialty chemical export licensing shifts. Forecasts embed assumptions regarding IBAMA enforcement consistency and ANVISA inspection cadence without guarantee of regulatory continuity. Quarterly review of trivalent chromium chemistry import volumes and São Paulo state plating facility closure announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Medical Metal Tubing Market
Metals
Europe Welding Consumables Market
Metals
Global Stretch Spring Wire Market
Metals
Aluminum Scrap Recycling Market
Metals
Armour Steel Plate Market
Metals
Steel Drums and Ibcs Market
Metals
Battery Metals Market
Metals
Nickel Oxide Target Market
Metals
Brazing Strips Market
Metals
High-End Copper Foil Market
Metals
Cerium Market
Metals
Powder Metallurgy Market
Metals
Platinum Group Metals Market
Metals
Asia-Pacific Aluminum Casting Market
Metals
Finished Steel Products Market
Metals
Grain Oriented Electrical Steel Market