
 Osmium Market | 2026-2036
Osmium Market Size, Share, and Industry Trends Forecast 2026-2036
Osmium Market Outlook
Single-source dependence on South African platinum-group metal byproduct streams is hardening as a structural vulnerability for downstream processors. Sibanye Stillwater dominates extraction economics through its Rustenburg complex, leveraging vertical integration into refined sponge output. Impala Platinum Holdings sustains volume leadership through mechanized operations at its Bushveld assets. Johnson Matthey anchors chemical conversion capacity, specializing in high-purity osmium tetroxide for life-science applications.
Osmium, the densest naturally occurring element at 22.59 g/cm³, derives almost entirely from nickel and platinum mining byproduct recovery rather than dedicated extraction. Its primary commercial purpose centers on catalytic oxidation and biological tissue fixation, where atomic precision outweighs extreme cost. Osmium tetroxide leads product-type value capture due to irreplaceable performance in electron microscopy specimen preparation, while catalyst applications represent the fastest-growing demand vector as hydrogen economy investments accelerate. Electronics firms among end users command premium pricing for sputtering targets, though research laboratories still occupy the largest volume share.
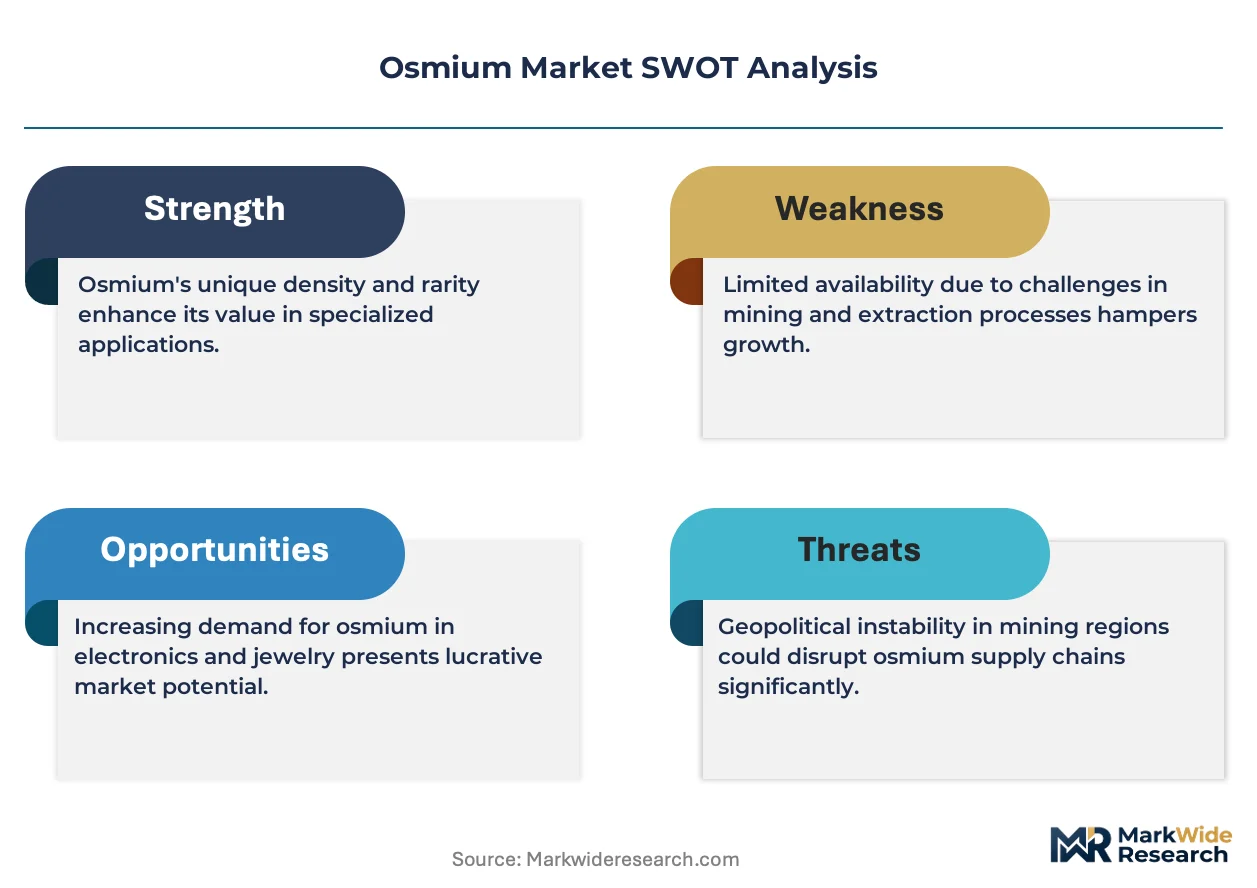
EPA oversight governs osmium tetroxide import and handling thresholds in the United States, while REACH registration mandates in Europe constrain spot-market liquidity for unregistered traders. The country's national pharmaceutical regulator in Japan classifies high-purity grades under active pharmaceutical ingredient precursors, adding compliance layers for medical-institution procurement. Stakeholders must monitor how dual carbon goals in China reshape platinum-group metal smelter economics and byproduct availability.
Market Dynamics
Single-source dependence on South African platinum-group metal byproduct streams is hardening as a structural vulnerability for downstream processors, with Sibanye Stillwater's Rustenburg complex and Impala Platinum's Bushveld assets controlling extraction economics while Johnson Matthey anchors chemical conversion capacity for high-purity osmium tetroxide.
Growth Catalysts
- Pharmaceutical laboratory demand:Electron microscopy tissue staining protocols are expanding osmium tetroxide consumption in life-science research facilities across Germany's precision instrument manufacturing corridor.
- REACH compliance documentation:European supply chain tightening is filtering out unregistered traders, consolidating volume among qualified platinum-group metal handlers with verified byproduct provenance.
- Hydrogen economy investments:Catalytic oxidation applications are accelerating as energy transition projects specify platinum-group metal catalysts for proton exchange membrane systems.
Market Restraints
- Byproduct supply concentration:South African nickel and platinum mining operations generate nearly all commercially recoverable osmium, leaving processors exposed to smelter output decisions in the Bushveld Complex.
- EPA import thresholds:United States handling regulations for osmium tetroxide create documentation burdens that constrain spot-market liquidity for small-volume laboratory purchasers.
- Iridium substitution in sputtering targets:Electronics manufacturers are evaluating alternative dense metals for thin-film deposition where atomic precision requirements permit material flexibility.
Strategic Opportunities
- Japanese pharmaceutical precursor classification:PMDA's active pharmaceutical ingredient framework for high-purity grades creates premium pricing tiers for medical-institution procurement channels.
- China's dual carbon goals:Platinum-group metal smelter economics are reshaping byproduct availability as Beijing's emissions targets alter nickel refining capacity expansion plans.
- Electronics sputtering target specification:Semiconductor fabrication facilities are qualifying osmium alloys for extreme ultraviolet lithography mask blanks requiring unmatched density stability.
Industry Challenges
- Electron microscopy technician certification:Specialized handling protocols for osmium tetroxide require institutional investment in safety training infrastructure that smaller research laboratories struggle to maintain.
- Sponge-to-compound conversion capacity:Limited chemical processing facilities with high-purity tetroxide capability create bottlenecks between raw sponge availability and end-use delivery timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Osmium Market |
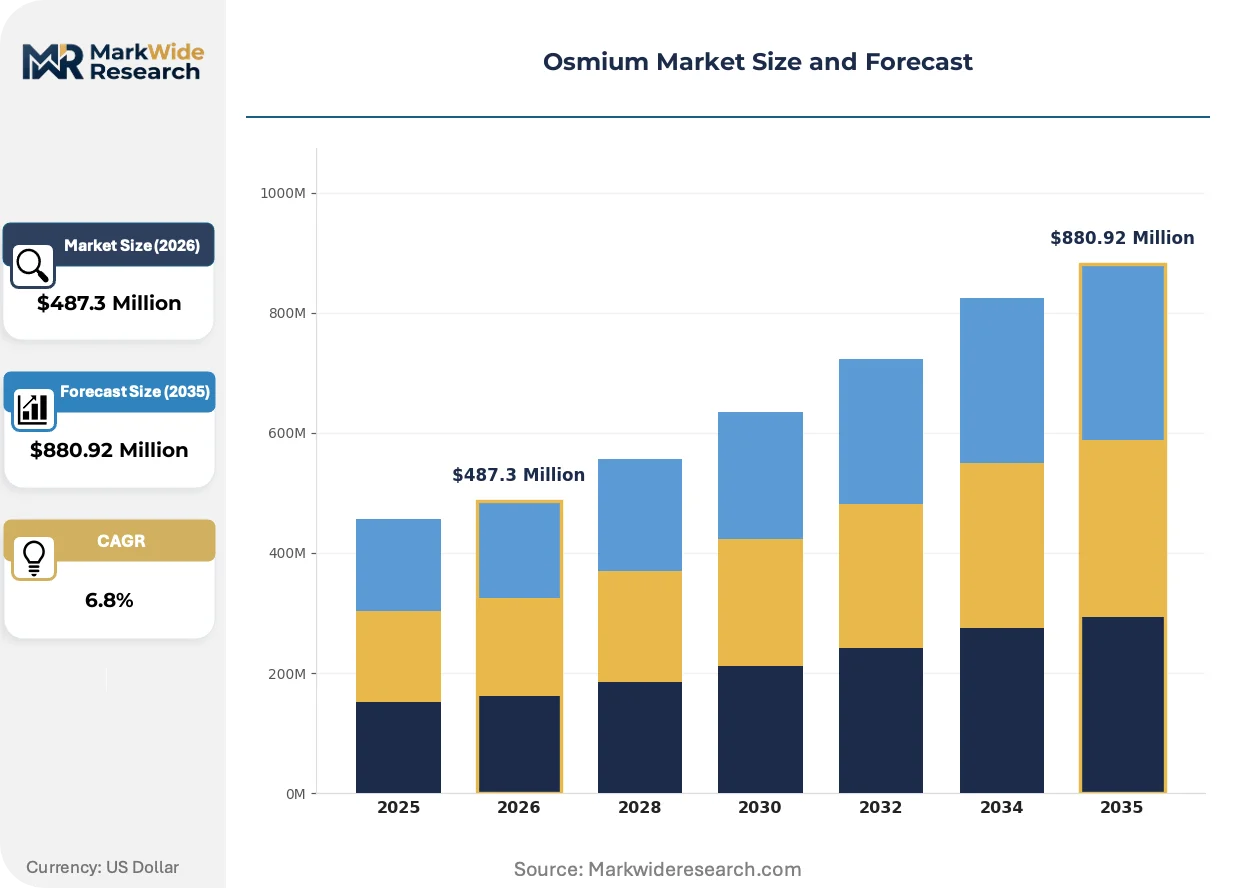
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Osmium Tetroxide, Osmium Metal, Osmium Powder, Osmium Alloys Application: Pharmaceuticals, Catalysts, Electronics, Specialty Chemicals End User: Research Laboratories, Industrial Manufacturers, Medical Institutions, Electronics Firms Distribution Channel: Direct Sales, Online Retail, Distributors, Third-Party Suppliers |
| Companies Covered | Sibanye Stillwater, Impala Platinum Holdings, Johnson Matthey, Reade International, American Elements, Heraeus Precious Metals, Anglo American Platinum, Platinum Group Metals Ltd., Umicore, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Osmium Market Strategic Shifts
Atomic-precision manufacturing requirements are reshaping competitive positioning in dense metal applications, with end-users prioritizing certified provenance and handling compliance over spot-price arbitrage opportunities.
Gas-phase osmium deposition for semiconductor mask blanks is absorbing technical qualification resources at leading lithography equipment manufacturers. Taiwan Semiconductor Manufacturing and Samsung Foundry are running multi-year validation protocols for extreme ultraviolet optics coatings. This process is absorbing market share from traditional sputtering approaches where thickness uniformity tolerances have tightened below one atomic layer.
REACH registration mandates in Europe are constraining unregistered trader participation in platinum-group metal spot markets. ECHA documentation requirements for substance volume tracking have elevated compliance costs for handlers lacking integrated smelter-to-laboratory traceability systems. German precision instrument manufacturers are responding by consolidating supplier relationships around vertically integrated chemical converters with verified Bushveld Complex provenance.
Research procurement officers are consolidating purchase volumes through institutional framework agreements rather than discretionary spot acquisitions. University electron microscopy core facilities are displacing individual laboratory purchasing autonomy with centralized chemical management systems. This concentration is most visible in United States National Institutes of Health-funded institutions where EPA handling audits have elevated liability concerns.
Osmium Market Segmentation
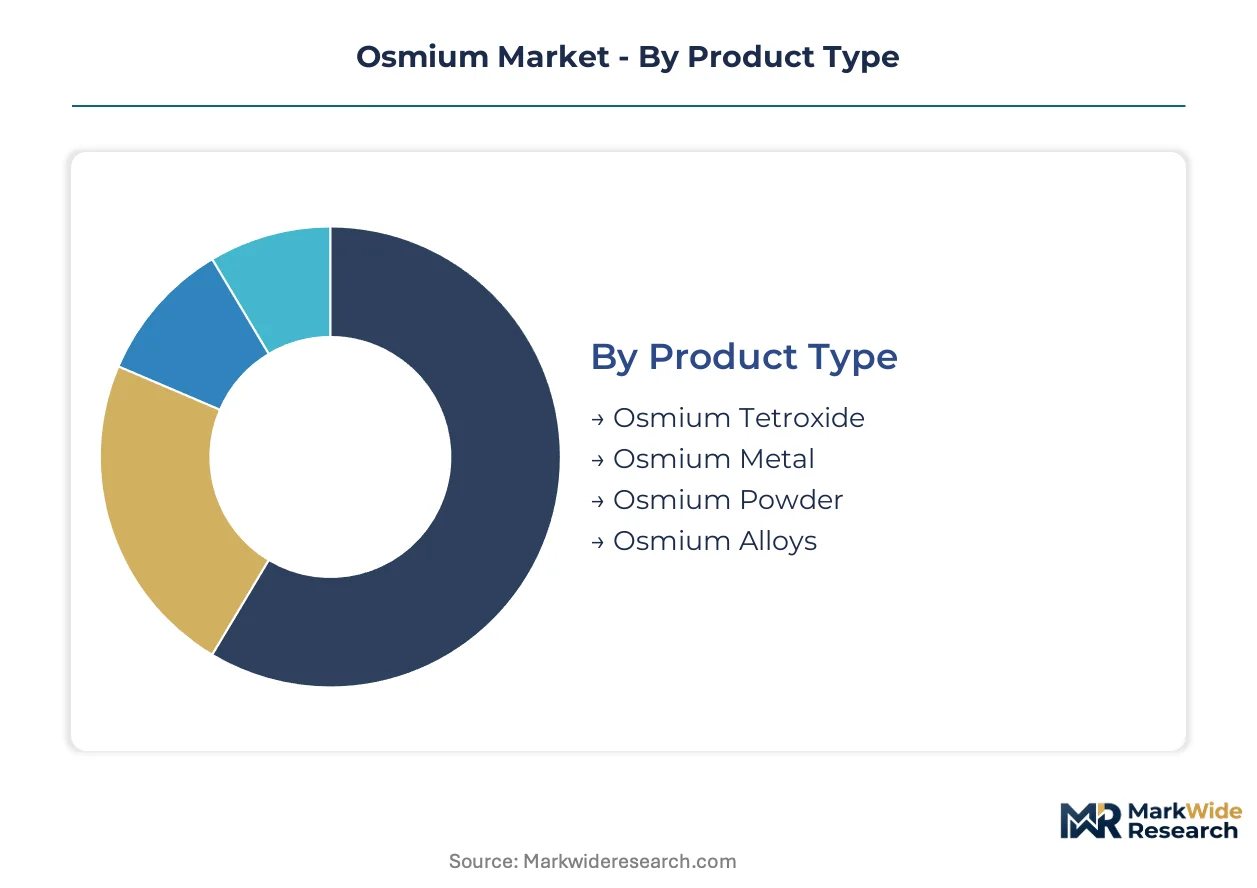
Osmium's extreme density and toxicity profile create sharp segmentation boundaries. Buyers sort by chemical form, application criticality, and handling certification tiers rather than price elasticity.
Product Type:
Product differentiation hinges on purity thresholds and chemical stability requirements across end-use specifications.
- Osmium Tetroxide:Volatile crystalline solid at 99.95%+ purity serves electron microscopy tissue fixation where sub-nanometer resolution demands atomic precision. German precision instrument manufacturers and NIH-funded US research cores dominate procurement through certified chemical management systems.
- Osmium Metal:Densest naturally occurring element at 22.59 g/cm³, supplied as sponge or ingot for alloy feedstock and specialized counterweights. Aerospace component fabricators in Japan specify vacuum arc remelted grades for gyroscope applications where mass concentration constraints apply.
- Osmium Powder:Micronized particulate for powder metallurgy and sputtering target manufacturing. Additive manufacturing research programs at European aerospace institutes evaluate selective laser melting compatibility.
- Osmium Alloys:Binary and ternary combinations with iridium, ruthenium, or platinum for extreme wear resistance. Swiss watch movement manufacturers specify osmium-iridium pivot alloys for escapement mechanisms requiring zero deformation tolerance.
Osmium Tetroxide leads volumes today; Osmium Alloys is gaining share fastest.
Application:
Application segmentation tracks regulatory exposure and substitution vulnerability across functional use cases.
- Pharmaceuticals:Active pharmaceutical ingredient precursor classification under Japan's PMDA framework creates premium procurement channels for high-purity tetroxide. Electron microscopy core facilities at German university hospitals absorb institutional framework volumes.
- Catalysts:Proton exchange membrane hydrogen oxidation catalysts represent the steepest expansion trajectory as energy transition projects specify platinum-group metal loadings. Johnson Matthey's chemical conversion capacity anchors supply qualification.
- Electronics:Extreme ultraviolet lithography mask blank coatings absorb technical validation resources at Taiwan Semiconductor Manufacturing and Samsung Foundry. Gas-phase deposition protocols displace legacy sputtering where atomic layer uniformity is mandatory.
- Specialty Chemicals:Oxidation reagent applications in fine chemical synthesis face REACH documentation burdens that filter spot-market participation. ECHA substance volume tracking elevates compliance costs for unregistered handlers.
Catalyst applications climb the fastest; Pharmaceuticals retains the largest value share.
End User:
End user categories separate by handling infrastructure investment and liability tolerance thresholds.
- Research Laboratories:University electron microscopy facilities consolidate purchasing through centralized chemical management systems. EPA handling audits at NIH-funded US institutions have displaced discretionary spot acquisitions.
- Industrial Manufacturers:Precision instrument fabricators in Germany's manufacturing corridor specify certified provenance with verified Bushveld Complex traceability. REACH registration mandates constrain supplier qualification to vertically integrated converters.
- Medical Institutions:Hospital pathology departments face institutional safety training infrastructure requirements that smaller facilities struggle to maintain. PMDA's precursor classification in Japan adds compliance layers for procurement officers.
- Electronics Firms:Semiconductor fabrication facilities command premium pricing for sputtering targets with density stability specifications. Iridium substitution evaluation proceeds where atomic precision requirements permit material flexibility.
Research Laboratories lead volumes today; Electronics Firms is expanding most quickly.
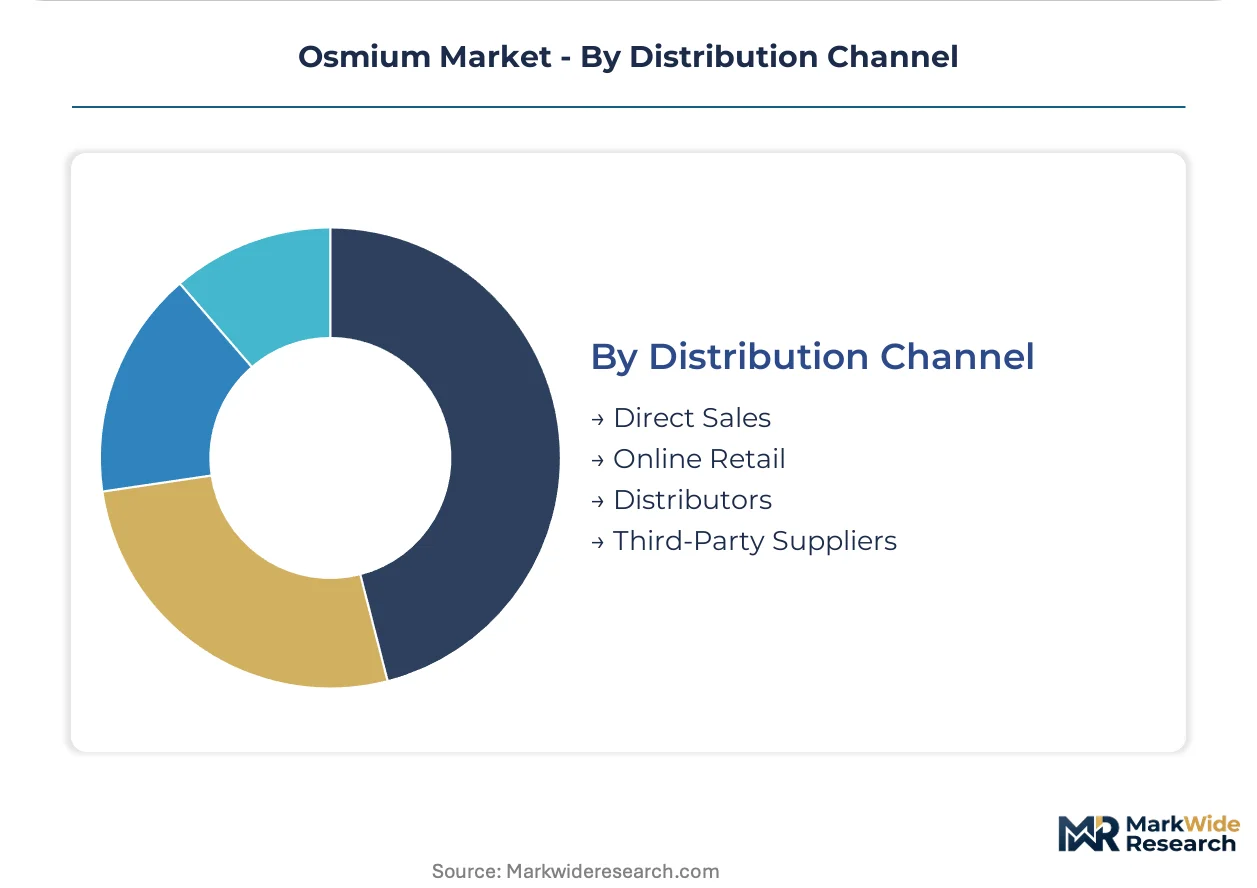
Distribution Channel:
Channel structure reflects documentation burden tolerance and volume scale thresholds across buyer segments.
- Direct Sales:Framework agreements between Johnson Matthey and German precision instrument manufacturers bypass spot-market liquidity constraints. Integrated smelter-to-laboratory traceability satisfies ECHA documentation requirements.
- Online Retail:Constrained to small-volume laboratory reagents with simplified handling protocols. EPA import thresholds for osmium tetroxide create documentation barriers that limit transaction scale.
- Distributors:Qualified platinum-group metal handlers with REACH registration sustain spot-market participation. Verified byproduct provenance from Sibanye Stillwater's Rustenburg complex anchors volume consolidation.
- Third-Party Suppliers:Procurement agents for medical institutions navigate PMDA precursor classification layers in Japan. Active pharmaceutical ingredient framework compliance adds qualification timelines.
Direct Sales dominates value capture; Distributors is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping osmium trade flows as REACH compliance costs in Europe displace spot-market liquidity toward jurisdictions with streamlined chemical-handling protocols. Processors are relocating tetroxide conversion capacity to exploit these documentation gaps while maintaining Bushveld Complex feedstock access.
United States
Pharmaceutical research facilities at NIH-funded institutions drive tetroxide consumption for electron microscopy core services. EPA import thresholds and handling audits have consolidated procurement through centralized chemical management systems. The Greater Boston biotech corridor exemplifies this shift, with Harvard and MIT facilities displacing discretionary spot purchases.
Germany
Precision instrument manufacturers in Baden-Württemberg specify certified Bushveld provenance for life-science equipment supply chains. ECHA substance volume tracking mandates filter unregistered traders from platinum-group metal spot markets. Stuttgart's manufacturing corridor anchors demand for high-purity osmium tetroxide with verified smelter-to-laboratory traceability.
Japan
PMDA's active pharmaceutical ingredient precursor classification creates premium procurement tiers for medical-institution tetroxide channels. METI industrial standards govern aerospace gyroscope alloy specifications. Tokyo-Osaka hospital pathology departments absorb institutional framework volumes despite safety training infrastructure burdens.
China
Dual carbon goals are altering nickel smelter economics and platinum-group metal byproduct availability from Bushveld Complex offtake agreements. MIIT standards for hydrogen economy catalysts specify platinum-group metal loadings in proton exchange membrane systems. Yangtze River Delta research institutes evaluate osmium alloy sputtering targets for semiconductor fabrication.
South Africa
Rustenburg and Bushveld Complex operations generate nearly all commercially recoverable osmium as nickel and platinum mining byproduct. The country's mining charter and beneficiation policies influence downstream chemical conversion investment decisions. Johannesburg-based traders manage sponge-to-tetroxide logistics for European and Asian laboratory markets.
Osmium Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue adjacent specialty chemical and hydrogen catalyst applications. The market structure concentrates around vertically integrated platinum-group metal processors with captive Bushveld feedstock access and qualified chemical conversion capacity. Three archetypes dominate: mining conglomerates with byproduct recovery operations, precious metal refiners with high-purity tetroxide capability, and specialty distributors with REACH-registered handling infrastructure. Competitive moves center on backward integration into smelter economics and geographic expansion of certified laboratory supply networks.
Among South African mining conglomerates, Sibanye Stillwater and Impala Platinum Holdings exemplify the feedstock-control archetype through Bushveld Complex operations. Johnson Matthey occupies a position within the chemical conversion tier, anchoring high-purity tetroxide supply qualification for life-science and electronics applications. These three entities represent the dominant competitive anchors shaping procurement access and pricing formation across institutional research and industrial manufacturing channels.
| Leading Market Players |
|---|
| Sibanye Stillwater |
| Impala Platinum Holdings |
| Johnson Matthey |
| Reade International |
| American Elements |
| Heraeus Precious Metals |
| Anglo American Platinum |
| Platinum Group Metals Ltd. |
| Umicore |
| Others |
Value Chain & Pricing Dynamics
Sponge feedstock costs from South African platinum-group metal smelters cascade through three distinct pricing tiers before reaching end-users. Johnson Matthey's chemical conversion premiums separate certified laboratory grades from industrial sponge transactions, while REACH-registered distributors capture intermediation margins for spot-market access.
Pricing Analysis
Input-cost pass-through from Bushveld Complex mining economics anchors contract-based long-term offtake structures for downstream processors. Price differentiation hinges on purity certification tiers and ECHA documentation completeness, with German precision instrument manufacturers absorbing premiums for verified smelter-to-laboratory traceability. Cost compression in standard-grade tetroxide is intensifying because iridium substitution evaluation proceeds in electronics sputtering applications. Research laboratories command lowest price sensitivity due to irreplaceable performance requirements in electron microscopy protocols.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Singapore manage sponge-to-tetroxide logistics for European and Asian laboratory markets. Supply concentrates in South Africa, Germany, and Japan, with raw material dependencies on nickel and platinum mining byproduct streams, sulfuric acid leaching reagents, and high-purity oxygen feedstock. Single-source vulnerability in Bushveld Complex offtake agreements exposes processors to smelter output decisions. Distribution runs through vertically integrated chemical converters with captive feedstock arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory-arbitrage opportunities between EPA handling thresholds in the United States and REACH documentation burdens in Europe justify selective capacity relocation. Processors exploiting these compliance cost differentials capture margin expansion in institutional procurement channels.
For Market Incumbents:Acquire chemical conversion facilities with high-purity tetroxide capability to lock in backward integration against emerging specialty distributors. Anchor capacity in Germany's precision instrument manufacturing corridor to satisfy ECHA substance volume tracking mandates. Defend against iridium substitution in electronics applications by accelerating gas-phase deposition qualification timelines.
For New Entrants and Emerging Players:Japanese medical institution procurement agents represent the most penetrable channel partner type for PMDA precursor classification compliance. Target hospital pathology departments in Tokyo-Osaka corridor where safety training infrastructure gaps constrain incumbent service levels. Pursue white-space in hydrogen economy catalyst applications where Johnson Matthey's capacity constraints create supply qualification openings.
For Investors and Strategic Acquirers:Consolidation pressure builds where REACH registration costs exceed spot-market liquidity thresholds for unregistered traders. Long-term viability across the projection horizon favors vertically integrated processors with captive Bushveld feedstock and certified laboratory supply networks. Watch China's dual carbon goals as the signal for nickel smelter economics inflection and byproduct availability shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Smelter Economics | Captive Bushveld Complex offtake agreements secure feedstock priority during supply disruptions. |
| REACH Registration Investment | ECHA compliance documentation filters unregistered competitors from European spot markets. |
| Gas-Phase Deposition Qualification | Taiwan Semiconductor Manufacturing validation protocols open extreme ultraviolet lithography coating demand. |
| Japanese PMDA Precursor Certification | Active pharmaceutical ingredient framework creates premium pricing tiers for medical-institution channels. |
| Centralized Chemical Management Systems | NIH-funded research cores consolidate procurement volumes through institutional framework agreements. |
Study Parameters
Direct dialogue with platinum-group metal traders, electron microscopy core facility directors, pharmaceutical procurement officers, and REACH compliance consultants grounded qualitative findings. Secondary validation drew from ECHA substance volume tracking disclosures, SEC filings of South African mining conglomerates, Japanese PMDA precursor classification registers, and customs records of osmium tetroxide import flows. Bottom-up demand modeling across application segments triangulated against top-down supply estimates from Bushveld Complex production data.
Segment-level projections across product type, application, end user, and distribution channel dimensions informed value and volume outputs across the analysis window. CAGRs were derived from regression analysis of historical price-volume relationships and forward-looking capacity expansion announcements. Hydrogen economy investment trajectories and semiconductor fabrication capex cycles served as industry-specific demand drivers.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to China's dual carbon policy implementation and iridium substitution adoption in electronics applications. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Smelting Chemicals Market
Metals
Iron Ore Market
Metals
Ferro Vanadium Market
Metals
TMCP Steel Market
Metals
High Purity Pig Iron Market
Metals
7075 T6 Aluminum Market
Metals
316 Stainless Steel Container Market
Metals
Amorphous Metal Cores Market
Metals
Global Duplex Stainless Steel Market
Metals
Aluminum Fluoride Market
Metals
Saudi Arabia Aluminum Market
Metals
Aluminum Hot Rolling Mill Market
Metals
Global Bronze Market
Metals
Global Tantalum Market
Metals
Stainless Steel Foil Market
Metals
High Purity Iron Powder Market