
 Steel Long Products Market | 2026-2036
Steel Long Products Market Size, Share, and Industry Trends Forecast 2026-2036
Steel Long Products Market Intelligence
Infrastructure contractors are collapsing the historical dominance of automotive OEMs as the primary demand anchor for steel long products. ArcelorMittal leverages its European section mills to supply bridge and rail projects with certified structural grades. POSCO Holdings anchors its competitive position through captive scrap-to-billet integration at its Pohang complex. Tata Steel Group differentiates via specialized seismic rebar output for high-risk construction zones.
Steel long products encompass rolled, forged, extruded, and tempered forms of carbon and alloy steel with cross-sections elongated along one axis, typically produced through continuous casting followed by hot rolling to achieve tensile strengths ranging from 400 to 600 MPa depending on grade specification. These products serve primarily as load-bearing structural elements in reinforced concrete, framed construction, and heavy engineering applications. Rebar commands the largest volume share within product type segmentation due to its irreplaceable role in concrete reinforcement across residential and commercial verticals. Wire Rod exhibits the fastest structural expansion as downstream drawing operations multiply for automotive fastener and cable applications. Sections concentrate margin pools in specialized heavy profiles where rolling mill configuration limits competitive entry.
The EU's Construction Products Regulation and CE marking requirements shape market access by mandating declared performance characteristics for structural steel placed on European markets. China's GB standards, administered by SAMR, enforce grade-specific chemical composition and mechanical property thresholds that filter import eligibility. India's BIS certification for structural steels under IS 1786 creates compliance barriers for uncertified foreign suppliers. Stakeholders must monitor divergence between regional carbon accounting methodologies as embodied emissions thresholds begin penetrating procurement specifications.
Market Dynamics
Infrastructure contractors across Southeast Asia are collapsing the historical dominance of automotive OEMs as the primary demand anchor for steel long products, redirecting rolling mill capacity toward certified structural grades for bridge and rail megaprojects.
Growth Catalysts
- Seismic-grade rebar mandates:China's GB standards for seismic-grade steel administered by SAMR are tightening material certification requirements and filtering import eligibility for high-risk construction zones.
- Scrap-to-billet integration:Captive scrap processing at integrated complexes is compressing input cost volatility and securing billet supply for specialized section production.
- Mumbai-Ahmedabad industrial corridor:India's western corridor is driving concentrated section steel consumption as infrastructure contractors scale rebar procurement for deepening megaproject pipelines.
Market Restraints
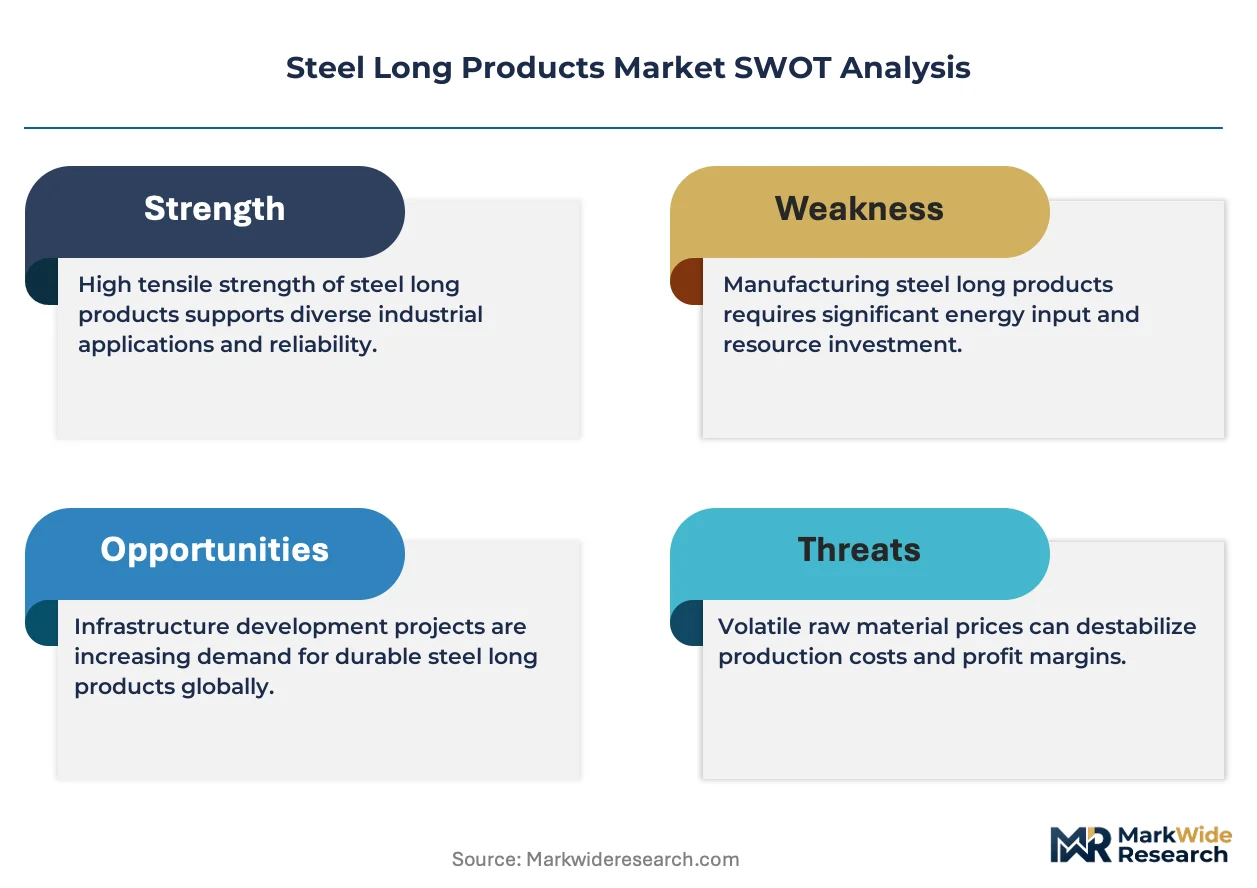
- Iron ore and scrap price volatility:Input cost swings for ferrous raw materials are compressing margin predictability at non-integrated rolling operations.
- EU Construction Products Regulation friction:CE marking requirements and declared performance characteristics are creating compliance barriers for uncertified foreign suppliers accessing European markets.
- Composite reinforcement substitution:Fiber-reinforced polymer bars are penetrating corrosive-environment applications where lifecycle cost calculations favor non-metallic alternatives.
Strategic Opportunities
- India BIS certification gaps:Uncertified foreign suppliers face exclusion from structural steel procurement under IS 1786, creating white space for early compliance investment.
- Wire rod downstream drawing:Automotive fastener and cable applications are multiplying demand for precision wire rod as electric vehicle architectures expand high-tensile fastening requirements.
- Embodied emissions thresholds:Divergent regional carbon accounting methodologies are beginning to penetrate procurement specifications, rewarding mills with verified low-carbon production routes.
Industry Challenges
- Metallurgical talent scarcity:Specialized rolling mill engineers and process metallurgists with expertise in microalloying for high-strength grades are in short supply across Southeast Asian operations.
- Certification timeline compression:BIS and SAMR approval cycles for new grade introductions are extending product development calendars and delaying market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Steel Long Products Market |
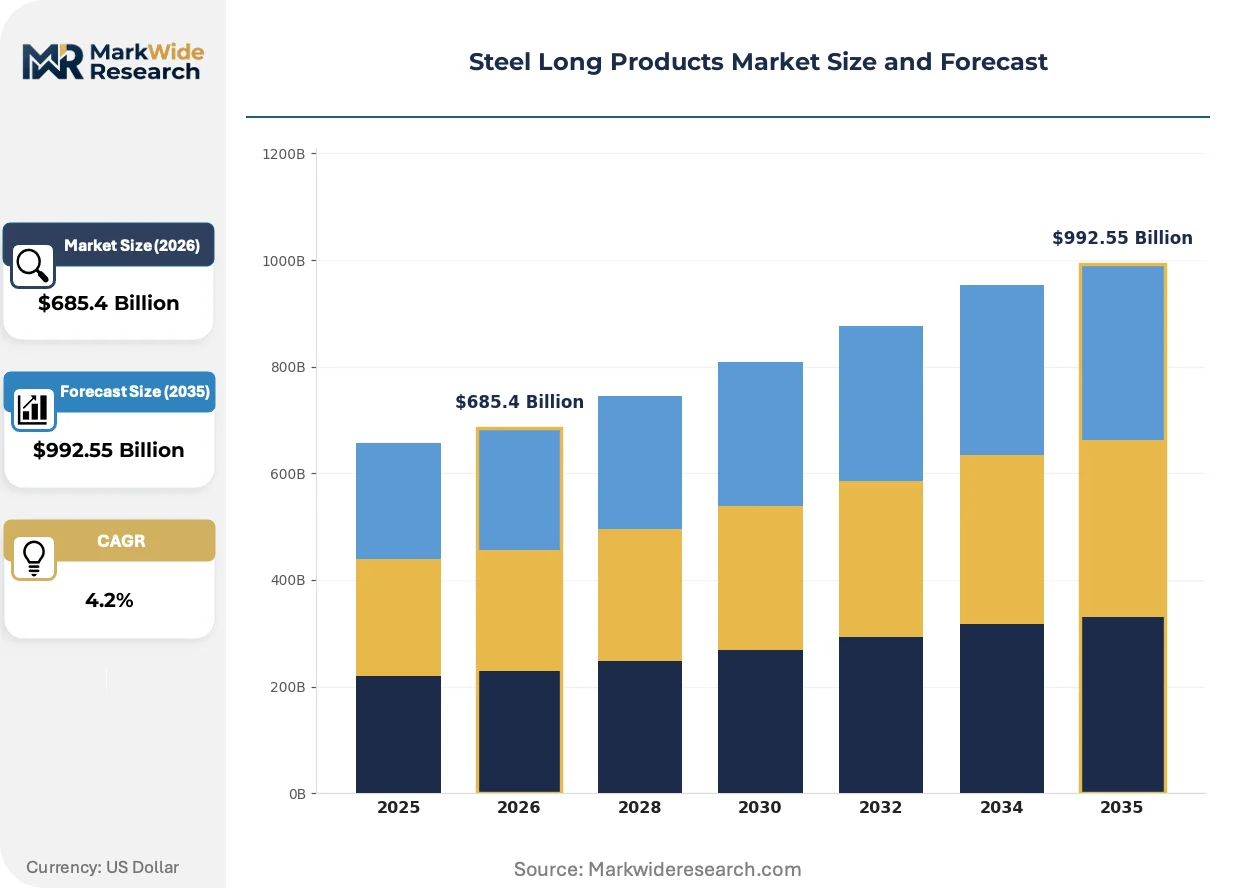
| Market Size in 2026 | $685.4 Billion |
| Market Size in 2035 | $992.55 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rebar, Wire Rod, Sections, Billets Application: Construction, Automotive, Manufacturing, Infrastructure End User: Contractors, OEMs, Fabricators, Distributors Form: Rolled, Forged, Extruded, Tempered |
| Companies Covered | Nippon Steel Corporation, Shagang Group, China Baowu Group, POSCO Holdings, Jianlong Group, ArcelorMittal, HBIS Group, Tata Steel Group, Ansteel Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Steel Long Products Market Strategic Shifts & Innovations
Electrification of rolling mill operations and precision metallurgy are reshaping cost structures and product performance envelopes across the steel long products value chain.
Quenched and self-tempered (QST) rebar production is supplanting traditional microalloying routes for achieving 500 MPa yield strengths. Southeast Asian infrastructure contractors are specifying QST grades for seismic-critical structures at accelerating rates. This metallurgical shift is compressing alloy consumption per ton and reducing dependence on vanadium and niobium suppliers.
The EU's revised Construction Products Regulation is mandating declared performance characteristics and digital product passports for structural steel placed on European markets. Rolling mills serving bridge and rail projects must now maintain batch-level traceability and third-party certification. Heavy section producers with existing quality management systems are adapting fastest, while merchant bar suppliers face documentation system investments.
Buyers are consolidating rebar procurement through tier-one distributors capable of bundling certified grades with logistics and just-in-time delivery. Infrastructure contractors in India's western corridor are abandoning fragmented local mill relationships in favor of single-source agreements with integrated suppliers. This channel concentration is compressing margins at independent rolling mills while rewarding distributors with certification capabilities and working capital depth.
Steel Long Products Market Segmentation
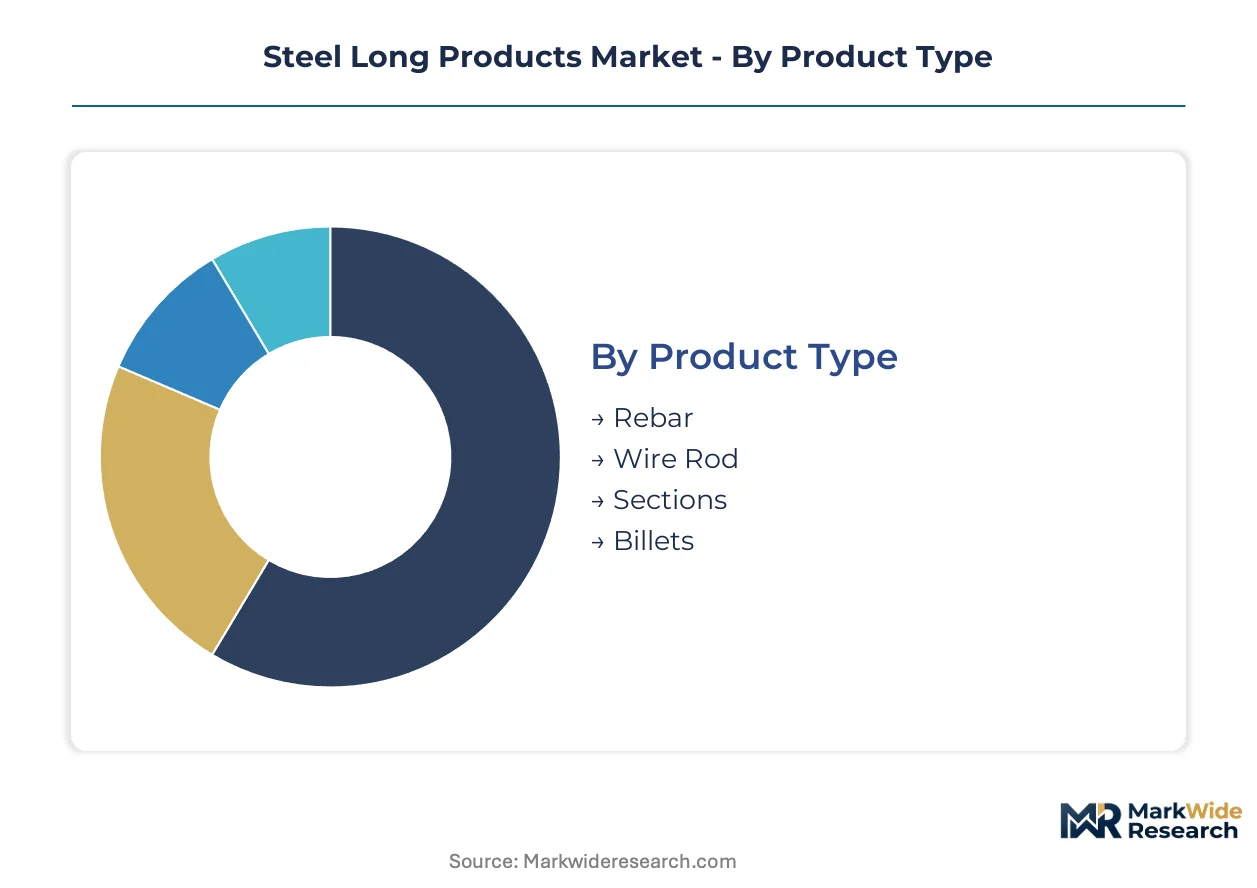
Segmentation in steel long products reveals how substitution pressures and certification requirements reshape procurement patterns across construction, automotive, and heavy engineering verticals. Distinct product specifications, end-user capabilities, and forming technologies create divergent margin pools and competitive barriers.
Product Type:
Wire Rod faces the most acute substitution threat from synthetic fiber cables in select automotive applications, while Rebar maintains irreplaceable structural positioning in reinforced concrete.
- Rebar:Ribbed steel bars with surface deformations engineered for concrete bond strength, typically specified at 400-600 MPa yield grades. Infrastructure contractors across India's western corridor scale procurement for Mumbai-Ahmedabad corridor megaprojects as seismic-grade certification tightens under BIS IS 1786.
- Wire Rod:Continuous-cast coils drawn down to 5.5-16mm diameters for downstream cold processing. Automotive fastener and EV cable applications in Southeast Asia multiply demand for precision-drawn grades as high-tensile fastening requirements expand.
- Sections:I-beams, H-beams, and channel profiles serving load-bearing structural frames.
- Billets:Semi-finished casting products feeding rolling mill operations for finished long products.
Rebar anchors the volume base while Wire Rod gains share at the steepest rate.
Application:
Cost tier stratification separates premium-certified structural grades from commodity construction steels, with certification investment creating divergent margin pools.
- Construction:Residential and commercial verticals consuming rebar and light sections for concrete reinforcement and framing. Seismic-grade mandates under China's GB standards administered by SAMR filter import eligibility for high-risk zones.
- Infrastructure:Bridge, rail, and energy projects requiring certified heavy sections with batch-level traceability. EU Construction Products Regulation CE marking mandates declared performance characteristics and digital product passports for European market access.
- Automotive:Chassis components, suspension elements, and powertrain fasteners drawn from wire rod feedstock.
- Manufacturing:General industrial equipment and machinery frames utilizing standard structural grades.
Infrastructure commands the premium tier while Construction maintains the deepest volume footprint.
End User:
Customer capability divides the market between certification-equipped integrators and fragmented local procurement.
- Contractors:Infrastructure and construction firms consolidating procurement through tier-one distributors capable of bundling certified grades with logistics. India's western corridor contractors abandon fragmented mill relationships for single-source agreements with integrated suppliers.
- Distributors:Channel intermediaries with certification capabilities and working capital depth capturing margin pools from channel concentration.
- OEMs:Automotive and equipment manufacturers with direct mill relationships for specification-grade feedstock.
- Fabricators:Steel service centers processing sections and rebar to finished structural components.
Contractors drive the largest absolute tonnage while Distributors capture expanding margin share from channel consolidation.
Form:
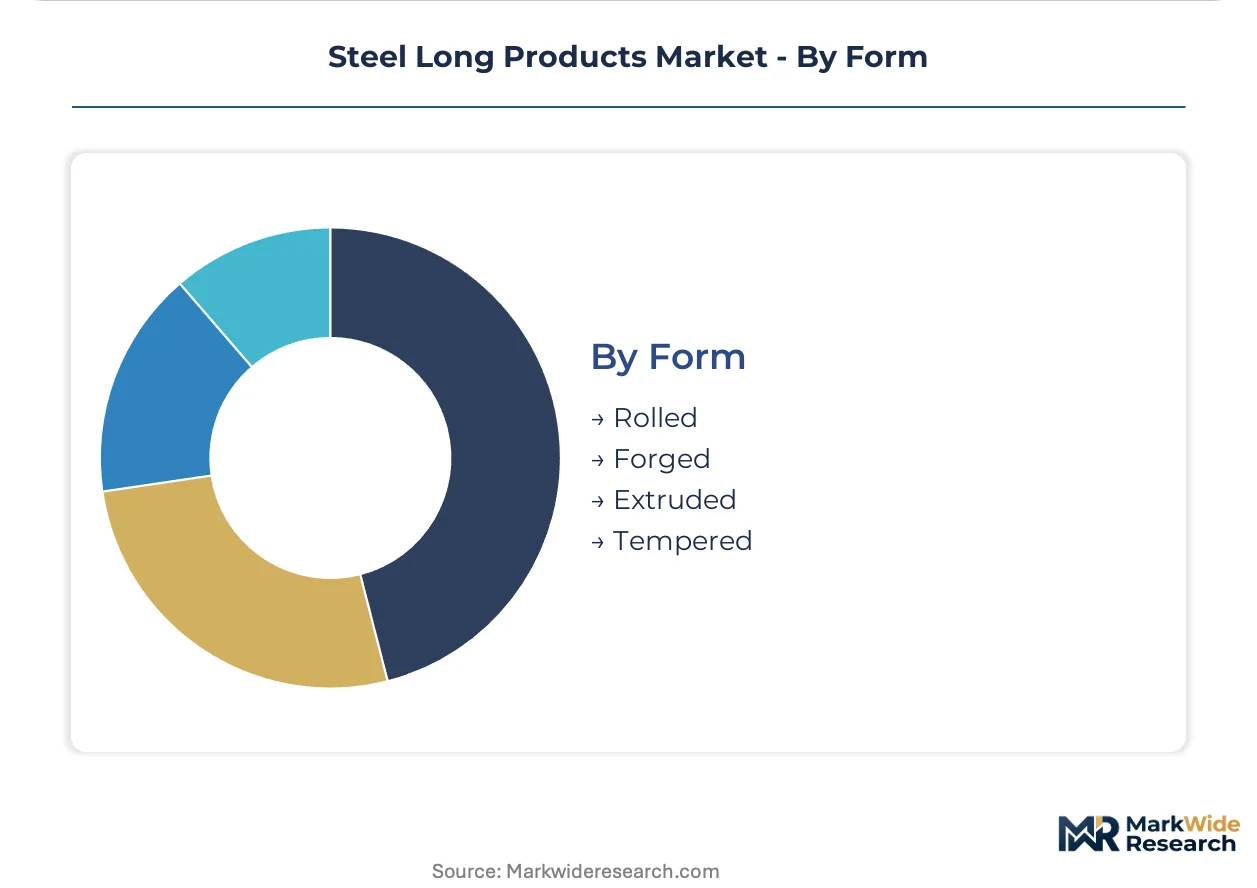
Maturity gradients separate established hot-rolling capacity from emerging precision forming technologies with distinct capital intensity profiles.
- Rolled:Hot-rolled long products from continuous casting feedstock, representing the dominant production route for rebar, wire rod, and sections. Southeast Asian rolling mills redirect capacity toward certified structural grades as infrastructure demand displaces automotive offtake.
- Tempered:Quenched and self-tempered (QST) rebar production achieving 500 MPa yields without microalloying, compressing vanadium and niobium consumption per ton.
- Forged:Hammer or press-formed components for heavy machinery and energy applications requiring directional grain structure.
- Extruded:Complex cross-sections produced through die extrusion for specialized architectural and industrial applications.
Rolled forms dominate installed capacity while Tempered grades climb fastest on metallurgical efficiency gains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese mills dominate export flows to Southeast Asian infrastructure contractors, while Indian domestic absorption tightens regional trade balances. European producers redirect section steel toward bridge and rail certification tiers.
China
SAMR-administered GB standards for seismic-grade steel filter import eligibility and redirect domestic rolling capacity toward certified structural grades. Dual carbon goals under MEE oversight compress embodied emissions thresholds for construction steel procurement. Tangshan and Jiangsu province mills supply rebar for Southeast Asian megaprojects at accelerating shipment rates.
India
BIS certification under IS 1786 creates compliance barriers for uncertified foreign suppliers accessing structural steel procurement. Mumbai-Ahmedabad industrial corridor contractors consolidate rebar procurement through tier-one distributors with certification capabilities. Gujarat and Maharashtra rolling mills capture margin pools from channel concentration as fragmented local relationships dissolve.
Japan
METI oversight of JIS standards maintains grade-specific mechanical property thresholds for structural applications. Automotive fastener and cable applications multiply demand for precision wire rod as EV architectures expand. Kansai and Chubu region producers anchor supply relationships with Southeast Asian distributors.
South Korea
MFDS-aligned quality frameworks shape export eligibility for construction-grade long products. POSCO Holdings leverages captive scrap-to-billet integration at Pohang complex to compress input cost volatility. Busan-Ulsan industrial belt concentrates section steel production for regional bridge and rail projects.
Germany
CE marking requirements under EU Construction Products Regulation mandate declared performance characteristics and digital product passports. REACH compliance adds chemical composition documentation burdens for structural steel placed on European markets. North Rhine-Westphalia and Bavaria heavy section producers adapt quality management systems fastest to batch-level traceability mandates.
Steel Long Products Market Key Industry Players
Player mix skews toward integrated steel groups with captive raw material positions and certification-equipped distributors. Structure concentrates around three strategic archetypes: backward-integrated mills controlling scrap-to-billet supply chains, premium-grade specialists commanding seismic and structural certification tiers, and scale-driven exporters serving Southeast Asian infrastructure pipelines. Competitive moves center on M&A consolidation of rolling assets and capacity expansion targeting certified structural grades.
Within the integrated mill tier, ArcelorMittal and POSCO Holdings exemplify archetypes combining captive raw material control with certification depth. Tata Steel Group occupies a position bridging premium-grade specialization and geographic diversification. Among Chinese producers, China Baowu Group and HBIS Group represent scale-driven configurations serving domestic absorption and selective export flows. These named entities anchor industry-level patterns without exhaustively mapping competitive positions.
| Leading Market Players |
|---|
| Nippon Steel Corporation |
| Shagang Group |
| China Baowu Group |
| POSCO Holdings |
| Jianlong Group |
| ArcelorMittal |
| HBIS Group |
| Tata Steel Group |
| Ansteel Group |
| Others |
Cost & Logistics Intelligence
CE marking requirements under the EU Construction Products Regulation simultaneously gate supply qualification and enable price differentiation between certified structural grades and uncertified commodity tonnage. Infrastructure contractors in India's western corridor now pay premiums for BIS-certified rebar that fragmented local mills cannot match.
Pricing Analysis
Conventional microalloying routes command higher alloy surcharges than quenched and self-tempered alternatives achieving equivalent 500 MPa yields. Pricing stratifies across seismic-certified, structural-grade, and commodity construction tiers based on certification depth and batch traceability documentation. Cost compression in commodity rebar intensifies as Chinese export volumes displace regional rolling capacity. Price-sensitive residential contractors in Southeast Asia gravitate toward uncertified tonnage, while bridge and rail projects absorb premium structural grades with minimal elasticity.
Supply Chain Analysis
Strait of Malacca transit underwrites raw material flows to Southeast Asian rolling mills dependent on Australian iron ore and Japanese scrap exports. Geographic supply concentrates in China, India, and South Korea, with Tangshan and Jiangsu province mills feeding regional infrastructure pipelines. Ferrous raw material costs hinge on seaborne iron ore volatility and vanadium-niobium alloy pricing. Single-source vulnerability concentrates in Chinese billet exports to non-integrated rolling operations. Distribution runs through tier-one distributors bundling certified grades with logistics and just-in-time delivery capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as certification mandates splinter demand between seismic-grade specialists and commodity suppliers. Infrastructure contractors consolidating procurement through integrated distributors create niches for compliance-equipped entrants.
For Market Incumbents: Secure captive scrap-to-billet integration at Pohang or Tangshan-scale complexes to compress input cost volatility. Deepen BIS and SAMR certification portfolios before timeline compression extends product development calendars. Channel control through tier-one distributors with working capital depth defends margin pools against merchant bar competitors facing documentation system investments.
For New Entrants and Emerging Players: Anchor in India's western corridor where Mumbai-Ahmedabad contractors abandon fragmented mill relationships. Target wire rod downstream drawing for automotive fastener applications as EV architectures expand high-tensile fastening requirements. Pursue go-to-market partnerships with certification-equipped distributors capable of bundling logistics with grade documentation.
For Investors and Strategic Acquirers: EU Construction Products Regulation digital product passport mandates reshape the acquisition landscape toward heavy section producers with existing quality management systems. Five-to-ten year viability favors backward-integrated mills with verified low-carbon production routes. Watch for divergence between regional carbon accounting methodologies penetrating procurement specifications as the inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Scrap-to-Billet Integration | Captive processing at Pohang-style complexes compresses input cost volatility for section producers. |
| Seismic Certification Investment | BIS IS 1786 and SAMR GB compliance opens procurement channels to India's western corridor megaprojects. |
| QST Metallurgy Transition | Quenched and self-tempered routes reduce vanadium-niobium dependence while achieving 500 MPa yields. |
| Distributor Channel Consolidation | Tier-one bundling of certified grades with logistics captures margin pools from fragmented local relationships. |
| Digital Product Passport Implementation | Batch-level traceability systems satisfy EU Construction Products Regulation mandates for bridge and rail access. |
Research Approach
Initial hypotheses were tested against primary input from rolling mill operations directors, infrastructure procurement managers, scrap broker network heads, and regulatory compliance officers at SAMR and BIS, then refined against customs trade data, SEC filings from listed steel groups, EPC contractor project databases, and national standards body certification registries. Bottom-up volume estimates from regional rolling capacity and top-down demand triangulation from construction and infrastructure project pipelines were cross-validated.
Variance decomposition across product type, application vertical, end-user capability tier, and forming technology underpinned the analytical framework over the projection horizon. CAGRs were derived from segmented growth rate reconciliation against macro construction and automotive production forecasts. Industry-specific inputs incorporated scrap-to-billet cost spreads, seismic-grade certification penetration curves, and wire rod drawing capacity expansion in Southeast Asian automotive supply chains.
Material uncertainties — iron ore and scrap price volatility, certification timeline extensions at BIS and SAMR, composite reinforcement substitution rates — sit outside the modeled envelope. Forecasts reflect assumptions about infrastructure project execution and regulatory enforcement intensity. Practitioners should keep alternative scenarios live as embodied emissions thresholds and regional carbon accounting divergence evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Aluminum Casting Market
Metals
Refined Nickel Market
Metals
High Purity Aluminium Market
Metals
Global Precious Metal Market
Metals
Copper Azoles Market
Metals
Hafnium Foil Market
Metals
Powder Metallurgy Market
Metals
Beryllium Copper for Industrial Equipment Market
Metals
Titanium Mill Products Market
Metals
US and Mexico Stainless Steel Market
Metals
Cold Drawn Wire Market
Metals
Pump Casing Materials Market
Metals
Ruthenium Market
Metals
Aluminum Powders Pastes and Flakes Market
Metals
Copper Wire Market
Metals
Metal Injection Molding (Mim) Powders Market