
 Lightweight Aluminium Pistons Market | 2026-2036
Lightweight Aluminium Pistons Market Size, Share, and Industry Trends Forecast 2026-2036
Lightweight Aluminium Pistons Market Foresight
China is rewriting capacity dynamics for lightweight aluminium pistons as domestic foundries scale billet and forged output for both local OEMs and export programs. MAHLE GmbH leverages its European R&D footprint to sustain technology leadership in thermal barrier coatings. Rheinmetall Automotive anchors high-volume supply relationships with German premium automakers through captive forging operations. Tenneco Inc. competes on machining precision across its North American and Asian production platforms.
Lightweight aluminium pistons are cylindrical components machined from aluminium alloys, typically containing silicon and copper additions, that transfer combustion force to crankshafts via connecting rods while minimizing reciprocating mass. Cast pistons dominate volume production for mass-market automotive engines due to lower unit economics, though forged variants command premium positioning in high-performance and racing applications where fatigue resistance determines component life. Powder metallurgy technology is gaining traction in aerospace engine segments where near-net-shape forming reduces material waste and machining time. Coated pistons represent a concentrated margin pool as thermal spray and anodized surface treatments extend service intervals in motorcycle and motorsport end uses.
The US EPA and NHTSA coordinate corporate average fuel economy enforcement that directly incentivizes gram-level mass reduction in engine architectures. China's MIIT administers passenger vehicle corporate average fuel consumption regulations that phase in stricter limits, compelling domestic automakers to specify lighter pistons. The EU Green Deal and REACH chemical restrictions are reshaping alloy formulations and coating chemistries across European supply chains. Stakeholders must monitor evolving multi-jurisdiction efficiency mandates and assess whether regional coating certification requirements will fragment procurement specifications or consolidate around transnational standards.
Market Dynamics
Corporate average fuel economy mandates across major automotive markets are compressing engine component mass targets, forcing OEM procurement teams to requalify piston suppliers against stricter gram-per-kilowatt specifications that favor forged aluminium architectures over traditional cast iron alternatives.
Growth Catalysts
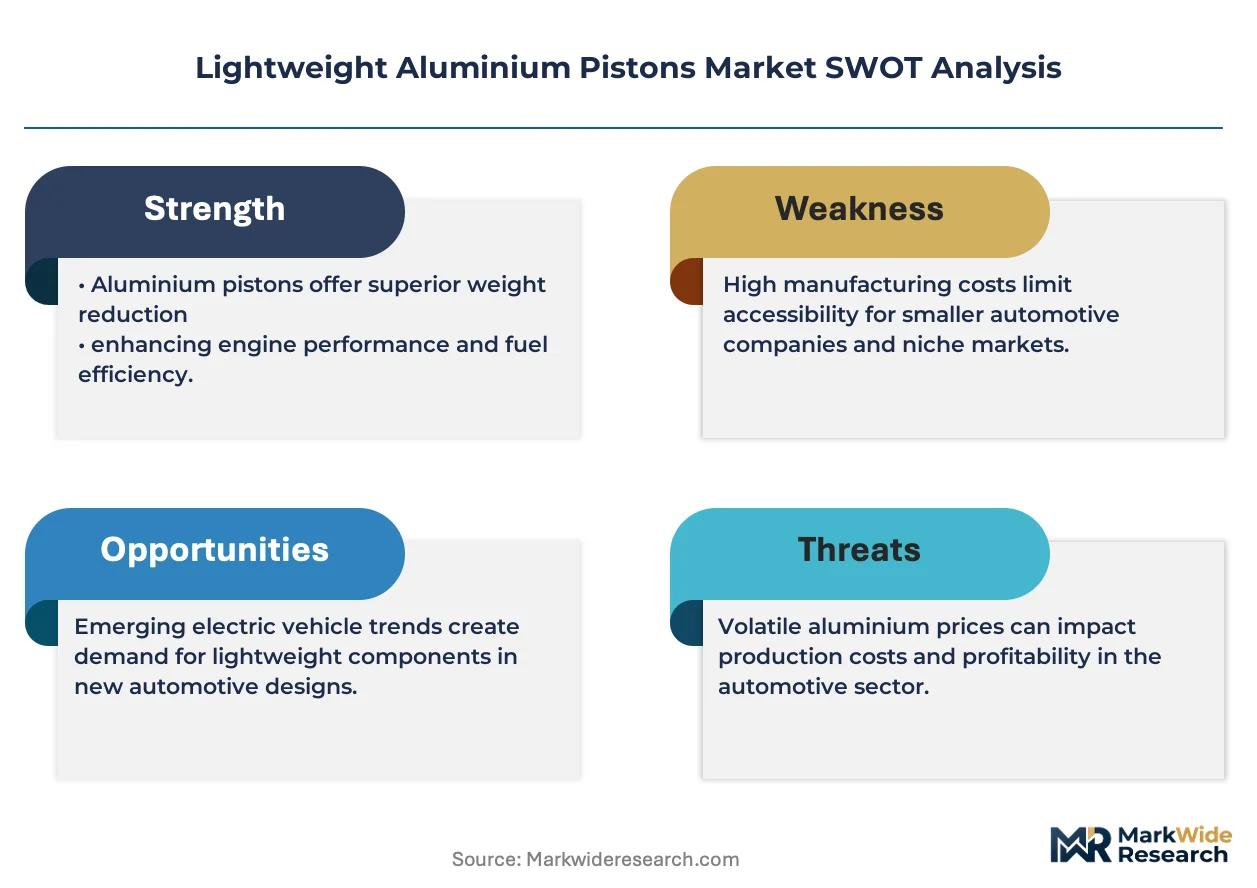
- China MIIT fuel consumption regulations:Phase-in of stricter corporate average limits compels domestic automakers to specify lighter pistons in new engine programs.
- Powder metallurgy near-net-shape forming:Aerospace engine manufacturers adopt this process to reduce material waste and machining time in low-volume production runs.
- German premium automaker demand concentration:Stuttgart and Munich manufacturing belts anchor high-volume supply relationships for forged piston assemblies.
Market Restraints
- Silicon and copper alloy input volatility:Foundry margins compress when primary aluminium and alloying element prices spike on commodity exchanges.
- Single-source forging capacity risk:Captive forging operations in Central Europe create geographic concentration exposure for just-in-time supply chains.
- REACH chemical restrictions:ECHA oversight of coating chemistries forces reformulation of thermal barrier and anodized surface treatments.
Strategic Opportunities
- India PLI scheme for automotive components:Domestic foundries can access production-linked incentives to scale billet and forged output for export programs.
- Thermal spray coating certification gap:Motorcycle and motorsport end uses lack harmonized testing protocols, creating first-mover advantage for validated suppliers.
- Dual carbon goals in China:NMPA and MEE alignment on decarbonization creates procurement preference for low-carbon primary aluminium in piston alloys.
Industry Challenges
- Thermal barrier coating application specialist shortage:Plasma spray technicians with aerospace-grade certification command premium wages and limited labor pool mobility.
- Multi-jurisdiction efficiency mandate tracking burden:Procurement teams must reconcile divergent EPA, MIIT, and EU Green Deal compliance timelines in global platform engineering.
- Legacy cast piston tooling amortization:Mass-market foundries face stranded asset risk as OEMs accelerate forged architecture transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lightweight Aluminium Pistons Market |
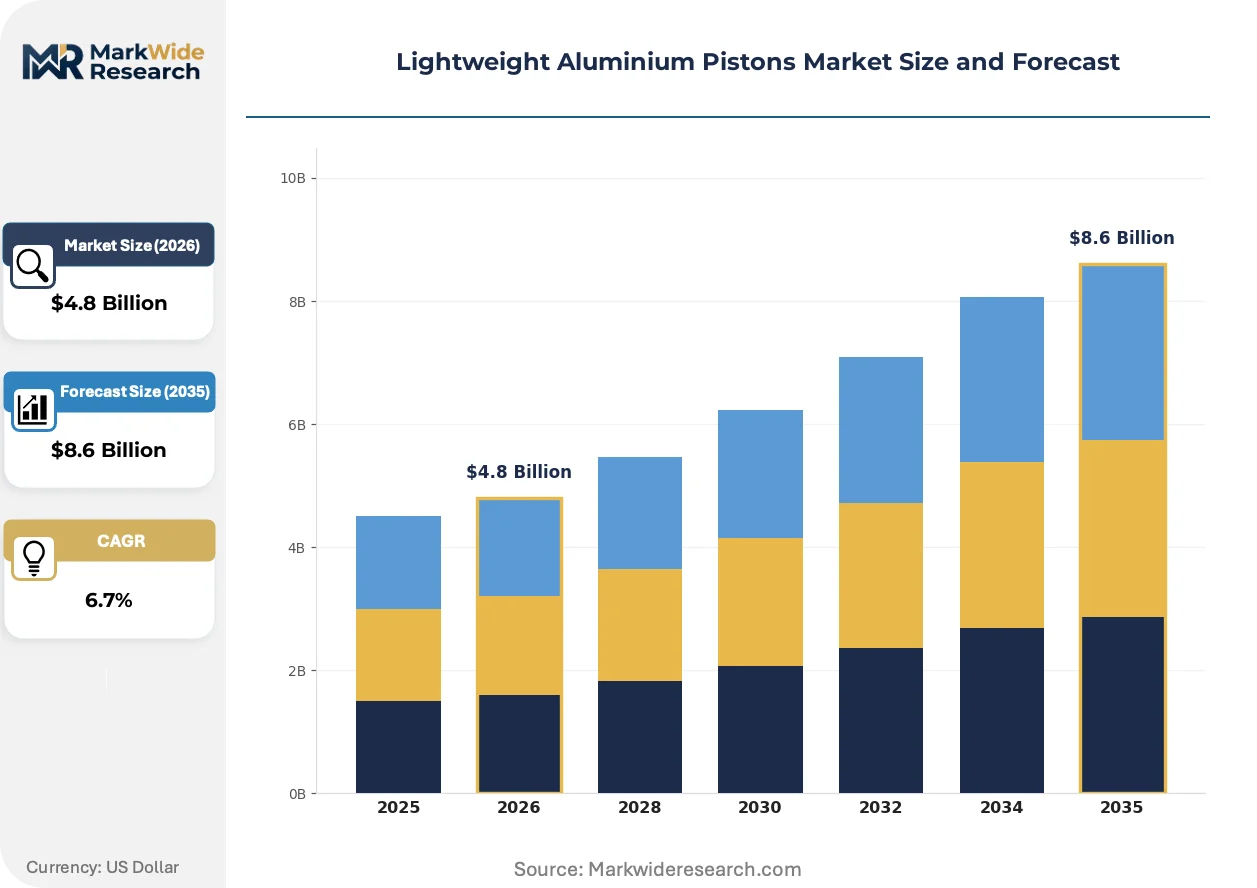
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Forged Pistons, Cast Pistons, Billet Pistons, Coated Pistons Application: Automotive Engines, Aerospace Engines, Motorcycle Engines, Racing Engines End User: OEMs, Aftermarket Suppliers, Aviation Manufacturers, Motorsport Teams Technology: Machining, Casting, Powder Metallurgy, 3D Printing |
| Companies Covered | MAHLE GmbH, Rheinmetall Automotive, Tenneco Inc., Aisin Seiki Co., Ltd., Hitachi Astemo, Riken Corporation, ART Metal MFG. Co., Ltd., Binzhou Bohai Piston Co., Ltd., BorgWarner Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lightweight Aluminium Pistons Market Shifts & Advancements
Material science advances and regulatory chemistry restrictions are simultaneously enabling and constraining next-generation piston architectures, creating divergent innovation paths across automotive, aerospace, and motorsport end uses.
Silicon-carbide reinforced aluminium matrix composites are rendering obsolete conventional hypereutectic alloys in high-performance racing applications. Formula 1 and top-tier motorsport engine builders have completed supplier qualification for these materials. The technology is compressing acceptable service intervals for thermal fatigue resistance in extreme combustion environments.
EU REACH annex XVII restrictions on hexavalent chromium compounds are forcing coating suppliers to accelerate trivalent chrome and ceramic-alternative development programs. Anodizing shops serving European automotive Tier 1s face process revalidation costs. Motorcycle piston manufacturers in Italy and Spain are most exposed due to decorative finish requirements.
Consolidated procurement by platform engineering teams is displacing legacy component-silo buying in multinational OEMs. Powertrain directors now mandate cross-vehicle-line piston specifications to amortize qualification costs. This concentration is most visible in Germany, where Volkswagen Group and BMW have centralized forging supplier panels under single contract frameworks.
Lightweight Aluminium Pistons Market Segmentation
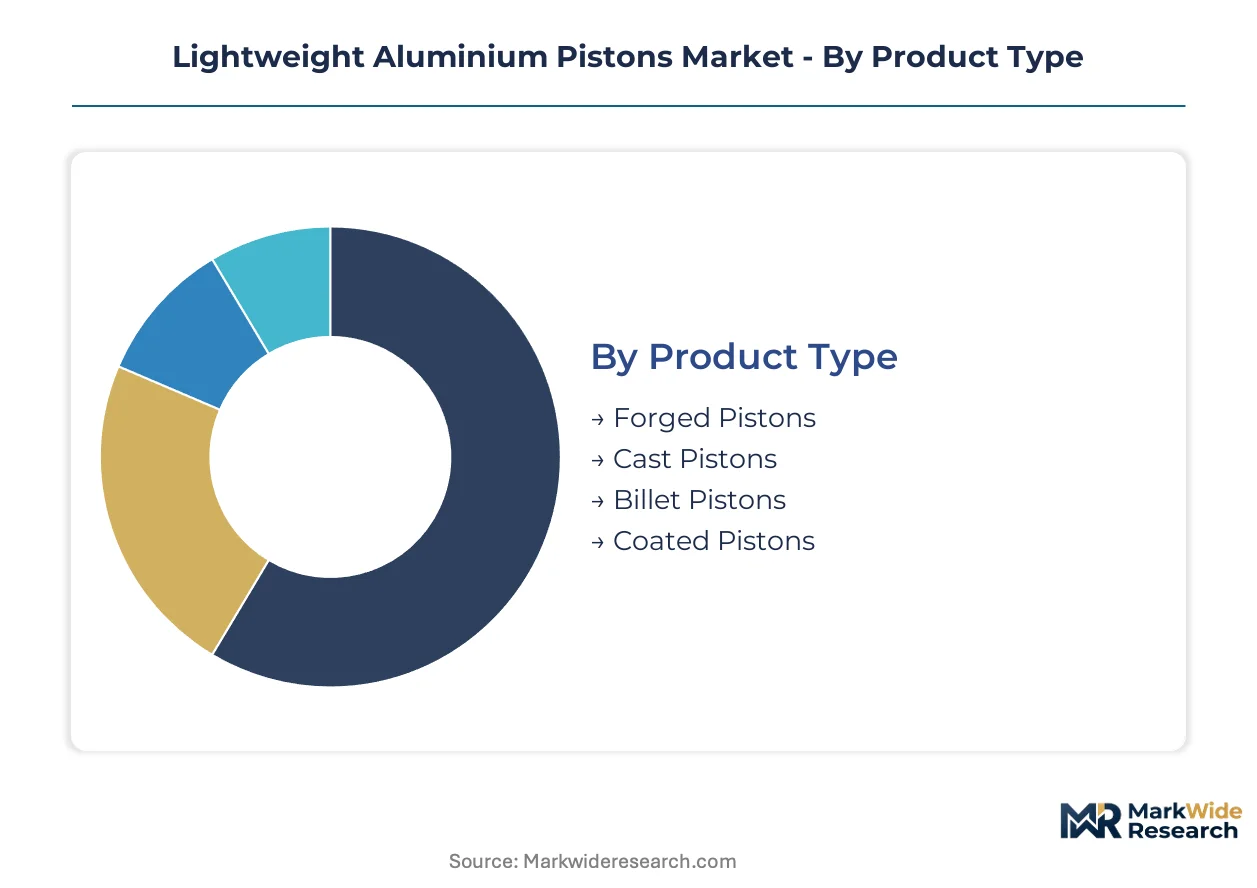
Segmentation in the lightweight aluminium pistons market reveals how manufacturing economics, performance requirements, and regulatory pressures fragment procurement patterns across end-use verticals. Suppliers must align production capabilities with distinct qualification protocols that separate mass-market automotive from aerospace and motorsport tiers.
Product Type:
Mature forging and casting technologies anchor volume production, while emerging coating and billet architectures capture premium positioning in performance-critical applications.
- Forged Pistons:These components undergo high-pressure deformation of aluminium alloy billets to align grain structures along stress paths, delivering superior fatigue resistance for high-compression engines. German premium automakers in Stuttgart and Munich specify forged architectures to meet corporate average fuel economy mandates. Cast Pistons handle the majority of throughput; Coated Pistons is the fastest mover on share.
- Cast Pistons:Gravity and pressure die casting of hypereutectic aluminium-silicon alloys dominates mass-market production due to lower tooling amortization and cycle times. Foundries in China's manufacturing belts supply domestic OEMs facing MIIT fuel consumption regulations.
- Billet Pistons:CNC-machined from solid alloy stock for low-volume racing and custom applications where forging die economics fail.
- Coated Pistons:Thermal barrier and anodized surface treatments extend service intervals; motorcycle and motorsport end uses drive specification.
Forged variants command qualification panels at German premium OEMs; coated architectures are climbing the fastest as thermal management requirements intensify.
Application:
Volume concentration tracks automotive production scale, while margin pools concentrate in aerospace and racing segments where material certification barriers limit supplier entry.
- Automotive Engines:Passenger vehicle and light truck powertrains consume the majority of lightweight piston output, with procurement teams specifying gram-per-kilowatt mass targets under EPA and NHTSA corporate average fuel economy enforcement. China's domestic automakers accelerate forged adoption under MIIT phase-in schedules.
- Aerospace Engines:Powder metallurgy near-net-shape forming reduces material waste in low-volume turbine and reciprocating engine programs. EASA and FAA certification protocols demand extensive fatigue testing that extends supplier qualification timelines.
- Motorcycle Engines:High-revving single and twin-cylinder architectures prioritize reciprocating mass reduction; Italian and Spanish manufacturers specify decorative anodized finishes facing REACH hexavalent chromium restrictions.
- Racing Engines:Silicon-carbide reinforced aluminium matrix composites from Formula 1 supplier qualification programs now penetrate top-tier motorsport.
Automotive applications absorb the bulk of unit volume; aerospace and racing segments deliver the steepest margin expansion trajectories.
End User:
Procurement concentration distinguishes captive OEM supply relationships from fragmented aftermarket distribution, with aviation and motorsport tiers operating on project-based batch economics.
- OEMs:Volkswagen Group and BMW have centralized forging supplier panels under single contract frameworks to amortize qualification costs across vehicle lines. Platform engineering teams now mandate cross-vehicle-line piston specifications.
- Aftermarket Suppliers:Independent distributors and engine rebuilders source cast and billet replacements for legacy vehicle parc maintenance; inventory risk concentrates in slow-moving SKU portfolios.
- Aviation Manufacturers:Airframe and engine OEMs specify pistons against FAA and EASA material traceability requirements that extend lead times.
- Motorsport Teams:Formula 1 and endurance racing programs commission bespoke forged and composite pistons on annual development cycles.
OEM procurement panels dominate volume commitment; motorsport teams represent the most volatile demand pattern with annual specification turnover.
Technology:
Process selection determines capital intensity and geometric capability, with conventional machining and casting facing displacement from additive and powder routes in niche applications.
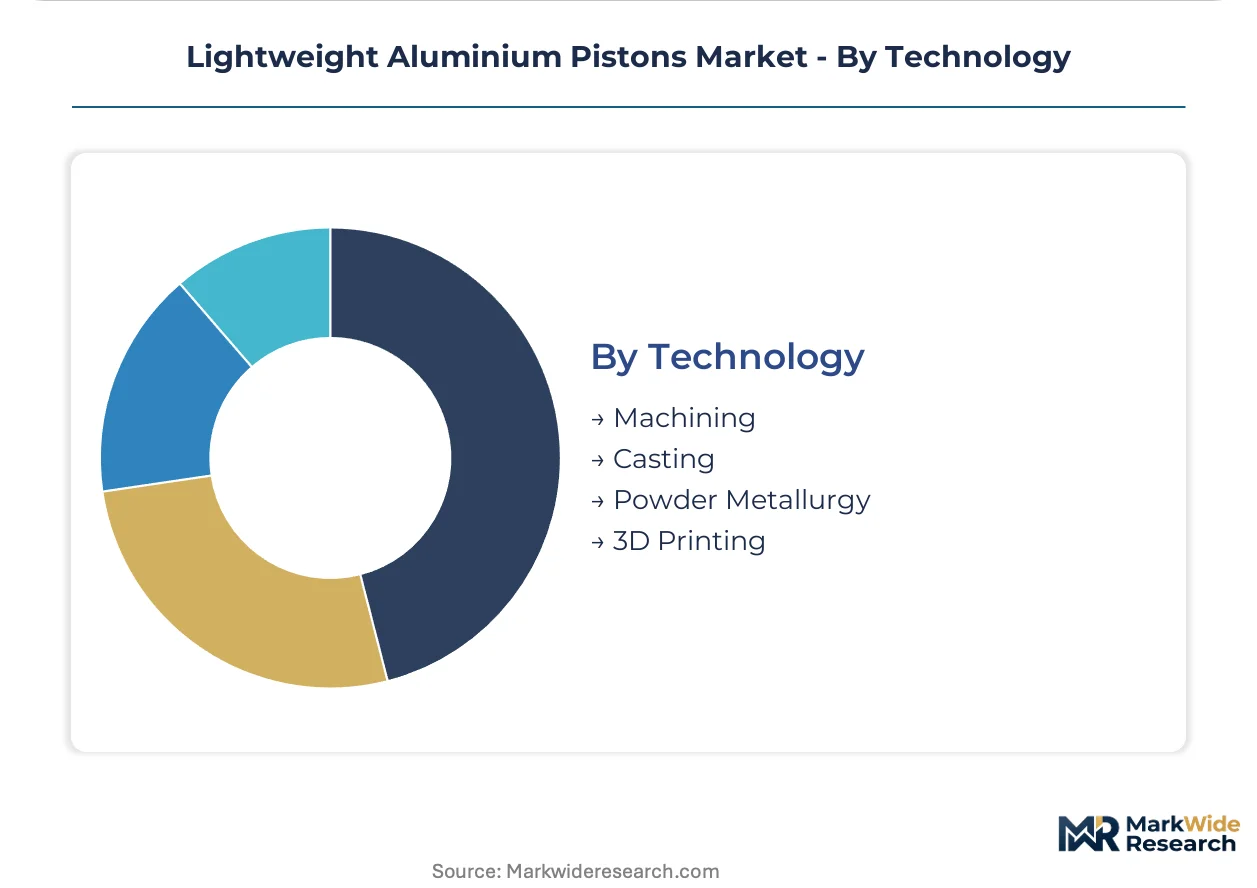
- Machining:CNC finishing operations precision-grind piston skirts and ring grooves to micron tolerances; Tenneco Inc. competes on machining precision across North American and Asian production platforms.
- Casting:Gravity die and squeeze casting of hypereutectic alloys remains the cost baseline for mass-market automotive; China's domestic foundries scale billet and forged output for export programs.
- Powder Metallurgy:Near-net-shape forming from pre-alloyed powders reduces machining waste in aerospace low-volume production runs.
- 3D Printing:Laser powder bed fusion enables topology-optimized cooling galleries for racing prototypes; process certification barriers limit production adoption.
Casting and machining handle current throughput; powder metallurgy is expanding most quickly in aerospace qualification pipelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT anchors the dominant geography, with fuel consumption regulations compelling automakers to specify lighter pistons across new engine programs. The report identifies five countries where production concentration and regulatory pressure intersect most directly.
China
Domestic foundries scale billet and forged output for local OEMs and export programs. NMPA and MIIT alignment on dual carbon goals creates procurement preference for low-carbon primary aluminium in piston alloys. Manufacturing belts in the Yangtze River Delta and Pearl River Delta concentrate high-volume casting operations serving BYD and Geely.
Germany
Premium automakers in Stuttgart and Munich anchor high-volume supply relationships for forged piston assemblies. EU Green Deal and REACH chemical restrictions reshape alloy formulations and coating chemistries across supply chains. The Baden-Württemberg manufacturing corridor hosts captive forging operations supplying Volkswagen Group and BMW centralized procurement panels.
United States
EPA and NHTSA coordinate corporate average fuel economy enforcement that directly incentivizes gram-level mass reduction in engine architectures. Machining precision competition intensifies across North American production platforms. The Southeast automotive corridor spanning Tennessee and Alabama concentrates piston finishing operations for transplant OEMs.
Japan
High-revving engine architectures prioritize reciprocating mass reduction in motorcycle and compact automotive applications. METI administers industrial standards that influence alloy specifications for export-oriented manufacturers. The Aichi Prefecture cluster around Nagoya anchors precision machining capabilities serving Toyota and Honda powertrain divisions.
India
Domestic foundries access production-linked incentives under the PLI scheme for automotive components to scale billet and forged output for export programs. BIS certification requirements align with emerging fuel efficiency mandates for passenger vehicles. The Gujarat and Tamil Nadu manufacturing corridors concentrate new capacity investments by aluminium processors.
Lightweight Aluminium Pistons Market Competitive Landscape
Capability concentration sits with forging specialists and coating technology holders; scale advantage sits with integrated automotive Tier 1s with captive machining networks. The market structures around three tiers: premium forged suppliers serving German OEMs, high-volume cast producers for mass-market programs, and coating specialists capturing margin in motorsport and motorcycle segments. Dominant competitive moves include backward integration into primary aluminium sourcing and strategic partnerships with aerospace certification bodies.
Within the European forging tier, MAHLE GmbH and Rheinmetall Automotive exemplify capability concentration through captive R&D and production integration. Tenneco Inc. occupies a position spanning North American and Asian machining platforms. These three entities represent distinct archetypes: technology leadership through thermal barrier development, supply security through vertical forging control, and geographic scale through multi-continental production footprints.
| Leading Market Players |
|---|
| MAHLE GmbH |
| Rheinmetall Automotive |
| Tenneco Inc. |
| Aisin Seiki Co., Ltd. |
| Hitachi Astemo |
| Riken Corporation |
| ART Metal MFG. Co., Ltd. |
| Binzhou Bohai Piston Co., Ltd. |
| BorgWarner Inc. |
| Others |
Supply & Pricing Matrix
The Baden-Württemberg manufacturing corridor around Stuttgart anchors European forging capacity, and its captive supply relationships with Volkswagen Group and BMW translate directly into pricing power for qualified Tier 1 suppliers. German premium OEM procurement panels compress supplier margins through consolidated contract frameworks, while Chinese foundries in the Yangtze River Delta undercut on unit economics for mass-market cast piston programs.
Pricing Analysis
Geographic price spreads between German forged piston assemblies and Chinese cast alternatives compress as MIIT fuel consumption regulations accelerate specification convergence. Three-tier pricing structure across premium forged, standard cast, and economy uncoated levels tracks certification grade and thermal barrier coating investment. Pricing pressure stems from silicon and copper alloy input volatility on commodity exchanges. Aftermarket rebuilders exhibit highest price sensitivity; motorsport teams show lowest sensitivity due to annual specification turnover.
Supply Chain Analysis
Tariff exposure between China and Western automotive markets dominates supply chain risk calculus for piston manufacturers with cross-border billet shipments. Production concentrates in China, Germany, and Japan, with each hub serving distinct OEM qualification tiers. Raw material dependencies rest on primary aluminium ingot, silicon carbide reinforcement powders, and hexavalent chromium alternatives for REACH-compliant coatings. Single-source forging capacity risk in Central Europe threatens just-in-time supply chains. Distribution runs through captive OEM supplier panels and fragmented aftermarket distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires substitution defense against silicon-carbide reinforced aluminium matrix composites penetrating top-tier motorsport and aerospace applications. Incumbents must navigate material science advances that threaten conventional hypereutectic alloy positioning.
For Market Incumbents: Insulate forging qualification relationships with German premium OEMs through thermal barrier coating R&D investment at MAHLE GmbH's European footprint. Backward integration into low-carbon primary aluminium sourcing addresses NMPA and MEE dual carbon procurement preferences in China. Defend against powder metallurgy displacement in aerospace by accelerating EASA certification timelines. For New Entrants and Emerging Players: Build out thermal spray coating certification capabilities for motorcycle and motorsport end uses where harmonized testing protocols remain absent. India's PLI scheme for automotive components offers the most penetrable geography for scaled billet and forged export capacity. Target platform engineering centralization trends by qualifying across multiple vehicle lines simultaneously. For Investors and Strategic Acquirers: Carve-out targets emerge from automotive Tier 1s divesting non-core piston operations under portfolio consolidation pressures. Long-term viability over the next decade hinges on coating technology ownership and aerospace certification access. Watch for MIIT fuel consumption regulation phase-in acceleration as the critical demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Low-Carbon Aluminium | NMPA and MEE alignment on dual carbon goals creates procurement preference for decarbonized primary metal inputs. |
| Thermal Barrier Coating Certification Investment | ECHA REACH restrictions on hexavalent chromium force reformulation of plasma spray and anodized surface treatments. |
| Powder Metallurgy Capability Buildout | EASA and FAA fatigue testing protocols extend qualification timelines but lock in aerospace margin pools. |
| Platform Standardization Partnership | Volkswagen Group and BMW centralized procurement panels amortize qualification costs across vehicle lines. |
| India PLI Scheme Capacity Expansion | Domestic foundries in Gujarat and Tamil Nadu access production-linked incentives for export program scale. |
Research Methodology
Initial hypotheses were tested against primary input from OEM platform engineers, Tier 1 supplier procurement leads, foundry operations managers, and thermal spray coating technicians and refined through secondary validation. Primary interviews explored gram-per-kilowatt specification trajectories and REACH compliance reformulation timelines. Secondary sources included EPA and NHTSA corporate average fuel economy enforcement documents, MIIT passenger vehicle consumption regulation filings, ECHA REACH annex XVII restriction updates, and IHS Markit vehicle production databases. Bottom-up piston unit demand modeling triangulated against top-down automotive powertrain production forecasts.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation modeled by manufacturing process, application vertical, end-user procurement type, and regional regulatory cluster. CAGRs were derived from production volume trajectories and alloy input cost curves. Industry-specific forecast inputs incorporated MIIT phase-in schedules for fuel consumption limits and EASA certification pipeline durations for powder metallurgy aerospace components.
The forecast holds incumbent behavior within observed patterns; aggressive moves by silicon-carbide composite specialists or accelerated REACH restriction timelines would shift outcomes. Forecasts assume continued primary aluminium price volatility and stable German premium OEM supplier panel structures. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Zinc Dust Market
Metals
Global Electrolytic Copper Foil Market
Metals
India Steel Market
Metals
Medium Carbon Steel Market
Metals
Carbotanium Market
Metals
GCC Metal Forging Market
Metals
Huntite Market
Metals
Metal Coil Lamination Market
Metals
GCC Aluminium Cans Market
Metals
Japan Aluminium Powder Market
Metals
Bismuth Oxide Market
Metals
Global Welding Powder Market
Metals
North America Grain Oriented Electrical Steel Market
Metals
Global Copper Sputtering Target Market
Metals
Welding Materials Market
Metals
Aluminum Flat Products Market