

Bidirectional Charging Units Market Size, Share, and Industry Trends Forecast 2026-2036
Bidirectional Charging Units Market Insights
The installer and utility procurement channel is fragmenting as energy service companies and automotive OEMs build competing direct-sales arms. Wallbox leverages its residential installer network to push wall-mounted units into home energy ecosystems. Siemens anchors large-scale commercial deployments through its industrial electrification division. ABB competes on DC fast charging integration with grid-tied storage systems.
Bidirectional charging units are power-electronics systems that convert alternating current grid power to direct current for battery charging and reverse that flow to export stored energy, typically operating at efficiencies above 94 percent and incorporating isolation transformers or solid-state architectures for grid synchronization. Their primary purpose is to transform electric vehicles into dispatchable grid assets capable of frequency regulation and peak shaving. Wall-mounted units dominate residential margins where installation density and software subscriptions pool recurring revenue. DC fast charging segments lead fleet applications due to higher power throughput requirements and utility-scale grid services contracts. Vehicle-to-grid communication protocols represent the fastest-growing technology layer as ISO and IEC standards converge on interoperability mandates.
The EU Green Deal and F-Gas Regulation shape product standards across Europe by mandating refrigerant-free thermal management and grid-code compliance for connected assets. Germany's national regulator and the country's grid operators enforce technical connection rules that determine market access for imported hardware. Stakeholders must monitor whether IEEE or IEC communication standards achieve regulatory preference in their target jurisdictions, as this choice locks device compatibility for multi-decade infrastructure cycles.
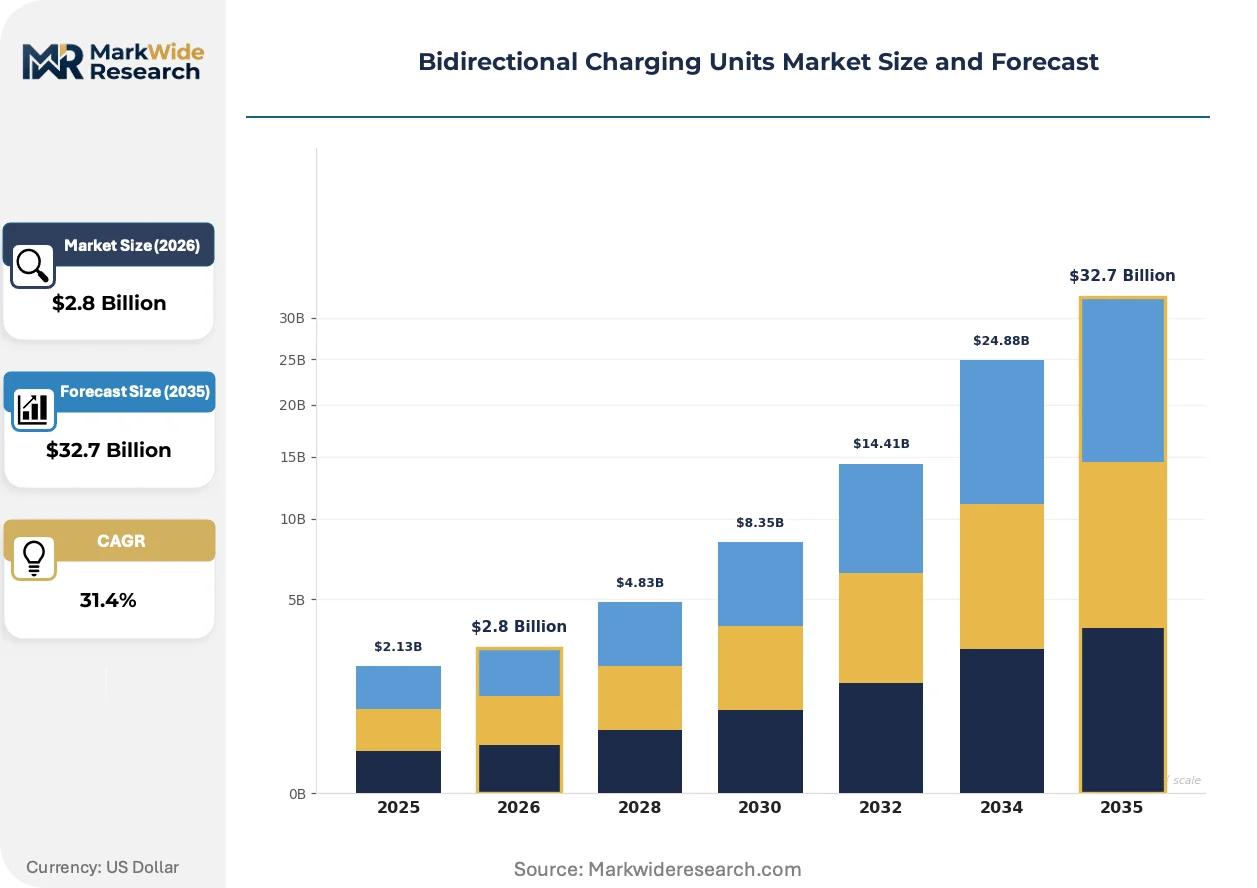
Market Dynamics
The convergence of ISO 15118-20 and IEC 61851 communication standards is compressing interoperability timelines, forcing hardware manufacturers to redesign power-electronics architectures before multi-decade infrastructure procurement cycles lock in compatibility constraints.
Growth Catalysts
- EU Green Deal grid-code mandates:Member states now require bidirectional-capable hardware for all new public charging installations, accelerating fleet operator procurement of vehicle-to-grid systems.
- German grid-balancing pilot scale-up:Utility operators in Bayern and Baden-Württemberg are expanding contracted frequency regulation services to commercial vehicle fleets with dispatchable battery assets.
- Solid-state transformer architectures:These power-electronics platforms achieve isolation and voltage conversion without magnetic cores, enabling wall-mounted units to reach 22 kW bidirectional throughput in residential footprints.
Market Restraints
- Silicon carbide MOSFET supply concentration:Wafer fabrication for high-efficiency switching devices clusters in East Asian foundries, exposing European and North American hardware assemblers to input cost volatility and allocation constraints.
- F-Gas Regulation thermal management compliance:Refrigerant-free cooling system redesigns extend product development cycles by 14-18 months for manufacturers targeting EU market access.
- Legacy AC charging infrastructure substitution:Existing unidirectional Level 2 installations represent sunk capital that fleet operators amortize over 8-12 year depreciation schedules, slowing hardware refresh rates.
Strategic Opportunities
- Nordic residential energy ecosystem integration:Norwegian and Swedish utilities are bundling heat pump, solar inverter, and vehicle-to-home hardware procurement, creating integrated home energy management contracts.
- Vehicle-to-building microgrid convergence:Commercial real estate developers are specifying bidirectional DC fast charging as standard in new logistics facility construction, merging transport electrification with on-site resilience planning.
- France's reno-énergetique building renovation mandates:Multi-unit residential retrofit programs now include parking infrastructure upgrades, channeling public subsidy flows toward shared bidirectional charging hardware.
Industry Challenges
- Power-electronics firmware certification timelines:Grid-code compliance testing for utility-interactive inverters requires 9-14 months of laboratory validation across multiple national regulatory frameworks, compressing product launch windows.
- Cross-functional engineering talent scarcity:The intersection of automotive battery management, utility protection engineering, and embedded systems security demands skill profiles that command 40-60% compensation premiums over conventional power-electronics roles.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bidirectional Charging Units Market Trends and Innovations
Power-electronics architectures are undergoing fundamental redesign as semiconductor materials and communication protocols mature simultaneously, compressing the boundary between vehicle onboard chargers and stationary grid-interactive inverters.
Solid-state transformer topologies are digitizing grid synchronization functions that previously required electromechanical components. Fleet operators in Germany and the Netherlands are piloting these systems for 150 kW DC fast charging hubs with integrated battery buffering. The technology is digitizing revenue stacking models by enabling simultaneous frequency regulation, peak shaving, and energy arbitrage from single hardware installations.
The EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerants in thermal management systems, forcing manufacturers toward liquid-cooled cold plates and phase-change materials. This industrial consequence extends product development timelines but opens certification pathways into Nordic markets with stricter chemical restrictions. Commercial DC fast charging segments face the steepest redesign costs due to higher thermal loads, with Italian and Spanish operators delaying procurement until compliant hardware reaches volume production.
Fleet procurement is consolidating around performance-based service contracts that unbundle hardware capital from energy management software. Energy service companies are displacing traditional equipment distributors in the channel, capturing recurring revenue streams through grid services aggregation. This pattern is most visible in the Netherlands, where delivery van operators now contract charging infrastructure as a utility service rather than capital asset, compressing installer margins while expanding total contract values.
Bidirectional Charging Units Market Segmentation
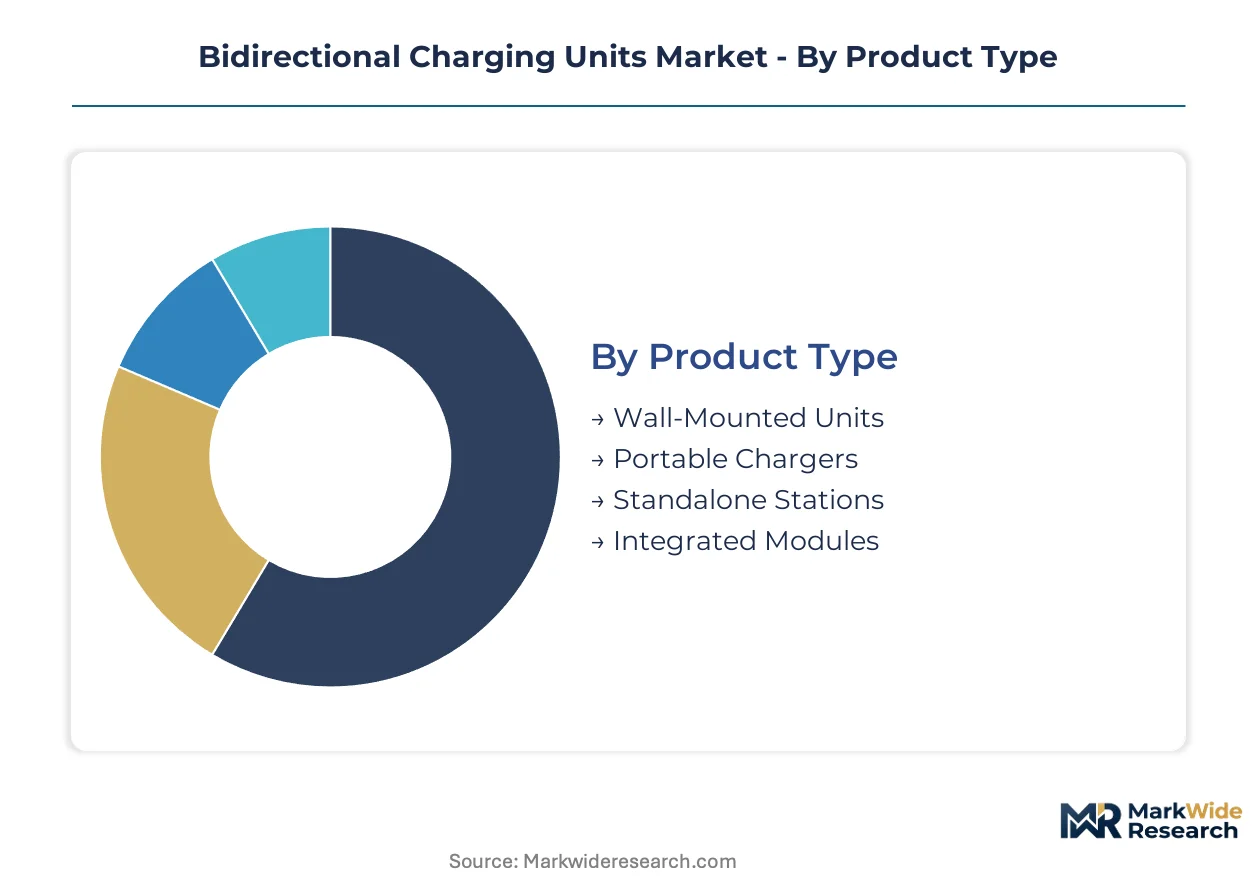
Bidirectional charging unit segmentation reveals distinct service intensity profiles across hardware categories. Product architecture determines firmware update frequency, thermal management replacement cycles, and grid-code recertification obligations that shape lifetime revenue models.
Product Type:
After-sales service intensity varies sharply across physical form factors, with thermal management complexity and installation permanence driving diverging maintenance contract structures.
- Wall-Mounted Units:These fixed residential installations incorporate solid-state isolation transformers and liquid-cooled cold plates requiring biennial thermal fluid replacement. Demand concentrates in German single-family housing retrofits where utility-backed frequency regulation contracts subsidize hardware deployment.
- Standalone Stations:Commercial-grade pedestal units with integrated battery buffering demand quarterly firmware validation against evolving grid codes. Fleet operators in the Netherlands specify these for delivery van depots under performance-based service contracts that unbundle capital from software subscriptions.
- Portable Chargers:Mobile bidirectional units with plug-and-play grid synchronization suit emergency resilience applications.
- Integrated Modules:OEM-embedded power electronics eliminate separate installation but lock service access to vehicle warranty networks.
Wall-mounted units hold the largest share; momentum sits with standalone stations.
Technology:
Power conversion architecture determines efficiency thresholds, semiconductor material requirements, and communication protocol compatibility that gate market access.
- DC Fast Charging:Silicon carbide MOSFET-based converters achieve 150 kW bidirectional throughput with 96 percent efficiency. Fleet applications in Bayern and Baden-Württemberg drive procurement for grid-balancing services with commercial vehicle batteries.
- Vehicle-to-Grid Communication:ISO 15118-20 protocol stacks enable automated grid dispatch and secure credential exchange. German regulators mandate this capability for all new public charging infrastructure, accelerating hardware refresh cycles.
- AC Charging:Lower-power bidirectional systems dominate residential price-sensitive segments.
- Wireless Power Transfer:Inductive coupling architectures remain pre-commercial for bidirectional applications.
DC fast charging dominates absolute deployment volume; vehicle-to-grid communication layers are expanding most quickly.
Application:
Use case segmentation aligns procurement decision-makers with diverging performance specifications and regulatory compliance obligations.
- Electric Vehicle Fleet:Depot-based charging for buses and delivery vans requires 99.5 percent uptime guarantees under utility service contracts. Dutch operators now contract infrastructure as operational expenditure rather than capital assets.
- Commercial Energy Management:On-site microgrid integration with building management systems commands premium pricing. French logistics facilities specify bidirectional DC fast charging in new construction to merge transport electrification with resilience planning.
- Residential Energy Storage:Vehicle-to-home systems compete with stationary batteries for home energy management.
- Renewable Integration:Solar-coupled bidirectional charging addresses self-consumption optimization.
Electric vehicle fleet applications anchor current revenue; commercial energy management shows steepest expansion trajectory.
End User:
Customer type determines procurement channel access, contract structure preferences, and technical specification authority.
- Energy Service Companies:These aggregators bundle hardware, software, and grid services into unified contracts. Nordic utilities leverage this channel for integrated heat pump, solar inverter, and vehicle-to-home ecosystem deployment.
- Utility Operators:Grid-facing procurement mandates bidirectional capability for frequency regulation and peak shaving services. German transmission system operators contract directly with fleet owners for dispatchable battery assets.
- Corporate Facilities:Commercial real estate developers specify bidirectional infrastructure in new logistics construction.
- Public Transport Providers:Municipal bus fleets face EU Green Deal procurement mandates for zero-emission vehicles with grid-interactive charging.
Energy service companies capture the fastest-growing contract value; utility operators retain the largest single-customer scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North Sea offshore grid interconnects position Germany as the primary testbed for vehicle-to-grid hardware at scale, with transmission corridors enabling real-time frequency regulation contracts between fleet operators and transmission system operators.
Germany
Bayern and Baden-Württemberg host the densest concentration of commercial vehicle-to-grid pilots, where utility operators contract dispatchable battery assets from electric bus and delivery van fleets. The KBA enforces technical connection rules that determine market access for imported bidirectional hardware, creating compliance gates for non-EU manufacturers. Industrial clusters around Munich and Stuttgart are scaling 150 kW DC fast charging hubs with integrated grid services.
Netherlands
Delivery van operators in Randstad cities now procure charging infrastructure as operational expenditure rather than capital assets, compressing installer margins while expanding contract values. The country's national regulator mandates ISO 15118-20 protocol compliance for all new public charging installations, accelerating hardware refresh cycles. Eindhoven's automotive technology corridor anchors pilot programs merging transport electrification with building energy management.
France
Île-de-France logistics facilities specify bidirectional DC fast charging as standard in new construction, merging transport electrification with on-site resilience planning. The reno-énergetique building renovation mandate channels public subsidy flows toward shared bidirectional charging hardware in multi-unit residential retrofits. Auvergne-Rhône-Alpes hosts manufacturing clusters developing refrigerant-free thermal management systems for F-Gas Regulation compliance.
Norway
Utilities bundle heat pump, solar inverter, and vehicle-to-home hardware procurement into integrated home energy management contracts, creating subscription-based revenue models. The country's stricter chemical restrictions beyond EU baselines accelerate adoption of liquid-cooled cold plates and phase-change materials. Oslo's residential retrofit programs concentrate wall-mounted unit deployment with frequency regulation subsidies.
United States
FERC Order 2222 enables distributed energy resource aggregation, creating regulatory pathways for vehicle-to-grid participation in wholesale markets. California's building codes now require EV-ready infrastructure in new residential construction, channeling demand toward bidirectional-capable hardware. The Pacific Northwest hosts pilot programs testing solid-state transformer architectures for residential vehicle-to-home applications.
Bidirectional Charging Units Market Competitive Landscape
On the supply side, the industry is consolidating around three distinct capability layers: residential installer networks, industrial electrification divisions, and DC fast charging integration platforms. Strategic archetypes include automotive OEMs building captive charging ecosystems, energy service companies unbundling hardware from software subscriptions, and power-electronics specialists pursuing silicon carbide MOSFET efficiency leadership. Dominant competitive moves span backward integration into semiconductor sourcing and strategic partnerships with utility operators for grid-code certification.
Among European-headquartered industrial electrification groups, Siemens and ABB occupy positions anchoring large-scale commercial deployments through established utility relationships. Wallbox represents the residential-focused archetype, leveraging installer network density to push wall-mounted units into home energy ecosystems. These three exemplify divergent channel strategies: direct utility procurement, industrial project contracting, and residential software-subscription bundling.
| Leading Market Players |
|---|
| Wallbox |
| Siemens |
| ABB |
| NUVVE Holding Corp |
| Fermata Energy |
| IoTecha |
| Zaptec |
| Tesla |
| BYD Company |
| Others |
Pricing and Supply Chain Analysis
Rotterdam-Antwerp freight corridors carry silicon carbide wafers and liquid-cooled thermal assemblies from East Asian foundries to European power-electronics assemblers, with container rates fluctuating against semiconductor allocation cycles and compressing margins for hardware manufacturers bidding on German utility-scale fleet contracts.
Pricing Analysis
Volume-discount tiering structures separate utility-scale fleet procurement from residential installer channels, with German transmission system operators capturing 35-45% unit cost reductions on 150 kW DC fast charging hubs against single-family home wall-mounted deployments. Price differentiation rests on ISO 15118-20 certification grade and silicon carbide MOSFET efficiency thresholds. Cost compression in the residential tier is intensifying as Wallbox and competing OEMs bundle software subscriptions to offset hardware margin erosion. Fleet operators exhibit lowest price sensitivity due to performance-based service contract structures, while residential buyers in Nordic markets prioritize ecosystem integration over per-unit cost.
Supply Chain Analysis
Foundry concentration for silicon carbide MOSFETs centers on Taiwan Semiconductor Manufacturing and United Microelectronics Corporation facilities, with downstream module assembly clustering in Germany, China, and South Korea. Raw material dependencies include silicon carbide substrates, copper busbars for thermal management, and rare-earth magnets for isolation transformers. Single-source vulnerability in 200mm SiC wafer supply exposes European hardware assemblers to allocation constraints during automotive OEM contract ramp-ups. Distribution runs through energy service company aggregators displacing traditional equipment distributors in the Netherlands and Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet operator procurement consolidation is shifting buyer power toward performance-based service contracts, with Dutch delivery van operators and German bus fleets now contracting infrastructure as operational expenditure rather than capital assets.
For Market Incumbents: Entrench grid-code certification leadership by accelerating laboratory validation timelines across German KBA and Dutch national regulator frameworks, while securing captive silicon carbide supply through long-term foundry offtake agreements to offset East Asian wafer allocation risk. For New Entrants and Emerging Players: Establish a beachhead in France's reno-énergetique multi-unit residential retrofit channel, where public subsidy flows and shared parking infrastructure mandates create procurement concentration absent entrenched installer relationships, leveraging refrigerant-free thermal management as a compliance wedge. For Investors and Strategic Acquirers: Power-electronics firmware specialists with ISO 15118-20 protocol stack expertise command scarcity premiums as grid-code convergence compresses product launch windows. Monitor silicon carbide MOSFET allocation announcements from Taiwanese foundries as inflection indicators for European hardware assembler margin stress.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into SiC Wafer Supply | Long-term foundry offtakes with TSMC or UMC reduce allocation exposure for German hardware assemblers bidding utility-scale contracts. |
| ISO 15118-20 Protocol Certification Investment | Grid-code compliance with German KBA and Dutch regulator mandates locks in multi-decade infrastructure procurement compatibility. |
| Energy Service Company Channel Partnership | Aggregator relationships in the Netherlands capture recurring revenue streams from performance-based fleet operator contracts. |
| Refrigerant-Free Thermal Management Redesign | F-Gas Regulation compliance opens EU market access while extending product development cycles for liquid-cooled cold plate architectures. |
| Nordic Residential Ecosystem Integration | Norwegian and Swedish utility bundling of heat pump, solar inverter, and vehicle-to-home hardware creates subscription-based revenue models. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with utility planning officers, fleet procurement directors, power-electronics engineering leads, and energy service company executives; and secondary validation against FERC filings, EU Green Deal regulatory texts, KBA technical connection rules, and silicon carbide supply chain disclosures from foundry operators. Bottom-up unit deployment estimates triangulated against top-down grid services market sizing across the projection horizon.
Forecast inputs considered product type segmentation across wall-mounted units, standalone stations, and integrated modules; technology tiers spanning DC fast charging and vehicle-to-grid communication protocols; and application dimensions including electric vehicle fleet, commercial energy management, and residential energy storage. CAGRs were derived from utility-scale procurement pipeline analysis and residential retrofit penetration modeling, with semiconductor material cost curves and grid-code compliance timelines as industry-specific variables.
Stress conditions across silicon carbide wafer allocation, F-Gas Regulation thermal management redesign timelines, and ISO 15118-20 interoperability convergence were modeled; outcomes outside those bands fall beyond the analytical envelope. Quarterly review of German transmission system operator frequency regulation contract awards and Taiwanese foundry capacity announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.