
 Electric Vehicle Charging Adapter Market | 2026-2036
Electric Vehicle Charging Adapter Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle Charging Adapter Market Foresight
Electrical engineering talent scarcity is bifurcating the competitive landscape between firms with captive design teams and those dependent on contract development. Tesla leverages its proprietary connector ecosystem to sustain vertical integration across charging hardware and vehicle platforms. ChargePoint anchors its position through broad interoperability certifications with multiple regional standards. ABB competes on manufacturing scale, operating high-volume DC fast charging adapter production lines serving European and North American infrastructure rollouts.
An electric vehicle charging adapter is an electromechanical coupling device that bridges incompatible connector geometries between electric vehicles and charging infrastructure, typically incorporating conductive pins rated for currents from 16A to 500A, thermal sensors, and locking mechanisms to ensure safe power transfer. Its primary commercial purpose is to eliminate stranded-asset risk for charging network operators and vehicle owners facing fragmented connector standards across jurisdictions. CCS Combo adapters command the largest installed base among DC fast charging configurations, while CHAdeMO maintains residual demand from legacy Japanese vehicle fleets. Smart Charging technology represents the fastest-expanding segment as bidirectional power management and load-balancing protocols become embedded in adapter firmware.
The EU Green Deal and F-Gas Regulation shape product design requirements for thermal management materials in European-sold adapters, while NHTSA and FCC standards govern electromagnetic compatibility and safety labeling in the United States. China's GB standards and MIIT directives mandate domestic connector specifications that influence adapter variants produced by Shanghai Zencar Industry for export markets. Stakeholders must monitor regulatory divergence between CCS2 dominance in Europe and NACS standardization momentum in North America to align adapter portfolios with evolving certification obligations.
Market Dynamics
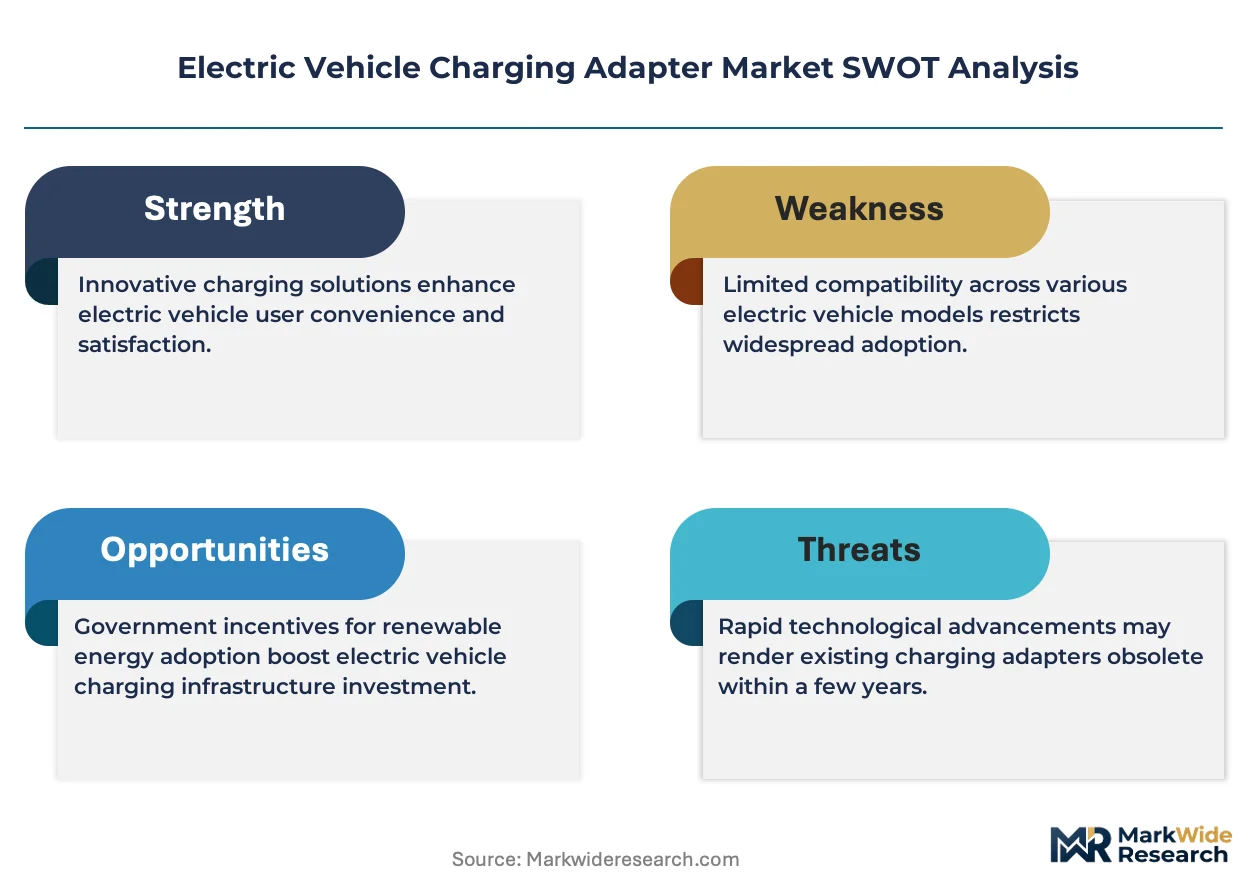
Connector standardization wars between CCS2, NACS, and residual CHAdeMO protocols are forcing adapter manufacturers to engineer multi-protocol hardware while regulatory mandates across Germany, the United States, and China accelerate incompatible infrastructure buildouts.
Growth Catalysts
- Fleet electrification mandates:Corporate fleet operators in Germany and California are procuring standardized adapter inventories to unify charging access across mixed-vehicle pools, creating sustained institutional demand for multi-protocol hardware.
- EU Green Deal infrastructure funding:The European Commission's autobahn corridor electrification program is mandating interoperable charging hardware, directly expanding adapter deployment at highway service stations.
- Silicon carbide thermal management:Advanced semiconductor materials are enabling compact 500A-rated adapters with active cooling, unlocking higher-power DC fast charging in smaller form factors.
Market Restraints
- Copper and rare earth price volatility:Lanthanum and neodymium supply concentration in Chinese processing facilities creates input cost instability for magnetic locking mechanism production.
- Technical limitation in bidirectional firmware:Vehicle-to-grid communication protocols remain immature, delaying smart adapter deployment despite hardware readiness.
- Regulatory friction from FCC Part 15:United States electromagnetic compatibility certification timelines extend 8-14 months, constraining product launch velocity for North American market entry.
Strategic Opportunities
- Underpenetrated Indian commercial fleet segment:India's Bureau of Indian Standards is finalizing AC charging connector specifications, creating first-mover positioning for adapter manufacturers before infrastructure lock-in.
- Regulatory tailwind from IRA domestic content bonuses:United States Inflation Reduction Act tax credits for North American-assembled charging hardware incentivize localized adapter production.
- Technology convergence of wireless power transfer:Inductive charging pad retrofits for existing conductive ports are emerging as a bridge technology, requiring new adapter form factors.
Industry Challenges
- Embedded systems firmware engineering scarcity:Competent talent for ISO 15118 protocol implementation commands premium compensation, constraining product development bandwidth at mid-tier manufacturers.
- Multi-jurisdiction certification complexity:Simultaneous CE marking, FCC authorization, and MIIT GB standard compliance requires redundant testing programs that compress margin structures.
- Legacy CHAdeMO inventory stranding:Japanese vehicle fleet depreciation curves are shortening effective demand windows for CHAdeMO-to-CCS adapter variants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle Charging Adapter Market |
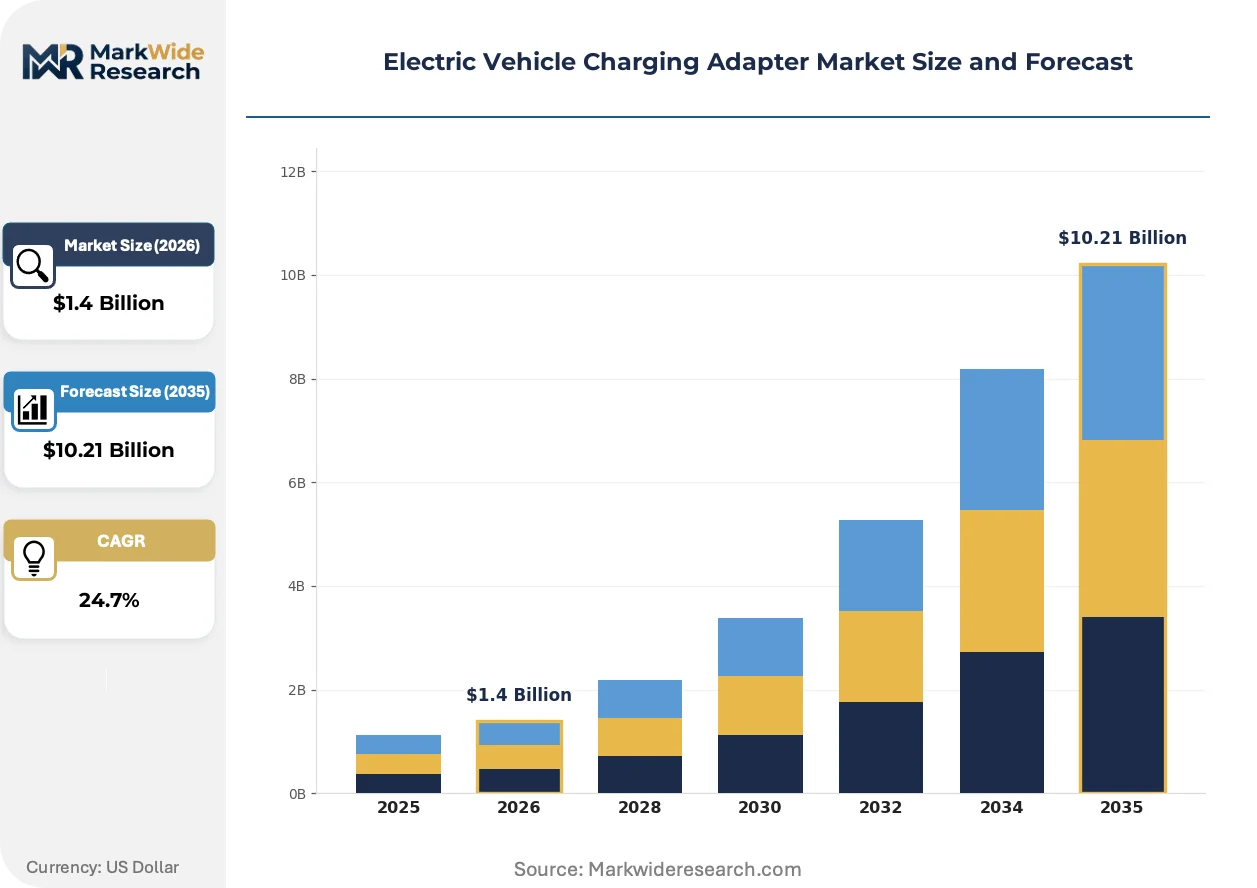
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $10.21 Billion |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Type 1, Type 2, CHAdeMO, CCS Combo, Tesla Connector Application: Personal Vehicles, Fleet Operations, Commercial Parking, Public Charging Stations Technology: AC Charging, DC Fast Charging, Wireless Charging, Smart Charging End User: Vehicle Owners, Rental Services, Corporate Fleets, Charging Service Providers |
| Companies Covered | Tesla, ChargePoint, ABB, Siemens, Schneider Electric, Robert Bosch GmbH, Eaton Corporation plc, Shanghai Zencar Industry Co. Ltd, Pod Point, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle Charging Adapter Market Shifts & Advancements
Active materials science breakthroughs and firmware architecture advances are compressing adapter size-to-power ratios while regulatory fragmentation across connector standards accelerates hardware complexity.
Silicon carbide power semiconductors are replacing traditional IGBT modules in high-current adapter designs, enabling thermal efficiency gains that permit 350kW throughput in palm-sized housings. Fleet procurement teams at German logistics operators are specifying SiC-based units for autobahn corridor depots. The technology is fragmenting competitive positioning between legacy thermal engineers and semiconductor-native entrants.
EU F-Gas Regulation phase-down schedules are banning hydrofluorocarbon cooling agents in adapter thermal management systems, forcing refrigerant transitions to CO2 or propane-based alternatives. European manufacturers are redesigning active cooling loops to accommodate lower-GWP working fluids. German KBA type-approval processes are extending 4-6 months as certification bodies validate new thermal architectures.
Leasing structures for adapter hardware are displacing outright purchase models among United States commercial fleet operators seeking to match asset lifecycles to vehicle replacement cycles. Charging-as-a-service providers are bundling adapter subscriptions with network access fees. California-based fleet managers are piloting per-mile pricing arrangements that align hardware costs to utilization intensity.
Electric Vehicle Charging Adapter Market Segmentation
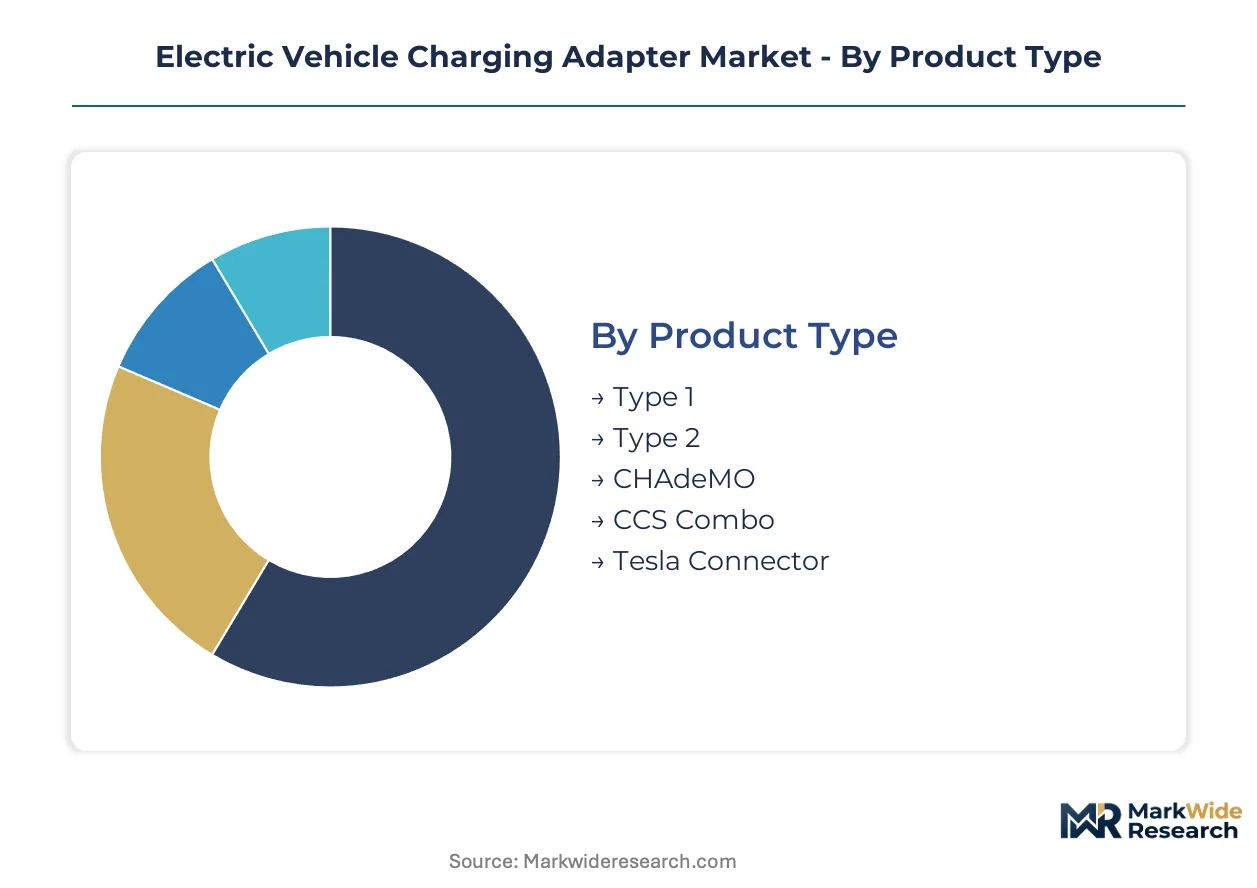
Adapter manufacturers face divergent technical requirements across connector geometries, power protocols, and user environments. Segmentation reveals where standardization pressure concentrates demand and where fragmentation sustains premium pricing for multi-protocol hardware.
Product Type:
Substitute threat intensifies around legacy Japanese connectors as European and North American infrastructure buildouts standardize on CCS2 and NACS geometries.
- CCS Combo:Combines AC and DC pins in a single housing rated up to 500A with liquid cooling integration. German autobahn corridor investments and California fleet electrification mandates are concentrating procurement volume for CCS1 and CCS2 variants.
- Tesla Connector:Proprietary geometry now licensing to third-party manufacturers under NACS standardization momentum. North American charging network operators are retrofitting existing hardware to accommodate the connector's compact form factor and 350kW throughput capability.
- Type 1:Single-phase AC connector dominant in Japanese and early North American passenger vehicles.
- Type 2:Three-phase AC standard mandated across EU member states for home and destination charging.
- CHAdeMO:DC fast charging protocol with bidirectional capability facing declining new vehicle integration.
CCS Combo anchors the volume base while Tesla Connector gains share at the steepest rate.
Application:
Cost tier differentiation separates high-utilization fleet assets from intermittent consumer use cases with divergent durability specifications.
- Fleet Operations:Institutional procurement of ruggedized adapters with telemetry integration for asset tracking. German logistics operators and California delivery fleets are standardizing on MIL-STD-810G vibration-rated units for depot charging.
- Public Charging Stations:Multi-protocol hardware with IP67 ingress protection and 50,000-cycle mechanical durability. EU Green Deal infrastructure funding is mandating interoperable adapter deployment at highway service stations across member states.
- Personal Vehicles:Consumer-grade adapters prioritizing portability and cost over cycle life.
- Commercial Parking:Destination charging hardware with load-balancing firmware for multi-vehicle sites.
Fleet Operations command the premium tier while Public Charging Stations drive aggregate unit demand.
Technology:
Power conversion architecture separates mature AC electromechanical designs from semiconductor-dependent DC and wireless segments with divergent R&D intensity.
- DC Fast Charging:Silicon carbide power stages enabling 350kW throughput in compact housings with active thermal management. German KBA type-approval processes are validating new cooling loop designs under F-Gas Regulation phase-down schedules.
- Smart Charging:ISO 15118 protocol implementation with bidirectional power management and dynamic load balancing. Firmware engineering scarcity is constraining deployment timelines despite hardware readiness.
- AC Charging:Passive electromechanical coupling without power conversion electronics.
- Wireless Charging:Inductive pad retrofits requiring new adapter form factors for conductive port bridging.
DC Fast Charging dominates installed value while Smart Charging climbs the fastest on protocol maturation.
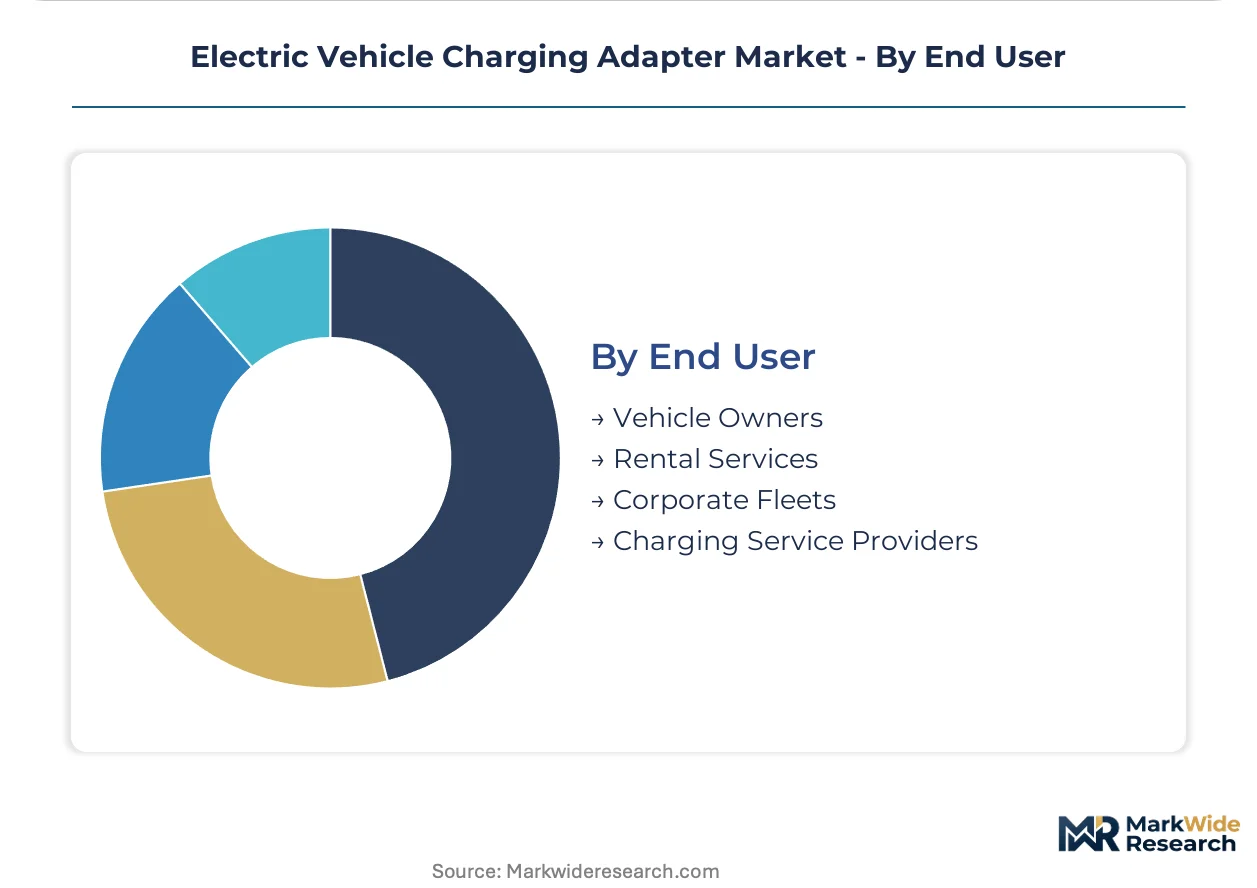
End User:
Customer type determines procurement modality, with corporate buyers favoring leasing structures and service providers seeking volume discounts on standardized inventories.
- Charging Service Providers:Network operators procuring multi-protocol adapter pools to minimize stranded-asset risk across mixed-connector infrastructure. California-based CaaS platforms are piloting per-mile pricing arrangements aligning hardware costs to utilization intensity.
- Corporate Fleets:Standardized adapter inventories unifying charging access across mixed-vehicle pools with replacement cycle matching through leasing structures.
- Vehicle Owners:Individual consumers purchasing single-unit adapters for emergency or destination charging access.
- Rental Services:Short-term vehicle operators requiring durable hardware with minimal training requirements for transient users.
Charging Service Providers concentrate procurement volume while Corporate Fleets expand most quickly on electrification mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal anchors adapter demand in Germany, where KBA type-approval processes and autobahn corridor electrification are reshaping procurement patterns. National ICE phase-out mandates across member states are forcing connector standardization investments.
United States
California fleet electrification mandates and IRA domestic content bonuses are concentrating adapter procurement among logistics operators. FCC Part 15 certification timelines extend 8-14 months, constraining product launch velocity. Detroit-area automotive suppliers are retrofitting production lines for NACS-standard hardware.
Germany
Autobahn corridor charging investments and fleet standardization requirements are driving multi-protocol adapter demand. KBA type-approval processes are extending 4-6 months under F-Gas Regulation thermal validation requirements. Stuttgart and Munich industrial clusters host DC fast charging adapter manufacturing for European distribution.
China
MIIT GB standards and dual carbon goals are mandating domestic connector specifications for adapter variants. Shanghai Zencar Industry produces export-oriented units from Yangtze River Delta manufacturing bases. Shenzhen electronics clusters supply silicon carbide power semiconductors for high-current designs.
India
BIS is finalizing AC charging connector specifications, creating first-mover positioning before infrastructure lock-in. Bureau of Indian Standards certification requirements are accelerating local testing facility investments. Maharashtra and Gujarat automotive corridors are attracting adapter assembly investments from international suppliers.
Japan
Residual CHAdeMO fleet maintenance sustains adapter demand despite declining new vehicle integration. METI directives on charging interoperability are pressuring legacy infrastructure retrofits. Nagoya and Osaka industrial zones maintain production capacity for bidirectional-capable hardware.
Electric Vehicle Charging Adapter Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive semiconductor design capabilities separating premium positioning from contract-dependent competitors. The upper tier commands manufacturing scale and protocol certification breadth, while mid-tier players compete on regional regulatory relationships and fleet service contracts. Two strategic archetypes dominate: vertically integrated automotive-electronics conglomerates with in-house power semiconductor production, and charging-network-native hardware specialists with firmware engineering depth. Competitive moves concentrate on silicon carbide thermal management licensing and multi-jurisdiction certification bundling to compress margin structures.
Among integrated automotive-electronics conglomerates, Tesla and ABB exemplify divergent strategic positions. Tesla occupies a proprietary ecosystem anchor, leveraging vertical control across vehicle platforms and charging hardware to sustain connector standardization influence. ABB represents the manufacturing-scale archetype, operating high-volume production lines serving European and North American infrastructure rollouts. Shanghai Zencar Industry Co. Ltd sits within the export-specialist tier, producing GB-standard variants for international markets subject to MIIT directives.
| Leading Market Players |
|---|
| Tesla |
| ChargePoint |
| ABB |
| Siemens |
| Schneider Electric |
| Robert Bosch GmbH |
| Eaton Corporation plc |
| Shanghai Zencar Industry Co. Ltd |
| Pod Point |
| Others |
Supply & Pricing Matrix
Fourteen-month FCC Part 15 certification timelines compress pricing power for North American entrants while extending inventory carrying costs, concentrating margin pressure on mid-tier manufacturers lacking captive semiconductor design teams. German KBA type-approval delays under F-Gas Regulation thermal validation requirements create parallel bottlenecks that favor established players with strategic component stockpiles.
Pricing Analysis
Geographic price spreads of 40-60% separate EU-certified premium adapters from economy-grade Asian imports lacking CE marking. Three-tier pricing structure across premium, standard, and economy levels differentiates by certification grade and active cooling integration, with fleet procurement teams at German logistics operators commanding volume discounts. Cost compression in the consumer tier intensifies because Shenzhen electronics clusters flood export markets with unbranded CCS-to-Type 2 variants. Charging-as-a-service providers exhibit lowest price sensitivity due to per-mile pricing models, while individual vehicle owners drive aggressive unit-cost negotiation.
Supply Chain Analysis
Just-in-time inventory strategies dominate silicon carbide power semiconductor procurement from Shenzhen and Shanghai clusters, though German manufacturers maintain 90-day strategic stockpiles of rare-earth magnetic alloys against lanthanum supply volatility. Adapter production draws from Yangtze River Delta electronics bases, Stuttgart industrial clusters, and Detroit-area automotive supplier networks. Single-source vulnerability concentrates in Chinese rare-earth processing facilities for neodymium-dependent locking mechanisms. Distribution runs through charging network operators, fleet procurement consortia, and aftermarket automotive channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Adapter-as-a-service subscription models expand faster than hardware unit sales, with California fleet managers piloting per-mile pricing that bundles firmware updates and replacement cycles into recurring revenue streams.
For Market Incumbents: Compound certification breadth across CE marking, FCC authorization, and MIIT GB standards to raise rival entry costs. Lock in silicon carbide thermal management licensing agreements with Yangtze River Delta foundries before capacity constraints tighten. Defend against semiconductor-native entrants by accelerating KBA type-approval pipelines for CO2-cooled designs. For New Entrants and Emerging Players: Firmware engineering services for ISO 15118 protocol implementation present a service-layer gap where incumbents under-serve mid-tier manufacturers. Target Indian commercial fleet segments before BIS specification finalization locks in infrastructure standards. Pursue white-label partnerships with Maharashtra automotive corridor assemblers lacking captive design teams. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified automotive-electronics conglomerates with under-monetized charging hardware divisions. Five-to-ten year viability hinges on protocol consolidation between CCS2 and NACS geometries. Monitor NHTSA connector standardization directives as inflection indicators for stranded-asset risk in CHAdeMO-dependent inventories.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Jurisdiction Certification Bundling | Compresses rival margin structures by amortizing CE, FCC, and MIIT testing across product families. |
| Silicon Carbide Thermal Management Licensing | Unlocks 350kW throughput in compact housings for German autobahn corridor deployments. |
| Firmware-as-a-Service Platform Development | Captures recurring revenue from ISO 15118 protocol updates and dynamic load-balancing algorithms. |
| Strategic Stockpile of Rare-Earth Magnets | Hedges lanthanum price volatility from Chinese processing concentration for locking mechanism production. |
| India First-Mover Assembly Investment | Positions before BIS specification lock-in across Maharashtra and Gujarat automotive corridors. |
Research Methodology
A standing panel of charging network procurement directors, fleet operations managers, KBA certification engineers, and silicon carbide semiconductor sourcing leads provided ongoing calibration across primary interview cycles. Secondary validation drew from SEC filings of listed charging infrastructure providers, EU Green Deal implementation progress reports, MIIT GB standard publication records, and FCC equipment authorization databases. Bottom-up unit demand modeling triangulated against top-down infrastructure investment forecasts.
Consistency checks validated volume outputs against IEA electric vehicle deployment projections and national ICE phase-out mandate timelines. Segmentation dimensions spanned connector geometry, power protocol, cooling architecture, and regional regulatory cluster. CAGRs derived from logistic diffusion curves fitted to fleet electrification penetration rates and autobahn corridor buildout schedules. Forecast inputs incorporated silicon carbide foundry capacity expansion announcements and F-Gas Regulation phase-down compliance timelines.
Underlying assumptions cover connector standardization convergence between CCS2 and NACS protocols, with deviation risk concentrated in Japanese CHAdeMO fleet depreciation curves and Chinese rare-earth export policy shifts. Revision becomes warranted when NHTSA or KBA mandates accelerate incompatible infrastructure buildouts beyond modeled penetration rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Micro Mobility Charging Infrastructure Market
Electric Vehicle Charging
Wireless Charging Market
Electric Vehicle Charging
Japan Electric Vehicles (EV) Charging Equipment Market
Electric Vehicle Charging
Battery Liquid Cooling Plates for Electric Vehicle Market
Electric Vehicle Charging
Electric Vehicle Showroom Charger Market
Electric Vehicle Charging
Global EV Charger Market
Electric Vehicle Charging
Spain Electric Vehicle (EV) Charging Equipment Market
Electric Vehicle Charging
PV BESS EV Charging Systems Market
Electric Vehicle Charging
Global EV Charging Piles Market
Electric Vehicle Charging
Germany Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
EV Charging Facilities Market
Electric Vehicle Charging
Smart EV Charger Market
Electric Vehicle Charging
Electric Vehicle Fast and Rapid Charger Market
Electric Vehicle Charging
Solar Carport Charging Station Market
Electric Vehicle Charging
Electric Bus Charging Infrastructure Market
Electric Vehicle Charging
Electric Vehicle Charging System Market