
 Electric Vehicle Charger and Charging Station Market | 2026-2036
Electric Vehicle Charger and Charging Station Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle Charger and Charging Station Market Insights
DC fast-charging certification tiers above 150 kW is rotating the competitive landscape toward high-reliability hardware. Tesla leverages its proprietary connector standard and Supercharger network density to dominate highway corridor deployment. ABB sustains its industrial electrification heritage through grid-integration engineering for fleet-scale installations. Siemens differentiates with modular power electronics that scale from 50 kW urban units to 350 kW highway systems.
An electric vehicle charger and charging station is an electromechanical system that converts grid alternating current into direct current at specified voltage and amperage levels to replenish onboard battery packs, with DC fast chargers typically delivering 50 kW to 350 kW through liquid-cooled cable assemblies. Its primary commercial purpose is to reduce vehicle downtime for fleet operators and extend daily range for passenger EV owners without home charging access. DC Fast Chargers capture the dominant share of capital deployment in highway and fleet applications where throughput per port drives returns. Smart Charging Systems represent the fastest-expanding technology segment as utilities and operators deploy load-balancing algorithms to manage grid demand peaks. Residential Charging Points remain the highest-volume application but operate on thinner hardware margins offset by installation and software services.
The US Department of Transportation coordinates with NHTSA and EPA to embed charger reliability standards into federal highway electrification funding eligibility. The EU Green Deal and F-Gas Regulation shape European procurement by mandating energy efficiency disclosures and restricting fluorinated coolant use in high-power thermal management systems. China's GB standards and MIIT technology roadmaps enforce domestic interoperability protocols that influence export design requirements. Stakeholders must monitor which certification regimes their target markets adopt, as divergence between CCS, NACS, and GB/T connector standards will determine factory tooling and inventory allocation decisions.
Market Dynamics
The transition from CCS to NACS connector standards across North American highway infrastructure is forcing incumbent manufacturers to retool production lines and recertify hardware architectures before federal electrification funding deadlines.
Growth Catalysts
- EPA tailpipe regulations:Fleet operators in the United States face accelerating electrification mandates that expand depot charging procurement budgets and compress installation timelines.
- China's coastal manufacturing clusters:BYD and domestic suppliers dominate charger component production, creating export-ready supply capacity that lowers hardware costs for international markets.
- DC fast-charging certification tiers above 150 kW:Highway corridor operators prioritize high-reliability hardware that reduces downtime and maximizes vehicle throughput per port.
Market Restraints
- Copper and silicon carbide price volatility:Power electronics input costs swing with mining output and semiconductor fab capacity allocation, squeezing hardware margins.
- Fluorinated coolant restrictions:The EU F-Gas Regulation limits thermal management fluid options for liquid-cooled cable assemblies above 350 kW.
- Connector standard divergence:Factory tooling must accommodate CCS, NACS, and GB/T protocols simultaneously, fragmenting production runs and inventory pools.
Strategic Opportunities
- India's PLI scheme for advanced chemistry cell manufacturing:Domestic battery production growth will require parallel charging infrastructure buildout in industrial corridors around Chennai and Pune.
- Vehicle-to-grid integration:Bidirectional charging hardware convergence with home energy management systems opens residential software revenue streams.
- Germany's KBA fast-track certification pathway:Streamlined type-approval processes for 800-volt architectures accelerate product launch timelines for European highway networks.
Industry Challenges
- Power electronics engineering talent scarcity:Grid-integration specialists with high-voltage DC experience command premium compensation, constraining R&D team expansion.
- Utility interconnection queues:Fleet-scale installations above 1 MW face 18-to-24-month grid connection delays in congested transmission zones.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle Charger and Charging Station Market |
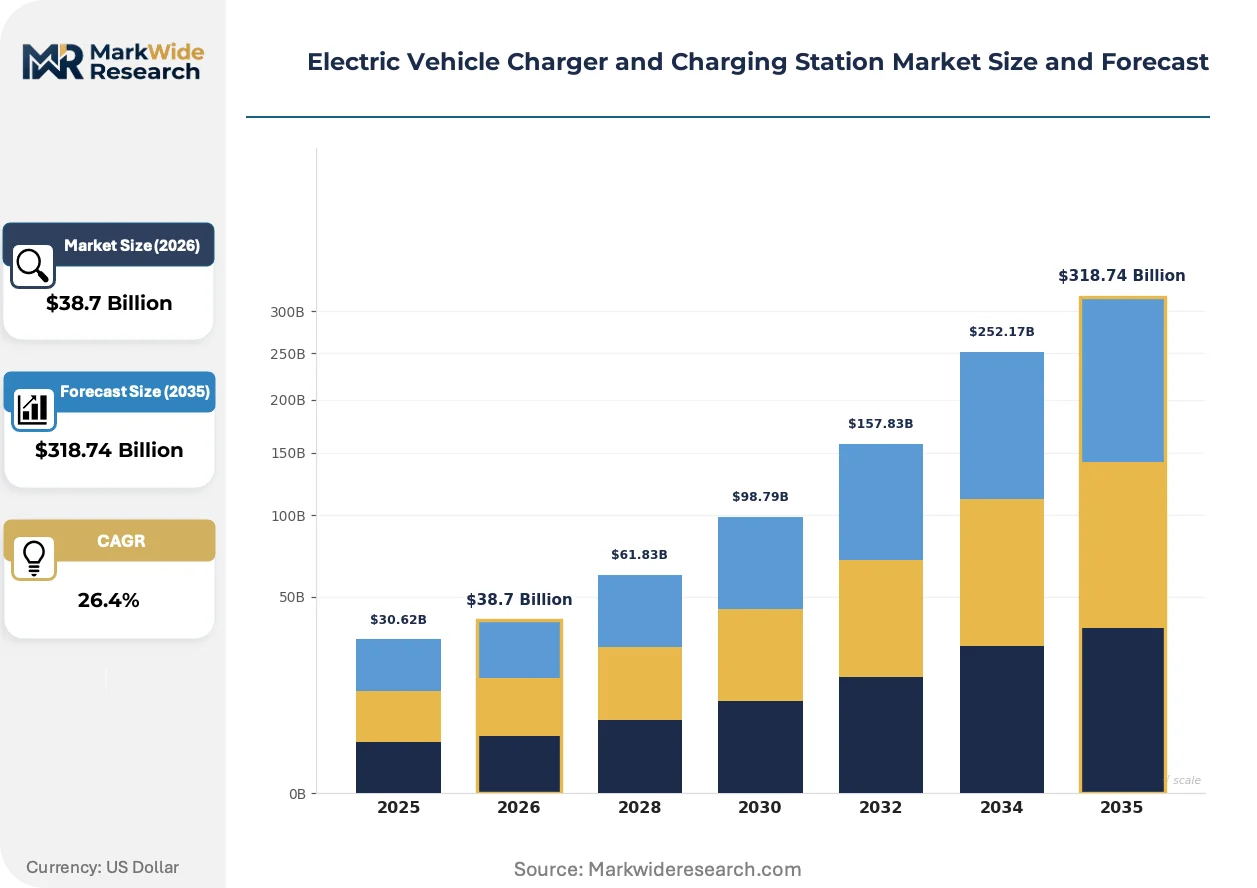
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $318.74 Billion |
| CAGR (2026 – 2036) | 26.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Chargers, DC Fast Chargers, Wireless Chargers, Portable Chargers, Inductive Chargers Technology: Level 1 Charging, Level 2 Charging, Level 3 Charging, Bidirectional Charging, Smart Charging Systems Application: Public Charging Stations, Residential Charging Points, Fleet Charging Solutions, Commercial Charging Infrastructure, Workplace Charging End User: Passenger Vehicles, Commercial Vehicles, Electric Two-Wheelers, Electric Buses, Specialty Electric Vehicles |
| Companies Covered | Tesla, ChargePoint, ABB, EVBox, BYD, Schneider Electric, Siemens, Eaton, BP Pulse, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle Charger and Charging Station Market Trends and Innovations
Hardware commoditization is compressing margins at the charging module level while software-defined load management and energy storage integration create new value capture layers for system integrators.
Liquid-cooled cable assemblies rated for sustained 500-amp delivery are fragmenting the high-power charging segment into performance tiers that separate premium highway corridor hardware from standard urban depot equipment. Fleet operators with 24-hour utilization requirements specify these systems despite 40% capital cost premiums. The technology is fragmenting procurement committees into reliability-focused and cost-focused buyer factions with incompatible vendor shortlists.
The EU Green Deal's embedded carbon disclosure requirements for public infrastructure procurement are reshaping European tender specifications. Charger manufacturers must document upstream emissions from aluminum enclosures and copper windings to qualify for national subsidy programs. German and French highway concession operators now weight lifecycle carbon intensity equally with capital expenditure in bid evaluations.
Fleet operators are consolidating charging procurement under centralized energy management departments rather than distributing decisions across regional maintenance managers. This concentration shifts vendor relationships from transactional hardware sales toward decade-long service contracts with guaranteed uptime clauses. The pattern is most visible in North American logistics networks where electrification timelines synchronize with vehicle replacement cycles.
Electric Vehicle Charger and Charging Station Market Segmentation
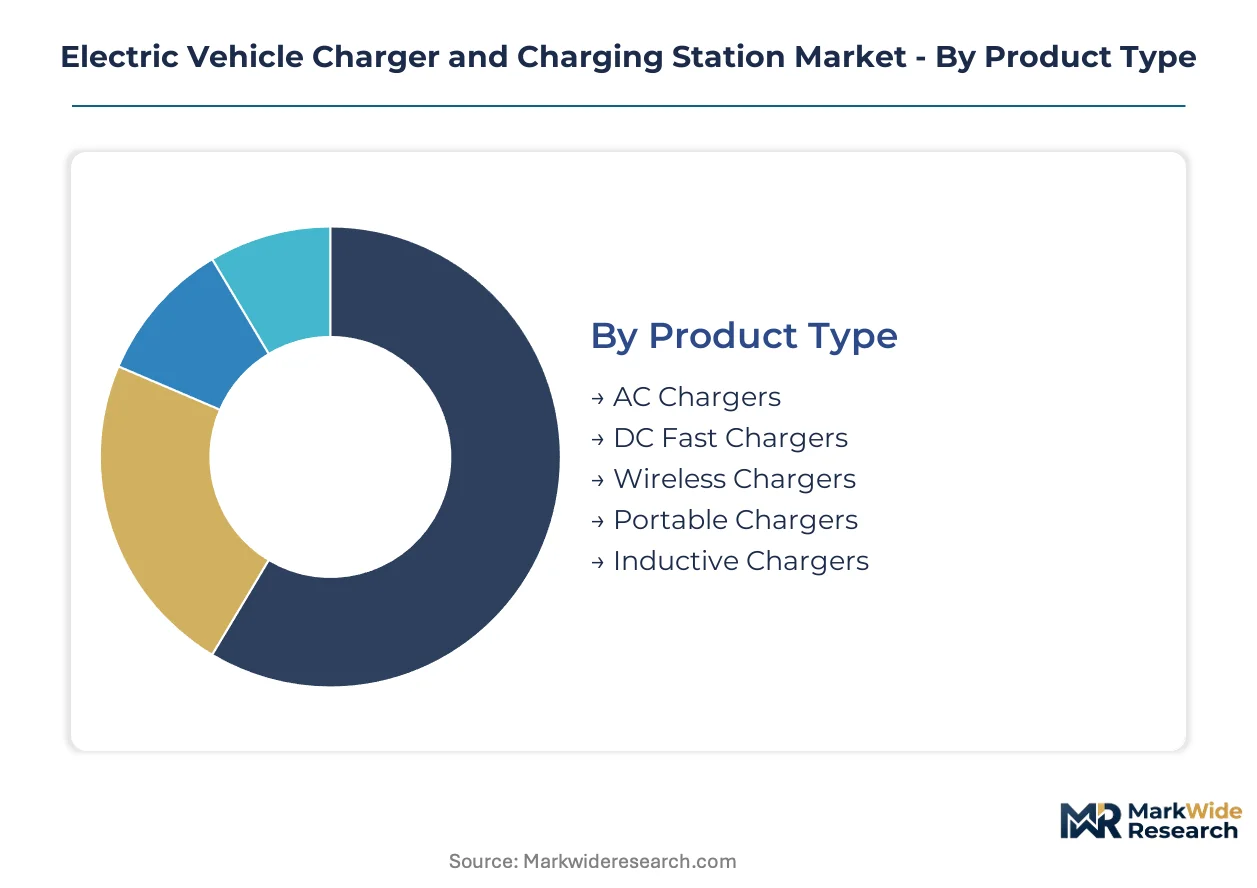
Charger procurement patterns diverge sharply across installation contexts, with highway operators prioritizing throughput reliability while fleet managers optimize for depot utilization cycles. Understanding these segment boundaries clarifies where hardware margins compress versus where software and service layers capture value.
Product Type:
EPA tailpipe regulations and NHTSA electrification mandates in the United States have created divergent certification requirements that favor DC architectures for commercial procurement while AC systems dominate residential subsidy programs.
- DC Fast Chargers:These systems convert grid AC to DC onboard at 50 kW to 350 kW through liquid-cooled cable assemblies, enabling 20-to-80-percent battery replenishment in 20-40 minutes. Highway corridor operators in Germany and the United States specify these units for 24-hour throughput maximization, though copper and silicon carbide price volatility squeezes hardware margins.
- AC Chargers:Level 1 and Level 2 alternating current systems deliver 3.3 kW to 19.2 kW through onboard vehicle rectifiers, requiring simpler installation and lower grid interconnection costs. China's coastal manufacturing clusters produce these units at scale for domestic residential deployment and export markets, with MIIT GB standards enforcing interoperability protocols that shape design requirements.
- Wireless Chargers:Inductive pad systems transfer power across air gaps at 3.6 kW to 11 kW for automated fleet depot operations.
- Portable Chargers:Mobile emergency units provide 1.4 kW to 7.2 kW through standard wall outlets for roadside assistance networks.
- Inductive Chargers:Road-embedded dynamic charging systems enable in-motion power transfer for bus rapid transit corridors in South Korea and Sweden.
DC Fast Chargers handle the majority of throughput; Smart Charging Systems are climbing the fastest on share.
Technology:
Cost tier differentiation separates basic hardware from integrated energy management platforms, with premium pricing attaching to grid-interactive capabilities that utilities require for demand response programs.
- Smart Charging Systems:Networked platforms with load-balancing algorithms adjust power delivery based on grid demand peaks, renewable energy availability, and time-of-use pricing signals. European operators under EU Green Deal procurement rules now weight lifecycle carbon intensity equally with capital expenditure, favoring systems with embedded emissions documentation.
- Level 3 Charging:DC fast-charging infrastructure above 150 kW requires dedicated medium-voltage grid connections and active thermal management, with Germany's KBA fast-track certification pathway accelerating 800-volt architecture approvals for highway networks.
- Bidirectional Charging:Vehicle-to-grid capable hardware enables residential energy arbitrage and emergency backup power, with Japanese METI standards driving V2H integration requirements.
- Level 2 Charging:240-volt AC systems dominate workplace and multi-unit dwelling installations where overnight dwell times accommodate slower replenishment.
- Level 1 Charging:Standard 120-volt outlet charging provides baseline accessibility for plug-in hybrid owners with limited daily range requirements.
Level 3 Charging commands the highest capital deployment per port; Bidirectional Charging is expanding most quickly as home energy management convergence accelerates.
Application:
Customer type concentration shifts vendor relationships from transactional hardware sales toward service contracts, with centralized energy management departments consolidating procurement authority across North American logistics networks.
- Fleet Charging Solutions:Depot-scale installations above 1 MW serve 24-hour utilization requirements for logistics and transit operators, facing 18-to-24-month utility interconnection queues in congested US transmission zones. Guaranteed uptime clauses in decade-long service contracts now dominate vendor selection criteria over unit capital cost.
- Public Charging Stations:Highway corridor and urban fast-charging hubs prioritize vehicle throughput per port, with NACS connector standard transition forcing incumbent manufacturers to retool production lines before federal electrification funding deadlines.
- Residential Charging Points:Single-family home installations operate on thinner hardware margins offset by installation and software subscription services.
- Commercial Charging Infrastructure:Retail and hospitality destinations deploy chargers as amenity infrastructure to extend customer dwell times.
- Workplace Charging:Employer-subsidized Level 2 systems capture daytime parking inventory for commuter electric vehicle owners without home charging access.
Public Charging Stations handle the majority of throughput; Fleet Charging Solutions are gaining share fastest as electrification timelines synchronize with vehicle replacement cycles.
End User:
Application context determines power level requirements and utilization patterns, with commercial duty cycles justifying premium hardware investments that passenger vehicle economics cannot support.
- Commercial Vehicles:Medium- and heavy-duty trucks require 350 kW to 1 MW charging infrastructure for depot-based replenishment between duty cycles, with India's PLI scheme for advanced chemistry cell manufacturing driving parallel charging buildout around Chennai and Pune industrial corridors.
- Electric Buses:Transit agencies specify opportunity charging at route termini and depot overnight charging, with EU F-Gas Regulation restrictions on fluorinated coolants limiting thermal management fluid options for high-power cable assemblies.
- Passenger Vehicles:Light-duty owners utilize mixed residential, workplace, and public infrastructure with charging behavior shaped by home access availability.
- Electric Two-Wheelers:Battery swap networks and low-power AC charging dominate last-mile delivery and personal mobility in India and Southeast Asian markets.
- Specialty Electric Vehicles:Mining equipment, port cargo handlers, and agricultural machinery require ruggedized enclosures and modified connector geometries for off-highway deployment.
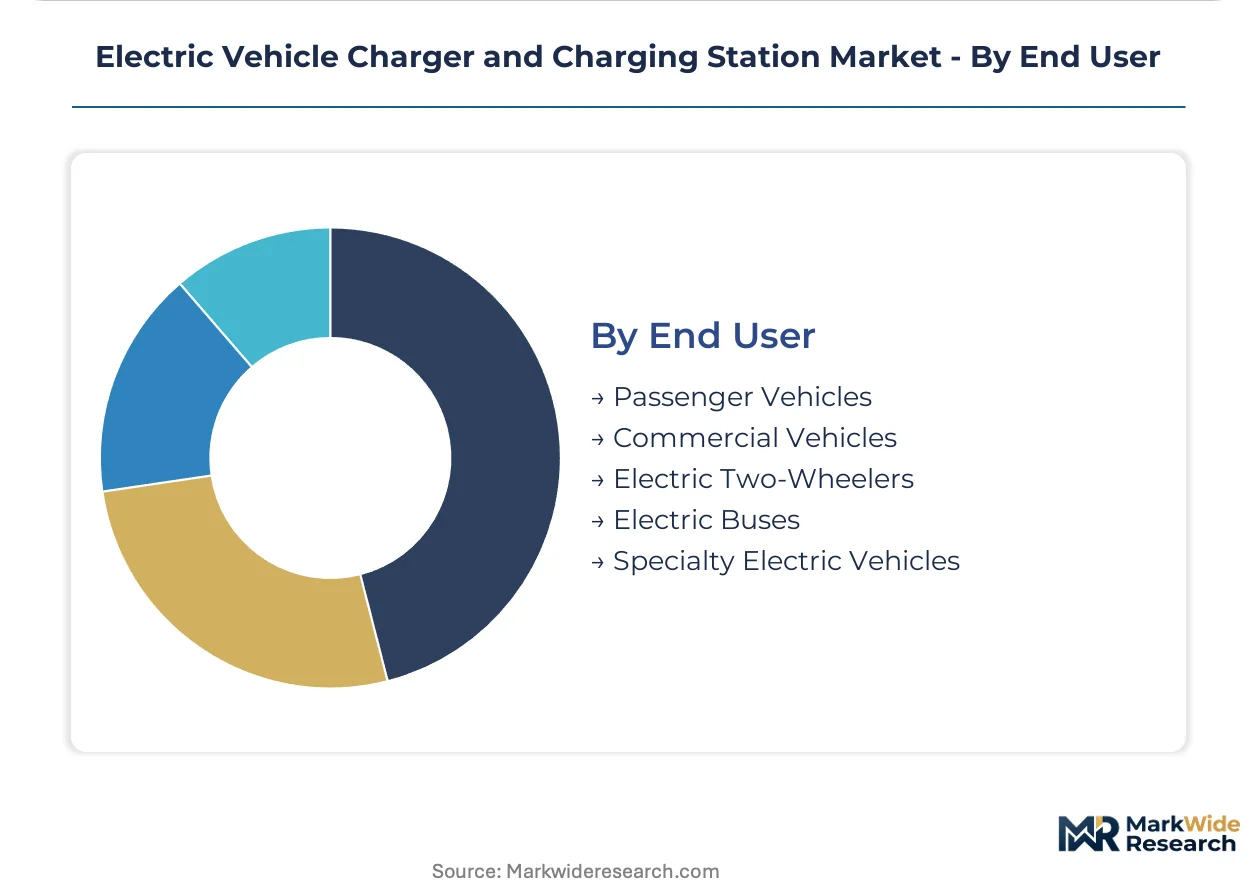
Passenger Vehicles represent the highest volume addressable market; Commercial Vehicles are expanding most quickly on infrastructure investment intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and the United States absorb 40% hardware cost premiums for liquid-cooled 500-amp systems, while Indian and Southeast Asian operators prioritize sub-50 kW AC units where capital constraints dominate procurement committees.
United States
Fleet operators with 24-hour depot utilization requirements drive demand for 1 MW+ installations with guaranteed uptime clauses. NHTSA and EPA tailpipe regulations compress electrification timelines for logistics networks. Texas and California industrial corridors face 18-to-24-month utility interconnection queues that delay project commissioning.
Germany
Highway concession operators weight lifecycle carbon intensity equally with capital expenditure in tender evaluations. The KBA fast-track certification pathway accelerates 800-volt architecture approvals for corridor deployment. Bavaria and Baden-Württemberg manufacturing clusters supply precision power electronics for domestic and export markets.
China
Coastal manufacturing clusters in Guangdong and Jiangsu provinces dominate charger component production for domestic and export markets. MIIT GB standards enforce domestic interoperability protocols that shape design requirements for international shipments. BYD and local suppliers capture volume leadership through integrated supply chains.
India
Industrial corridors around Chennai and Pune require parallel charging infrastructure buildout as domestic battery production scales under the PLI scheme for advanced chemistry cell manufacturing. State electricity regulators negotiate demand-charge frameworks for fleet-scale installations. Gujarat and Maharashtra lead procurement volume for depot electrification.
South Korea
Bus rapid transit corridors deploy road-embedded dynamic inductive charging for in-motion power transfer. METI-aligned V2H integration standards drive bidirectional hardware development for residential energy arbitrage. Seoul Capital Area concentrates smart grid pilot programs with utility-controlled load balancing.
Electric Vehicle Charger and Charging Station Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated automotive groups controlling proprietary connector standards while independent hardware fabricators compete on module pricing. The market structure concentrates around three strategic tiers: automotive-captive networks with proprietary protocols, industrial electrification conglomerates with grid-integration heritage, and pure-play charging specialists scaling through software-defined load management. Dominant competitive moves include strategic partnerships with fleet operators for decade-long service contracts and capacity expansion in coastal manufacturing zones to capture export demand.
Among automotive-captive networks, Tesla exemplifies the proprietary-standard archetype through its Supercharger density and NACS connector adoption. Industrial electrification groups include ABB and Siemens, which occupy positions anchored in grid-scale engineering heritage and modular power electronics platforms. These three represent the primary competitive anchors shaping procurement patterns across highway corridor and fleet depot segments.
| Leading Market Players |
|---|
| Tesla |
| ChargePoint |
| ABB |
| EVBox |
| BYD |
| Schneider Electric |
| Siemens |
| Eaton |
| BP Pulse |
| Others |
Pricing and Supply Chain Analysis
Eighteen-to-twenty-four-month utility interconnection queues for fleet-scale installations above 1 MW concentrate pricing power with manufacturers holding certified 800-volt architectures and liquid-cooled cable assemblies, while copper and silicon carbide price volatility compresses hardware margins across standard urban depot equipment.
Pricing Analysis
Service contract revenue tiers spanning decade-long uptime guarantees now drive lifetime value more than unit hardware margins. DC fast-charging systems stratify across premium, standard, and economy tiers based on certification level above 150 kW and liquid-cooled thermal management capability. Cost compression in standard AC charger modules intensifies because China's coastal manufacturing clusters flood export markets with volume production. Fleet operators with 24-hour utilization requirements demonstrate lowest price sensitivity, while residential buyers and small commercial installers face acute capital constraints.
Supply Chain Analysis
Inventory buffers for silicon carbide wafers and liquid-cooled cable assemblies extend lead-time bands as mining output and semiconductor fab capacity allocation swing with power electronics demand. Manufacturing concentrates in China, Germany, and the United States, with Guangdong and Jiangsu provinces dominating component fabrication for domestic and export markets. The supply chain draws from copper cathode, silicon carbide substrate, and fluorinated thermal management fluid inputs. Single-source vulnerability sits with semiconductor-grade silicon carbide production. Distribution runs through direct OEM relationships for fleet-scale deployments and electrical distributor networks for residential and small commercial channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electric vehicle charger market represents high-growth infrastructure disruption justified by the EPA tailpipe regulation inflection forcing fleet electrification timelines and NHTSA highway electrification funding eligibility embedding reliability standards.
For Market Incumbents: Consolidate service contract portfolios with logistics networks facing compressed electrification timelines under EPA mandates. Deepen backward integration into silicon carbide power module production to defend margins against semiconductor price volatility. Prioritize KBA fast-track certification investment for 800-volt architectures to capture German highway concession tenders weighting lifecycle carbon intensity.
For New Entrants and Emerging Players: Lead with India's PLI scheme for advanced chemistry cell manufacturing as domestic battery production scales around Chennai and Pune industrial corridors. Target depot-scale fleet charging solutions where guaranteed uptime clauses displace unit capital cost as vendor selection criteria. Pursue software-defined load management platforms as the go-to-market angle to bypass hardware margin compression.
For Investors and Strategic Acquirers: Long-term, this sits as a grid-integration infrastructure play because fleet electrification mandates and vehicle-to-grid convergence create decade-long service revenue visibility. Acquisition targets should center on power electronics engineering teams with high-voltage DC experience commanding premium compensation. The signal to watch is utility interconnection queue clearance rates as an inflection indicator for project commissioning velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Connector Standard Transition | NACS adoption across North American highway infrastructure forces incumbent retooling before federal funding deadlines. |
| Backward Integration | In-house silicon carbide module production insulates margins from semiconductor fab capacity allocation swings. |
| Service Contract Consolidation | Decade-long uptime guarantees with fleet operators displace transactional hardware sales as primary revenue. |
| Certification Fast-Track Investment | KBA streamlined type-approval accelerates 800-volt product launches for German highway networks. |
| Software-Defined Load Management | Grid-interactive platforms capture utility demand response revenue streams beyond commoditized charging modules. |
Research Methodology
The analysis maps DC fast-charging architectures, AC residential systems, smart charging platforms, and bidirectional hardware, each validated through fleet energy managers, utility interconnection planners, power electronics procurement leads, and hardware certification engineers. Primary interviews combined with secondary validation from NHTSA electrification funding guidance, EPA tailpipe regulation filings, EU Green Deal procurement specifications, and MIIT GB standard documentation. Bottom-up unit economics triangulated against top-down infrastructure investment forecasts.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled charger type, power level tier, application context, and end-use duty cycle as segmentation dimensions. CAGRs derived from infrastructure deployment timelines synchronized with fleet vehicle replacement cycles and utility grid interconnection capacity. Forecast inputs incorporated copper and silicon carbide price trajectory assumptions alongside regulatory compliance cost estimates.
Underlying assumptions cover fleet electrification mandate enforcement timelines, semiconductor fab capacity expansion, and utility interconnection queue clearance rates, with deviation risk concentrated in raw material price volatility and connector standard divergence. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
HVAC Electronically Commutated Motor (ECM) Market
Electric Vehicle Charging
Electric Vehicle AC Charging Pile Market
Electric Vehicle Charging
Electric Vehicle Charging Station Raw Materials Market
Electric Vehicle Charging
EV Smart Charge Controller Market
Electric Vehicle Charging
Bi Directional Electric Vehicle Charger Market
Electric Vehicle Charging
Electric Vehicle (EV) Charging Station Operation Market
Electric Vehicle Charging
Wireless Charging Market
Electric Vehicle Charging
Heavy-Duty Electric Vehicle Charging Infrastructure Market
Electric Vehicle Charging
Solar Charging Station Market
Electric Vehicle Charging
US Electric Vehicle Charging Infrastructure Market
Electric Vehicle Charging
Battery Swap Station Market
Electric Vehicle Charging
Stationary Electric Vehicle Charging Gun Market
Electric Vehicle Charging
EV Charging Networks Market
Electric Vehicle Charging
Electric Vehicle Battery Charger Market
Electric Vehicle Charging
Smart EV Charger Market
Electric Vehicle Charging
Smart EV Battery Charger Market