
 Power Equipment Testing Market | 2026-2036
Power Equipment Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Power Equipment Testing Market Insights
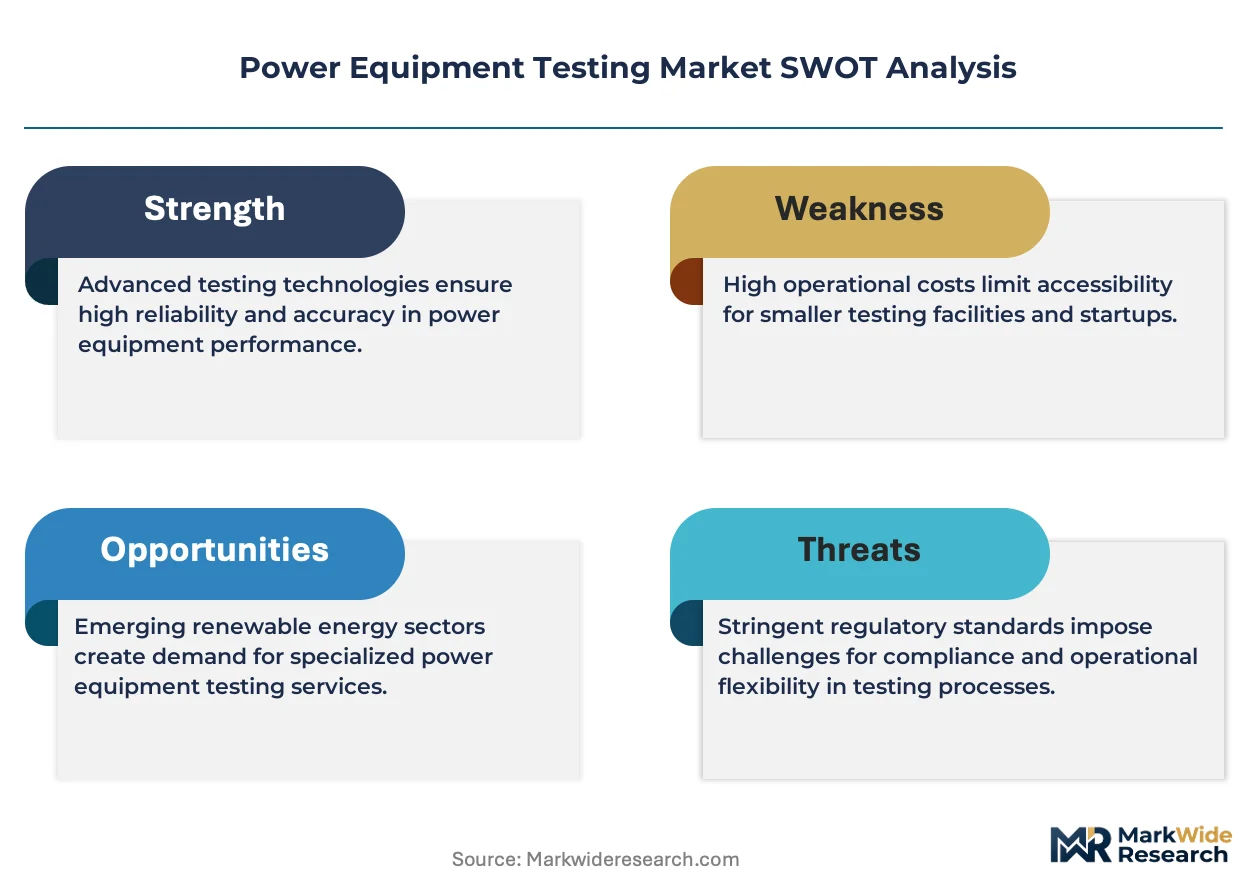
Shortage of certified high-voltage test engineers is redrawing competitive boundaries across the power equipment testing landscape. SGS SA leverages its accredited laboratory network to dominate third-party transformer certification in Europe. Bureau Veritas anchors its position through deep relationships with Middle Eastern utilities requiring independent switchgear validation. Chroma ATE Inc. specializes in automated test systems for power semiconductor devices, competing on throughput speed against traditional manual protocols.
Power equipment testing encompasses diagnostic and certification procedures applied to electrical apparatus operating above 1 kV, including insulation resistance measurement, partial discharge detection, and dynamic mechanical endurance cycling to verify performance under rated fault conditions. The primary purpose is to ensure grid reliability, personnel safety, and compliance with contractual warranty terms before energization. Transformer testing commands the largest revenue pool within product type segments due to aging infrastructure replacement cycles and the complexity of liquid-immersed unit diagnostics. Renewable energy application testing is expanding fastest as offshore wind and utility-scale solar installations require specialized pre-commissioning protocols for variable frequency drives and inverter-transformer interfaces.
FERC Order 693 in the United States mandates periodic testing of bulk power system assets under NERC reliability standards, while IEC 62271 series specifications govern switchgear type testing across European and Asian markets. CE marking under the EU Low Voltage Directive and Machinery Directive creates mandatory third-party intervention points for equipment imported into European member states. IEEE C37 and GB standards in China establish parallel but non-identical test regimes that multinational service providers must navigate simultaneously. Stakeholders should monitor evolving grid code harmonization efforts between IEC and national standards bodies to anticipate where accreditation investments will yield preferential market access.
Market Dynamics
The shortage of certified high-voltage test engineers is compressing service capacity and forcing utilities to outsource diagnostic work to accredited third-party laboratories, redrawing competitive boundaries across transformer and switchgear certification.
Growth Catalysts
- FERC Order 693:Mandatory NERC reliability testing for bulk power system assets in the United States sustains recurring revenue streams for transformer diagnostics and switchgear validation services.
- Offshore wind installations:Pre-commissioning protocols for variable frequency drives and inverter-transformer interfaces in North Sea and East Asian projects expand specialized testing demand.
- GB standards harmonization:China's alignment of national switchgear test regimes with IEC 62271 series specifications accelerates multinational laboratory accreditation investments.
Market Restraints
- SF6 gas phase-down:F-Gas Regulation restrictions in Europe constrain availability of sulfur hexafluoride for high-voltage switchgear insulation testing, forcing protocol redesigns.
- Test equipment concentration:Precision instrument manufacturing concentrates in Germany and Japan, exposing service providers to extended lead times for replacement capacitors and partial discharge sensors.
- Skill pipeline gaps:University engineering programs in North America and Western Europe produce fewer graduates specializing in high-voltage dielectric theory than retirement rates demand.
Strategic Opportunities
- India grid expansion:Central Electricity Authority mandates for new substation commissioning create unmet demand for portable transformer test sets and dissolved gas analysis services.
- Digital twin integration:Convergence of online monitoring sensors with physics-based asset models enables predictive testing schedules that reduce unplanned outage costs for transmission operators.
- CE marking expansion:EU Machinery Directive updates for power conversion equipment imported from Southeast Asia create mandatory third-party intervention points for independent validation.
Industry Challenges
- Accreditation timeline compression:IEC 17025 laboratory certification cycles for high-voltage test bays extend 18-24 months, delaying market entry for new service entrants.
- Legacy asset integration:Utilities operating pre-1980 oil-filled transformers lack baseline dissolved gas analysis records, complicating condition-based maintenance algorithm training.
- Cross-standard navigation:Multinational equipment suppliers must simultaneously satisfy IEEE C37 dielectric withstand requirements and GB short-circuit test protocols, doubling documentation burden.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power Equipment Testing Market |
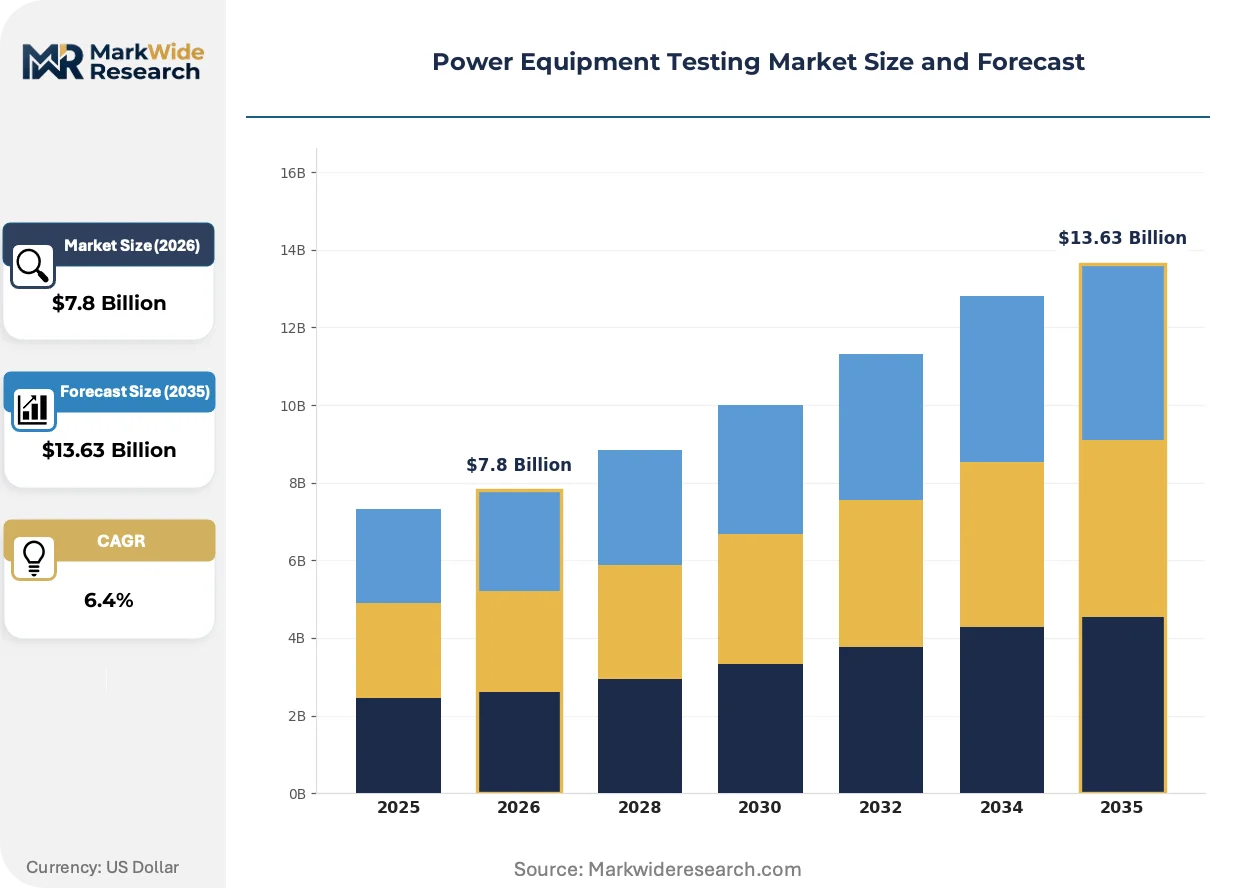
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.63 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Generators, Transformers, Circuit Breakers, Switchgear Testing Type: Electrical Testing, Mechanical Testing, Thermal Testing, Durability Testing End User: Utilities, Manufacturers, Research Institutions, Contractors Application: Industrial Power, Commercial Power, Renewable Energy, Backup Power |
| Companies Covered | Bureau Veritas, SGS SA, Intertek Group plc, Keysight Technologies, Chroma ATE Inc., Rohde & Schwarz, National Instruments Corporation, TÜV Rheinland, Tektronix, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Equipment Testing Market Trends and Innovations
Diagnostic instrumentation is fragmenting into modular, software-defined platforms that decouple hardware acquisition from analytics subscriptions, reshaping how utilities provision test capacity across centralized laboratories and field-deployable units.
Very low frequency (VLF) cable testing technology is bifurcating the medium-voltage diagnostics segment. Transmission operators in Germany and California adopt 0.1 Hz sinusoidal withstand methods for aged XLPE insulation assessment. The approach compresses field test duration from hours to minutes while reducing equipment transport mass, enabling single-technician deployment models that displace crew-based DC testing protocols.
EU F-Gas Regulation phase-down mandates are accelerating SF6 alternative gas adoption in switchgear type testing protocols. Manufacturers must now validate insulation performance using fluoronitrile or vacuum interrupter designs under IEC 62271-203 revised editions. European notified bodies face accreditation backlogs for these modified test regimes, delaying product market entry for Asian switchgear exporters.
Utility procurement departments now unbundle after-sales diagnostic services from original equipment manufacturer warranty packages. Transmission system operators in Texas and Queensland negotiate direct contracts with independent testing laboratories for transformer dissolved gas analysis, bypassing manufacturer service divisions. This shift concentrates purchasing power among regional procurement consortiums and compresses service margins for integrated equipment vendors.
Power Equipment Testing Market Segmentation
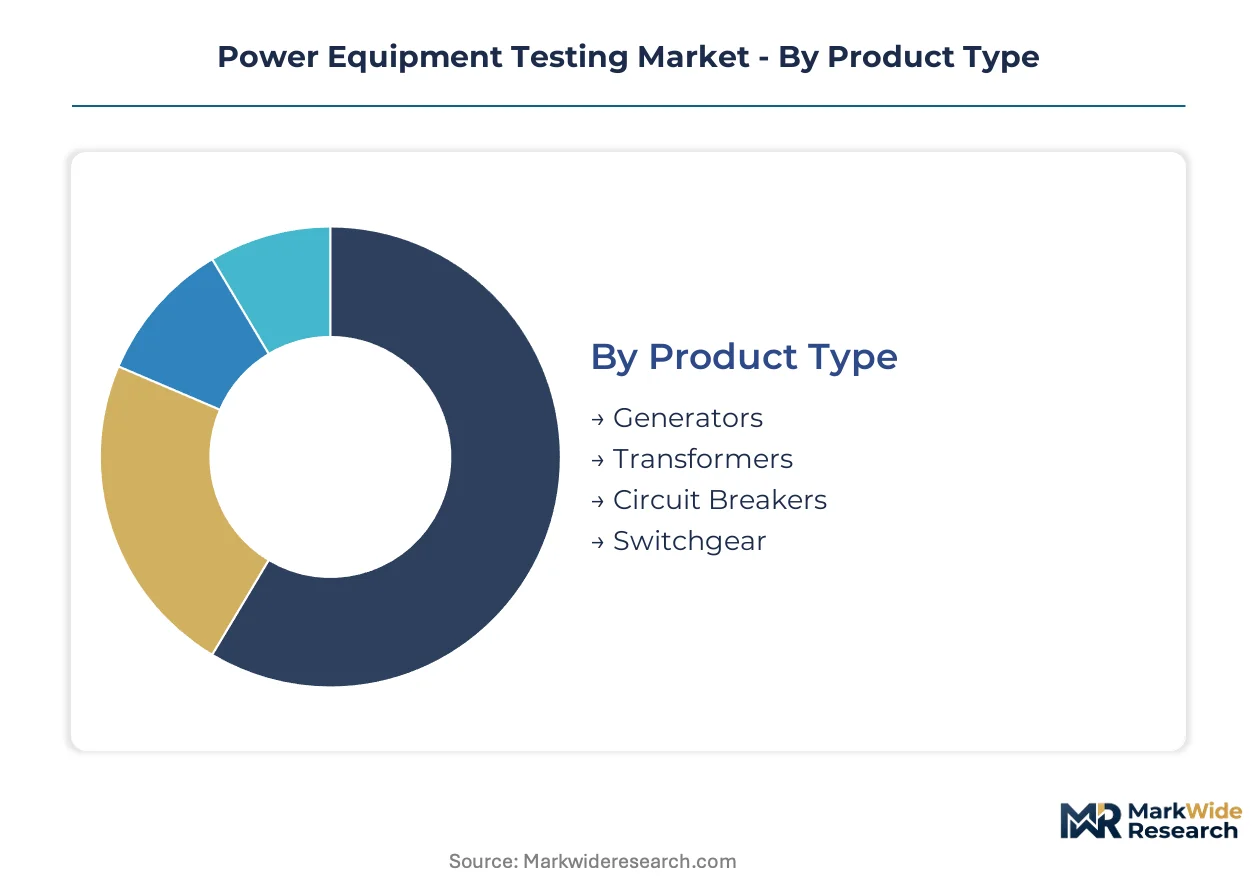
Power equipment testing demand fragments across equipment lifecycle stages, with revenue concentration shifting from factory acceptance testing toward in-service diagnostics as grid assets age. Testing protocols vary sharply by voltage class and insulation medium, creating distinct margin pools that specialized laboratories target.
Product Type:
Margin pools concentrate in liquid-immersed apparatus diagnostics where dissolved gas analysis and partial discharge detection command premium pricing.
- Transformers:Liquid-immersed and dry-type units require dissolved gas analysis, turns ratio verification, and excitation current measurement. Demand concentrates in China's State Grid expansion and Germany's offshore wind transformer replacement cycles.
- Switchgear:Gas-insulated and air-insulated assemblies need dielectric withstand testing and mechanical endurance cycling. IEC 62271 certification mandates in Europe and GB standard alignment in China sustain laboratory capacity utilization.
- Circuit Breakers:Dynamic closing/opening time measurement and contact resistance testing for medium-voltage distribution networks.
- Generators:Stator winding insulation resistance and rotor balancing protocols for utility-scale thermal and hydro plants.
Transformers hold installed capacity. Switchgear is rotating up the share rankings.
Testing Type:
Electrical diagnostics generate the highest revenue per test hour due to specialized high-voltage bay requirements and certified engineer scarcity.
- Electrical Testing:Insulation resistance, power factor, and partial discharge measurement at rated voltage stress. Offshore wind pre-commissioning in the North Sea and East Asian markets drives specialized very low frequency cable diagnostics demand.
- Thermal Testing:Infrared thermography and temperature rise verification under load conditions. Hot-spot detection in aged utility transformers gains priority as FERC Order 693 enforcement tightens.
- Mechanical Testing:Contact timing, operating force, and vibration analysis for switching apparatus.
- Durability Testing:Accelerated aging and fault current withstand cycling to validate warranty terms.
Electrical testing commands technician time. Thermal testing is climbing the fastest as predictive maintenance adoption spreads.
End User:
Procurement authority concentrates among transmission system operators with captive laboratory investments or long-term third-party contracts.
- Utilities:Transmission and distribution operators conduct acceptance testing and periodic diagnostics under NERC reliability standards and national grid codes. Texas and Queensland utilities now unbundle testing from OEM service contracts.
- Manufacturers:Factory acceptance testing and type certification for export markets. CE marking requirements under EU Machinery Directive create mandatory intervention points for European-bound equipment.
- Contractors:Commissioning services for new substation and renewable energy installations.
- Research Institutions:Pre-commercial validation and standard development support for emerging insulation technologies.
Utilities anchor volume commitment. Manufacturers are gaining share as export certification complexity rises.
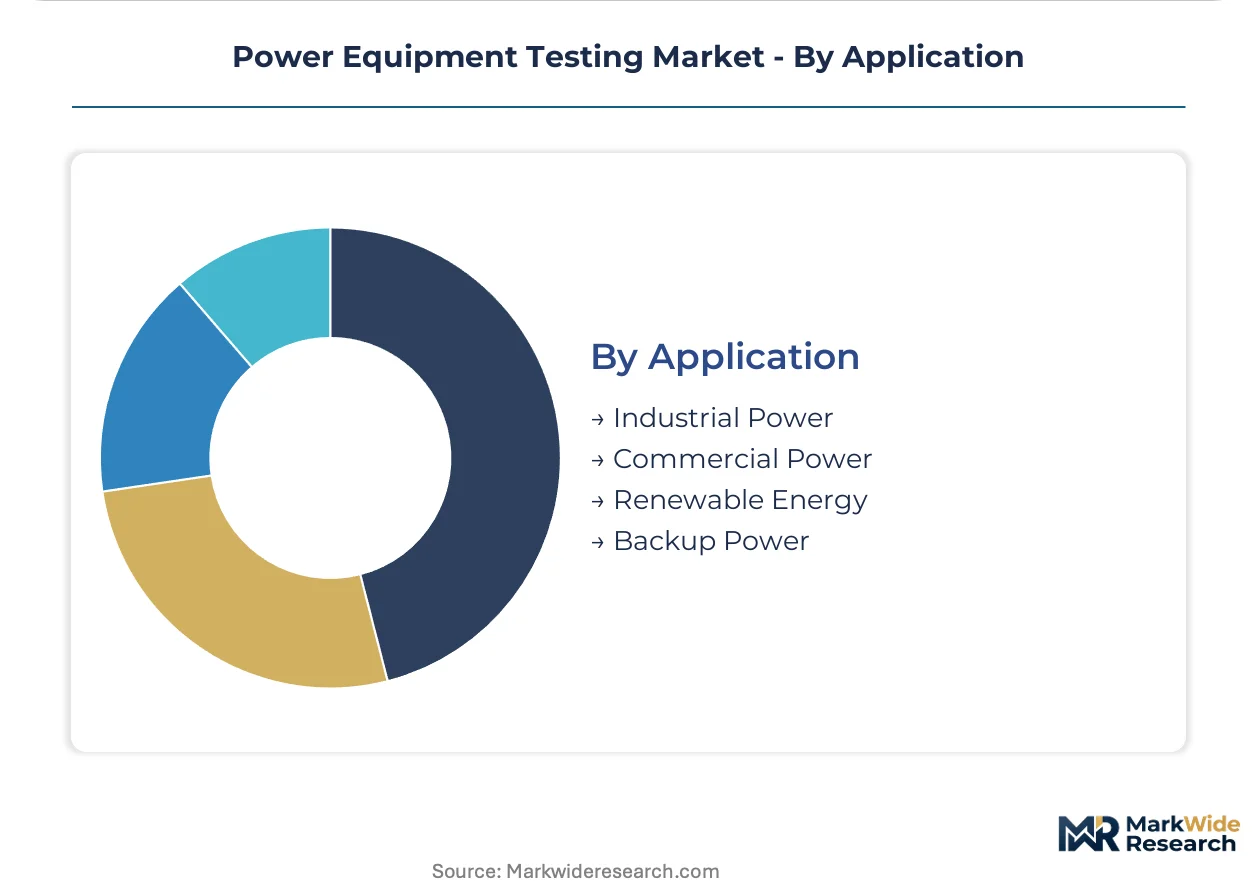
Application:
Revenue per test varies inversely with standardization—custom renewable energy protocols command 40-60% premiums over routine industrial acceptance testing.
- Renewable Energy:Variable frequency drive, inverter-transformer interface, and grid code compliance testing for offshore wind and utility-scale solar. Pre-commissioning protocols in North Sea projects and China's coastal wind zones expand specialized demand.
- Industrial Power:Motor control center and substation acceptance testing for manufacturing and processing facilities.
- Commercial Power:Data center and healthcare facility backup power system validation.
- Backup Power:Diesel and battery energy storage system startup reliability verification.
Industrial power holds baseline volume. Renewable energy is gaining share fastest as capacity additions accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FERC Order 693 anchors demand in the United States, while IEC 62271 certification requirements and GB standards harmonization reshape laboratory investments across Europe and China. Grid modernization programs and renewable energy expansion create divergent growth trajectories by geography.
United States
Texas and California utilities unbundle testing services from OEM warranty packages, creating procurement consortiums that concentrate purchasing power. FERC Order 693 mandates NERC reliability testing for bulk power system assets, sustaining recurring revenue for transformer diagnostics. The ERCOT grid operator in Texas drives specialized dissolved gas analysis demand as aging infrastructure replacement accelerates.
Germany
Offshore wind installations in the North Sea expand pre-commissioning protocols for inverter-transformer interfaces. EU F-Gas Regulation restrictions constrain SF6 availability for switchgear insulation testing, forcing protocol redesigns among notified bodies. The Ruhr industrial cluster hosts accredited laboratories validating alternative fluoronitrile insulation designs under revised IEC 62271-203 editions.
China
State Grid Corporation accelerates transformer testing capacity investments as grid modernization programs expand. GB standards alignment with IEC 62271 series specifications accelerates multinational laboratory accreditation. The Yangtze River Delta concentration around Shanghai drives specialized demand for automated test systems in power semiconductor device manufacturing.
India
Central Electricity Authority mandates for new substation commissioning create unmet demand for portable transformer test sets. Skill pipeline gaps in high-voltage dielectric theory compress service capacity, forcing utilities toward third-party outsourcing. The Maharashtra industrial corridor around Mumbai anchors dissolved gas analysis service expansion as distribution infrastructure ages.
Japan
Precision instrument manufacturing concentrates partial discharge sensor production, exposing service providers to extended equipment lead times. METI grid code harmonization efforts with IEC standards reshape accreditation requirements for export-bound equipment. The Chubu region around Nagoya maintains specialized test bay capacity for high-voltage cable diagnostics.
Power Equipment Testing Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with accredited laboratory networks and automated test system manufacturers occupying distinct competitive positions. Third-party certification providers leverage regulatory mandates to secure long-term utility contracts, while equipment specialists compete on throughput speed against manual protocols. Two strategic archetypes dominate: integrated testing service networks and precision instrumentation manufacturers. Competitive moves concentrate on geographic accreditation expansion and technology licensing partnerships.
Within the accredited service network tier, Bureau Veritas exemplifies Middle Eastern utility relationships, SGS SA anchors European transformer certification positioning, and Chroma ATE Inc. represents automated test system specialization. These three occupy positions that illustrate how geographic focus and technical differentiation separate market participants. Bureau Veritas and SGS SA sit within the third-party validation segment where regulatory mandates create barriers, while Chroma ATE Inc. exemplifies the equipment manufacturer archetype competing on protocol speed.
| Leading Market Players |
|---|
| Bureau Veritas |
| SGS SA |
| Intertek Group plc |
| Keysight Technologies |
| Chroma ATE Inc. |
| Rohde & Schwarz |
| National Instruments Corporation |
| TÜV Rheinland |
| Tektronix, Inc. |
| Others |
Pricing and Supply Chain Analysis
Long-term service contracts with capacity reservation clauses lock in both high-voltage test bay access and multi-year price visibility for transmission operators facing IEC 17025 accreditation bottlenecks. These arrangements concentrate purchasing power among utility consortiums in Texas and Queensland while exposing independent laboratories to margin compression from fixed-cost absorption.
Pricing Analysis
Geographic price spreads of 35-50% separate German offshore wind pre-commissioning protocols from routine Indian substation acceptance testing. Project-based pricing with after-sales diagnostic bundling dominates transformer certification, with premium tiers commanded by IEC 62271-accredited laboratories and economy tiers served by portable field-test operators. Cost compression in thermal imaging services is intensifying because predictive maintenance algorithm commoditization erodes specialist premiums. OEM-integrated service divisions show least price sensitivity due to warranty compliance mandates, while municipal distribution utilities in emerging markets exhibit highest sensitivity to per-test rates.
Supply Chain Analysis
Partial discharge sensor manufacturing concentrates in Japan and Germany, creating chokepoint exposure for service providers dependent on replacement instrument procurement. Precision capacitor production draws from South Korean metallized film suppliers and Swiss dielectric fluid blenders, with logistics vulnerability concentrated in transpacific semiconductor freight lanes. Distribution runs through authorized distributor networks anchored by regional equipment specialists rather than direct manufacturer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Recurring-revenue diagnostic subscriptions are expanding faster than hardware sales as utilities unbundle after-sales services from OEM warranty packages. This service-attach dynamic revalues laboratory networks above test equipment manufacturing in investor assessments.
For Market Incumbents: Fortify accreditation moats by accelerating IEC 17025 high-voltage bay certification in India and Southeast Asia before regional competitors consolidate utility relationships. Backward integration into dissolved gas analysis consumables production defends margin position against reagent supply volatility from specialty chemical distributors. For New Entrants and Emerging Players: Differentiate on portable VLF cable testing speed against crew-based DC protocols in California and German transmission markets. Target unmet demand for automated power semiconductor test systems in China's Yangtze River Delta manufacturing clusters, leveraging throughput advantages over manual transformer ratio verification. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among accredited third-party laboratories with multi-year utility framework agreements rather than project-dependent commissioning contractors. Acquisition focus should center on European notified bodies with SF6-alternative gas validation capabilities under revised IEC 62271-203 editions. Monitor F-Gas Regulation enforcement intensity as inflection indicator for alternative insulation testing demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Accreditation Network Expansion | IEC 17025 laboratory certification in India captures Central Electricity Authority substation commissioning mandates. |
| SF6-Alternative Protocol Development | Fluoronitrile validation capability under EU F-Gas Regulation secures European notified body positioning. |
| Digital Twin Integration Partnership | Physics-based asset model convergence with online monitoring sensors enables predictive testing schedules for ERCOT operators. |
| Automated Test System Licensing | Throughput-speed technology transfer to Chinese power semiconductor manufacturers accelerates regional market penetration. |
| Utility Procurement Consortium Engagement | Direct dissolved gas analysis contracting with Texas and Queensland transmission operators bypasses OEM service divisions. |
Research Methodology
Cross-validation between primary interviews with utility maintenance directors and secondary regulatory filing analysis anchors the qualitative findings. Stakeholder engagement encompassed transmission system operator planning officers, high-voltage test laboratory managers, OEM aftermarket service heads, and precision instrument procurement leads. Secondary sources included FERC Order 693 enforcement records, IEC standard revision documentation, EU F-Gas Regulation implementation notices, and State Grid Corporation capital expenditure disclosures. Bottom-up service revenue aggregation triangulated against top-down grid investment flow analysis.
Sensitivity analysis across voltage class, equipment lifecycle stage, and regional regulatory framework variations informed the projection framework. Segmentation dimensions encompassed product type, testing protocol, end-user procurement authority, and renewable energy application intensity. CAGRs were derived from installed base replacement cycles, standards harmonization timelines, and accreditation capacity expansion rates. Forecast inputs incorporated offshore wind capacity addition pipelines and dissolved gas analysis technician supply constraints.
The analysis sits within stated boundaries; outcomes outside sustained grid modernization investment levels or accelerated SF6 phase-down timelines would require recalibration. Forecasts reflect assumptions regarding IEC-GB standards convergence progress and NERC reliability standard enforcement continuity. Practitioners should keep alternative scenarios live as F-Gas Regulation implementation intensity and high-voltage engineering graduate pipeline recovery evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
Global Power Supply Market
Power Equipment
Power Generation Equipment MRO Market
Power Equipment
Power Grid Primary and Secondary Fusion Equipment Market
Power Equipment
Turbomachinery Control Systems, Retrofitting, and Ancillary Services Market
Power Equipment
Process Plants Gas Turbine Market
Power Equipment
Industrial Gas Turbine Sales Market
Power Equipment
Deaerators Market
Power Equipment
SCR Power Controller Market
Power Equipment
South America Nuclear Power Plant Equipment Market
Power Equipment
Wind Turbine Components Market
Power Equipment
Power Magnetics for MV AC Drive Market
Power Equipment
Global Transformerless UPS Market
Power Equipment
France Power EPC Market
Power Equipment
Magnetic Bearing Market
Power Equipment
ASEAN Power EPC Market
Power Equipment
Power Conditioning Services Market