
 Electric Vehicle (EV) Public Charging Station Market | 2026-2036
Electric Vehicle (EV) Public Charging Station Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle (EV) Public Charging Station Market Insights
Ultra-fast charging specifications above 350 kW is reorganizing capital allocation across the EV public charging landscape. Tesla sustains manufacturing scale through its proprietary connector ecosystem and integrated software stack. ABB competes on hardware modularity, enabling operators to upgrade power output without full site reconstruction. ChargePoint anchors network density through its cloud-integrated management platform spanning multiple charger tiers.
Electric vehicle public charging stations are electromechanical systems that convert grid alternating current into direct current compatible with onboard battery management systems, with DC fast chargers delivering 50 kW to 350 kW through liquid-cooled cable assemblies and CCS or NACS connector protocols. Their commercial purpose centers on reducing range anxiety and enabling intercity travel for battery-electric vehicles with limited onboard energy storage. DC fast charger deployments command the dominant share of new capital deployment, while bidirectional charger installations are attracting fresh investment as vehicle-to-grid protocols mature. Application-level demand concentrates at transportation hubs and public parking lots, where dwell times align with charging duration and foot traffic supports utilization rates.
FERC interconnection standards, EPA tailpipe regulations, and NHTSA fuel economy mandates collectively shape infrastructure buildout timelines and charger performance requirements across the United States. The EU Green Deal and F-Gas Regulation drive comparable standardization pressures in Europe, particularly around grid integration and refrigerant-based thermal management systems. Stakeholders must monitor evolving connector protocol battles between NACS and CCS architectures as these technical choices lock in decade-long equipment cycles and determine network interoperability economics.
Market Dynamics
Ultra-fast DC charging specifications above 350 kW are reorganizing capital allocation across the EV public charging landscape, compressing site development timelines while demanding upgraded grid interconnection capacity and liquid-cooled cable architectures.
Growth Catalysts
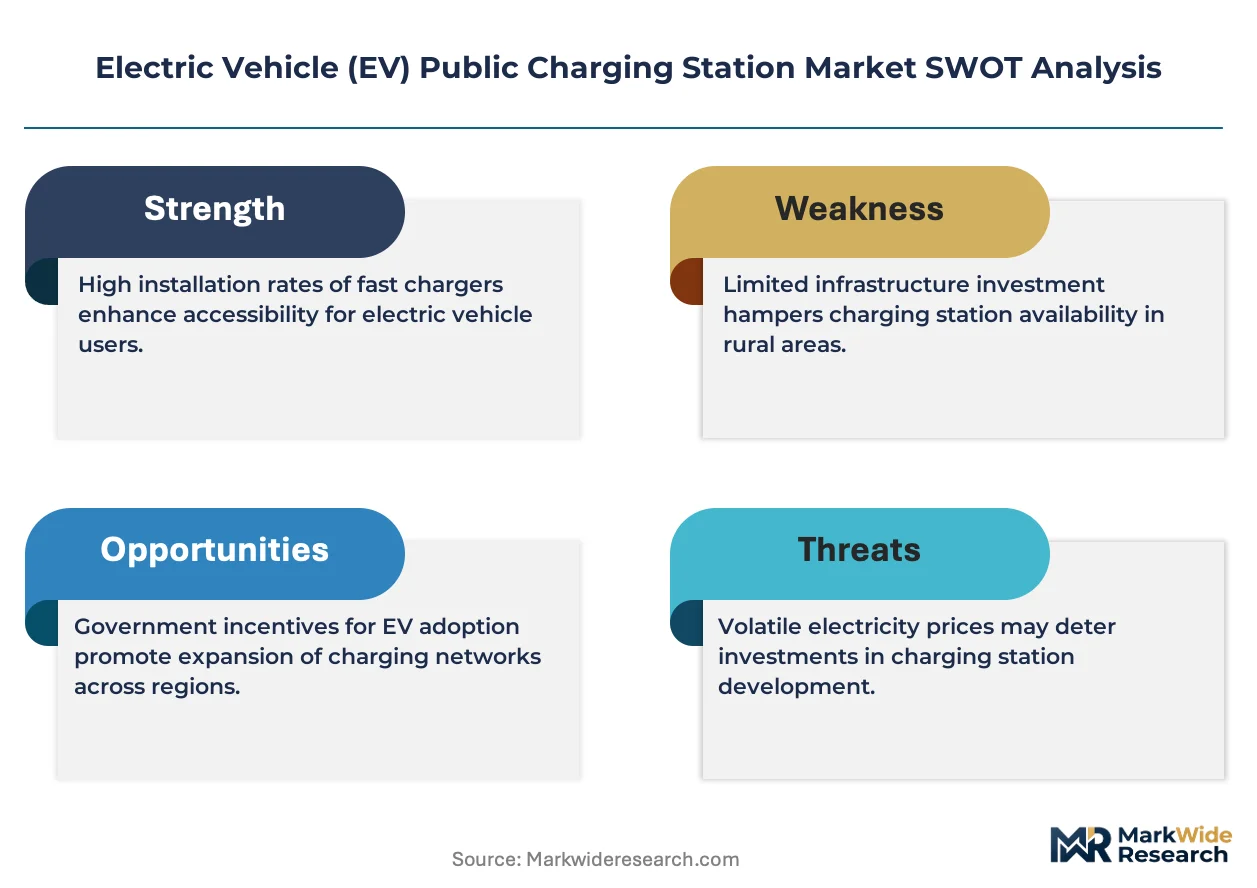
- US IRA tax credits:The Inflation Reduction Act's Alternative Fuel Refueling Property Credit accelerates deployment along interstate corridors and in disadvantaged communities through direct cost offsets.
- Fleet electrification mandates:California's Advanced Clean Trucks regulation and comparable state-level zero-emission vehicle requirements in New York and Washington pull charging infrastructure into logistics hubs and last-mile depots.
- Silicon carbide power electronics:Wider bandgap semiconductors enable higher switching frequencies and thermal efficiency in DC fast charger inverters, reducing footprint and cooling requirements.
Market Restraints
- Transformer lead times:Utility-scale distribution equipment from North American and European manufacturers currently extends 18-24 months, gating site energization regardless of charger hardware availability.
- Copper and rare earth price volatility:Liquid-cooled cable assemblies and permanent magnet motors in cooling systems expose capital budgets to commodity swings in Chilean copper and Chinese-processed rare earth elements.
- Grid interconnection queues:FERC Order 2023 reforms have not yet cleared regional transmission organization backlogs, delaying commercial operation dates for high-capacity charging sites.
Strategic Opportunities
- Vehicle-to-grid protocols:IEEE 2030.5 and ISO 15118-20 standardization creates revenue stacking through frequency regulation and peak shaving for bidirectional-capable charging assets.
- India's PLI scheme:The Production Linked Incentive program for automobile and auto component manufacturing is drawing charger OEM investment into Gujarat and Tamil Nadu manufacturing corridors.
- Curbside charging integration:Municipal streetlight and parking meter infrastructure in Paris, Amsterdam, and Seoul offers anchor tenancy for low-power AC charging without dedicated real estate acquisition.
Industry Challenges
- Certification timeline compression:UL 2594 and IEC 61851-23 testing protocols for 350 kW+ systems require 6-9 month laboratory cycles that misalign with operator deployment schedules.
- Interoperability testing burden:NACS and CCS connector variants across Tesla, ABB, Siemens, and domestic Chinese stacks multiply firmware validation requirements for network software providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle (EV) Public Charging Station Market |
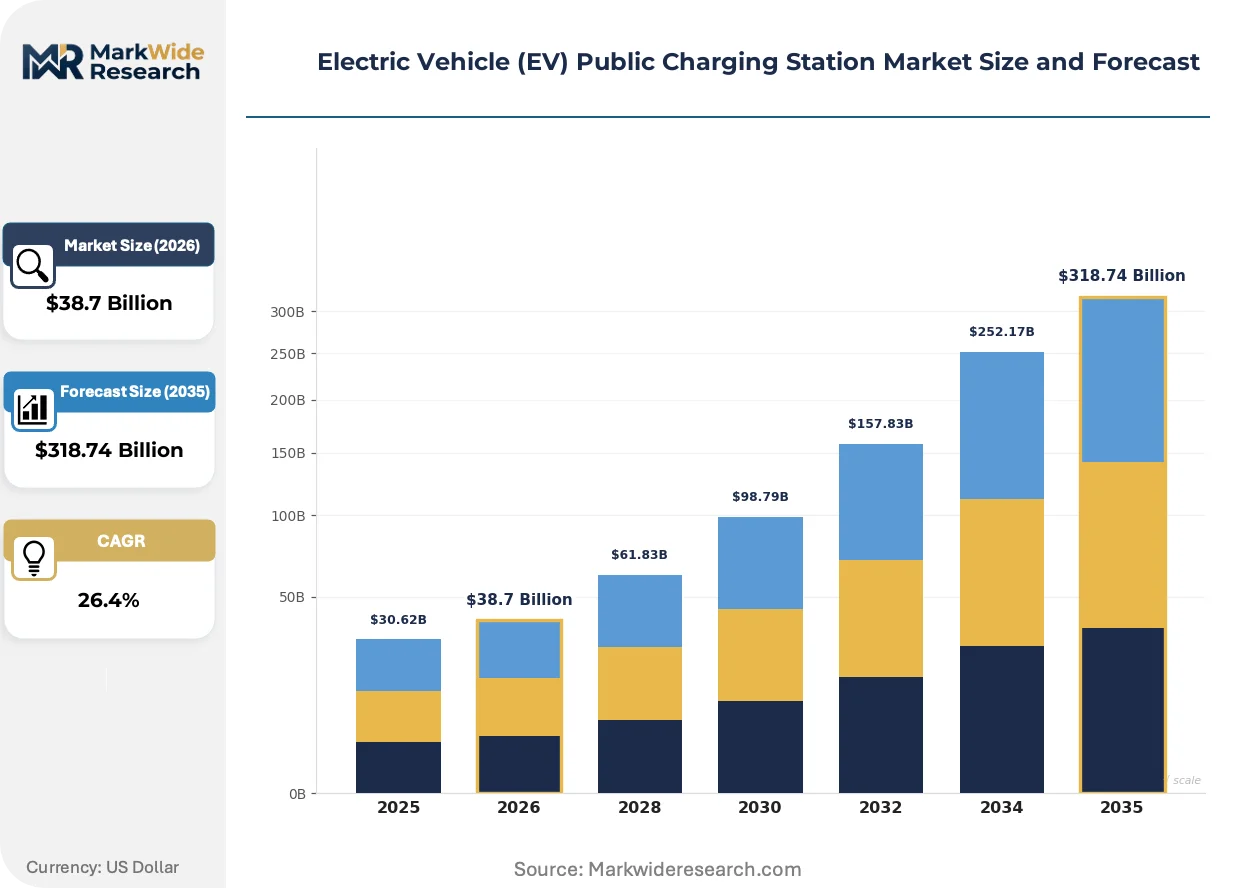
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $318.74 Billion |
| CAGR (2026 – 2036) | 26.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Charger Type: Level 1, Level 2, DC Fast Charger, Wireless Charger, Ultra-Fast Charger, Bidirectional Charger Connectivity: Wi-Fi, Cellular, RFID, Ethernet, Bluetooth, NFC Application: Public Parking Lots, Shopping Centers, Office Complexes, Transportation Hubs, Universities, Hospitality Venues End User: Fleet Operators, Individual Drivers, Commercial Parking Providers, Municipal Authorities, Energy Service Companies, Retail Chains |
| Companies Covered | Tesla, ChargePoint, ABB, Shell Recharge, BP Pulse, EVgo, EVBox, Blink Charging, Siemens, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle (EV) Public Charging Station Market Trends and Innovations
Modular power conversion architectures and dynamic load management software are fragmenting the traditional monolithic charger design paradigm, enabling incremental capacity expansion and software-defined power delivery curves.
Liquid-cooled cable assemblies rated for 500A continuous current are decomposing the thermal bottleneck that previously constrained charging rates to 350 kW. European highway corridor operators in Germany and the Netherlands are adopting these systems for 800V battery architectures. The technology is decomposing site power requirements by enabling higher throughput per stall rather than linear stall expansion.
The EU F-Gas Regulation's phasedown of hydrofluorocarbon refrigerants is forcing thermal management redesigns in charger cooling loops. Manufacturers are migrating to CO2 transcritical and propane-based systems for power electronics temperature control. This transition most affects high-latitude European deployments where ambient temperature swings stress conventional vapor-compression designs.
Fleet operators are consolidating charging procurement under single-network contracts with guaranteed uptime SLAs, displacing the earlier model of fragmented public charging card roaming. Logistics providers in California's Central Valley and Germany's Rhine-Ruhr corridor are negotiating dedicated depot infrastructure with energy-as-a-service terms. This concentration is most visible in heavy-duty trucking electrification where fuel cost predictability outweighs per-kWh rate minimization.
Electric Vehicle (EV) Public Charging Station Market Segmentation
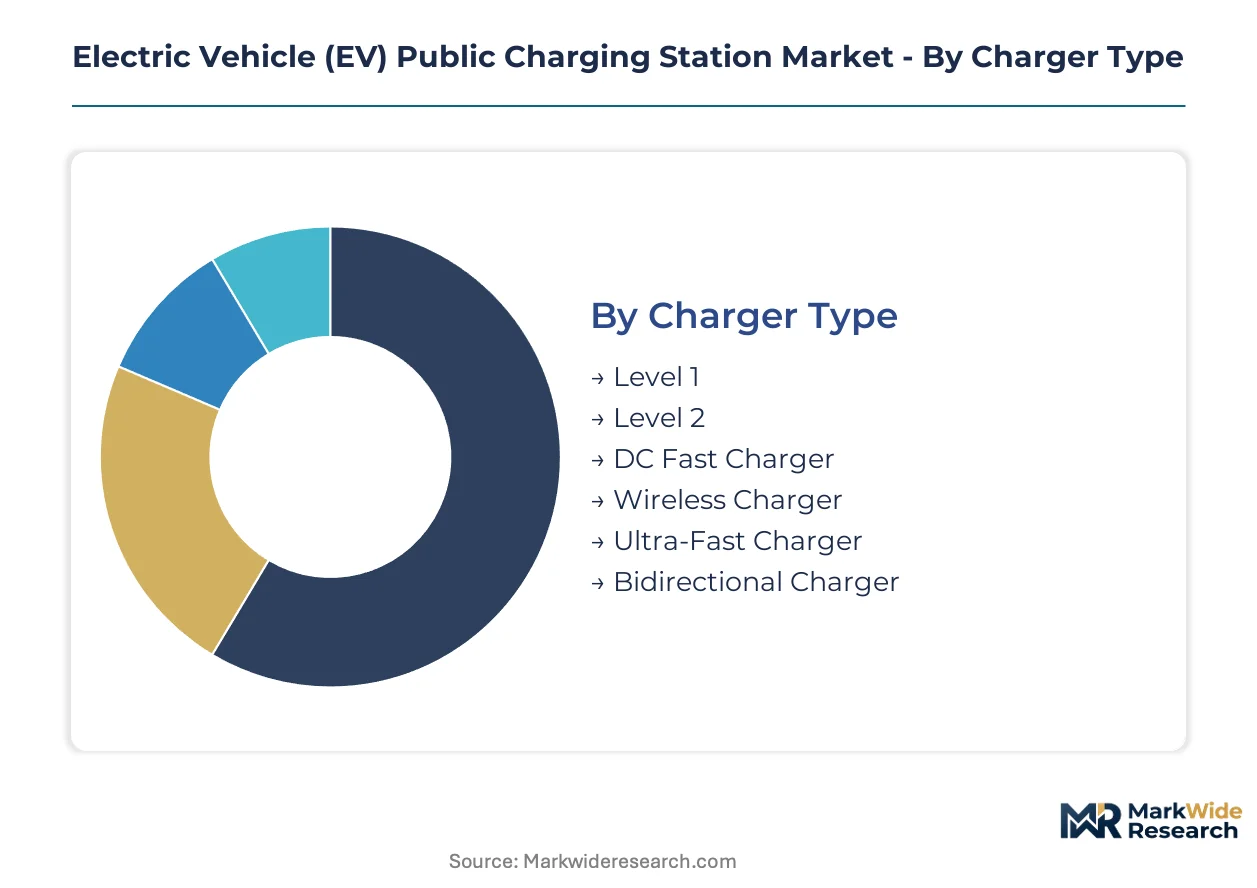
Segmentation in the EV public charging market reveals distinct margin architectures across hardware tiers, connectivity protocols, and customer procurement patterns. Understanding where capital concentrates within each dimension enables operators to align site development with utilization economics and regulatory incentive structures.
Charger Type:
Margin pools concentrate in high-power DC infrastructure where silicon carbide inverters and liquid-cooled cable assemblies command hardware premiums.
- Level 1:Residential-grade 120V alternating current systems deliver 1.4 kW through standard J1772 connectors. Demand clusters in workplace installations and multi-unit dwellings in California and New York where overnight dwell times offset slow charging rates.
- Level 2:240V alternating current systems output 3.3 kW to 19.2 kW through J1772 or Mennekes connectors. Deployment concentrates at shopping centers and office complexes in Germany and the Netherlands where 4-8 hour parking durations align with charging cycles.
- DC Fast Charger:Direct current systems deliver 50 kW to 350 kW through CCS or NACS protocols. Highway corridor operators in the United States prioritize these units for interstate travel coverage under NEVI program requirements.
- Wireless Charger:Inductive power transfer systems eliminate connector wear through magnetic resonance coupling. Pilot installations concentrate at fleet depots in Sweden and Norway where automated alignment reduces driver intervention.
- Ultra-Fast Charger:Specifications exceeding 350 kW utilize liquid-cooled 500A cable assemblies for 800V battery architectures. German autobahn corridor operators lead deployment as Porsche, Hyundai, and Kia expand compatible vehicle platforms.
- Bidirectional Charger:Vehicle-to-grid capable systems enable frequency regulation and peak shaving revenue streams. California's CAISO market and Japan's METI demonstration programs drive early commercialization.
The dominant share belongs to DC Fast Charger, while Ultra-Fast Charger is closing the gap fastest.
Connectivity:
Revenue differentiation stems from reliability tiers rather than bandwidth, with cellular backhaul commanding premiums in remote highway locations.
- Wi-Fi:Local area network protocols enable low-cost data transmission at sites with existing internet infrastructure. Shopping center operators in France and Spain leverage tenant Wi-Fi networks to minimize recurring connectivity costs.
- Cellular:4G LTE and 5G modules provide ubiquitous coverage independent of site infrastructure. Transportation hubs in rural United States corridors depend on cellular as primary backhaul where fiber penetration lags.
- RFID:Radio-frequency identification enables physical card authentication for fleet billing reconciliation. German logistics providers require RFID integration for ISO 15118-2 Plug and Charge interoperability.
- Ethernet:Wired local area network connections deliver highest reliability for high-traffic sites. Urban curbside installations in Amsterdam and Seoul utilize Ethernet where municipal fiber exists.
- Bluetooth:Short-range protocols support mobile app pairing for session initiation. Hospitality venues in Italy and Portugal adopt Bluetooth for guest experience simplification.
- NFC:Near-field communication enables contactless payment without app installation. Municipal authorities in London and Singapore specify NFC for universal access compliance.
Cellular holds the installed base lead, though NFC is expanding most quickly among new municipal specifications.
Application:
Utilization rates vary threefold across site types, with transportation hubs capturing highest throughput per stall.
- Public Parking Lots:Surface and structured parking facilities integrate charging as amenity differentiation. Operators in Chicago and Toronto prioritize these sites for IRA disadvantaged community bonus credit eligibility.
- Shopping Centers:Retail-anchored installations align charging duration with typical shopping dwell times of 60-90 minutes. French retail chains Carrefour and Auchan deploy Level 2 and 150 kW DC systems at hypermarket locations.
- Office Complexes:Workplace charging serves employee vehicles during 8-hour workdays. Suburban office parks in Texas and Georgia install Level 2 infrastructure for tenant retention.
- Transportation Hubs:Airports, train stations, and intermodal terminals combine high foot traffic with extended parking durations. Frankfurt Airport and Amsterdam Schiphol anchor European ultra-fast charging corridors.
- Universities:Campus installations serve student, faculty, and visitor vehicles with sustainability visibility. University of California system campuses deploy solar-canopy charging under state carbon neutrality mandates.
- Hospitality Venues:Hotels and resorts offer overnight charging for traveling EV owners. Boutique properties in Norway's fjord region and California's wine country differentiate through Tesla Destination Charger partnerships.
Transportation Hubs generate highest revenue per stall, while Hospitality Venues are gaining share fastest through destination charging partnerships.
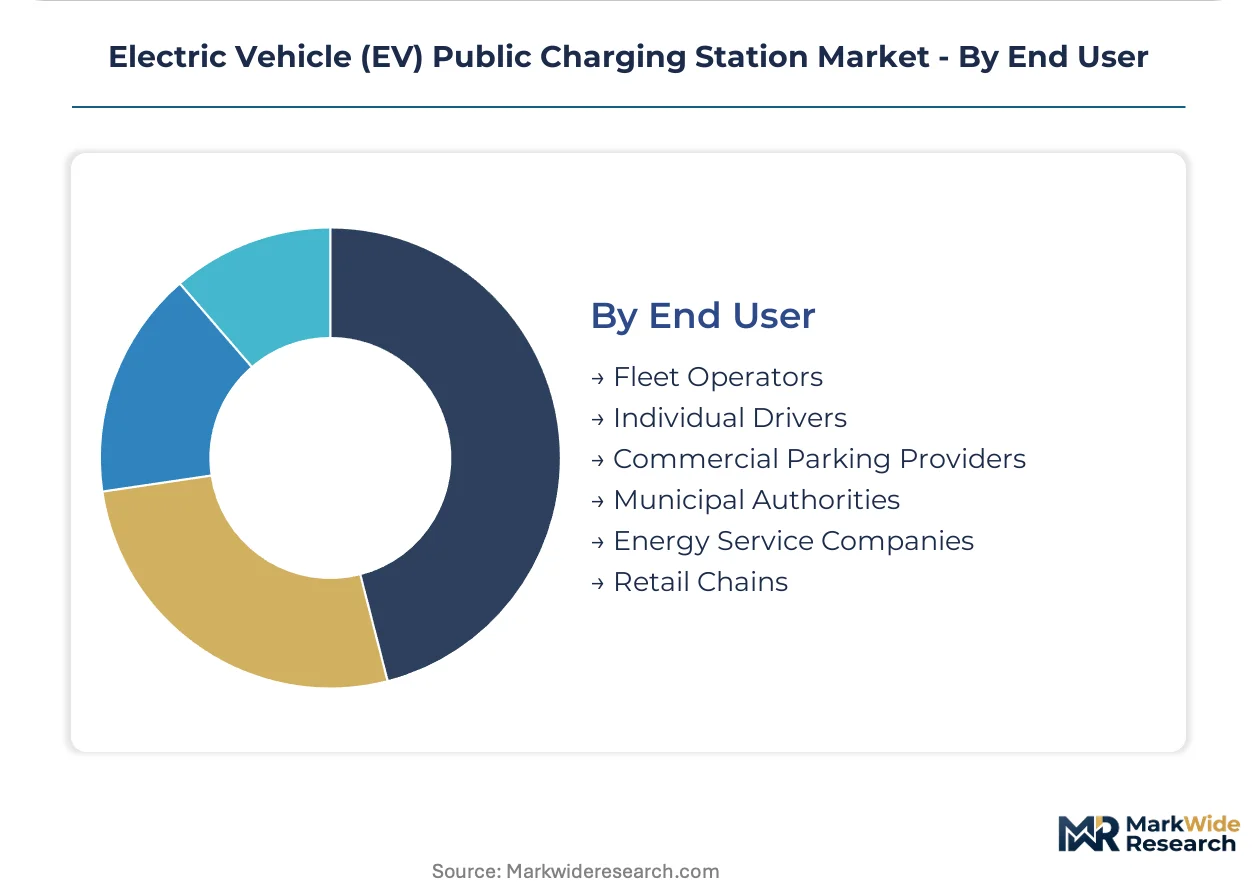
End User:
Procurement concentration is accelerating toward fleet operators who negotiate multi-site contracts with uptime guarantees.
- Fleet Operators:Logistics, delivery, and ride-hail fleets require depot and opportunity charging at scale. Amazon's Rivian delivery van deployment in Southern California and DHL's German electric truck fleet drive dedicated infrastructure investment.
- Individual Drivers:Retail charging access reduces range anxiety for owners without home charging. Urban apartment dwellers in Seoul and Paris depend on public infrastructure for daily vehicle operation.
- Commercial Parking Providers:Private parking operators monetize stalls through charging service fees. Q-Park in the Netherlands and ParkWhiz in the United States integrate charging into reservation platforms.
- Municipal Authorities:City and regional governments deploy curbside and public lot infrastructure for equitable access. Los Angeles Department of Water and Power and Transport for London operate publicly owned networks.
- Energy Service Companies:Utilities and energy retailers offer charging-as-a-service with bundled electricity supply. E.ON Drive in Germany and Electrify America in the United States combine generation, storage, and charging assets.
- Retail Chains:Consumer-facing brands deploy charging to extend customer dwell time. Tesco in the United Kingdom and Walmart in the United States install chargers at supercenter locations.
Fleet Operators command the largest committed capital pipelines, though Energy Service Companies are climbing the fastest through integrated energy offerings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Charger manufacturing capacity concentrates in Germany, China, and the United States, while deployment economics pull infrastructure investment toward highway corridors and fleet depots in jurisdictions with binding zero-emission mandates. National subsidy programs and utility interconnection standards determine site energization velocity more than hardware availability.
United States
NEVI formula funding and IRA tax credits accelerate corridor deployment along Interstate highways from California through Texas to Florida. FERC interconnection standards and EPA tailpipe regulations shape buildout timelines, with California's Advanced Clean Trucks regulation pulling infrastructure into Central Valley logistics hubs serving Amazon and DHL electrified fleets.
Germany
Autobahn corridor operators prioritize 350 kW+ liquid-cooled systems for Porsche, Hyundai, and Kia 800V architectures. The EU Green Deal and F-Gas Regulation drive thermal management redesigns, with Rhine-Ruhr logistics providers negotiating dedicated depot infrastructure under energy-as-a-service contracts for heavy-duty trucking electrification.
China
State Grid Corporation and private operators deploy ultra-fast charging along Beijing-Shanghai and Guangzhou-Shenzhen expressways to serve BYD, NIO, and XPeng vehicle platforms. MIIT GB standards and dual carbon goals mandate infrastructure density targets, with Yangtze River Delta manufacturing clusters producing silicon carbide power electronics for domestic charger OEMs.
Netherlands
Randstad metropolitan charging density leads European utilization rates through Q-Park integrations and Shell Recharge highway coverage. The country's national climate agreement mandates 1.7 million charging points by 2030, with Amsterdam Schiphol Airport anchoring ultra-fast corridors connecting Germany and Belgium.
India
Gujarat and Tamil Nadu manufacturing corridors attract charger OEM investment under the PLI scheme for automobile and auto component manufacturing. CEA technical standards and state-level electric vehicle policies in Maharashtra and Karnataka concentrate deployment at Mumbai and Bengaluru transportation hubs serving fleet operators and individual drivers without home charging access.
Electric Vehicle (EV) Public Charging Station Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the EV public charging landscape. The market structure fragments across integrated automotive OEMs, pure-play network operators, and industrial electrical equipment manufacturers. Three strategic archetypes dominate: proprietary ecosystem builders, modular hardware specialists, and cloud-integrated platform providers. Competitive dynamics center on connector protocol alignment and vertical integration into energy management software rather than hardware differentiation alone.
Within the integrated automotive tier, Tesla anchors proprietary ecosystem control through its NACS connector standard and Supercharger network density. ABB and Siemens occupy positions as modular hardware specialists with industrial electrical equipment heritage, serving operators requiring upgradeable power architectures. ChargePoint exemplifies the cloud-integrated platform archetype, spanning multiple charger tiers through software-defined network management without captive manufacturing.
| Leading Market Players |
|---|
| Tesla |
| ChargePoint |
| ABB |
| Shell Recharge |
| BP Pulse |
| EVgo |
| EVBox |
| Blink Charging |
| Siemens |
| Others |
Pricing and Supply Chain Analysis
Silicon carbide power module substitution for conventional silicon IGBT inverters simultaneously shifts procurement geography toward Yangtze River Delta manufacturing clusters and compresses hardware cost curves for ultra-fast DC charger tiers. This material transition reconfigures supplier power dynamics as Chinese wafer fabs capture incremental value while European and North American assemblers absorb margin pressure.
Pricing Analysis
NEVI formula funding dictates the pricing tier structure across the United States EV charging landscape, with disadvantaged community bonus credits creating a three-tier pricing structure across premium, standard, and economy levels based on site qualification status and interconnection complexity. Price differentiation stems from liquid-cooled cable assembly specifications and UL 2594 certification tiers, with highway corridor operators least price-sensitive due to uptime SLA penalties while municipal curbside deployments face acute budget constraints.
Supply Chain Analysis
Port congestion at Shanghai and Rotterdam constrains inbound logistics for liquid-cooled cable assemblies and silicon carbide wafers, extending lead times for North American charger OEMs. Manufacturing concentrates in China, Germany, and the United States, with supply chains drawing from Chilean copper, Chinese-processed rare earth elements, and Taiwanese semiconductor substrates. Single-source vulnerability in permanent magnet motor cooling systems threatens production continuity, while distribution runs through direct OEM-operator contracts and energy-as-a-service intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EV public charging station market sits in early-cycle expansion, with fleet electrification mandates pulling infrastructure investment ahead of consumer vehicle parity. California's Advanced Clean Trucks regulation exemplifies the regulatory tailwind accelerating deployment velocity.
For Market Incumbents: Secure transformer allocation commitments through 18-24 month forward contracts with utilities, insulating site energization timelines from distribution equipment shortages. Consolidate firmware validation capabilities across NACS and CCS protocol stacks to reduce interoperability testing burdens, while expanding silicon carbide inverter backward integration into Yangtze River Delta supply corridors. For New Entrants and Emerging Players: Differentiate on dynamic load management software for multi-tenant commercial parking installations, where incumbent hardware providers lack cloud-native orchestration depth. Target India's Gujarat and Tamil Nadu manufacturing corridors under PLI scheme incentives, deploying curbside AC charging through municipal streetlight infrastructure partnerships with lowest capital intensity. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed fleet charging specialists holding California Central Valley depot contracts with Amazon and DHL. Long-term viability hinges on vehicle-to-grid revenue stack capture under IEEE 2030.5 standardization. Watch CAISO frequency regulation market participation rates as the inflection signal for bidirectional charger asset valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Inverter Vertical Integration | Yangtze River Delta wafer sourcing reduces thermal footprint and cooling costs for 350 kW+ systems. |
| NACS Protocol Certification Investment | UL 2594 laboratory accreditation accelerates Tesla network interoperability and operator deployment timelines. |
| Fleet Depot Energy-as-a-Service Contracts | Amazon and DHL electrified logistics commitments anchor guaranteed revenue streams in California and Germany. |
| Vehicle-to-Grid Software Platform Development | CAISO frequency regulation participation unlocks revenue stacking for bidirectional charging assets. |
| Municipal Curbside Infrastructure Partnerships | Paris and Amsterdam streetlight integrations minimize real estate acquisition costs for low-power AC deployment. |
Research Methodology
Desk research of FERC interconnection filings, EPA tailpipe regulatory dockets, and NEVI program disbursement records preceded structured interviews with utility planning officers, fleet charging procurement leads, charger OEM platform engineers, and municipal transportation authority directors. Primary fieldwork combined with secondary validation across IEA EV outlook databases, EIA electricity market data, and SEC equipment manufacturer disclosures. Bottom-up site deployment modeling triangulated against top-down infrastructure investment forecasts.
Variance decomposition across charger type, connectivity protocol, application segment, and end-user procurement pattern anchored the analytical framework over the projection horizon. CAGRs derived from logistic diffusion modeling of fleet electrification penetration curves and consumer EV adoption S-curves, with silicon carbide cost decline trajectories and transformer lead time assumptions as key forecast inputs.
Material uncertainties — copper and rare earth commodity volatility, FERC Order 2023 interconnection queue clearance velocity, NACS-CCS protocol standardization outcomes — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory incentive continuity and grid upgrade investment pacing. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Japan Electric Vehicle Charging Station Market
Electric Vehicle Charging
Bi Directional Electric Vehicle Charger Market
Electric Vehicle Charging
Second Life Electric Vehicle Battery Market
Electric Vehicle Charging
AC Electric Vehicle Charging Station Market
Electric Vehicle Charging
Smart EV Charger Market
Electric Vehicle Charging
Europe EV Charging Stations Market
Electric Vehicle Charging
EV Charging Facilities Market
Electric Vehicle Charging
EV DC Chargers Market
Electric Vehicle Charging
Global Automotive Charging System Market
Electric Vehicle Charging
Public EV Charging Pile Market
Electric Vehicle Charging
Multi-Brand Universal Home Charging Pile Market
Electric Vehicle Charging
Sweden Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Electric Vehicle Charging Plugs Market
Electric Vehicle Charging
Electric Vehicle Charging Management Software Market
Electric Vehicle Charging
Portable Charging Units Market
Electric Vehicle Charging
Charging As a Service Market