
 Portable Charging Units Market | 2026-2036
Portable Charging Units Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Charging Units Market Analytics
Gallium nitride (GaN) semiconductor technology is fragmenting the traditional silicon-based charger ecosystem, enabling smaller form factors and higher wattage densities. Anker Innovations leverages its GaNPrime architecture to dominate premium power bank tiers. Samsung Electronics anchors its mobile ecosystem with proprietary Super Fast Charging protocols across Galaxy device portfolios. Xiaomi Corporation competes aggressively on cost-engineered wall chargers in emerging Asian markets.
Portable charging units are electrochemical energy storage and conversion devices designed to replenish battery-powered electronics through wired or wireless power transfer, typically incorporating lithium-ion cells with energy densities ranging from 100-265 Wh/kg and output capacities between 5W and 240W. Their primary commercial purpose centers on untethered power delivery for consumer electronics, industrial field equipment, and emergency backup systems. Power banks lead unit shipments due to smartphone dependency, while USB-C technology captures the fastest growth as universal charging standards consolidate across laptops and tablets. Wireless charging segments command premium pricing in wearable applications where connector-free designs enhance device durability.
The EU Battery Regulation and REACH compliance frameworks are elevating recyclability and substance restriction requirements for lithium-ion cells sold across Europe. The US FCC mandates electromagnetic interference certifications for all RF-emitting wireless charging pads distributed domestically. Japan's METI enforces PSE safety marks on portable batteries to prevent thermal runaway incidents in consumer products. Stakeholders must monitor evolving interoperability mandates between regional fast-charging standards as OEMs negotiate protocol licensing terms.
Market Dynamics
GaN semiconductor technology is compressing charger form factors while EU Battery Regulation mandates force recyclability redesigns across lithium-ion supply chains, creating simultaneous pull-and-push pressures on manufacturers.
Growth Catalysts
- EU Battery Regulation recyclability mandates:The framework requires minimum recycled content thresholds and carbon footprint declarations, compelling manufacturers to redesign cell architectures and secure closed-loop material partnerships.
- USB-C universal charging standard:The IEC 62684 protocol consolidation across laptops, tablets, and smartphones eliminates proprietary cable fragmentation, reducing consumer friction and inventory complexity for retailers.
- Germany automotive roadside assistance integration:OEM assistance programs are embedding portable charging units into fleet service vehicles, creating institutional demand channels beyond consumer retail.
Market Restraints
- Lithium carbonate price volatility:Raw material input swings of 300% between 2021-2023 compress margin predictability for cell packagers without long-term offtake agreements.
- China cell manufacturing concentration:Over 70% of global lithium-ion cell production sits in Fujian and Guangdong provinces, exposing supply continuity to single-geography logistics disruptions.
- Silicon-based charger incumbent lock-in:Established semiconductor fabs resist retooling for GaN wafers, slowing technology transition timelines for cost-sensitive tier-two manufacturers.
Strategic Opportunities
- India BIS certification pathway:The Bureau of Indian Standards mandatory IS 16046 registration for lithium-ion batteries creates first-mover advantage for compliant exporters before domestic capacity matures.
- Wireless charging wearable integration:Connector-free power transfer eliminates ingress points in fitness bands and medical patches, opening premium pricing tiers in health monitoring applications.
- Vehicle-to-load (V2L) bidirectional systems:Convergence of EV battery architectures with portable power stations enables campsite and emergency backup use cases beyond traditional consumer electronics.
Industry Challenges
- Cross-protocol licensing complexity:Proprietary fast-charging standards from device OEMs require per-unit royalty negotiations, fragmenting product development roadmaps.
- EU REACH SVHC substance tracking:The European Chemicals Agency candidate list updates force continuous supply chain auditing for cobalt, nickel, and electrolyte solvent compliance.
- Thermal runaway testing capacity bottleneck:UN 38.3 certification backlogs at accredited laboratories extend product launch timelines by 4-8 months for new cell formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Charging Units Market |
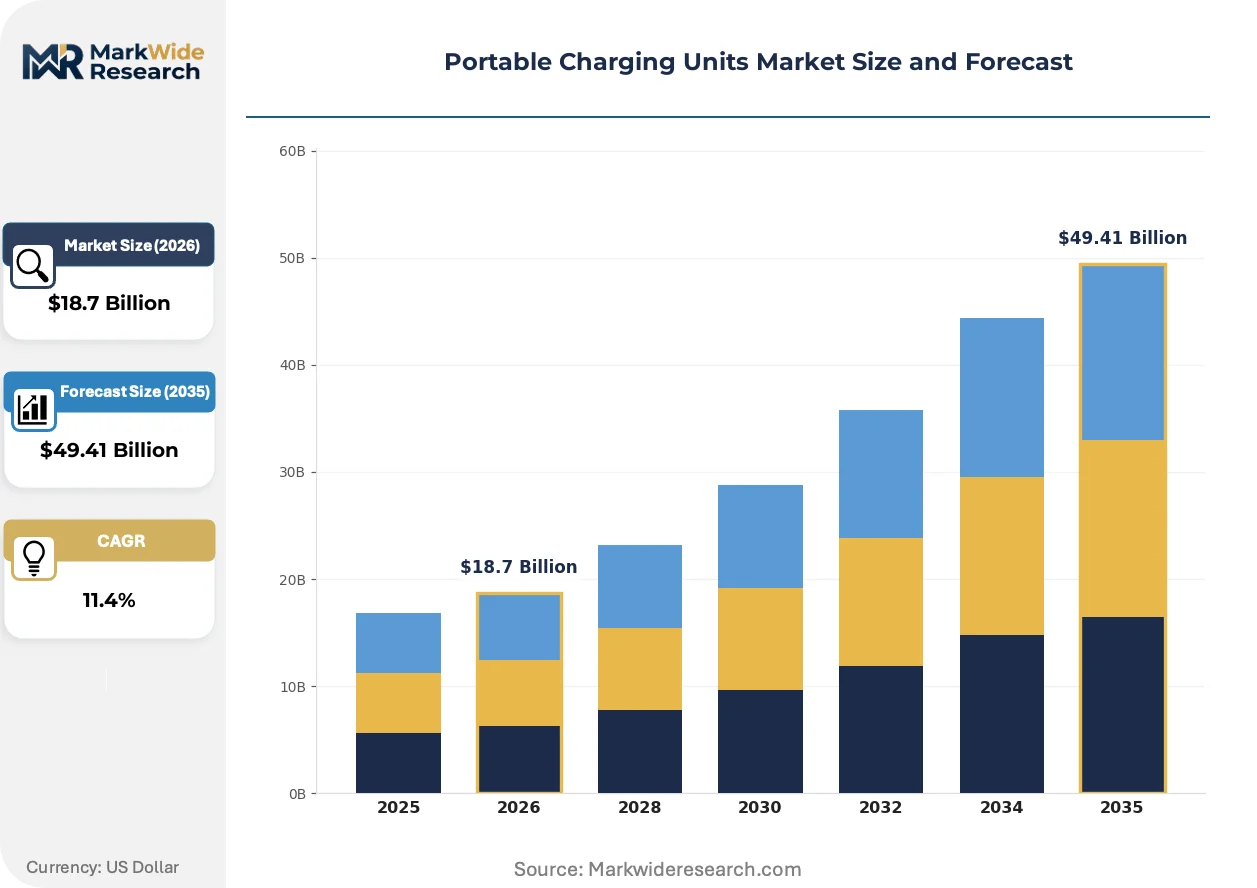
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall Chargers, Car Chargers, Power Banks, Solar Chargers Technology: USB-C, Quick Charge, Wireless, Lithium-ion Application: Smartphones, Tablets, Laptops, Wearables End User: Consumers, Corporates, Travelers, Students |
| Companies Covered | Anker Innovations, Apple Inc., AUKEY, Baseus, Belkin, Xiaomi Corporation, Samsung Electronics, RAVPower, Alpha Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Charging Units Market Evolving Landscape
Active matrix power management is redefining how charging units interact with device batteries, shifting from passive voltage delivery to negotiated power contracts.
GaN semiconductor technology replaces silicon MOSFETs in high-frequency switching circuits, enabling 65W+ outputs from palm-sized enclosures. Enterprise procurement teams in field services and medical device fleets are specifying GaN-based units for weight-sensitive mobile workforces. The technology is digitizing power negotiation protocols, allowing chargers to query device state-of-charge and thermal conditions before committing to full current delivery.
The EU Battery Regulation's digital battery passport mandate requires QR-coded lifecycle tracking from cell production through recycling. Manufacturers must deploy blockchain-anchored data systems to satisfy ECHA audit requirements for carbon footprint and material provenance. Premium product tiers are responding earliest, embedding passport compliance as a competitive differentiator in German and French retail channels.
Subscription-based power-as-a-service models are displacing outright equipment purchases among commercial fleet operators. Logistics companies in the Netherlands and Belgium now lease portable charging pools with swap-out maintenance rather than capitalizing depreciating hardware assets. This shift concentrates buyer power with procurement consortia, compressing distributor margins while expanding recurring revenue streams for OEMs with captive financing arms.
Portable Charging Units Market Segmentation
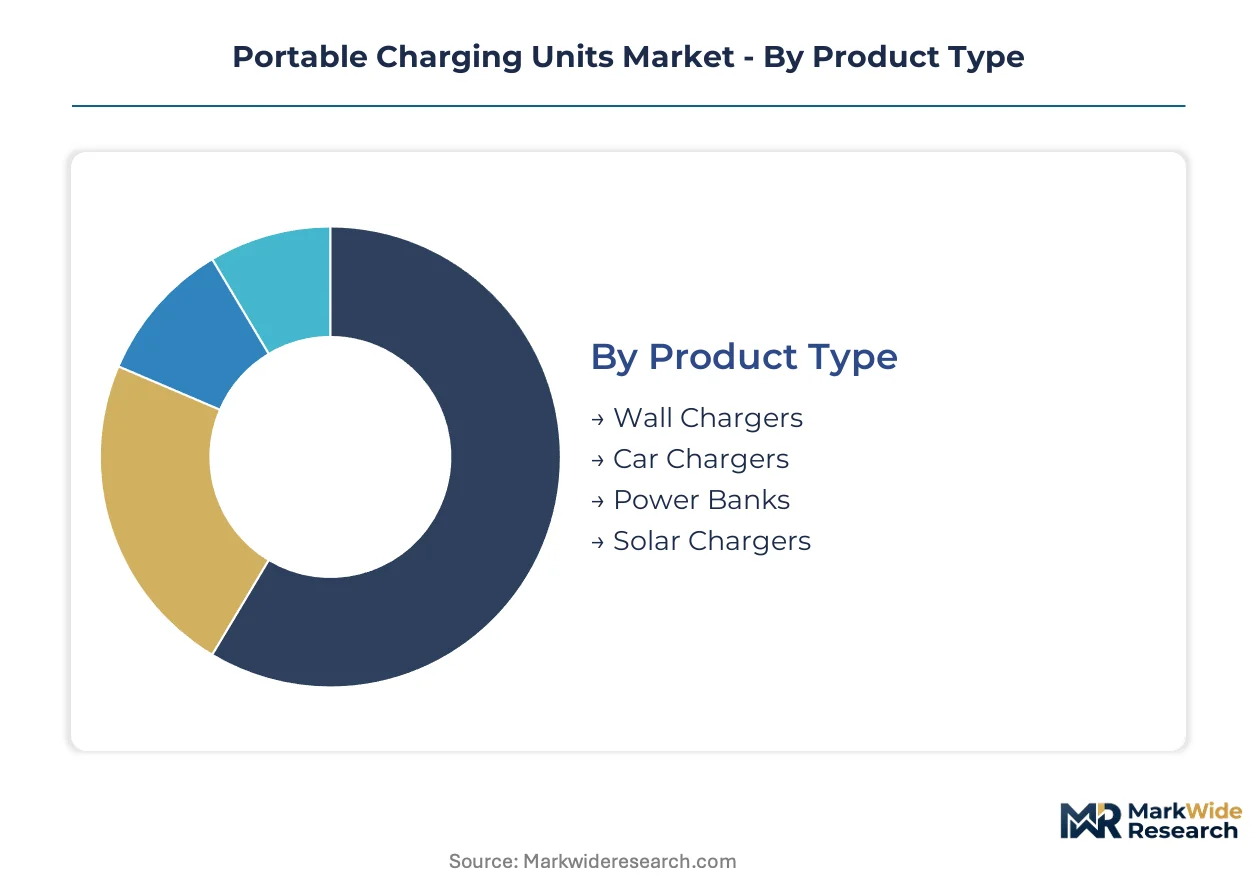
Segmentation in portable charging units reveals divergent margin profiles and service intensity requirements across product architectures. After-sales support demands vary sharply between disposable wall chargers and enterprise-grade power banks with multi-year warranty obligations.
Product Type:
After-sales-service intensity escalates dramatically from fixed-installation wall units to field-deployable power banks requiring battery health monitoring and replacement logistics.
- Power Banks:Lithium-ion cell packs with 5,000-30,000mAh capacities dominate commercial mobility use cases. Fleet operators in Germany specify these for roadside assistance vehicles where cell degradation tracking and swap programs create recurring service revenue. Demand concentrates in automotive OEM assistance programs integrating portable charging into service infrastructure.
- Wall Chargers:AC-DC conversion modules delivering 5W to 240W through fixed installations carry minimal post-sale obligations. Consumer electronics retailers in India stock these as high-velocity, low-touch SKUs where BIS certification compliance represents the primary value-add service.
- Car Chargers:Vehicle-mounted DC adapters with 12V/24V inputs serve commercial logistics and passenger transport fleets.
- Solar Chargers:Photovoltaic-integrated units with MPPT controllers target off-grid field operations and emergency preparedness segments.
By volume, Wall Chargers leads. By growth pace, Power Banks is ahead.
Technology:
Cost tier stratification separates premium GaN-enabled protocols from commodity silicon-based alternatives, with certification complexity scaling alongside power density.
- USB-C:IEC 62684 universal standard with PD 3.1 protocol support up to 240W eliminates cable fragmentation across laptop and tablet ecosystems. Enterprise procurement in the Netherlands specifies USB-C exclusively to simplify inventory and reduce field service complexity for mixed-device fleets.
- Wireless:Qi and proprietary magnetic alignment systems enable connector-free power transfer for sealed wearable devices. Medical patch manufacturers in France pay premium pricing for ingress-proof charging where connector durability failures previously drove warranty costs.
- Quick Charge:Proprietary voltage negotiation protocols from device OEMs require per-unit licensing.
- Lithium-ion:Electrochemical cell chemistry underlying all rechargeable portable formats.
By installed base, Lithium-ion underpins all segments. By protocol adoption velocity, USB-C is climbing the fastest.
Application:
Application-driven volume concentration in smartphones masks steeper expansion trajectories in laptop and wearable segments where power requirements outpace battery density improvements.
- Smartphones:Handheld communication devices with 3,000-5,000mAh batteries requiring daily replenishment cycles. Power bank attachment rates in India exceed 40% of smartphone sales, with BIS-certified units commanding retail shelf priority before domestic cell manufacturing matures.
- Laptops:Mobile computing platforms with 45W-100W power demands drive USB-C PD adoption. Corporate IT procurement in Germany specifies 65W+ GaN chargers to reduce traveler carry weight while maintaining compatibility across Dell, HP, and Lenovo fleet deployments.
- Tablets:Hybrid consumption devices with intermediate power requirements between phones and laptops.
- Wearables:Fitness bands and medical monitors with sub-1W charging needs favor wireless inductive systems.
By shipment volume, Smartphones dominates. By pricing expansion, Laptops shows the steepest trajectory.
End User:
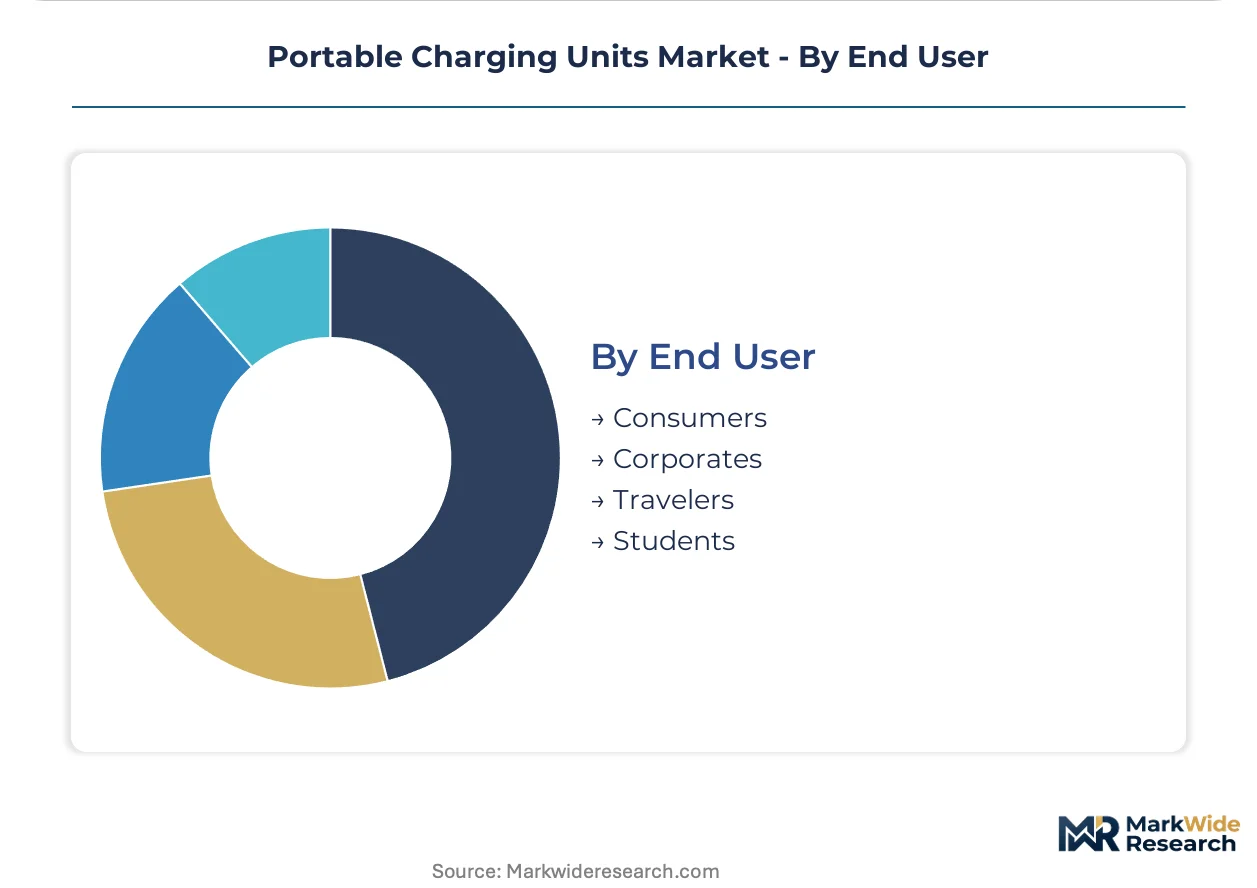
Customer type determines procurement channel structure, with corporate buyers consolidating through fleet management contracts while travelers and students drive retail fragmentation.
- Corporates:Enterprise and institutional buyers with standardized device fleets and centralized IT procurement. Logistics operators in Belgium lease portable charging pools through power-as-a-service contracts, outsourcing hardware lifecycle management to OEM financing arms rather than capitalizing depreciating assets.
- Consumers:Individual purchasers selecting based on price-performance ratios and brand recognition. German retail channels show early adoption of EU Battery Regulation digital passport compliance as a competitive differentiator in premium product tiers.
- Travelers:Mobile individuals prioritizing compact form factors and multi-device compatibility.
- Students:Price-sensitive demographic with high device dependency and limited replacement budgets.
By transaction frequency, Consumers leads. By contract value concentration, Corporates is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports lithium-ion cells and GaN semiconductor components to Germany, where automotive OEMs embed portable charging into roadside assistance fleets. Trade corridors connect Fujian manufacturing clusters with Rotterdam distribution hubs serving Dutch and Belgian logistics operators.
United States
FCC electromagnetic interference certifications govern wireless charging pad distribution, with enterprise IT procurement specifying USB-C PD chargers for Dell and HP fleet standardization. Silicon Valley hardware startups and Austin semiconductor fabs drive GaN technology adoption for compact high-wattage designs.
Germany
Automotive OEM assistance programs create institutional demand channels beyond consumer retail, with KBA vehicle safety standards influencing charger integration protocols. Munich and Stuttgart engineering clusters develop bidirectional V2L systems converging EV architectures with portable power stations.
China
MIIT industrial policy accelerates domestic GaN wafer production, reducing dependency on imported silicon MOSFETs. Shenzhen and Dongguan electronics manufacturing clusters supply over 70% of global lithium-ion cell packaging capacity, serving Indian and Southeast Asian export markets.
India
BIS mandatory IS 16046 certification for lithium-ion batteries creates first-mover advantage for compliant exporters before domestic cell manufacturing matures under PLI scheme incentives. Maharashtra and Gujarat industrial corridors attract power bank assembly investments from Chinese and Korean component suppliers.
Netherlands
Power-as-a-service leasing models concentrate procurement power with logistics consortia in Rotterdam and Eindhoven, compressing distributor margins while expanding recurring revenue for OEM financing arms. Dutch fleet operators specify USB-C exclusively to simplify mixed-device inventory management.
Portable Charging Units Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market strata. The vendor base organizes around three archetypes: semiconductor-integrated platform owners, component-scale fabricators, and regional certification specialists. Consolidation pressures favor players with captive GaN wafer supply or BIS pre-certification status. Dominant competitive moves include strategic partnerships for closed-loop lithium recycling and geographic expansion into India's compliance-window period.
Within the platform-owner tier, Anker Innovations and Samsung Electronics exemplify divergent ecosystem strategies. Anker leverages GaNPrime architecture dominance in premium power bank tiers through direct-to-consumer channel control. Samsung anchors proprietary Super Fast Charging protocols across Galaxy device portfolios, creating switching costs for accessory procurement. Xiaomi Corporation occupies a position between these poles, competing aggressively on cost-engineered wall chargers in emerging Asian markets while building BIS certification pipelines for Indian market entry.
| Leading Market Players |
|---|
| Anker Innovations |
| Apple Inc. |
| AUKEY |
| Baseus |
| Belkin |
| Xiaomi Corporation |
| Samsung Electronics |
| RAVPower |
| Alpha Group |
| Others |
Value Network & Pricing Analysis
Fujian and Guangdong province cell manufacturing clusters anchor upstream lithium-ion supply, concentrating margin capture with packagers who secure long-term offtake agreements while tier-two assemblers absorb spot-market volatility.
Pricing Analysis
GaN-enabled premium tiers command substantial markups over silicon-based legacy chargers and emerging solid-state prototypes. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and after-sales bundling intensity. Cost compression in economy wall chargers is intensifying because BIS pre-certified Indian market entrants are flooding Asian retail channels with undifferentiated units. Fleet procurement teams in Germany demonstrate lowest price sensitivity, while Indian consumer electronics retailers operate on thinnest margins.
Supply Chain Analysis
Lithium carbonate, cobalt sulfate, and electrolyte solvents feed from Chilean salares, Congolese mining concessions, and Chinese petrochemical complexes. China, South Korea, and Japan concentrate cathode active material production and cell finishing capacity. Single-source vulnerability runs through Fujian-based BMS semiconductor fabrication. Distribution runs through Rotterdam hub consolidation for European automotive OEM programs and direct Shenzhen-India air freight for BIS certification-window urgency.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GaN wafer fabrication expertise and UN 38.3 thermal runaway testing accreditation represent the scarcest capabilities, separating viable scale players from margin-compressed assemblers dependent on merchant cell supply.
For Market Incumbents: Entrench GaNPrime architecture dominance through backward integration into Taiwanese wafer supply and exclusive roadside assistance fleet contracts with German automotive OEMs. Prioritize EU Battery Regulation digital passport compliance as a switching-cost mechanism against emerging Asian competitors lacking ECHA audit infrastructure.
For New Entrants and Emerging Players: India's BIS certification window before domestic PLI scheme cell capacity matures represents the most penetrable entry point for compliant exporters. Mid-market power-as-a-service leasing contracts with Dutch logistics consortia offer recurring revenue anchoring. Lead with USB-C PD 3.1 exclusivity to bypass proprietary protocol licensing complexity.
For Investors and Strategic Acquirers: Capital is best deployed toward GaN-integrated platform owners with captive financing arms capable of scaling subscription revenue models. Long-term viability hinges on closed-loop lithium recycling partnerships and regional certification pre-positioning. Watch for UN 38.3 laboratory capacity expansion as an inflection signal for new cell formulation launch velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| GaN Wafer Supply Agreement | Taiwanese semiconductor foundries anchor premium charger output capacity for Anker and Samsung tiers. |
| BIS Certification Pre-Positioning | Early IS 16046 registration secures retail shelf priority before Indian domestic cell manufacturing matures. |
| EU Battery Passport Deployment | Blockchain-anchored lifecycle tracking satisfies ECHA audit requirements for German and French premium channels. |
| Power-as-a-Service Launch | Rotterdam and Eindhoven logistics consortia outsource hardware lifecycle management to OEM financing arms. |
| Thermal Runaway Testing Investment | UN 38.3 accredited laboratory capacity alleviates 4-8 month product launch bottlenecks for new cell formulations. |
Research Methodology
Two parallel data streams informed the analysis: structured interviews with portable charging OEM procurement directors, GaN semiconductor foundry operations managers, and Dutch logistics fleet operators; alongside secondary validation through customs trade records, BIS certification registries, and EU ECHA substance restriction updates. Bottom-up cell shipment tallies triangulated against top-down automotive OEM assistance program deployment schedules.
Forecast inputs span product type segmentation across power banks, wall chargers, and V2L bidirectional systems; technology tiering by GaN versus silicon semiconductor architecture; and application splits between consumer electronics, enterprise fleet, and automotive roadside assistance. CAGRs derive from installed base replacement cycles and protocol adoption velocity modeling. Lithium carbonate spot price volatility and EU Battery Regulation compliance cost trajectories feed scenario-weighted projections across the analysis window.
Macroeconomic conditions sit as an overlay; deviation in EV fleet electrification pace and lithium mining concession permitting timelines would shift the trajectory. Cross-checking against IEA electric vehicle outlook benchmarks and EU critical raw materials inventory disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Automotive EV Charging Adapters Market
Electric Vehicle Charging
Global EV Charging Piles Market
Electric Vehicle Charging
US Electric Vehicle Charging Infrastructure Market
Electric Vehicle Charging
Europe EV Charging Stations Market
Electric Vehicle Charging
Micro Mobility Charging Infrastructure Market
Electric Vehicle Charging
EV Charge Management Software Market
Electric Vehicle Charging
Italy Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
EV DC Fast Charger Market
Electric Vehicle Charging
South America Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Bidirectional EV Charger and V2X Grid Integration Test Systems Market
Electric Vehicle Charging
Public EV Charger Market
Electric Vehicle Charging
High Power Charger for Electric Vehicle Market
Electric Vehicle Charging
Germany EV Charging Infrastructure Market
Electric Vehicle Charging
EV Charging System Test and Certification Equipment Market
Electric Vehicle Charging
France Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Wireless Electric Vehicle Charger Market