
 Micro Mobility Charging Infrastructure Market | 2026-2036
Micro Mobility Charging Infrastructure Market Size, Share, and Industry Trends Forecast 2026-2036
Micro Mobility Charging Infrastructure Market Intelligence
Urban fleet procurement channels is reconfiguring how charging hardware reaches end users. Robert Bosch GmbH leverages its automotive supplier relationships to anchor fleet-dedicated station deployments across German cities. SWIFTMILE competes through sidewalk-integrated form factors designed for dense pedestrian corridors. Perch Mobility specializes in software-layer monetization that extends hardware utilization rates for shared micromobility operators.
Micro mobility charging infrastructure encompasses electrical systems engineered to replenish batteries for lightweight electric vehicles, typically operating at power levels below seven kilowatts and incorporating either conductive cable connections or inductive coil transfer mechanisms. The primary commercial purpose centers on sustaining vehicle availability for shared and personally owned fleets operating within constrained urban geographies. Fast chargers currently dominate capital deployment in high-turnover locations such as transit hubs, while wireless chargers represent the fastest-growing installation category as inductive pad technology matures for curbside integration. Solar-powered chargers occupy a niche margin pool where municipal sustainability mandates offset higher upfront equipment costs through operational energy arbitrage.
The EU Green Deal and F-Gas Regulation shape product standards for refrigerant-based thermal management in charging cabinets, while the EPA guides stationary source electrical permitting for US sidewalk installations. India's CEA mandates grid interconnection protocols that affect public station rollout timelines in Delhi and Bengaluru. Stakeholders must monitor how evolving battery chemistry standards influence connector compatibility across e-bike and e-scooter fleets before committing to long-dated infrastructure contracts.
Market Dynamics
The collision of municipal decarbonization mandates with battery-swappable hardware maturation is compressing deployment timelines for sidewalk-integrated charging systems. Fleet operators now prioritize interoperability protocols that span multiple vehicle OEMs, forcing infrastructure providers to abandon proprietary connector architectures.
Growth Catalysts
- Battery-as-a-Service Models:Shared micromobility operators in East Asian megacities are outsourcing capital-intensive battery assets to third-party swap-station networks, accelerating station density without balance-sheet strain.
- EU Green Deal Corridor Mandates:Carbon-neutral urban transport requirements are compelling municipal transit authorities in Copenhagen and Amsterdam to expand dockless e-scooter charging networks through dedicated curb-space allocations.
- Inductive Pad Maturation:Wireless power transfer efficiency gains above ninety percent are eliminating conductive cable maintenance burdens for high-turnover transit hub installations.
Market Restraints
- Lithium-Ion Price Volatility:Raw material cost swings for cobalt and nickel are inflating total cost of ownership calculations for battery-swappable cabinet deployments.
- East Asian Supply Concentration:Inductive coil manufacturing clusters in Shenzhen and Taipei are creating single-source vulnerability for wireless charging pad procurement.
- F-Gas Thermal Management Constraints:The EU F-Gas Regulation is restricting refrigerant-based cooling options for high-power charging cabinets, limiting thermal design flexibility.
Strategic Opportunities
- Indian Grid Interconnection White Space:India's CEA-mandated protocols for public station rollout in Delhi and Bengaluru remain undersupplied relative to projected two-wheeler electrification curves.
- Solar-Energy Arbitrage Niches:Municipal sustainability mandates in German and French cities are offsetting higher upfront equipment costs for photovoltaic-integrated curbside chargers.
- Software-Layer Monetization Convergence:Shared fleet operators are unbundling charging hardware from energy management platforms, creating recurring revenue attachment points for utilization optimization tools.
Industry Challenges
- Interoperability Certification Timelines:Evolving battery chemistry standards are delaying connector compatibility approvals across heterogeneous e-bike and e-scooter fleets.
- Sidewalk Electrical Permitting Complexity:The EPA's stationary source guidelines for US sidewalk installations are extending deployment cycles through multi-jurisdictional approval requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Micro Mobility Charging Infrastructure Market |
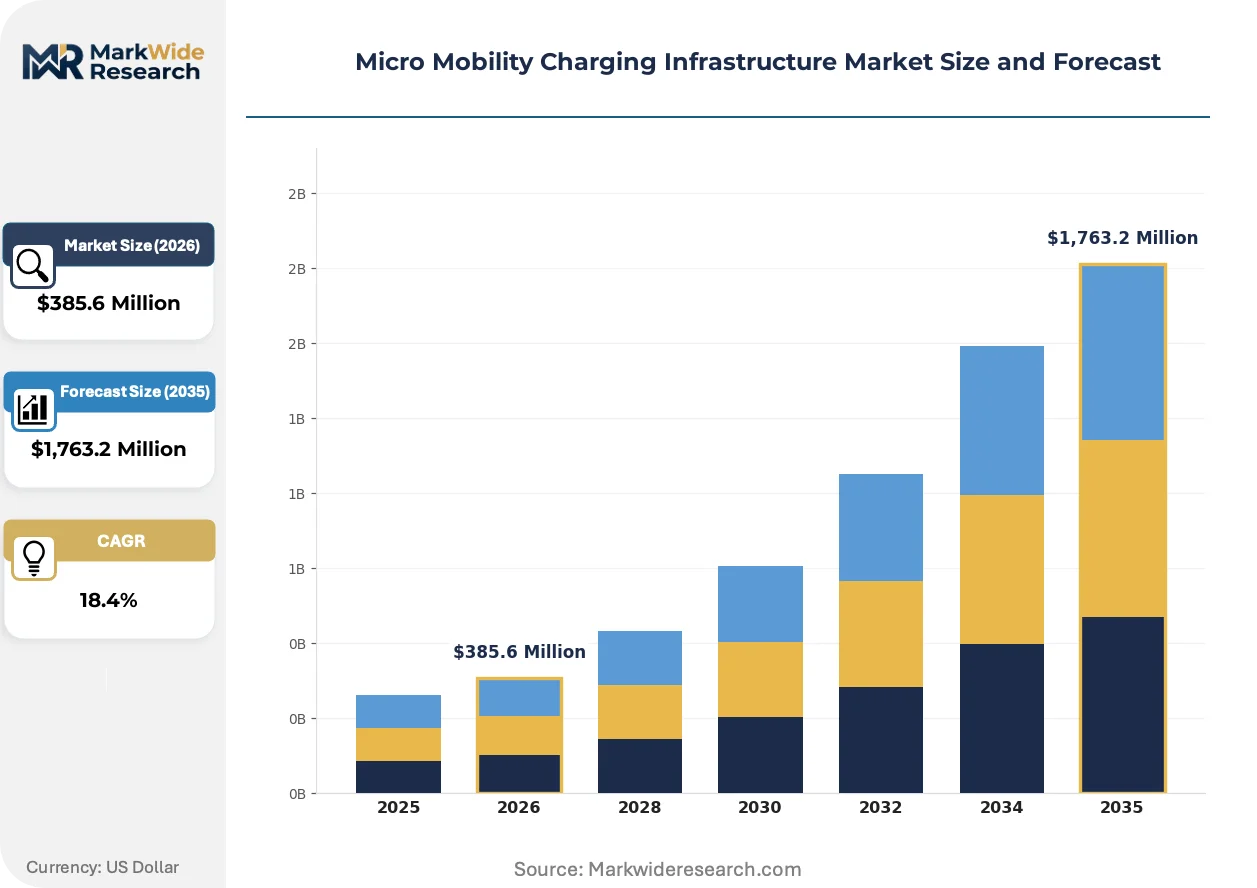
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $1,763.2 Million |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Charging Station Type: Fast Chargers, Level 2 Chargers, Wireless Chargers, Solar-Powered Chargers Vehicle Compatibility: E-Bikes, Electric Scooters, E-Mopeds, Electric Skateboards, E-Rickshaws Installation Model: Public Stations, Private Stations, Fleet-Dedicated Stations, Shared Charging Points End User Segment: Urban Commuters, Delivery Operators, Tour Operators, Campus Residents |
| Companies Covered | Bikeep, SWIFTMILE, Robert Bosch GmbH, Giulio Barbieri SRL, Flower Turbines, Ather Energy, Magment GmbH, Perch Mobility, The Mobility House GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Micro Mobility Charging Infrastructure Market Strategic Shifts & Innovations
Hardware-software decoupling is restructuring how charging infrastructure generates returns. Vendors are repositioning from equipment sales toward energy-service subscriptions, while regulatory pressure on refrigerants and grid interconnection is forcing thermal and power-electronics redesigns.
Inductive wireless charging pads are collapsing the distinction between parking and refueling for dense pedestrian corridors. Fleet operators in Amsterdam and Singapore are deploying coil-embedded sidewalk sections that eliminate cable-handling labor. The technology is collapsing dwell-time constraints that previously limited vehicle turnover at high-utilization hubs.
The EU F-Gas Regulation is prohibiting high-global-warming-potential refrigerants in charging cabinet thermal management systems. Manufacturers are pivoting toward phase-change materials and liquid-cooled architectures to maintain power density compliance. Stationary charging infrastructure in Northern European markets is absorbing the steepest compliance cost increments.
Fleet procurement departments are consolidating vendor relationships around full-service energy contracts rather than capital hardware purchases. Shared micromobility operators in Copenhagen and Berlin are outsourcing charging logistics to infrastructure-as-a-service providers. German municipal transit authorities are pioneering this shift through multi-year availability-guarantee agreements.
Micro Mobility Charging Infrastructure Market Segmentation
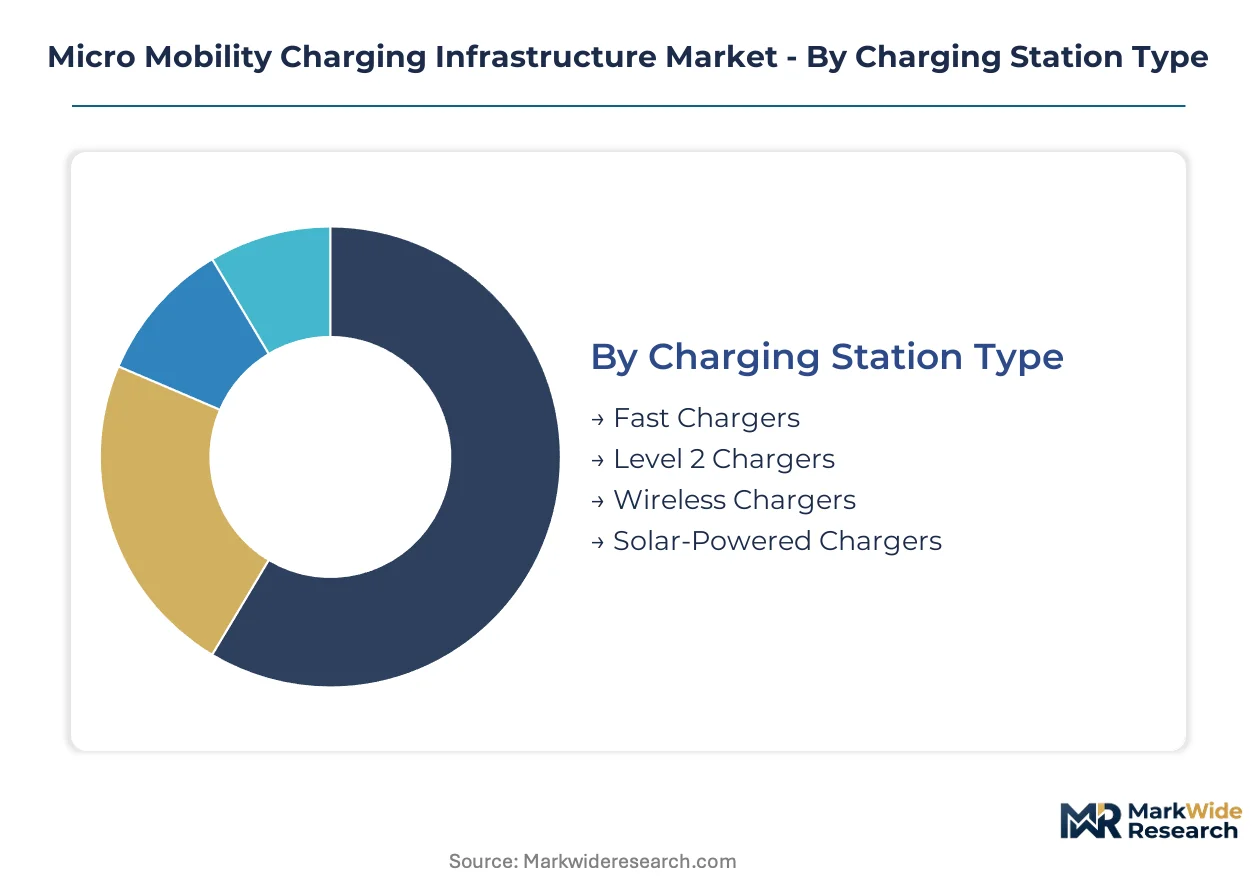
Segmentation in micro mobility charging infrastructure reveals how power delivery specifications, vehicle interface requirements, and deployment ownership models create distinct investment profiles. Infrastructure providers configure hardware specifications and monetization mechanisms differently across each dimension.
Charging Station Type:
Mature conductive technologies dominate installed base economics while emerging wireless systems capture capital deployment momentum.
- Fast Chargers:High-power conductive units operating above three kilowatts enable sub-hour replenishment cycles. Transit hubs in Copenhagen and Amsterdam concentrate procurement for fleet turnover maximization.
- Level 2 Chargers:Standard conductive connections between one and three kilowatts balance equipment cost against dwell-time tolerance. Workplace and residential installations in German cities absorb steady procurement volumes.
- Wireless Chargers:Inductive pad systems embedding coils into sidewalk infrastructure eliminate cable handling. Singapore and Amsterdam pilots validate coil-embedded corridor feasibility.
- Solar-Powered Chargers:Photovoltaic-integrated curbside units offset grid dependency through on-site generation. Municipal sustainability mandates in French and German cities absorb premium equipment costs.
Fast chargers retain volume leadership; wireless chargers hold the steepest expansion curve.
Vehicle Compatibility:
Application intensity varies sharply across vehicle categories, with commercial-use segments demanding higher station density per unit deployed.
- E-Bikes:Battery capacities between 0.3 and 0.7 kilowatt-hours require modest power delivery. European urban commuters in Copenhagen and Amsterdam generate consistent utilization rates at public stations.
- Electric Scooters:Dockless shared fleets dominate infrastructure demand through high-turnover charging requirements. Municipal curb-space allocations in Copenhagen and Amsterdam prioritize scooter-compatible station density.
- E-Mopeds:Higher-capacity batteries between one and three kilowatt-hours extend range for delivery applications. Southeast Asian delivery operators in Vietnamese and Indonesian cities drive swap-station network expansion.
- Electric Skateboards:Portable form factors enable indoor charging, limiting dedicated infrastructure demand. Campus residents in US and European universities represent the primary addressable base.
- E-Rickshaws:Three-wheeled commercial vehicles with four to five kilowatt-hour batteries require specialized high-current connections. Delhi and Bengaluru public station rollouts under CEA protocols target this segment.
Electric scooters command the densest station-to-vehicle ratios; e-rickshaws are climbing fastest on electrification policy support.
Installation Model:
Ownership economics separate capital-heavy municipal deployments from leaner fleet-operator arrangements.
- Public Stations:Municipality-owned curb-side infrastructure serving mixed vehicle types. Copenhagen and Amsterdam transit authorities expand dockless e-scooter charging networks through dedicated allocations.
- Private Stations:Residential or workplace installations serving individual owners. German workplace charging subsidies accelerate corporate campus deployment.
- Fleet-Dedicated Stations:Operator-controlled hubs optimizing vehicle availability. Shared micromobility operators in Copenhagen and Berlin outsource charging logistics to infrastructure-as-a-service providers.
- Shared Charging Points:Multi-tenant access models splitting capital burden across user groups. Apartment complexes in dense European cities pilot subscription-based access.
Fleet-dedicated stations capture capital deployment priority; shared charging points gain share fastest on cost-splitting economics.
End User Segment:
Utilization patterns and willingness-to-pay diverge between discretionary personal mobility and revenue-generating commercial operations.
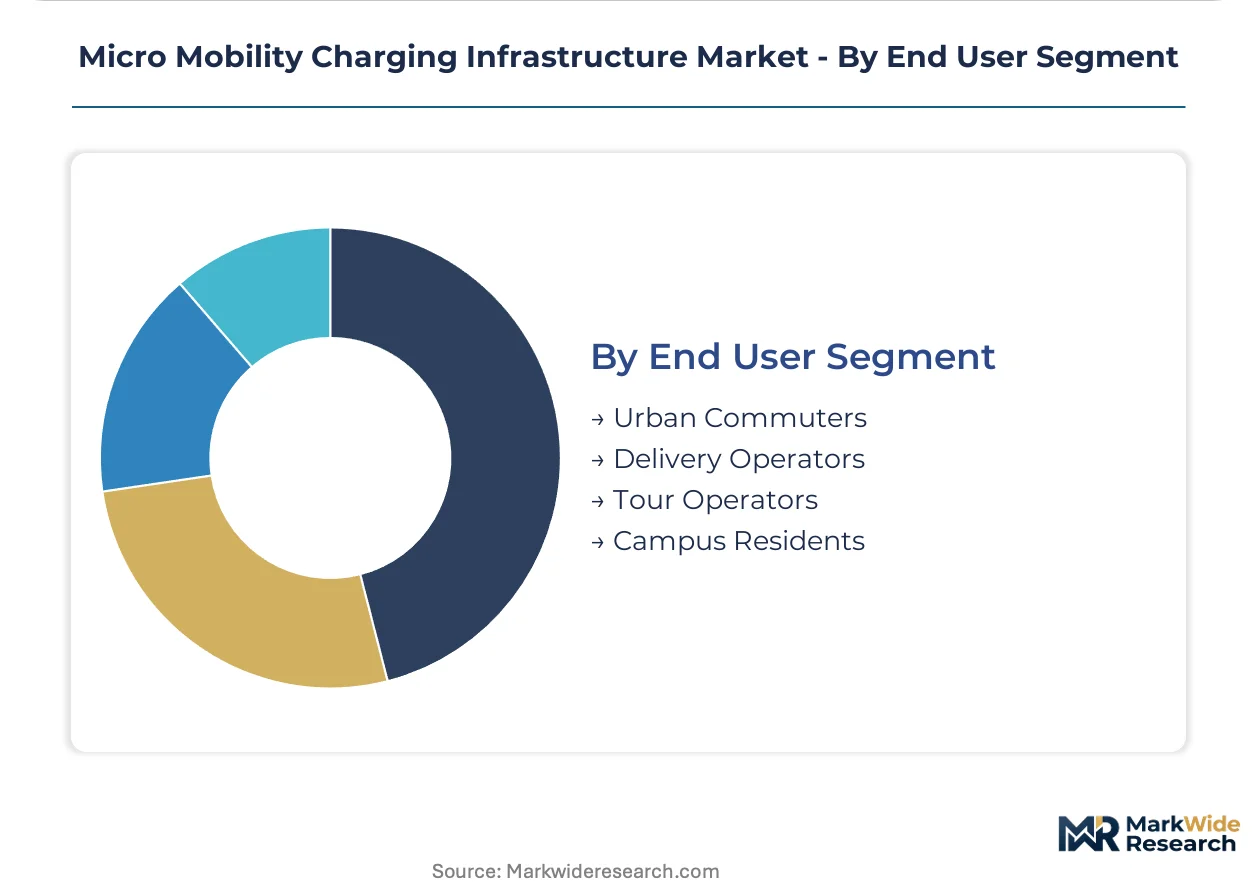
- Urban Commuters:Daily trip regularity enables predictable charging demand. Amsterdam and Copenhagen residents integrate e-scooter charging into multimodal commute patterns.
- Delivery Operators:High-mileage commercial use demands battery-swap infrastructure for minimal downtime. East Asian megacity logistics networks outsource capital-intensive battery assets to third-party swap-station networks.
- Tour Operators:Seasonal demand concentration challenges station utilization economics. European heritage city fleets require flexible contract terms.
- Campus Residents:Captive geographies with controlled parking enable dedicated infrastructure. US university sustainability offices procure solar-integrated charging for student e-bike fleets.
Delivery operators drive swap-station density requirements; urban commuters anchor baseline utilization stability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Urban sidewalk charging corridors in Amsterdam and Copenhagen anchor Europe's deployment density, while Shenzhen's inductive coil manufacturing clusters supply wireless pad hardware worldwide. Grid interconnection protocols in Delhi and Bengaluru underwrite India's public station rollout timelines.
Germany
Fleet-dedicated station deployments absorb the majority of capital allocation through infrastructure-as-a-service contracts. The EU F-Gas Regulation restricts refrigerant-based thermal management in charging cabinets, forcing liquid-cooled redesigns. Robert Bosch GmbH leverages automotive supplier relationships to anchor hardware procurement across Berlin and Munich transit corridors.
Netherlands
Dockless e-scooter charging networks expand through dedicated curb-space allocations in Amsterdam and Rotterdam. EU Green Deal carbon-neutral transport mandates compress municipal procurement timelines. Coil-embedded sidewalk pilots in Amsterdam validate inductive wireless charging feasibility for dense pedestrian zones.
India
E-rickshaw electrification in Delhi and Bengaluru drives demand for high-current public station connections. CEA-mandated grid interconnection protocols extend deployment cycles through technical compliance requirements. Swap-station networks concentrate in Bengaluru's delivery operator corridors to minimize commercial vehicle downtime.
Singapore
Inductive pad installations embed coils directly into sidewalk infrastructure for seamless power transfer. The city-state's land-scarcity constraints prioritize space-efficient charging form factors. Wireless charging pilots along Orchard Road commercial corridors eliminate cable-handling labor for shared fleet operators.
United States
Campus-based solar-integrated charging serves university e-bike fleets in controlled parking geographies. EPA stationary source electrical permitting extends sidewalk installation timelines through multi-jurisdictional approvals. SWIFTMILE competes through sidewalk-integrated form factors designed for dense pedestrian corridors in coastal metropolitan areas.
Micro Mobility Charging Infrastructure Market Key Industry Players
On the supply side, the industry is consolidating around three strategic archetypes: automotive-tier suppliers repurposing manufacturing scale, pure-play charging specialists optimizing form-factor integration, and software-layer monetization platforms extending hardware utilization. Competitive positioning hinges on fleet procurement channel access and interoperability protocol adoption. M&A activity concentrates on energy-management software acquisitions, while geographic expansion targets municipal transit authority relationships.
Among European automotive-tier suppliers, Robert Bosch GmbH and Giulio Barbieri SRL occupy positions leveraging established industrial customer relationships. Within the pure-play charging specialist tier, SWIFTMILE exemplifies sidewalk-integrated hardware design for dense urban deployment. Perch Mobility anchors the software-layer monetization archetype, representing the shift toward utilization optimization platforms unbundled from capital hardware sales.
| Leading Market Players |
|---|
| Bikeep |
| SWIFTMILE |
| Robert Bosch GmbH |
| Giulio Barbieri SRL |
| Flower Turbines |
| Ather Energy |
| Magment GmbH |
| Perch Mobility |
| The Mobility House GmbH |
| Others |
Cost & Logistics Intelligence
Overcapacity in Shenzhen inductive coil manufacturing clusters is compressing margins for wireless charging pad suppliers while simultaneously enabling aggressive pricing postures for fleet-dedicated station deployments. Capacity utilization below break-even thresholds in East Asian component hubs is forcing suppliers to absorb cost compression through volume-discount tiering rather than exit, creating asymmetric pricing power for infrastructure-as-a-service aggregators negotiating multi-year procurement contracts.
Pricing Analysis
Volume-discount tiering structures dominate procurement negotiations between shared micromobility operators and charging hardware vendors. Three-tier pricing structure across premium, standard, and economy levels separates CE-certified cabinet systems with liquid-cooled thermal management from basic conductive units and refurbished swap-station hardware. Price differentiation hinges on interoperability certification density and after-sales service bundling. Cost compression in economy-tier conductive stations is intensifying because East Asian manufacturing overcapacity feeds component spot-market softness. Fleet operators with thousand-unit annual procurement volumes exhibit lowest price sensitivity; municipal transit authorities with single-digit pilot deployments face steepest budget constraints.
Supply Chain Analysis
Export-control regimes limiting power-electronics semiconductor flows to Chinese charging cabinet manufacturers are forcing thermal management redesigns and alternative sourcing strategies. Supply concentrates in China for inductive coils and power modules, South Korea for battery management systems, and Germany for precision thermal components. Raw material dependencies span copper windings, ferrite cores, and refrigerant alternatives under EU F-Gas compliance. Single-source vulnerability in Shenzhen coil manufacturing clusters threatens wireless pad procurement continuity. Distribution runs through automotive-tier supplier networks for fleet-dedicated deployments and direct OEM relationships for municipal sidewalk installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The micro mobility charging infrastructure market is entering a cyclical recovery phase driven by municipal decarbonization mandate acceleration post-pandemic procurement delays. Fleet operator balance-sheet normalization and infrastructure-as-a-service contract standardization are restoring capital deployment velocity.
For Market Incumbents: Pre-empt interoperability standard fragmentation by anchoring connector protocol coalitions before regulatory bodies mandate specifications. Secure backward integration into battery management system firmware to defend margin position against software-layer unbundling threats. Accelerate certification investment for EU F-Gas-compliant thermal architectures to capture Copenhagen and Amsterdam municipal procurement windows.
For New Entrants and Emerging Players: Build out swap-station density in Indian e-rickshaw corridors where CEA grid interconnection protocols have slowed incumbent rollout timelines. Target Bengaluru and Delhi delivery operator networks as the most penetrable commercial segment. Pursue infrastructure-as-a-service contract structures that unbundle hardware capital from energy management subscriptions.
For Investors and Strategic Acquirers: Capital is best deployed toward software-layer monetization platforms with utilization optimization algorithms and recurring revenue attachment rates. Long-term viability across the analysis window favors energy-service subscription models over capital equipment sales. Monitor fleet operator procurement department consolidation around full-service contracts as the inflection signal for hardware-software decoupling maturity.
| Strategic Initiative | Industry Significance |
|---|---|
| Interoperability Protocol Coalition | Robert Bosch GmbH anchors multi-OEM connector standardization across Berlin transit corridors. |
| Battery-as-a-Service Expansion | East Asian megacity logistics networks outsource capital-intensive swap-station assets to third-party networks. |
| F-Gas-Compliant Thermal Redesign | Liquid-cooled architectures maintain power density under EU refrigerant restrictions. |
| Sidewalk-Integrated Form Factor | Coil-embedded corridor pilots in Amsterdam eliminate cable-handling labor costs. |
| Software-Layer Monetization | Perch Mobility extends hardware utilization rates through energy optimization platforms. |
Research Approach
A standing panel of fleet operations directors, municipal transit procurement managers, charging hardware engineering leads, and energy-service contract specialists provided ongoing calibration throughout the analysis window. Primary fieldwork combined structured interviews with shared micromobility operators in Copenhagen, Amsterdam, and Berlin alongside technical discussions with component suppliers in Shenzhen and Taipei. Secondary validation drew from EU Green Deal implementation tracking, CEA grid interconnection protocol filings, EPA stationary source permitting databases, and municipal curb-space allocation records. Bottom-up station deployment counts triangulated against top-down fleet electrification projections.
Scenario-bracketing framed projections across the modeling period through sensitivity analysis of municipal mandate acceleration, battery chemistry standard evolution, and wireless charging efficiency maturation curves. Segmentation dimensions included charging station type, vehicle compatibility tier, installation ownership model, and end-user utilization intensity. CAGRs were derived from logistic diffusion modeling of infrastructure penetration rates against fleet electrification curves, incorporating inductive pad technology maturation timelines and swap-station network density thresholds.
The forecast holds incumbent behavior within observed patterns; aggressive moves by automotive-tier suppliers repurposing manufacturing scale or pure-play software platforms capturing fleet procurement channels would shift outcomes. Material shifts in EU F-Gas thermal compliance costs, lithium-ion raw material price volatility, or India's CEA interconnection protocol revisions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Bidirectional EV Charger and V2X Grid Integration Test Systems Market
Electric Vehicle Charging
Electric Vehicle Charging Adapter Market
Electric Vehicle Charging
EV Charging Software Market
Electric Vehicle Charging
EV Solar Charging Wallbox Market
Electric Vehicle Charging
Electric Vehicle DC Fast Charging Station Market
Electric Vehicle Charging
Engineered Polymers in Electric Charging Infrastructure Market
Electric Vehicle Charging
Europe Electric Vehicle Chargers Market
Electric Vehicle Charging
Wireless Charging Market
Electric Vehicle Charging
Second Life Electric Vehicle Battery Market
Electric Vehicle Charging
Denmark Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Charging As a Service Market
Electric Vehicle Charging
Combined Charging System Market
Electric Vehicle Charging
Home Charging Piles Market
Electric Vehicle Charging
Europe EV Charging Stations Market
Electric Vehicle Charging
High-Thermal-Conductivity Gap-Fill Adhesives for EV Battery Cooling Plates Market
Electric Vehicle Charging
North America Electric Vehicle Charging Equipment Market