
 EV Charging Software Market | 2026-2036
EV Charging Software Market Size, Share, and Industry Trends Forecast 2026-2036
EV Charging Software Market Insights
ISO 15118-2 vehicle-to-grid communication certification is reorganizing competitive access in EV charging software, forcing vendors to prove plug-and-charge interoperability before utility procurement cycles. ChargePoint leverages its integrated hardware-software stack to dominate North American fleet deployments. Driivz anchors European utility contracts through its white-label platform architecture. AMPECO specializes in cloud-native architectures for multi-tenant operator environments.
EV charging software encompasses the middleware, network management, and user-facing applications that coordinate power delivery, session authentication, and tariff settlement across charging infrastructure. The technology relies on OCPP 2.0.1 message protocols and JSON-RPC framing to enable real-time telemetry exchange between charge points and central management systems. Cloud-based solutions now lead deployment preferences among municipal and utility buyers seeking elastic scaling without capital-intensive server farms. Public charging networks represent the fastest-growing deployment segment as highway corridor electrification accelerates across multiple jurisdictions. Residential consumer platforms remain the most mature category, with margin pools shifting toward dynamic load-balancing subscriptions.
The Federal Energy Regulatory Commission's Order 2222 in the US enables distributed energy resource aggregation, directly expanding addressable revenue for software vendors managing bidirectional charging. Europe's Alternative Fuels Infrastructure Regulation mandates payment roaming and data interoperability, forcing platform consolidation among national operators. Stakeholders must monitor how cybersecurity mandates from ISO 15118-20 and national grid codes reshape R&D budgets and partnership requirements.
Market Dynamics
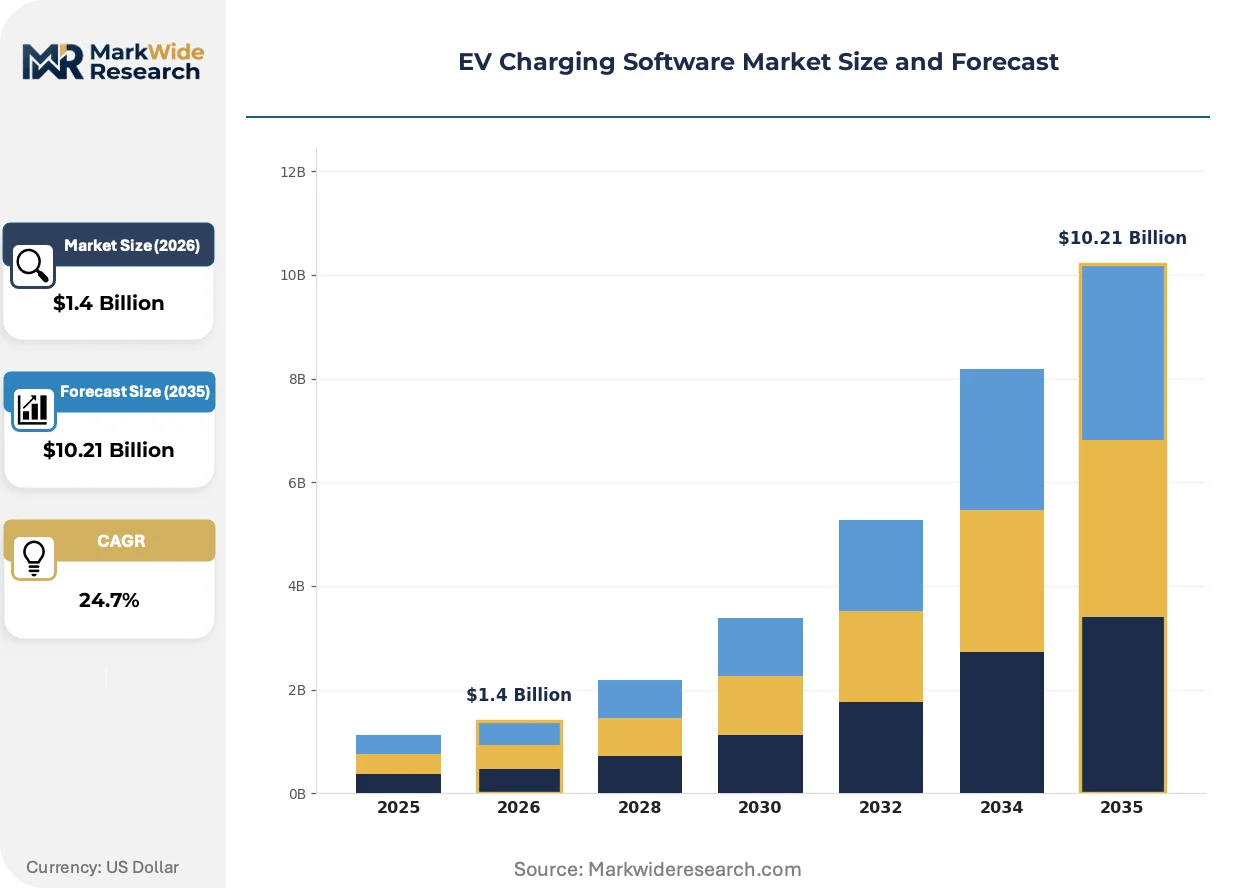
The EV charging software market is experiencing a fundamental restructuring as ISO 15118-2 plug-and-charge certification becomes a mandatory procurement filter for utility-scale deployments, compressing vendor qualification timelines and elevating interoperability testing budgets.
Growth Catalysts
- California Title 24 mandates:New commercial construction in the state must incorporate EV-ready electrical infrastructure, creating baseline demand for charge management platforms before occupancy.
- Fleet electrification:Logistics operators deploying dispersed charging assets require centralized software stacks to coordinate power scheduling across depot and opportunity-charging locations.
- Germany's roaming interoperability:Utility-backed networks mandate standardized software interfaces, forcing platform consolidation that benefits vendors with pre-certified protocol stacks.
Market Restraints
- Silicon supply concentration:Power electronics for charge controllers depend on semiconductor fabrication concentrated in East Asian foundries, exposing deployment timelines to geopolitical friction.
- Cybersecurity certification costs:ISO 15118-20 and national grid code compliance requires dedicated R&D expenditure that squeezes margin for mid-tier software vendors.
- Grid interconnection queues:Utility approval timelines for high-capacity charging installations extend 18-36 months in transmission-constrained regions, delaying software subscription revenue recognition.
Strategic Opportunities
- Bidirectional charging aggregation:FERC Order 2222 enables distributed energy resource participation in wholesale markets, opening revenue streams for software managing vehicle-to-grid dispatch.
- Cloud-native multi-tenancy:Municipal and cooperative utilities seek elastic scaling without capital-intensive server infrastructure, favoring SaaS architectures over on-premise deployments.
- Highway corridor electrification:Federal infrastructure funding accelerates public charging network buildout along interstate corridors, expanding addressable endpoints for network management platforms.
Industry Challenges
- OCPP 2.0.1 migration complexity:Charge point operators maintaining mixed-protocol fleets face integration overhead when upgrading legacy hardware to support JSON-RPC message framing.
- Embedded systems talent scarcity:Firmware engineering for real-time power control competes with broader IoT and automotive sectors, elongating vendor hiring cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EV Charging Software Market |
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $10.21 Billion |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Centralized System, Distributed System, Cloud-Based Solution, On-Premises Solution Deployment: Public Charging, Private Charging, Fleet Charging, Workplace Charging End User: Residential Consumers, Commercial Entities, Municipalities, Utility Providers Technology: Open Charge Point Protocol, OCPP, JSON-RPC, RFID Authentication |
| Companies Covered | ChargePoint, Driivz, AMPECO, GreenFlux, EV Connect, EVBox, ChargeLab, Virta, Etrel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EV Charging Software Market Trends and Innovations
Software architectures for EV charging are diverging along deployment-model lines as buyers prioritize either deep customization or rapid scalability, fragmenting vendor strategies between white-label platforms and integrated hardware-software stacks.
Edge computing for charge point control is fragmenting the traditional cloud-centric architecture. Municipal operators and highway corridor deployers are adopting localized processing to reduce latency for real-time load balancing and maintain session continuity during network outages. This shift compresses addressable market for pure SaaS vendors while creating openings for hybrid deployment specialists.
The Alternative Fuels Infrastructure Regulation in Europe mandates payment roaming and data interoperability across national borders. Platform operators must reconfigure tariff settlement engines and user authentication flows to comply, accelerating consolidation among national charging networks. Germany and the Netherlands are experiencing the most visible restructuring as incumbent utilities absorb independent software providers.
Subscription preferences among fleet operators are pivoting toward dynamic load-balancing services rather than per-session transaction fees. Large logistics buyers negotiate enterprise contracts that bundle energy management, demand charge optimization, and vehicle telemetry integration. This unbundling is most advanced in North American fleet deployments where electricity costs represent a larger share of total cost of ownership.
EV Charging Software Market Segmentation
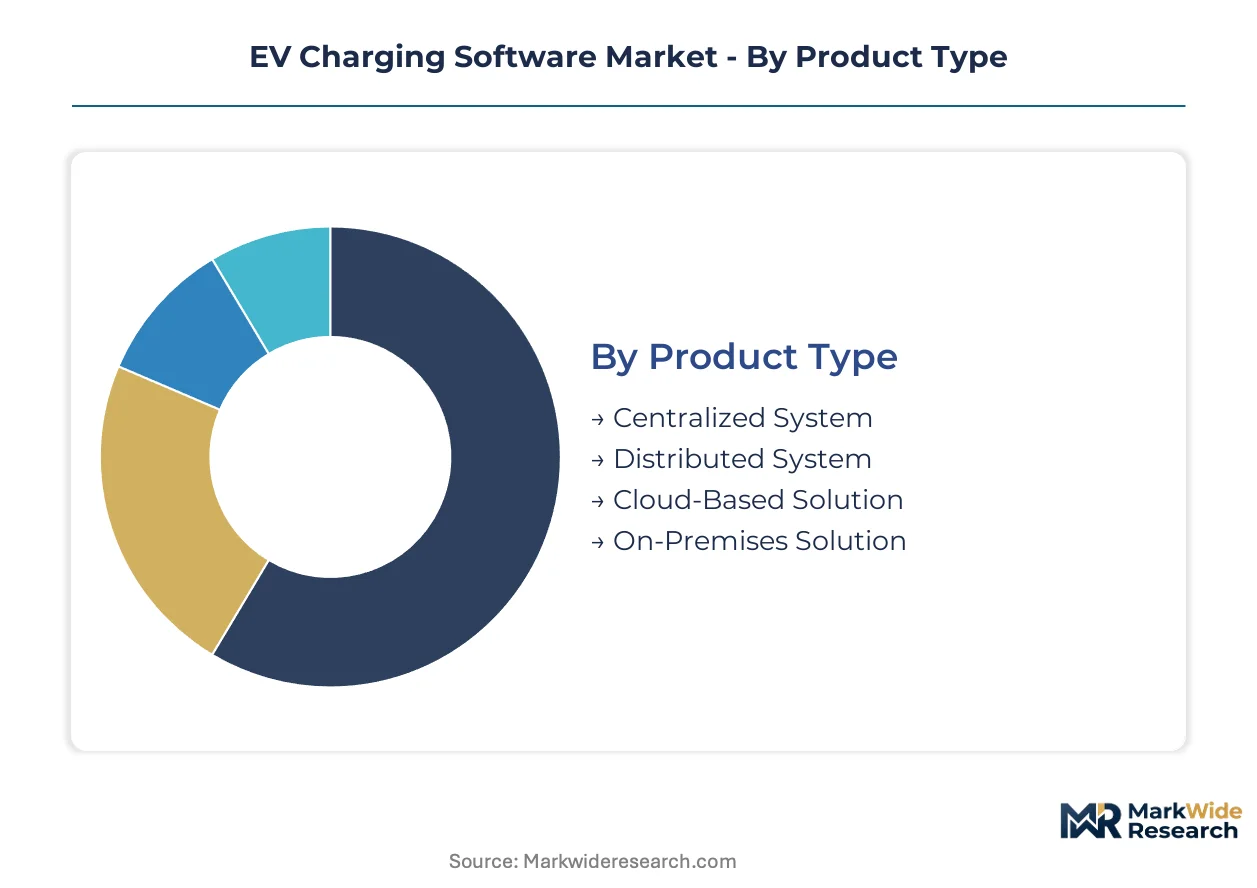
Segmentation in EV charging software reveals how architectural choices determine vendor competitiveness across procurement cycles. Deployment models and protocol standards create distinct margin structures that reshape vendor positioning as interoperability mandates tighten.
Product Type:
Distributed systems face intensifying substitution pressure from cloud-native alternatives as municipal buyers prioritize elastic scaling over capital-intensive server infrastructure.
- Centralized System:Single-tenant architecture consolidating charge point control through dedicated server clusters. Utility providers in Germany specify these for high-availability grid integration where latency tolerance is minimal.
- Distributed System:Federated control nodes processing telemetry at regional hubs. Fleet operators across North America deploy these to maintain session continuity during WAN outages across dispersed depot locations.
- Cloud-Based Solution:Multi-tenant SaaS platforms with API-first integration. Cooperatives favor these for zero upfront infrastructure spend.
- On-Premises Solution:Air-gapped deployments for cybersecurity-critical installations. Defense and critical infrastructure buyers mandate these despite higher TCO.
Cloud-based solutions anchor the volume base while distributed systems gain share at the steepest rate.
Deployment:
Cost tier stratification separates enterprise fleet contracts from transactional public charging, with pricing power concentrating in integrated energy management bundles.
- Public Charging:Highway corridor and urban fast-charging networks requiring 24/7 uptime guarantees. Federal infrastructure funding in the US accelerates endpoint expansion along interstate routes.
- Fleet Charging:Depot and opportunity-charging coordination for logistics operators. Dynamic load-balancing subscriptions displace per-session fees as the dominant revenue model here.
- Private Charging:Single-tenant installations for commercial property owners. California Title 24 mandates embed these in new construction before occupancy.
- Workplace Charging:Employer-sponsored installations with employee authentication. Tax incentive structures in multiple jurisdictions drive employer adoption.
Fleet charging commands the highest contract values while public charging expands endpoint count most aggressively.
End User:
Application maturity varies sharply, with residential platforms commoditizing as utility and municipal segments demand specialized grid-integration capabilities.
- Utility Providers:Grid-edge orchestration platforms managing bidirectional dispatch. FERC Order 2222 enables wholesale market participation revenue streams here.
- Commercial Entities:Retail and workplace installations prioritizing customer dwell-time optimization. Property managers bundle charging with parking revenue systems.
- Municipalities:Public infrastructure with open-network interoperability mandates. European AFIR regulation forces payment roaming compliance.
- Residential Consumers:Home energy management with solar and storage integration. Margin pools shift toward dynamic rate optimization subscriptions.
Utility providers drive the steepest R&D investment while residential consumers represent the largest installed base.
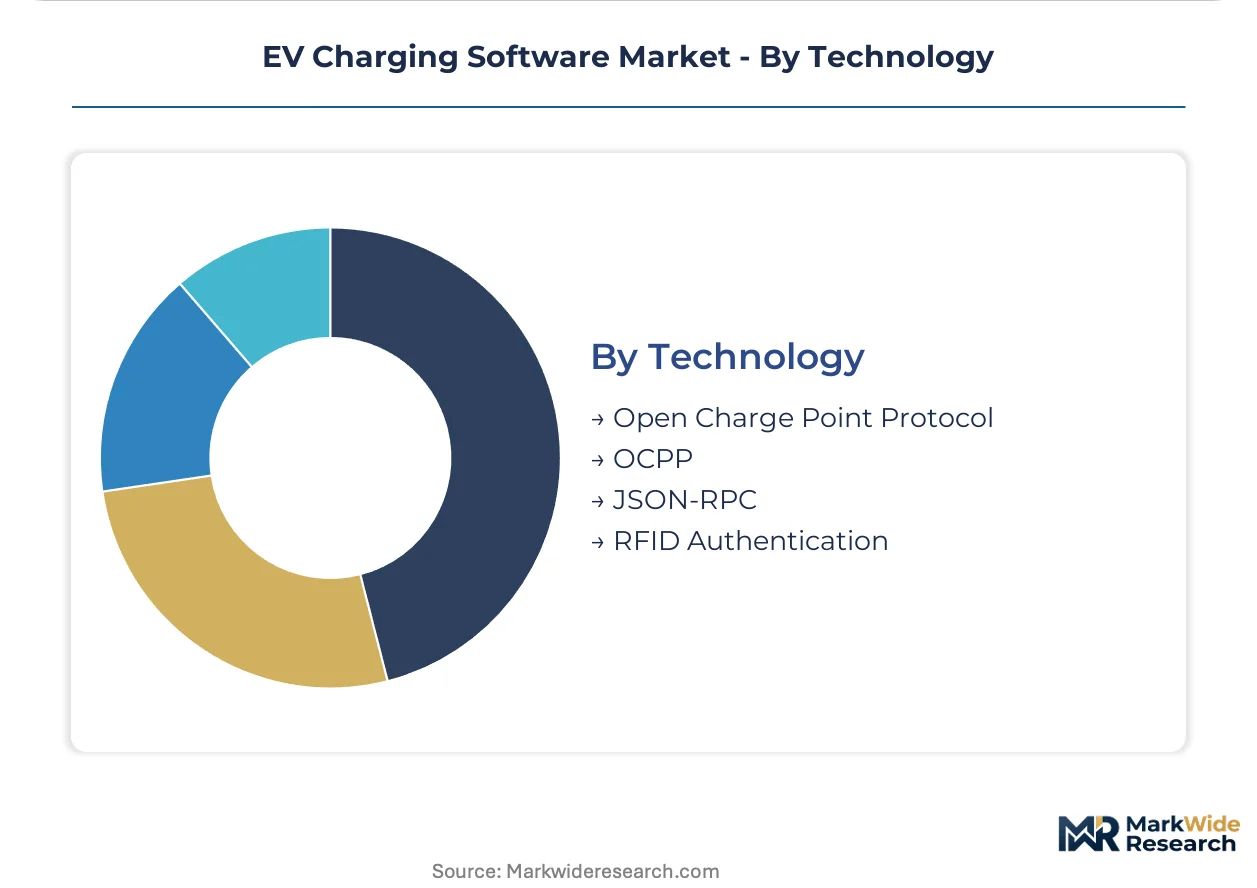
Technology:
Protocol certification hierarchies are consolidating vendor access, with ISO 15118-2 compliance becoming a non-negotiable procurement filter.
- OCPP:Dominant open protocol for charge point-to-central system communication. Version 2.0.1 with JSON-RPC framing is mandatory for new utility tenders.
- Open Charge Point Protocol:Legacy 1.6J installations requiring migration investment. Mixed-fleet operators face integration overhead during upgrades.
- JSON-RPC:Message framing standard enabling real-time telemetry exchange. Embedded systems talent scarcity elongates vendor implementation timelines.
- RFID Authentication:Card-based user verification for closed-network deployments. Roaming interoperability mandates in Europe displace this for open networks.
OCPP anchors current procurement specifications while ISO 15118-2 plug-and-charge protocols capture the steepest certification investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal and state-level mandates across multiple jurisdictions are accelerating software procurement timelines as utilities and fleet operators modernize charging infrastructure. California's Title 24 building code and Germany's roaming interoperability requirements exemplify how regulation is compressing vendor qualification windows. Procurement concentrates in markets where grid-edge orchestration capabilities align with wholesale market participation rules.
United States
FERC Order 2222 enables distributed energy resource aggregation, expanding revenue potential for bidirectional charging management platforms. The Federal Highway Administration's National Electric Vehicle Infrastructure program funds highway corridor buildouts requiring 24/7 network uptime guarantees. Fleet electrification clusters in California's Central Valley and Texas's Dallas-Fort Worth metroplex are driving enterprise software contract values upward.
Germany
Utility-backed roaming networks mandate ISO 15118-2 certified software stacks, forcing platform consolidation among national operators. The Alternative Fuels Infrastructure Regulation requires payment roaming and data interoperability across borders. Munich and Stuttgart automotive clusters are absorbing independent software providers into captive utility platforms to meet certification deadlines.
China
MIIT's national standards for vehicle-to-grid communication are harmonizing with ISO protocols to enable export-oriented vendor certification. State Grid Corporation's massive charging network deployment creates demand for centralized management systems at provincial scale. Shenzhen and Shanghai municipal operators are piloting edge-computing architectures to reduce latency for real-time load balancing.
United Kingdom
Ofgem's regulatory framework for electric vehicle smart charging mandates cybersecurity standards that elevate R&D expenditure for market entry. The government's Rapid Charging Fund accelerates highway corridor deployment along the Strategic Road Network. London's Ultra Low Emission Zone expansion is embedding charge management software into commercial property development pipelines.
Netherlands
AFIR implementation is forcing national charging networks to reconfigure tariff settlement engines for cross-border interoperability. The country's dense charging infrastructure per capita creates demand for multi-tenant SaaS platforms among municipal operators. The Eindhoven-Brabant technology corridor hosts software vendors specializing in cloud-native architectures for cooperative utilities.
EV Charging Software Market Competitive Landscape
Player mix skews toward integrated hardware-software stacks and white-label platform specialists. The vendor base concentrates around three strategic archetypes: vertically integrated infrastructure providers, utility-focused white-label platforms, and cloud-native multi-tenant specialists. Consolidation pressure intensifies as ISO 15118-2 certification becomes a non-negotiable procurement filter. Dominant competitive moves include strategic partnerships for protocol certification and geographic expansion through utility channel relationships.
Within the integrated infrastructure tier, ChargePoint occupies a position exemplifying hardware-software convergence for fleet deployments. Driivz and AMPECO represent contrasting archetypes in the platform specialization segment, with the former anchoring European utility contracts and the latter occupying a position in cloud-native multi-tenant environments. These three companies illustrate how certification timelines and procurement channel access are restructuring competitive access across regional markets.
| Leading Market Players |
|---|
| ChargePoint |
| Driivz |
| AMPECO |
| GreenFlux |
| EV Connect |
| EVBox |
| ChargeLab |
| Virta |
| Etrel |
| Others |
Pricing and Supply Chain Analysis
Eighteen-to-thirty-six-month grid interconnection queues compress vendor cash conversion cycles while elevating working capital requirements, concentrating pricing power among software providers with pre-certified protocol stacks and utility channel relationships. This lead-time band forces buyers to lock multi-year subscriptions early, creating tiered contract value dispersion across certification-holding and non-certified vendors.
Pricing Analysis
Certification level creates the primary spread between ISO 15118-2 compliant and legacy protocol vendors, with three-tier pricing structure across premium plug-and-charge, standard OCPP 2.0.1, and economy RFID-authentication tiers. Cloud-native SaaS platforms command subscription premiums over on-premise deployments due to elastic scaling guarantees. Cost compression in the economy tier intensifies because embedded systems talent scarcity elongates implementation timelines for mid-tier vendors. Municipal utilities exhibit highest price sensitivity due to procurement committee oversight, while enterprise fleet operators prioritize dynamic load-balancing capabilities over per-session cost.
Supply Chain Analysis
Forty-five-to-ninety-day firmware integration cycles constrain vendor deployment velocity, with semiconductor fabrication for power controllers drawing from Taiwan, South Korea, and China. Cloud infrastructure services rest on hyperscaler data centers concentrated in the United States, Germany, and China. Single-source vulnerability in automotive-grade microcontroller supply creates qualification risk for charge point hardware-software bundles. Distribution runs through utility procurement channels and direct fleet operator sales teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EV charging software market sits in early-cycle expansion as FERC Order 2222 and Europe's AFIR regulation accelerate procurement timelines for grid-edge orchestration platforms. Fleet electrification mandates across North America and Germany's roaming interoperability requirements create sustained tailwinds for certified vendors.
For Market Incumbents: Fortify protocol certification moats through accelerated ISO 15118-20 compliance investment ahead of national grid code deadlines. Deepen backward integration into edge-computing hardware to capture hybrid deployment opportunities as municipal buyers prioritize latency reduction. Defend against cloud-native entrants by embedding dynamic load-balancing algorithms into long-term fleet operator contracts. For New Entrants and Emerging Players: Lead with white-label platform specialization targeting cooperative utilities in the Netherlands and United Kingdom seeking zero-upfront SaaS architectures. Municipal operators in transmission-constrained regions represent the most penetrable segment due to extended grid interconnection timelines delaying incumbent deployments. Pursue channel partnerships with European energy retailers requiring rapid AFIR compliance. For Investors and Strategic Acquirers: Long-term, this sits as a grid-edge infrastructure play because vehicle-to-grid aggregation revenue streams under FERC Order 2222 expand addressable market beyond software licensing into energy trading participation. Target acquisition archetypes include ISO 15118-2 certified vendors with utility channel density in Germany or cloud-native multi-tenant specialists serving North American fleet operators. Monitor OCPP 2.0.1 migration completion rates across mixed-fleet operators as inflection indicator for consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 15118-2 Certification Investment | Unlocks utility procurement cycles in Germany and qualifies vendors for roaming network mandates under AFIR. |
| Edge-Computing Hardware Development | Reduces latency for real-time load balancing in highway corridor deployments across California and Texas. |
| Cloud-Native Multi-Tenancy Expansion | Captures cooperative utility demand in the Netherlands seeking elastic scaling without server infrastructure. |
| Fleet Operator Channel Partnerships | Secures enterprise contracts bundling energy management with demand charge optimization in logistics clusters. |
| Bidirectional Charging Platform Integration | Enables wholesale market participation revenue under FERC Order 2222 for utility provider customers. |
Research Methodology
Desk research of regulatory filings from FERC and Ofgem, hyperscaler capex disclosures, and charge point operator deployment databases preceded structured interviews with utility planning officers, fleet electrification managers, software platform engineers, and municipal procurement leads. Primary fieldwork combined with secondary validation across SEC filings, EIA grid interconnection data, and IEA EV policy tracking enabled bottom-up endpoint counting and top-down market sizing triangulation.
Variance decomposition across deployment model, end-user segment, protocol certification tier, and regional regulatory framework shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level endpoint expansion rates and average revenue per user trajectories, with cloud adoption curves and ISO 15118-2 certification timelines as key industry-specific forecast inputs.
Underlying assumptions cover sustained federal infrastructure funding, semiconductor supply normalization, and grid interconnection queue stability, with deviation risk concentrated in cybersecurity mandate acceleration and geopolitical friction affecting East Asian foundry output. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Stationary Electric Vehicle Charging Gun Market
Electric Vehicle Charging
Bidirectional EV Charger and V2X Grid Integration Test Systems Market
Electric Vehicle Charging
Copper in Electric Vehicle Market
Electric Vehicle Charging
EV Charge Management Software Market
Electric Vehicle Charging
APAC Electric Vehicle Charging Station Market
Electric Vehicle Charging
Second Life Electric Vehicle Battery Market
Electric Vehicle Charging
Germany Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Wireless Charging Market
Electric Vehicle Charging
North America Wireless Charging Market
Electric Vehicle Charging
Norway Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Charging As a Service Market
Electric Vehicle Charging
Global EV Charger Market
Electric Vehicle Charging
Pantograph Charger Market
Electric Vehicle Charging
Home EV Chargers Market
Electric Vehicle Charging
EV Charging Point Market
Electric Vehicle Charging
Electric Vehicle Charging Plugs Market