
 North America Drilling Completion Fluids Market | 2026-2036
North America Drilling Completion Fluids Market Size, Share, and Industry Trends Forecast 2026-2036
North America Drilling Completion Fluids Market Insights
Asset-light leasing frameworks for drilling fluid supply and recycling infrastructure is reconfiguring capital deployment across the competitive landscape. Schlumberger leverages integrated service contracts to anchor offshore project economics in the Gulf of Mexico. Halliburton sustains R&D intensity in high-pressure well chemistries, while Baker Hughes competes through geographic dominance in Canadian oil sands operations.
Drilling completion fluids are engineered liquid and slurry systems formulated with weighting agents, viscosifiers, and emulsifiers to maintain hydrostatic pressure, transport cuttings, and stabilize wellbore walls during drilling and completion operations. Water-based fluids dominate onshore applications due to lower disposal costs and simpler regulatory compliance, though synthetic fluids command premium positioning in high-temperature horizontal drilling where thermal stability exceeds 300°F. Oil-based fluids retain share in reactive shale formations where inhibition properties prevent wellbore collapse, while foam fluids address underbalanced drilling in depleted reservoirs across the Appalachian Basin.
EPA effluent limitation guidelines and OSHA workplace exposure standards constrain formulation chemistry and disposal pathways for service providers and operators. Texas Railroad Commission and New Mexico Oil Conservation Division field rules further dictate fluid reporting and pit closure timelines. Stakeholders must monitor evolving state-level groundwater protection mandates and assess captive recycling investments against third-party logistics costs.
Market Dynamics
Horizontal well complexity in the Permian Basin and Appalachian shale plays is forcing fluid systems to manage longer laterals and higher bottom-hole temperatures, compressing formulation tolerance windows while EPA discharge rules tighten water reuse mandates.
Growth Catalysts
- EPA Effluent Limitation Guidelines:Stricter discharge standards for drilling waste are accelerating closed-loop fluid recycling investments across Texas and New Mexico field operations.
- Extended-reach horizontal drilling:Lateral lengths exceeding 15,000 feet in the Delaware Basin demand synthetic fluid thermal stability above 300°F, expanding premium formulation consumption.
- Water scarcity protocols:Texas Railroad Commission groundwater protection mandates are driving operator adoption of brine-based and produced-water fluid systems to reduce freshwater withdrawal.
Market Restraints
- Barite supply concentration:Weighting agent sourcing depends heavily on Chinese export quotas and shipping lane congestion, creating input cost volatility for fluid density management.
- Synthetic base fluid cost structure:Alpha-olefin and internal olefin feedstock prices track crude oil and natural gas liquids, compressing margin predictability for high-performance systems.
- Technical limitation in ultra-HPHT wells:Current emulsion stability breaks down above 400°F and 25,000 psi, restricting synthetic fluid deployment in deep Gulf of Mexico pre-salt targets.
Strategic Opportunities
- Canadian oil sands thermal operations:Steam-assisted gravity drainage projects in Alberta require specialized high-temperature completion fluids with minimal formation damage, an underpenetrated application segment.
- OSHA silica exposure standards:Tighter workplace crystalline silica limits are creating regulatory tailwinds for liquid additive delivery systems that eliminate dry powder handling.
- Real-time fluid monitoring:Integration of downhole sensors with automated mud property adjustment is collapsing response time for weight and viscosity management in extended-reach wells.
Industry Challenges
- Specialized mud engineering talent:The retirement wave of experienced drilling fluid chemists is outpacing university petroleum engineering program output, creating formulation expertise gaps.
- Multi-state compliance complexity:Operators working across Texas, New Mexico, and Colorado must navigate divergent pit closure timelines and fluid reporting formats, extending permitting cycles.
- Legacy water treatment infrastructure:Third-party recycling facilities in the Permian lack capacity for high-salinity produced water blending, forcing operators into costly transportation logistics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Drilling Completion Fluids Market |
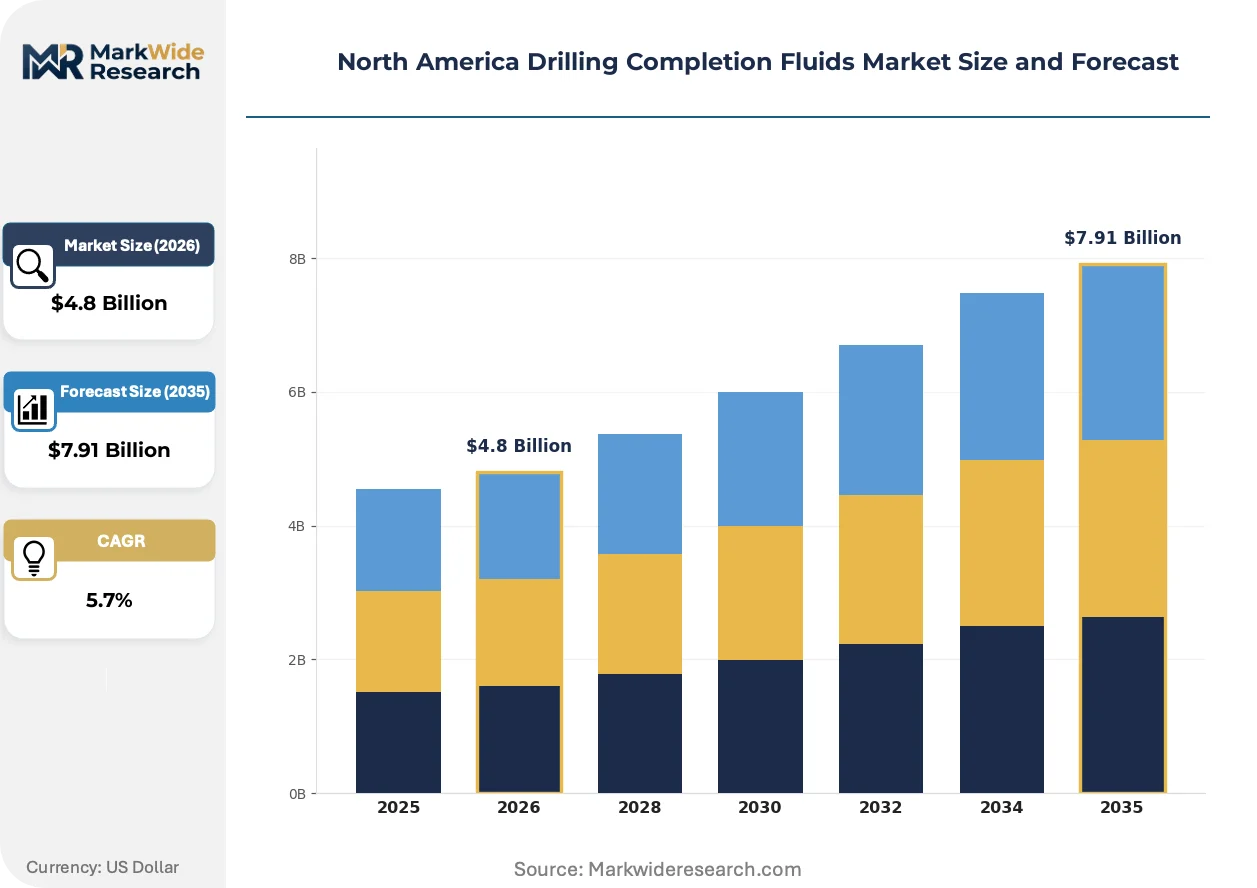
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Based Fluids, Oil-Based Fluids, Synthetic Fluids, Foam Fluids Application: Onshore Wells, Offshore Wells, High-Pressure Wells, Horizontal Drilling End User: Oil & Gas Companies, Service Providers, Contractors, Independent Operators Distribution Channel: Direct Sales, Distributors, Online Platforms, Retailers |
| Companies Covered | Schlumberger, Halliburton, Baker Hughes, CES Energy Solutions, Newpark Resources, Tetra Technologies, National Oilwell Varco, Weatherford International, Anchor Drilling Fluids USA, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Drilling Completion Fluids Market Trends and Innovations
Digital automation and chemistry convergence are compressing the traditional service model, shifting value capture from bulk fluid supply to precision performance guarantees tied to drilling efficiency metrics.
Nano-engineered weighting agents are collapsing the density-to-viscosity tradeoff that has constrained high-performance water-based fluid design for decades. Operators in the Midland Basin sub-basins are piloting these materials at commercial scale. The technology is collapsing the historical performance gap between water-based and synthetic systems in reactive shale intervals.
EPA's pending effluent limitation guideline revisions for oil and gas extraction are mandating zero-discharge thresholds for certain synthetic fluid components in coastal watersheds. This industrial consequence is accelerating bio-based ester chemistry R&D. Gulf of Mexico offshore contractors are most affected, responding with pre-emptive formulation registration submissions to secure drilling permits.
Integrated service contracts now bundle fluid supply with real-time performance guarantees rather than volume-based pricing. Independent operators in the STACK and SCOOP plays are driving this shift, replacing traditional day-rate mud engineering with outcome-based fee structures tied to rate-of-penetration targets. Oklahoma and North Dakota land drilling markets exhibit the fastest contract model conversion.
North America Drilling Completion Fluids Market Segmentation
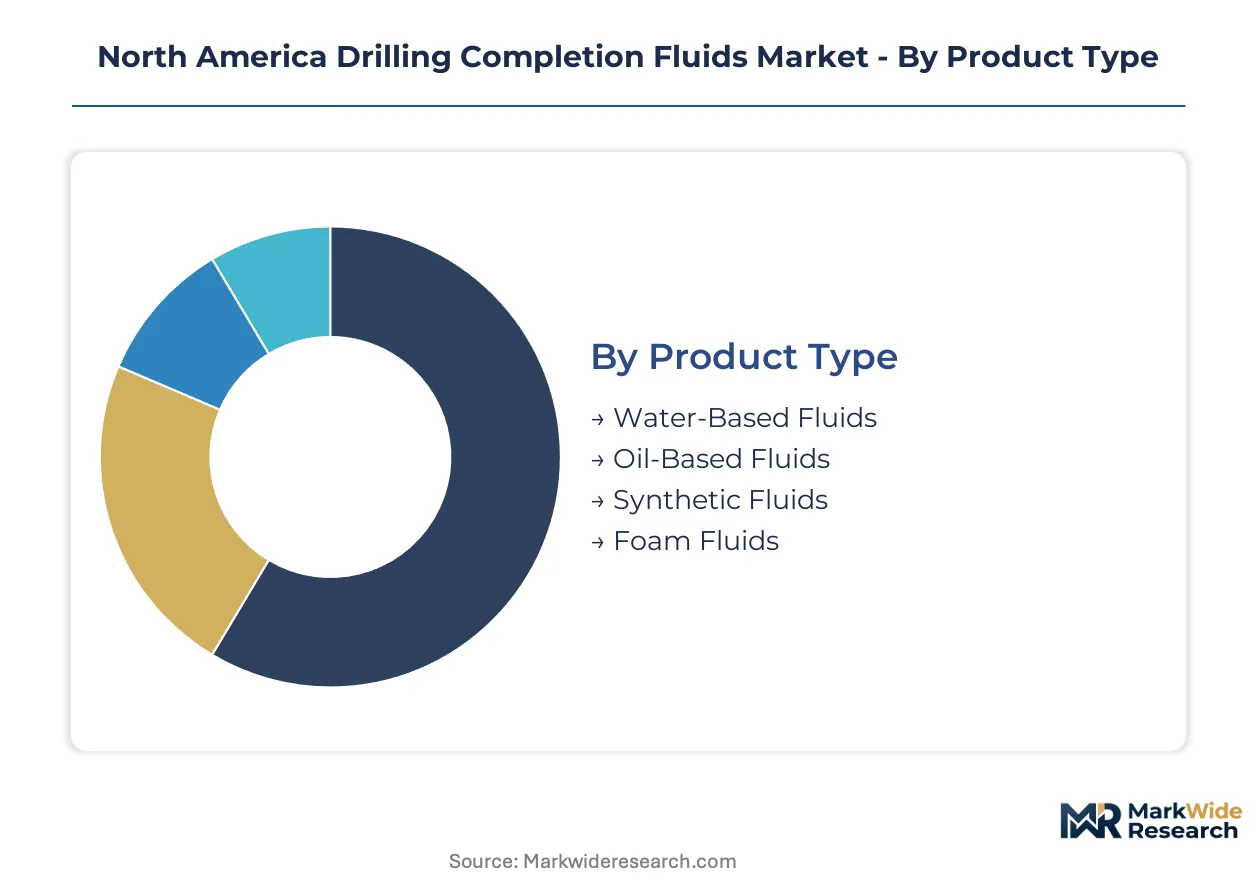
Drilling completion fluid selection hinges on formation reactivity, thermal stress, and disposal economics. Each segmentation dimension reveals distinct procurement patterns across Permian Basin operators and Gulf of Mexico contractors.
Product Type:
Cost tier differentiation separates commodity formulations from premium synthetic systems engineered for extreme downhole conditions.
- Water-Based Fluids:Bentonite clay and polymer suspensions dominate onshore Texas and New Mexico operations where EPA discharge compliance favors lower-toxicity waste streams. Delaware Basin independent operators specify these systems for vertical and shallow horizontal wells under 10,000 feet measured depth.
- Oil-Based Fluids:Diesel or mineral oil continuous-phase systems deliver superior shale inhibition in reactive formations where wellbore stability failures risk sidetrack costs. Operators in the Eagle Ford and Anadarko basins deploy these fluids despite higher disposal fees and stricter Texas Railroad Commission pit closure requirements.
- Synthetic Fluids:Internal olefin and ester base fluids command premium positioning in extended-reach laterals exceeding 15,000 feet.
- Foam Fluids:Nitrogen or air-liquid mixtures address underbalanced drilling in depleted Appalachian Basin reservoirs.
Water-based fluids command the established base. The steepest expansion runs through synthetic systems.
Application:
Well architecture and pressure regime dictate formulation specifications and service intensity.
- Onshore Wells:Vertical and directional drilling in Texas, New Mexico, and North Dakota consumes the majority of water-based and synthetic fluid volume. Pad drilling efficiencies and batch completion programs concentrate fluid demand around Midland Basin and Delaware Basin infrastructure clusters.
- Horizontal Drilling:Extended-reach laterals in the Permian and Appalachian basins impose thermal stability and lubricity demands that compress formulation tolerance windows. Synthetic fluid consumption per well runs multiples higher than vertical equivalents.
- Offshore Wells:Gulf of Mexico shelf and deepwater projects require synthetic and oil-based systems with zero-discharge compatibility.
- High-Pressure Wells:HPHT pre-salt targets in federal Gulf waters test emulsion stability above 400°F and 25,000 psi.
Onshore applications anchor volume throughput. Horizontal drilling is gaining share fastest.
End User:
Customer type determines contract structure, technical support requirements, and inventory positioning.
- Oil & Gas Companies:Supermajors and large independents in the Permian Basin negotiate integrated service contracts bundling fluid supply with real-time performance guarantees tied to rate-of-penetration targets.
- Independent Operators:STACK and SCOOP play producers in Oklahoma drive adoption of outcome-based fee structures replacing traditional day-rate mud engineering.
- Service Providers:Schlumberger, Halliburton, and Baker Hughes maintain captive fluid formulation and recycling infrastructure.
- Contractors:Regional drilling contractors in North Dakota and Colorado source fluids through distributor networks with limited technical customization.
Oil and gas companies command the established base. Independent operators are expanding procurement fastest.
Distribution Channel:
Supply chain configuration reflects customer scale, geographic concentration, and formulation complexity.
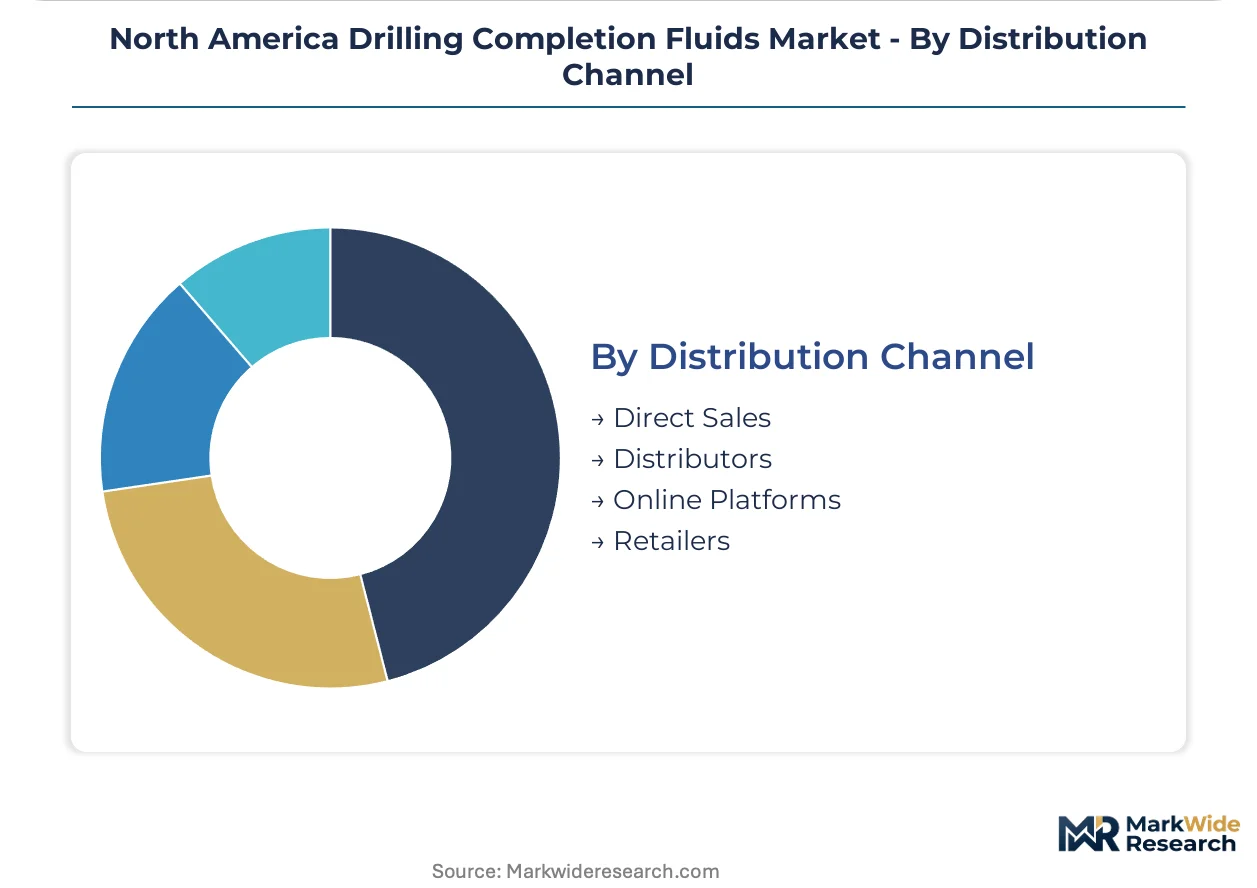
- Direct Sales:Integrated service providers and major operators in Texas and New Mexico maintain dedicated supply agreements with formulation plants positioned near Midland and Hobbs logistics hubs.
- Distributors:Regional fluid distributors serve Oklahoma and North Dakota land drilling markets with standardized water-based systems and additive packages.
- Online Platforms:Digital procurement portals are emerging for commodity additives and weighting agents in Canadian oil sands operations.
- Retailers:Limited presence for drilling completion fluids; confined to specialty chemical components and replacement additives.
Direct sales command the established base. Distributor networks are expanding fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
North America runs a structural surplus in drilling completion fluids, with formulation plants concentrated in Texas and Louisiana exporting to Canadian oil sands and Mexican offshore markets. The region imports specialty barite weighting agents under Chinese export quota constraints.
United States
Permian Basin operators in Texas and New Mexico consume the majority of synthetic and water-based fluid volume for extended-reach laterals exceeding 15,000 feet. EPA effluent limitation guidelines mandate closed-loop recycling systems in coastal watersheds, compressing disposal economics. Midland and Odessa anchor the continent's densest fluid logistics cluster, with batch plants positioned within 50 miles of active rig counts.
Canada
Alberta's steam-assisted gravity drainage projects demand high-temperature completion fluids with minimal formation damage characteristics. Health Canada and provincial regulators enforce stricter groundwater protection protocols than US counterparts, favoring brine-based formulations. Calgary and Edmonton host the primary distribution nodes serving both oil sands thermal operations and Saskatchewan conventional drilling.
Mexico
Energy reform implementation has opened offshore Gulf blocks to private operators, importing synthetic fluid expertise from US service providers. The national oil conservation regulator maintains fluid reporting requirements aligned with international best practices. Ciudad del Carmen and Tampico function as the primary supply points for deepwater exploration campaigns in the southern Gulf.
North America Drilling Completion Fluids Market Competitive Landscape
On the supply side, the industry is consolidated around integrated oilfield service providers with captive formulation and recycling infrastructure. Three strategic archetypes dominate: full-service multinationals bundling fluid supply with real-time performance guarantees; regional specialists concentrating on specific basin chemistries; and asset-light distributors serving commodity water-based formulations. Competitive intensity centers on integrated service contract capture and captive recycling network expansion.
Within the integrated service tier, Schlumberger, Halliburton, and Baker Hughes occupy positions defined by geographic and technological specialization rather than pure scale differentiation. Schlumberger anchors Gulf of Mexico offshore economics through bundled project contracts. Halliburton exemplifies sustained R&D intensity in high-pressure well chemistries. Baker Hughes represents geographic dominance in Canadian oil sands thermal operations.
| Leading Market Players |
|---|
| Schlumberger |
| Halliburton |
| Baker Hughes |
| CES Energy Solutions |
| Newpark Resources |
| Tetra Technologies |
| National Oilwell Varco |
| Weatherford International |
| Anchor Drilling Fluids USA |
| Others |
Pricing and Supply Chain Analysis
Midland Basin formulation plant utilization running at 82% is compressing spot pricing flexibility while pushing integrated service providers toward longer-term offtake commitments. This capacity tightness simultaneously elevates supplier bargaining power and accelerates operator migration to bundled performance contracts that internalize price volatility.
Pricing Analysis
Industrial OEM buyers anchor contract structures around volume-scaled base fluid supply with performance-linked incentive clauses. Three-tier pricing separates synthetic premium formulations from standard water-based systems and economy brine blends, with thermal stability certification and EPA discharge compliance as the primary grade differentiators. Cost compression in synthetic base stocks is intensifying because alpha-olefin feedstock prices track volatile natural gas liquids benchmarks. Independent operators in the Permian exhibit the highest price sensitivity, while Gulf of Mexico supermajors prioritize technical performance over unit cost.
Supply Chain Analysis
Tariff exposure between China and the United States dominates weighting agent procurement risk, as barite concentrate imports face unpredictable export quota restrictions. Formulation chemistry draws from Chinese barite, domestic bentonite from Wyoming deposits, and synthetic base fluids manufactured in Texas and Louisiana. Single-source vulnerability concentrates in high-purity barite for high-density drilling applications. Distribution runs through dedicated supply agreements with batch plants positioned near Midland and Hobbs logistics hubs, supplemented by regional distributor networks serving Oklahoma and North Dakota land drilling markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through Permian Basin operator consolidation, with supermajors and large independents capturing negotiating leverage over fluid suppliers through integrated service contract aggregation.
For Market Incumbents: Harden formulation expertise retention against the retiring chemist demographic by embedding automated fluid monitoring systems that reduce manual engineering dependence. Deepen backward integration into captive barite processing to offset Chinese supply quota volatility. Priority investment in real-time downhole sensor integration preserves premium positioning against commodity fluid distributors. For New Entrants and Emerging Players: Canadian oil sands thermal operations in Alberta represent the most penetrable white-space segment, with specialized high-temperature completion fluid demand outpacing incumbent service intensity. Target SAGD operators with brine-based formulations that satisfy Health Canada groundwater protection mandates. Go-to-market leverage rests on partnering with Calgary-based distribution nodes to bypass established Edmonton supply corridors. For Investors and Strategic Acquirers: Capital is best deployed toward asset-light fluid recycling infrastructure operators that capture EPA-mandated closed-loop investment cycles without fixed plant exposure. Long-term viability favors recyclers with multi-basin logistics networks spanning Texas, New Mexico, and Colorado regulatory jurisdictions. The inflection signal to watch is Texas Railroad Commission produced-water blending capacity expansion announcements that validate third-party recycling economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Barite Processing | Captive weighting agent supply insulates margins from Chinese export quota volatility. |
| Real-Time Fluid Monitoring Deployment | Downhole sensor integration collapses response time for weight and viscosity management. |
| Closed-Loop Recycling Capacity Expansion | EPA effluent guidelines mandate zero-discharge systems in coastal watersheds. |
| Bio-Based Ester Chemistry R&D | Pending EPA guideline revisions accelerate synthetic fluid component substitution. |
| Canadian Oil Sands Thermal Fluid Registration | Health Canada protocols favor brine-based formulations with minimal formation damage. |
Research Methodology
Initial hypotheses were tested against primary input from drilling fluid chemists, Permian Basin procurement directors, EPA regulatory affairs specialists, and third-party recycling facility operators and refined through secondary validation against SEC 10-K filings, Texas Railroad Commission discharge records, EIA drilling productivity reports, and customs trade data for barite imports. Bottom-up well count and fluid consumption intensity models were triangulated against top-down service provider revenue segmentation.
Demand-supply balance dynamics across the analysis window were modeled through well architecture evolution, thermal stability requirements, and regulatory compliance cost trajectories. Segmentation dimensions included fluid system type, well geometry classification, operator scale tier, and state-level regulatory cluster. CAGRs were derived from rig count forecasts, lateral length extension trends, and fluid consumption per foot intensity curves calibrated against historical operating data.
Practitioners should monitor EPA effluent limitation guideline revision timelines, Chinese barite export quota announcements, and Permian Basin produced-water recycling capacity utilization for early signals of forecast deviation. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Middle East and Africa Drill Collar Market
Oil & Gas
Tight Gas Market
Oil & Gas
Planned LNG Market
Oil & Gas
Oil and Gas Automation and Instrumentation Market
Oil & Gas
US Oil and Gas Analytics Market
Oil & Gas
Asia Pacific Oil Storage Tank Service Market
Oil & Gas
AI in Oil and Gas Market
Oil & Gas
Frac Services Market
Oil & Gas
Canada Oil and Gas Market
Oil & Gas
Mexico Oil and Gas Market
Oil & Gas
North Sea Oil and Gas Upstream Market
Oil & Gas
Crown Block Market
Oil & Gas
Egypt Oil and Gas Market
Oil & Gas
Subsea Well Intervention Market
Oil & Gas
US Sand Control Systems Market
Oil & Gas
Global Completion Equipment and Services Market