
 APAC Electric Vehicle Charging Station Market | 2026-2036
APAC Electric Vehicle Charging Station Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Electric Vehicle Charging Station Market Insights
Market Dynamics
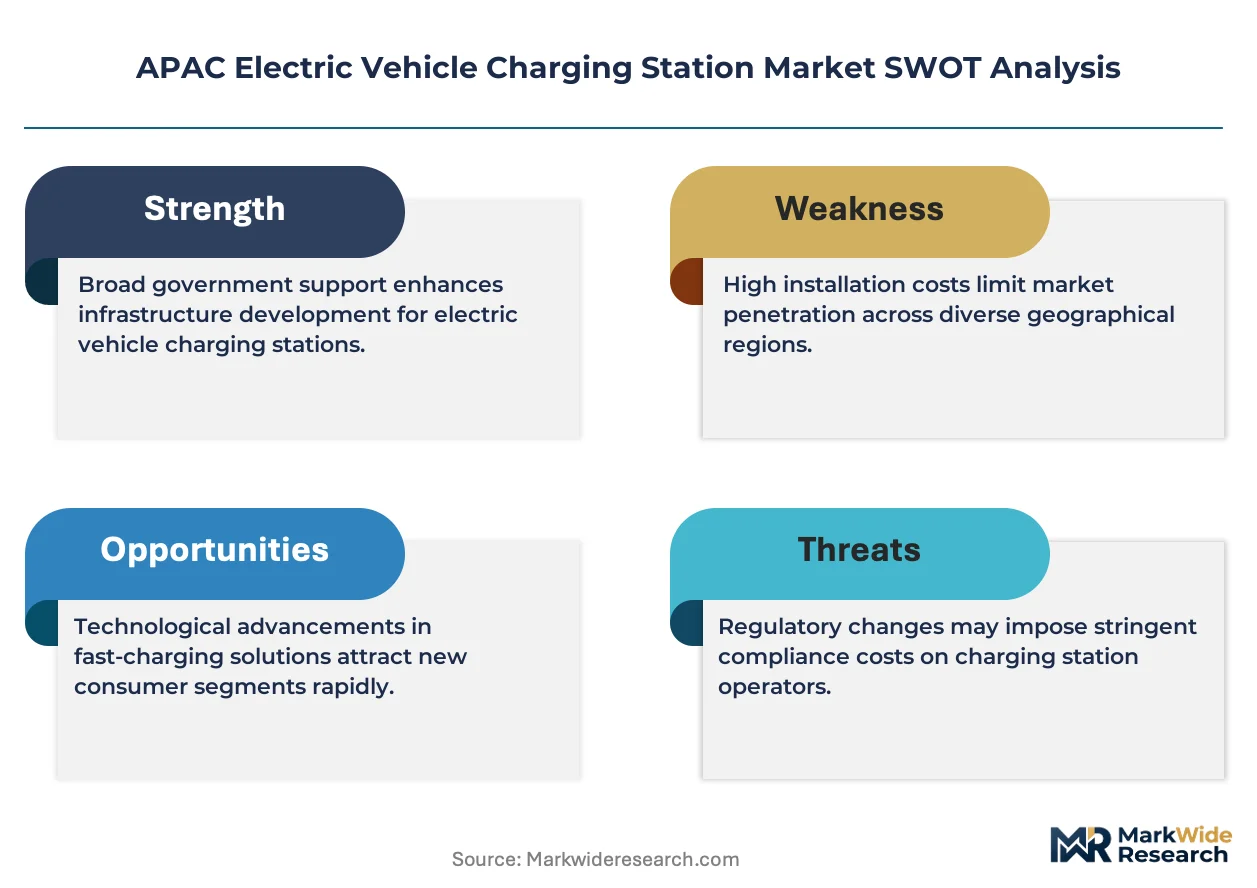
Asset-light leasing models and infrastructure-as-a-service financing are reshaping competitive entry barriers across the APAC Electric Vehicle Charging Station landscape. TGOOD leverages its integrated manufacturing footprint to sustain cost advantages in high-power transformer production. BYD anchors its position through captive demand from its electric bus and taxi deployments. Star Charge dominates distributed charging networks via direct utility partnerships in eastern China.
Technology and Segmentation
APAC Electric Vehicle Charging Station infrastructure comprises conductive power electronics, grid-interactive inverters, and connector assemblies engineered to deliver 50 kW to 350 kW DC output for battery electric vehicles. DC Fast Chargers capture the dominant margin pool as fleet operators prioritize sub-30-minute turnaround cycles, while Battery Swapping Stations carve a specialized niche in taxi-dense corridors where NIO and BAIC platforms operate. Public Charging applications lead absolute installation counts, though Fleet Charging exhibits the steepest growth trajectory as logistics electrification mandates tighten across ASEAN member states.
Regulatory Environment
China's MIIT enforces GB/T 27930 communication protocols and dual carbon goals that compel state-owned utilities to expand intercity fast-charging corridors. India's CEA mandates technical standards for grid connectivity, while Japan's METI subsidizes CHAdeMO-CCS convergence testing to preserve export compatibility for domestic suppliers. Stakeholders must monitor whether ASEAN harmonizes charging standards before national procurement silos harden into incompatible infrastructure islands.
Market Dynamics
China's MIIT-mandated GB/T protocol unification is compressing hardware fragmentation and forcing suppliers to consolidate around interoperable power electronics platforms across the region.
Growth Catalysts
- MIIT Protocol Mandates:China's unified communication standards eliminate connector incompatibility, reducing procurement complexity for fleet operators deploying mixed-vehicle depots.
- Logistics Electrification Directives:ASEAN member states are tightening commercial vehicle emission thresholds, compelling freight operators to install dedicated fast-charging infrastructure at distribution hubs.
- High-Power Silicon Carbide Modules:Wider bandgap semiconductors enable 350 kW output densities that cut electric bus turnaround times below fifteen minutes.
Market Restraints
- Transformer Supply Bottlenecks:High-voltage grid connection equipment concentrates among Japanese and South Korean foundries, creating eighteen-month lead times for 1 MVA+ units.
- Land Acquisition Friction:India's state-level electricity boards face right-of-way disputes along the Mumbai-Delhi highway corridor, delaying corridor charging rollouts.
- Grid Capacity Constraints:Vietnam's provincial power infrastructure lacks substation redundancy for simultaneous 150 kW+ draws, capping site density in Ho Chi Minh City peripheries.
Strategic Opportunities
- Indonesia's Archipelago Deployment:The national utility PLN is tendering island-hopping marine vessel electrification, creating demand for shore-side fast-charging at Java-Sumatra ferry terminals.
- Battery Swapping Convergence:NIO's modular pack architecture is licensing to Thai taxi cooperatives, opening standardized swap station networks in Bangkok's dense urban core.
- Australia's NEM Grid Integration:The national electricity market's frequency control ancillary services framework allows charging operators to monetize vehicle-to-grid dispatch during peak demand events.
Industry Challenges
- Power Electronics Talent Scarcity:Malaysia's electrical engineering pipeline produces insufficient thermal management specialists for liquid-cooled 350 kW dispenser design.
- Multi-Protocol Certification Complexity:Japan's CHAdeMO Association and China's GB/T working groups maintain divergent test procedures, forcing manufacturers to duplicate validation cycles for cross-border sales.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Electric Vehicle Charging Station Market |
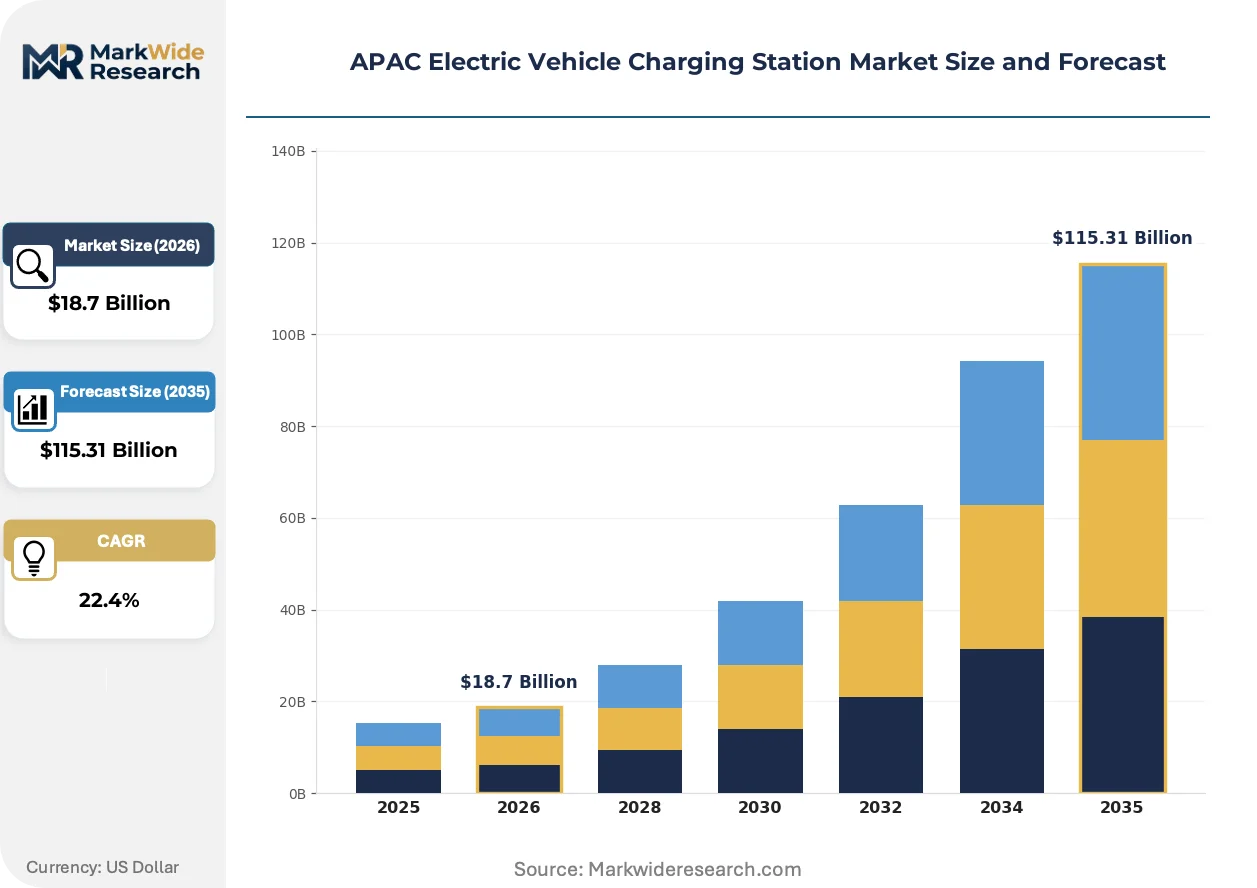
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $115.31 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DC Fast Chargers, AC Level 2 Chargers, Wireless Chargers, Battery Swapping Stations Technology: Plug-in Chargers, Inductive Charging, Conductive Charging, Ultra-Fast Charging Application: Public Charging, Residential Charging, Workplace Charging, Fleet Charging End User: Commercial Fleet Operators, Government Fleets, Private Vehicle Owners, Taxi Services |
| Companies Covered | Star Charge, BYD, Delta Electronics, State Grid Corporation of China, Tata Power, Schneider Electric, ABB Ltd., TGOOD, EVCOME, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Electric Vehicle Charging Station Market Trends and Innovations
Digital twin architectures and predictive load balancing are displacing static capacity planning across APAC charging networks, enabling dynamic pricing and grid-stabilizing demand response.
Silicon carbide power modules are virtualizing the thermal management burden in 350 kW dispensers, cutting cooling system mass by forty percent versus insulated-gate bipolar transistor stacks. Korean battery electric bus manufacturers are specifying these modules for depot installations above 500 kW aggregated capacity. The technology is virtualizing site preparation costs, enabling faster deployment in dense urban footprints where excavation and civil works dominate project timelines.
Japan's METI convergence subsidies are accelerating CHAdeMO-CCS dual-cable dispenser deployment, preserving domestic supplier export access to European and North American markets. The policy forces domestic hardware manufacturers to maintain dual-protocol engineering capabilities rather than specializing on single standards. Tokyo's metropolitan government procurement now requires dual-cable compatibility for all public charging infrastructure tenders, compressing single-protocol vendor margins.
Fleet operators are consolidating charging procurement under energy-as-a-service contracts that bundle hardware, installation, and electricity supply into per-kilometer rates. This displaces capital-intensive ownership models for logistics operators with thin balance sheets. The shift is most visible across Southeast Asia's last-mile delivery networks, where regional e-commerce platforms prefer operational expenditure structures over property-plant-equipment expansion.
APAC Electric Vehicle Charging Station Market Segmentation
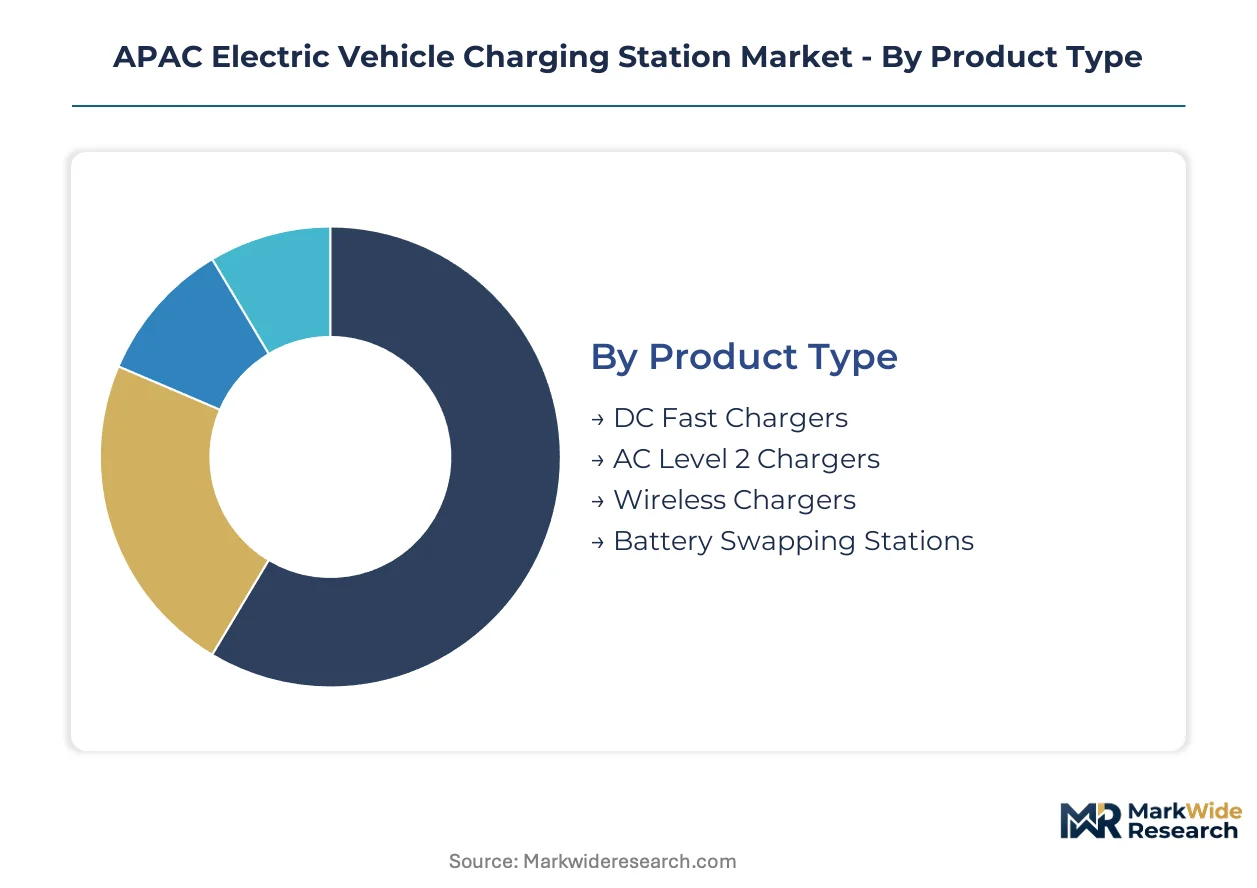
Segmentation in the APAC Electric Vehicle Charging Station market reveals divergent equipment lifecycles and capital recovery profiles. Fast-turnover segments like fleet charging demand ruggedized hardware with 24/7 utilization, while residential installations recover investment over longer depreciation schedules with intermittent use patterns.
Product Type:
DC Fast Chargers and Battery Swapping Stations turn over fastest with fleet operators cycling equipment through multiple daily sessions, while AC Level 2 and Wireless units see slower utilization curves in parking-dwell applications.
- DC Fast Chargers:These units deliver 50 kW to 350 kW through conductive power electronics with liquid-cooled cable assemblies. Demand concentrates along India's Maharashtra-Gujarat industrial corridor where state utilities tender highway corridor installations to serve long-haul freight electrification.
- Battery Swapping Stations:Modular pack architectures enable sub-three-minute exchanges through automated robotic systems. NIO and BAIC platforms anchor demand in taxi-dense Chinese corridors where vehicle uptime metrics dominate procurement decisions.
- AC Level 2 Chargers:These 7 kW to 22 kW units serve workplace and residential dwell-time charging with lower infrastructure costs.
- Wireless Chargers:Inductive pad systems eliminate connector wear in automated guided vehicle applications at logistics hubs.
DC Fast Chargers dominate installed base. Battery Swapping Stations is where expansion concentrates.
Technology:
Ultra-Fast Charging and Plug-in systems command premium pricing tiers through silicon carbide power modules, while Inductive and Conductive platforms occupy cost-optimized niches with simpler thermal management.
- Ultra-Fast Charging:Silicon carbide power modules enable 350 kW output densities that cut electric bus turnaround times below fifteen minutes. Korean battery electric bus manufacturers specify these modules for depot installations above 500 kW aggregated capacity.
- Plug-in Chargers:GB/T 27930 communication protocols unify connector compatibility across China's state-owned utility networks. MIIT mandates compress hardware fragmentation and force supplier consolidation around interoperable power electronics platforms.
- Inductive Charging:Magnetic resonance systems enable hands-free operation in enclosed parking structures with limited maintenance access.
- Conductive Charging:Direct-contact systems anchor the technology mix through mature supply chains and standardized connector geometries.
Plug-in Chargers capture volume leadership. Ultra-Fast Charging is climbing the fastest as fleet operators prioritize sub-thirty-minute turnaround cycles.
Application:
Public Charging infrastructure scales through municipal procurement with standardized tender specifications, while Fleet Charging exhibits steepest expansion trajectory as logistics electrification mandates tighten across ASEAN member states.
- Fleet Charging:Depot-based installations aggregate multiple high-power dispensers for coordinated overnight charging of commercial vehicle pools. Southeast Asia's last-mile delivery networks prefer energy-as-a-service contracts that bundle hardware and electricity supply into per-kilometer rates.
- Public Charging:Intercity corridor installations require grid-interactive inverters with demand response capabilities. China's state-owned utilities expand fast-charging corridors under dual carbon goals that compel infrastructure deployment.
- Residential Charging:Single-unit wallbox installations serve private vehicle owners with overnight dwell-time scheduling.
- Workplace Charging:Employer-subsidized installations capture daytime parking hours with slower AC charging speeds.
Public Charging leads absolute installation counts. Fleet Charging is gaining share fastest as commercial operators consolidate procurement under operational expenditure structures.
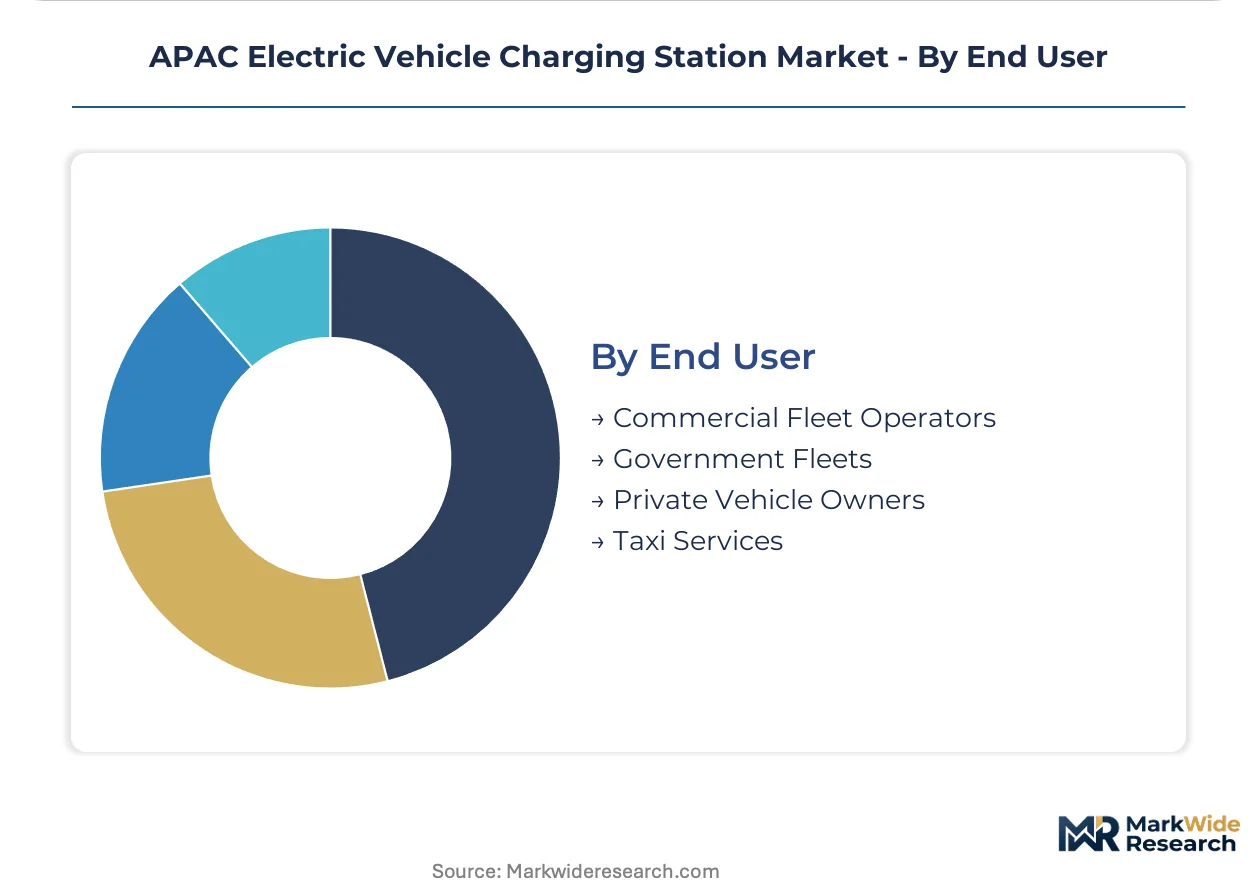
End User:
Commercial Fleet Operators and Taxi Services drive highest utilization intensity with equipment depreciation recovered through daily revenue generation, while Government Fleets and Private Vehicle Owners operate on extended replacement cycles.
- Commercial Fleet Operators:These stakeholders consolidate charging procurement under energy-as-a-service contracts that displace capital-intensive ownership models. Regional e-commerce platforms across Southeast Asia prefer operational expenditure structures over property-plant-equipment expansion.
- Taxi Services:NIO's modular pack architecture licenses to Thai taxi cooperatives, opening standardized swap station networks in Bangkok's dense urban core where vehicle downtime carries acute revenue penalties.
- Government Fleets:Municipal bus operators anchor demand through electrification mandates with procurement transparency requirements.
- Private Vehicle Owners:Individual purchasers prioritize residential and workplace charging access over public infrastructure dependency.
Commercial Fleet Operators dominate contract value. Taxi Services is where technology convergence concentrates through battery swapping platform licensing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
APAC's charging infrastructure trade flows reflect divergent manufacturing capabilities and import dependencies. China maintains net exporter status through integrated power electronics supply chains, while India and Southeast Asian markets absorb hardware inflows to bridge domestic production gaps.
China
State Grid Corporation of China and Southern Power Grid deploy intercity fast-charging corridors under MIIT-mandated GB/T 27930 protocols. The dual carbon goals compel state-owned utilities to expand infrastructure deployment. Yangtze River Delta cities including Shanghai and Suzhou concentrate manufacturing of silicon carbide power modules for 350 kW dispensers.
India
CEA technical standards for grid connectivity govern highway corridor installations along the Maharashtra-Gujarat industrial belt. State utilities in Maharashtra tender depot-based charging for commercial fleets. Tata Power anchors charging networks in Mumbai and Delhi-NCR through utility partnerships and captive renewable energy sourcing.
Japan
METI subsidizes CHAdeMO-CCS convergence testing to preserve export compatibility for domestic suppliers. Tokyo metropolitan procurement mandates dual-cable dispensers for all public infrastructure tenders. Nagoya's automotive engineering base supplies thermal management systems for liquid-cooled high-power dispensers.
South Korea
MFDS-equivalent electrical safety certifications apply to high-voltage grid connection equipment. Korean battery electric bus manufacturers specify silicon carbide modules for depot installations exceeding 500 kW aggregated capacity. Busan-Ulsan industrial complex hosts foundries producing 1 MVA+ transformers with eighteen-month order backlogs.
Australia
The National Electricity Market's frequency control ancillary services framework allows charging operators to monetize vehicle-to-grid dispatch. New South Wales and Victoria lead installation counts through state-level fleet electrification mandates. Sydney and Melbourne metropolitan councils bundle charging infrastructure into transit-oriented development approvals.
APAC Electric Vehicle Charging Station Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic archetypes: integrated manufacturers with captive transformer production, utility-affiliated network operators with preferential grid access, and specialist power electronics firms with semiconductor design capabilities. Competitive positioning depends on backward integration into high-voltage components, direct utility partnerships for site procurement, and multi-protocol certification breadth. Capacity expansion and strategic licensing agreements represent the dominant competitive moves as players pre-position for ASEAN market entry.
Within the integrated manufacturer tier, TGOOD and BYD exemplify divergent strategic positioning. TGOOD leverages its manufacturing footprint to sustain cost advantages in high-power transformer production. BYD anchors its position through captive demand from affiliated electric bus and taxi deployments. Star Charge occupies a distinct position among utility-partnered network operators, dominating distributed charging networks through direct State Grid Corporation of China relationships in eastern China.
| Leading Market Players |
|---|
| Star Charge |
| BYD |
| Delta Electronics |
| State Grid Corporation of China |
| Tata Power |
| Schneider Electric |
| ABB Ltd. |
| TGOOD |
| EVCOME |
| Others |
Pricing and Supply Chain Analysis
Japanese and South Korean foundry concentration in 1 MVA+ transformer production feeds directly into margin capture at the high-voltage grid connection tier, where eighteen-month order backlogs let incumbent suppliers command premium positioning.
Pricing Analysis
Commercial fleet operators anchor pricing stratification across premium, standard, and economy tiers differentiated by silicon carbide module grade and after-sales service bundling. Cost compression in standard-tier hardware intensifies as Chinese GB/T-certified suppliers expand manufacturing scale. Small logistics operators with thin balance sheets exhibit acute price sensitivity, while state-owned utilities with captive procurement budgets show minimal elasticity.
Supply Chain Analysis
Delta Electronics and TGOOD contract-manufacturing capacity in Taiwan and eastern China anchors power electronics assembly, with silicon carbide wafer sourcing drawing from Japanese and South Korean substrate foundries. Raw material dependencies span copper busbar, liquid-cooled cable assemblies, and high-frequency magnetic cores. Single-source vulnerability concentrates in 1 MVA+ transformer supply. Distribution runs through direct utility procurement channels and energy-as-a-service platform aggregators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Power electronics thermal management expertise scarcity constrains 350 kW dispenser deployment velocity, creating asymmetric returns for stakeholders who secure specialized engineering pipelines before ASEAN electrification mandates tighten.
For Market Incumbents: Pre-empt margin erosion from silicon carbide cost curves by locking multi-year supply agreements with Japanese substrate foundries. Accelerate certification investment for CHAdeMO-CCS dual-protocol compatibility before Tokyo metropolitan procurement mandates harden. Defensive capacity addition in Vietnam and Indonesia hedges against land acquisition friction in India's highway corridor. For New Entrants and Emerging Players: Build out battery swapping station networks in Thai taxi cooperatives and Indonesian archipelago ferry terminals where incumbent charging infrastructure remains sparse. License modular pack architectures from established Chinese platforms to bypass R&D capital intensity. White-space penetration runs through energy-as-a-service contracts with Southeast Asian last-mile delivery networks. For Investors and Strategic Acquirers: Capital is best deployed toward utility-affiliated network operators with preferential State Grid Corporation of China site access and direct procurement relationships. Long-term viability across the analysis window hinges on backward integration into transformer production or captive silicon carbide module supply. Monitor ASEAN regulatory harmonization negotiations as inflection signal for cross-border infrastructure scalability.| Strategic Initiative | Industry Significance |
|---|---|
| GB/T Protocol Certification Investment | MIIT mandates compress hardware fragmentation, favoring suppliers with unified communication stack compliance. |
| Silicon Carbide Module Supply Agreement | Korean bus manufacturers specify these components for depot installations, creating captive demand pools. |
| Dual-Cable Dispenser Platform Development | METI convergence subsidies preserve Japanese supplier export access to European and North American markets. |
| Energy-as-a-Service Contract Expansion | Southeast Asian e-commerce platforms prefer operational expenditure structures over capital-intensive ownership. |
| Transformer Manufacturing Capacity Addition | Eighteen-month order backlogs at Japanese and South Korean foundries signal supply-constrained pricing power. |
Research Methodology
Desk research of MIIT regulatory filings, CEA technical standards, and ASEAN member state procurement databases preceded structured interviews with utility planning officers, charging network procurement leads, fleet operations managers, and power electronics engineering directors. Primary fieldwork with State Grid Corporation of China regional planners and PLN tender officials cross-validated secondary data on deployment timelines. Bottom-up installation counts and top-down infrastructure investment flows were triangulated to anchor market sizing.
Assumptions around GB/T protocol adoption velocity, silicon carbide cost curve trajectories, and ASEAN regulatory harmonization progress were held fixed across the projection horizon while fleet electrification mandate stringency and land acquisition clearance rates were stress-tested. Segmentation modeling spanned charger power tier, communication protocol type, application environment, and end-user procurement structure. CAGRs were derived from equipment replacement cycles and infrastructure investment run-rates.
Stress conditions across transformer lead times, grid connection approval velocities, and battery swapping station utilization rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions around sustained logistics electrification policy support and stable raw material supply from Japanese and South Korean foundries. Quarterly review of ASEAN regulatory harmonization indicators and state-level electricity board tender awards is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Electric Vehicle Grid Integration Solutions Market
Electric Vehicle Charging
Oman EV Charging Station Market
Electric Vehicle Charging
Global Automotive Charging System Market
Electric Vehicle Charging
Automotive EV Charging Adapters Market
Electric Vehicle Charging
EV DC Chargers Market
Electric Vehicle Charging
Solar Charging Station Market
Electric Vehicle Charging
North America Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Electric Vehicle Charging Station Raw Materials Market
Electric Vehicle Charging
Electric Vehicle Charging Adapter Market
Electric Vehicle Charging
Global Electric Vehicle Charging As a Service Market
Electric Vehicle Charging
EV DC Fast Charger Market
Electric Vehicle Charging
Asia-Pacific Electric Vehicle Charging Cable Market
Electric Vehicle Charging
Second Life Electric Vehicle Battery Market
Electric Vehicle Charging
Netherlands Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Smart EV Charger Market
Electric Vehicle Charging
Electric Vehicle Charging System Market