
 Germany Electric Vehicle Charging Equipment Market | 2026-2036
Germany Electric Vehicle Charging Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Electric Vehicle Charging Equipment Market Insights
Project finance and leasing structures for charging infrastructure assets is rewriting competitive entry barriers across Germany. Siemens AG leverages its industrial automation heritage to anchor manufacturing scale for high-power charging modules. ABB Ltd competes through technology leadership in grid-integrated DC fast charging systems for highway corridors. Compleo Charging Solutions AG specializes in modular hardware architectures that reduce deployment lead times for fleet operators.
Germany electric vehicle charging equipment comprises power electronics, cable assemblies, and control systems engineered to deliver alternating or direct current at outputs ranging from 3.7 kW residential units to 350 kW ultra-fast highway dispensers. These systems enable energy transfer between grid infrastructure and electric vehicle battery packs while managing thermal loads, communication protocols, and user authentication. AC chargers sustain dominant installed volume across private residences and workplace parking where dwell times accommodate slower charging cycles. DC fast chargers occupy the highest-margin segment as commercial complexes and highway service stations prioritize throughput and revenue per charging event. Wireless chargers represent an emerging structural category where technology maturity and standardization gaps currently limit mass deployment.
Germany's Federal Network Agency (Bundesnetzagentur) enforces grid connection standards under the Energy Industry Act, while KBA type-approval requirements govern charging system safety certification for public deployment. The EU AFIR mandates minimum power output thresholds and payment interoperability across Germany's trans-European transport network corridors, directly shaping product specification requirements for network operators. Stakeholders must monitor how Berlin's building code amendments mandating pre-cabling in new construction alter demand timing between retrofit and greenfield installation channels.
Market Dynamics
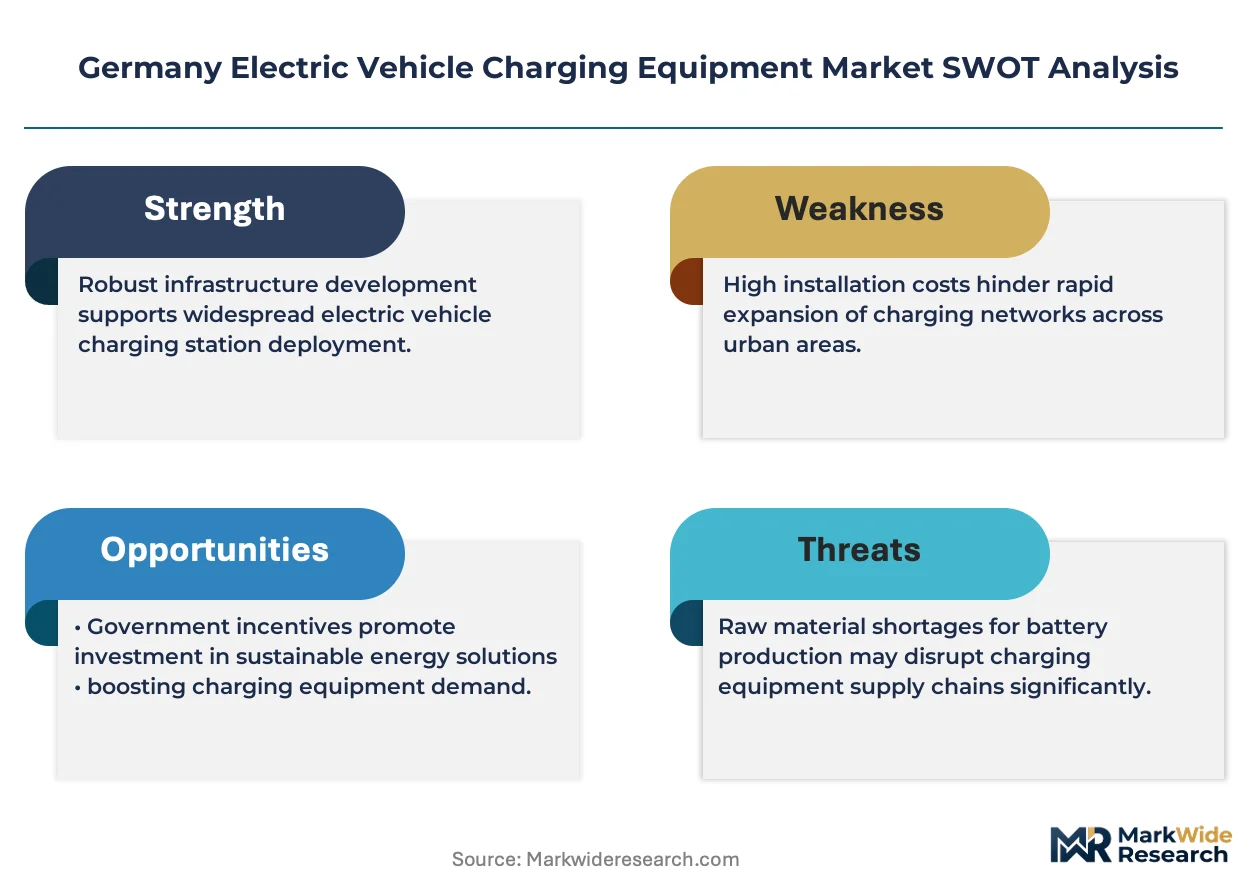
Germany's AFIR-mandated deployment targets are compressing installation timelines and forcing equipment suppliers to accelerate manufacturing scale-up while navigating grid connection bottlenecks at the distribution network level.
Growth Catalysts
- AFIR corridor mandates:The EU Alternative Fuels Infrastructure Regulation imposes binding power output minimums along Germany's trans-European transport network, compelling highway operators to install high-capacity DC infrastructure ahead of vehicle fleet turnover.
- Fleet electrification:Commercial vehicle operators across logistics and public transit sectors are converting depots into high-throughput charging hubs, generating concentrated demand for modular hardware architectures.
- Building code pre-cabling:Berlin's amendments to national construction standards mandate electrical readiness in new residential and commercial developments, shifting demand timing toward greenfield installation channels.
Market Restraints
- Copper and silicon carbide cost volatility:Power electronics manufacturing faces input price instability for critical semiconductor substrates and conductive materials, compressing module margins at the 50-150 kW segment.
- Grid connection queuing:Bundesnetzagentur approval timelines for medium-voltage hookups at highway service stations extend 18-24 months, creating deployment backlogs independent of equipment availability.
- AC charger margin erosion:Residential and workplace segments suffer commoditization pressure as standardized 11-22 kW hardware faces price competition from Asian manufacturing imports.
Strategic Opportunities
- Eastern metropolitan corridors:Leipzig-Dresden and Magdeburg-Halle transport axes remain underpenetrated relative to Rhine-Ruhr density, offering first-mover positioning for corridor charging networks.
- Vehicle-to-grid integration:Bidirectional charging protocols enabling fleet battery assets to participate in frequency regulation markets create new revenue streams for depot operators.
- Wireless inductive systems:Taxi and ride-hail applications in Munich and Hamburg are piloting pad-based charging at rank locations, circumventing cable management constraints in dense urban curb space.
Industry Challenges
- Power electronics engineering scarcity:German universities produce insufficient graduates specializing in high-frequency converter design and thermal management for 350 kW liquid-cooled systems.
- KBA type-approval duration:Federal Motor Transport Authority certification timelines for novel charging architectures extend 12-16 months, delaying product launches relative to competitor jurisdictions.
- Interoperability testing complexity:Multi-vendor communication protocol validation across ISO 15118 and OCPP standards requires dedicated certification facilities that remain capacity-constrained.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Electric Vehicle Charging Equipment Market |
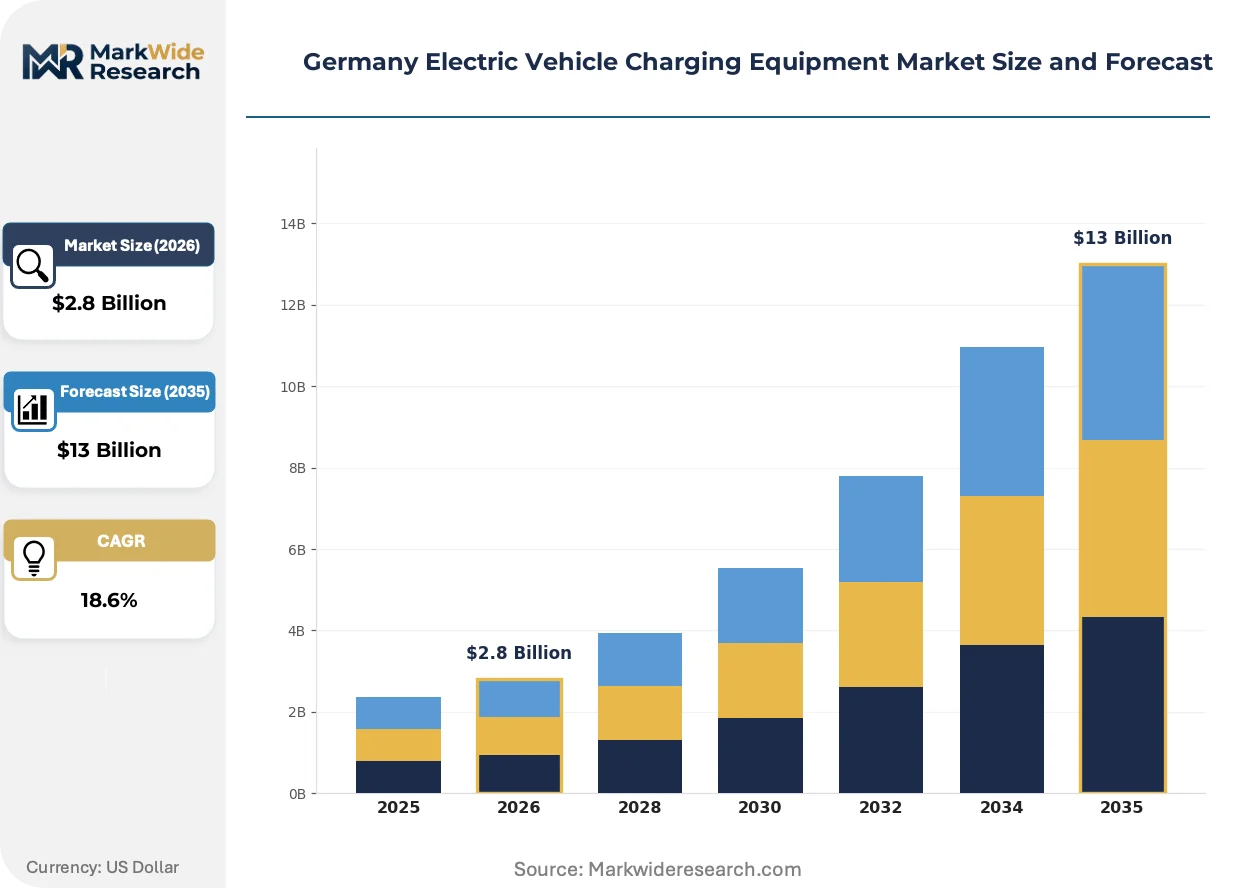
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Charger Type: AC Chargers, DC Fast Chargers, Wireless Chargers, Portable Chargers, Wall-mounted Chargers Connector Standard: Type 2, CCS, CHAdeMO, Tesla Supercharger, GB/T Application: Private Residences, Commercial Complexes, Fleet Depots, Public Parking Lots, Highway Service Stations End User: Electric Vehicle OEMs, Charging Network Operators, Property Managers, Municipal Authorities |
| Companies Covered | Siemens AG, ABB Ltd, Compleo Charging Solutions AG, Tesla Inc., ChargePoint Inc, EnBW, E.ON Drive GmbH, Alpitronic, Bosch, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Electric Vehicle Charging Equipment Market Trends and Innovations
Silicon carbide power semiconductors and dynamic load management software are restructuring equipment economics, while regulatory pressure on installation density accelerates product lifecycle compression.
Silicon carbide MOSFETs replace traditional silicon IGBTs in DC fast charging inverters, cutting switching losses by two-thirds and enabling higher power density in compact footprints. Fleet operators and highway concessionaires are specifying SiC-based architectures for new 150-350 kW installations. This semiconductor transition is rendering obsolete older IGBT-based designs that cannot achieve the thermal efficiency required for continuous high-output operation.
Berlin's implementation of AFIR through the Bundesnetzagentur enforcement framework tightens payment interoperability and ad-hoc access requirements at public charging points. Equipment suppliers must now pre-integrate contactless payment terminals and roaming protocol compliance into hardware designs. Highway corridor operators face the steepest compliance burden as they retrofit existing installations ahead of 2025 enforcement deadlines.
Leasing and equipment-as-a-service contracts displace direct capital purchase for fleet depot installations, transferring technology obsolescence risk from transport operators to charging infrastructure providers. Energy utilities and specialized asset financiers are capturing margin pools previously held by equipment vendors. This financing shift concentrates in North Rhine-Westphalia and Baden-Württemberg where commercial fleet density supports portfolio-scale underwriting.
Germany Electric Vehicle Charging Equipment Market Segmentation
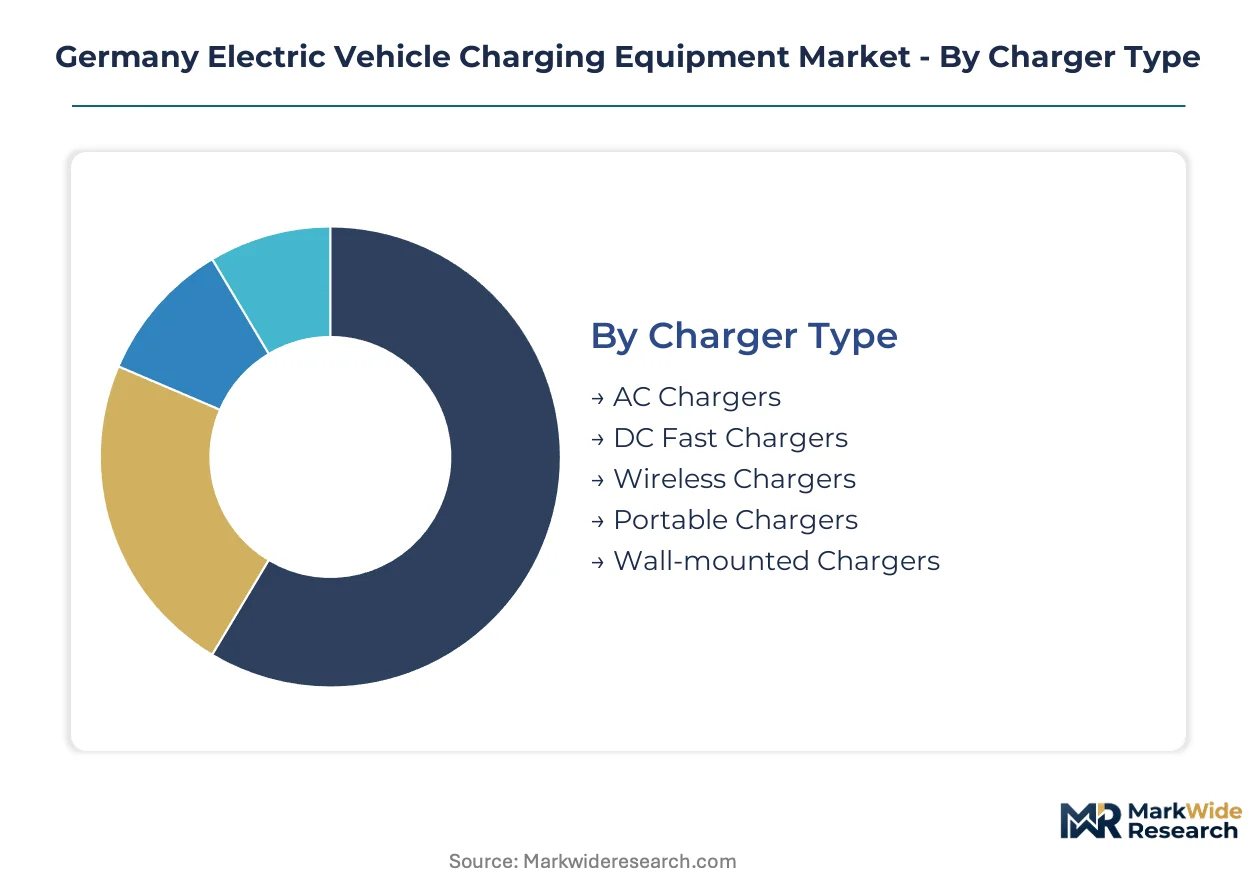
Segmentation reveals how equipment specifications diverge across installation environments in Germany. Charger type and connector standards determine hardware margins, while application context dictates procurement authority and financing structures.
Charger Type:
After-sales service intensity varies sharply across charger architectures, with liquid-cooled high-power units requiring specialized maintenance protocols that reshape vendor-customer relationships.
- AC Chargers:These units convert grid alternating current through onboard vehicle rectifiers, delivering 3.7-22 kW outputs suitable for overnight dwell cycles. Demand clusters in Berlin's new residential construction where pre-cabling mandates accelerate greenfield deployment ahead of vehicle ownership.
- DC Fast Chargers:Off-board rectifiers feed direct current straight to battery packs at 50-350 kW, slashing charging duration to 20-40 minutes. Highway service stations along the A9 Munich-Berlin corridor prioritize these units to capture transit traffic, though Bundesnetzagentur grid connection queues extend deployment timelines.
- Wireless Chargers:Inductive pad systems eliminate cable handling through magnetic resonance coupling.
- Portable Chargers:Mobile emergency units provide 2.3-3.7 kW backup charging from standard household outlets.
- Wall-mounted Chargers:Compact AC hardware designed for space-constrained parking structures and multi-unit residential installations.
AC Chargers hold the largest share; momentum sits with DC Fast Chargers.
Connector Standard:
Cost tier stratification emerges clearly across connector architectures, with proprietary systems commanding premium positioning against standardized alternatives.
- Type 2:The Mennekes-designed inlet dominates European AC charging through its seven-pin configuration supporting single-phase and three-phase power delivery. Workplace parking operators in Hamburg and Frankfurt standardize on this connector to maximize vehicle compatibility across mixed fleets.
- CCS:Combined Charging System integrates AC Type 2 pins with DC power contacts beneath a single inlet cover. AFIR corridor mandates explicitly reference CCS as the interoperability baseline for Germany's trans-European network, compelling highway infrastructure investment.
- CHAdeMO:Japanese-origin DC standard retains niche presence among early-import electric vehicle populations.
- Tesla Supercharger:Proprietary connector architecture undergoing European CCS retrofit compliance.
- GB/T:Chinese national standard with minimal German market presence outside imported vehicle populations.
Type 2 anchors installed volume; CCS gains share fastest as AFIR enforcement tightens.
Application:
Customer type fragmentation shapes procurement patterns distinctly across installation contexts, from individual homeowner decisions to municipal tender processes.
- Private Residences:Single-point installations serving individual vehicle owners, typically 11 kW AC wallboxes mounted in garages or carports. Baden-Württemberg's building code amendments accelerate pre-cabling requirements that shift demand timing toward new construction.
- Fleet Depots:Centralized charging hubs serving logistics and public transport operators with 20-50 simultaneous charging positions. Leipzig's distribution centers are converting to overnight depot charging to circumvent highway infrastructure bottlenecks.
- Commercial Complexes:Retail and office parking installations prioritizing customer dwell time extension.
- Public Parking Lots:Municipal or concession-operated curbside and garage infrastructure with ad-hoc payment requirements.
- Highway Service Stations:High-throughput corridor locations where AFIR mandates minimum power output thresholds and interoperability compliance.
Private Residences retain volume leadership; Fleet Depots show steepest expansion trajectory.
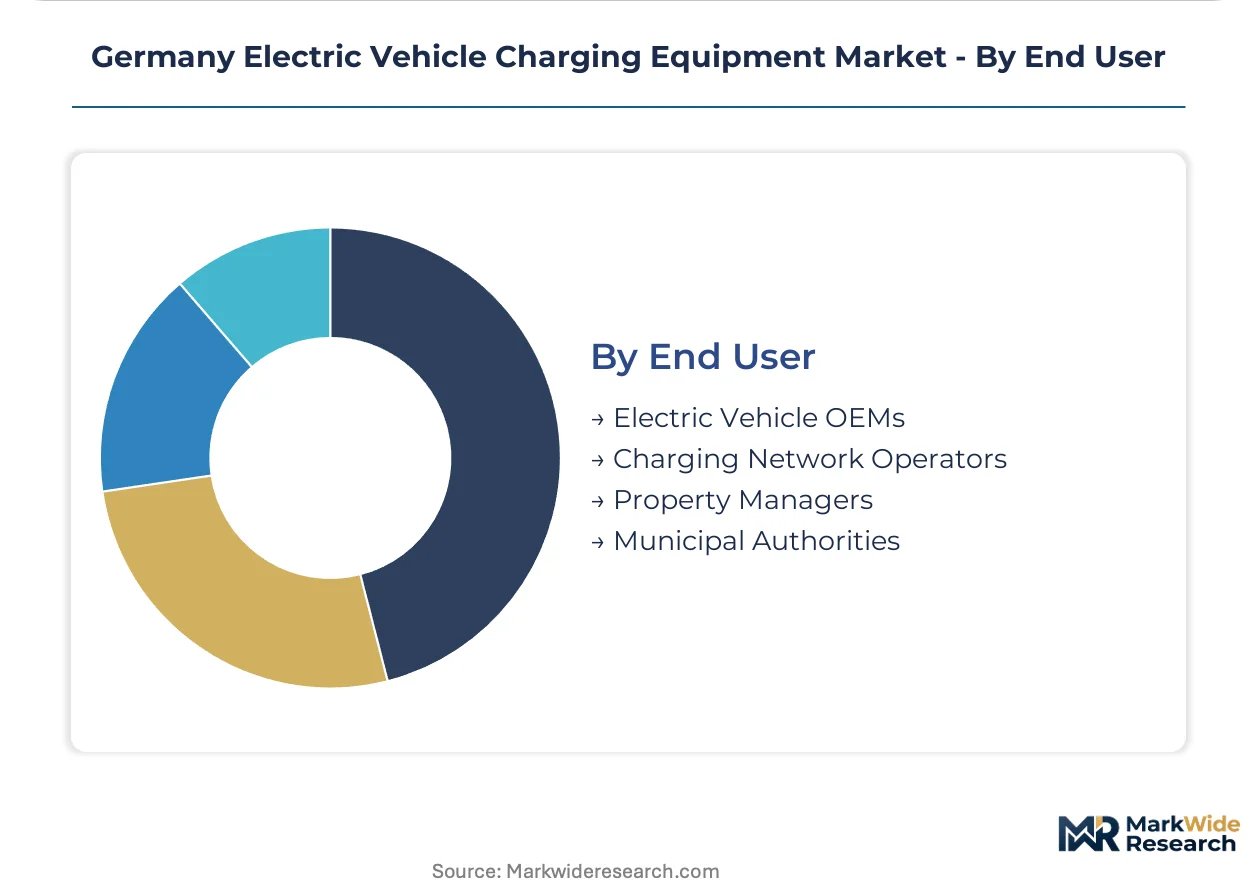
End User:
Supply concentration patterns differ markedly across buyer categories, with integrated OEMs sourcing differently than fragmented property manager segments.
- Charging Network Operators:Specialized infrastructure companies like Ionity and EnBW deploy capital at scale across corridor and urban locations, bundling hardware procurement with energy supply contracts and roaming platform integration.
- Electric Vehicle OEMs:Manufacturers including Volkswagen Group and BMW pre-install charging hardware at dealerships and bundle home charging packages with vehicle sales to secure aftermarket revenue streams.
- Property Managers:Residential and commercial building operators navigating split-incentive problems between landlord capital investment and tenant electricity consumption.
- Municipal Authorities:City governments procuring curbside infrastructure through public tender processes with local content and accessibility requirements.
Charging Network Operators command the largest procurement volumes; Electric Vehicle OEMs are expanding most quickly through bundled vehicle-charger offerings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Federal Ministry for Digital and Transport channels subsidies through the Charging Infrastructure Masterplan II, directing capital toward metropolitan corridors and underserved eastern regions. The policy framework prioritizes highway fast-charging density and depot electrification for commercial fleets.
Bavaria
Automotive manufacturing clusters around Munich and Ingolstadt drive concentrated demand for high-power charging infrastructure. The Bavarian State Ministry for Economic Affairs funds corridor expansion along the A9 autobahn toward Berlin. Siemens AG anchors industrial supply chains from its Nuremberg automation facilities.
North Rhine-Westphalia
Logistics operators in the Rhine-Ruhr conurbation convert distribution centers to overnight depot charging. The state's Climate Protection and Energy Agency coordinates grid connection approvals for fleet hubs. Cologne-Düsseldorf transport corridors exhibit the highest public charging point density outside Berlin.
Baden-Württemberg
Building code amendments in Stuttgart mandate pre-cabling for new residential construction, accelerating greenfield AC charger deployment. Robert Bosch GmbH maintains manufacturing presence for power electronics components. The state's automotive supply chain integrates charging hardware into vehicle platform development.
Berlin-Brandenburg
Municipal procurement drives curbside infrastructure expansion across Berlin's dense urban core. The Senate Department for Mobility administers tender processes with local content requirements. Tesla Inc. operates its European Gigafactory in Grünheide, creating adjacent demand for testing and validation infrastructure.
Lower Saxony
Volkswagen Group's Wolfsburg headquarters generates captive demand for charging equipment across corporate and dealer networks. The state's ports at Hamburg proximity position Bremen-Hanover logistics corridors for heavy-duty vehicle electrification. Grid operators in this region face acute connection queuing for highway service station upgrades.
Germany Electric Vehicle Charging Equipment Market Competitive Landscape
Channel-controlling players compete with product-specialist players across hardware supply and network operation segments. Siemens AG and ABB Ltd leverage industrial automation heritage to anchor manufacturing scale for high-power modules. The vendor base stratifies into three archetypes: integrated industrial conglomerates, pure-play charging specialists, and energy utility affiliates. Dominant competitive moves include backward integration into semiconductor sourcing and strategic partnerships with fleet operators for depot infrastructure.
Among German industrial conglomerates, Siemens AG and Bosch occupy positions exemplifying manufacturing-scale competitiveness in power electronics. Swiss-Swedish engineering group ABB Ltd represents technology leadership in grid-integrated systems. Pure-play specialists Compleo Charging Solutions AG exemplify modular hardware architectures reducing deployment lead times.
| Leading Market Players |
|---|
| Siemens AG |
| ABB Ltd |
| Compleo Charging Solutions AG |
| Tesla Inc. |
| ChargePoint Inc |
| EnBW |
| E.ON Drive GmbH |
| Alpitronic |
| Bosch |
| Others |
Pricing and Supply Chain Analysis
Chinese silicon carbide substrate manufacturing concentrates upstream supply for power electronics modules, anchoring margin capture at the semiconductor tier while German equipment assemblers face downstream price compression on standardized AC hardware.
Pricing Analysis
Certification level under KBA type-approval and AFIR interoperability compliance creates the primary spread between premium and commodity tiers. Three-tier pricing structure across certified highway corridor systems, workplace AC installations, and residential entry-level units dominates procurement patterns. Cost compression in the 11-22 kW AC segment intensifies because Asian manufacturing imports erode domestic vendor margins. Fleet depot operators show least price sensitivity due to equipment-as-a-service financing structures, while residential buyers concentrate price sensitivity at point-of-sale vehicle bundling decisions.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk assessment for silicon carbide MOSFETs and power electronics substrates. Manufacturing concentration in China, South Korea, and Taiwan feeds German assembly operations for high-frequency converter modules. Copper cable assemblies and liquid-cooled thermal management components rest on commodity price volatility and specialized automotive supplier networks. Distribution runs through OEM-direct channels for fleet operators and electrical wholesaler networks for residential retrofit installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent equipment suppliers must defend against hydrogen fuel cell infrastructure substitution in heavy-duty corridor applications, where long-haul electrification timelines remain uncertain.
For Market Incumbents: Build captive semiconductor sourcing moats through backward integration into silicon carbide substrate partnerships or long-term offtake agreements with Chinese suppliers. Secure KBA certification pipelines ahead of AFIR enforcement deadlines to lock out faster-follower competition. Prioritize grid connection queue management capabilities at Bundesnetzagentur to convert manufacturing scale into deployed market share before connection bottlenecks ease.
For New Entrants and Emerging Players: Eastern metropolitan corridors between Leipzig, Dresden, Magdeburg, and Halle present underpenetrated highway charging density relative to Rhine-Ruhr saturation. Target modular hardware architectures that compress deployment lead times for fleet depot conversions, where incumbent vendor relationships remain less entrenched. Pursue equipment-as-a-service financing partnerships with regional energy utilities to circumvent direct capital purchase barriers.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed charging network operators holding corridor concession contracts with near-term AFIR compliance obligations. Five-to-ten year viability hinges on successful technology refresh from IGBT to SiC architectures without stranding legacy installation bases. Monitor Bundesnetzagentur grid connection approval velocity as the inflection signal for deployment capacity expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Technology Transition | Upgrading from IGBT to SiC MOSFETs enables 350 kW continuous output in compact footprints for highway corridors. |
| AFIR Compliance Certification | Pre-integrating contactless payment and roaming protocols meets Bundesnetzagentur enforcement timelines for corridor operators. |
| Fleet Depot Infrastructure Partnerships | Leasing structures transfer technology obsolescence risk from transport operators to equipment providers in North Rhine-Westphalia. |
| Grid Connection Queue Management | Securing medium-voltage hookup approvals ahead of 18-24 month Bundesnetzagentur timelines unlocks deployment capacity. |
| Vehicle-to-Grid Protocol Development | Bidirectional charging integration enables fleet battery assets to capture frequency regulation revenue streams. |
Research Methodology
The analysis maps AC residential, DC fast charging, and wireless inductive sub-sectors, each validated through charging network procurement directors, fleet operations managers, and Bundesnetzagentur regulatory officials. Primary interviews with power electronics engineers at Siemens and ABB manufacturing facilities, combined with secondary validation through KBA type-approval databases, AFIR regulatory filings, and Bundesnetzagentur grid connection records, anchor demand-side and supply-side triangulation. Bottom-up installation forecasts and top-down energy utility capex disclosures cross-validate market sizing across the projection horizon.
Assumption sets held German AFIR corridor mandates and building code pre-cabling amendments fixed while varying electric vehicle fleet turnover rates and silicon carbide substrate supply elasticity. Segmentation modeling across charger type, connector standard, application context, and end-user procurement authority generates volume and value outputs. CAGRs derive from installed base replacement cycles, greenfield construction permitting velocity, and equipment-as-a-service contract penetration assumptions. Forecast inputs include highway traffic density metrics, commercial fleet electrification commitments from logistics operators, and distribution network upgrade timelines from regional grid operators.
Macroeconomic conditions sit as an overlay; deviation in German industrial electricity pricing, copper commodity volatility, or EU-China trade tariff schedules would shift the trajectory. Forecasts reflect documented assumptions about technology transition timelines and regulatory enforcement intensity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Electric Vehicle DC Fast Charging Station Market
Electric Vehicle Charging
Electric Vehicle Charger Market
Electric Vehicle Charging
North America Electric Vehicle Charging Cable Market
Electric Vehicle Charging
Electric Vehicle (EV) Charging Station Infrastructure Market
Electric Vehicle Charging
Solar Charge Controller Market
Electric Vehicle Charging
Electric Vehicle Charger Operations and Maintenance Services Market
Electric Vehicle Charging
North America EV Charging Stations Market
Electric Vehicle Charging
Asia-Pacific Wireless Electric Vehicle Charging Market
Electric Vehicle Charging
Global Electric Vehicle (EV) Charging Service Market
Electric Vehicle Charging
EV Battery Rental and Swapping Market
Electric Vehicle Charging
Denmark Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
United States Electric Vehicle Charging Systems and Equipment Market
Electric Vehicle Charging
Solar-Based Electronic Vehicle Market
Electric Vehicle Charging
Europe Airport Electric Vehicle Charging Station Market
Electric Vehicle Charging
EV Charging Software Market
Electric Vehicle Charging
Wireless Charging Market