
 Solar Carport Charging Station Market | 2026-2036
Solar Carport Charging Station Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Carport Charging Station Market Analysis
Electrician and solar installer labor pools is bifurcating growth trajectories across the Solar Carport Charging Station Market, with certified EVSE specialists commanding premium deployment rates while general electrical contractors struggle with integrated photovoltaic-plus-storage qualifications. Tesla leverages its Supercharger network footprint to anchor utility-scale carport projects across North American retail corridors. Beam Global specializes in off-grid, transportable solar carport units that sustain municipal and disaster-relief applications without trenching or grid interconnection delays.
A solar carport charging station integrates photovoltaic canopy structures with electric vehicle supply equipment, typically mounting crystalline silicon or thin-film panels on elevated steel or aluminum framing that provides weather protection while generating 150 kW to 1 MW+ per installation site. The primary commercial purpose is dual-use land optimization, converting parking acreage into distributed generation assets that offset peak demand charges and reduce fleet electrification operating costs. Canopy and ground-mounted product types dominate current deployment volumes, though modular installation configurations are capturing margin pools in multi-site commercial rollouts where standardized foundations accelerate permitting. High-power and ultra-high-power ratings are outpacing low-power segments as fleet operators prioritize DC fast-charging throughput over Level 2 dwell-time economics.
US developers navigate IRA incentive stacking alongside NEC Article 690 solar PV codes and OSHA fall-protection mandates for elevated canopy work, while European projects face CE marking, EU Green Deal carbon-accounting requirements, and REACH compliance for aluminum structural coatings. China's MIIT dual carbon goals and GB standards for EV charging interface interoperability are accelerating domestic NEV fleet transitions that pull carport infrastructure demand through state-owned enterprise procurement channels. Stakeholders must monitor how evolving grid interconnection queue reforms and inverter-based resource ride-through requirements reshape project finance structures before committing capital to multi-year deployment pipelines.
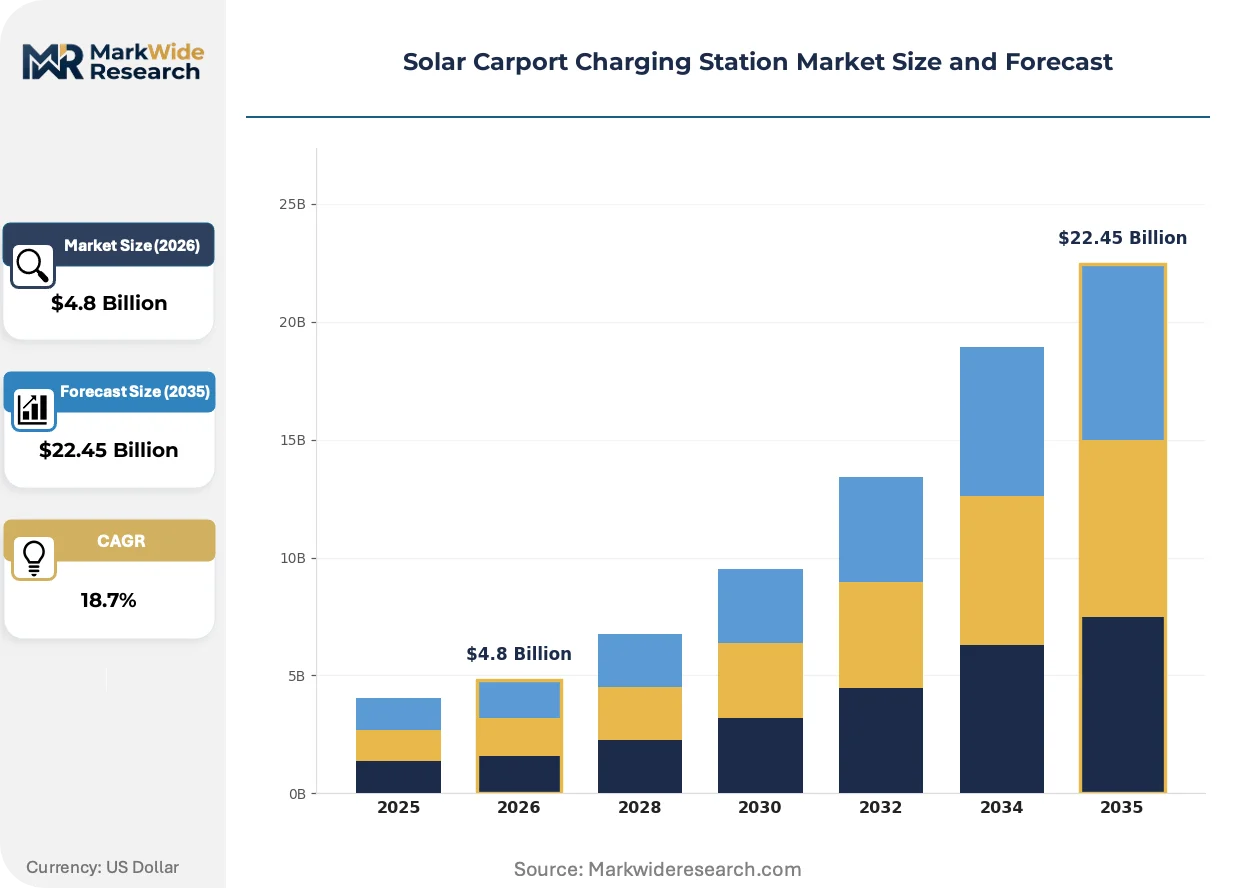
Market Dynamics
Commercial fleet electrification timelines are compressing procurement cycles for canopy-integrated solar-plus-storage systems as operators seek to defray peak demand charges through distributed generation assets sited on existing parking infrastructure.
Growth Catalysts
- US IRA Tax Credit Stacking:The Inflation Reduction Act's 30% investment tax credit for solar PV combined with alternative fuel infrastructure credits is restructuring project finance for multi-site fleet depots.
- California CPUC Mandates:The state's building code requires solar readiness on new commercial parking structures, pre-wiring installations for future EVSE integration.
- Bifacial Panel Efficiency Gains:Double-sided crystalline silicon modules are capturing reflected albedo from concrete parking surfaces, boosting yield per canopy acre.
Market Restraints
- Aluminum Tariff Volatility:Section 232 duties on imported structural aluminum are inflating canopy framing costs for domestic fabricators reliant on Canadian and Chinese supply.
- Grid Interconnection Queues:US utility-scale solar plus storage projects face 3-5 year queue delays in ERCOT and CAISO territories, freezing capital deployment timelines.
- DC Fast-Charging Standards Fragmentation:CCS1, NACS, and CHAdeMO connector coexistence is forcing redundant hardware investments at multi-tenant commercial sites.
Strategic Opportunities
- Texas ERCOT Ancillary Services:Battery-equipped carport arrays can bid frequency regulation into wholesale markets, stacking revenue streams beyond EV charging.
- Municipal Resilience Microgrids:Transportable off-grid solar carport units are serving disaster-relief staging areas and emergency response coordination points.
- EU Green Deal Carbon Accounting:Scope 3 emissions disclosure requirements are pushing logistics operators toward on-site renewable generation for fleet charging.
Industry Challenges
- EVSE-Solar Integration Certification:NEC Article 690 PV code compliance and UL 2594 EVSE safety standards require cross-trained technicians scarce in regional labor markets.
- Foundation Engineering Complexity:Geotechnical variability across asphalt-over-clay and permeable paver substrates is extending civil design timelines for standardized canopy products.
- Utility Rate Structure Uncertainty:Net metering reforms in Arizona and Nevada are eroding avoided-cost calculations that underpin project pro formas.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Carport Charging Station Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.45 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Canopy, Ground-mounted, Wall-mounted, Hybrid End User: Commercial, Residential, Municipal, Educational Installation Type: Fixed, Adjustable, Retractable, Modular Power Rating: Low-power, Medium-power, High-power, Ultra-high-power |
| Companies Covered | Beam Global, Tesla, SunPower Corporation, Schneider Electric, Enel X, Tata Power Company, Trina Solar, ABB, SMA Solar Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Carport Charging Station Market Emerging Trajectories
Power electronics and structural engineering advances are converging to reduce footprint and installation labor for canopy-mounted generation systems. Three developments are altering competitive positioning.
Solid-state transformer technology is miniaturizing medium-voltage interconnection hardware that previously required pad-mounted substations and extensive trenching. Fleet operators at constrained urban sites are adopting these compact units to avoid utility infrastructure upgrades. The technology is compressing project timelines from 18 months to under 6 months for 500 kW+ installations.
The US Department of Energy's National Electric Vehicle Infrastructure Formula Program is mandating 97% uptime reliability standards for federally funded charging stations. Program administrators are requiring predictive maintenance contracts and network interoperability certifications. Highway corridor sites in Texas and Florida are prioritizing hardware with ISO 15118 plug-and-charge compliance to minimize transaction friction.
Third-party fleet charging-as-a-service contracts are displacing capital ownership models for regional delivery operators. Logistics providers in California's Central Valley are signing 10-year power purchase agreements that bundle canopy construction, PV generation, and managed charging into per-mile rates. The structure transfers technology obsolescence risk to infrastructure developers while locking in fuel cost visibility for fleet managers.
Solar Carport Charging Station Market Segmentation
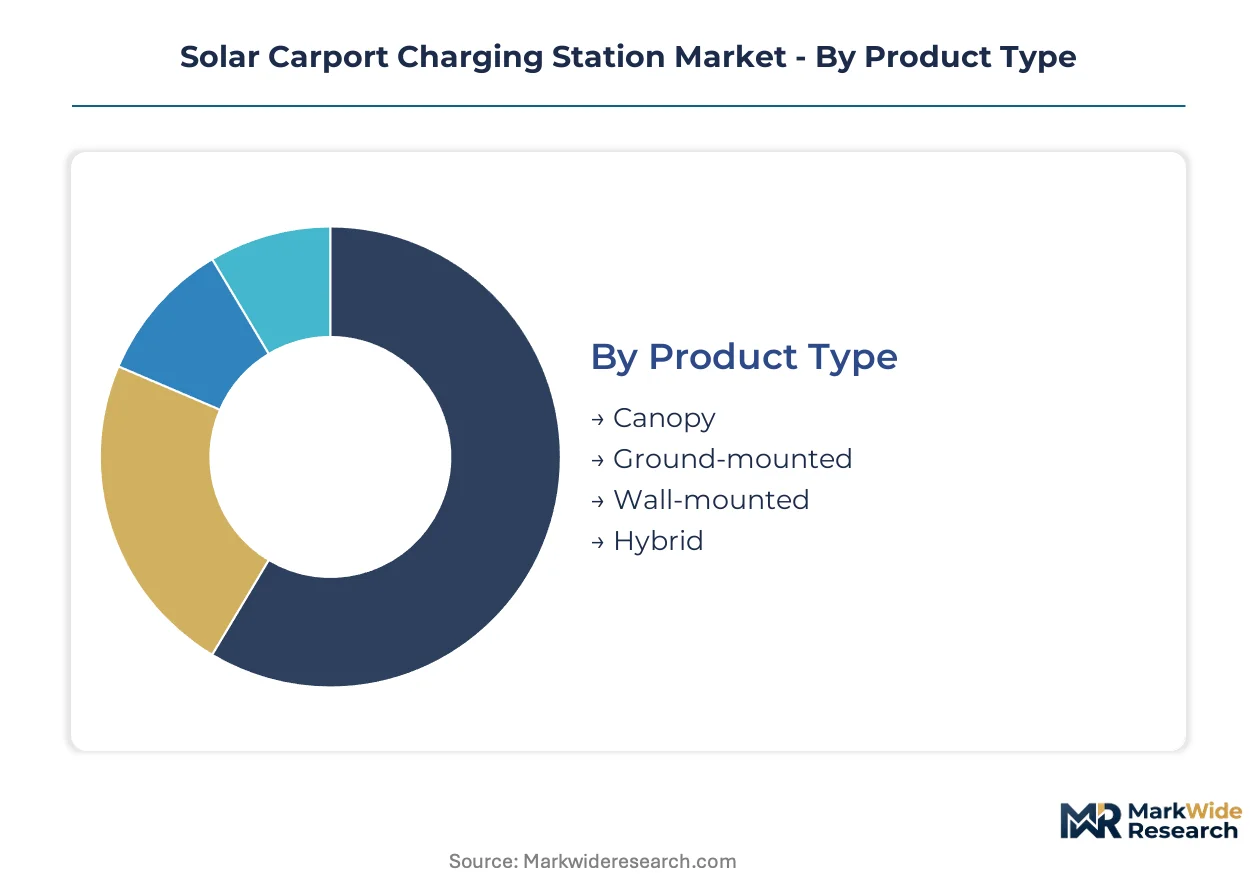
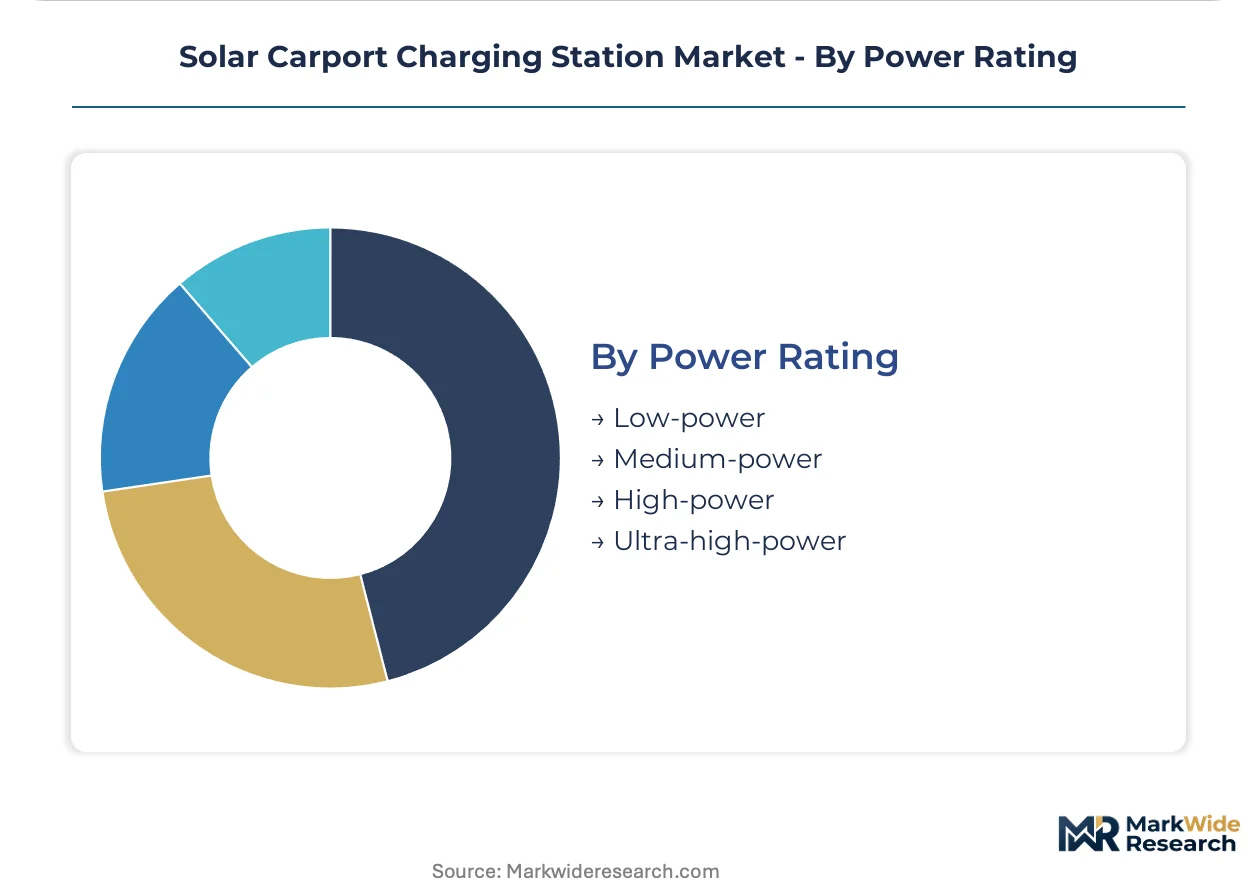
Segmentation in the Solar Carport Charging Station Market reveals how procurement channels bifurcate between fleet operators seeking integrated canopy-plus-storage systems and municipalities prioritizing transportable, off-grid configurations. Channel mix varies sharply by product architecture and power rating, with high-power DC fast-charging deployments concentrating through specialized EVSE integrators while modular installations flow through general electrical contractors.
Product Type:
Canopy systems dominate commercial fleet procurement through specialized solar-EVSE integrators, while ground-mounted and hybrid configurations reach municipalities via engineering-procurement-construction firms.
- Canopy:Elevated steel or aluminum framing supports crystalline silicon or thin-film photovoltaic modules above parking bays, delivering weather protection alongside 150 kW to 1 MW generation capacity per site. Fleet operators in California, Texas, and Florida are concentrating procurement here, driven by dual-use land optimization and IRA tax credit stacking that rewards integrated solar-plus-storage assets on existing parking infrastructure.
- Ground-mounted:Free-standing array structures occupy dedicated land parcels adjacent to parking facilities, typically deploying at logistics depots and distribution centers with surplus acreage. Demand is concentrating in Texas ERCOT territory where battery-equipped arrays bid frequency regulation into wholesale markets, stacking revenue streams beyond EV charging throughput.
- Wall-mounted:Facade-integrated photovoltaic panels attach to building exteriors with attached EVSE, serving constrained urban sites where canopy footprint is unavailable.
- Hybrid:Combined canopy and building-integrated photovoltaic systems optimize generation across multiple surfaces, capturing margin pools in multi-site commercial rollouts.
By volume, Canopy leads. By growth pace, Hybrid configurations are expanding most quickly as standardized foundations accelerate permitting across standardized multi-site deployments.
End User:
Cost tier stratification separates capital-intensive commercial fleet deployments from municipal resilience microgrids operating on constrained public budgets.
- Commercial:Fleet operators and retail property managers deploy canopy-integrated systems to defray peak demand charges through distributed generation assets sited on existing parking infrastructure. Procurement cycles are compressing as operators seek IRA incentive stacking and 10-year charging-as-a-service contracts that transfer technology obsolescence risk to infrastructure developers.
- Residential:Single-family and multi-family property owners install smaller-scale carport systems, typically at 6-20 kW capacity with Level 2 EVSE integration.
- Municipal:City governments and public agencies deploy transportable off-grid solar carport units for disaster-relief staging areas and emergency response coordination points, prioritizing units that sustain operations without trenching or grid interconnection delays.
- Educational:K-12 districts and university campuses install canopy systems to support electrified campus fleets while meeting sustainability procurement mandates.
Commercial deployments command the highest revenue per installation. Municipal applications are climbing the fastest as FEMA resilience funding and state emergency preparedness grants expand addressable infrastructure budgets.
Installation Type:
Volume concentration favors fixed foundations for standardized fleet rollouts, while margin pools shift toward adjustable and modular systems serving geotechnically variable substrates.
- Fixed:Permanent concrete pier or slab foundations anchor standardized canopy structures, dominating deployment volumes across multi-site commercial fleet depots where replication drives unit economics.
- Adjustable:Tilt-angle mechanisms optimize photovoltaic yield across seasonal sun angles, commanding premium pricing in high-latitude markets where winter generation penalties are acute.
- Retractable:Collapsible framing structures withstand extreme weather events and permit temporary site reconfiguration, serving municipal resilience applications and seasonal event venues.
- Modular:Pre-fabricated foundation and framing components accelerate permitting and reduce on-site labor, gaining share fastest in multi-site commercial rollouts where civil design standardization compresses project timelines.
Fixed installations anchor current volume. Modular configurations are gaining share fastest as standardized foundations accelerate permitting timelines and reduce geotechnical engineering variability.
Power Rating:
Customer type stratification separates fleet operators prioritizing DC fast-charging throughput from workplace and residential sites optimizing dwell-time economics.
- Low-power:Level 2 AC charging at 3-19 kW serves workplace and residential dwell-time applications where vehicles park for 4-8 hour intervals.
- Medium-power:20-49 kW DC charging bridges fleet depot and public corridor applications with moderate throughput requirements.
- High-power:50-149 kW DC fast-charging enables 30-60 minute charging sessions for commercial fleet operators and highway corridor sites. California's Central Valley logistics providers are concentrating procurement here, driven by 10-year power purchase agreements that bundle canopy construction, PV generation, and managed charging into per-mile rates.
- Ultra-high-power:150 kW and above DC fast-charging supports heavy-duty fleet electrification and corridor charging with 15-25 minute session targets. Texas and Florida highway corridor sites are prioritizing hardware with ISO 15118 plug-and-charge compliance to minimize transaction friction and meet NEVI Formula Program 97% uptime reliability standards.
High-power installations lead by current revenue contribution. Ultra-high-power systems are expanding most quickly as heavy-duty fleet electrification timelines compress and NEVI funding mandates accelerate corridor deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California fleet operators deploy canopy-integrated systems for dual-use land optimization, while German logistics hubs prioritize ground-mounted arrays with battery frequency regulation. Chinese state-owned enterprises anchor procurement volumes through MIIT dual carbon mandates, diverging from US commercial fleet electrification timelines.
United States
Commercial fleet operators in California, Texas, and Florida compress procurement cycles for canopy-plus-storage systems. IRA tax credit stacking restructures project finance across multi-site depots. California's Central Valley logistics providers sign 10-year power purchase agreements bundling canopy construction and managed charging into per-mile rates.
Germany
Logistics operators face EU Green Deal Scope 3 emissions disclosure requirements pushing on-site renewable generation. CE marking and REACH compliance for aluminum structural coatings regulate procurement. The Ruhr industrial corridor concentrates ground-mounted deployments where battery-equipped arrays bid frequency regulation into wholesale markets.
China
State-owned enterprises accelerate domestic NEV fleet transitions through MIIT dual carbon goals. GB standards for EV charging interface interoperability pull carport infrastructure demand through centralized procurement channels. Yangtze River Delta manufacturing clusters anchor canopy fabrication capacity serving fleet electrification mandates.
India
Municipal resilience applications drive transportable off-grid unit demand for disaster-relief staging areas. BIS certification requirements and state-level solar-plus-storage mandates intersect with high EV penetration corridors. Maharashtra and Gujarat industrial zones concentrate pilot deployments for logistics fleet electrification.
United Kingdom
Workplace charging schemes and fleet electrification targets compress commercial procurement timelines. CSRD carbon accounting requirements push logistics operators toward on-site generation assets. London and Southeast England anchor canopy deployments at retail corridors and distribution centers seeking dual-use land optimization.
Solar Carport Charging Station Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with consolidated canopy fabricators and EVSE integrators commanding premium deployment rates while regional electrical contractors struggle with cross-certification requirements. The market structure bifurcates between utility-scale project developers and modular transportable unit specialists. Strategic archetypes include integrated solar-plus-storage platform providers, off-grid resilience specialists, and high-throughput DC fast-charging hardware manufacturers. Competitive moves concentrate on IRA incentive-aligned project finance structuring and predictive maintenance contract bundling for NEVI uptime compliance.
Among integrated platform providers, Tesla and SunPower Corporation occupy positions spanning canopy fabrication through managed charging services, while Beam Global exemplifies the off-grid resilience archetype with transportable units. Schneider Electric and Enel X sit within the European energy services tier, anchoring project development capabilities across EU Green Deal compliance frameworks. These five companies represent the dominant competitive vectors: integrated platform scale, modular transportability, and energy services bundling.
| Leading Market Players |
|---|
| Beam Global |
| Tesla |
| SunPower Corporation |
| Schneider Electric |
| Enel X |
| Tata Power Company |
| Trina Solar |
| ABB |
| SMA Solar Technology |
| Others |
Supply Flow & Price Mechanics
UL 2703 certification for solar mounting systems gates supplier qualification while simultaneously stratifying price tiers across canopy-integrated installations, forcing fabricators to absorb testing costs or cede share to certified incumbents. The interaction between certification burden and procurement scale is compressing margins for mid-tier electrical contractors while rewarding integrated platform providers with volume leverage.
Pricing Analysis
Long-term power purchase agreements dominate fleet operator procurement, bundling canopy construction, photovoltaic generation, and managed charging into per-mile rates that transfer technology obsolescence risk to infrastructure developers. Price differentiation rests on NEC Article 690 compliance tier and after-sales predictive maintenance bundling for NEVI uptime requirements. Cost compression in standard canopy configurations is intensifying because aluminum tariff volatility and grid interconnection queue delays are freezing capital deployment timelines. Municipal buyers exhibit highest price sensitivity due to constrained FEMA resilience budgets, while commercial fleet operators prioritize throughput reliability over unit cost.
Supply Chain Analysis
Strait of Malacca transit underwrites crystalline silicon module delivery schedules to Southeast Asian fabrication hubs, creating logistics vulnerability for canopy-integrated projects with compressed procurement cycles. Manufacturing gravity centers on China for photovoltaic cells, Vietnam for module assembly, and domestic US fabricators for structural aluminum framing. Raw material dependencies span polysilicon feedstock, aluminum structural extrusions, and solid-state transformer components. Single-source vulnerability concentrates in Chinese polysilicon refining capacity. Distribution runs through specialized solar-EVSE integrators for high-power deployments and general electrical contractors for modular installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity is emerging as fleet electrification timelines bifurcate between utility-scale canopy developers and transportable off-grid specialists, creating niche margin pools for cross-certified providers.
For Market Incumbents: Secure NEC Article 690 and UL 2594 cross-certification pipelines to defend against emerging EVSE-solar integrators poaching multi-site fleet contracts. Anchor capacity additions in Texas ERCOT and California CAISO territories where frequency regulation revenue stacking justifies battery-equipped canopy investments. Vertical integration into solid-state transformer sourcing compresses project timelines from 18 months to under 6 months for constrained urban sites. For New Entrants and Emerging Players: Predictive maintenance service gaps where incumbents under-serve NEVI Formula Program uptime requirements offer immediate white-space entry. Municipal resilience microgrids in FEMA-funded disaster corridors represent the most penetrable segment given transportable unit demand acceleration. A charging-as-a-service go-to-market angle transfers capital burden to infrastructure developers while capturing recurring revenue visibility. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across modular installation configurations as standardized foundations reduce geotechnical engineering variability. Acquisition targets should screen for cross-certified technician pools and established utility interconnection relationships rather than pure hardware fabrication. The signal to watch is grid interconnection queue reform progress in ERCOT and CAISO territories as inflection indicator for capital deployment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Cross-Certification Investment | NEC Article 690 and UL 2594 dual qualification opens multi-site fleet procurement channels. |
| Frequency Regulation Stacking | Texas ERCOT ancillary services bidding creates revenue streams beyond EV charging throughput. |
| Solid-State Transformer Adoption | Compact medium-voltage hardware avoids utility infrastructure upgrades at constrained urban sites. |
| Predictive Maintenance Bundling | NEVI Formula Program 97% uptime mandates require ISO 15118-compliant service contracts. |
| Modular Foundation Standardization | Pre-fabricated components accelerate permitting across geotechnically variable substrates. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of EIA project databases, FERC interconnection filings, and IRA incentive guidance documents to validate deployment timelines and capital structures. Primary interviews engaged fleet electrification managers, solar EPC contractors, utility interconnection planners, and EVSE integration specialists. Secondary sources span SEC 10-K disclosures from listed canopy fabricators, NEVI Formula Program administrative records, and state-level building code amendments. Bottom-up installation counts triangulate against top-down incentive allocation estimates across the analysis window.
Segmentation dimensions modeled include product architecture, power rating tier, installation type, and end-user category across the projection horizon. CAGRs derive from capacity-weighted average deployment velocities and incentive-adjusted payback period sensitivity. Industry-specific forecast inputs incorporate IRA tax credit stacking eligibility windows and utility rate structure reform scenarios in Arizona and Nevada.
Underlying assumptions cover continued IRA incentive continuity, aluminum tariff stability, and grid interconnection queue progression, with deviation risk concentrated in NEC code amendments and NEVI uptime standard enforcement. Practitioners should keep alternative scenarios live as FEMA resilience funding allocations and state-level solar-plus-storage mandates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
South Korea Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Electric Vehicle (EV) Charging Infrastructure Market
Electric Vehicle Charging
North America Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
North America EV Charging Stations Market
Electric Vehicle Charging
Two Wheel Electric Vehicle Charger Market
Electric Vehicle Charging
Home EV Chargers Market
Electric Vehicle Charging
Airport Charging Stations Market
Electric Vehicle Charging
Norway Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Electric Vehicle Charging System Market
Electric Vehicle Charging
EV DC Fast Charger Market
Electric Vehicle Charging
Engineered Polymers in Electric Charging Infrastructure Market
Electric Vehicle Charging
Electric Vehicle Charging Adapter Market
Electric Vehicle Charging
Electric Vehicle Supply Equipment (EVSE) Market
Electric Vehicle Charging
Bidirectional EV Charger and V2X Grid Integration Test Systems Market
Electric Vehicle Charging
Australia Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Electric Vehicle Quick Charging Station Market