
 Transmission Overload Protectors Market | 2026-2036
Transmission Overload Protectors Market Size, Share, and Industry Trends Forecast 2026-2036
Transmission Overload Protectors Market Analytics
Utility procurement is unwinding from conventional fuse-based architectures toward electronic and smart sensor technologies. Eaton Corporation leverages its vertical integration into semiconductor-grade trip units to sustain margin pools in North American utility contracts. Siemens AG anchors European demand through IEC-certified product lines that dominate German industrial machinery retrofits. ABB Ltd. competes across renewable energy applications with thermal-electronic hybrid designs that navigate stringent grid-code requirements in China and India.
Transmission overload protectors are electromechanical or electronic safety devices engineered to interrupt power flow when current exceeds calibrated thresholds, typically rated between milliamps and kiloamps depending on application voltage class. These devices serve the primary commercial purpose of preventing thermal damage to motors, transformers, and distribution lines while maintaining grid stability. Circuit breakers occupy the largest value share due to reusable operation cycles, though smart sensor-integrated protectors represent the fastest-expanding margin pool as OEMs demand predictive diagnostic capability. Motor starters remain structurally mature with replacement-driven demand concentrated in legacy industrial machinery fleets across North America and Europe.
The US National Electrical Code administered by NFPA shapes product certification requirements for overload protectors deployed in industrial and commercial installations. IEC 60947 standards govern European market access, while China's GB 14048 series mandates specific breaking capacity tests for domestic electromechanical protector sales. India's BIS certification and the PLI scheme for domestic manufacturing are tightening compliance pathways for imported electronic protection devices. Stakeholders must monitor divergence between regional smart grid interoperability standards before committing to platform-specific R&D roadmaps.
Market Dynamics
OEM procurement unwinding from pure electromechanical specifications toward smart sensor-integrated systems is compressing replacement cycles and forcing component suppliers to absorb semiconductor content costs.
Growth Catalysts
- IEC 60947 trip-curve tolerances:Tightened European standards for industrial machinery retrofits are mandating precision-calibrated protectors that command higher unit values and accelerate fleet replacement schedules.
- Grid modernization investments:Utility capital deployment across Germany, China, and the United States is expanding substation automation budgets and creating dedicated procurement channels for electronic protection devices.
- Factory automation acceleration:Motor control center upgrades in automotive and food processing plants are specifying integrated thermal-electronic hybrids with predictive diagnostic capability.
Market Restraints
- Copper and silver contact volatility:Electromechanical protector manufacturers face margin compression from precious metal price swings in breaker contact assemblies, with limited pass-through power in utility contracts.
- Semiconductor supply concentration:Smart sensor-integrated trip units depend on concentrated Asian foundry capacity, creating lead time vulnerability for North American and European OEM qualification programs.
- Fuse-based architecture persistence:Legacy industrial machinery fleets in mature economies retain fuse protection due to maintenance staff familiarity and minimal capital requirements, slowing electronic conversion.
Strategic Opportunities
- Renewable energy grid-code requirements:Wind and solar interconnection standards in China and India are mandating bidirectional fault protection that thermal-electronic hybrid designs uniquely satisfy.
- India PLI scheme for domestic manufacturing:Production-linked incentives for electronic components are creating local assembly pathways that reduce import duty exposure for smart protector platforms.
- Edge computing convergence:Integration of overload protection data with facility energy management systems is opening software-recurring revenue models for hardware suppliers.
Industry Challenges
- IEC-NEMA certification divergence:Product teams must maintain parallel testing protocols for European and North American markets, extending launch timelines and engineering overhead.
- Legacy motor starter integration:Electronic protectors face mechanical incompatibility with existing contactor coils in retrofits, requiring custom adapter development per OEM specification.
- Field service skill gaps:Electromechanical technician workforces lack training on semiconductor-grade trip unit diagnostics, constraining aftermarket service network expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transmission Overload Protectors Market |
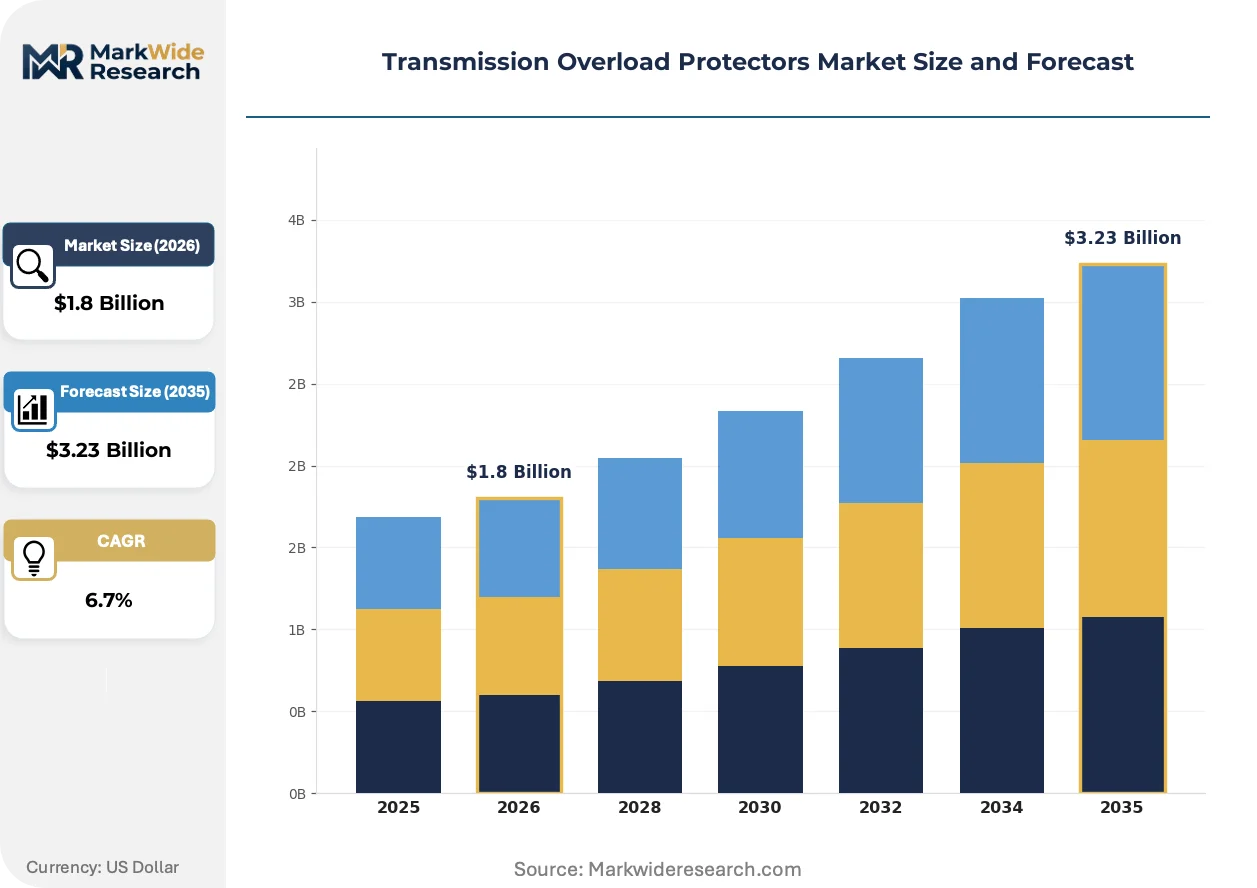
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Circuit Breakers, Fuse Protectors, Overcurrent Relays, Motor Starters Application: Industrial Machinery, Automotive, HVAC Systems, Renewable Energy End User: Manufacturers, Contractors, Utilities, OEMs Technology: Electronic, Electromechanical, Thermal, Smart Sensors |
| Companies Covered | Eaton Corporation, Mitsubishi Electric Corporation, Siemens AG, Fuji Electric Co., Ltd., Rockwell Automation, Inc., ABB Ltd., General Electric Company, Bondioli & Pavesi S.p.A., Schneider Electric SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transmission Overload Protectors Market Evolving Landscape
Smart sensor integration is compressing the traditional separation between protection hardware and condition monitoring software, collapsing procurement categories and redrawing supplier relationships across industrial electrical equipment.
Microprocessor-based electronic trip units with embedded current transformers and temperature sensing are supplanting traditional bimetallic thermal elements in motor protection applications. Automotive battery plant operators and data center power distribution buyers are specifying these platforms for reset precision and communication protocol compatibility. The shift is compressing margins for pure electromechanical specialists while rewarding semiconductor-capable suppliers with multi-year service contract attachments.
China's GB 14048 series mandates specific breaking capacity tests for domestic electromechanical protector sales, creating a certification barrier that foreign manufacturers must navigate through joint ventures or local testing partnerships. The standard's thermal endurance requirements exceed IEC baselines for certain voltage classes, forcing design modifications for market access. Domestic Chinese suppliers leverage this friction to defend position in state-owned utility procurement where GB compliance is non-negotiable.
Buyer concentration among industrial conglomerates with centralized engineering standards is consolidating supplier relationships around full-line electrical equipment portfolios. Discrete overload protector specialists face exclusion from approved vendor lists that favor integrated motor control and protection platforms. This pattern is most pronounced in German automotive manufacturing and US oil and gas processing, where procurement teams prioritize single-source accountability over component-level optimization.
Transmission Overload Protectors Market Segmentation
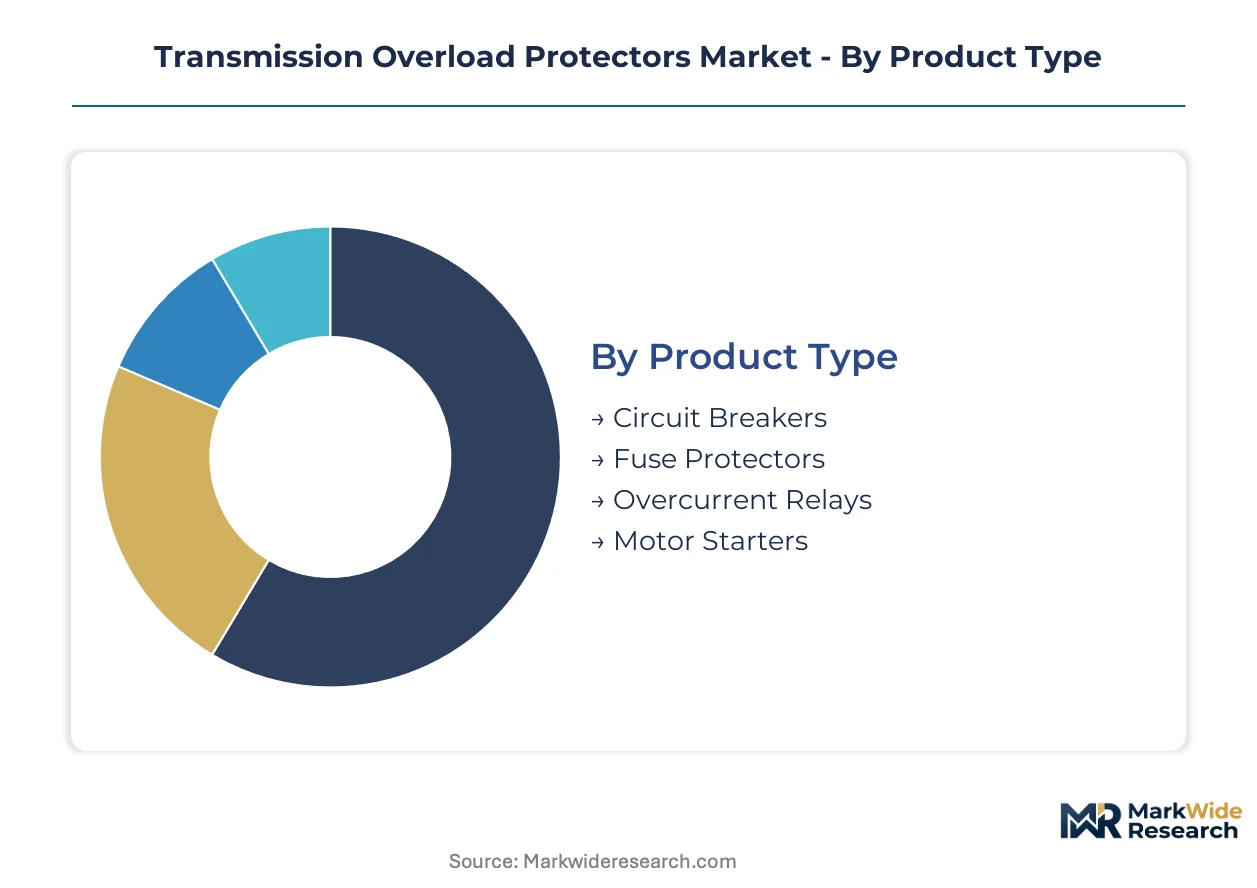
Overload protector procurement patterns diverge sharply across product architectures and end-use contexts. Segment-specific certification requirements and technology substitution timelines create distinct margin profiles that suppliers must navigate.
Product Type:
Domestic assembly concentrates on electromechanical platforms for replacement markets, while export-led demand pulls electronic and smart-integrated units toward German and Chinese industrial clusters.
- Circuit Breakers:Reusable trip mechanisms with calibrated thermal-magnetic or electronic actuation dominate installed base maintenance. German automotive plants and US data centers specify these for reset precision and reduced downtime. IEC 60947 precision tolerances are accelerating fleet replacement in European industrial machinery.
- Motor Starters:Integrated contactor-overload combinations protect three-phase motors across legacy manufacturing footprints. North American food processing and metalworking facilities drive replacement demand where electromechanical technician familiarity sustains fuse-compatible architectures.
- Fuse Protectors:Single-use thermal cutoff devices retain cost advantage in low-duty agricultural and residential applications.
- Overcurrent Relays:Precision detection elements coordinate with upstream breakers in utility substation protection schemes.
Circuit breakers command the established base. The steepest expansion runs through motor starters with embedded smart sensor platforms.
Application:
Cost tier stratification separates premium-specified renewable energy installations from standard industrial machinery retrofits and economy-tier HVAC replacements.
- Industrial Machinery:Motor control centers in automotive stamping plants and chemical processing facilities demand thermal-electronic hybrids with predictive diagnostic capability. German machinery OEMs specify IEC-certified platforms with tightened trip-curve precision for export markets.
- Renewable Energy:Wind turbine generator protection and solar inverter integration require bidirectional fault detection compliant with China's GB grid codes and India's CEA interconnection standards. Thermal-electronic hybrid designs navigate these stringent requirements.
- Automotive:Battery plant power distribution and EV charging infrastructure specify microprocessor-based units with communication protocol compatibility.
- HVAC Systems:Commercial building automation drives replacement cycles for compact electromechanical protectors in compressor and fan motor applications.
Industrial machinery absorbs the highest unit volumes. Renewable energy applications are climbing the fastest as grid-code mandates proliferate.
End User:
Customer type determines procurement channel structure, with centralized utility buyers demanding multi-year service attachments and fragmented contractor markets prioritizing inventory availability.
- Utilities:Transmission and distribution operators across Germany, China, and the United States deploy capital toward substation automation and electronic protection device upgrades. FERC-interfaced procurement in the US and state-owned utility frameworks in China create divergent qualification pathways.
- OEMs:Integrated motor control platform manufacturers consolidate supplier relationships around full-line electrical equipment portfolios. German automotive manufacturing and US oil and gas processing prioritize single-source accountability.
- Manufacturers:In-house facility engineering teams specify protectors for production line motor control centers.
- Contractors:Electrical installation firms stock electromechanical units for maintenance-driven replacement in legacy industrial footprints.
Utilities anchor the highest-value procurement. OEMs are gaining share fastest through platform consolidation and embedded smart sensor specifications.
Technology:
Supply concentration in Asian semiconductor foundries shapes availability timelines for advanced trip units, while electromechanical production disperses across regional metalworking clusters.
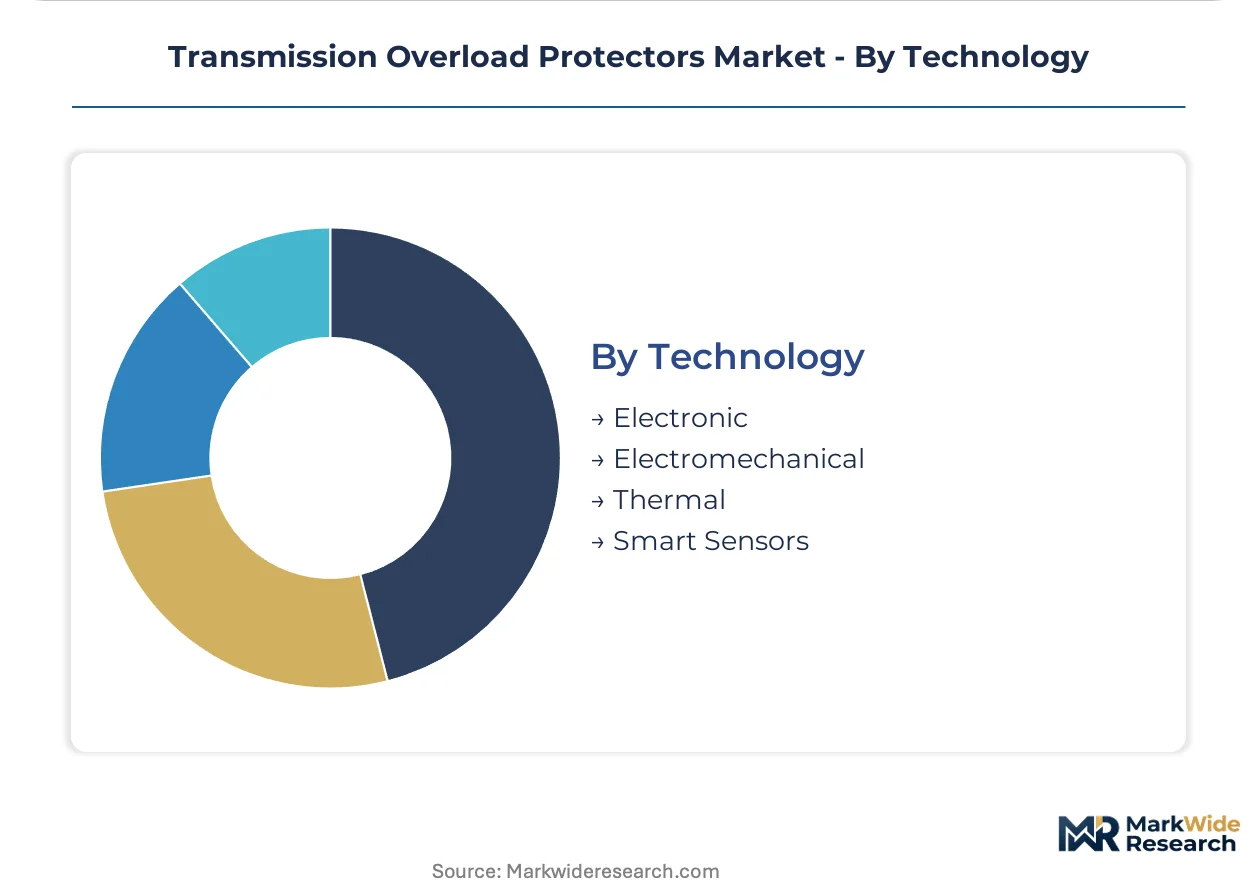
- Smart Sensors:Microprocessor-based units with embedded current transformers and temperature sensing collapse the boundary between protection hardware and condition monitoring software. Data center power distribution and automotive battery plant operators specify these platforms for communication protocol compatibility and multi-year service contract attachments.
- Electronic:Solid-state trip units with precise calibration and reset capability displace bimetallic elements in precision motor protection applications.
- Thermal:Bimetallic strip actuation retains position in cost-sensitive HVAC and residential applications with minimal cycling requirements.
- Electromechanical:Solenoid and thermal-magnetic mechanisms dominate replacement demand in legacy industrial machinery fleets where maintenance staff familiarity constrains technology conversion.
Electromechanical platforms retain the installed base. Smart sensor integration is expanding most quickly as OEMs demand predictive diagnostic capability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The German transmission grid interconnects with ten neighboring countries through high-voltage direct current links, creating Europe's densest protection device procurement corridor. China's ultra-high voltage backbone stretches 40,000 kilometers and mandates bidirectional fault protection for every interconnection node. The United States Eastern Interconnection serves 265 million people across 31 states and requires continuous overload protector upgrades for aging substation infrastructure.
Germany
Industrial machinery retrofits in automotive stamping plants and chemical processing facilities drive precision-calibrated protector demand. IEC 60947 tightened trip-curve tolerances mandate fleet replacement across legacy manufacturing footprints. The Ruhr industrial cluster and Bavarian automotive belt concentrate procurement for thermal-electronic hybrid units with predictive diagnostic capability.
China
State-owned utility frameworks deploy capital toward 14th Five-Year Plan grid modernization targets spanning ultra-high voltage corridors. GB 14048 series mandates specific breaking capacity tests exceeding IEC baselines for domestic electromechanical protector sales. Yangtze River Delta manufacturing hubs and Pearl River Delta export zones pull smart sensor-integrated units toward industrial automation clusters.
United States
FERC-interfaced procurement channels expand substation automation budgets across the Eastern and Western Interconnections. NFPA-administered National Electrical Code shapes certification requirements for industrial and commercial overload protector installations. Texas ERCOT grid isolation and California renewable interconnection mandates create divergent specification pathways for thermal-electronic hybrid designs.
India
Wind turbine generator protection and solar inverter integration require bidirectional fault detection compliant with CEA interconnection standards. PLI scheme production-linked incentives for electronic components create local assembly pathways reducing import duty exposure. Gujarat solar parks and Tamil Nadu wind corridors concentrate renewable energy grid-code compliance procurement.
Japan
Automotive battery plant power distribution and precision motor control centers specify microprocessor-based units with communication protocol compatibility. METI industrial standards govern semiconductor-grade trip unit certification for factory automation upgrades. Kanto manufacturing belt and Nagoya automotive cluster anchor demand for reset-precision electronic protection platforms.
Transmission Overload Protectors Market Competitive Landscape
Concentration sits with diversified electrical equipment conglomerates maintaining full-line portfolios across protection, control, and distribution hardware. The vendor base stratifies into three tiers: integrated platform manufacturers commanding multi-year utility contracts, component specialists serving replacement markets, and emerging Asian fabricators competing on domestic certification compliance. Two dominant competitive moves reshape positioning: backward integration into semiconductor-grade trip unit production to capture smart sensor margins, and joint venture formation with state-owned utilities to satisfy local content requirements in China and India.
Among Germany-based industrial conglomerates, Siemens AG exemplifies the integrated platform archetype through IEC-certified product lines. US-based diversified manufacturers like Eaton Corporation and Rockwell Automation, Inc. occupy positions within the North American utility and factory automation procurement channels. Japanese electrical equipment specialists including Mitsubishi Electric Corporation and Fuji Electric Co., Ltd. represent the precision-manufacturing tier serving automotive and semiconductor facility applications.
| Leading Market Players |
|---|
| Eaton Corporation |
| Mitsubishi Electric Corporation |
| Siemens AG |
| Fuji Electric Co., Ltd. |
| Rockwell Automation, Inc. |
| ABB Ltd. |
| General Electric Company |
| Bondioli & Pavesi S.p.A. |
| Schneider Electric SE |
| Others |
Value Network & Pricing Analysis
Twenty-six-week lead times for semiconductor-grade trip units concentrate pricing power with Asian foundry suppliers while forcing European and North American OEMs to absorb inventory carrying costs or sacrifice margin through expedited freight. This supply-chain rigidity amplifies price premiums for smart sensor-integrated protectors and compresses negotiable space in utility procurement contracts.
Pricing Analysis
Volume-discount tiering separates multi-year utility framework agreements from spot purchases by electrical contractors. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and after-sales service bundling. Cost compression in electromechanical platforms intensifies because copper and silver contact volatility limits pass-through power. Contractors stocking replacement inventory exhibit highest price sensitivity; data center operators specifying predictive diagnostic capability show lowest.
Supply Chain Analysis
Strategic stockpiling of semiconductor-grade components dominates procurement behavior as foundry capacity constraints persist, contrasting with just-in-time metalworking inputs for electromechanical assembly. Manufacturing concentrates in China, Germany, and the United States. Production draws from concentrated Asian semiconductor foundries, copper contact suppliers in Chile and Zambia, and precision metalworking clusters in Central Europe. Single-source vulnerability in trip unit chipsets threatens qualification timelines. Distribution runs through authorized electrical distributor networks serving contractor replacement markets and direct OEM supply agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from predictive diagnostic platforms and multi-year calibration contracts is expanding faster than hardware unit sales, reframing competitive advantage around software-recurring models rather than component volume.
For Market Incumbents: Consolidate backward integration into semiconductor-grade trip unit production to capture smart sensor margins and reduce foundry dependency. Secure IEC-NEMA dual certification capacity to compress launch timelines against certification-divergence friction. Anchor aftermarket service networks with technician training programs addressing field diagnostic skill gaps.
For New Entrants and Emerging Players: Anchor in India's PLI scheme assembly pathways to bypass import duty exposure and serve Gujarat solar park and Tamil Nadu wind corridor procurement. Target renewable energy grid-code compliance as the most penetrable segment where thermal-electronic hybrid designs face limited incumbent saturation. Pursue joint venture formation with state-owned utilities to satisfy local content requirements.
For Investors and Strategic Acquirers: Long-term, this sits as a grid-modernization infrastructure play because substation automation capital deployment across Germany, China, and the United States sustains replacement-cycle visibility independent of industrial cyclicality. Acquisition targets should display captive semiconductor sourcing or established utility framework relationships. Monitor divergence between regional smart grid interoperability standards as inflection indicator for platform-specific R&D commitment levels.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Semiconductor Trip Units | Captures smart sensor margins and reduces foundry lead-time vulnerability for North American OEM qualification programs. |
| IEC-NEMA Dual Certification Investment | Compresses product launch timelines amid tightening European trip-curve tolerances and NFPA electrical code divergence. |
| Joint Venture with State-Owned Utilities | Secures local content compliance for China's GB 14048 series and India's CEA interconnection standard procurement channels. |
| Technician Training Network Expansion | Addresses field service skill gaps constraining aftermarket penetration in legacy electromechanical fleet maintenance. |
| Predictive Diagnostic Platform Development | Opens software-recurring revenue models through edge computing convergence with facility energy management systems. |
Research Methodology
Desk research of IEC and NEMA standard filings, utility procurement databases, and semiconductor foundry capacity disclosures preceded structured interviews with utility protection engineers, OEM motor control platform managers, electrical distributor category buyers, and aftermarket service technicians. Primary fieldwork combined with secondary validation from customs trade data, SEC electrical equipment segment disclosures, and state-owned utility capital expenditure reports. Bottom-up unit shipment estimates triangulated against top-down grid modernization investment flows.
Variance decomposition across product architecture, application voltage class, and end-user procurement channel shaped the analytical framework over the projection horizon. CAGRs derived from segmented replacement-cycle modeling and technology substitution timelines. Forecast inputs incorporated foundry capacity expansion announcements, PLI scheme disbursement schedules, and renewable energy interconnection mandate proliferation rates.
Decision-makers should treat outputs as directional under assumptions of continued grid modernization capital deployment and stable semiconductor supply concentration; material deviation in foundry capacity allocation or regulatory standard harmonization would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Orifice Reducers Market
Valves
Global Thermostatic Radiator Valve Market
Valves
China Explosion-Proof Equipment Market
Valves
Steam Trap Market
Valves
Leak Detection Market
Valves
Europe Butterfly Valve Market
Valves
North America High Voltage Switchgear Market
Valves
Global Fluid Management Systems Market
Valves
Global Industrial Thermostatic Control Valves Market
Valves
Mobile Hydraulic Valves Market
Valves
Pinch Valve Market
Valves
Choke and Kill Manifold Market
Valves
Gas Equipment Market
Valves
Total Containment Vessels Market
Valves
Pipeline and Process Services Market
Valves
Reciprocating Compressor Components Market