
 Battery Light Towers Market | 2026-2036
Battery Light Towers Market Size, Share, and Industry Trends Forecast 2026-2036
Battery Light Towers Market Insights
Event rental fleets and remote mining operators is rotating toward battery light towers as diesel cost volatility and noise ordinances reshape procurement criteria. Generac Power Systems leverages its vertically integrated generator manufacturing to offer hybrid-battery configurations that bridge runtime gaps. Atlas Copco sustains technology leadership through its proprietary energy management systems that optimize lithium-ion discharge cycles. Wacker Neuson anchors European demand with compact battery units engineered for urban construction zones with strict decibel limits.
Battery light towers are self-contained illumination systems integrating photovoltaic panels, lithium-ion battery banks, and high-efficiency LED arrays to deliver off-grid lighting without combustion engines or grid connectivity. Units typically achieve 50,000+ hour LED lifespans and operate at under 65 decibels, serving construction sites, mining operations, emergency response zones, and outdoor events where emissions compliance and acoustic control matter. LED light towers command the dominant revenue share due to their energy efficiency and longevity, while hybrid light towers represent the fastest-expanding category as buyers seek to eliminate range anxiety during extended deployments. Site illumination applications generate the deepest margin pools because infrastructure contractors prioritize total cost of ownership over upfront capital expenditure.
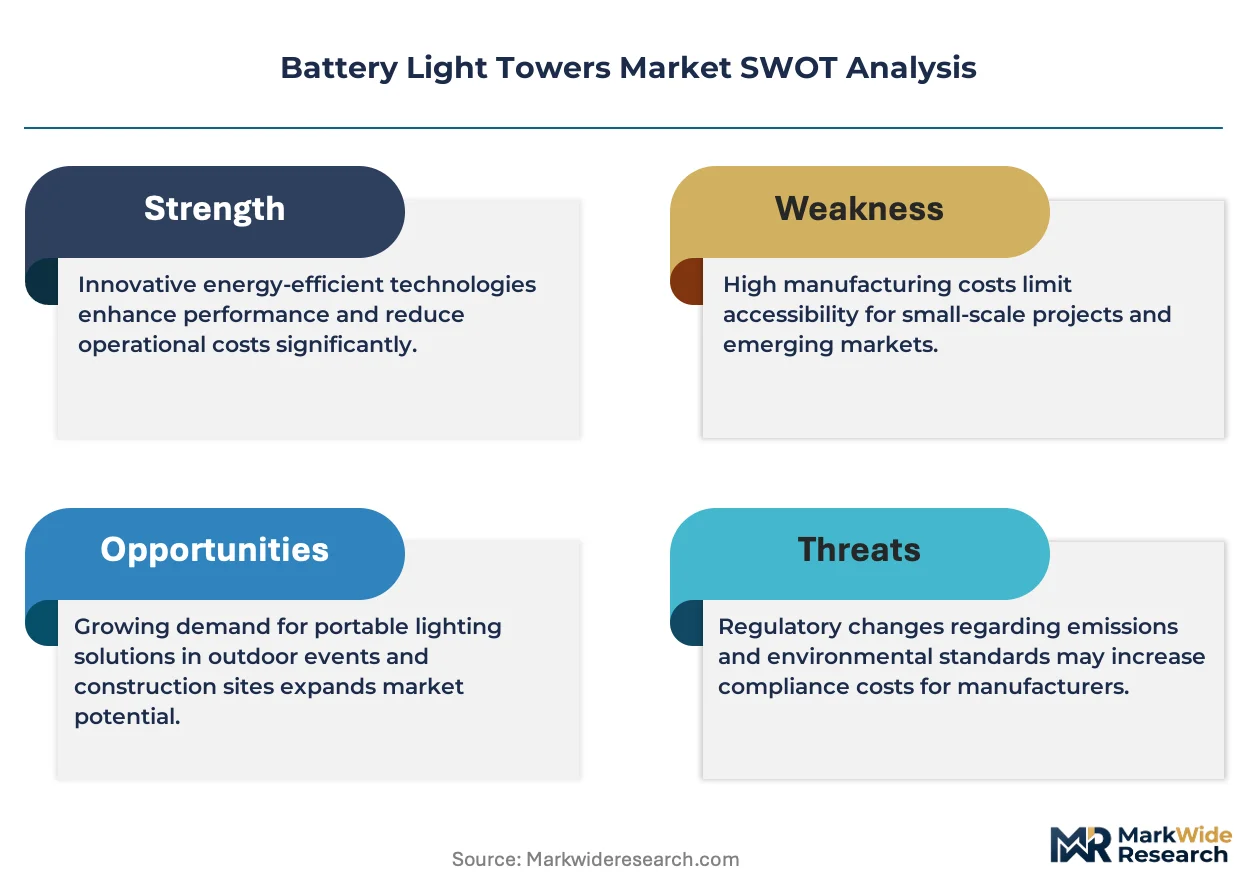
EPA emission standards for non-road diesel engines in the United States and EU Stage V regulations administered by ECHA compel fleet operators to evaluate zero-emission alternatives, directly expanding addressable demand for battery-powered units. OSHA workplace noise exposure limits further restrict diesel generator deployment in enclosed or densely populated work zones, creating regulatory tailwinds for silent battery systems. Stakeholders must monitor lithium supply contract structures and regional battery recycling mandates as these factors will determine total cost of ownership calculations and vendor selection criteria.
Market Dynamics
EPA emission standards for non-road diesel engines and EU Stage V regulations administered by ECHA are compelling fleet operators toward zero-emission alternatives, restructuring procurement criteria across construction, mining, and event rental sectors.
Growth Catalysts
- OSHA workplace noise exposure limits:These restrictions suppress diesel generator deployment in enclosed work zones, accelerating silent battery system adoption across US infrastructure projects.
- Lithium-ion discharge optimization:Proprietary energy management systems now extend operational runtime, making battery units viable for multi-shift mining operations in Western Australia's Pilbara region.
- Diesel cost volatility:Fuel price uncertainty is rotating event rental fleet procurement toward battery-powered inventory to stabilize total cost of ownership calculations.
Market Restraints
- Lithium supply contract concentration:Raw material sourcing bottlenecks in Chile and Australia create input cost volatility that compresses vendor margin structures.
- Range anxiety in extended deployments:Battery capacity limitations force hybrid configurations for remote site electrification, inflating upfront capital requirements versus pure diesel alternatives.
- EU battery recycling mandates:Extended producer responsibility frameworks under ECHA guidance add compliance overhead to total cost of ownership calculations for European fleet operators.
Strategic Opportunities
- Urban construction decibel limits:Compact battery units engineered for strict acoustic controls are penetrating European city centers where diesel deployment faces municipal prohibition.
- Photovoltaic-battery convergence:Integrated solar charging arrays are opening off-grid applications in emergency response zones lacking generator fuel logistics.
- India's PLI scheme for advanced chemistry cells:Domestic battery manufacturing incentives are lowering landed costs for South Asian infrastructure contractors evaluating fleet electrification.
Industry Challenges
- Field technician electrification competency:Maintenance crews trained on combustion generator repair require reskilling for lithium-ion diagnostics and high-voltage safety protocols.
- Multi-standard certification timelines:Simultaneous EPA, CE marking, and ISO compliance testing extends product launch cycles by 8-14 months for multi-regional vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery Light Towers Market |
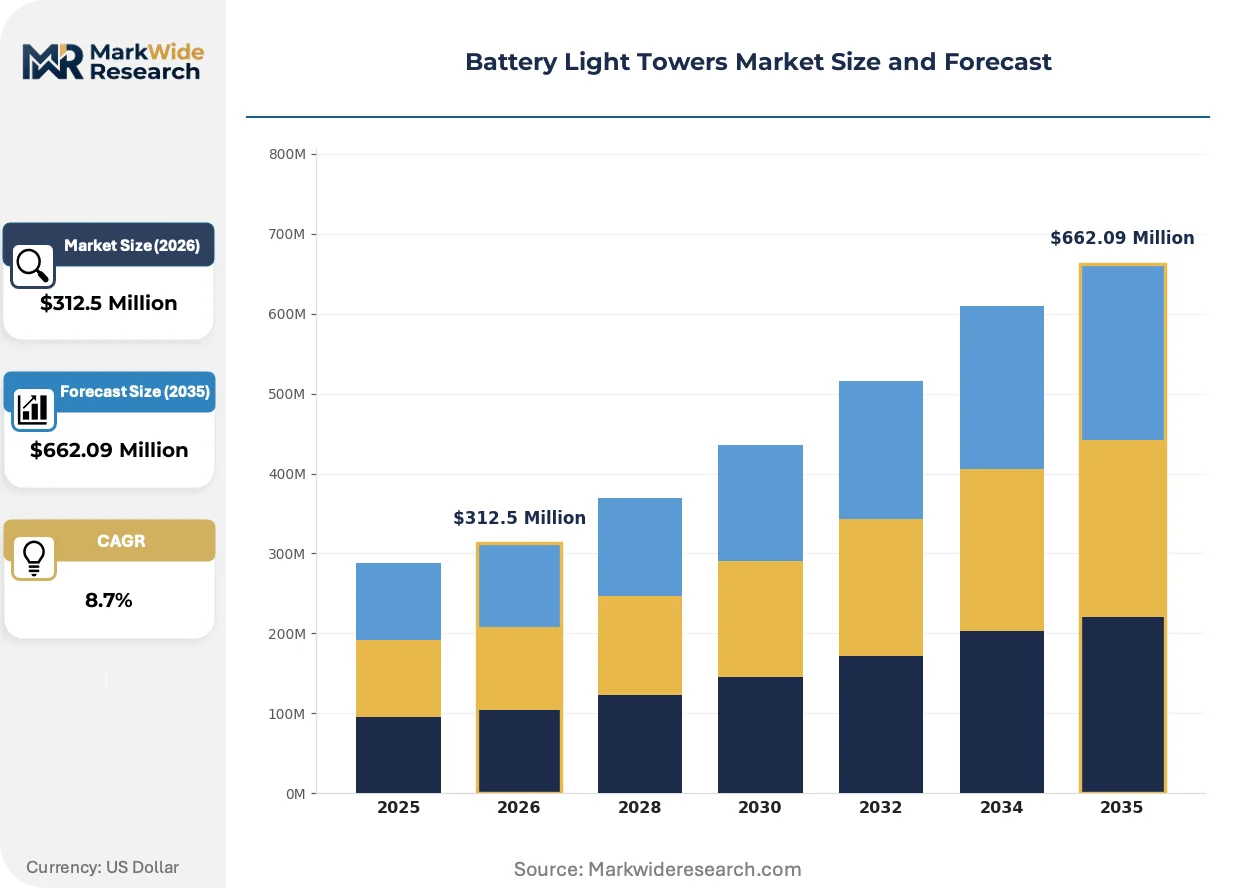
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $662.09 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Light Towers, Fixed Light Towers, LED Light Towers, Hybrid Light Towers End User: Construction, Events, Mining, Emergency Services Technology: Solar Power, Diesel Power, Battery Power, Hybrid Technology Application: Site Illumination, Emergency Lighting, Outdoor Events, Security Lighting |
| Companies Covered | Generac Power Systems, Atlas Copco, Terex Corporation, Wacker Neuson, Doosan Portable Power, Larson Electronics, United Rentals, JCB, Progress Solar Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery Light Towers Market Trends and Innovations
Active differentiation in battery light tower architectures is fragmenting competitive positioning as vendors pursue divergent technical strategies around energy density, charging speed, and hybrid integration depth.
Lithium iron phosphate chemistry is fragmenting the premium segment from conventional lithium-ion offerings through superior thermal stability and extended cycle life. Mining operators in Australia's Pilbara iron ore region are specifying LFP configurations for 24-hour continuous operation in extreme ambient temperatures. This chemistry shift is fragmenting vendor R&D allocation between energy density optimization and safety certification pathways.
EPA Tier 4 Final and EU Stage V emission standards are eliminating new diesel generator sales in regulated jurisdictions, forcing rental fleet operators to accelerate battery unit procurement. Construction contractors in Germany's Rhine-Ruhr metropolitan zone face municipal diesel bans that compress replacement timelines. Equipment lessors are responding with guaranteed residual value programs to absorb buyer technology risk.
Total cost of ownership contracting is displacing capital purchase models in North American infrastructure procurement. Large-scale contractors now demand performance-based illumination service agreements with guaranteed uptime metrics. This financing shift is most visible in Texas energy corridor projects where EPC firms bundle lighting services into integrated site preparation contracts rather than owning depreciating assets.
Battery Light Towers Market Segmentation
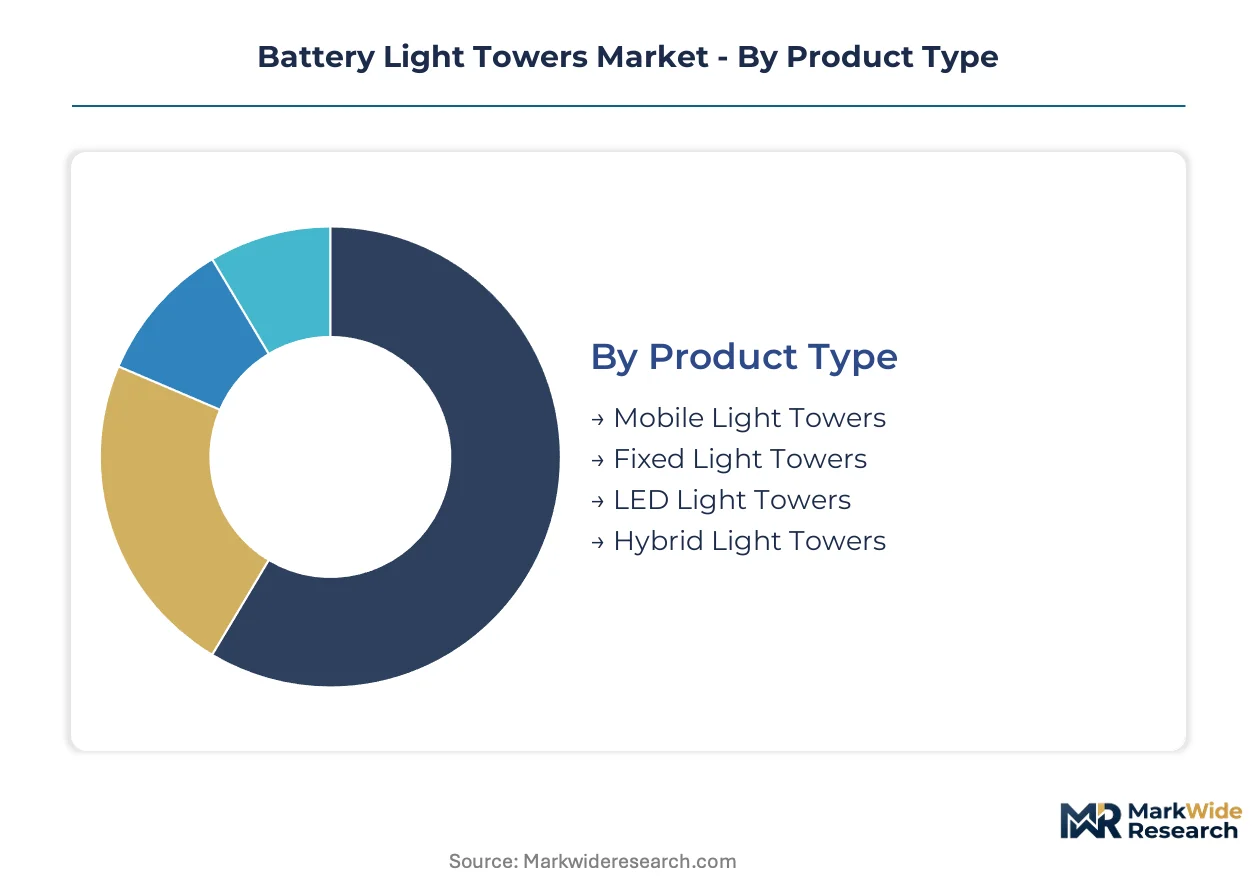
Battery light tower procurement channels diverge sharply by segment. Mining contractors favor direct manufacturer relationships for fleet standardization. Event rental companies source through equipment distributors with flexible lease terms. Construction firms split purchases between national dealers and regional rental houses based on project duration.
Product Type:
Channel mix varies by mobility requirements and power architecture. Mobile units flow through rental fleets for temporary deployments. Fixed installations move via EPC contractors with multi-year service agreements. LED and hybrid configurations increasingly bypass traditional distribution through direct vendor partnerships with tier-one mining and infrastructure operators.
- Mobile Light Towers:Trailer-mounted units with telescopic masts deploy rapidly across construction sites and emergency response zones. Demand concentrates in Texas energy corridor infrastructure projects where contractors prioritize rapid relocation between well pads. OSHA noise restrictions in densely populated work zones suppress diesel alternatives, accelerating silent battery configurations.
- Hybrid Light Towers:Dual-power architectures combining lithium-ion banks with compact generators eliminate range anxiety during extended deployments. Pilbara iron ore operators in Western Australia specify these for 24-hour continuous operation where solar charging gaps would strand pure battery units. Diesel cost volatility and EPA Tier 4 Final compliance costs rotate procurement toward hybrid systems as bridge technology.
- LED Light Towers:Solid-state illumination arrays deliver 50,000+ hour lifespans with minimal thermal output.
- Fixed Light Towers:Permanent installations serve security perimeters and industrial facility lighting with grid-tied or off-grid configurations.
By volume, LED Light Towers leads. By growth pace, Hybrid Light Towers is ahead.
End User:
Customer type determines specification rigor and contract structure. Mining operators demand performance guarantees and extreme-weather certification. Event rental fleets prioritize interchangeability and rapid deployment logistics. Emergency services require failsafe autonomy without fuel supply dependencies.
- Mining:Surface and underground extraction operations require explosion-rated enclosures and vibration-resistant assemblies. Western Australia's Pilbara region anchors procurement volume as BHP and Rio Tinto execute decarbonization commitments under state environmental standards. Lithium iron phosphate chemistry dominates specifications for thermal stability in 50°C ambient conditions.
- Construction:Infrastructure contractors bundle illumination into integrated site preparation contracts rather than capital purchases. Germany's Rhine-Ruhr metropolitan zone faces municipal diesel bans that compress replacement timelines for rental fleet operators. Guaranteed residual value programs absorb buyer technology risk.
- Events:Festival and outdoor entertainment producers prioritize acoustic compliance and rapid setup.
- Emergency Services:Disaster response agencies require autonomous operation independent of fuel logistics chains.
Mining commands the largest absolute spend. Construction shows the steepest expansion trajectory.
Technology:
Power source selection tracks regulatory intensity and fuel access reliability. Solar-battery convergence opens off-grid applications where generator logistics prove prohibitive. Pure diesel faces structured decline under EPA and EU Stage V emission standards.
- Battery Power:Lithium-ion systems with integrated photovoltaic charging achieve complete combustion elimination. India's PLI scheme for advanced chemistry cells reduces landed costs for South Asian infrastructure contractors evaluating fleet electrification. OSHA workplace noise exposure limits accelerate adoption in enclosed US work zones.
- Solar Power:Photovoltaic-integrated units serve emergency response zones and remote security installations lacking grid connectivity or fuel supply infrastructure.
- Diesel Power:Conventional generator-based systems face regulatory phase-out in Tier 4 Final and Stage V jurisdictions.
- Hybrid Technology:Generator-battery combinations bridge runtime gaps during extended cloudy periods or high-load continuous operation.
Battery Power leads current installations. Hybrid Technology is gaining share fastest among new procurement.
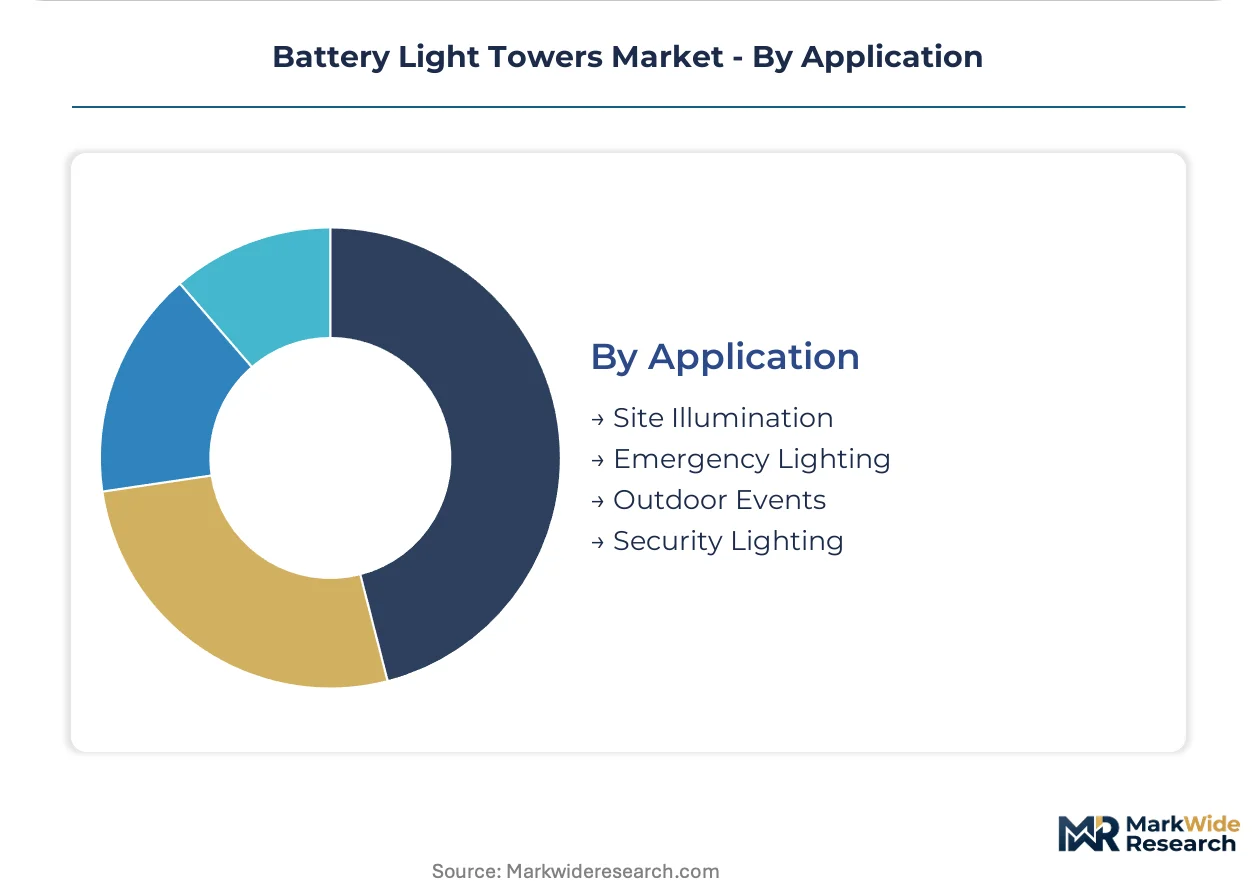
Application:
Use case determines performance specifications and procurement economics. Continuous industrial operation demands ruggedization and predictive maintenance integration. Intermittent event deployment prioritizes transportability and rapid deployment.
- Site Illumination:Infrastructure construction and mining operations require high-lumen output across large footprints with minimal shadowing. Total cost of ownership contracting displaces capital purchase models in North American procurement as EPC firms bundle lighting services into integrated contracts. Performance-based agreements with guaranteed uptime metrics now dominate Texas energy corridor projects.
- Emergency Lighting:Disaster response and grid-failure backup applications prioritize immediate deployment without fuel logistics dependencies.
- Outdoor Events:Temporary entertainment and festival installations emphasize acoustic compliance and aesthetic integration.
- Security Lighting:Perimeter monitoring and critical infrastructure protection require motion-sensing integration and vandal-resistant enclosures.
Site Illumination generates deepest margin pools. Emergency Lighting climbs the fastest as climate-related grid instability expands addressable demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's battery manufacturing base supplies lithium-ion cells to light tower assemblers across Australia, Germany, and the United States, creating a trade corridor that shapes regional deployment economics and procurement lead times.
United States
Texas energy corridor infrastructure projects and California urban construction zones drive procurement volume. OSHA workplace noise exposure limits suppress diesel generator deployment in enclosed work sites. Houston-based contractors bundle battery light tower services into integrated site preparation contracts with guaranteed uptime metrics.
Germany
Rhine-Ruhr metropolitan construction activity and Bavarian industrial facility upgrades anchor demand. Municipal diesel bans administered under EU Stage V regulations compress replacement timelines for rental fleet operators. Frankfurt equipment lessors offer guaranteed residual value programs to absorb buyer technology risk.
Australia
Western Australia's Pilbara iron ore region concentrates mining procurement as BHP and Rio Tinto execute decarbonization commitments. State environmental standards restrict diesel emissions at remote extraction sites. Perth-based fleet operators specify lithium iron phosphate chemistry for thermal stability in extreme ambient temperatures.
India
South Asian infrastructure contractors evaluate fleet electrification amid expanding highway and renewable energy construction. The PLI scheme for advanced chemistry cells reduces landed costs for domestic battery manufacturing. Maharashtra-based EPC firms pilot solar-battery light tower configurations for off-grid project sites.
United Arab Emirates
Expo legacy infrastructure and NEOM northwest development projects generate demand for silent illumination systems. Dubai municipal authorities enforce strict decibel limits for urban construction zones. Abu Dhabi-based rental fleets rotate toward hybrid-battery units to eliminate range anxiety during extended desert deployments.
Battery Light Towers Market Competitive Landscape
Listed leaders compete with private specialists across capital access and portfolio breadth, producing a tiered structure where scale advantages concentrate in North American and European hands while regional fabricators capture price-sensitive procurement. The vendor base separates into three archetypes: diversified power equipment conglomerates with captive distribution networks, rental fleet operators with vertical integration into service logistics, and specialized solar-battery integrators focused on off-grid configurations. Dominant competitive moves include strategic partnerships between cell manufacturers and tower assemblers to secure lithium supply, plus geographic expansion through distributor acquisitions in high-growth Asian markets.
Within the diversified equipment tier, Generac Power Systems and Atlas Copco exemplify scale-driven positioning through integrated manufacturing footprints and established rental channel relationships. Wacker Neuson occupies a specialist position among European compact equipment fabricators, leveraging regional proximity to German construction markets with strict acoustic regulations. Terex Corporation represents the capital-goods conglomerate archetype with broad infrastructure exposure across multiple illumination and access equipment categories.
| Leading Market Players |
|---|
| Generac Power Systems |
| Atlas Copco |
| Terex Corporation |
| Wacker Neuson |
| Doosan Portable Power |
| Larson Electronics |
| United Rentals |
| JCB |
| Progress Solar Solutions |
| Others |
Pricing and Supply Chain Analysis
Lithium iron phosphate chemistry substitution for conventional lithium-ion is redrawing procurement geography toward Chinese cell manufacturers while compressing margin structures for tower assemblers locked into long-term supply agreements. This chemistry migration simultaneously concentrates supply risk in East Asian production hubs and forces pricing recalibration across premium and standard equipment tiers.
Pricing Analysis
The prior-generation diesel-to-battery pricing gap is narrowing as EPA Tier 4 Final compliance costs inflate conventional generator landed costs, while next-generation solid-state battery prototypes threaten to disrupt current lithium-ion pricing architecture. Equipment procurement stratifies across premium LFP configurations, standard lithium-ion offerings, and residual diesel-hybrid economy tiers, with price differentiation driven by thermal stability certification and regional logistics costs. Cost compression in the standard tier intensifies because Chinese cell oversupply feeds into aggressive tower assembler pricing. Mining contractors in Western Australia exhibit lowest price sensitivity due to decarbonization mandates, while event rental fleets in European urban centers face acute margin pressure from municipal acoustic compliance deadlines.
Supply Chain Analysis
China, South Korea, and Japan anchor lithium-ion cell production for battery light tower integration, with Australian spodumene concentrate and Chilean brine extraction feeding upstream material flows. Tower assembly draws from aluminum extrusion mills in Germany, LED array fabricators in Taiwan, and photovoltaic panel suppliers in Vietnam. Single-source vulnerability concentrates in refined lithium hydroxide processing, where geographic concentration creates tariff exposure from escalating US-China trade measures. Distribution runs through captive rental fleet networks for mining and construction verticals, while emergency services and event producers source via regional equipment distributors with flexible lease structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery light tower markets are reconfiguring around service-attach revenue, with predictive maintenance contracts and guaranteed uptime performance agreements expanding faster than hardware unit sales as EPC firms outsource operational risk.
For Market Incumbents: Fortify lithium supply positioning through offtake agreements with Australian spodumene producers or backward integration into cell manufacturing partnerships, while accelerating EPA and EU Stage V certification coverage to defend against emerging solar-battery integrators. Channel control through rental fleet acquisitions in Texas and Western Australia absorbs buyer technology risk and locks out modular competitors. For New Entrants and Emerging Players: CE marking fast-track programs for compact urban configurations open immediate penetration pathways in Germany's Rhine-Ruhr metropolitan zone, where municipal diesel bans compress replacement timelines and incumbent capacity constraints create fulfillment gaps. Target India's PLI scheme beneficiary tier for domestic battery manufacturing partnerships, leveraging landed cost advantages against imported equipment. Go-to-market execution should anchor on solar-battery hybrid units for Maharashtra-based infrastructure contractors piloting off-grid configurations. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed rental fleet operators in North America and Australia, where decarbonization mandates and service contract expansion create platform rollup opportunities. Long-term viability hinges on lithium supply contract structures and regional recycling mandate compliance overhead. The signal to watch is consolidation velocity among German equipment lessors offering guaranteed residual value programs, which indicates risk absorption capacity and buyer confidence inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Lithium Supply Agreement | Secures cell input pricing stability for tower assemblers facing Australian spodumene volatility. |
| Hybrid Configuration Launch | Bridges runtime gaps for Pilbara mining operators requiring 24-hour continuous illumination. |
| Service Contract Expansion | Captures recurring revenue from Texas EPC firms outsourcing uptime risk via performance agreements. |
| CE Marking Acceleration | Unlocks Rhine-Ruhr municipal procurement compressed by EU Stage V diesel ban timelines. |
| Photovoltaic Integration | Opens emergency response applications where fuel logistics chains prove unreliable or prohibitive. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with fleet procurement directors, EPC contract managers, rental house operations heads, and aftermarket service specialists, combined with secondary validation against customs trade records, SEC equipment manufacturer filings, and Australian state environmental compliance databases. Bottom-up unit shipment estimates triangulated against top-down construction and mining capex allocation patterns.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning power architecture, mobility configuration, end-use vertical, and regional regulatory intensity. CAGRs derived from elasticity-adjusted demand curves incorporating lithium price scenarios and diesel cost volatility bands. Industry-specific inputs included OSHA noise enforcement trajectories, EU battery recycling mandate implementation schedules, and India's PLI scheme capacity buildout timelines.
Underlying assumptions cover lithium supply contract stability and EPA Tier 4 Final enforcement continuity, with deviation risk concentrated in Chilean brine extraction disruptions and escalation of US-China cell tariff schedules. Recalibration cycles align with material shifts in mining decarbonization commitments and municipal diesel ban expansion across European construction markets.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Military Battery Packs Market
Batteries
Disposable Batteries Market
Batteries
Japan Battery Market
Batteries
US Solar Battery Market
Batteries
India Electric Vehicle Battery Manufacturing Equipment Market
Batteries
North America NMC Battery Pack Market
Batteries
Forklift Battery Rental Market
Batteries
Europe Lead-Acid Battery Market
Batteries
Nimh Battery Market
Batteries
China Battery Market
Batteries
United States Household Battery Market
Batteries
Primary Battery Market
Batteries
Semi-Solid Flow Battery Market
Batteries
Europe Battery Systems for Electric Vehicles Market
Batteries
Hybrid Flow Battery Market
Batteries
Smart Battery Charger Market