
 Europe Battery Energy Storage System Market | 2026-2036
Europe Battery Energy Storage System Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Battery Energy Storage System Market Foresight
CE marking under the EU Battery Regulation is bifurcating the supplier landscape into qualified incumbents and excluded challengers. Wärtsilä leverages its grid-scale software stack to dominate Nordic frequency regulation contracts. LG Energy Solution anchors cell supply through its Polish manufacturing base, while Fluence Energy competes on integrated hardware-software platforms for utility customers.
A battery energy storage system is an electrochemical assembly rated from kilowatt-hours to gigawatt-hours, utilizing lithium iron phosphate or nickel manganese cobalt oxide cells managed by battery management systems maintaining state-of-charge precision within two percent. Its primary purpose is temporal arbitrage, grid stabilization, and renewable firming for power networks and commercial load centers. Li-ion batteries occupy the dominant share due to declining cell costs and established recycling pathways, while flow batteries extend into long-duration applications where six-to-twelve hour discharge cycles justify higher capital intensity. Virtual power plant technology is gaining structural traction as aggregators pool distributed assets for wholesale market participation.
The EU Green Deal, CE marking requirements under the EU Battery Regulation, and national capacity mechanisms administered by regulators including Germany's Bundesnetzagentur shape product standards and market access across member states. ECHA's evolving substance restrictions on cobalt and nickel compounds are forcing cell chemistry redesigns and supply chain documentation protocols. Stakeholders must monitor how the EU AI Act's risk classification rules apply to autonomous grid dispatch algorithms before committing to next-generation control platforms.
Market Dynamics
Utility-scale grid operators across Europe are accelerating procurement timelines as the EU Green Deal and REPowerEU plan compress carbon reduction mandates into actionable capacity tenders. This regulatory compression is bifurcating the supplier landscape between qualified incumbents with CE marking compliance and excluded challengers lacking certified manufacturing footprints.
Growth Catalysts
- REPowerEU Plan:The EU's energy security framework mandates rapid renewable deployment, forcing transmission system operators to procure front-of-meter storage for grid stabilization and renewable firming.
- Frequency regulation contracts:Nordic grid operators are issuing multi-year capacity payments for fast-response battery systems that maintain grid frequency within narrow operational bands.
- Lithium iron phosphate chemistry:Declining cell costs and established recycling pathways under the EU Battery Regulation are pulling Li-ion systems into commercial and industrial load centers.
Market Restraints
- Cobalt and nickel compound restrictions:ECHA's evolving substance documentation protocols are forcing cell chemistry redesigns that extend qualification timelines and raise compliance costs.
- Polish manufacturing concentration:Cell supply chains anchor heavily in Central European production hubs, creating geographic vulnerability to single-point disruptions.
- Flow battery capital intensity:Long-duration alternatives face structural cost barriers where six-to-twelve hour discharge cycles struggle against Li-ion learning curves.
Strategic Opportunities
- Virtual power plant aggregation:Distributed asset pooling for wholesale market participation remains underdeveloped in Southern European markets, creating white space for platform operators.
- Autonomous grid dispatch algorithms:The EU AI Act's risk classification framework creates first-mover advantage for control platform vendors that secure compliance ahead of mandated deadlines.
- Industrial load centers:Commercial behind-the-meter installations in Germany and Italy show penetration gaps relative to utility-scale deployment rates.
Industry Challenges
- CE marking certification timelines:The EU Battery Regulation's conformity assessment procedures create multi-quarter approval delays that compress project development windows.
- Legacy SCADA integration:Battery management systems must interface with decades-old grid control infrastructure, raising commissioning complexity and failure modes.
- Specialized technician scarcity:Field service capacity for thermal runaway response and high-voltage maintenance lags behind installed base expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Battery Energy Storage System Market |
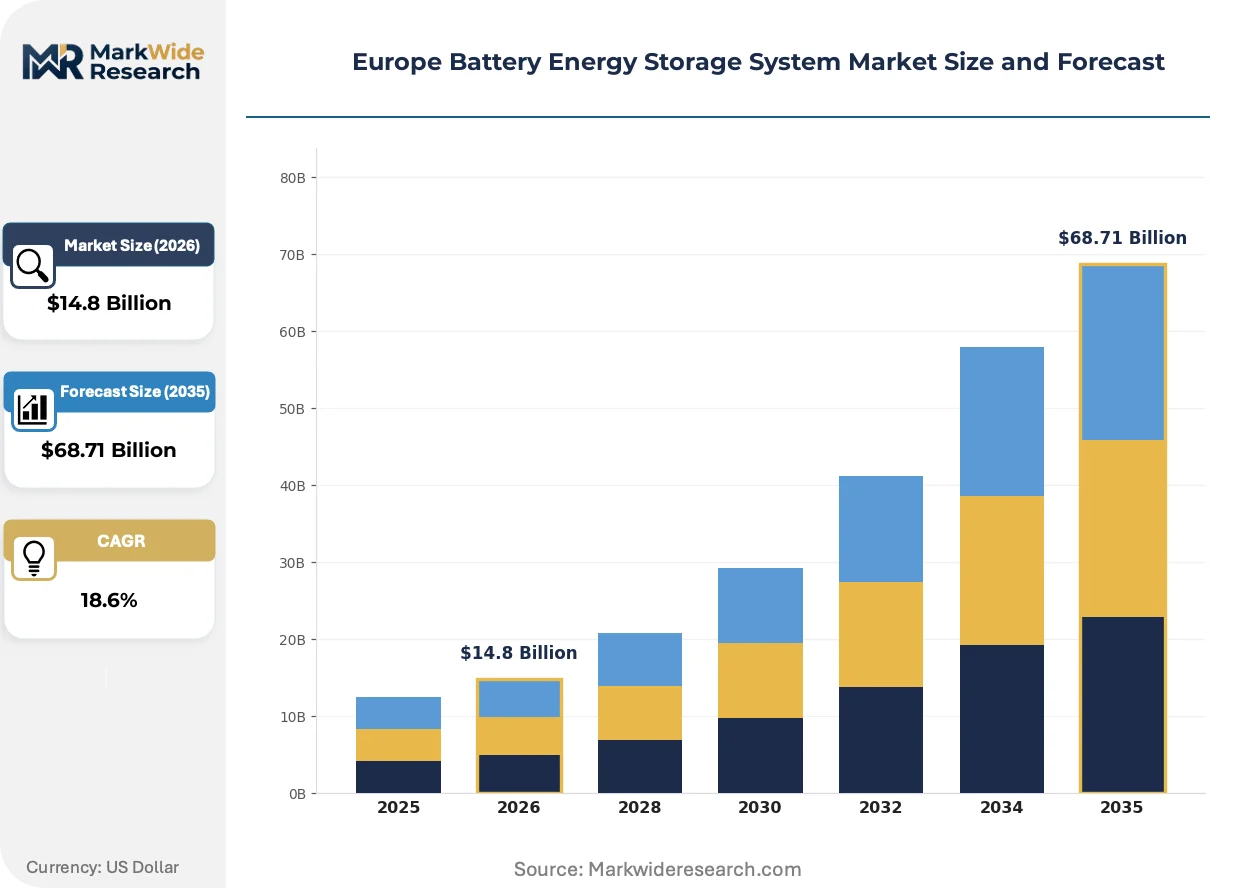
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $68.71 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Li-ion Batteries, Lead-acid Batteries, Flow Batteries, Nickel-based Batteries End User: Residential, Commercial, Utility, Industrial Technology: Grid-Scale, Microgrid, Off-Grid, Virtual Power Plant Deployment: Onsite, Offsite, Hybrid, Mobile |
| Companies Covered | Wärtsilä, LG Energy Solution, Fluence Energy, ABB, Siemens Energy, Tesla, Hitachi Energy, Schneider Electric, BYD, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Battery Energy Storage System Market Shifts & Advancements
Software-defined control architectures are displacing hardware-centric system designs across European grid-scale deployments. This shift compresses commissioning timelines while enabling remote algorithm updates that extend asset economic life.
Solid-state electrolyte research is decomposing the traditional liquid-electrolyte safety paradigm that has constrained Li-ion deployment in dense urban substations. German transmission operators are piloting prototype cells for downtown Berlin installations where thermal runaway risks previously blocked permitting. The technology is decomposing the geographic exclusion zones that have limited battery siting in population centers.
The EU AI Act's risk classification rules for autonomous energy systems are forcing control platform vendors to rearchitect dispatch algorithms ahead of enforcement deadlines. Industrial consequence includes mandatory human-in-the-loop requirements for high-risk grid applications that autonomous vendors previously marketed as fully automated. German and Spanish regulators are issuing interim guidance that treats frequency regulation as high-risk, compressing vendor compliance roadmaps.
Aggregators are unbundling hardware procurement from software subscriptions, allowing utilities to separate capex and opex decisions. This model disrupts traditional integrated system vendors by enabling component sourcing from multiple suppliers. The shift is most visible in Italian commercial and industrial segments where energy service companies now dominate project origination.
Europe Battery Energy Storage System Market Segmentation
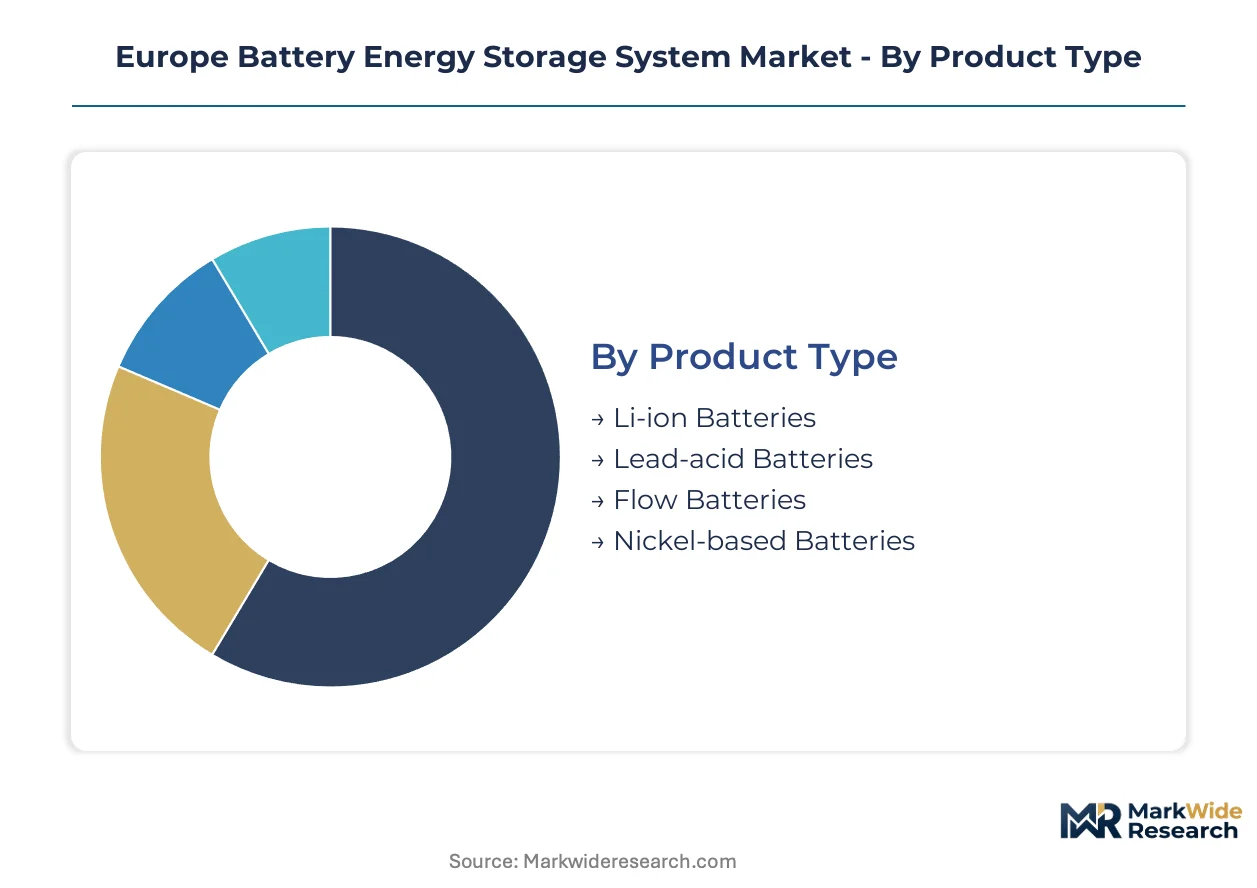
Segmentation reveals how CE marking requirements under the EU Battery Regulation and national capacity mechanisms create divergent compliance burdens across product categories. Each dimension carries distinct regulatory, technical, and commercial characteristics that shape procurement patterns among German transmission operators, Spanish renewable developers, and Italian industrial energy managers.
Product Type:
REACH substance restrictions and ECHA documentation protocols force distinct chemistry choices across the four battery families, with cobalt and nickel compound limitations driving reformulation timelines and supply chain requalification.
- Li-ion Batteries:Lithium iron phosphate and nickel manganese cobalt oxide cells dominate front-of-meter tenders due to declining manufacturing costs and established recycling pathways under the EU Battery Regulation. German transmission system operators specify these systems for frequency regulation contracts requiring sub-second response times.
- Flow Batteries:Vanadium and zinc-bromide chemistries enable six-to-twelve hour discharge cycles for renewable firming applications where capital intensity can be amortized across longer duration revenue streams. Spanish solar-plus-storage developers pilot these systems for evening peak displacement.
- Lead-acid Batteries:Mature recycling infrastructure and lower upfront costs sustain demand in Italian commercial behind-the-meter installations with moderate cycling requirements.
- Nickel-based Batteries:Nickel-metal hydride and nickel-cadmium variants retain niche utility in Nordic cold-climate microgrids where temperature tolerance outweighs energy density priorities.
Li-ion batteries handle the majority of throughput; flow batteries are gaining share fastest as long-duration procurement accelerates.
End User:
Customer scale determines access to wholesale market revenue streams and eligibility for national capacity mechanisms administered by regulators including Germany's Bundesnetzagentur.
- Utility:Transmission and distribution operators procure front-of-meter systems for grid stabilization, renewable firming, and ancillary services. Nordic grid operators issue multi-year capacity payments for fast-response assets.
- Commercial:Energy service companies aggregate retail loads for peak shaving and demand charge management. Italian commercial segments show penetration gaps relative to utility-scale deployment rates.
- Industrial:Manufacturing facilities deploy behind-the-meter storage for power quality assurance and process continuity. German automotive and chemical plants anchor early adoption.
- Residential:Homeowners pair rooftop solar with battery systems for self-consumption optimization. Spanish net metering reforms are expanding addressable market scope.
Utility procurement commands the largest project sizes; commercial installations are expanding most quickly as energy service companies unbundle hardware from software subscriptions.
Technology:
Control architecture sophistication determines eligibility for frequency regulation contracts and compliance burden under the EU AI Act's risk classification framework.
- Grid-Scale:Centralized battery plants rated from tens to hundreds of megawatts provide bulk power services and transmission deferral. Wärtsilä's software stack dominates Nordic frequency regulation tenders.
- Virtual Power Plant:Aggregated distributed assets participate in wholesale markets through pooled dispatch. Southern European markets remain underdeveloped, creating white space for platform operators.
- Microgrid:Island-capable systems serve remote industrial facilities and rural communities. Italian islands and Greek archipelagos anchor deployment demand.
- Off-Grid:Standalone systems electrify remote locations without network connection. Alpine tourism infrastructure and agricultural operations sustain niche demand.
Grid-scale systems absorb the dominant share of capital deployment; virtual power plant aggregation is climbing the fastest as regulatory frameworks mature.
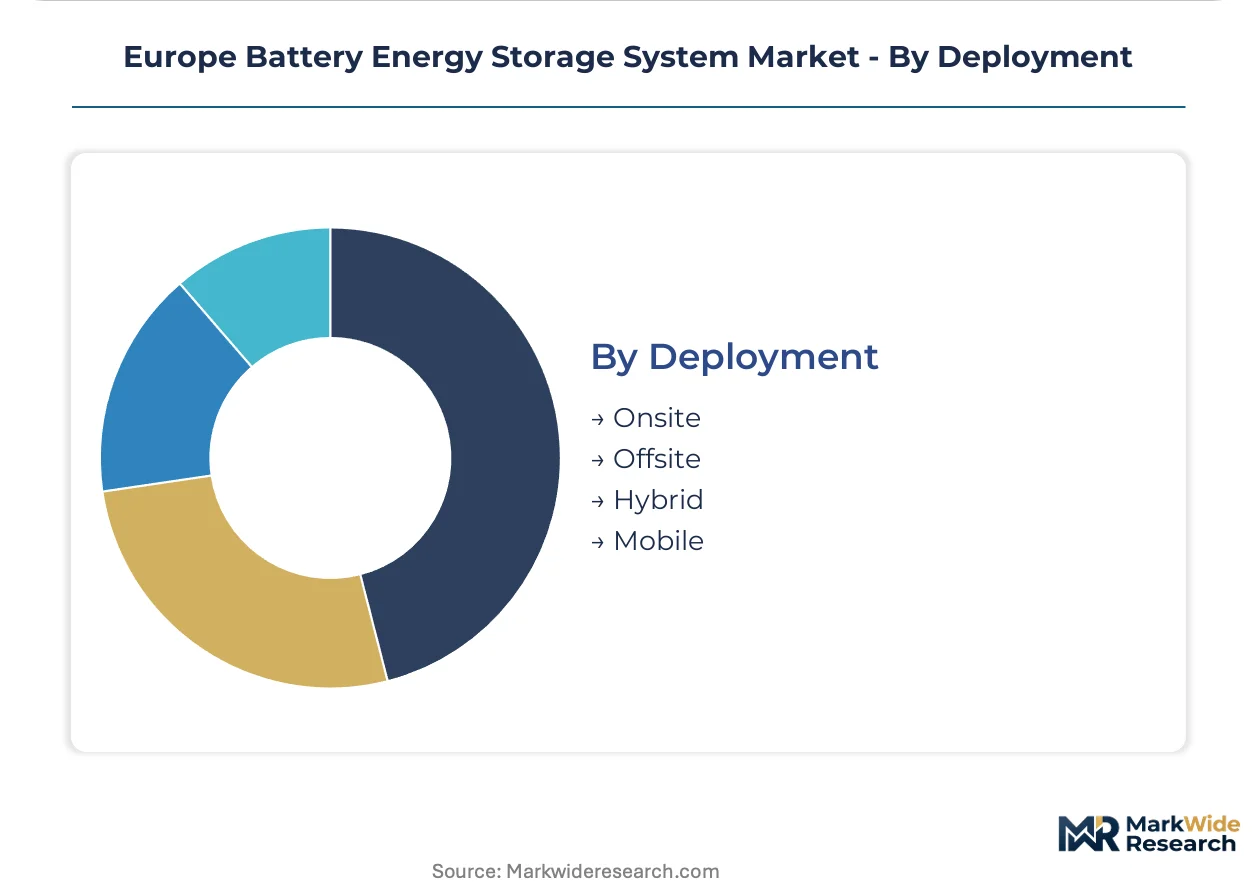
Deployment:
Siting flexibility and interconnection complexity create divergent project development timelines and permitting pathways across member states.
- Onsite:Co-located with generation or load assets to minimize transmission losses and land use conflicts. German industrial parks and Spanish solar farms concentrate deployment.
- Offsite:Strategically positioned for network congestion relief and wholesale market access. Transmission-connected projects in northern Germany serve as renewable export buffers.
- Hybrid:Integrated with solar PV or wind generation to optimize shared interconnection and control systems. Spanish and Portuguese renewable developers favor this architecture.
- Mobile:Containerized or trailer-mounted systems for temporary grid support and emergency response. German transmission operators deploy these for substation maintenance coverage.
Onsite deployment accounts for the greatest installed capacity; hybrid configurations are expanding most rapidly as renewable pairing economics improve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German transmission system operators command the largest capacity tenders, while Spanish renewable developers and Italian industrial energy managers concentrate procurement across distinct buyer archetypes.
Germany
Industrial load centers in the automotive and chemical sectors anchor behind-the-meter deployment. Bundesnetzagentur capacity mechanisms shape procurement timelines for transmission-connected projects. Northern Germany hosts renewable export buffers serving as grid stabilization assets.
Spain
Solar-plus-storage developers pilot long-duration systems for evening peak displacement. Net metering reforms expand residential addressable markets under national energy transition frameworks. Andalusia and Catalonia concentrate hybrid deployment clusters.
Italy
Commercial and industrial segments show penetration gaps relative to utility-scale rates. Energy service companies dominate project origination through unbundled hardware-software models. Italian islands sustain microgrid demand for island-capable systems.
Poland
Central European manufacturing concentration creates geographic vulnerability to single-point disruptions. Cell supply chains anchor heavily in Polish production hubs serving regional demand. Warsaw and Silesian industrial zones concentrate battery assembly capacity.
United Kingdom
Frequency regulation contracts drive front-of-meter procurement for grid stabilization services. National Grid ESO issues multi-year capacity payments for fast-response assets. Scottish renewable zones pair storage with wind generation for firming applications.
Europe Battery Energy Storage System Market Competitive Landscape
Player mix skews toward integrated system vendors with certified manufacturing footprints and software-defined control platforms. Market structure bifurcates between qualified incumbents holding CE marking compliance and excluded challengers lacking conformity assessment documentation. Strategic archetypes include hardware-centric fabricators, software-stack specialists, and hybrid platform operators. Dominant competitive moves center on strategic partnerships for supply chain security and geographic expansion into underpenetrated Southern European markets.
Within the integrated platform tier, Wärtsilä leverages its grid-scale software stack for Nordic frequency regulation positioning, while LG Energy Solution anchors cell supply through its Polish manufacturing base. Fluence Energy occupies a position competing on integrated hardware-software architectures for utility-scale customers. These three exemplify distinct archetypes: Wärtsilä represents software-first incumbency, LG Energy Solution exemplifies cell manufacturing concentration, and Fluence Energy sits within the hybrid platform specialization.
| Leading Market Players |
|---|
| Wärtsilä |
| LG Energy Solution |
| Fluence Energy |
| ABB |
| Siemens Energy |
| Tesla |
| Hitachi Energy |
| Schneider Electric |
| BYD |
| Others |
Supply & Pricing Matrix
CE marking requirements under the EU Battery Regulation gate both supplier qualification and price differentiation simultaneously, creating a bifurcated market where certified incumbents command premium positioning over excluded challengers lacking conformity assessment documentation.
Pricing Analysis
Long-term offtake contracts with lithium carbonate indexation dominate utility-scale procurement, separating premium-tier integrated platform vendors from standard-tier hardware fabricators and economy-tier component assemblers. Price differentiation hinges on CE marking certification grade and software stack sophistication. Cost compression in standard-tier systems is intensifying as Polish cell supply expands. Commercial and industrial segments exhibit highest price sensitivity due to unbundled hardware-software procurement models.
Supply Chain Analysis
Poland anchors cell assembly capacity for European demand, while South Korea and Japan feed cathode active materials and separator films into regional production hubs. Raw material dependencies center on lithium hydroxide, nickel sulfate, and cobalt compounds sourced from diversified extraction zones. Single-source vulnerability concentrates in Polish manufacturing corridors serving German and Nordic offtakers. Distribution runs through transmission system operator tenders and energy service company channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating among German transmission system operators and Nordic grid operators issuing multi-gigawatt-hour tenders, compressing supplier margins and favoring scale incumbents with certified manufacturing footprints.
For Market Incumbents: Compound software-defined control architecture advantages to extend economic asset life and lock in multi-year frequency regulation contracts. Defend against emerging platform operators by deepening backward integration into battery management system firmware. Prioritize CE marking recertification ahead of evolving ECHA substance restriction deadlines. For New Entrants and Emerging Players: Lead with virtual power plant aggregation platforms targeting underpenetrated Southern European commercial segments where energy service companies dominate project origination. Capture Italian industrial load centers through unbundled software subscriptions rather than integrated hardware competition. Position around EU AI Act compliance for autonomous dispatch algorithms as a first-mover differentiator. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed energy service companies holding contracted project pipelines but lacking captive cell supply. Five-to-ten year viability hinges on securing long-term lithium offtake agreements and software platform recurring revenue conversion. Watch for inflection when Spanish net metering reforms accelerate residential distributed asset aggregation.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Fast-Track Certification | Accelerates market access ahead of EU Battery Regulation enforcement deadlines for qualified suppliers. |
| Virtual Power Plant Platform Launch | Captures Southern European white space where aggregators pool distributed assets for wholesale participation. |
| Backward Integration into BMS Firmware | Reduces commissioning complexity and failure modes from legacy SCADA integration challenges. |
| Polish Cell Manufacturing Scale-Up | Secures regional supply security against geographic concentration risks in Central European hubs. |
| EU AI Act Compliance Roadmap | Enables autonomous grid dispatch algorithms ahead of mandated human-in-the-loop requirements. |
Research Methodology
A standing panel of utility planning officers, EPC contractors, battery management system engineers, and energy service company executives provided ongoing calibration across primary interviews and secondary validation. Sources included Bundesnetzagentur tender databases, ENTSO-E grid development plans, EU Battery Regulation implementation guidance, and cell manufacturer capacity announcements. Bottom-up project pipelines were triangulated against top-down regulatory capacity targets.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. Segmentation dimensions modeled include battery chemistry family, end-user scale tier, control architecture type, and deployment siting configuration. CAGRs were derived from installed base expansion rates and revenue per megawatt-hour trajectories informed by frequency regulation contract pricing and capacity mechanism remuneration levels.
Forecasts assume regulatory continuity in EU Green Deal implementation and REPowerEU plan deployment schedules; material policy shifts would require re-modeling. Specific risks include ECHA substance restriction acceleration, Polish manufacturing disruption, and EU AI Act risk reclassification for grid applications. Recalibration cycles align with material shifts in national capacity mechanism design and cell chemistry qualification timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Storage
Battery Energy Storage System Fire Protection Market
Energy Storage
Marine Energy Storage System Market
Energy Storage
Off-Grid Energy Storage Systems Market
Energy Storage
Home Solar Energy Storage Battery Market
Energy Storage
Energy Storage Sodium Ion Battery Market
Energy Storage
Residential Energy Storage System Market
Energy Storage
Battery Energy Storage Market
Energy Storage
Hydrogen Storage System Market
Energy Storage
ASEAN Energy Storage Market
Energy Storage
Solar Storage Inverter Market
Energy Storage
Lead Acid Battery for Energy Storage Market
Energy Storage
Mobile Energy Storage Systems Market
Energy Storage
High Capacity Power Banks Market
Energy Storage
Battery Cell Dry Room Dehumidification Systems Market
Energy Storage
Superconducting Magnetic Energy Storage Market
Energy Storage
Global Data Center Energy Storage Market