

Residential Solar Energy Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Residential Solar Energy Storage Market Insights
Modular battery rack systems paired with hybrid inverters is recalibrating how homeowners size and upgrade storage capacity without full system replacement. Tesla leverages its integrated Powerwall-to-vehicle software stack to anchor premium positioning in North American installations. Enphase Energy competes through microinverter-coupled modular architecture that simplifies incremental expansion for residential integrators. Panasonic Holdings sustains its cell supply relationships with Japanese housing developers seeking all-electric home certifications.
Residential solar energy storage encompasses electrochemical systems designed to capture, retain, and dispatch photovoltaic generation behind the meter, typically operating at 48V to 400V DC with 5 kWh to 20 kWh usable capacity and round-trip efficiency exceeding 90 percent. These systems buffer intermittent solar output to align household load profiles with generation peaks, reducing grid import dependency and enabling time-of-use arbitrage. Lithium-ion batteries occupy the dominant share of new installations due to declining cell costs and established recycling pathways, while sodium-ion chemistries represent an emerging structural alternative for cost-sensitive markets with moderate cycle depth requirements. Powerwall systems lead in brand recognition and installer familiarity, though modular storage architectures are capturing faster growth as homeowners prioritize scalable capital deployment.
Federal Investment Tax Credit provisions under IRS guidance and state-level net metering reforms across multiple U.S. jurisdictions directly shape payback calculations and storage attachment rates for solar installations. Germany's Bundesnetzagentur grid code requirements and Australia's Clean Energy Council battery safety standards mandate specific inverter response behaviors and installation certifications that filter market access for equipment suppliers. Stakeholders must monitor evolving interconnection standards and utility rate restructuring timelines to anticipate where storage economics shift from subsidy-dependent to standalone retail value.
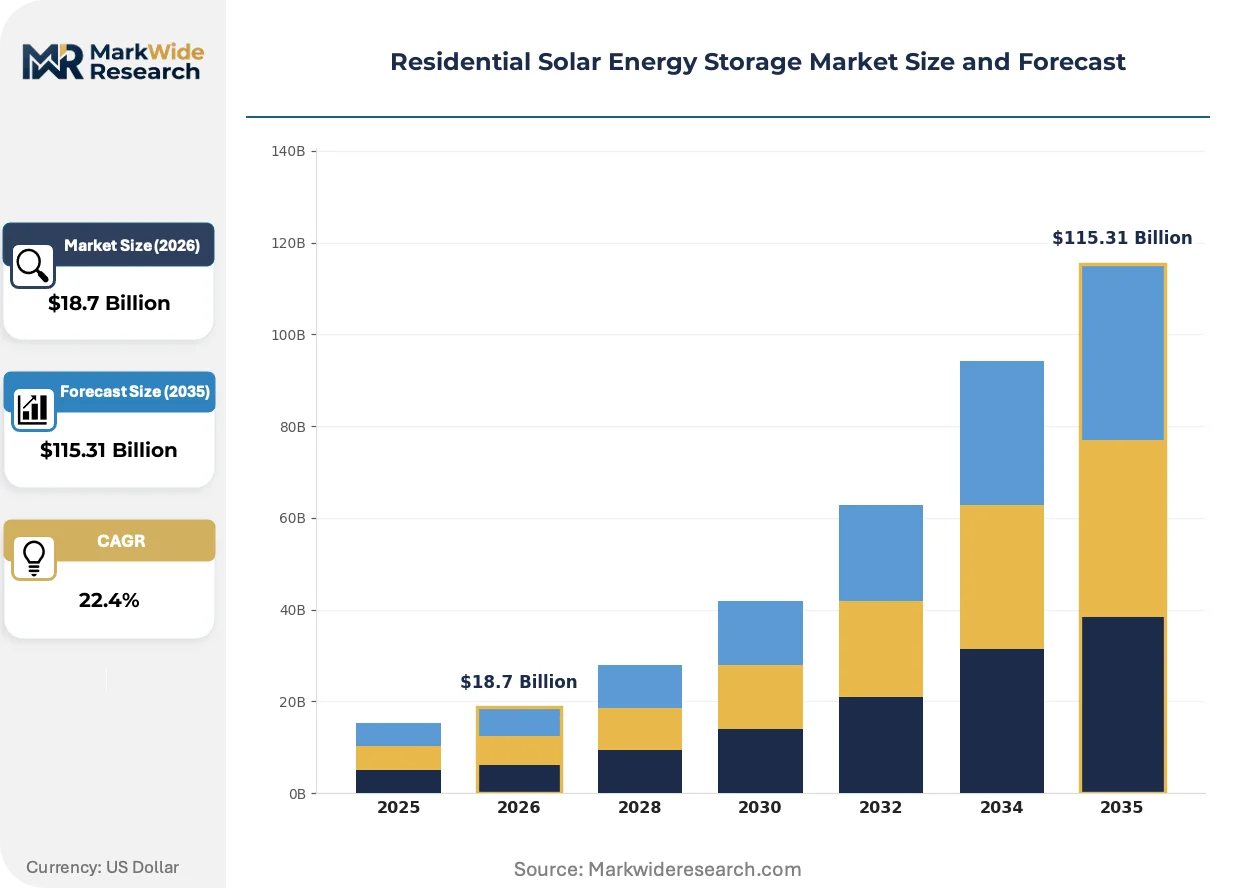
Market Dynamics
Feed-in tariff reductions across Germany, Australia, and California are forcing households toward self-consumption optimization, recalibrating storage economics from grid-export dependency to behind-the-meter arbitrage.
Growth Catalysts
- California NEM 3.0 reforms:Reduced export compensation rates compress payback periods for battery-coupled solar, accelerating attachment rates in the state's largest residential markets.
- Lithium iron phosphate chemistry:Improved thermal stability and extended cycle life enable longer-duration residential configurations without active cooling systems.
- Suburban single-family installations:Roof ownership rates and available wall space for inverter-battery enclosures concentrate demand in detached housing stock across the United States, Germany, and Australia.
Market Restraints
- Lithium carbonate price volatility:Raw material swings compress module margins and delay project financing commitments for integrators.
- Cell supply concentration:Asian cathode and electrolyte suppliers control critical upstream capacity, exposing non-integrated assemblers to allocation risk.
- Interconnection queue delays:Utility review timelines for behind-the-meter storage exceed 90 days in several U.S. jurisdictions, freezing project completions.
Strategic Opportunities
- All-electric home certifications:Japanese housing developers seek bundled solar-storage packages to meet METI efficiency mandates and qualify for preferential mortgage rates.
- Sodium-ion chemistry:Moderate cycle depth requirements in seasonal storage applications open cost-sensitive market segments currently underserved by lithium-ion economics.
- Aggregator-enabled grid services:Virtual power plant participation creates incremental revenue streams beyond self-consumption, improving project IRRs in deregulated retail markets.
Industry Challenges
- Certification timeline fragmentation:Australia's Clean Energy Council battery safety standards and Germany's Bundesnetzagentur grid code requirements demand separate testing protocols, duplicating compliance costs for multi-market suppliers.
- Electrical contractor skill gaps:High-voltage DC battery installation and hybrid inverter commissioning require specialized training that outpaces vocational program throughput in key installation markets.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Residential Solar Energy Storage Market Trends and Innovations
Software-defined energy management is compressing hardware differentiation cycles, forcing suppliers to compete on fleet orchestration capabilities rather than standalone cell specifications.
Hybrid inverter architectures with integrated DC-coupled battery management are unifying power conversion and charge control into single enclosures. Suburban installers in California and Texas favor these configurations for reduced wiring complexity and faster commissioning timelines. This unification is compressing standalone inverter margins and elevating software integration as the primary vendor selection criterion.
EU Green Deal implementation and the revised Energy Performance of Buildings Directive mandate solar-ready infrastructure in new residential construction across member states. Builders in Germany, the Netherlands, and Spain must pre-wire electrical panels and designate mechanical space for future battery installation. Residential developers in these markets are responding by negotiating multi-year supply agreements with storage OEMs to lock in volume pricing.
Homeowner procurement preferences are migrating from equipment ownership toward performance guarantees and maintenance-inclusive service agreements. Third-party ownership platforms in Arizona, Colorado, and Florida are displacing traditional cash-and-carry distribution through lease structures that bundle monitoring, warranty extension, and eventual cell replacement. This shift is most visible in markets where time-of-use rate differentials exceed 30 cents per kilowatt-hour and where utility interconnection fees penalize small-scale solar without storage.
Residential Solar Energy Storage Market Segmentation
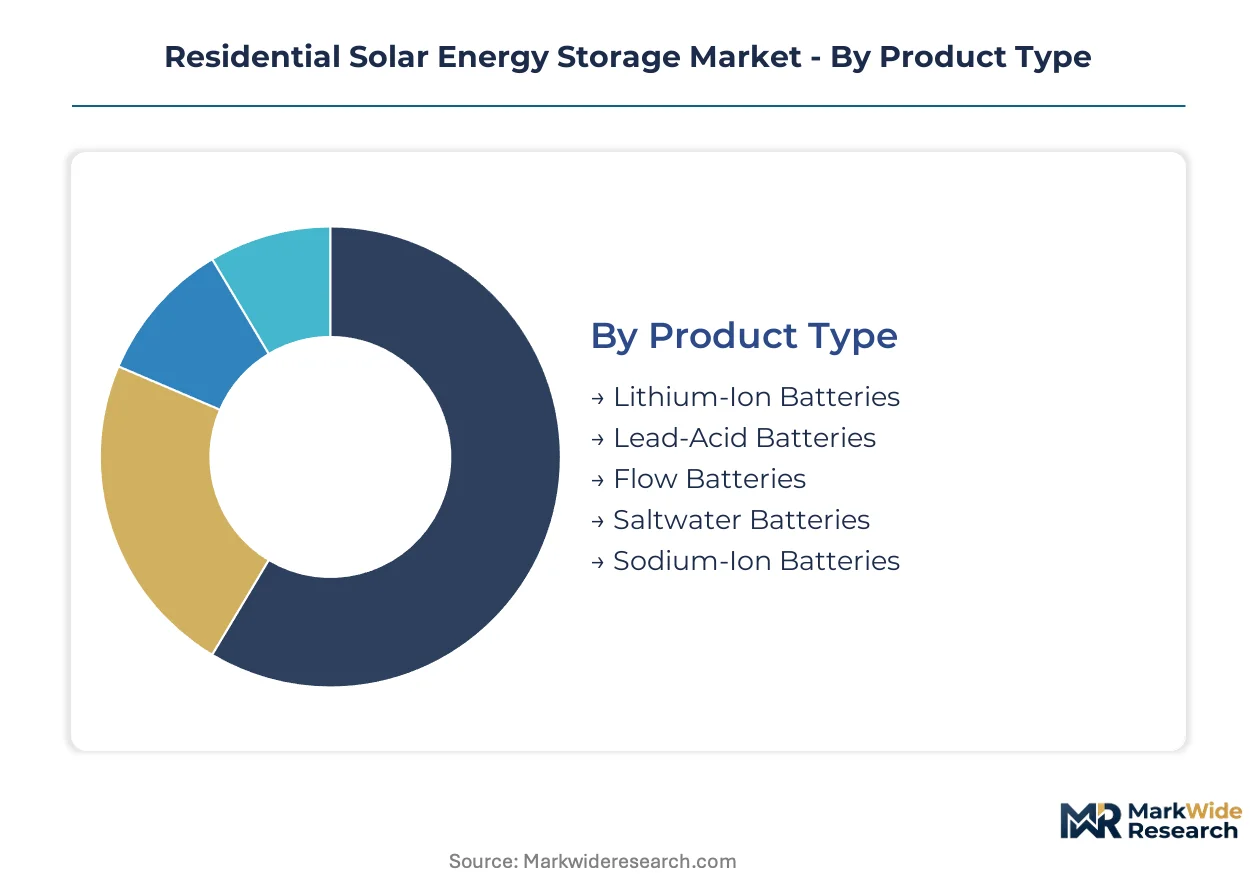
Residential solar energy storage segments fragment across electrochemical chemistries, integration architectures, and procurement channels. Each dimension carries distinct margin profiles, certification requirements, and installer skill dependencies that shape supplier strategy.
Product Type:
Chemistry selection determines cycle life, thermal management requirements, and end-of-life handling protocols for installers and homeowners.
- Lithium-Ion Batteries:Dominant lithium iron phosphate cells deliver 6,000+ cycles at 90 percent round-trip efficiency without active cooling. Demand concentrates in California and Australian suburban retrofits where NEM 3.0 export reductions and feed-in tariff cuts force self-consumption optimization.
- Lead-Acid Batteries:Sealed AGM configurations persist in off-grid cabins and RV applications where upfront capital constraints outweigh cycle depth requirements. Installers in rural Texas and Arizona favor these for simplicity despite shorter 1,200-cycle lifespans.
- Flow Batteries:Vanadium redox systems enable 20-year calendar life with unlimited cycle depth, suiting seasonal storage in German all-electric home developments.
- Saltwater Batteries:Aqueous electrolyte chemistry eliminates thermal runaway risk for basement installations in fire-code-restricted jurisdictions.
- Sodium-Ion Batteries:Emerging Prussian white cathode designs target cost-sensitive markets with moderate daily cycling needs.
Volume sits with lithium-ion; growth tilts toward sodium-ion as cathode supply chains diversify.
Technology:
Integration architecture determines wiring complexity, upgrade pathways, and inverter compatibility for residential contractors.
- Powerwall Systems:Integrated AC-coupled enclosures with vehicle-to-home software stacks command premium positioning in North American markets. Tesla's closed ecosystem limits third-party inverter mixing but reduces commissioning time for certified installers.
- Modular Storage:Rack-mounted lithium iron phosphate blocks scale from 5 kWh to 40 kWh through incremental additions. Enphase microinverter coupling dominates suburban California and Texas markets where homeowners prioritize phased capital deployment.
- Hybrid Inverters:Single-enclosure DC-coupled units unify solar generation and battery management, reducing balance-of-system costs for new installations.
- AC Coupled:Retrofit-friendly configurations add storage to existing solar arrays without DC rewiring, accelerating attachment rates in legacy markets.
- DC Coupled:Direct battery-to-inverter connections maximize round-trip efficiency for new-build installations with simultaneous solar and storage procurement.
Revenue concentrates in modular architectures; steepest expansion trajectory belongs to hybrid inverters as new construction mandates spread.
Application:
Use case selection drives capacity sizing, software features, and revenue stacking potential for system owners.
- Backup Power:Outage resilience configurations prioritize instantaneous transfer switches and 10-20 kWh capacity for 24-48 hour critical load coverage. Demand clusters in hurricane-exposed Florida and Texas markets where grid reliability concerns dominate purchase decisions.
- Energy Arbitrage:Time-of-use rate optimization algorithms charge batteries during low-rate periods and discharge during peak pricing. California's 30+ cent per kilowatt-hour differentials create compelling payback math for automated dispatch systems.
- Load Shifting:Solar generation alignment with evening demand peaks reduces grid import dependency in German and Australian markets with declining export compensation.
- Grid Services:Virtual power plant participation aggregates residential batteries for frequency regulation and demand response in deregulated retail markets.
- Off-Grid Power:Standalone systems with oversized solar arrays and 20+ kWh storage serve remote properties beyond utility distribution infrastructure.
Deployment volume favors backup power; fastest share gains accrue to grid services as aggregator platforms mature.
End User:
Procurement channel determines pricing power, warranty terms, and installation timeline expectations.
- Homeowners:Direct purchasers prioritize brand recognition, monitoring apps, and installer network density. Cash buyers in California and Arizona drive premium product attachment; third-party ownership platforms displace direct sales in high-interconnection-fee jurisdictions.
- Residential Developers:New construction specifiers negotiate multi-year supply agreements for solar-ready electrical infrastructure. German builders bundle storage to meet EU Green Deal efficiency mandates and secure preferential mortgage rates.
- Solar Integrators:Installation contractors select products based on inventory turns, training support, and margin protection programs.
- Energy Retailers:Utility affiliates and competitive suppliers bundle storage with retail electricity contracts to reduce customer churn.
- Property Managers:Multi-family housing operators pilot shared battery systems for common area load management in California and New York regulatory pilots.
Transaction volume rests with homeowners; developer channel expansion accelerates fastest under building code mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in East Asian cell production zones while deployment concentrates in high-electricity-rate suburban markets across North America, Europe, and Australia. This geographic split creates supply chain exposure for installers dependent on overseas battery module sourcing.
United States
California NEM 3.0 export compensation cuts compress solar-only payback periods and accelerate battery attachment rates in Los Angeles and San Diego metro areas. Federal Investment Tax Credit provisions under IRS guidance extend to standalone storage systems through 2032. Texas installers report 40-day interconnection queue delays in ERCOT jurisdictions, freezing project completions in Houston and Dallas suburbs.
Germany
Feed-in tariff reductions to 8.2 euro cents per kilowatt-hour force households toward self-consumption optimization in Bavaria and Baden-Württemberg. Bundesnetzagentur grid code requirements mandate specific inverter response behaviors for frequency regulation participation. Residential developers in North Rhine-Westphalia negotiate multi-year supply agreements with storage OEMs to meet EU Green Deal efficiency mandates.
Australia
State-level feed-in tariff cuts in New South Wales and Victoria shift economics toward behind-the-meter arbitrage for suburban solar owners. Clean Energy Council battery safety standards mandate separate testing protocols that filter market access for equipment suppliers. Installer networks concentrate in Queensland's Sunshine Coast and Perth's metropolitan corridor where rooftop penetration exceeds 35 percent.
Japan
METI efficiency mandates for all-electric home certifications drive bundled solar-storage procurement by housing developers in Kanto and Kansai regions. Preferential mortgage rates from Japan Housing Finance Agency reward properties with pre-installed battery infrastructure. Panasonic Holdings sustains cell supply relationships with major housing developers seeking zero-energy building compliance.
Residential Solar Energy Storage Market Competitive Landscape
The competitive structure tilts toward integrated system architects commanding installer loyalty through software ecosystems and closed hardware coupling. Tier-one suppliers with captive vehicle-to-home platforms occupy premium positioning, while modular specialists compete on incremental expansion flexibility. Strategic moves concentrate on microinverter-battery integration partnerships and virtual power plant aggregation licensing.
Within the integrated ecosystem tier, Tesla and Enphase Energy anchor divergent architectural philosophies. Tesla exemplifies the vertically coupled approach through its Powerwall-to-vehicle software stack, while Enphase Energy occupies the modular expansion vector with microinverter-coupled rack architectures. Panasonic Holdings represents the industrial conglomerate archetype, leveraging established cell supply relationships with Japanese housing developers. Specialist challengers including Sonnen and BYD compete through regional certification depth and cost-engineered lithium iron phosphate configurations.
| Leading Market Players |
|---|
| Tesla |
| Enphase Energy |
| SolarEdge Technologies |
| Panasonic Holdings |
| LG Energy Solution |
| BYD |
| Sonnen |
| Huawei |
| SMA Solar Technology |
| Others |
Pricing and Supply Chain Analysis
California NEM 3.0 export compensation cuts and similar feed-in tariff reductions across Germany and Australia are compressing project economics and forcing integrators toward modular, phased procurement models that favor suppliers with inventory flexibility and regional warehousing over pure manufacturing scale. This demand-side restructuring rewards battery assemblers with captive cell supply agreements and punishes spot-market dependent competitors.
Pricing Analysis
Cost-down pressure on mid-tier lithium iron phosphate systems accelerates because integrators in Texas and Arizona are consolidating purchase volumes around fewer SKU configurations to simplify installer training. Pricing stratifies across premium integrated ecosystems, standard modular rack systems, and economy lead-acid alternatives, with differentiation driven by UL 9540A fire safety certification tier and virtual power plant software bundling. California's 30+ cent per kilowatt-hour time-of-use spreads sustain premium pricing for automated dispatch capabilities, while off-grid cabin applications in rural markets exhibit acute price sensitivity to upfront capital outlay.
Supply Chain Analysis
End-of-life battery refurbishment flows and second-life grid storage applications are emerging as critical reverse-logistics nodes that shape cell sourcing decisions for residential OEMs. Cathode active material production concentrates in China, South Korea, and Japan, with electrolyte and separator supply anchored in East Asian chemical processing clusters. Module assembly draws from lithium carbonate, copper foil, and polyolefin separator inputs exposed to commodity price volatility and ocean freight rate swings. Distribution runs through certified installer networks and regional distribution warehouses rather than direct-to-consumer channels, concentrating working capital requirements on integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cell supply concentration in East Asian cathode and electrolyte production zones creates persistent allocation bottlenecks that prop pricing power for vertically integrated suppliers with captive upstream capacity.
For Market Incumbents: Acquire sodium-ion cell development capabilities and Prussian white cathode IP to hedge lithium carbonate volatility and preempt emerging chemistry substitution threats. Secure multi-year supply agreements with German housing developers and Japanese METI-certified builders before EU Green Deal efficiency mandates harden procurement relationships. Invest in UL 9540A testing infrastructure to accelerate certification timelines and defend margin position against modular specialists with faster market access. For New Entrants and Emerging Players: The 15-20 kWh capacity gap between Tesla's premium Powerwall positioning and economy lead-acid alternatives creates white-space opportunity for cost-engineered lithium iron phosphate systems with basic backup functionality. Target Australian suburban retrofits in Queensland and Perth where rooftop penetration exceeds 35 percent but aggregator-enabled grid services remain underdeveloped. Pursue white-label partnerships with Texas and Florida solar integrators seeking faster inventory turns and reduced training overhead. For Investors and Strategic Acquirers: The window for entry favors modular architecture specialists with microinverter coupling expertise and software-defined fleet orchestration platforms. Long-term viability hinges on virtual power plant aggregation licensing and utility-scale demand response contract access. Monitor FERC interconnection rulemakings and state-level net metering reform timelines as inflection indicators for storage attachment rate acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Virtual Power Plant Aggregation Licensing | Unlocks incremental revenue streams beyond self-consumption for residential battery fleets in deregulated ERCOT and CAISO markets. |
| Sodium-Ion Chemistry Scale-Up | Reduces lithium carbonate dependency for cost-sensitive seasonal storage applications with moderate cycle depth requirements. |
| Hybrid Inverter Platform Integration | Compresses balance-of-system costs and commissioning timelines for California and Texas suburban installers. |
| Backward Integration into Cathode Supply | Secures allocation priority and margin protection against Asian supplier concentration risks. |
| EU Green Deal Certification Program | Qualifies bundled solar-storage packages for preferential mortgage rates in German and Dutch new construction markets. |
Research Methodology
Independent corroboration across utility interconnection databases, state regulatory filings, and equipment certification registries underwrites the qualitative findings in this study. Primary interviews with IPP project developers, EPC contractors, utility planning officers, and grid operators combined with secondary validation from FERC filings, EIA deployment data, IEA technology roadmaps, and Clean Energy Council safety standards. Bottom-up installation counts and top-down market sizing triangulate volume estimates across the analysis window.
Comparable-period anchoring to historical NEM 2.0 attachment rates and pre-reform German feed-in tariff penetration levels structured the forecast framework across the projection horizon. Segmentation dimensions modeled include electrochemical chemistry, integration architecture, application use case, procurement channel, and regional regulatory cluster. CAGRs were derived from installer survey data on system pricing trajectories and cell cost curve assumptions, with lithium carbonate spot price volatility and interconnection queue timelines as key forecast inputs.
Inputs from EPC contractors and utility interconnection officers were available through the study window; gaps in proprietary fleet performance data from virtual power plant operators introduce uncertainty bands around revenue stacking projections. Forecasts reflect documented assumptions on policy continuity and supply chain cost trajectories. Practitioners should monitor FERC Order 2222 implementation progress and lithium carbonate futures pricing for early signals of forecast revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.