
 Global Carbon Steel Tubing in Oil and Gas Lift Applications Market | 2026-2036
Global Carbon Steel Tubing in Oil and Gas Lift Applications Market Size, Share, and Industry Trends Forecast 2026-2036
Global Carbon Steel Tubing in Oil and Gas Lift Applications Market Intelligence
Demand from agile independent producers focused on unconventional assets is collapsing the long-cycle procurement models historically favored by major petroleum refiners. This shift favors suppliers with responsive supply chains. Tenaris leverages its extensive global manufacturing footprint to serve these varied customers. Vallourec specializes in premium connections and high-strength grades for complex wells, while ArcelorMittal competes on production scale and its integrated steelmaking capabilities.
Carbon steel tubing for oil and gas lift applications comprises tubular products engineered to withstand high pressures and corrosive downhole environments. Manufactured primarily to API 5CT specifications using specific grades like J55 or N80, this tubing forms the conduit for artificial lift systems. Seamless tubing continues to command the market for high-pressure gas lift systems. In contrast, Electric Resistance Welded (ERW) tubing offers a cost-effective alternative for lower-pressure applications such as rod lift.
Product quality and interoperability are governed by standards from the American Petroleum Institute (API) and the International Organization for Standardization (ISO). Environmental regulations from bodies like the U.S. EPA and similar authorities in Canada and Brazil influence material selection and integrity testing protocols. Producers must now balance the pursuit of cost efficiency in manufacturing with investments in material grades capable of meeting stricter performance mandates for deeper wells.
Market Dynamics
The imperative to maximize recovery from mature and unconventional oil and gas fields serves as the central structural force in this market. This dynamic elevates the technical requirements for artificial lift systems, directly influencing demand for carbon steel tubing engineered for higher pressures and more complex well conditions.
Growth Catalysts
- Enhanced Oil Recovery Programs:The redevelopment of aging reservoirs in basins across North America and the North Sea necessitates new gas lift and rod lift installations, driving recurring demand for API-grade tubing.
- Unconventional Asset Development:Hydraulic fracturing operations in shale plays, particularly in the United States and Argentina, require durable tubing solutions capable of withstanding the stresses of multi-stage completions and production cycles.
- API Specification Updates:Evolving API 5CT standards for material toughness and connection performance compel operators to upgrade their tubular inventories, creating a replacement cycle for higher-performance carbon steel grades.
Market Restraints
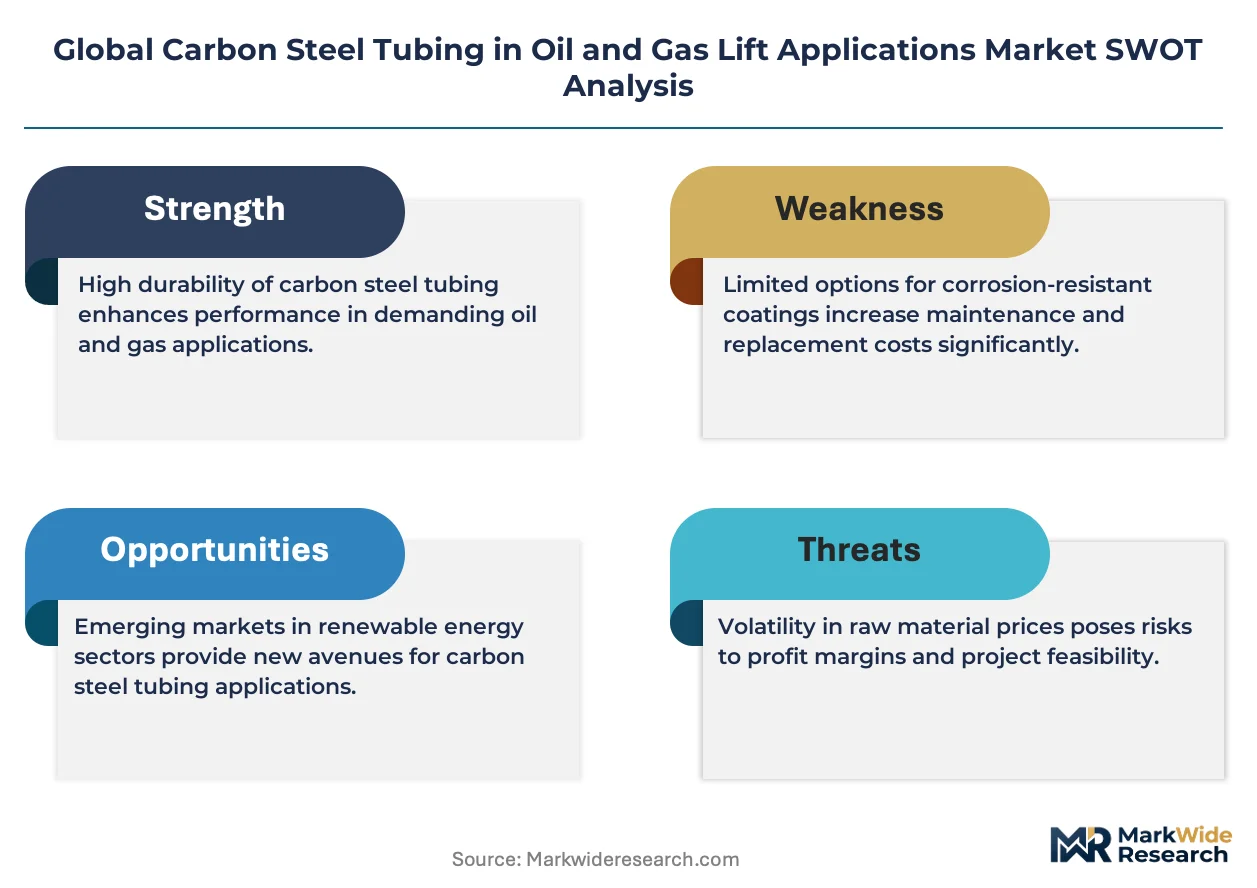
- Input Cost Volatility:Fluctuations in the price of key raw materials, particularly iron ore and metallurgical coal, create significant cost pressure and margin uncertainty for tubing manufacturers.
- Corrosion in Sour Service:Carbon steel tubing faces technical limitations in wells with high concentrations of hydrogen sulfide (H2S), creating a performance ceiling and risk of failure without costly chemical inhibition programs.
- Substitution from Alternatives:In ultra-high-pressure or highly corrosive environments, the performance advantages of Corrosion Resistant Alloys (CRAs) and composite tubing present a persistent substitution threat.
Strategic Opportunities
- Deepwater and Offshore Expansion:Major offshore projects, especially in Brazil's pre-salt fields and Guyana, represent a significant opportunity for suppliers of high-strength seamless tubing with premium connections.
- Carbon Sequestration Projects:The build-out of Carbon Capture, Utilization, and Storage (CCUS) infrastructure creates a new application vertical for tubular goods used in CO2 injection and monitoring wells.
- Digital-Ready Tubing:Integrating fiber optic sensing capabilities or other digital markers into tubing offers a path to value-added services for real-time downhole monitoring and well integrity management.
Industry Challenges
- Manufacturing Lead Times:The production of specialized seamless tubing grades, especially for sour service or high-collapse applications, involves long lead times that complicate operator project planning and inventory management.
- Talent Gaps in Welding:A shortage of welders and technicians certified to work with proprietary premium connections creates installation bottlenecks and increases operational risk for exploration and production companies.
- Fragmented Regulatory Landscapes:Manufacturers must navigate a complex web of environmental and safety standards from different authorities, such as the U.S. EPA and Canada's provincial regulators, increasing compliance costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Carbon Steel Tubing in Oil and Gas Lift Applications Market |
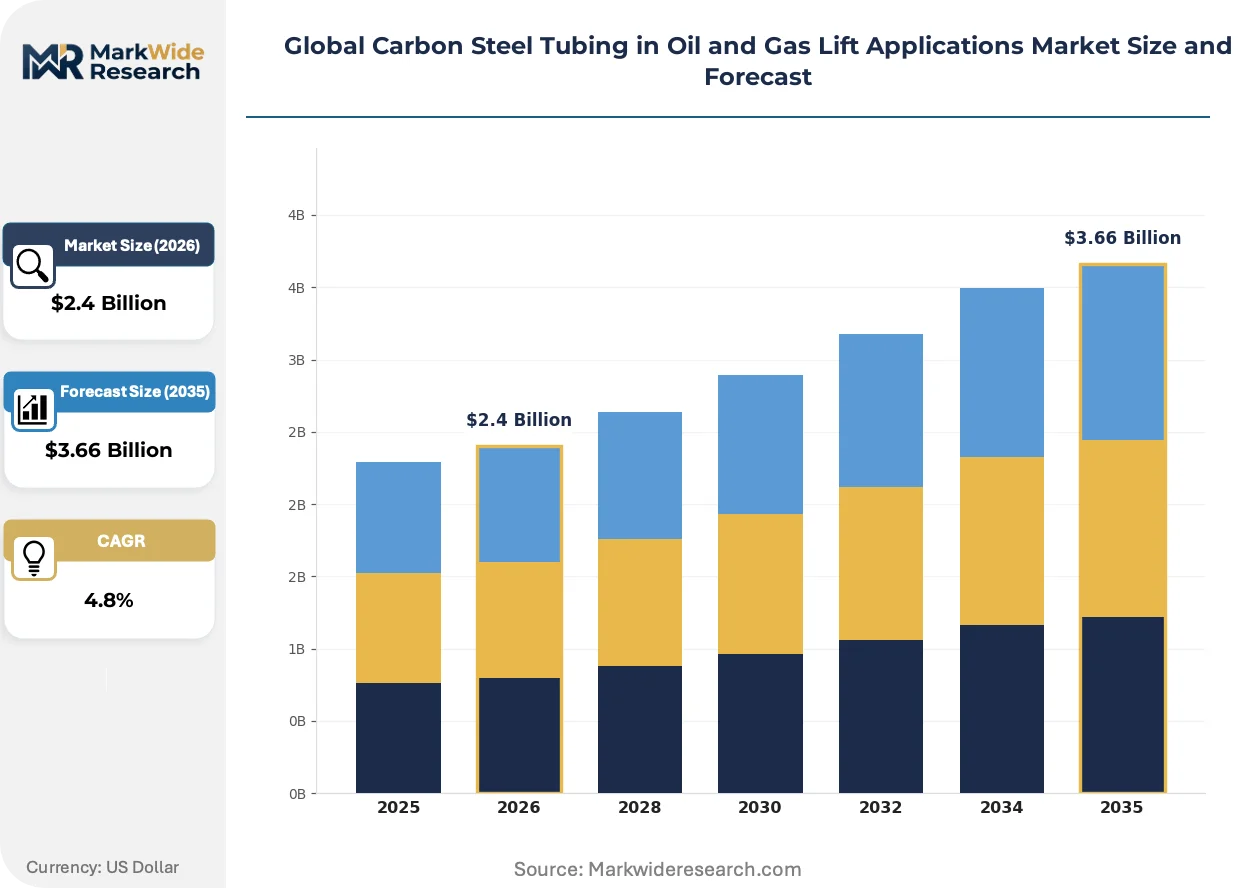
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.66 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Seamless Tubing, Welded Tubing, ERW Tubing, Cold Drawn Tubing Application: Rod Lift, Gas Lift, Electrical Submersible Pump, Plunger Lift, Progressive Cavity Pump End User: Petroleum Refiners, Independent Producers, Service Operators, Pipeline Companies Service Type: Inspection, Maintenance, Repair, Installation, Testing |
| Companies Covered | Tenaris, Vallourec, Nippon Steel Corporation, ArcelorMittal, U.S. Steel Tubular Products, Webco Industries, JFE Holdings, TMK Group, Marcegaglia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Carbon Steel Tubing in Oil and Gas Lift Applications Market Strategic Shifts & Innovations
Material science advancements and evolving operational philosophies are redefining performance expectations for carbon steel tubing. The focus is shifting from basic conveyance to ensuring long-term well integrity and meeting stricter environmental mandates, pushing innovation in both metallurgy and connection technology.
Advanced high-strength, low-alloy (HSLA) steel grades offer enhanced mechanical properties and improved resistance to specific downhole corrosive agents. Operators in complex fields, such as those with high-pressure gas lift requirements, are steadily adopting these materials. The availability of these intermediate-performance steels is decomposing the market's rigid, binary choice between standard carbon steel and far more expensive corrosion-resistant alloys.
Environmental regulations targeting methane abatement, including new rules from the U.S. EPA and similar initiatives in Canada, are influencing product selection. These mandates increase the emphasis on gas-tight premium connections to prevent fugitive emissions from wellheads and production strings. Gas lift systems in particular are facing heightened scrutiny, compelling a move toward tubing connections with validated performance under API and ISO testing protocols.
Agile purchasing models are disrupting traditional supply chain relationships, especially in fast-cycle unconventional plays. This trend favors suppliers capable of providing just-in-time inventory from regional service centers rather than relying on long-lead-time mill runs. This shift in procurement behavior is most visible in North American shale basins, where independent producers prioritize speed and flexibility in their drilling programs.
Global Carbon Steel Tubing in Oil and Gas Lift Applications Market Segmentation
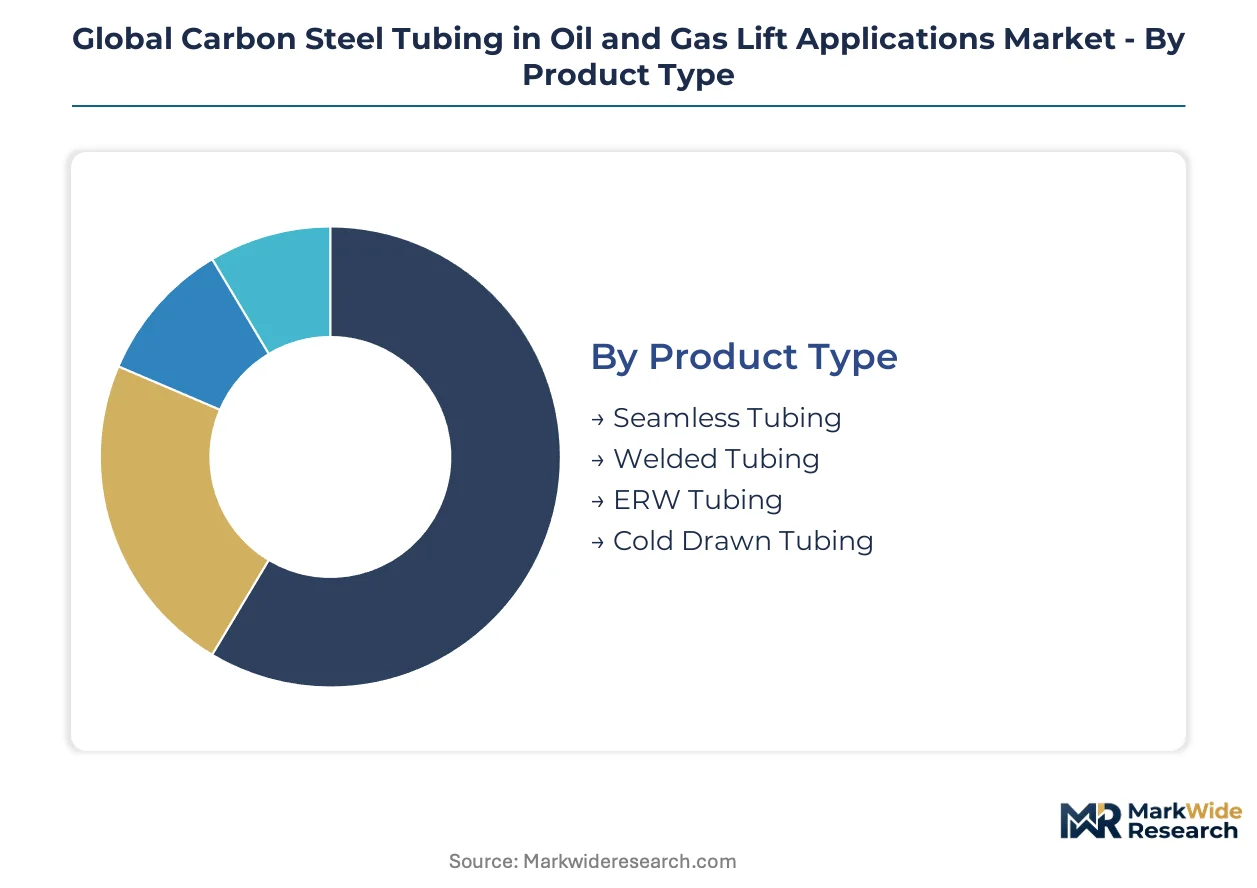
Understanding the varied requirements across the carbon steel tubing market is essential for suppliers to align product offerings and service models effectively. This market segments based on the specific manufacturing process, the artificial lift technology employed, the operational profile of the end-user, and the lifecycle support services required.
Product Type:
The procurement channels for carbon steel tubing vary significantly based on the product’s manufacturing process and intended application.
- Seamless Tubing:Seamless tubing involves piercing a solid steel billet, offering superior pressure containment and integrity for demanding downhole conditions. Demand concentrates in Brazil's deepwater projects, where high-strength materials are critical for complex well designs.
- Welded Tubing:Welded tubing is manufactured by forming steel plates or strips into a cylindrical shape and joining the edges with a weld, suitable for less critical applications. This product type finds use in various onshore shallow well completions.
- ERW Tubing:Electric Resistance Welded (ERW) tubing is formed from steel strip and welded longitudinally, providing a cost-effective solution for less strenuous applications. North American shale basins utilize ERW tubing extensively for rod lift systems due to its economic efficiency.
- Cold Drawn Tubing:Cold drawn tubing undergoes a cold-working process to achieve precise dimensions and enhanced mechanical properties for specific performance needs. This specialized tubing serves niches requiring tighter tolerances.
Seamless Tubing dominates the installed base for high-pressure gas lift systems. ERW Tubing is where expansion concentrates for cost-sensitive unconventional plays.
Application:
The performance demands placed on carbon steel tubing are directly shaped by the specific artificial lift technology employed in a well.
- Rod Lift:Rod lift systems utilize a reciprocating pump powered by a surface unit, creating a lower pressure environment for the tubing compared to gas lift. Rod lift applications are expanding in US shale plays, offering an efficient method for lower-volume wells.
- Gas Lift:Gas lift systems inject high-pressure gas into the production string to reduce the density of the fluid column, requiring tubing with high burst strength and integrity. Demand for gas lift applications is strong in mature North Sea fields, supporting enhanced oil recovery initiatives.
- Electrical Submersible Pump:Electrical Submersible Pump (ESP) systems use a downhole pump driven by an electric motor, necessitating tubing capable of housing power cables and handling fluid flow. ESP applications are common in high-volume wells across various global regions.
- Plunger Lift:Plunger lift systems employ a free-traveling plunger to remove liquids from gas wells, requiring tubing with a smooth internal bore for efficient operation. This method is gaining traction in gas-producing regions of Canada.
- Progressive Cavity Pump:Progressive Cavity Pump (PCP) systems use a helical rotor within a stator to move viscous fluids, demanding tubing robust enough for abrasive and heavy oil environments. PCP use is prevalent in heavy oil fields, including those in Venezuela.
Gas Lift applications drive the need for premium tubing grades. Rod Lift systems represent a growing segment for standard carbon steel products.
End User:
The purchasing strategies and technical specifications for carbon steel tubing are heavily influenced by the operational scale and strategic priorities of distinct end-user categories.
- Petroleum Refiners:Major petroleum refiners, often operating integrated upstream and downstream assets, typically engage in long-cycle procurement models for their tubing needs. Their operations in the Gulf of Mexico demand robust, high-integrity tubular goods for offshore platforms.
- Independent Producers:Independent producers, characterized by agile operations and a focus on unconventional assets, prioritize rapid delivery and flexible supply chains for their tubing requirements. These producers are particularly active in the Permian Basin, driving demand for responsive suppliers.
- Service Operators:Service operators provide equipment and personnel to exploration and production companies, often requiring a diverse inventory of tubing for various project scopes. These companies support drilling and completion activities across multiple international markets.
- Pipeline Companies:Pipeline companies primarily focus on the transportation of oil and gas, utilizing tubing for specific well connections or infrastructure maintenance rather than primary production. Their tubing needs are highly specialized for connection integrity.
Independent Producers are rapidly shaping new procurement models. Petroleum Refiners maintain consistent demand for established tubing standards.
Service Type:
Ensuring the long-term integrity and operational efficiency of carbon steel tubing throughout its lifecycle necessitates a range of specialized service offerings.
- Installation:Installation services involve the precise running and make-up of tubing strings into the wellbore, requiring specialized equipment and skilled technicians. Offshore projects in Guyana demand highly experienced installation crews for complex deepwater completions.
- Maintenance:Maintenance services focus on preventative measures and corrective actions to uphold tubing performance and prevent failures, including cleaning and minor repairs. Regular maintenance protocols are critical for extending tubing life in corrosive environments across Canadian heavy oil fields.
- Repair:Repair services address damaged tubing sections or connections, aiming to restore functionality and prevent well integrity issues without full replacement. These services are crucial for managing unexpected failures in aging infrastructure.
- Inspection:Inspection services involve non-destructive testing and visual examinations to assess the condition and integrity of tubing, identifying potential defects or corrosion. Regular inspections are mandated by regulatory bodies like the U.S. EPA for well integrity.
- Testing:Testing services include pressure testing, material verification, and performance evaluations to ensure tubing meets specified standards and operational requirements. API and ISO standards govern these critical verification processes.
Installation services are foundational for new well completions. Maintenance services are gaining prominence for life extension in aging assets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global network of oil and gas pipelines, particularly in North America, underwrites demand for carbon steel tubing in critical production regions. This infrastructure facilitates the transport of hydrocarbons from wellheads to processing facilities, requiring robust tubular goods. Demand patterns reflect both mature field redevelopment and new unconventional plays.
United States
Unconventional asset development and enhanced oil recovery programs drive significant demand for carbon steel tubing. U.S. EPA regulations on methane abatement increase the emphasis on gas-tight premium connections for well integrity. The Permian Basin in Texas drives significant activity for rod lift systems and high-pressure gas lift applications.
Brazil
Deepwater and pre-salt field expansion projects propel the need for high-strength seamless tubing with premium connections. ANVISA standards influence material selection and integrity testing protocols for complex offshore operations. Offshore projects in the Campos and Santos Basins require specialized tubular goods for extreme pressure and depth conditions.
Canada
Heavy oil recovery and expanding gas-producing regions create consistent demand for various carbon steel tubing grades. Health Canada and provincial regulators influence integrity testing protocols and material handling in environmentally sensitive areas. Alberta's oil sands and gas plays in British Columbia utilize various artificial lift systems, including plunger lift and rod lift.
Saudi Arabia
Maintaining production levels from mature fields and advancing gas injection programs sustain the market for carbon steel tubing. SFDA regulations ensure material quality and performance for critical oil and gas infrastructure. Eastern Province fields, including Ghawar, rely on tubing for enhanced recovery efforts and production string maintenance.
Norway
North Sea mature field redevelopment and new gas lift installations necessitate premium tubing grades for demanding offshore environments. NORSOK standards dictate stringent material and connection performance for subsea and platform wells. Offshore platforms in the Norwegian Continental Shelf demand premium tubing grades for high-pressure gas lift systems.
Global Carbon Steel Tubing in Oil and Gas Lift Applications Market Key Industry Players
Concentration sits with large, integrated steelmakers and specialized tubular goods manufacturers. The market structure exhibits a tiered approach, with premium product providers serving complex applications and cost-effective suppliers addressing standard requirements. Strategic archetypes include global integrated producers, regional specialists, and niche solution providers. Capacity expansion and strategic partnerships are dominant competitive moves among these players.
Global integrated steelmakers like ArcelorMittal exemplify the scale-driven segment, leveraging extensive raw material access and production capabilities. Specialists such as Tenaris occupy a position in global supply chain responsiveness, serving varied customers with extensive manufacturing footprints. Vallourec represents the premium segment, focusing on high-strength grades and advanced connections for complex well environments.
| Leading Market Players |
|---|
| Tenaris |
| Vallourec |
| Nippon Steel Corporation |
| ArcelorMittal |
| U.S. Steel Tubular Products |
| Webco Industries |
| JFE Holdings |
| TMK Group |
| Marcegaglia |
| Others |
Cost & Logistics Intelligence
Project-based contracts for specialized tubing lock in both supply access and price visibility for large-scale offshore developments, creating stability for premium product segments. Volatility in raw material costs, however, continuously pressures margins for manufacturers of standard grades.
Pricing Analysis
Volume-discount tiering structures characterize pricing across carbon steel tubing, with premium connections and high-strength grades commanding higher prices. Price differentiation stems from material quality grades like API 5CT, specific certification levels, and the volume scale of the order. Cost compression in standard ERW tubing stems from intense competition and overcapacity in some regional markets. Independent producers exhibit the highest price sensitivity, while major petroleum refiners prioritize performance and reliability over marginal cost savings.
Supply Chain Analysis
China, Japan, and South Korea anchor global steel production, providing essential raw materials for carbon steel tubing manufacturing. The supply chain relies heavily on consistent access to iron ore and metallurgical coal, making it vulnerable to input cost volatility. Single-source vulnerabilities for specialized components, like certain premium connection patents, also pose a structural risk. Distribution runs through a dual model of direct mill sales for large contracts and regional service centers for just-in-time inventory, particularly in North American shale basins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive moat story, primarily due to the regulatory entrenchment of API standards that mandate rigorous material and connection performance for well integrity.
For Market Incumbents:Consolidate market share by acquiring niche manufacturers specializing in high-strength grades or premium connection technologies. Invest in advanced material grades to counter substitution threats from Corrosion Resistant Alloys (CRAs) in sour service environments. Expand global manufacturing footprints to serve agile independent producers, leveraging existing certifications and established supply chains. Focus R&D on gas-tight premium connections to meet evolving environmental regulations from bodies like the U.S. EPA.
For New Entrants and Emerging Players:Anchor in cost-effective ERW tubing solutions for rod lift systems, targeting the expanding unconventional plays in North America. Identify white-space opportunities in value-added services, such as integrating fiber optic sensing capabilities into tubing for real-time monitoring. Develop responsive supply chains with regional inventory hubs to meet the rapid delivery demands of independent producers. Focus initial market penetration on less critical applications where cost efficiency is a primary driver.
For Investors and Strategic Acquirers:Capital is best deployed toward specialized manufacturers of seamless tubing and premium connection providers that offer proven solutions for deepwater and sour service applications. The long-term viability of this market is secured by the imperative for enhanced oil recovery and emerging carbon sequestration projects. An acquisition target archetype includes companies with strong intellectual property in connection technology or advanced metallurgical capabilities. Increased investment in Carbon Capture, Utilization, and Storage (CCUS) infrastructure serves as a key signal to watch for market expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for HSLA Grades | Addresses the growing demand for higher-performance materials in complex well conditions. |
| Premium Connection R&D | Enhances well integrity and reduces fugitive emissions, meeting stricter environmental mandates. |
| Regional Service Center Network | Improves supply chain responsiveness for independent producers in fast-cycle unconventional plays. |
| Digital Integration in Tubing | Offers new value-added services for real-time downhole monitoring and operational efficiency. |
| Carbon Capture Project Partnerships | Opens new application verticals for tubular goods in CO2 injection and monitoring wells. |
Research Approach
The analysis maps product types, artificial lift applications, end-users, and service types, each validated through extensive primary interviews with production engineers, procurement managers, material scientists, and regulatory compliance officers. Secondary validation draws from API standards, ISO specifications, U.S. EPA reports, and company financial filings. Bottom-up and top-down triangulation ensures robust data integrity.
Consistency checks against historical market performance and industry benchmarks informed the analytical framework across the analysis window. Segmentation dimensions modeled include product type, specific artificial lift application, end-user category, service type, and material grade. Compound annual growth rates were derived from historical trends, market drivers, and specific industry inputs such as crude oil prices and natural gas prices.
Underlying assumptions cover stable geopolitical conditions, with deviation risk concentrated in raw material price shocks or unforeseen shifts in global energy policy. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Riserless Light Well Intervention Market
Oil & Gas
Oilfield Air Drilling Market
Oil & Gas
Norway Oilfield Equipment Market
Oil & Gas
Algeria Oil and Gas Upstream Market
Oil & Gas
Coal Seam Gas Market
Oil & Gas
China Oil and Gas Market
Oil & Gas
Global Drilling Jars Market
Oil & Gas
Marine Oil Water Separators Market
Oil & Gas
Russian Federation Oil and Gas Upstream Market
Oil & Gas
Oil and Gas Security Services Market
Oil & Gas
Europe Hydraulic Fracturing Market
Oil & Gas
India Artificial Lift Systems Market
Oil & Gas
Global LNG Liquefaction Equipment Market
Oil & Gas
Oilwell Spacer Fluids Market
Oil & Gas
United States Onshore Drilling Fluid Market
Oil & Gas
East Africa Oil and Gas Market