
 Barium Fluoride Market | 2026-2036
Barium Fluoride Market Size, Share, and Industry Trends Forecast 2026-2036
Barium Fluoride Market Intelligence
The EU F-Gas Regulation is hardening fluorochemical sourcing requirements across optical component supply chains. Solvay leverages its integrated fluorine chemistry platform to sustain high-purity barium fluoride output for European photonics customers. American Elements anchors North American supply through vertically controlled rare earth and alkaline earth processing. Merck KGaA competes on electronic-grade material certification for semiconductor lithography systems.
Barium fluoride is an inorganic compound with the chemical formula BaF₂, exhibiting transmission from the deep ultraviolet through the mid-infrared range and a melting point of 1368°C, making it essential for optical windows, lenses, and prisms in demanding spectroscopic and laser applications. Optical-grade crystals command premium positioning due to stringent bubble and inclusion specifications required by defense and research end users. Powder and pellet formats serve industrial-grade scintillator manufacturing where purity thresholds remain lower but volume throughput scales faster.
EPA oversight governs fluorochemical waste streams in the United States, while REACH registration in Europe mandates full toxicological dossiers for barium fluoride importers and manufacturers. China's GB standards and Japan's JIS specifications create divergent purity benchmarks that fragment qualification protocols for multinational suppliers. Stakeholders must monitor regulatory harmonization progress between these jurisdictions to anticipate compliance cost shifts and qualification timeline changes.
Market Dynamics
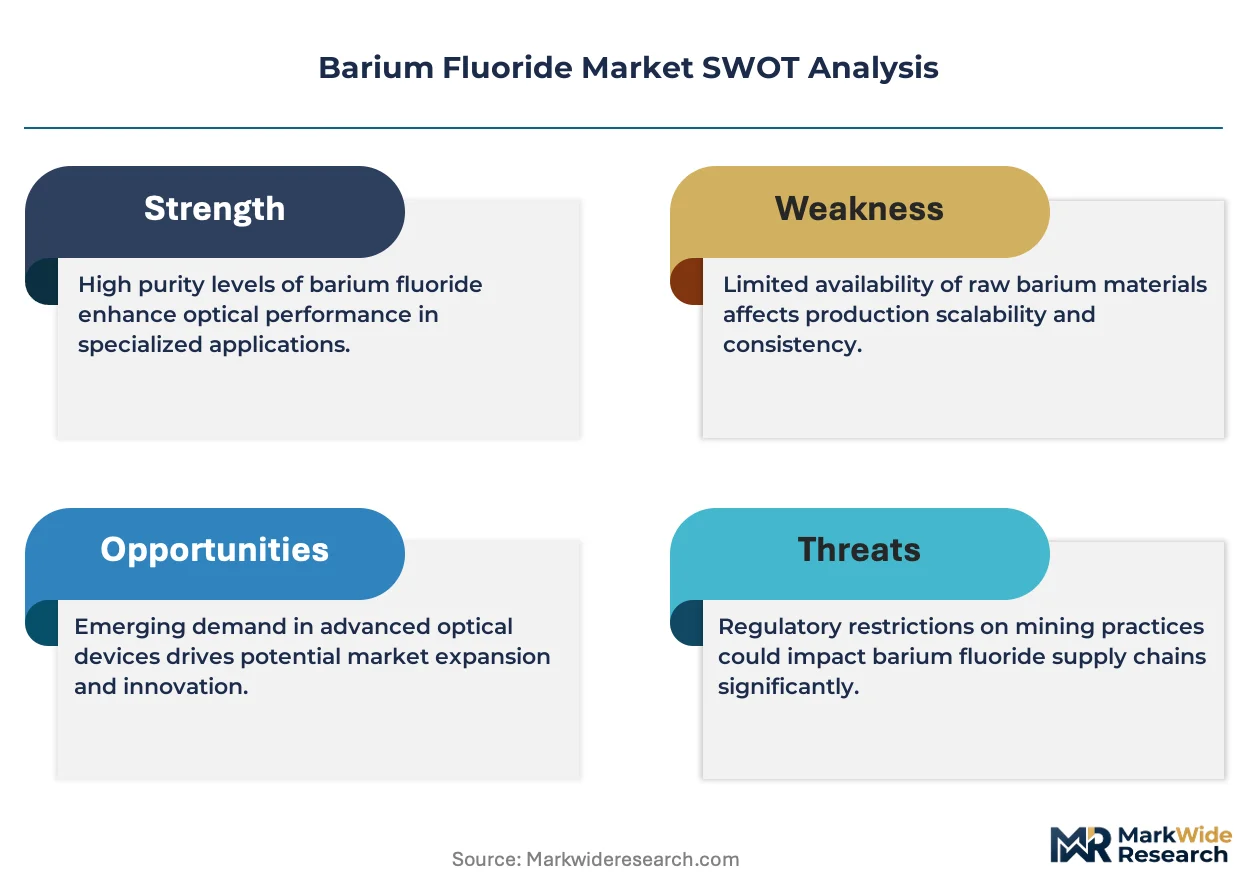
Optical-grade crystal qualification protocols are fragmenting as defense procurement agencies impose divergent purity specifications across jurisdictions, forcing suppliers to maintain parallel production streams and certification dossiers.
Growth Catalysts
- REACH Registration Mandates:European ECHA requirements for full toxicological dossiers are consolidating compliant supplier bases and locking out marginal producers unable to bear documentation costs.
- Infrared Spectroscopy Expansion:Defense agencies in multiple jurisdictions are specifying barium fluoride windows for thermal imaging systems, creating pull-through demand for certified optical-grade material.
- China's GB Standard Harmonization:Beijing's alignment of national purity benchmarks with semiconductor lithography requirements is opening qualification pathways for domestic crystal growers.
Market Restraints
- Fluorspar Input Volatility:Acid-grade fluorspar concentrate prices swing with Chinese export quota decisions, compressing margin predictability for fluoride processors.
- Single-Source Crystal Growth Equipment:High-temperature Bridgman furnace fabrication concentrates among German and Japanese equipment houses, creating bottleneck risk for capacity expansion.
- Calcium Fluoride Substitution:UV-transmitting CaF₂ lenses are displacing BaF₂ in select deep-UV lithography stages where water immersion compatibility permits material switching.
Strategic Opportunities
- Scintillator Pellet Industrialization:Radiation detection OEMs are qualifying lower-purity pressed pellet formats for volume security screening deployments, opening throughput-scaled revenue pools.
- EU Green Deal Fluorine Recovery:Brussels' circular economy mandates for fluorochemical waste valorization are creating first-mover advantage for integrated processors with captive recycling infrastructure.
- Quantum Sensor Cryogenics:Superconducting detector research programs are specifying barium fluoride substrates for cryogenic optical interfaces, seeding next-generation application development.
Industry Challenges
- Crystal Growth Technician Scarcity:Mastery of oxygen-free atmosphere Bridgman techniques requires decade-long apprenticeship pipelines that universities no longer supply.
- Dual-Use Export Licensing Friction:ITAR and EU dual-use regulations impose 90-180 day approval windows on optical-grade shipments, disrupting just-in-time defense supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Barium Fluoride Market |
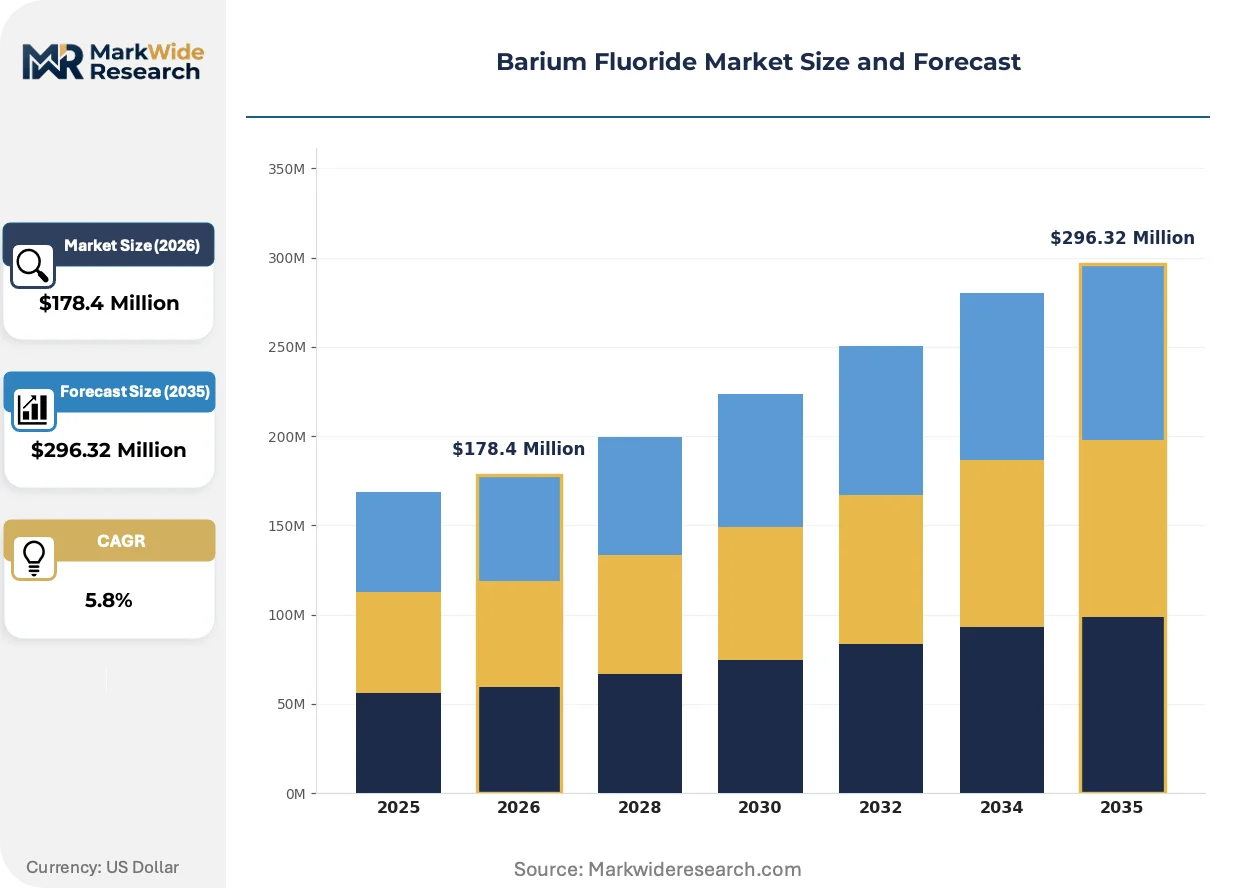
| Market Size in 2026 | $178.4 Million |
| Market Size in 2035 | $296.32 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crystals, Powder, Pellets, Optical Windows Grade: Electronic Grade, Optical Grade, Industrial Grade, Purified Grade Application: UV Optics, Infrared Spectroscopy, Scintillators, Laser Systems, Radiation Detectors End User: Research Institutes, Defense Sector, Electronics Manufacturers, Scientific Laboratories |
| Companies Covered | Solvay, American Elements, Barium & Chemicals, Inc., GFS Chemicals, Inc., Super Conductor Materials, Inc., Alfa Aesar, Thermo Fisher Scientific, International Crystal Laboratories, All-Chemie, Ltd., Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Barium Fluoride Market Strategic Shifts & Innovations
Advanced crystal growth automation and regulatory data digitization are compressing qualification timelines while fragmenting supplier competitive advantages across certification tiers.
Machine-learning-guided thermal gradient control in Bridgman furnaces is rewriting yield economics for optical-grade boule production. Defense prime contractors are qualifying AI-optimized crystal lots for infrared window applications within 18-month cycles rather than legacy 36-month protocols. This compression is enabling smaller crystal houses to contest historically entrenched supply relationships.
EPA fluorochemical waste stream oversight is hardening discharge permitting for United States-based processors. Facilities must now demonstrate closed-loop fluoride recovery exceeding 95% mass efficiency to maintain operating licenses. Semiconductor lithography material suppliers are responding by consolidating etching and refining operations to capture waste streams internally.
Defense procurement offices are unbundling optical component specifications from system integrator contracts, enabling direct qualification relationships with crystal growers. This disintermediation is visible in United Kingdom and Australian thermal imaging programs where national laboratories now certify window suppliers independently of prime contractors. The shift rewards specialized crystal houses with documented pedigree traceability.
Barium Fluoride Market Segmentation
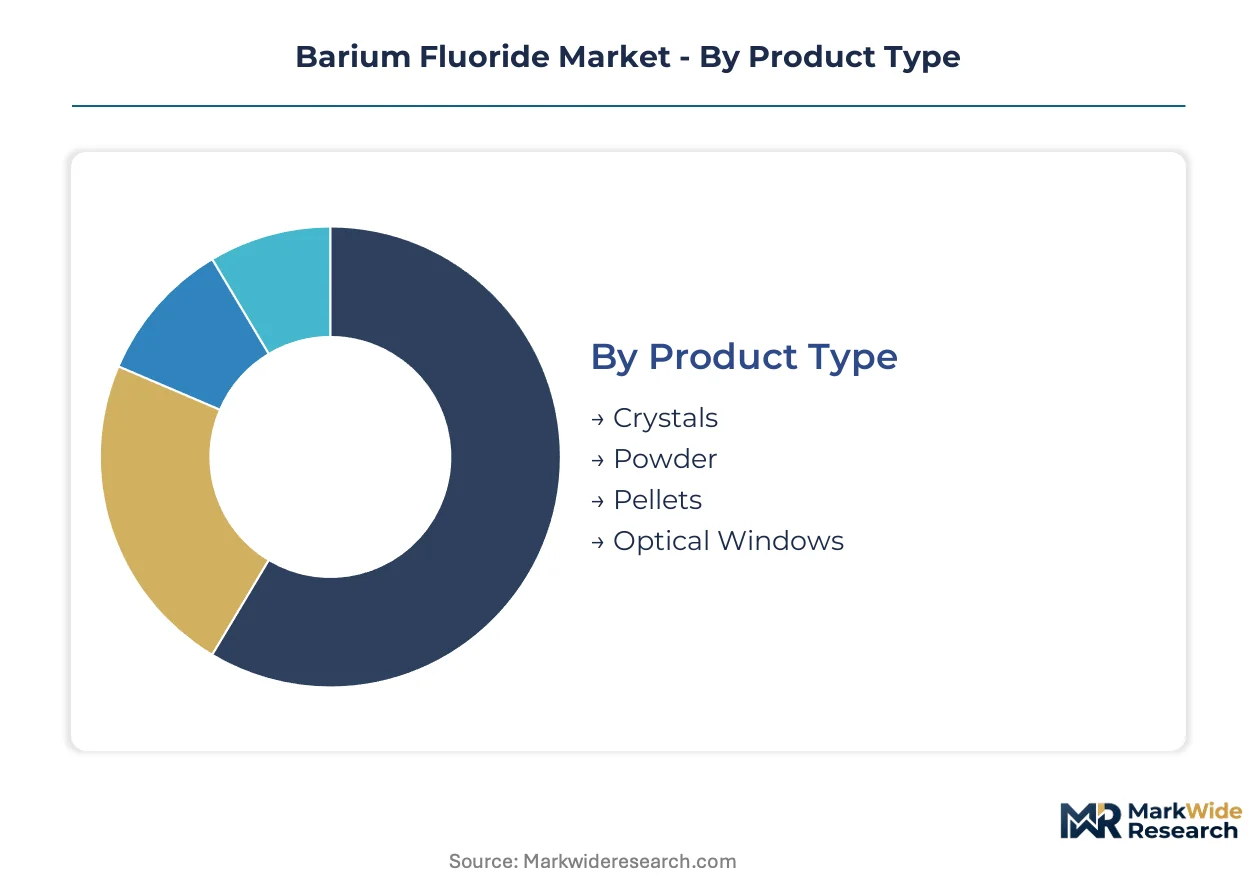
Barium fluoride supply chains fragment sharply across specification tiers. Crystal growers, powder processors, and defense integrators operate under divergent purity protocols and qualification timelines that reshape procurement patterns.
Product Type:
Technical specifications determine pricing power and customer stickiness across the four product formats.
- Crystals:Single-crystal boules grown via Bridgman methods transmit from deep UV through mid-infrared. Defense agencies in the United States and Japan specify these for thermal imaging windows, with qualification cycles stretching 18-36 months.
- Optical Windows:Precision-polished flats and domes serve spectroscopic instruments and laser systems. German and Japanese equipment houses dominate the high-temperature furnace fabrication required for optical-grade production, creating supply bottlenecks.
- Powder:Milled particulate feeds scintillator manufacturing where lower purity thresholds permit volume throughput scaling.
- Pellets:Pressed cylindrical forms streamline radiation detector assembly for security screening deployments.
Mature deployment sits with Crystals. Newer deployment is concentrated in Pellets.
Grade:
Certification tiers separate defense-aerospace suppliers from commodity chemical processors.
- Optical Grade:Stringent bubble and inclusion specifications command premium positioning. ECHA REACH registration mandates and EPA fluorochemical waste oversight force documentation investments that lock out marginal producers.
- Electronic Grade:Semiconductor lithography systems demand this tier for deep-UV transmission compatibility. Merck KGaA and Solvay compete on material certification for photonics customers.
- Industrial Grade:Bulk chemical applications tolerate higher impurity loads.
- Purified Grade:Intermediate refinement for specialty optical coatings.
Established revenue concentration rests with Optical Grade. Expanding most quickly is Electronic Grade.
Application:
End-use performance requirements fragment supplier competitive advantages.
- Infrared Spectroscopy:Thermal imaging windows for defense platforms drive pull-through demand. United Kingdom and Australian procurement offices now certify suppliers independently of system integrators.
- UV Optics:Deep-UV lithography stages specify barium fluoride where water immersion compatibility matters, though calcium fluoride substitution pressures this segment.
- Scintillators:Radiation detection OEMs qualify pressed pellet formats for volume security screening.
- Laser Systems:High-power laser windows require thermal shock resistance.
- Radiation Detectors:Nuclear monitoring applications span industrial and scientific end users.
Longstanding demand anchors Infrared Spectroscopy. Gaining share fastest is Scintillators.
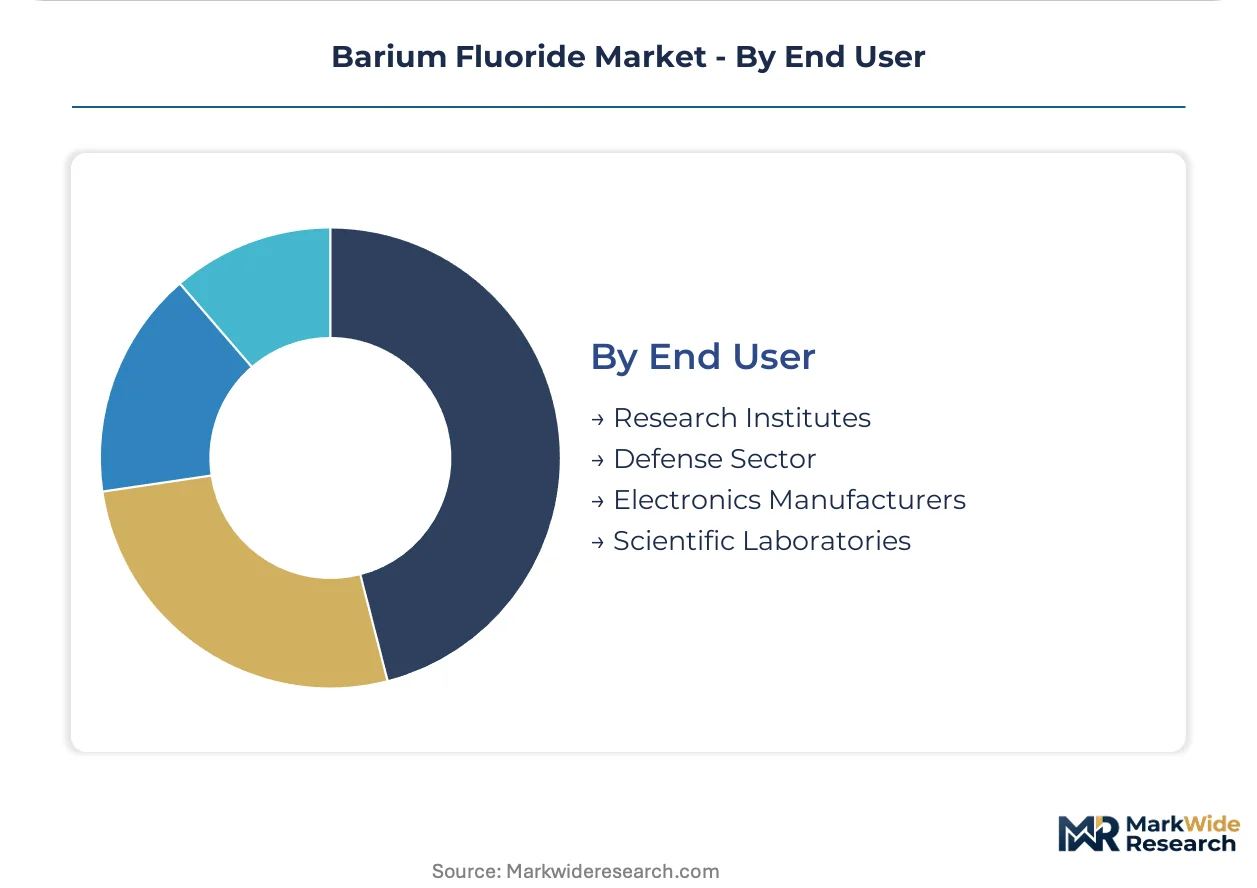
End User:
Procurement sophistication and qualification timelines diverge sharply across customer categories.
- Defense Sector:ITAR and EU dual-use regulations impose 90-180 day approval windows on optical-grade shipments. National laboratories in multiple jurisdictions now maintain direct supplier relationships.
- Research Institutes:Academic and government laboratories specify smaller volumes with demanding pedigree documentation.
- Electronics Manufacturers:Semiconductor fabs require electronic-grade certification for lithography systems.
- Scientific Laboratories:Analytical instrument builders source optical components for spectroscopy platforms.
Contract maturity concentrates with Defense Sector. Procurement momentum is shifting toward Electronics Manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai anchors global barium fluoride crystal fabrication, with Chinese producers supplying optical-grade boules to defense contractors across three continents. National purity benchmarks and export licensing protocols fragment procurement timelines for multinational buyers.
China
Semiconductor lithography expansion and thermal imaging defense programs drive crystal demand. GB standards harmonization with semiconductor-grade specifications accelerates domestic qualification pathways. Shanghai and Jiangsu province host the dominant Bridgman furnace clusters serving Asian photonics supply chains.
United States
Defense agency infrared spectroscopy specifications and EPA fluorochemical waste oversight shape procurement patterns. ITAR licensing imposes 90-180 day approval windows on optical-grade shipments. Texas and Arizona processing facilities consolidate etching operations to capture waste streams internally under tightened discharge permits.
Germany
EU F-Gas Regulation compliance and REACH registration mandates filter supplier bases for European photonics customers. ECHA toxicological dossier requirements lock out marginal producers unable to bear documentation costs. Bavarian chemical processors leverage integrated fluorine chemistry platforms for high-purity output.
Japan
JIS specifications for optical-grade crystals diverge from Chinese and American benchmarks, forcing parallel certification streams. METI-supported research programs specify barium fluoride substrates for quantum sensor cryogenics. Nagoya and Kyushu industrial corridors concentrate high-temperature furnace fabrication expertise.
United Kingdom
National laboratory certification of window suppliers proceeds independently of prime contractor relationships under new procurement protocols. Defense procurement offices unbundle optical component specifications from system integrator contracts. Scottish and English research facilities drive pedigree documentation requirements for smaller crystal houses.
Barium Fluoride Market Key Industry Players
The competitive structure tilts toward integrated fluorochemical processors with captive raw material supply. Three tiers separate optical-grade crystal growers from powder processors and commodity chemical traders. Dominant archetypes include vertically integrated alkaline earth processors, specialized Bridgman furnace operators, and electronic-grade material certifiers. Capacity expansion and strategic partnerships represent the primary competitive moves as qualification timelines compress.
Among European integrated processors, Solvay anchors the high-purity tier through its fluorine chemistry platform serving photonics customers. American Elements occupies a position among North American vertically controlled processors with rare earth and alkaline earth operations. Merck KGaA sits within the electronic-grade certification tier competing on semiconductor lithography material standards.
| Leading Market Players |
|---|
| Solvay |
| American Elements |
| Barium & Chemicals, Inc. |
| GFS Chemicals, Inc. |
| Super Conductor Materials, Inc. |
| Alfa Aesar, Thermo Fisher Scientific |
| International Crystal Laboratories |
| All-Chemie, Ltd. |
| Merck KGaA |
| Others |
Cost & Logistics Intelligence
Acid-grade fluorspar concentrate flows from Chinese export quotas through German furnace fabricators into three-tier pricing structures across premium optical-grade crystals, standard electronic-grade pellets, and economy industrial powders. ECHA REACH registration costs and EPA discharge compliance investments concentrate pricing power with integrated processors possessing captive fluorine chemistry platforms.
Pricing Analysis
Yield-based pricing anchors optical-grade barium fluoride contracts, with defense agencies paying premiums for certified transmission performance in thermal imaging windows. Three-tier pricing structure across premium optical, standard electronic, and economy industrial levels separates qualification-intensive crystal growers from volume pellet processors. Cost compression in industrial-grade powders is intensifying because scintillator OEMs are consolidating supplier bases for security screening deployments. Research institutes exhibit lowest price sensitivity due to pedigree documentation requirements, while commodity chemical traders face margin erosion from fluorspar input volatility.
Supply Chain Analysis
Certification gating through ECHA REACH dossiers, EPA fluorochemical permits, and JIS optical specifications fragments supplier bases and extends qualification timelines for multinational buyers. Bridgman furnace fabrication concentrates in Germany and Japan, drawing from Chinese fluorspar concentrates, German precision equipment, and Japanese JIS-certified crystal growth expertise. Single-source vulnerability sits with high-temperature furnace engineering capacity. Distribution runs through defense prime contractors, semiconductor lithography OEMs, and radiation detector assemblers with divergent purity protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into acid-grade fluorspar sourcing and captive fluoride recovery infrastructure defines competitive positioning in this market. Players securing upstream mineral supply and downstream certification relationships are consolidating margin control.
For Market Incumbents: Anchor market position by acquiring Bridgman furnace operators in Nagoya and Kyushu corridors to secure crystal growth capacity. Invest in AI-guided thermal gradient automation to compress 36-month qualification cycles toward 18-month protocols. Calcium fluoride substitution in deep-UV lithography threatens electronic-grade pricing power. Defend by deepening electronic-grade certification relationships with semiconductor lithography OEMs.
For New Entrants and Emerging Players: Capture scintillator pellet industrialization opportunities in radiation detection security screening, the most penetrable segment due to lower purity thresholds and volume throughput scaling. Target direct qualification relationships with United Kingdom and Australian national laboratories unbundling from prime contractor procurement. Pursue EU Green Deal fluorine recovery infrastructure partnerships as entry credential.
For Investors and Strategic Acquirers: METI quantum sensor cryogenics research program expansion is the leading indicator that superconducting detector substrate demand will reshape long-term crystal specifications. Five-to-ten year viability favors integrated fluorochemical processors with captive rare earth and alkaline earth operations. Acquisition target archetype: specialized Bridgman furnace operators with documented pedigree traceability and national laboratory relationships.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluorspar Sourcing | Secures acid-grade concentrate supply against Chinese export quota volatility for European processors. |
| AI-Guided Crystal Growth Automation | Compresses Bridgman furnace yield optimization cycles from legacy protocols toward 18-month qualification windows. |
| EU Green Deal Fluorine Recovery Infrastructure | Captures Brussels circular economy mandates for 95% mass efficiency closed-loop processing licenses. |
| Direct National Laboratory Qualification | Bypasses defense prime contractor intermediation in United Kingdom and Australian thermal imaging programs. |
| Electronic-Grade Certification Investment | Locks semiconductor lithography material standards against calcium fluoride substitution pressure. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with crystal growth technicians, defense procurement officers at national laboratories, semiconductor lithography material managers, and fluorochemical plant directors combined with secondary validation from ECHA registration databases, EPA discharge permits, and Japanese METI research program disclosures. Bottom-up volume modeling across crystal, powder, pellet, and window formats triangulated against top-down fluorochemical industry aggregates.
Data-stream reconciliation between defense agency procurement specifications, semiconductor fab material certifications, and scintillator OEM pellet qualification protocols shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product format, certification grade tier, end-use application, and regional regulatory cluster. CAGRs derived from weighted average growth contributions across these segments, with specific inputs from infrared spectroscopy defense budgets, lithography system deployment pipelines, and radiation detection security screening procurement.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Chinese fluorspar export policy shifts, calcium fluoride substitution acceleration in semiconductor lithography, and defense procurement unbundling velocity. Forecasts reflect documented assumptions regarding qualification timeline compression and regulatory harmonization progress. A model refresh is warranted upon material change in ECHA REACH registration cost structures or EPA fluorochemical waste discharge enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Absorbent Booms and Socks Market
Specialty Materials
Glass Ionomer Cement Market
Specialty Materials
PVB Interlayers Market
Specialty Materials
Halloysite Market
Specialty Materials
Acrylic Fine Particle Market
Specialty Materials
Niobium Pentoxide Market
Specialty Materials
Crusher Backing Materials Market
Specialty Materials
PCB Prepreg Material Market
Specialty Materials
Reflective Polarizing Films Market
Specialty Materials
Adhesion Laminated Surface Protection Films Market
Specialty Materials
Global Flexible Substrates Market
Specialty Materials
Polyimide Films Market
Specialty Materials
Silicone Solutions Market
Specialty Materials
Global Poly Vents Market
Specialty Materials
Global Cellulose Acetate Market
Specialty Materials
Europe Green Sic Market