
 Leather Testing Machine Market | 2026-2036
Leather Testing Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Leather Testing Machine Market Outlook
The leather testing machine market is rebalancing between premium precision systems and commodity-grade equipment as footwear and automotive buyers diverge on accuracy requirements and capital budgets. Instron leverages its load-frame engineering heritage to dominate high-force tensile and flexural applications for automotive seat leather. Shimadzu sustains technology leadership in spectroscopic and thermal analysis modules that integrate with mechanical testers. Asian Test Equipments competes aggressively on delivered cost for mechanical abrasion and tear units serving small-batch tanneries across South and Southeast Asia.
Leather testing machines evaluate physical, chemical, and mechanical properties of raw hides, finished leather, and bonded materials through calibrated force application, environmental simulation, and surface analysis. Dynamic testing machines subject specimens to repeated stress cycles at controlled frequencies to predict fatigue life in automotive upholstery and shoe soles. Digital testing systems lead technology adoption where footwear brands in Vietnam and Indonesia require automated data logging for buyer compliance portals. Wear testing machines represent the fastest-growing product category as automotive manufacturers expand validation for steering-wheel wraps and seating surfaces. Quality control applications capture the largest share of installed base, though research and development spending is accelerating as bio-based leather alternatives enter pilot production.
ISO 17025 laboratory accreditation frameworks and REACH chemical restrictions in the European Union elevate demand for traceable, multi-parameter testing platforms. The U.S. EPA and California Air Resources Board regulate volatile organic compound emissions from leather finishing, pushing tanneries toward verified testing protocols. China's GB standards and SAMR certification requirements for imported equipment shape procurement decisions among domestic manufacturers. Stakeholders must monitor convergence between mechanical testing and chemical analysis functions as single-platform systems displace separate instrument purchases.
Market Dynamics
Automotive upholstery validation protocols are intensifying test cycle frequency as OEMs extend warranty coverage for interior surfaces, forcing tanneries to upgrade from periodic batch testing to continuous inline quality verification systems.
Growth Catalysts
- REACH chemical compliance:ECHA's restricted substance lists now cover chromium VI and azo dyes, mandating expanded spectroscopic testing capacity at European tanneries.
- Automotive seating production:German and Italian OEMs require abrasion resistance certification for steering-wheel wraps and seat bolsters, driving repeat equipment orders.
- Bio-based leather alternatives:Mycelium and lab-grown collagen materials require new mechanical property baselines, creating demand for modified flexural and tensile fixtures.
Market Restraints
- Capital intensity:Multi-parameter testing platforms require six-figure investments that small-batch tanneries in Bangladesh and Pakistan cannot finance without leasing structures.
- Input cost volatility:Precision load cells and optical sensors depend on rare earth supply chains concentrated in Chinese processing facilities.
- Technical limitation:Existing wear testers cannot simulate the combined UV-thermal-mechanical stress of automotive dashboard environments in single-cycle protocols.
Strategic Opportunities
- Indonesian footwear clusters:Nike and Adidas supplier factories in Java lack accredited laboratories, creating service bureau opportunities for mobile testing units.
- California Proposition 65:Warning label requirements for chromium exposure are pushing US distributors to demand pre-certified leather, favoring exporters with integrated testing.
- Digital twin integration:Convergence of physical testers with predictive material modeling software allows remote calibration and reduced downtime for Vietnam-based manufacturers.
Industry Challenges
- ISO 17025 accreditation timelines:Laboratory certification requires 12-18 months of documented proficiency testing, delaying revenue recognition for new market entrants.
- Legacy system integration:Tanneries running 1990s-era mechanical testers face data format incompatibilities with modern LIMS and buyer compliance portals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Leather Testing Machine Market |
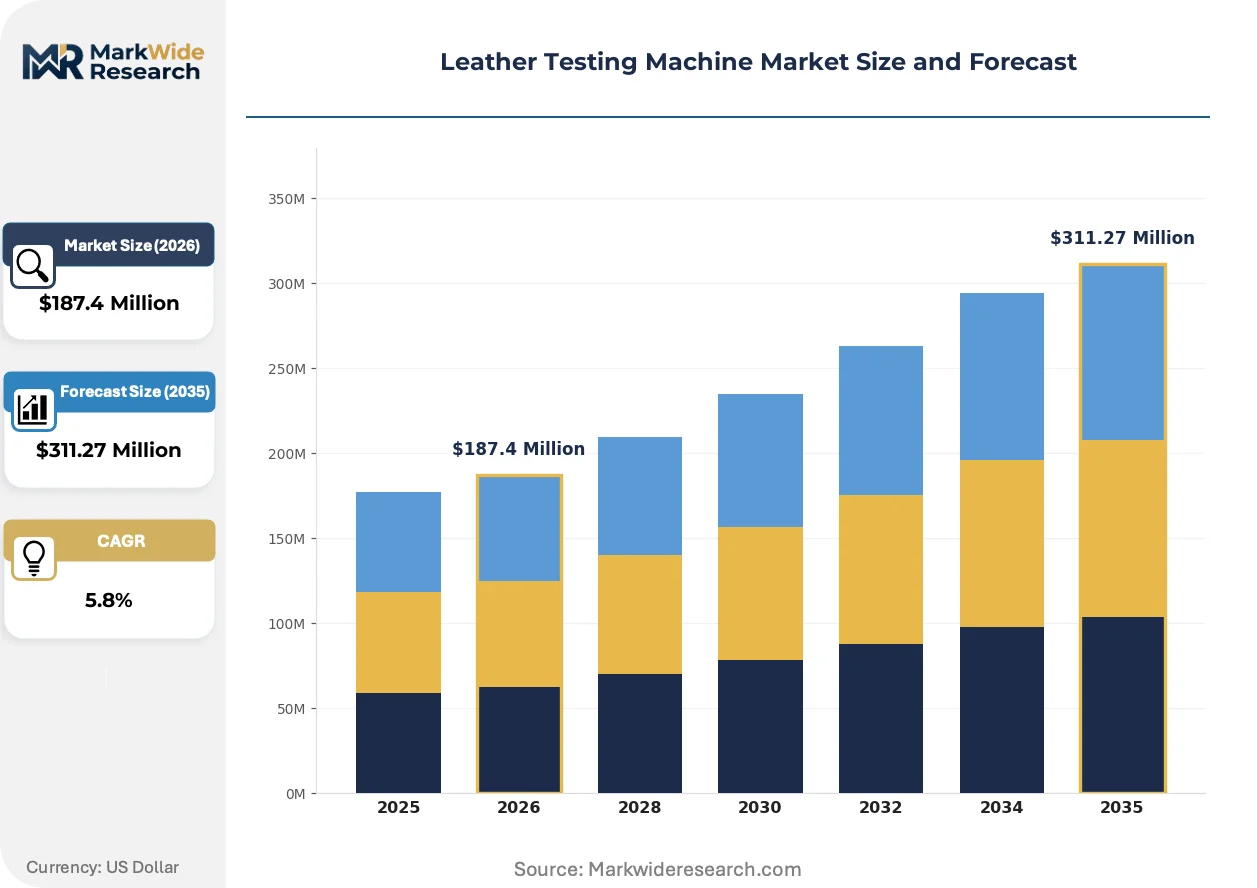
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Static Testing Machines, Dynamic Testing Machines, Wear Testing Machines, Tear Testing Machines End User: Footwear Industry, Automotive Manufacturers, Apparel Producers, Leather Goods Manufacturers Technology: Digital Testing Systems, Mechanical Testing Systems, Microprocessor-based Systems, Hybrid Testing Setups Application: Quality Control, Material Development, Research & Development, Compliance Testing |
| Companies Covered | Ektron Tek Co., Ltd., Agilent Technologies, Asian Test Equipments, Shimadzu, Instron, TESTEX Textile Testing Instruments, AMETEK Inc., MTS Systems, Sataton Instruments Sciences Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Leather Testing Machine Market Strategic Shifts
Testing equipment architecture is bifurcating between benchtop units for rapid QC checks and floor-standing systems for R&D-grade material characterization, with software-defined functionality replacing dedicated hardware modules.
Automated robotic sample handling is expanding into high-throughput tanneries where Vietnamese footwear suppliers process thousands of hides daily. Adidas and Nike compliance teams now mandate digital traceability from cut to finished goods, compressing acceptable test turnaround from 48 hours to 4 hours. This velocity requirement is expanding into mid-tier equipment segments previously served by manual testers.
REACH authorization requirements for dimethyl fumarate and other biocides are forcing European finishers to validate every chemical batch. Tanneries in Italy's Arzignano cluster are retrofitting existing mechanical testers with FTIR modules to avoid separate instrument capital expenditure. The regulatory burden is heaviest on automotive leather suppliers exporting to Germany and France.
Certification-driven procurement now dominates capital equipment selection for export-oriented tanneries. Indonesian and Bangladeshi manufacturers prioritize machines with pre-loaded ISO, ASTM, and IULTCS test methods over lower-cost alternatives lacking accredited protocols. This preference shift is most visible in new facility builds near Ho Chi Minh City and Dhaka's Savar tannery zone.
Leather Testing Machine Market Segmentation
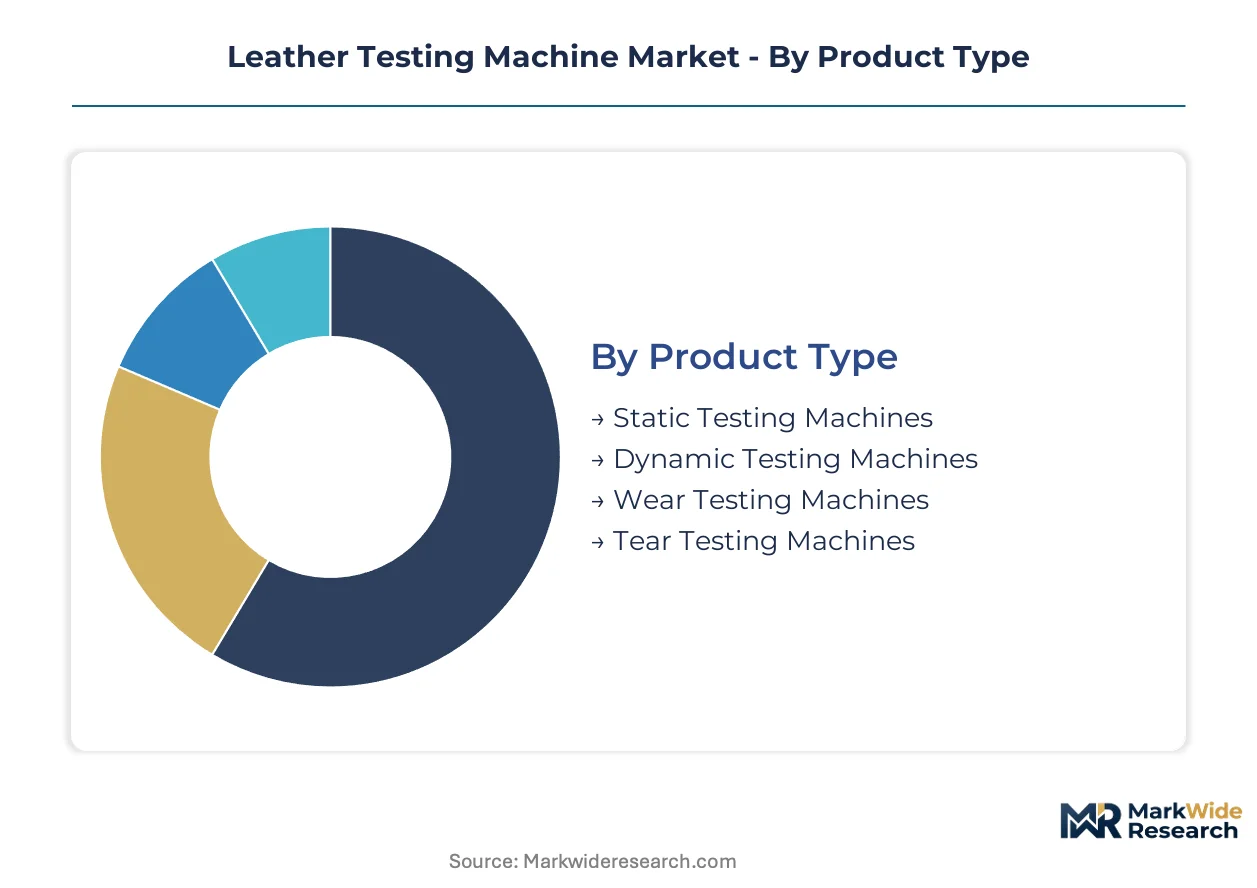
Leather testing machine procurement diverges sharply between high-volume footwear factories demanding rapid throughput and automotive suppliers requiring multi-parameter validation for safety-critical upholstery. Equipment selection hinges on whether buyers prioritize capital efficiency or accreditation depth.
Product Type:
Buyers segment first by test cycle complexity, with capital budgets scaling directly from single-load static units to multi-axis dynamic systems.
- Static Testing Machines:These units apply constant force or displacement to measure tensile strength, elongation, and seam slippage under steady-state conditions. Italian automotive leather suppliers in Arzignano deploy static testers for incoming hide certification where batch consistency matters more than fatigue simulation.
- Dynamic Testing Machines:Systems subject specimens to repeated stress cycles at controlled frequencies, predicting material failure under simulated use. German OEM seating programs in Stuttgart and Munich mandate dynamic validation for steering-wheel wraps exposed to millions of rotational cycles.
- Wear Testing Machines:Equipment simulates surface abrasion through controlled friction against standardized abradants. Vietnamese footwear clusters near Ho Chi Minh City are scaling wear testing capacity for export compliance with Adidas and Nike protocols.
- Tear Testing Machines:Instruments measure resistance to crack propagation using trouser or wing-rip fixtures. Small-batch tanneries in Bangladesh rely on tear testers for basic quality gates before shipment to European distributors.
Static testing machines lead on scale; wear testing machines lead on momentum.
End User:
Application intensity varies by sector, with automotive buyers accepting longer test cycles in exchange for traceable compliance documentation.
- Footwear Industry:Factories in Indonesia's Java cluster process thousands of hides daily, demanding four-hour test turnaround from cut to finished goods. Nike and Adidas compliance portals now reject suppliers lacking automated data logging infrastructure.
- Automotive Manufacturers:German and Italian OEMs extend warranty coverage for interior surfaces, forcing tanneries to upgrade from periodic batch testing to continuous inline verification. REACH chemical compliance adds spectroscopic testing requirements for chromium VI and azo dyes.
- Apparel Producers:Garment leather suppliers focus on color fastness and handle testing for fashion cycles. Italian luxury brands in Tuscany require specialized flexural fixtures for soft glove leathers.
- Leather Goods Manufacturers:Bag and accessory makers in China's Guangdong province prioritize tear and abrasion resistance for high-wear items. Domestic brands are scaling quality assurance infrastructure alongside export growth.
Automotive manufacturers lead on scale; footwear industry leads on momentum.
Technology:
Digital adoption accelerates where buyer compliance portals mandate automated data capture, creating technology tiering between connected and standalone equipment.
- Digital Testing Systems:Platforms integrate load-frame controllers with cloud-based LIMS connectivity, enabling real-time buyer portal uploads. Indonesian supplier factories lacking accredited laboratories are prioritizing digital systems for service bureau partnerships.
- Mechanical Testing Systems:Conventional dial-gauge and manual-load equipment persists in small-batch operations where capital constraints outweigh traceability requirements. Pakistan's tanneries in Karachi maintain mechanical units for basic QC gates.
- Microprocessor-based Systems:Mid-tier equipment offers programmable test sequences without full network integration. Bangladesh's Savar tannery zone favors these units for pre-loaded ISO and ASTM method compliance.
- Hybrid Testing Setups:Configurations combine mechanical actuation with digital data acquisition, bridging legacy infrastructure and modern reporting requirements. Indian manufacturers in Kanpur deploy hybrid systems during phased facility upgrades.
Mechanical testing systems lead on scale; digital testing systems lead on momentum.
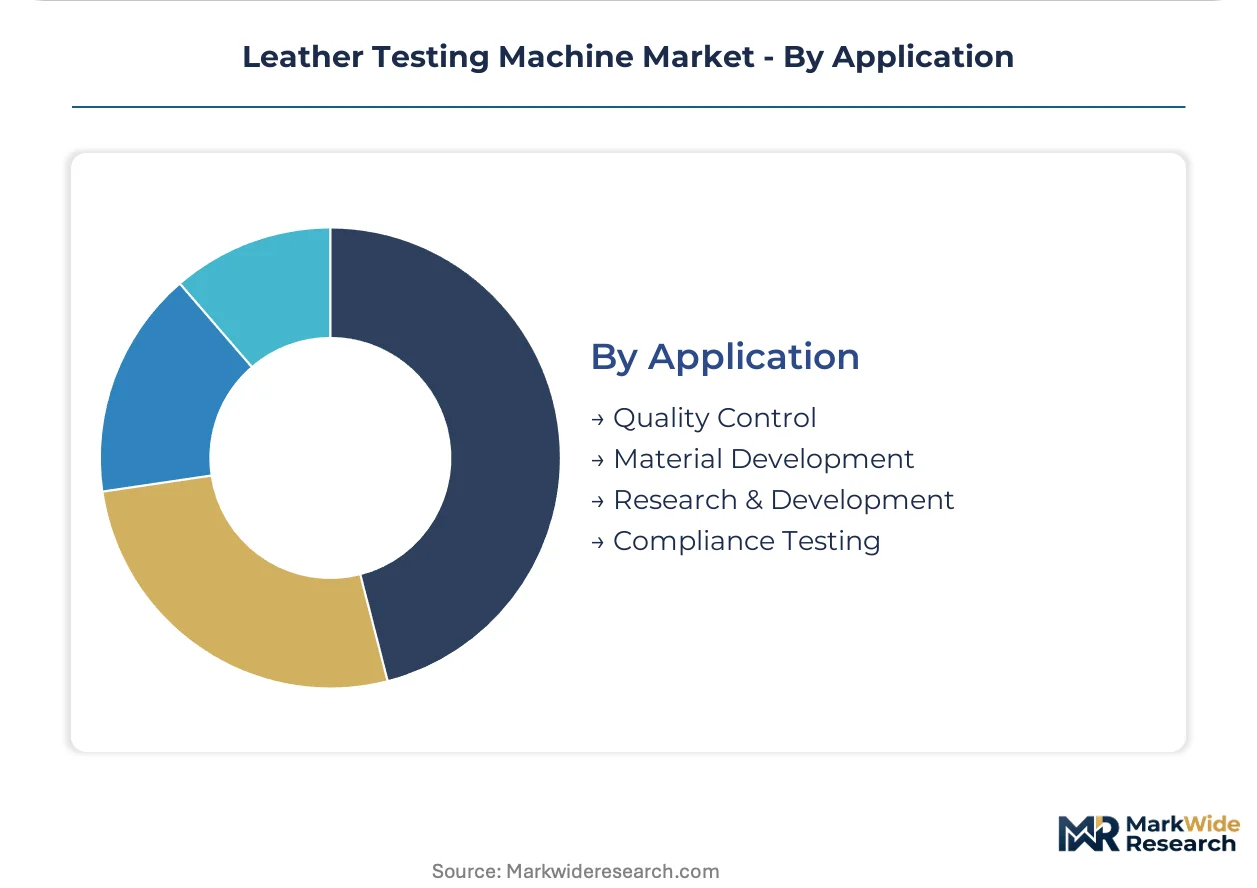
Application:
Procurement patterns split between routine quality gates and specialized validation for novel materials or regulatory submissions.
- Quality Control:Routine batch verification dominates installed base, with tanneries testing every lot for tensile strength and color consistency. China's domestic leather goods exporters are scaling QC infrastructure to match automotive seating production growth.
- Material Development:Bio-based leather alternatives from mycelium and lab-grown collagen require new mechanical property baselines. California-based material startups are commissioning modified flexural and tensile fixtures for pilot production validation.
- Research & Development:Academic and corporate laboratories explore failure mechanisms under combined UV-thermal-mechanical stress. Existing equipment limitations in simulating dashboard environments are driving fixture innovation.
- Compliance Testing:REACH authorization and California Proposition 65 requirements mandate documented chemical and physical validation. European finishers are retrofitting mechanical testers with FTIR modules to avoid separate instrument purchases.
Quality control leads on scale; compliance testing leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized technicians in Stuttgart, Arzignano, and Ho Chi Minh City anchor the industry's geographic footprint, clustering around automotive OEMs and footwear export zones. These workforce concentrations drive procurement patterns for precision load-frame systems and rapid-throughput abrasion units.
Germany
Automotive seating programs in Stuttgart and Munich extend warranty coverage for interior surfaces, mandating dynamic validation for steering-wheel wraps. ECHA's REACH restrictions on chromium VI and azo dyes compel tanneries to install spectroscopic testing modules. The Baden-Württemberg cluster hosts OEM validation labs that specify equipment for supplier certification.
Italy
Luxury automotive leather suppliers in Arzignano deploy static testers for incoming hide certification where batch consistency dominates. Italy's finishers face REACH authorization requirements for dimethyl fumarate, retrofitting mechanical testers with FTIR capabilities. Tuscany's glove leather specialists demand specialized flexural fixtures for soft material validation.
United States
California Proposition 65 warning label requirements for chromium exposure push distributors toward pre-certified leather sourcing. The EPA and California Air Resources Board regulate volatile organic compound emissions from finishing operations. Domestic automotive interior programs in Michigan and Ohio are expanding abrasion resistance protocols for seat bolsters.
China
Domestic leather goods exporters and automotive seating production in Guangdong province scale quality assurance infrastructure simultaneously. SAMR certification requirements for imported equipment shape procurement decisions among manufacturers. The Yangtze River Delta concentration of tanneries is upgrading from mechanical to digital testing systems for buyer portal compliance.
Vietnam
Footwear supplier factories near Ho Chi Minh City process thousands of hides daily, demanding four-hour test turnaround from cut to finished goods. Nike and Adidas compliance portals now mandate automated data logging infrastructure. The region lacks accredited laboratories, creating service bureau opportunities for mobile testing units.
Leather Testing Machine Market Competitive Environment
Capital-heavy producers compete with asset-light designers across a bifurcated equipment market. Precision load-frame manufacturers serving automotive OEMs operate at extended production cycles and six-figure price points, while rapid-throughput abrasion unit fabricators target footwear clusters with compressed delivery timelines. The vendor base separates into three strategic archetypes: heritage engineering houses with load-cell expertise, spectroscopic technology specialists, and cost-optimized mechanical equipment fabricators. Competitive moves center on retrofit partnerships for legacy system integration and software licensing for predictive material modeling platforms.
Among heritage engineering houses, Instron and Shimadzu occupy positions representing distinct technology vectors—load-frame heritage versus spectroscopic integration. Asian Test Equipments exemplifies the cost-optimized archetype serving small-batch tanneries across South and Southeast Asia. These three anchors illustrate how geographic origin and corporate structure map to strategic positioning: Massachusetts-based Instron Corporation, Kyoto-rooted Shimadzu Co., Ltd., and the regionally-named Asian Test Equipments each represent tiered approaches to capital intensity and accreditation depth.
| Leading Market Players |
|---|
| Ektron Tek Co., Ltd. |
| Agilent Technologies |
| Asian Test Equipments |
| Shimadzu |
| Instron |
| TESTEX Textile Testing Instruments |
| AMETEK Inc. |
| MTS Systems |
| Sataton Instruments Sciences Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Family-owned precision engineering houses in Germany and Japan anchor supply for high-force load-frame systems, concentrating pricing power among heritage manufacturers while cost-optimized fabricators in India and China compete on delivered equipment for small-batch tanneries. This ownership fragmentation creates divergent pricing discipline: European and Japanese specialists maintain premium positioning through accreditation bundling, whereas Asian mechanical equipment producers absorb margin compression to capture volume in South and Southeast Asian footwear clusters.
Pricing Analysis
The bundled-vs-unbundled service split defines pricing architecture across the leather testing machine market. Three-tier pricing structure across premium, standard, and economy levels separates Instron-grade automotive validation systems from mid-tier microprocessor units and basic mechanical testers. Price differentiation hinges on ISO 17025 pre-certification depth and after-sales calibration service bundling. Pricing pressure stems from Indonesian and Bangladeshi tanneries demanding shorter payback periods on capital equipment. Small-batch operators in Pakistan exhibit highest price sensitivity; German automotive seating programs show lowest sensitivity due to warranty compliance mandates.
Supply Chain Analysis
Precision load-cell supply rests on Japanese and German specialty sensor producers, with rare-earth-dependent optical modules drawing from Chinese processing facilities. Raw material dependencies span high-grade steel alloys for load frames, rare earth elements for optical sensors, and specialty polymers for environmental simulation chambers. Single-source vulnerability concentrates in Chinese rare earth refining for spectroscopic components. Distribution runs through authorized dealer networks for premium equipment and direct factory relationships for cost-optimized units serving high-volume footwear clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: European REACH compliance costs and California Proposition 65 liability exposure push testing demand toward Vietnamese and Indonesian service bureaus with lower labor overhead and faster turnaround economics.
For Market Incumbents: Acquire mobile testing service capabilities to capture Indonesian and Vietnamese footwear clusters lacking accredited laboratories. Defend against Asian Test Equipments' cost-optimized incursions by embedding predictive calibration software that reduces downtime for automotive OEM validation programs. Certification investment in pre-loaded ASTM and IULTCS test methods preserves pricing power against unbundled competitors. For New Entrants and Emerging Players: Cloud-connected LIMS integration offers a technology-first wedge into mid-tier tanneries upgrading from mechanical to digital systems. Target Bangladesh's Savar tannery zone and Pakistan's Karachi leather corridor for unpenetrated mechanical replacement cycles. Go-to-market through leasing structures addresses capital intensity barriers for small-batch operators unable to finance six-figure multi-parameter platforms. For Investors and Strategic Acquirers: Valuations sit cheapest among Indian and Chinese mechanical equipment fabricators with export capability but weak brand recognition in European automotive supply chains. Long-term viability hinges on spectroscopic-mechanical convergence as single-platform systems displace separate instrument purchases. Watch for REACH authorization expansion beyond chromium VI and dimethyl fumarate as inflection trigger accelerating retrofit demand.| Strategic Initiative | Industry Significance |
|---|---|
| FTIR Module Retrofit Partnership | Italian Arzignano finishers avoid separate capital expenditure while meeting REACH biocide validation requirements. |
| Mobile Testing Service Expansion | Vietnamese footwear suppliers gain four-hour turnaround without building accredited laboratories. |
| Digital Twin Software Licensing | German OEM validation labs enable remote calibration reducing downtime for Stuttgart seating programs. |
| Leasing Structure Introduction | Bangladeshi tanneries access multi-parameter platforms previously blocked by capital constraints. |
| Robotic Sample Handling Integration | Indonesian Nike and Adidas suppliers process thousands of hides daily with compressed test cycles. |
Study Parameters
Coverage spans Germany, Italy, the United States, China, Vietnam, and Indonesia, with primary inputs from each region combining equipment manufacturer interviews, tannery operations directors, automotive OEM validation engineers, and aftermarket service heads. Secondary validation draws from SAMR certification databases, EPA emission filings, ECHA restricted substance lists, and customs equipment import records. Bottom-up equipment shipment tracking triangulates against top-down tannery capital expenditure surveys across the analysis window.
Granularity-level framing models product type, end user, technology tier, and application at the country-cluster level, with separate treatment for automotive seating versus footwear export zones. CAGRs derive from equipment replacement cycle analysis and regulatory mandate timing across geographies. Forecast inputs incorporate REACH authorization expansion schedules and California Air Resources Board enforcement patterns for volatile organic compound emissions.
The model holds under steady regulatory enforcement intensity and intact rare earth supply chains; deviation in Chinese export restrictions or REACH substance list acceleration would shift equipment procurement timing. Forecasts reflect these assumptions without claiming predictive certainty. A small set of named triggers—ECHA biocide authorization expansion, California Proposition 65 chromium litigation volume, and Indonesian footwear export growth—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Sample Preparation Market
Testing Equipment
Continuous Flow Analyzer Market
Testing Equipment
Global Chromatography Columns Market
Testing Equipment
Laboratory Balances and Scales Market
Testing Equipment
Global Host Cell Contaminant Testing Market
Testing Equipment
Liquid Analytical Instrument Market
Testing Equipment
In Vitro Toxicity Testing Market
Testing Equipment
North America Dissolved Gas Analyzer Market
Testing Equipment
Clean-Up Gel Permeation Chromatography Market
Testing Equipment
Ultrasonic Testing Market
Testing Equipment
Laboratory Centrifuge and Accessories Market
Testing Equipment
Global Liquid Chromatography Instruments Market
Testing Equipment
Global Liquid Chromatography Systems Market
Testing Equipment
Chloride Reagents Kits Market
Testing Equipment
Glass Testing Instruments Market
Testing Equipment
Rubber Testing Equipment Market