
 Polyimide Films Market | 2026-2036
Polyimide Films Market Size, Share, and Industry Trends Forecast 2026-2036
Polyimide Films Market Intelligence
Aftermarket service revenue for polyimide film converters is tilting toward technical consulting and application engineering. DuPont leverages its fluoropolymer heritage to anchor high-temperature laminate specifications for aerospace tier-1 suppliers. KANEKA CORPORATION sustains dominance in flexible printed circuit substrates through captive polyimide resin synthesis in Japan. PI Advanced Materials Co., Ltd. competes aggressively in OLED display cover films, extending its position through proprietary colorless polyimide formulations.
Polyimide films are aromatic heterocyclic polymer sheets synthesized from dianhydrides and diamines, typically processed via two-step polyamic acid casting followed by thermal imidization at 300°C to achieve glass transition temperatures exceeding 360°C; they function primarily as electrical insulation and dimensional stability layers in environments where conventional polymers degrade. The flexible product category leads volume consumption due to its indispensability in roll-to-roll electronics manufacturing, while the enhanced segment captures disproportionate margin pools from semiconductor tape-automated bonding applications. Aerospace application demand remains structurally constrained by qualification cycles, whereas electronics application growth concentrates in flexible hybrid electronics where polyimide substrates replace rigid PCB formats.
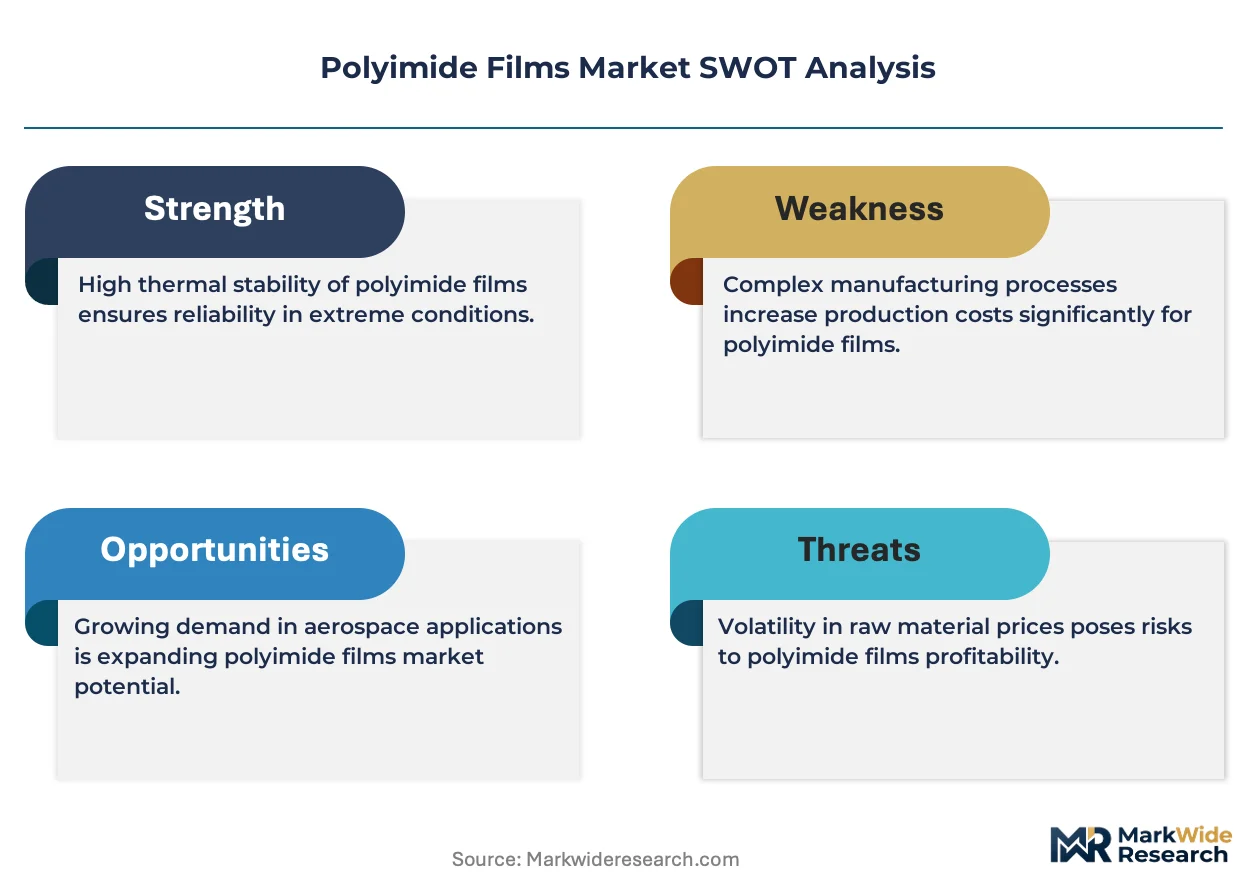
FDA device biocompatibility requirements and EPA perfluorinated substance scrutiny are elevating testing burdens for medical-grade film entrants, while REACH SVHC disclosure obligations in Europe force supply chain transparency down to monomer sourcing. The EU F-Gas Regulation indirectly pressures fluorinated polyimide variants used in semiconductor etch equipment, redirecting R&D toward non-fluorinated alternatives. Stakeholders must monitor evolving semiconductor export controls and polymer recycling mandates to anticipate which product grades will face supply constraints or premium pricing.
Market Dynamics
East Asian electronics manufacturers are compressing substrate qualification timelines while simultaneously tightening thermal performance specifications, forcing polyimide film suppliers to accelerate R&D cycles without sacrificing reliability validation.
Growth Catalysts
- Flexible Hybrid Electronics:Roll-to-roll manufacturing lines in South Korea and Japan are replacing rigid PCB formats with polyimide substrates for wearable sensors and automotive interior electronics.
- REACH SVHC Disclosure:European supply chain transparency mandates down to monomer sourcing are favoring film converters with vertically integrated resin synthesis capabilities over merchant purchasers.
- Semiconductor Tape-Automated Bonding:China's packaging corridor is scaling procurement of enhanced-grade films for high-density chip interconnects, creating sustained volume pull.
Market Restraints
- Pyromellitic Dianhydride Supply Concentration:Three Japanese chemical producers control over 70% of refined PMDA feedstock, exposing film manufacturers to input cost volatility and allocation risk.
- F-Gas Regulatory Pressure:The EU F-Gas Regulation is restricting fluorinated polyimide variants used in semiconductor etch equipment, forcing premature R&D redirection toward non-fluorinated alternatives.
- Glass-Substitute Competition:Ultra-thin borosilicate and chemically strengthened glass sheets are capturing display cover applications where optical clarity requirements exceed polyimide transmission limits.
Strategic Opportunities
- Medical-Grade Biocompatibility:FDA device clearance pathways for implantable flexible electronics are opening addressable markets in neurostimulation and cardiac monitoring substrates.
- India Electronics Manufacturing:PLI scheme incentives for semiconductor packaging and display assembly are creating import-substitution opportunities for domestic film conversion capacity.
- Photovoltaic Backsheet Convergence:Polyimide-fluoropolymer laminates are displacing conventional PET films in concentrated solar power installations requiring 150°C+ operating temperatures.
Industry Challenges
- Imidization Process Control:Achieving consistent glass transition temperatures above 360°C requires thermal profiling expertise that resides with aging specialist engineers in Japan and Germany.
- Aerospace Qualification Cycles:FAA and EASA material certification for structural aircraft insulation extends 4-7 years, locking working capital in inventory before revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyimide Films Market |
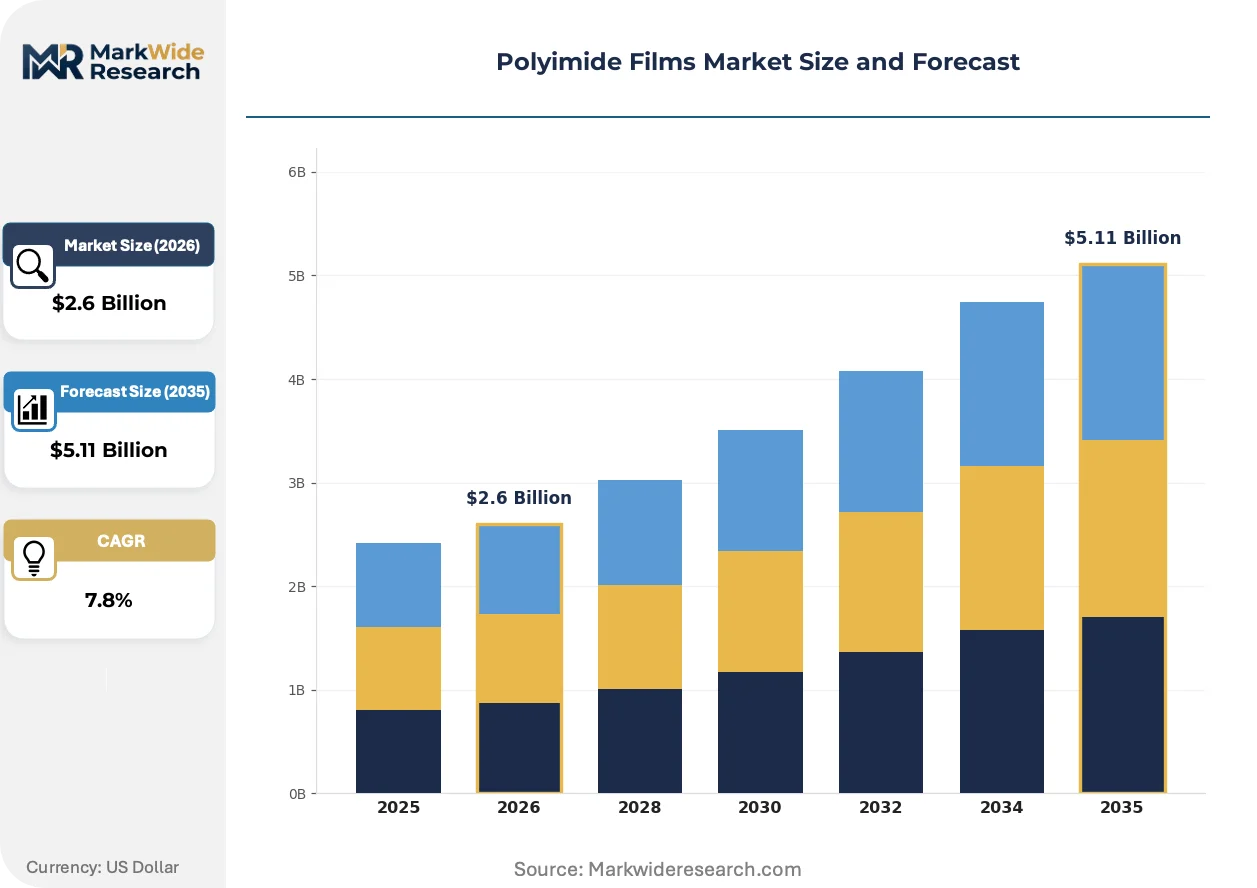
| Market Size in 2026 | $2.6 Billion |
| Market Size in 2035 | $5.11 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible, Rigid, Enhanced, Composite Application: Aerospace, Electronics, Automotive, Medical Form: Sheet, Roll, Tape, Film Technology: Thermal, Chemical, Mechanical, Electrical |
| Companies Covered | DuPont, KANEKA CORPORATION, PI Advanced Materials Co., Ltd., Toray Industries, Inc., Kolon Industries, Inc., Taimide Tech. Inc., Ube Industries, Ltd., SKC Kolon PI Inc., I.S.T Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyimide Films Market Strategic Shifts & Innovations
Material science breakthroughs and regulatory chemistry restrictions are jointly redirecting polyimide film development toward non-fluorinated high-performance variants and colorless optical grades.
Colorless polyimide formulations are migrating from yellow-tinted conventional aromatic structures to alicyclic and semi-alicyclic polymer backbones. OLED display cover film specifications in South Korea now demand 90%+ optical transmittance at 400-700nm wavelengths. PI Advanced Materials and competing Japanese suppliers are compressing development cycles from 36 months to 18 months to match panel maker roadmaps.
REACH authorization requirements for perfluorinated substances are forcing reformulation of semiconductor process equipment components. ECHA's 2023 restriction proposal on PFAS covers fluorinated polyimides used in etch chamber gaskets and wafer handling films. Equipment OEMs in Germany and the Netherlands are accelerating qualification of hydrocarbon-based alternatives ahead of anticipated 2026-2027 enforcement windows.
Application engineering services are unbundling from commodity film sales as converter margins compress. Japanese trading houses and Korean chemical distributors are building in-house technical teams to specify laminate constructions for automotive tier-1 suppliers. China-based flexible circuit manufacturers now expect 72-hour prototyping turnaround and on-site failure analysis as standard procurement terms.
Polyimide Films Market Segmentation
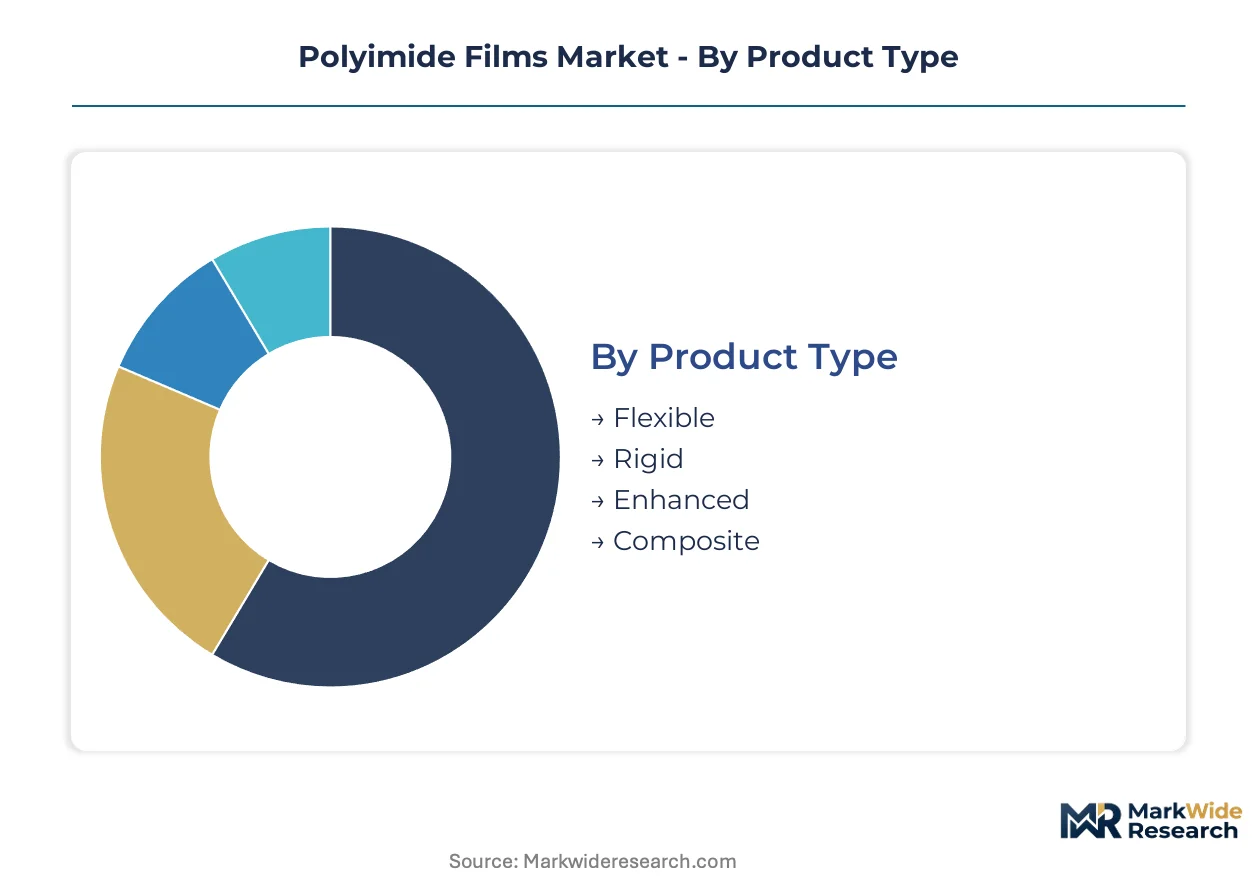
Polyimide film procurement cycles vary dramatically by end-use qualification requirements. Electronics manufacturers compress substrate validation to 18-month windows, while aerospace material certification extends across multiple years. Understanding these temporal dynamics helps suppliers align inventory and R&D resource allocation.
Product Type:
Flexible grades turn inventory fastest through roll-to-roll electronics manufacturing, while enhanced variants face extended qualification cycles in semiconductor packaging.
- Flexible:Cast polyamic acid films thermally imidized to 25-125 micron thicknesses serve as the substrate backbone for flexible printed circuit manufacturing. South Korean display panel clusters and Chinese flexible circuit converters consume the highest volumes, driven by wearable electronics and foldable smartphone cover window laminates.
- Enhanced:Ultra-high purity films with controlled coefficient of thermal expansion below 20 ppm/°C enable tape-automated bonding in advanced semiconductor packages. China's packaging corridor—particularly Jiangsu and Zhejiang provinces—scales procurement most aggressively as domestic chip assembly capacity expands.
- Rigid:Glass-reinforced laminates for structural insulation in aircraft and heavy electrical equipment carry 4-7 year aerospace qualification timelines.
- Composite:Polyimide-fluoropolymer multi-layer constructions for photovoltaic backsheet applications require extended weathering validation.
Flexible dominates installed base. Enhanced is where expansion concentrates.
Application:
Electronics applications command the steepest expansion trajectory, while medical-grade qualification creates the highest margin tier despite constrained volumes.
- Electronics:Flexible hybrid electronics manufacturing in Japan and South Korea replaces rigid PCB formats with polyimide substrates for automotive interior sensors and wearable health monitors. REACH SVHC disclosure mandates favor converters with captive resin synthesis capabilities.
- Aerospace:FAA and EASA structural insulation certification for commercial aircraft extends 4-7 years, locking working capital in qualification inventory before revenue recognition.
- Automotive:Battery module insulation and motor winding applications in Germany and Japan face tightening flame-retardant standards from KBA and METI.
- Medical:Implantable neurostimulation and cardiac monitoring substrates require FDA device biocompatibility clearance, creating premium pricing tiers.
Electronics commands volume leadership. Medical represents the highest-margin addressable frontier.
Form:
Roll formats optimize throughput in high-volume electronics converting, while sheet and tape forms serve fragmented specialty applications.
- Roll:Continuous web formats up to 1500mm width enable roll-to-roll manufacturing lines in South Korea and Japan, serving flexible circuit and display cover film production with minimal material waste.
- Sheet:Precision-die-cut sheets for prototype aerospace insulation and medical device laminates carry higher per-unit conversion costs.
- Tape:Pressure-sensitive adhesive constructions for semiconductor wafer dicing and temporary bonding in Japanese packaging facilities.
- Film:Unconverted base film for downstream laminate manufacturing in China and India.
Roll forms anchor production economics. Tape formats gain share in advanced packaging.
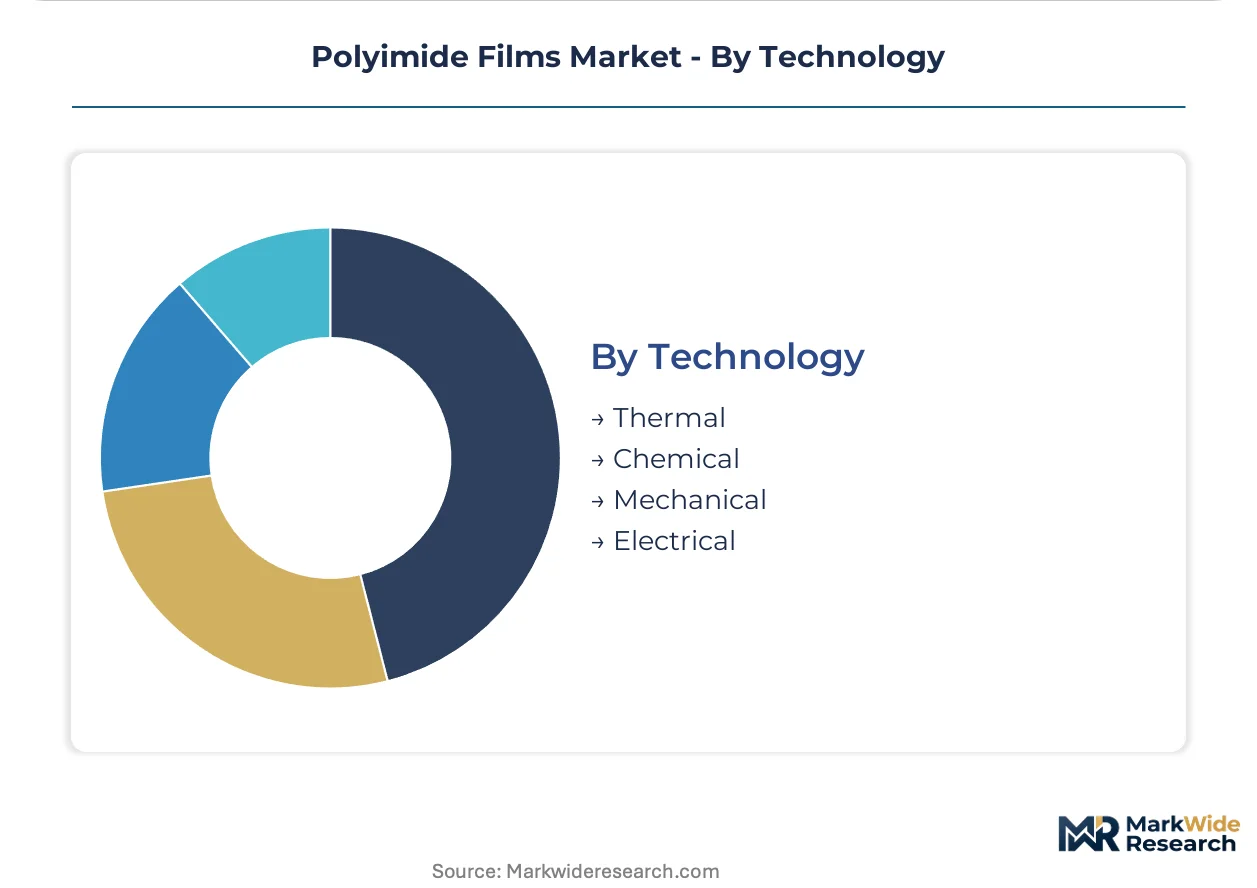
Technology:
Thermal imidization remains the cost-optimized baseline, while chemical and electrical variants address specialized performance requirements.
- Thermal:Two-step polyamic acid casting followed by staged heating to 300°C achieves glass transition temperatures exceeding 360°C, forming the process backbone for standard flexible electronics substrates.
- Chemical:Room-temperature imidization using dehydrating agents enables coating of temperature-sensitive substrates for medical device applications requiring lower thermal exposure.
- Mechanical:Oriented film stretching for biaxial strength enhancement in aerospace structural applications.
- Electrical:Corona and plasma surface treatments for adhesion promotion in multi-layer laminate constructions.
Thermal processes dominate capacity. Chemical imidization is climbing fastest in medical-grade segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Three Japanese chemical producers control over 70% of refined PMDA feedstock, concentrating upstream supply in East Asia while downstream film conversion clusters expand in China and South Korea. This geographic asymmetry shapes regional procurement strategies and inventory risk management across converter networks.
China
Jiangsu and Zhejiang provinces scale procurement of enhanced-grade films for domestic chip assembly capacity expansion. The country's dual carbon goals from MEE tighten energy intensity standards for polyimide resin synthesis operations. Shanghai and Suzhou packaging corridors concentrate demand for tape-automated bonding substrates as semiconductor self-sufficiency programs accelerate.
Japan
Captive polyimide resin synthesis capabilities in Osaka and Tokyo prefectures sustain dominance in flexible printed circuit substrates. METI maintains stringent chemical substance reporting under industrial safety frameworks. Nagoya aerospace clusters drive rigid-grade qualification cycles for structural aircraft insulation with 4-7 year certification timelines.
South Korea
OLED display cover film specifications from Seoul panel makers demand 90%+ optical transmittance, compressing supplier development cycles. MFDS oversees medical device substrate biocompatibility clearance pathways. Busan-Ulsan manufacturing belts integrate roll-to-roll electronics lines for automotive interior sensor applications.
Germany
KBA flame-retardant standards tighten material certification requirements for battery module insulation in automotive supply chains. The EU F-Gas Regulation restricts fluorinated polyimide variants used in semiconductor process equipment. Bavaria-based equipment OEMs accelerate qualification of hydrocarbon-based alternatives ahead of anticipated enforcement windows.
United States
FAA material certification for commercial aircraft structural insulation extends qualification cycles, locking working capital in inventory. FDA device clearance pathways for implantable flexible electronics open addressable markets in neurostimulation substrates. Texas and Arizona semiconductor packaging corridors scale procurement of high-purity film grades.
Polyimide Films Market Key Industry Players
Vertically integrated resin synthesizers and specialized film converters split the market into capability-differentiated tiers. Japanese chemical conglomerates with captive dianhydride supply occupy positions upstream, while Korean and Taiwanese converters dominate midstream roll-to-roll processing. Two competitive moves define current positioning: backward integration into monomer production to secure PMDA allocation, and geographic expansion toward China's packaging corridor to capture import-substitution volume.
Among Japanese resin heritage players, KANEKA CORPORATION exemplifies the vertically integrated archetype through captive polyimide synthesis capabilities, while PI Advanced Materials Co., Ltd. occupies a position within the optical-grade specialization tier targeting display panel specifications. DuPont anchors the diversified materials conglomerate segment, leveraging fluoropolymer heritage to specify high-temperature laminate constructions.
| Leading Market Players |
|---|
| DuPont |
| KANEKA CORPORATION |
| PI Advanced Materials Co., Ltd. |
| Toray Industries, Inc. |
| Kolon Industries, Inc. |
| Taimide Tech. Inc. |
| Ube Industries, Ltd. |
| SKC Kolon PI Inc. |
| I.S.T Corporation |
| Others |
Cost & Logistics Intelligence
Overcapacity signals in Chinese flexible circuit converting are compressing spot pricing for standard-grade substrates while tightening allocation premiums for enhanced semiconductor-grade films. Utilization differentials between commodity flexible grades and qualification-heavy enhanced variants are forcing suppliers to cross-subsidize R&D investments through selective pricing power in tape-automated bonding segments.
Pricing Analysis
Aftermarket service revenue from technical consulting and application engineering now drives lifetime value for film converters facing commodity margin erosion. Pricing stratifies across premium, standard, and economy tiers based on thermal performance certification and captive resin synthesis capabilities. Cost compression in flexible grades is intensifying because Chinese converters are scaling in-house slitting and adhesive coating operations. Display panel manufacturers in South Korea exhibit lowest price sensitivity due to optical transmittance specifications, while Indian electronics assemblers remain most sensitive to landed cost differentials.
Supply Chain Analysis
Export control restrictions on semiconductor manufacturing equipment are redirecting polyimide film flows toward non-restricted packaging corridors in Southeast Asia. Supply concentrates in Japan, South Korea, and China, with three Japanese chemical producers anchoring refined PMDA feedstock availability. Raw material dependencies center on pyromellitic dianhydride, diamine monomers, and fluoropolymer resins for composite laminates. Single-source vulnerability from Japanese PMDA concentration exposes converters to allocation risk during capacity tightness. Distribution runs through Japanese trading houses and Korean chemical distributors with embedded technical service capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from cyclical inventory destocking in display panel supply chains, with OLED cover film procurement resuming as panel maker utilization normalizes.
For Market Incumbents: Insulate margin pools in semiconductor-grade films by accelerating qualification of non-fluorinated formulations ahead of EU F-Gas enforcement windows. Secure captive PMDA supply through equity partnerships with Japanese chemical producers facing feedstock allocation constraints. Backward integration into monomer production represents the critical lever for defending position against merchant resin purchasers.
For New Entrants and Emerging Players: Establish a beachhead in India's semiconductor packaging corridor by licensing thermal imidization process expertise from aging Japanese specialist engineers. Medical-grade biocompatibility certification offers the most penetrable frontier given FDA clearance scarcity and premium pricing tiers. A technical service-led go-to-market approach aligns with Chinese flexible circuit manufacturers demanding 72-hour prototyping turnaround.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across colorless polyimide optical grades due to compressed 18-month development cycles and specialized alicyclic monomer requirements. Target acquisition profiles should emphasize converters with demonstrated aerospace qualification track records and captive resin synthesis capabilities. The signal to watch is REACH authorization timelines for PFAS restrictions redirecting equipment OEM procurement toward hydrocarbon-based alternatives.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Monomer Production | Secures PMDA allocation from Japanese chemical producers facing feedstock concentration risk. |
| Non-Fluorinated Formulation Development | Anticipates EU F-Gas Regulation restrictions on fluorinated polyimide semiconductor equipment components. |
| Medical-Grade Biocompatibility Certification | Opens FDA-cleared addressable markets in implantable neurostimulation and cardiac monitoring substrates. |
| India Manufacturing Footprint Expansion | Captures PLI scheme incentives for semiconductor packaging and display assembly import substitution. |
| Application Engineering Service Unbundling | Converts technical consulting capabilities into recurring revenue streams as film margins compress. |
Research Approach
Initial hypotheses were tested against primary input from polyimide resin synthesis plant managers, flexible circuit converter procurement leads, display panel maker materials engineers, and semiconductor packaging equipment OEMs and refined through secondary validation against customs trade data, SEC 10-K filings from listed chemical conglomerates, Japan Chemical Industry Association production statistics, and REACH SVHC disclosure databases. Bottom-up volume estimates from end-use application consumption were triangulated against top-down capacity assessments from major film manufacturing facilities.
Demand-supply balance modeling across the analysis window incorporated grade tier differentiation between flexible, enhanced, rigid, and composite variants, end-use industry segmentation spanning electronics, aerospace, automotive, and medical applications, and regional production hub clustering in East Asia. CAGRs were derived from regression analysis of historical procurement patterns and forward projection of qualification timeline compression in display and semiconductor segments. Forecast inputs included OLED panel maker roadmaps for optical transmittance specifications and anticipated enforcement windows for EU F-Gas and REACH PFAS restrictions.
Sensitivities concentrate around semiconductor export control expansions, polymer recycling mandate implementations, and aerospace qualification cycle extensions beyond historical 4-7 year baselines. Forecasts reflect documented assumptions regarding thermal imidization process yield improvements and monomer cost trajectories. Cross-checking against SEMI equipment bill-of-materials disclosures and panel maker substrate procurement forecasts is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Flexible Colored Polyurethane (PU) Foams Market
Specialty Materials
Global Synthetic Zeolite Market
Specialty Materials
Cadmium Sulfide Market
Specialty Materials
Dysprosium Oxide Sputtering Target Market
Specialty Materials
Global Cellulose Acetate Market
Specialty Materials
Asia-Pacific Reflective Tape Market
Specialty Materials
Charge Generation Materials (CGM) Market
Specialty Materials
Solar Backsheet Films Market
Specialty Materials
APAC Fluoroelastomer Market
Specialty Materials
Eptfe in Spotlight-Poly-Vents Market
Specialty Materials
United States Microspheres Market
Specialty Materials
Gutta-Percha Market
Specialty Materials
Europe Polyether Ether Ketone (Peek) Market
Specialty Materials
Water Soluble Film Market
Specialty Materials
Silicone Solutions for Leather and Textile Market
Specialty Materials
Lab Grown Diamonds Market