
 Crusher Backing Materials Market | 2026-2036
Crusher Backing Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Crusher Backing Materials Market Outlook
Aggregate producers is rotating toward premium epoxy formulations as mining houses prioritize total cost of ownership over upfront material spend. Henkel Corporation leverages its adhesive chemistry heritage to supply high-compressive-strength backing compounds for gyratory installations. ITW Performance Polymers anchors its position through specialized distribution to quarry operators across North America. ESCO Corporation differentiates via integrated wear solutions that pair backing materials with proprietary liner designs.
Crusher backing materials are two-component epoxy or polyurethane systems formulated to fill voids between crusher liners and the main frame, typically achieving compressive strengths exceeding 120 MPa and operating temperature thresholds near 120°C to absorb impact loads and prevent metal-to-metal contact. Their primary purpose centers on extending liner service life and reducing catastrophic machinery failure in high-abrasion comminution circuits. Epoxy formulations dominate installed base volumes due to proven adhesion to steel substrates and resistance to hydrocarbon contamination in mining environments. Polyurethane segments capture faster growth in recycling applications where impact resilience and faster cure cycles reduce equipment downtime. The metal production end-user channel concentrates margin pools, as smelters and refiners specify certified backing compounds aligned with OEM warranty requirements.
EPA regulations on volatile organic compound emissions constrain solvent-based formulation options in the United States, while REACH compliance in Europe mandates disclosure of epoxy resin hardener chemistries affecting cross-border supply qualification. OSHA permissible exposure limits for respirable crystalline silica amplify demand for pre-measured cartridge systems that reduce worker handling of dry filler components. Stakeholders must monitor evolving MEE environmental standards in China, as tightening enforcement on industrial chemical imports reshapes competitive access for foreign backing material suppliers serving domestic mining expansion.
Market Dynamics
Mining operators are compressing crusher liner replacement cycles to maximize throughput, forcing backing material suppliers to engineer faster-cure formulations that withstand elevated operating temperatures without sacrificing compressive strength. This operational pressure is reshaping R&D priorities across the supply base.
Growth Catalysts
- EPA VOC limits:United States emissions guidelines are accelerating reformulation toward solvent-free epoxy systems that eliminate workplace exposure hazards while maintaining adhesion performance.
- Australian iron ore expansion:Pilbara Basin operators are procuring premium backing compounds to extend gyratory crusher service intervals amid record production targets.
- Polyurethane cure speed:Recycling plant operators are specifying two-hour demold systems that reduce cone crusher downtime during scheduled maintenance windows.
Market Restraints
- Raw material concentration:Bisphenol A epoxy resin supply concentrates among Asian petrochemical producers, exposing formulators to feedstock price volatility and import tariff exposure.
- REACH disclosure burden:European hardener chemistry registration requirements are extending cross-border qualification timelines for non-EU suppliers seeking CE-marked product status.
- Cast metal liner longevity:Improved manganese steel metallurgy is extending primary liner life, compressing the addressable backing material replacement frequency in mature mining installations.
Strategic Opportunities
- Underpenetrated recycling sector:Construction and demolition waste processors in Germany and France represent untapped demand for impact-resistant polyurethane backing in mobile crushing circuits.
- Pre-measured cartridge systems:OSHA silica exposure rules are creating pull for factory-proportioned single-use kits that eliminate on-site mixing and reduce worker contact with dry fillers.
- Digital inventory integration:Mining houses are adopting vendor-managed consignment programs where suppliers maintain buffer stock at remote Australian and Chilean mine sites.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in epoxy-polymer hybrid systems for high-temperature abrasion resistance is concentrated among retiring technical staff at legacy suppliers.
- OEM warranty alignment:Crusher manufacturers require certified backing compound documentation for liner warranty claims, forcing material suppliers to maintain parallel qualification tracks across Metso, FLSmidth, and Sandvik specifications.
- Cold-weather cure reliability:Siberian and Canadian operators report inconsistent epoxy hardening at sub-zero installation temperatures, requiring heated enclosure protocols that extend maintenance windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crusher Backing Materials Market |
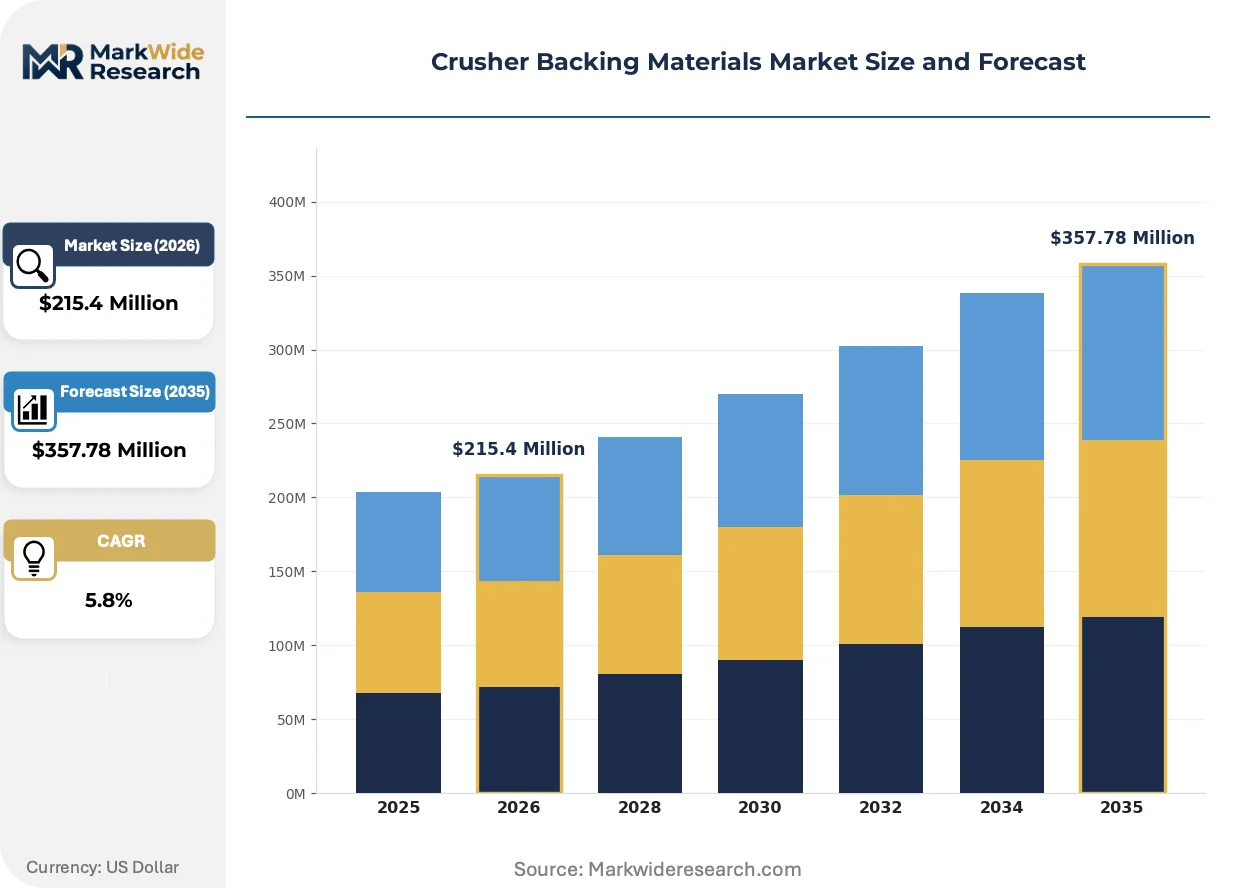
| Market Size in 2026 | $215.4 Million |
| Market Size in 2035 | $357.78 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyurethane, Resin, Compound Application: Mining, Quarrying, Recycling, Construction End User: Metal Production, Cement Industry, Aggregate Production, Waste Management Distribution Channel: Direct Sales, Distributors, Online Sales, Retail |
| Companies Covered | Henkel Corporation, ITW Performance Polymers, FLSmidth & Co. A/S, ESCO Corporation, Copps Industries, Columbia Steel Casting Co., Inc, Nordbak, ENVIROPOX, The Weir Group PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crusher Backing Materials Market Strategic Shifts
Formulation chemistry is pivoting toward environmental compliance without sacrificing mechanical performance, while distribution models adapt to remote mining logistics. Equipment OEMs are tightening material certification requirements that favor technically sophisticated suppliers.
Hybrid epoxy-polyurethane systems are displacing conventional pure epoxy formulations in high-impact recycling applications. Australian quarry operators are piloting these materials for their superior resilience to tramp metal events. The technology is displacing established two-component epoxies in secondary and tertiary crushing circuits where rapid cure and elongation properties outweigh pure compressive strength metrics.
REACH Article 33 disclosure mandates are forcing European suppliers to document Substances of Very High Concern in hardener packages. Formulators are reformulating with aliphatic amine alternatives that avoid SVHC classification but require extended cure schedules. Mining procurement teams in Germany and Sweden are prioritizing pre-registered products to avoid supply interruption during compliance audits.
Buyer consolidation among tier-one mining houses is compressing supplier margins through centralized global contracting. Rio Tinto and BHP are unbundling backing material procurement from liner supply agreements, forcing specialized compound manufacturers to compete directly on technical specifications rather than OEM channel relationships. This disintermediation is most visible in Western Australian iron ore operations where direct site-level purchasing authority has shifted from maintenance supervisors to corporate category managers.
Crusher Backing Materials Market Segmentation
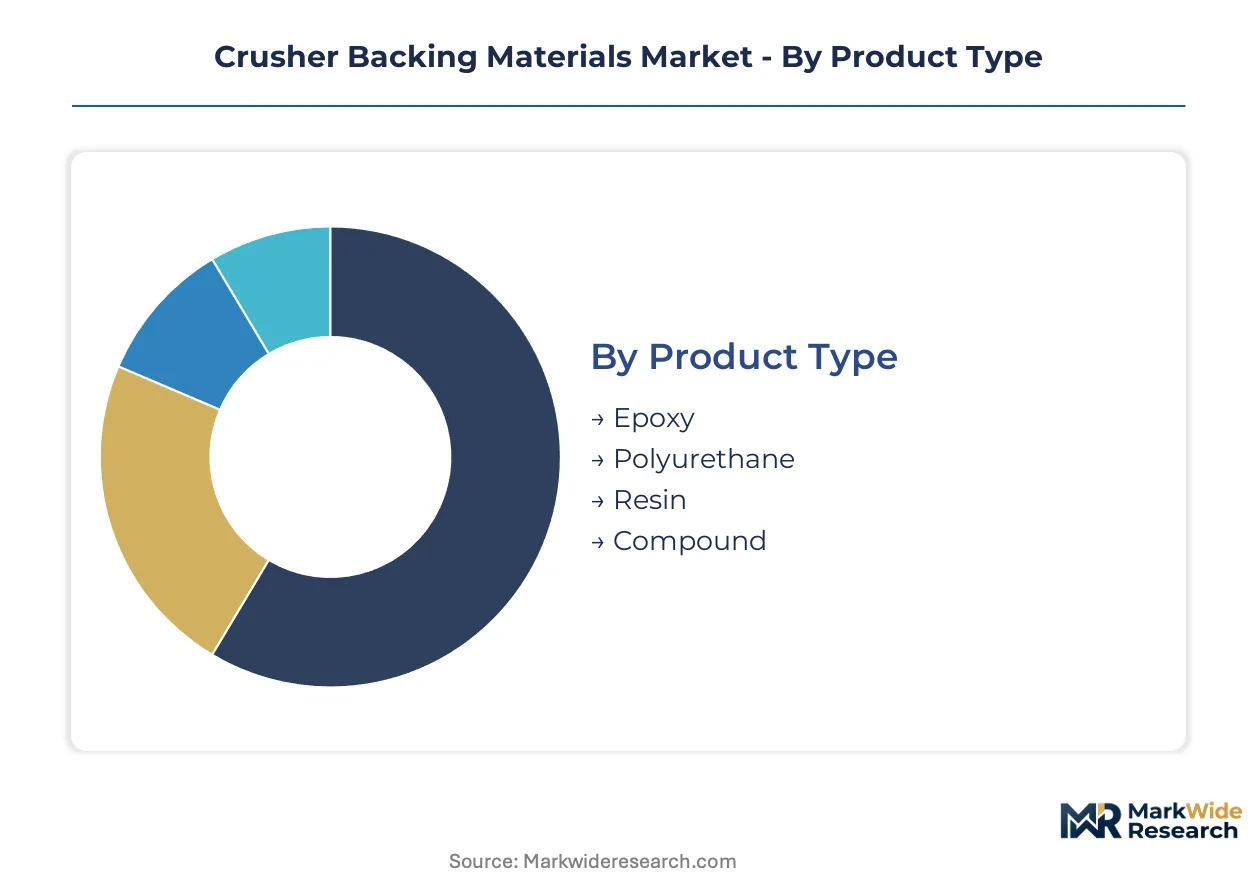
Crusher backing materials flow through distinct procurement channels shaped by end-use scale and technical certification requirements. Mining houses demand direct manufacturer relationships for warranty alignment, while smaller quarry operators rely on regional distributors for technical support and inventory flexibility.
Product Type:
Channel mix varies sharply by chemistry: epoxy formulations dominate direct sales to OEM-certified mining contracts, while polyurethane systems move through specialized industrial distributors serving recycling and mobile crushing fleets.
- Epoxy:Two-component systems formulated from bisphenol-A resins and aliphatic amine hardeners achieve compressive strengths exceeding 120 MPa and thermal stability to 120°C. Australian iron ore operators in the Pilbara Basin specify these compounds for gyratory crusher installations where extended cure cycles are acceptable against liner replacement schedules. Demand concentrates among smelters and refiners requiring OEM warranty documentation.
- Polyurethane:Elastomeric systems cure within two hours and absorb tramp metal impact through superior elongation properties. German and French construction waste processors are specifying these materials for mobile cone crushers where maintenance windows are compressed. The chemistry is gaining share fastest in recycling circuits.
- Resin:Specialty formulations for high-temperature hydrocarbon exposure in refinery slag processing.
- Compound:Pre-measured cartridge systems eliminating on-site mixing for OSHA silica compliance.
By volume, epoxy leads. By growth pace, polyurethane is ahead.
Application:
Cost tier stratification separates premium-specified mining procurement from price-sensitive construction aggregate buying, with recycling applications occupying a mid-tier technical-performance position.
- Mining:Primary gyratory and cone crusher installations in copper, gold, and iron ore comminution circuits demand certified backing compounds with documented compressive strength and thermal cycling performance. BHP and Rio Tinto procurement teams specify these materials through global framework agreements unbundled from liner supply contracts.
- Quarrying:Limestone and granite aggregate producers prioritize total cost of ownership over upfront material spend, driving specification of premium epoxy formulations through regional distributor networks. North American quarry operators anchor volume in this segment.
- Recycling:Construction and demolition waste processors in Western Europe require impact-resistant polyurethane systems for variable feedstock conditions.
- Construction:Infrastructure project contractors procure through retail channels for portable crushing equipment with limited technical specification requirements.
By installed base, mining dominates. By expansion trajectory, recycling is climbing fastest.
End User:
Customer type determines margin structure: metal production facilities negotiate technical certification premiums, while waste management operators prioritize unit cost and availability.
- Metal Production:Smelters and refiners mandate certified backing compounds aligned with crusher OEM warranty requirements, creating concentrated margin pools for technically sophisticated suppliers. These end users specify through direct manufacturer relationships with full documentation packages.
- Cement Industry:Clinker production facilities in India and China specify heat-resistant formulations for limestone primary crushing circuits, procuring through national distributors with technical field service capabilities.
- Aggregate Production:Crushed stone and sand producers across North America and Australia specify standard epoxy grades through regional supply houses.
- Waste Management:Municipal and private landfill operators processing construction debris specify polyurethane systems for mobile equipment through equipment rental channels.
By revenue concentration, metal production leads. By procurement volume growth, aggregate production is expanding most quickly.
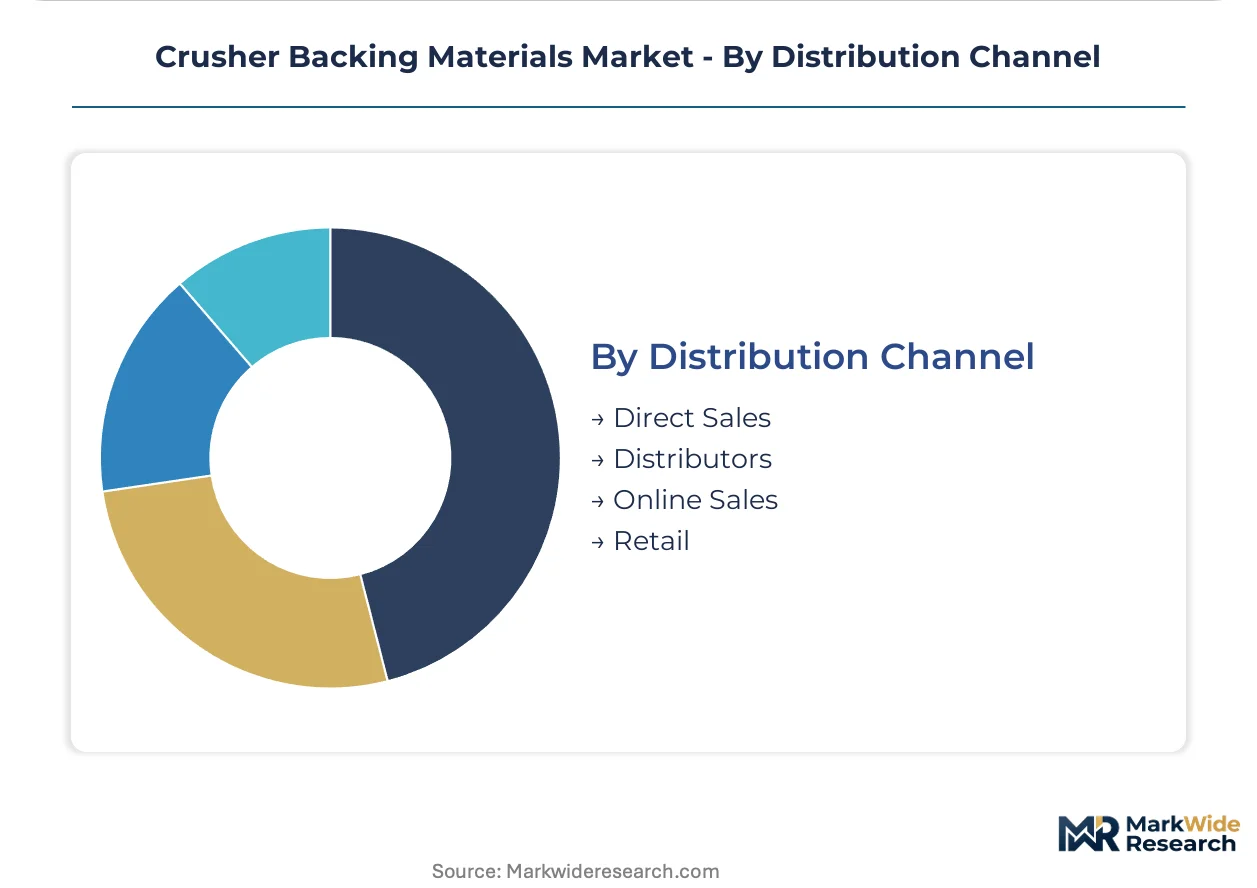
Distribution Channel:
Supply concentration in epoxy resin feedstocks shapes channel economics, with direct sales capturing technical-specification premiums and distributors absorbing inventory risk for standardized grades.
- Direct Sales:Manufacturer-to-mine-site relationships dominate premium epoxy procurement for gyratory crusher installations requiring OEM certification. Henkel Corporation and ITW Performance Polymers anchor this channel through technical field engineering support and consignment inventory programs at remote Australian and Chilean operations.
- Distributors:Regional industrial supply houses serve quarry and aggregate producers with standard formulations, providing localized technical support and just-in-time delivery. ESCO Corporation leverages this channel for integrated wear solutions pairing backing materials with proprietary liner designs.
- Online Sales:Emerging procurement route for standardized cartridge systems and technical documentation access.
- Retail:Limited to small-scale construction contractors with minimal specification requirements.
By transaction value, direct sales leads. By shipment frequency, distributors are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Pilbara rail network and Port Hedland bulk export terminals underwrite Australia's centrality to crusher backing material demand, while Chile's copper concentrate pipeline infrastructure positions it as the second anchor geography for high-specification compound procurement.
Australia
Pilbara Basin iron ore operators specify premium epoxy formulations for gyratory crusher installations amid record production targets. EPA-equivalent state environmental regulations in Western Australia mandate low-VOC workplace exposure protocols. Perth-based procurement teams at BHP and Rio Tinto operations now unbundle backing material contracts from liner supply agreements.
United States
Copper and gold mining in Arizona and Nevada drives replacement cycles for cone crusher wear components. EPA emissions guidelines and OSHA permissible exposure limits for respirable crystalline silica accelerate reformulation toward solvent-free systems. Quarry operators across the Mountain West and Southwest specify pre-measured cartridge kits to reduce on-site mixing hazards.
Germany
Construction and demolition waste processors in North Rhine-Westphalia and Bavaria represent untapped demand for impact-resistant polyurethane backing in mobile crushing circuits. REACH Article 33 disclosure mandates force reformulation with aliphatic amine alternatives avoiding Substances of Very High Concern classification. Industrial clusters around Düsseldorf and Munich pilot hybrid epoxy-polyurethane systems for variable feedstock conditions.
Chile
Copper concentrate pipeline infrastructure from mine sites to Pacific ports underwrites demand for certified backing compounds in primary comminution circuits. Vendor-managed consignment programs at remote Atacama Desert operations reduce inventory risk for specialized compound manufacturers. Antofagasta and Calama maintenance bases specify materials aligned with Metso and FLSmidth OEM warranty documentation.
China
Domestic iron ore mining expansion in Hebei and Liaoning provinces reshapes procurement volumes for standard epoxy grades. MEE environmental standards tightening enforcement on industrial chemical imports reshape competitive access for foreign suppliers. Yangtze River Delta and Shandong Peninsula cement clinker facilities specify heat-resistant formulations for limestone primary crushing circuits.
Crusher Backing Materials Market Competitive Environment
Concentration sits with adhesive chemistry specialists and integrated wear solution providers that maintain parallel qualification tracks across crusher OEM specifications. Three structural tiers define competitive positioning: multinational chemical conglomerates with field engineering capabilities, regional compound formulators serving distributor networks, and equipment OEMs bundling proprietary backing materials with liner systems. Dominant competitive moves include geographic expansion through consignment inventory programs at remote mine sites and portfolio diversification into pre-measured cartridge systems for regulatory compliance.
Among multinational adhesive specialists, Henkel Corporation and ITW Performance Polymers occupy positions emphasizing direct manufacturer-to-mine-site relationships with technical field support. ESCO Corporation exemplifies the integrated wear solution archetype, pairing backing material supply with proprietary liner design capabilities. FLSmidth & Co. A/S represents equipment OEM verticalization into certified compound documentation for warranty-aligned procurement. These three anchors illustrate the competitive tension between chemical formulators pursuing technical specification premiums and machinery manufacturers capturing margin through bundled aftermarket offerings.
| Leading Market Players |
|---|
| Henkel Corporation |
| ITW Performance Polymers |
| FLSmidth & Co. A/S |
| ESCO Corporation |
| Copps Industries |
| Columbia Steel Casting Co., Inc |
| Nordbak |
| ENVIROPOX |
| The Weir Group PLC |
| Others |
Value Chain & Pricing Dynamics
Sixty-day raw material lead times from Asian petrochemical hubs to North American formulators compress margin buffers and amplify pricing power for bisphenol-A resin suppliers serving epoxy backing compound manufacturers. This inventory exposure concentrates procurement leverage among integrated mining houses while forcing smaller quarry operators toward distributor-stocked standard grades.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates OEM-certified compounds for gyratory installations from distributor-grade epoxies and unbranded alternatives. Price differentiation hinges on compressive strength certification and Metso warranty alignment. Cost compression in standard grades is intensifying because BHP and Rio Tinto procurement teams unbundle backing materials from liner contracts. Aggregate producers prove most price-sensitive, while metal production facilities absorb technical certification premiums.
Supply Chain Analysis
Container availability constraints on Asia-North America trade lanes extend inbound logistics costs and force buffer stock accumulation at Australian port hubs. Bisphenol-A epoxy resin supply concentrates in China, South Korea, and Taiwan, with aliphatic amine hardeners sourcing from German and Japanese specialty chemical producers. Single-source vulnerability sits with Asian petrochemical feedstocks exposed to import tariff shifts. Distribution runs through direct manufacturer-to-mine-site relationships for premium grades and regional industrial distributors for standardized formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized formulation chemistry expertise for high-temperature abrasion resistance has concentrated among retiring technical staff at legacy suppliers, creating a capability scarcity that reshapes competitive durability and acquisition targeting.
For Market Incumbents: Compound technical field engineering capabilities with consignment inventory programs at remote Australian and Chilean mine sites to defend against buyer consolidation. Deepen backward integration into aliphatic amine hardener supply to offset Asian resin price volatility. Prioritize pre-measured cartridge system certification for OSHA silica compliance to capture regulatory-driven specification shifts. For New Entrants and Emerging Players: CE marking fast-track through REACH-registered aliphatic amine formulations opens European recycling sector penetration ahead of SVHC disclosure deadlines. Target German and French construction waste processors with two-hour cure polyurethane systems for mobile cone crushers. Pursue equipment rental channel partnerships to bypass entrenched distributor relationships in waste management segments. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because buyer concentration among tier-one mining houses compresses supplier margins and forces scale-driven exits among regional compound formulators. Acquire mid-cap adhesive chemistry specialists with parallel OEM qualification tracks across Metso, FLSmidth, and Sandvik specifications. Watch for BHP or Rio Tinto global framework agreement re-tendering as inflection signal for margin reset timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hardener Supply | Captive amine production insulates margin from Asian petrochemical price swings. |
| Pre-measured Cartridge Certification | OSHA silica compliance creates specification lock-in among US quarry operators. |
| Consignment Inventory Programs | Vendor-managed stock at Pilbara mine sites deepens buyer switching costs. |
| Hybrid Epoxy-Polyurethane Development | Australian recycling pilots validate resilience advantage over pure epoxy systems. |
| REACH-Registered Formulation Portfolio | Pre-registered hardener chemistry secures German and Swedish procurement continuity. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC filings from listed mining equipment OEMs, and EPA enforcement action databases. Interviews with plant engineers at copper concentrate facilities, procurement leads at Australian iron ore operations, distribution channel partners serving North American quarries, and technical R&D directors at adhesive formulators provided operational validation. Bottom-up volume estimates from crusher installation counts triangulate against top-down chemical consumption metrics from petrochemical trade associations.
Segmentation dimensions modeled span product chemistry, application severity tier, end-user industry, and distribution channel structure across the analysis window. CAGRs derive from elasticity-adjusted replacement cycle frequencies and mining capital expenditure trajectories. Industry-specific forecast inputs include gyratory crusher fleet expansion in Western Australia and polyurethane penetration rates in European recycling circuits.
Underlying assumptions cover stable EPA VOC enforcement intensity and REACH disclosure timeline adherence, with deviation risk concentrated in MEE environmental standard tightening that could restrict foreign supplier access to Chinese mining expansion. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Nitrocellulose Market
Specialty Materials
Dysprosium Oxide Sputtering Target Market
Specialty Materials
Alginate Films Market
Specialty Materials
Specialty Silicone Market
Specialty Materials
Dura Substitute Market
Specialty Materials
Global Montan Wax Market
Specialty Materials
Lab Grown Diamonds Market
Specialty Materials
Plastic Dielectric Films Market
Specialty Materials
North America Solar Control Window Films Market
Specialty Materials
Europe Polyether Ether Ketone (Peek) Market
Specialty Materials
Microwave Absorbing Materials Market
Specialty Materials
Metallic Hot Stamping Foils Market
Specialty Materials
Eptfe in Spotlight-Poly-Vents Market
Specialty Materials
Gutta-Percha Market
Specialty Materials
Polyester Medical Films Market
Specialty Materials
Asia-Pacific Colloidal Silica Market