

Acrylic Fine Particle Market Size, Share, and Industry Trends Forecast 2026-2036
Acrylic Fine Particle Market Insights
Aftermarket technical service revenue is rewriting profitability expectations for acrylic fine particle suppliers as commoditized base resin margins compress. BASF SE leverages its global technical service network to anchor premium positioning in architectural coatings formulations. NIPPON SHOKUBAI sustains leadership in high-purity grades for electronics applications through continuous process refinement. Dow Chemical Company competes on manufacturing scale across multiple regional production hubs.
Acrylic fine particles are spherical polymer beads typically ranging from 10 to 500 nanometers in diameter, synthesized through emulsion or suspension polymerization of acrylic acid esters and methacrylic acid derivatives; they function as film-forming binders, rheology modifiers, and opacity enhancers across formulated products. Homopolymers occupy mature volume positions in standard architectural paints where cost efficiency dominates procurement decisions. Co-Polymers represent the fastest-growing product category as hybrid compositions deliver balanced adhesion and weatherability for automotive refinish and protective coatings. Emulsion grades concentrate margin pools in waterborne industrial coatings as environmental compliance tightens solvent-based alternatives.
EPA regulations in the United States restrict hazardous air pollutant emissions from coatings manufacturing, compelling reformulation toward compliant acrylic dispersions. REACH registration requirements and the EU Green Deal carbon border adjustments in Europe shape product standards and market access conditions for imported acrylic particles. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions across multiple jurisdictions, as these intersect with stain-resistant coating applications where modified acrylic particles serve as transition materials.
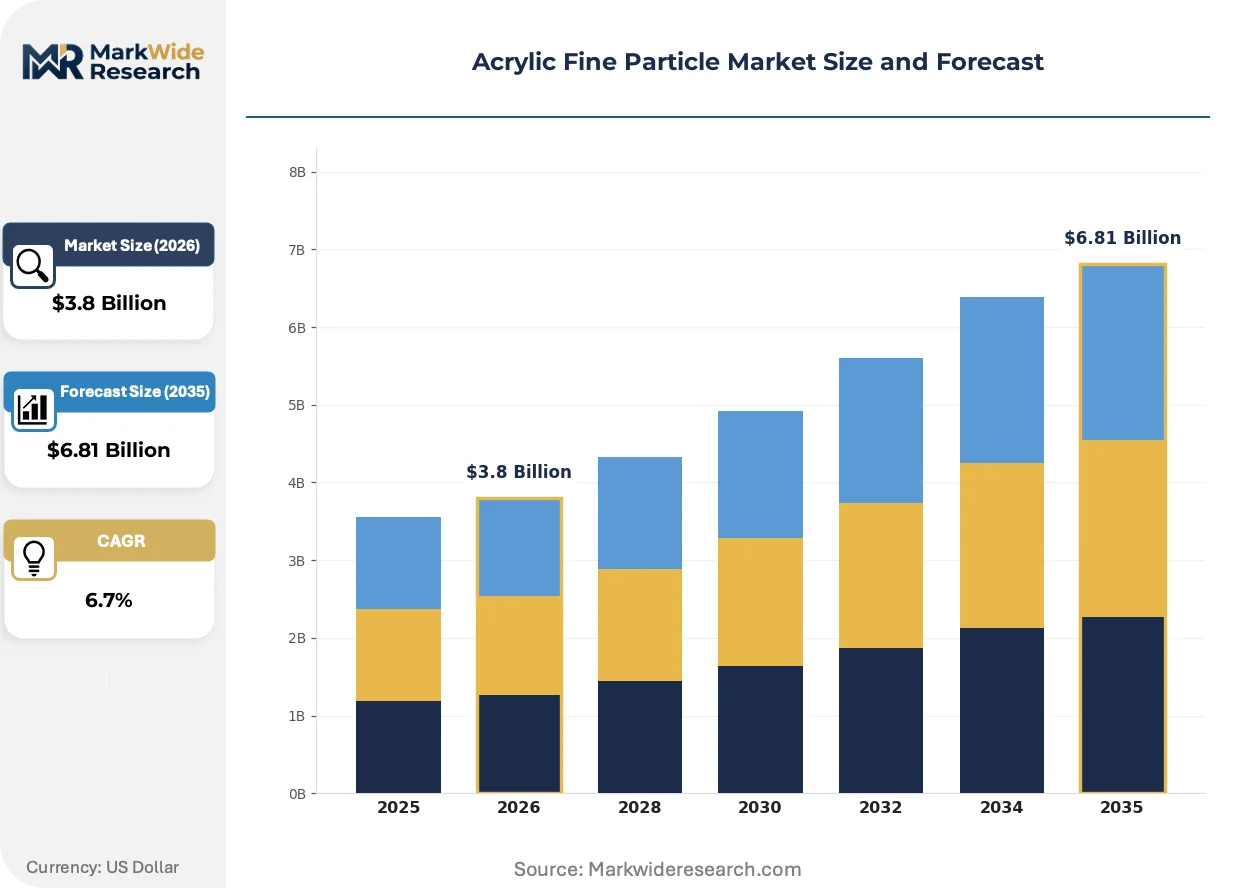
Market Dynamics
Waterborne coating formulations are displacing solvent-based systems across industrial and architectural end-uses, redirecting acrylic fine particle procurement toward emulsion-grade dispersions with tighter particle size distribution and lower volatile organic compound footprints.
Growth Catalysts
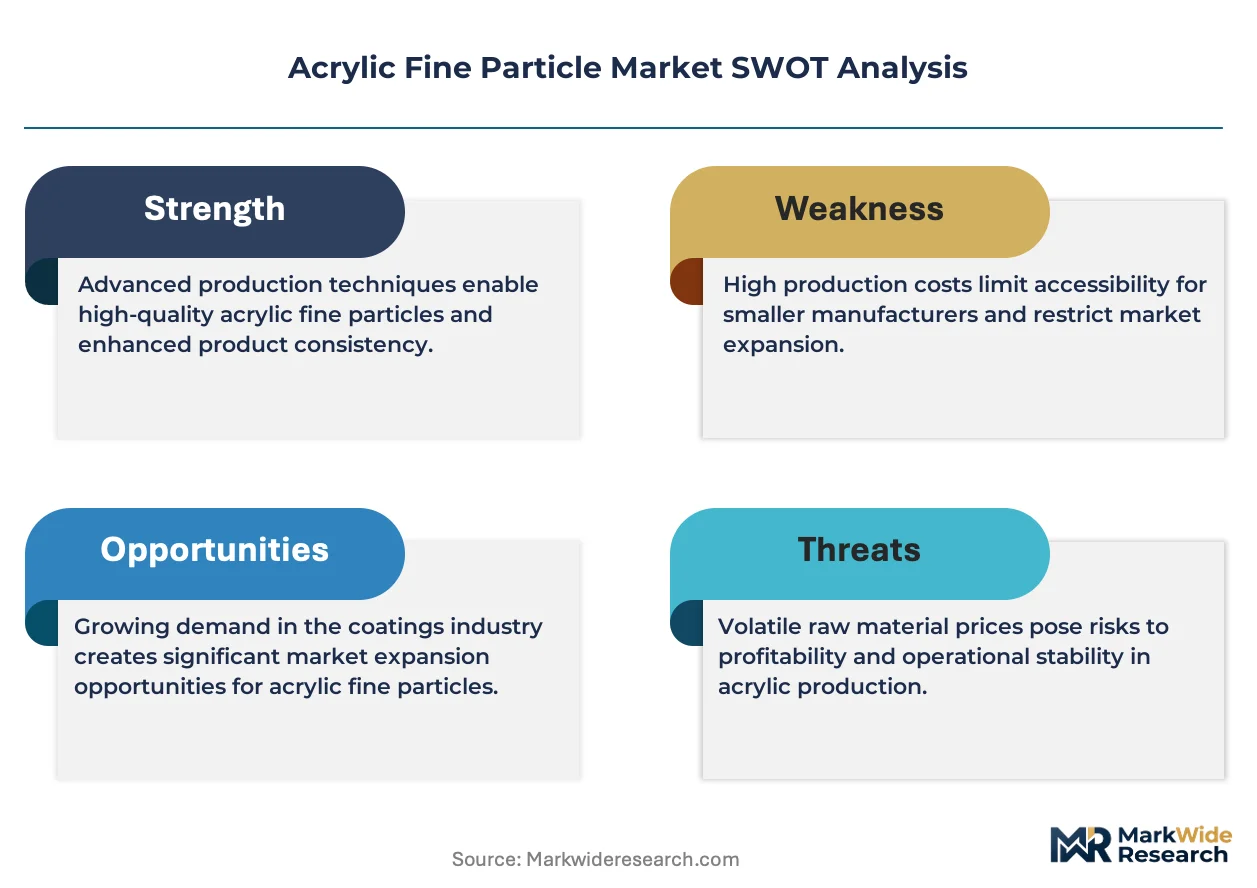
- REACH Phase-In Substances:ECHA registration deadlines for low-molecular-weight acrylic oligomers are accelerating reformulation investments toward compliant fine particle dispersions in European protective coatings.
- Automotive Refinish Waterborne Transition:Collision repair shops in Germany and France are adopting co-polymer acrylic systems to meet solvent emission limits without sacrificing metallic flake orientation.
- Electronics Miniaturization:Dielectric layer fabrication in printed circuit boards is consuming high-purity sub-100 nanometer acrylic particles for controlled dielectric constant and thermal stability.
Market Restraints
- Methyl Methacrylate Feedstock Volatility:Acrylic fine particle margins compress when propylene-derived monomer costs spike, particularly affecting homopolymer grades where substitution options are limited.
- Specialty Additive Supplier Concentration:Rheology modifier and dispersant technologies for nanoscale particle stabilization remain concentrated among a handful of European and Japanese chemical specialists.
- Per-Fluorinated Surface Treatment Phase-Out:PFAS restrictions under state-level U.S. legislation and pending EU harmonization are removing stain-resistant performance benchmarks that modified acrylic particles struggle to replicate.
Strategic Opportunities
- India Industrial Coatings Localization:Domestic paint producers under the PLI scheme for specialty chemicals are qualifying local acrylic dispersion suppliers to reduce import dependency on Southeast Asian resin sources.
- Photovoltaic Backsheet Encapsulation:UV-resistant co-polymer acrylic particles are penetrating solar module manufacturing as fluoropolymer alternatives face supply and sustainability scrutiny.
- Construction Chemicals Distribution:Direct-to-applicator digital platforms in Brazil are bypassing traditional distributor markups for waterproofing membrane formulations using acrylic fine particle binders.
Industry Challenges
- Emulsion Polymerization Process Control:Achieving sub-50 nanometer particle sizes with narrow polydispersity index requires reactor engineering expertise that commands premium compensation and extended training cycles.
- ISO 16000 Indoor Air Quality Certification:Documentation burdens for emissions testing in architectural applications extend product qualification timelines by 8-14 months for new acrylic dispersion introductions.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acrylic Fine Particle Market Trends and Innovations
Acrylic fine particle innovation is concentrating on particle architecture control and surface functionalization to unlock performance in adjacent materials science applications beyond traditional coatings binders.
Core-shell particle morphology is migrating from experimental specialty grades toward mainstream industrial coatings as formulators seek to decouple hardness development from film flexibility. Automotive OEM clearcoat specifications in Japan and Germany are adopting gradient-refractive-index particles to eliminate mottle in metallic basecoat systems. This architecture is compressing the performance gap between single-stage and basecoat-clearcoat systems in refinish applications.
The EU Green Deal carbon border adjustment mechanism is reshaping import economics for acrylic dispersion producers outside the European Economic Area. Chinese and South Korean resin exporters face embedded emissions calculations that disadvantage coal-intensive acrylate monomer production routes. Domestic European producers with bio-based feedstock certifications are capturing specification advantages in public procurement tenders for infrastructure coatings.
Technical service unbundling is fragmenting traditional supplier-customer relationships in North American architectural coatings. Large national paint retailers are building in-house formulation capabilities that reduce reliance on acrylic particle suppliers for color matching and failure analysis. This capability accumulation is most advanced in the U.S. Southwest, where desert climate durability testing has become an internal competency rather than an outsourced validation step.
Acrylic Fine Particle Market Segmentation
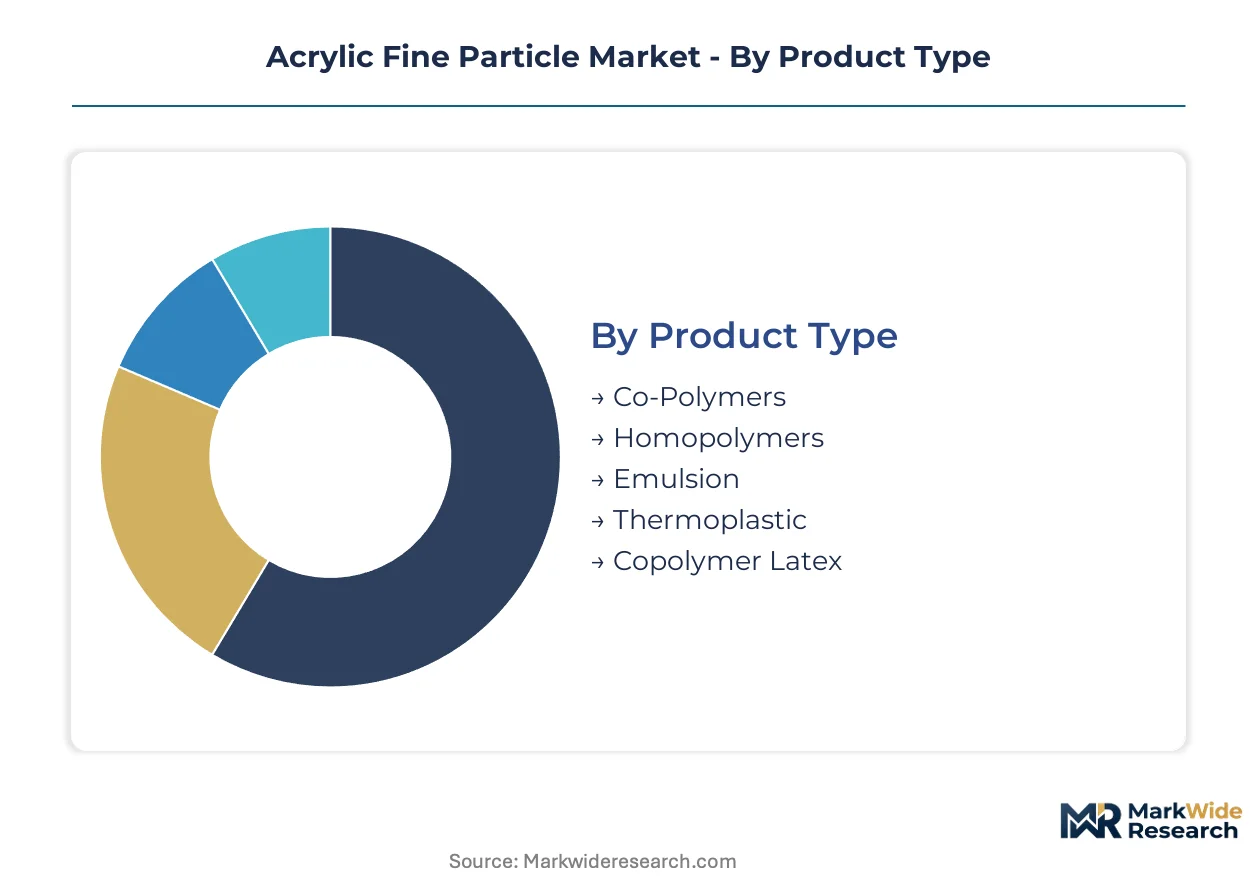
Segmentation in acrylic fine particles reveals how technical specifications align with procurement economics across formulated product industries. Buyers select particle architecture, dispersion format, and packaging logistics based on end-use performance thresholds and supply chain constraints.
Product Type:
Mature commodity grades dominate volume positions while engineered architectures command specification premiums in performance coatings.
- Co-Polymers:Hybrid compositions of acrylic acid esters with methacrylic derivatives or styrene deliver balanced adhesion and weatherability. Demand concentrates in automotive refinish shops across Germany and France where metallic flake orientation must survive solvent emission limits.
- Homopolymers:Single-monomer architectures based on methyl methacrylate or butyl acrylate offer cost efficiency in high-volume applications. Standard architectural paint manufacturers in China procure these grades as domestic capacity expansion localizes sourcing.
- Emulsion:Aqueous dispersions with controlled particle size distribution serve waterborne industrial coatings.
- Thermoplastic:Heat-fusible bead morphologies enable thermoforming and hot-melt compounding.
- Copolymer Latex:Pre-stabilized dispersion formats reduce downstream processing steps for formulators.
Homopolymers handle the majority of throughput; Co-Polymers are the fastest mover on share.
Application:
Coatings and adhesives absorb capacity while emerging segments reshape margin pools through technical service intensity.
- Paints & Coatings:Film-forming binders in architectural and industrial formulations demand sub-100 nanometer particles for gloss control and opacity. Waterborne system conversions in collision repair networks across Japan and Germany redirect procurement toward emulsion-grade dispersions.
- Adhesives & Sealants:Pressure-sensitive and structural bonding applications exploit tack development and cohesive strength from tailored glass transition temperatures. Construction chemical distributors in Brazil are qualifying direct-to-applicator digital platforms for waterproofing membrane binders.
- Printing Inks:Pigment dispersion stability and transfer efficiency drive particle surface chemistry specifications.
- Textiles Treatment:Hand modification and crease resistance in fabric finishing utilize soft-handle acrylic dispersions.
- Paper Finishing:Surface sizing and printability enhancement consume fine particle binders in coated paper grades.
Paints & Coatings absorbs the dominant volume position; Adhesives & Sealants is expanding most quickly as construction activity intensifies.
End User Industry:
Customer concentration varies by technical validation burden and formulation complexity requirements.
- Construction Firms:Waterproofing, tile adhesives, and exterior coatings procurement scales with infrastructure spending cycles. India's PLI scheme for specialty chemicals is qualifying domestic acrylic dispersion suppliers to reduce import dependency.
- Automotive Component Makers:OEM clearcoat and refinish specifications demand gradient-refractive-index particles for mottle elimination. Japanese and German automotive coating standards are compressing performance gaps between single-stage and basecoat-clearcoat systems.
- Electronics Assemblers:Dielectric layer fabrication in printed circuit boards requires high-purity sub-100 nanometer particles.
- Textile Manufacturers:Fabric finishing operations consume soft-handle dispersions for apparel and technical textiles.
- Packaging Companies:Print quality and barrier coatings drive particle size distribution requirements.
Construction Firms represent the largest addressable base; Electronics Assemblers is climbing the fastest on specification value.
Packaging Type:
Logistics economics and contamination risk determine format selection across customer scale tiers.
- Bulk Bags:Flexible intermediate bulk containers minimize unit logistics costs for high-volume architectural coatings producers. Domestic paint manufacturers in China specify bulk formats as captive dispersion capacity reduces drum-handling overhead.
- Drums:Steel and polymer drums preserve dispersion stability for mid-volume industrial coatings formulators. REACH-compliant protective coatings producers in Europe favor drum formats for batch traceability and ECHA registration documentation.
- Totes:Intermediate bulk containers bridge bulk and drum economics for regional coatings operations.
- Carboys:Rigid polymer containers serve laboratory and sampling quantities.
- Bottles:Small-format packaging supports specialty additive and dispersant sampling.
Bulk Bags capture the highest tonnage throughput; Drums is gaining share fastest as mid-tier formulators consolidate supply bases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in China and India squeeze margins on standard homopolymer grades, while Japanese and German electronics assemblers absorb premiums for sub-100 nanometer specifications without volume elasticity.
China
Domestic coatings producers expand captive dispersion capacity to localize specialty chemical sourcing. The country's dual carbon goals under MEE pressure coal-intensive acrylate monomer routes toward emission accounting. Yangtze River Delta clusters around Shanghai absorb tonnage throughput as waterborne architectural paint output scales.
Germany
Automotive refinish shops in Stuttgart and Munich adopt co-polymer systems for metallic flake orientation under solvent emission limits. REACH Phase-In Substances deadlines through ECHA accelerate reformulation investments in protective coatings. The Ruhr industrial corridor concentrates emulsion-grade dispersion demand from mid-tier formulators consolidating supply bases.
United States
EPA restrictions on hazardous air pollutant emissions from coatings manufacturing redirect procurement toward compliant acrylic dispersions. Large national paint retailers in the Southwest build in-house desert climate durability testing capabilities. Texas and California industrial coatings operations specify drum formats for batch traceability under environmental compliance documentation.
Japan
Electronics assemblers consume high-purity sub-100 nanometer particles for dielectric layer fabrication in printed circuit boards. METI standards on automotive OEM clearcoat specifications drive gradient-refractive-index particle adoption. Kanto and Kansai manufacturing belts anchor specification value as miniaturization intensifies.
India
Construction firms under the PLI scheme for specialty chemicals qualify domestic acrylic dispersion suppliers to reduce import dependency. BIS certification requirements shape product standards for waterproofing membrane formulations. Maharashtra and Gujarat industrial corridors scale direct-to-applicator digital platforms for construction chemicals distribution.
Acrylic Fine Particle Market Competitive Landscape
Capability concentration sits with European and Japanese specialists commanding reactor engineering expertise for sub-50 nanometer control; scale advantage sits with diversified chemical conglomerates operating multiple regional production hubs. The vendor base separates into three tiers: integrated petrochemical majors, pure-play acrylic dispersion specialists, and regional toll manufacturers serving captive formulations. Consolidation pressure runs through backward integration into acrylate monomer supply and technical service unbundling by large paint retailers.
Among diversified chemical majors, BASF SE and Dow Chemical Company occupy positions spanning global technical service networks and multi-hub manufacturing footprints. NIPPON SHOKUBAI exemplifies the specialist tier with concentration in high-purity grades. These three represent distinct strategic postures: BASF anchors premium positioning through formulation support intensity, Dow competes on manufacturing scale across regional dispersion assets, and NIPPON SHOKUBAI sustains leadership in electronics-grade specifications through continuous process refinement.
| Leading Market Players |
|---|
| BASF SE |
| NIPPON SHOKUBAI |
| Soken Chemical |
| Dow Chemical Company |
| Arkema Group |
| Mitsubishi Chemical Corporation |
| Sumitomo Chemical |
| LG Chem |
| Evonik Industries |
| Others |
Pricing and Supply Chain Analysis
Yangtze River Delta dispersion clusters around Shanghai anchor global acrylic fine particle capacity, translating concentrated methyl methacrylate feedstock access into pricing leverage over European and Indian buyers dependent on imported resin streams. This geographic concentration lets Chinese producers undercut landed costs for standard homopolymer grades while Japanese and German specialists preserve premiums through sub-100 nanometer specification control.
Pricing Analysis
Long-term offtake contracts dominate procurement between multinational coatings producers and integrated petrochemical majors, insulating volume buyers from methyl methacrylate spot volatility while locking in specification-grade premiums. Three-tier pricing structure across premium, standard, and economy levels separates electronics-grade sub-50 nanometer dispersions from architectural paint homopolymers and bulk industrial emulsions. Price differentiation hinges on particle size distribution certification and REACH registration documentation completeness. Cost compression in standard architectural grades is intensifying because Chinese domestic capacity expansion eliminates import markups. Construction chemical distributors in emerging markets exhibit highest price sensitivity; Japanese electronics assemblers absorb premiums without volume elasticity.
Supply Chain Analysis
Propylene-derived methyl methacrylate monomer supply concentrates in China, South Korea, and Germany, with acrylic fine particle production drawing from these feedstock hubs through integrated or toll-manufacturing arrangements. Key inputs span acrylate esters, suspension polymerization initiators, and nanoscale stabilization additives from European and Japanese specialty chemical suppliers. Single-source vulnerability runs through rheology modifier technologies concentrated among a handful of Japanese and European specialists. Distribution runs through direct technical service relationships for premium grades and construction chemical distributors for volume architectural applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Acrylic fine particle demand sits in early-cycle expansion as waterborne coating conversions accelerate across automotive refinish and protective coatings end-uses, with regulatory emission limits in Germany and Japan forcing formulation investments that favor compliant dispersion technologies.
For Market Incumbents: Insulate specification-grade positioning through captive production of sub-50 nanometer emulsion grades and backward integration into acrylate monomer supply. BASF SE's technical service network model offers a template for anchoring premium relationships against commodity resin compression. Capacity expansion in India's PLI-qualified zones addresses import substitution tailwinds while preempting regional toll-manufacturer emergence. For New Entrants and Emerging Players: Mid-tier industrial coatings formulators in Brazil and India represent the most penetrable entry point, as direct-to-applicator digital platforms fragment traditional distributor control and reduce incumbent relationship stickiness. Photovoltaic backsheet encapsulation offers a second white-space target, with UV-resistant co-polymer grades penetrating solar module manufacturing as fluoropolymer alternatives face supply and sustainability scrutiny. Lead with formulation partnership programs rather than commodity resin pricing. For Investors and Strategic Acquirers: Long-term, this sits as a specialty-chemical consolidation play because reactor engineering expertise for nanoscale particle control concentrates among European and Japanese specialists with limited exit liquidity. Target acquisition archetypes include pure-play dispersion specialists with electronics-grade certification and regional toll manufacturers serving captive formulations under long-term supply agreements. Monitor ECHA REACH Phase-In Substances registration deadlines as an inflection signal for reformulation-driven demand spikes.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylate Monomer Supply | Captive methyl methacrylate production insulates margins from propylene derivative volatility affecting homopolymer grades. |
| Sub-50 Nanometer Reactor Engineering Investment | Precision particle size control commands specification premiums in Japanese electronics and German automotive clearcoat applications. |
| REACH Phase-In Substances Registration | ECHA compliance documentation extends qualification timelines but locks out unregistered competitors from European protective coatings procurement. |
| Direct-to-Applicator Digital Platform Launch | Brazilian construction chemical distributors bypass traditional markups for waterproofing membrane formulations using acrylic binders. |
| Photovoltaic Backsheet Encapsulation Qualification | UV-resistant co-polymer grades penetrate solar module manufacturing as fluoropolymer alternatives face PFAS restriction scrutiny. |
Research Methodology
Operator-level perspectives from coatings formulators, automotive refinish shop managers, electronics assemblers, and construction chemical distributors anchored the qualitative base, supplemented by technical interviews with emulsion polymerization engineers and procurement leads at multinational paint producers. Secondary validation drew from ECHA registration databases, EPA hazardous air pollutant emission filings, customs trade data on acrylate monomer flows, and SEC 10-K disclosures from diversified chemical majors. Bottom-up capacity modeling across regional production hubs was triangulated against top-down demand estimates from end-use industry consumption patterns.
Scenario-bracketing around methyl methacrylate feedstock cost volatility, REACH implementation timelines, and waterborne coating conversion rates shaped the analytical framework across the projection horizon. Segmentation dimensions modeled included product architecture, application end-use, packaging logistics format, and regional production hub concentration. CAGRs were derived from slope-intercept analysis of historical consumption trajectories adjusted for regulatory inflection points and technology substitution elasticities. Industry-specific forecast inputs incorporated automotive OEM clearcoat specification evolution and electronics miniaturization intensity metrics.
Stress conditions across propylene derivative cost spikes, ECHA registration deadline acceleration, and PFAS restriction harmonization were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on waterborne conversion penetration rates and regional capacity commissioning schedules. Cross-checking against customs data on acrylate monomer trade flows and published capacity announcements from Yangtze River Delta producers is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.