
 Global Flexible Substrates Market | 2026-2036
Global Flexible Substrates Market Size, Share, and Industry Trends Forecast 2026-2036
Global Flexible Substrates Market Intelligence
Specialty polymer production in South Korea and Japan is decoupling from traditional semiconductor cycles, aligning more closely with consumer electronics product launches. DuPont de Nemours, Inc. leverages its extensive material science portfolio to serve high-performance applications. Kolon Industries, Inc. specializes in polyimide film manufacturing, a critical component for flexible displays. Teijin Limited competes through its development of advanced polyester films like polyethylene naphthalate.
Flexible substrates are thin, pliable materials like polymers or ultra-thin glass serving as the foundation for electronic circuits. They require high thermal stability and optical clarity to withstand device fabrication processes like vapor deposition. Polyimide films hold a dominant position due to superior properties needed for advanced consumer electronics applications. The printed electronics technology segment shows rapid expansion, enabling low-cost production of flexible sensors and RFID tags.
Material composition and end-of-life handling are governed by regulations such as the EU's RoHS directive and the EPA's substance control rules in the United States. In China, GB standards dictate material purity and performance criteria for electronics components, influencing market access for substrate manufacturers. Future investment decisions will hinge on balancing the performance demands of next-generation devices with increasing pressure for material recyclability and circularity.
Market Dynamics
The market's structure is defined by the intense performance demands of consumer electronics, particularly for foldable displays and wearables. This creates a direct link between material science innovation in polymers and the product launch cycles of major device manufacturers.
Growth Catalysts
- Wearable Electronics:Demand for lightweight, conformable displays and sensors in smartwatches and fitness trackers necessitates flexible substrates. The development of biocompatible materials further expands use in medical wearables.
- Printed Electronics:This low-cost manufacturing process enables high-volume production of flexible circuits, RFID tags, and sensors. It lowers the barrier to entry for new applications in smart packaging and logistics.
- South Korean Display Ecosystem:Concentrated manufacturing of OLED and flexible displays in South Korea creates a powerful demand center. This ecosystem accelerates substrate qualification and adoption for new device generations.
Market Restraints
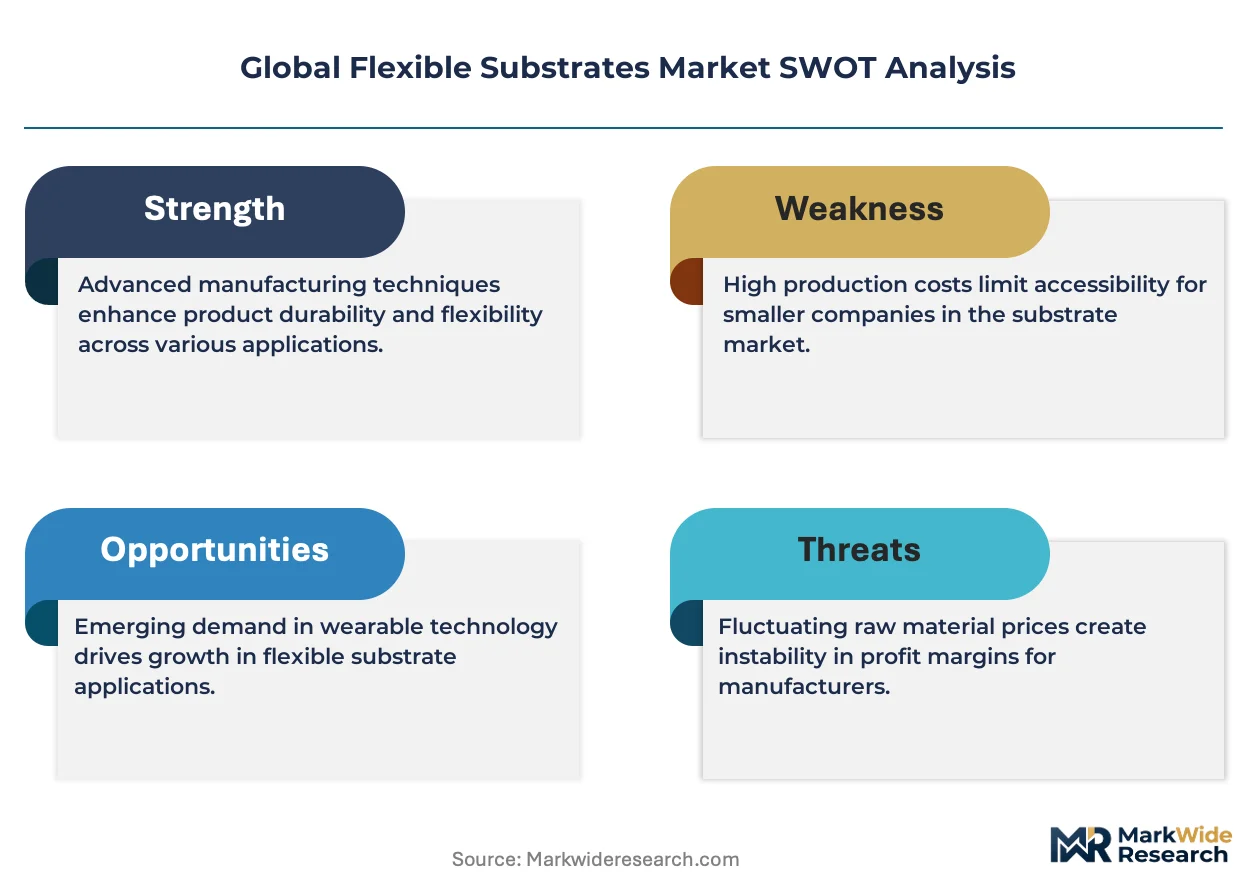
- High-Purity Polymer Costs:The production of high-performance polyimide and PEN films requires expensive, highly purified monomers. Price volatility in these chemical precursors directly impacts substrate manufacturing costs and margins.
- Moisture and Oxygen Permeability:Many polymer-based substrates exhibit higher permeability to moisture and oxygen than glass, which can degrade sensitive electronic components like OLEDs, requiring complex barrier films.
- Polyimide Film Supply Chain:A limited number of suppliers, primarily in Japan and South Korea, control the global supply of high-grade polyimide film, creating potential bottlenecks and pricing power concentration.
Strategic Opportunities
- Flexible Photovoltaics:The integration of flexible substrates into lightweight, rollable solar cells for portable power and building-integrated photovoltaics represents a significant new market vertical for substrate manufacturers.
- Circular Economy Mandates:EU directives promoting recyclability create an opportunity for substrates developed with bio-based polymers or designed for easier disassembly and recovery from end-of-life electronics.
- 5G Antenna Integration:The need for transparent, low-loss materials for 5G antennas integrated into device displays opens a new high-performance application space for advanced polymer and composite substrates.
Industry Challenges
- Roll-to-Roll Processing Complexity:Achieving high yields and maintaining uniform material properties during high-speed, roll-to-roll deposition and patterning processes remains a significant operational challenge, impacting cost-competitiveness.
- Lack of Testing Standards:A deficiency in standardized testing methodologies for mechanical flexibility and long-term reliability makes it difficult for device manufacturers to compare and qualify substrates from different vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Flexible Substrates Market |
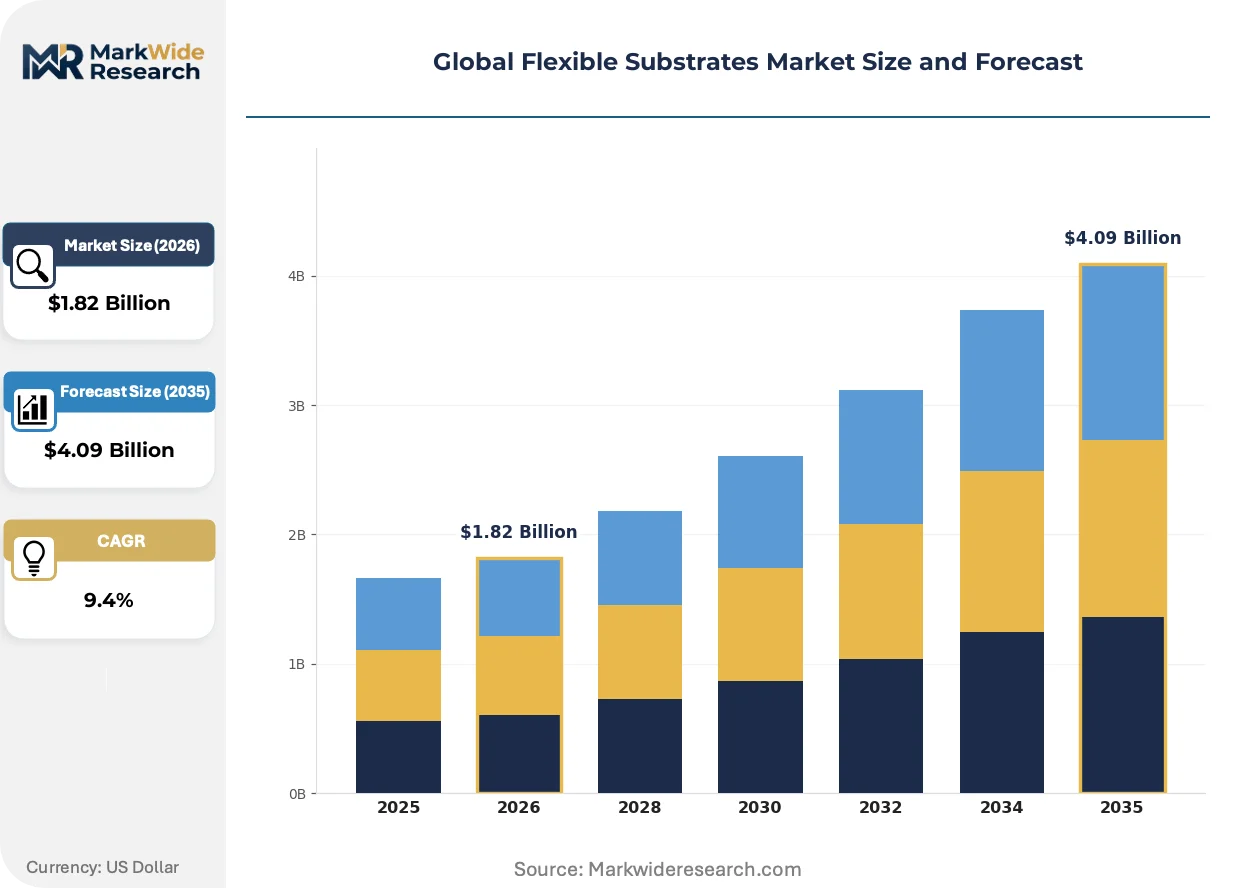
| Market Size in 2026 | $1.82 Billion |
| Market Size in 2035 | $4.09 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyimide, Polyester, Polyethylene Naphthalate, Polydimethylsiloxane, Polycarbonate Technology: Printed Electronics, Thin-Film Transistor, Organic Light Emitting Diode, Radio Frequency Identification, Solar Cells Application: Wearable Electronics, Consumer Electronics, Aerospace Systems, Smart Packaging, Security Devices End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers, Electronics Manufacturers |
| Companies Covered | DuPont de Nemours, Inc., Teijin Limited, Kolon Industries, Inc., Nippon Electric Glass Co., Ltd., 3M Company, Schott AG, DuPont Teijin Films, Nitto Denko Corporation, Ube Industries, Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Flexible Substrates Market Strategic Shifts & Innovations
Material science advancements are pushing substrates toward higher thermal and optical performance to meet next-generation device needs. Simultaneously, regulatory pressures and new production techniques are fundamentally altering material selection criteria and manufacturing economics for substrate producers.
Ultra-thin glass provides superior hermeticity and surface smoothness compared to polymer films. Foldable smartphone manufacturers are rapidly adopting this material as a protective cover layer for delicate OLED screens. This technology is converging with flexible polymer backplanes, creating hybrid substrate stacks that combine the optical quality of glass with the flexibility of polyimide.
The European Union's RoHS directive restricts hazardous substances in electronic equipment, directly impacting substrate composition. This regulation forces manufacturers to eliminate materials like certain flame retardants and plasticizers from their polymer formulations. The consumer electronics segment is most affected, driving investment in compliant materials that meet both regulatory and technical specifications.
Device manufacturers are increasingly seeking co-development partnerships with substrate suppliers early in the design cycle. This collaborative approach replaces the traditional transactional model where substrates were procured as commoditized components. The shift is most pronounced in the foldable phone and augmented reality glasses sectors, especially among design teams in South Korea and the United States.
Global Flexible Substrates Market Segmentation
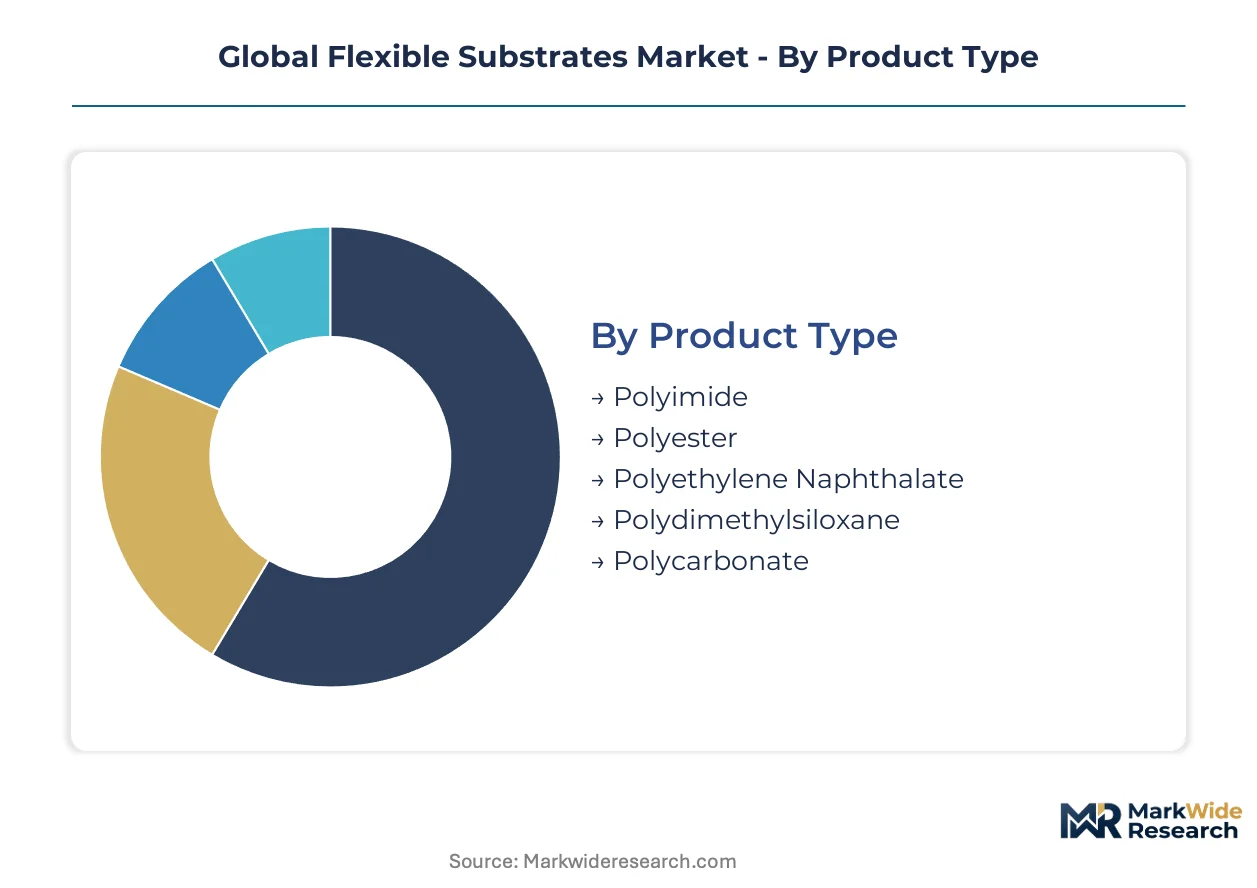
The Global Flexible Substrates Market is segmented to provide a detailed understanding of material composition, technological applications, and end-user demand. This segmentation highlights the diverse performance requirements and strategic investment areas across the industry value chain.
Product Type:
Flexible substrates are differentiated by their core material composition, influencing their thermal, optical, and mechanical properties for various electronic applications.
- Polyimide:These films offer superior thermal stability, mechanical strength, and chemical resistance, making them critical for advanced consumer electronics like flexible displays and high-performance circuit boards. Demand concentrates in South Korea and Japan, driven by their dominant display manufacturing ecosystems.
- Polyethylene Naphthalate:PEN films provide high transparency, good barrier properties, and improved thermal resistance compared to standard polyesters, enabling their use in advanced display backplanes and flexible solar cells. Device manufacturers in the United States increasingly adopt PEN for specific optical applications.
- Polyester:Standard polyester films offer a cost-effective solution for flexible electronics requiring moderate performance, finding use in flexible sensors and RFID tags.
- Polydimethylsiloxane:PDMS is a silicone-based polymer known for its excellent flexibility, biocompatibility, and optical clarity, suitable for medical wearables and soft robotics.
- Polycarbonate:Polycarbonate substrates provide good impact resistance and optical clarity, often used in flexible lighting and transparent electrodes.
Mature deployment sits with Polyimide. Newer deployment is concentrated in Polyethylene Naphthalate.
Technology:
The market's technology segmentation reflects distinct manufacturing processes and functional capabilities for flexible electronics across various industry verticals.
- Printed Electronics:This low-cost manufacturing process enables high-volume production of flexible circuits, sensors, and RFID tags, lowering the barrier to entry for new applications in smart packaging and logistics. China's electronics sector shows significant investment in printed electronics for high-volume consumer goods.
- Organic Light Emitting Diode:OLED technology utilizes flexible substrates for its light-emitting layers, enabling thin, lightweight, and conformable displays in smartphones, televisions, and wearable devices. South Korea's display manufacturers are primary drivers of OLED substrate demand.
- Thin-Film Transistor:TFT technology forms the backbone of many flexible displays, providing the switching elements for individual pixels on polymer or ultra-thin glass substrates.
- Radio Frequency Identification:RFID applications leverage flexible substrates for low-profile, durable tags used in inventory management, access control, and smart logistics.
- Solar Cells:Flexible substrates are integrated into lightweight, rollable photovoltaic devices for portable power, building-integrated photovoltaics, and niche energy harvesting applications.
Printed Electronics technology is expanding most quickly in new applications. Thin-Film Transistor technology maintains a stable, foundational presence.
Application:
End-use applications drive specific material and performance requirements across the flexible substrates market, dictating demand for specialized properties.
- Wearable Electronics:This segment demands lightweight, conformable, and often biocompatible substrates for smartwatches, fitness trackers, and medical patches, necessitating high flexibility and durability. Demand is particularly strong from consumer electronics brands in the United States and South Korea.
- Consumer Electronics:Foldable smartphones, rollable displays, and advanced tablets utilize flexible substrates for their screens, internal circuitry, and protective layers, requiring high optical clarity and mechanical resilience. Asian electronics manufacturers are the largest consumers in this segment.
- Aerospace Systems:Flexible substrates find use in lightweight avionics, flexible sensors for structural health monitoring, and advanced antenna systems in aircraft and spacecraft.
- Smart Packaging:This application integrates flexible sensors, RFID tags, and indicators into packaging for enhanced tracking, anti-counterfeiting, and freshness monitoring.
- Security Devices:Flexible substrates are incorporated into secure identification cards, biometric sensors, and tamper-evident labels for various authentication purposes.
Wearable Electronics applications are experiencing the steepest expansion trajectory. Aerospace Systems represent a niche but high-value segment.
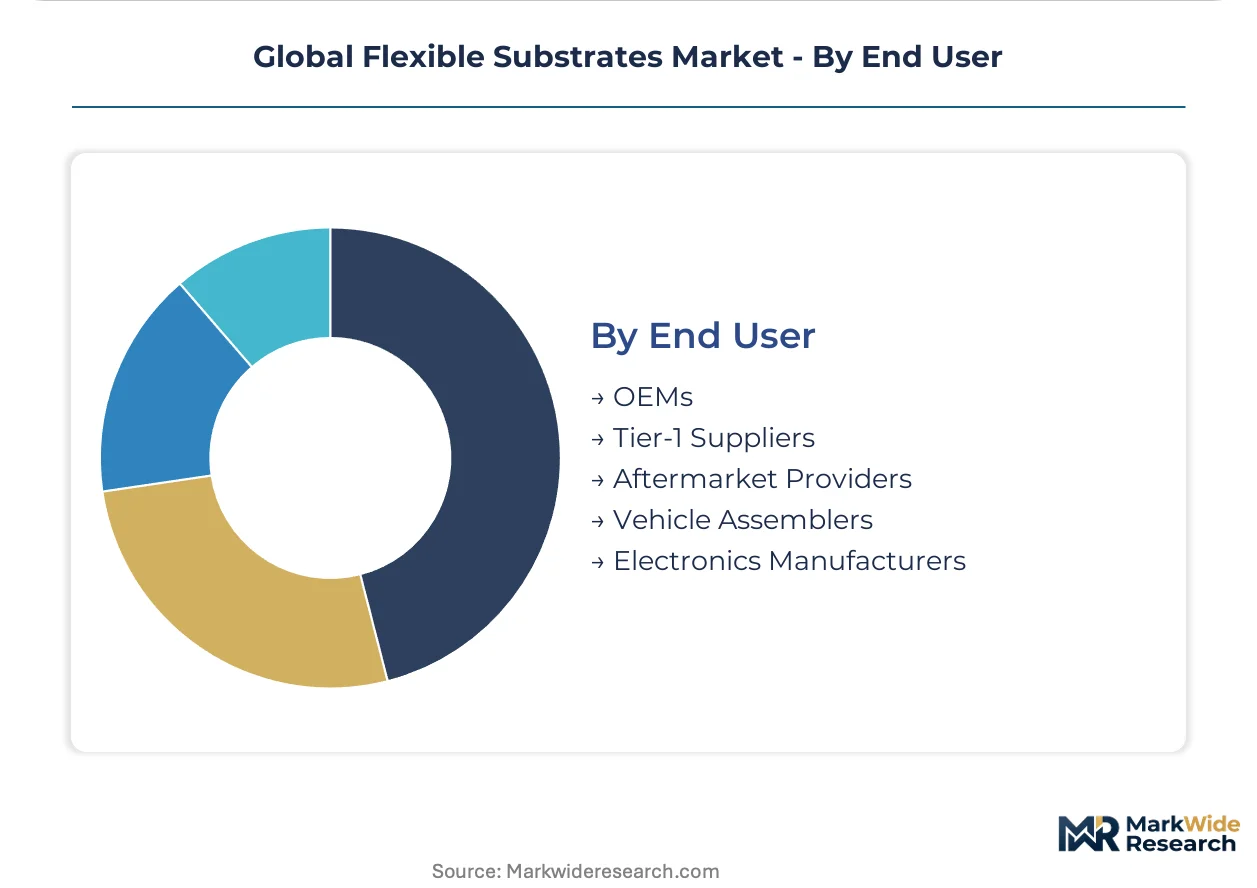
End User:
The end-user landscape for flexible substrates spans various points in the electronics supply chain, from component manufacturing to final product assembly.
- OEMs:Original Equipment Manufacturers integrate flexible substrates directly into their final products, such as smartphones, smartwatches, and medical devices, driving demand for customized solutions. Major electronics OEMs in South Korea and China are significant purchasers.
- Electronics Manufacturers:This category includes companies specializing in the fabrication of electronic components and modules, using flexible substrates for circuit boards, sensors, and display backplanes. These manufacturers require consistent material quality and high-volume supply.
- Tier-1 Suppliers:These companies provide sub-assemblies and critical components to OEMs, often requiring flexible substrates for display modules, battery packs, and sensor arrays.
- Vehicle Assemblers:The automotive industry utilizes flexible substrates for in-car displays, flexible lighting, and advanced driver-assistance system sensors, particularly in electric vehicles.
- Aftermarket Providers:This segment includes companies supplying replacement parts and repair services, where flexible substrates are used in repair kits for screens and circuit components.
Electronics Manufacturers represent the largest volume consumers of flexible substrates. Aftermarket Providers are gaining share fastest for repair and replacement needs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polyimide film production in South Korea and Japan anchors the global flexible substrates market, driven by advanced display manufacturing. This concentration influences material science innovations and supply chain dynamics worldwide. Demand centers also emerge from consumer electronics development and regulatory frameworks in other key regions.
South Korea
South Korean display manufacturers drive significant demand for flexible substrates, especially for OLED and foldable devices. The country's MFDS regulations influence biocompatible material development for medical wearables. Pyeongtaek and Cheonan host major display and component manufacturing hubs, accelerating substrate qualification for new device generations.
Japan
Japanese material science companies lead in high-purity polymer development, crucial for advanced flexible films. METI initiatives support R&D in next-generation materials like ultra-thin glass and specialized polyimides. Tokyo and Osaka serve as centers for advanced materials research and manufacturing, supplying critical components to global electronics.
United States
Device manufacturers in the United States increasingly adopt flexible substrates for consumer electronics and medical wearables. EPA substance control rules and the IRA's clean energy incentives shape material selection for sustainable applications like flexible photovoltaics. Silicon Valley and Boston act as innovation hubs for wearable electronics and advanced sensor development.
China
China's electronics sector shows significant investment in printed electronics for high-volume consumer goods and smart packaging. GB standards dictate material purity and performance criteria for electronic components, influencing market access for substrate manufacturers. Shenzhen and Shanghai are major production centers for flexible circuits and display modules.
Global Flexible Substrates Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue high-performance, specialized applications in next-generation devices. The market structure exhibits a tiered consolidation, with a few large chemical companies dominating raw material supply. Strategic archetypes include diversified material science giants, specialized film manufacturers, and integrated display component suppliers. Dominant competitive moves involve strategic partnerships for co-development and continuous capacity expansion in advanced film production.
Within the specialized film manufacturing archetype, Kolon Industries, Inc. exemplifies a focus on critical polyimide film production, essential for flexible displays. DuPont de Nemours, Inc. represents the diversified material science giant, leveraging its extensive material science portfolio to serve high-performance applications across various electronics segments. Teijin Limited also occupies a position in advanced film development, particularly with polyester films like polyethylene naphthalate, anchoring innovation in optical and thermal properties for display backplanes and flexible solar cells. These companies collectively illustrate the blend of material specialization and broad application support required in the flexible substrates market.
| Leading Market Players |
|---|
| DuPont de Nemours, Inc. |
| Teijin Limited |
| Kolon Industries, Inc. |
| Nippon Electric Glass Co., Ltd. |
| 3M Company |
| Schott AG |
| DuPont Teijin Films |
| Nitto Denko Corporation |
| Ube Industries, Ltd. |
| Others |
Cost & Logistics Intelligence
Strategic partnerships and co-development initiatives between device manufacturers and substrate suppliers anchor both the supply position and pricing power in the flexible substrates market. This collaborative model ensures specialized material development aligns with next-generation device requirements.
Pricing Analysis
Warranty and service bundling often dictates the total cost of ownership for advanced flexible substrates, extending beyond the initial per-unit transactional pricing. Contract-based long-term offtake agreements dominate for high-performance polyimide and PEN films, with price differentiation stemming from performance specifications and customization levels. Pricing pressure intensifies from high-volume consumer electronics manufacturers seeking cost reductions. Aerospace systems integrators demonstrate lower price sensitivity compared to consumer electronics OEMs.
Supply Chain Analysis
Single-source vulnerability sits with a limited number of specialized film manufacturers in Japan and South Korea for high-grade polyimide films. The supply chain draws heavily from high-purity monomers, critical for polyimide and polyethylene naphthalate production. Price volatility in these chemical precursors represents a significant structural risk. Distribution runs primarily through direct contracts with OEMs and electronics manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The flexible substrates market is poised for consolidation, driven by intense performance demands from consumer electronics manufacturers. This pressure forces out weaker players unable to meet stringent material specifications and high-volume production requirements.
For Market Incumbents: Hedge against the emergence of substitute technologies like ultra-thin glass by accelerating R&D into hybrid substrate stacks. Strengthen co-development partnerships with major device manufacturers in South Korea and the United States to secure long-term supply contracts. Invest in capacity expansion for specialized polyimide film production, particularly for high-temperature resistance. Pursue certification for biocompatible materials to expand into medical wearables, mitigating margin pressure in commoditized segments.
For New Entrants and Emerging Players: EU directives promoting recyclability in Europe open a window for bio-based polymer substrates designed for easier end-of-life recovery. Target the smart packaging segment by offering low-cost, high-volume printed electronics solutions for RFID tags and sensors. Focus on niche applications like flexible photovoltaics or specialized medical wearables where biocompatibility is a premium. Leverage advanced material science to meet unmet demands for circular economy mandates.
For Investors and Strategic Acquirers: Exit pathways concentrate in specialized film manufacturers and advanced material science startups with proprietary intellectual property. Long-term viability remains strong for companies addressing high-performance applications in foldable displays and medical wearables. Target firms with unique polymer formulations or expertise in complex roll-to-roll processing. The signal to watch is increased strategic partnerships between large chemical companies and innovative smaller players, indicating market validation.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion: Polyimide Films | Addresses growing demand for flexible displays from South Korean manufacturers. |
| Co-development Partnerships | Accelerates substrate qualification for new device generations in consumer electronics. |
| Bio-based Polymer R&D | Aligns with EU circular economy mandates for sustainable electronics components. |
| Roll-to-Roll Processing Optimization | Improves manufacturing yields and cost-competitiveness for high-volume flexible circuits. |
| Ultra-thin Glass Integration | Enhances hermeticity and surface smoothness for protective layers in foldable smartphones. |
Research Approach
Independent corroboration across company 10-K filings, industry association reports, and patent databases underwrites the qualitative findings. This study combined primary interviews with display R&D directors, material procurement specialists, and electronics manufacturing engineers. Secondary validation involved analysis of government electronics standards like GB standards in China and MFDS regulations in South Korea. Bottom-up and top-down triangulation ensured data consistency.
Rate-of-change decomposition informed the quantitative projections across the analysis window. The framework modeled segmentation dimensions including product type, technology, application, end-user, and regional regulatory frameworks. Compound annual growth rates were derived from historical data and projected market shifts. Key forecast inputs included polymer material innovation cycles and major device launch schedules.
The model assumes a particular technology adoption path; alternative pathways for ultra-thin glass or hybrid stacks would alter the outlook. Forecasts reflect assumptions regarding supply chain stability and regulatory evolution. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
South America Polyether Ether Ketone (Peek) Market
Specialty Materials
Adhesion Laminated Surface Protection Films Market
Specialty Materials
Niobium Pentoxide Market
Specialty Materials
Microwave Absorbing Materials Market
Specialty Materials
Carbon Mold Market
Specialty Materials
India Collagen Market
Specialty Materials
Silicone Solutions for Leather and Textile Market
Specialty Materials
Halloysite Market
Specialty Materials
Special Graphite Market
Specialty Materials
Charge Generation Materials (CGM) Market
Specialty Materials
PCB Prepreg Material Market
Specialty Materials
Hydrolysis Stable Polyester Films Market
Specialty Materials
Mesoporous Silica Market
Specialty Materials
Engineered Foam Market
Specialty Materials
Specialty and High Performance Films Market
Specialty Materials
Light Diffusion Materials Market