
 Europe Green Sic Market | 2026-2036
Europe Green Sic Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Green Sic Market Analytics
Modular substrate packaging is pivoting how European buyers configure Green SiC supply, shifting from standalone wafer purchases to integrated module-plus-driver bundles that reduce assembly steps. Esk-Sic GmbH anchors its position through captive refining capacity in Norway, while Infineon Technologies leverages its Dresden fabrication complex to control downstream substrate qualification. Washington Mills competes aggressively on abrasive-grade feedstock purity, a critical input for electronics-grade Green SiC production.
Green silicon carbide (SiC) is a synthetically produced crystalline compound of silicon and carbon, manufactured via the Acheson process at temperatures exceeding 2,200°C, prized for its wide bandgap of approximately 3.26 eV and thermal conductivity near 490 W/m·K that enables high-power, high-temperature semiconductor applications. Wafer and substrate segments dominate current European revenue as automotive qualification timelines favor established form factors, while power device technology leads adoption curves due to inverter efficiency mandates in electric vehicle platforms. Module configurations and RF device technology represent faster-growing pockets where margin pools deepen as defense and telecommunications buyers seek European-sourced alternatives.
The EU Green Deal, REACH chemical registration requirements, and the F-Gas Regulation collectively shape product standards and market access for Green SiC across Europe, pushing manufacturers toward lower-carbon production methods and transparent supply chain documentation. ECHA substance evaluation protocols now require detailed lifecycle data for SiC powders used in semiconductor manufacturing, raising compliance costs for non-integrated suppliers. Stakeholders must monitor how the EU AI Act and emerging CSRD reporting obligations will extend traceability requirements from raw material extraction through end-device deployment.
Market Dynamics
Modular substrate packaging is compressing traditional wafer procurement cycles across Europe's automotive corridor, forcing suppliers to bundle driver electronics with Green SiC substrates or lose qualification slots to integrated module competitors.
Growth Catalysts
- EU Green Deal decarbonization mandates:Binding emission targets for transport electrification are mandating SiC-based inverters in next-generation EV platforms, pulling substrate demand through Tier-1 power module suppliers.
- F-Gas Regulation phase-down:The progressive restriction of fluorinated greenhouse gases used in semiconductor etching is accelerating substitution toward Green SiC process chemistries that bypass F-gas-intensive manufacturing steps.
- Stuttgart-Munich automotive cluster concentration:OEM engineering centers and powertrain R&D facilities within this corridor are co-locating qualification labs with substrate vendors, compressing design-in timelines from 24 months to 14 months.
Market Restraints
- Quartz sand and petroleum coke input volatility:Acheson process feedstock costs fluctuate with energy-intensive mining operations in Norway and petroleum refining margins, squeezing margin predictability for non-integrated refiners.
- Norwegian hydropower supply concentration:Over 70% of European Green SiC refining capacity depends on Norwegian grid electricity, creating single-geography exposure to Nordic weather patterns and transmission constraints.
- Silicon nitride substitution in RF applications:Defense contractors are qualifying gallium nitride-on-silicon nitride alternatives for radar systems, threatening Green SiC's historical dominance in high-frequency power amplification.
Strategic Opportunities
- Polish and Romanian manufacturing greenfield sites:Lower industrial electricity rates and EU cohesion fund access are attracting substrate finishing operations to Eastern European markets currently dependent on German and French imports.
- CSRD supply chain disclosure requirements:The Corporate Sustainability Reporting Directive is creating first-mover advantage for vendors with lifecycle carbon data on Norwegian-sourced feedstock, differentiating bids for automotive OEM sustainability scorecards.
- GaN-SiC heterogeneous integration:Hybrid power modules combining gallium nitride switching with silicon carbide thermal management are opening new design wins in 800V EV architectures where neither material alone optimizes cost-performance tradeoffs.
Industry Challenges
- Acheson furnace operation expertise scarcity:Experienced kiln engineers capable of maintaining 2,200°C temperature uniformity across 50-meter resistor beds are retiring faster than vocational programs in Germany and Norway can replenish the pipeline.
- Automotive AEC-Q101 qualification timelines:Power device manufacturers face 18-month validation cycles for each new substrate supplier, freezing out second-source strategies and locking procurement to incumbent qualified vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Green Sic Market |
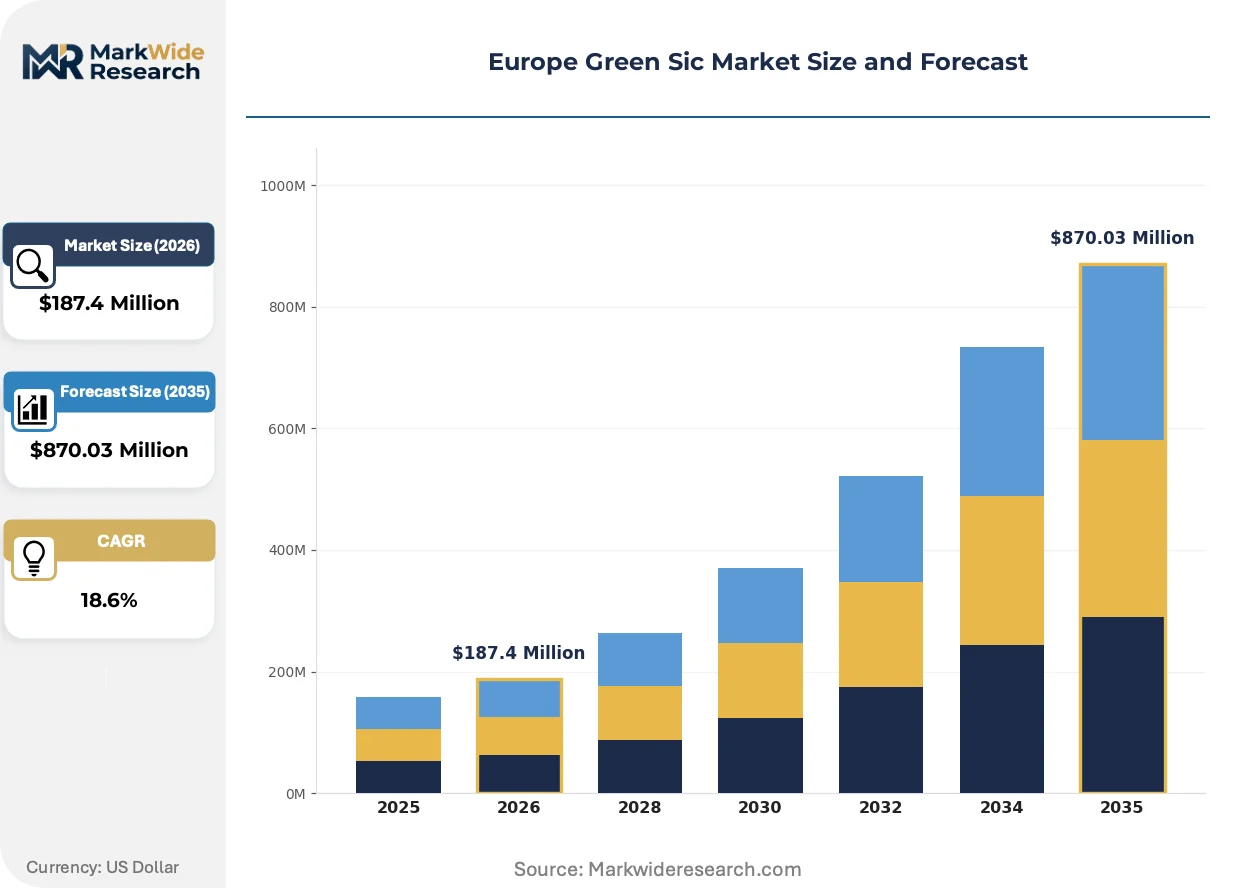
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $870.03 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wafer, Substrate, Bulb, Module End User: Consumer Electronics, Renewable Energy, Industrial Equipment, Automotive Technology: Power Devices, RF Devices, Photovoltaic Cells, High-Frequency Devices Application: Lighting, Power Supplies, Electric Vehicles, Communication |
| Companies Covered | Fiven ASA, Grindwell Norton, Washington Mills, General Abrasivi Srl, Esk-Sic GmbH, Esd-Sic bv, Snam SpA, CoorsTek, Infineon Technologies, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Green Sic Market Evolving Landscape
Green SiC manufacturing is bifurcating between commodity abrasive grades and electronics-grade substrates, with process control technologies becoming the decisive competitive wedge separating margin pools.
Photoluminescence wafer mapping is converging with machine-vision defect classification to enable 100% substrate screening without destructive sampling. Bosch and Continental's power electronics divisions are mandating this inspection protocol for 2027 platform qualifications. The technology is converging with legacy electrical testing to compress incoming quality assurance from three weeks to four days, forcing substrate vendors to retrofit capital equipment or exit automotive supply tiers.
REACH substance evaluation protocols now require full lifecycle toxicity data for SiC nanopowders used in chemical mechanical planarization slurries. ECHA's 2024 update to registration dossier requirements is blocking non-compliant imports from Chinese refiners lacking European representative offices. Semiconductor fabs in Dresden and Leuven are responding by dual-sourcing from Esk-Sic's Norwegian operations and domestic reprocessors with established SCIP database entries.
Automotive buyers are consolidating substrate procurement through module-level contracts rather than discrete wafer purchases. Tier-1 suppliers including Vitesco and BorgWarner now specify substrate-plus-driver integrated units, displacing standalone wafer vendors from direct OEM relationships. This concentration is most visible in Germany's Baden-Württemberg region, where Porsche and Mercedes-Benz engineering teams have eliminated standalone substrate technical reviews from their 2026 platform development gates.
Europe Green Sic Market Segmentation
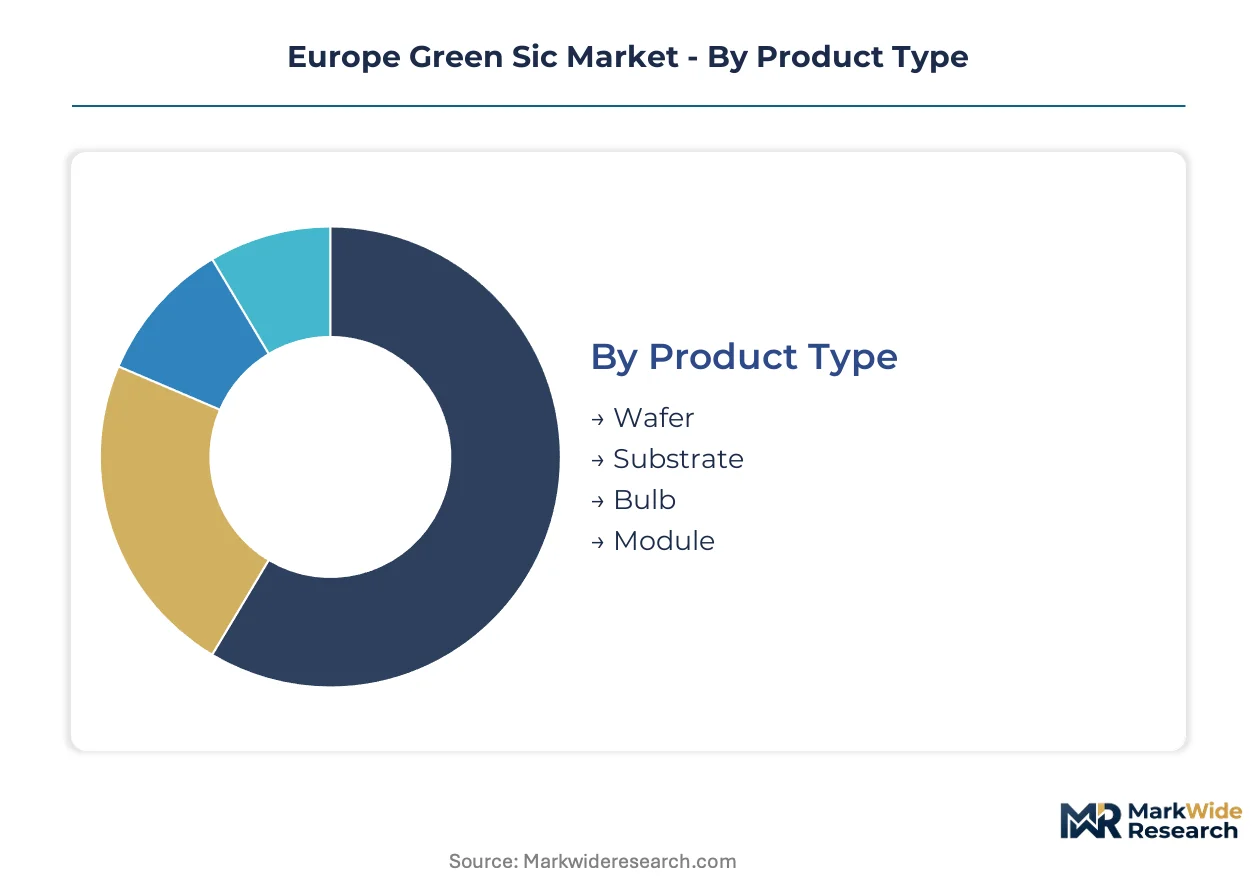
Segmentation in Europe's Green SiC market reveals how substrate form factors and integration depth determine procurement patterns. Automotive buyers increasingly favor embedded module configurations over discrete wafers, reshaping supplier qualification requirements across Germany's automotive corridor.
Product Type:
Integration depth varies sharply across product categories, with standalone wafers serving legacy qualification pipelines while module-embedded substrates capture new platform wins.
- Wafer:Discrete monocrystalline slices processed through chemical mechanical planarization for surface flatness below 0.5 nm RMS. Demand concentrates in Dresden and Leuven semiconductor fabs requiring custom thickness specifications for legacy power MOSFET lines. REACH registration dossier completeness now gates import eligibility for non-European wafer suppliers.
- Substrate:Polycrystalline or monocrystalline base layers engineered for thermal expansion matching with gallium nitride epilayers. Stuttgart-Munich engineering centers specify these for 800V traction inverter development, compressing qualification cycles through co-located metrology labs. The EU Green Deal's transport electrification mandates pull substrate demand through Tier-1 module suppliers.
- Bulb:Crushed abrasive-grade material serving non-electronics applications including precision grinding wheels. Esk-Sic's Norwegian refining operations dominate supply for German automotive tooling suppliers.
- Module:Integrated substrate-plus-driver units specified by Vitesco and BorgWarner for 2026 platform gates. Porsche and Mercedes-Benz engineering teams in Baden-Württemberg have eliminated standalone substrate reviews from procurement workflows.
Volume placements concentrate in Substrate; the faster expansion belongs to Module.
End User:
Cost tier stratification separates premium automotive qualification from volume industrial procurement, with renewable energy buyers occupying a mid-tier pricing band.
- Consumer Electronics:Smartphone and laptop charger manufacturers specifying Green SiC for compact adapter designs. German and French OEMs source through Asian module integrators, limiting direct European substrate relationships.
- Renewable Energy:Solar inverter and wind converter manufacturers requiring high-voltage switching efficiency. Polish and Romanian project developers are expanding procurement as domestic manufacturing greenfield sites reduce import dependency.
- Industrial Equipment:Motor drive and welding power supply manufacturers across Italy and Spain. ECHA substance evaluation protocols for SiC nanopowders in chemical mechanical planarization slurries raise compliance costs for non-integrated refiners.
- Automotive:Traction inverter and onboard charger applications dominating European Green SiC consumption. Binding emission targets under the EU Green Deal mandate SiC-based designs in next-generation EV platforms, with engineering concentration in Germany's Stuttgart-Munich corridor pulling substrate demand through compressed 14-month qualification timelines.
Revenue concentration sits with Automotive; Renewable Energy climbs fastest as Eastern European manufacturing expands.
Technology:
Maturity curves separate established power device architectures from emerging RF and photovoltaic applications still navigating qualification barriers.
- Power Devices:Schottky diodes and MOSFETs enabling high-efficiency switching in traction inverters. Infineon's Dresden fabrication complex controls downstream substrate qualification for this segment, leveraging captive process data.
- RF Devices:High-frequency power amplifiers for radar and telecommunications infrastructure. Defense contractors are qualifying gallium nitride-on-silicon nitride alternatives, threatening Green SiC's historical dominance in radar systems.
- Photovoltaic Cells:Emerging application in high-efficiency solar cell architectures. Italian research consortia are piloting SiC-based heterojunction designs with limited commercial scale.
- High-Frequency Devices:Base station and satellite communication components requiring wide bandgap performance. French telecommunications equipment manufacturers are sourcing through established substrate vendors with AEC-Q101 qualification history.
Commercial scale favors Power Devices; RF Devices face substitution pressure from competing wide bandgap materials.
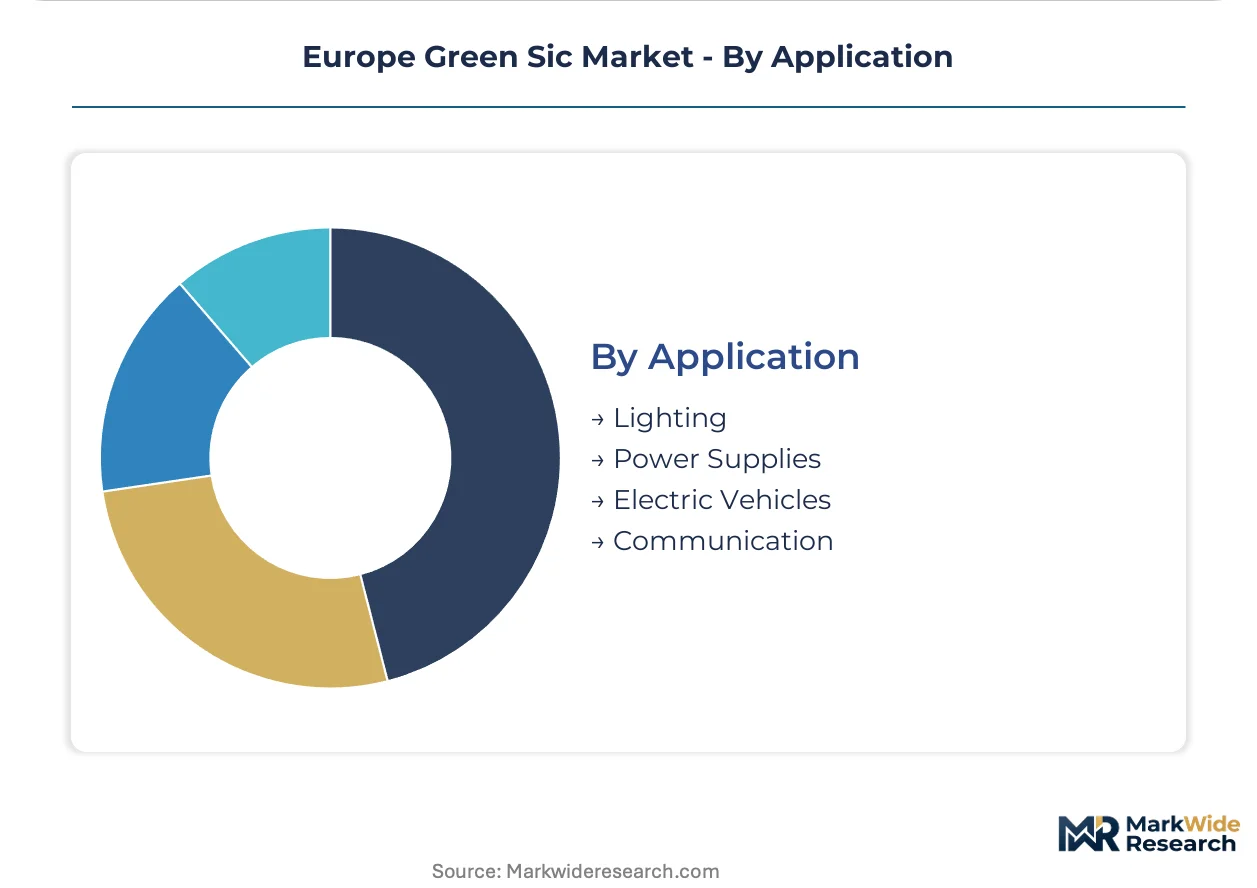
Application:
Supply concentration patterns mirror the geographic clustering of downstream manufacturing, with electric vehicle applications anchoring demand in Germany's automotive corridor.
- Lighting:LED driver and solid-state lighting applications with declining European substrate consumption. Asian LED packaging houses have captured volume production, limiting European Green SiC exposure.
- Power Supplies:Server rack and telecommunications rectifier applications requiring high-efficiency conversion. Dutch data center operators are specifying SiC-based designs under CSRD supply chain disclosure requirements.
- Electric Vehicles:Traction inverter, DC-DC converter, and onboard charger applications commanding premium substrate specifications. The F-Gas Regulation's phase-down of fluorinated greenhouse gases accelerates substitution toward Green SiC process chemistries that bypass F-gas-intensive manufacturing steps.
- Communication:5G base station and satellite ground station infrastructure. German and French defense procurement offices are mandating European-sourced substrates for strategic communication systems.
Procurement scale centers on Electric Vehicles; Communication applications gain share fastest as defense qualification timelines compress.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Norwegian hydropower refineries supply feedstock to downstream fabricators across the continent, while automotive demand concentrates in German industrial corridors. This production-consumption geography shapes procurement patterns and regulatory compliance obligations.
Germany
Stuttgart-Munich automotive engineering centers drive substrate qualification for 800V traction inverters under EU Green Deal transport electrification mandates. The F-Gas Regulation accelerates substitution away from fluorinated etching chemistries toward Green SiC process alternatives. Baden-Württemberg hosts Porsche and Mercedes-Benz procurement teams that eliminated standalone substrate reviews from 2026 platform gates.
France
Defense procurement offices mandate European-sourced substrates for strategic radar and satellite communication systems. ECHA substance evaluation protocols under REACH require full lifecycle toxicity data for SiC nanopowders used in chemical mechanical planarization. Auvergne-Rhône-Alpes telecommunications equipment manufacturers source through vendors with established AEC-Q101 qualification history.
Norway
Esk-Sic's captive refining capacity anchors European electronics-grade Green SiC supply through hydropower-dependent Acheson furnace operations. Over 70% of continental refining capacity depends on Norwegian grid electricity, creating exposure to Nordic weather patterns and transmission constraints. Coastal smelter locations leverage deepwater port access for quartz sand and petroleum coke feedstock imports.
Poland
Renewable energy inverter manufacturers expand procurement as domestic manufacturing greenfield sites reduce import dependency on German and French substrate finishing. EU cohesion fund access attracts substrate finishing operations seeking lower industrial electricity rates. Warsaw-based project developers specify SiC-based designs for solar and wind converter applications.
Belgium
Leuven semiconductor fabs dual-source from Norwegian operations and domestic reprocessors with established SCIP database entries under REACH registration requirements. ECHA's 2024 dossier updates block non-compliant imports from refiners lacking European representative offices. Flemish research consortia pilot heterogeneous integration combining gallium nitride switching with silicon carbide thermal management.
Europe Green Sic Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across substrate qualification tiers. The vendor base organizes around three strategic archetypes: captive refiners with backward integration into Norwegian hydropower, module integrators bundling driver electronics with substrate supply, and abrasive-grade feedstock suppliers pivoting toward electronics-grade purification. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with automotive qualification timelines favoring incumbents over new entrants.
Among Norwegian-based refiners, Esk-Sic GmbH anchors the captive production archetype through hydropower-dependent smelter operations. Washington Mills exemplifies the feedstock-specialist pivot, competing on abrasive-grade purity as a critical input pathway for electronics-grade production. Infineon Technologies occupies the module-integration position, leveraging Dresden fabrication complex control over downstream substrate qualification. These three represent distinct strategic postures within a market where automotive procurement consolidation favors bundled module supply over discrete wafer transactions.
| Leading Market Players |
|---|
| Fiven ASA |
| Grindwell Norton |
| Washington Mills |
| General Abrasivi Srl |
| Esk-Sic GmbH |
| Esd-Sic bv |
| Snam SpA |
| CoorsTek |
| Infineon Technologies |
| Others |
Value Network & Pricing Analysis
Acheson furnace engineers concentrated in Norway's coastal smelter towns command wage premiums that propagate through substrate pricing tiers, widening spreads between electronics-grade and abrasive-grade Green SiC as labor-cost differentials compound raw material volatility.
Pricing Analysis
Margin tightening in electronics-grade substrates reflects contract-based long-term offtake structures that lock automotive OEMs into 18-month qualification cycles with incumbent vendors. Pricing stratifies across AEC-Q101 certified premium tiers, REACH-compliant standard grades, and unregistered economy imports facing ECHA blockage. Cost-down pressure accelerates as module integrators bundle driver electronics, displacing standalone wafer margins. Renewable energy buyers in Poland and Romania exhibit highest price sensitivity; German automotive procurement teams prioritize qualification speed over unit cost.
Supply Chain Analysis
Experienced kiln operators retiring from Norway's hydropower-dependent smelter workforce constrain furnace utilization rates across European refining capacity. Feedstock supply draws from Norwegian quartz sand mining, petroleum coke from European refiners, and graphite electrodes sourced through limited qualified vendors. Single-geography exposure to Nordic grid electricity creates weather-dependent output volatility. Distribution runs through Dresden fabrication complexes for downstream qualification, with Leuven and Stuttgart-Munich corridor fabs completing substrate finishing operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Green SiC substrate supply remains structurally capped by Acheson furnace expertise scarcity, propping pricing power for qualified incumbents while locking out rapid capacity expansion.
For Market Incumbents: Hedge against gallium nitride-on-silicon nitride substitution in RF radar applications by accelerating GaN-SiC heterogeneous integration R&D. Secure backward integration into Norwegian hydropower refining through long-term offtake agreements with Esk-Sic GmbH, insulating feedstock access as ECHA registration requirements tighten. For New Entrants and Emerging Players: Direct-to-automotive-Tier-1 digital procurement platforms offer qualification bypass routes for module-embedded substrate vendors lacking AEC-Q101 history. Target Polish and Romanian renewable energy inverter manufacturers as the most penetrable segment, leveraging EU cohesion fund project visibility and lower domestic electricity costs for finishing operations. For Investors and Strategic Acquirers: Re-rating potential sits with captive Norwegian refiners possessing established SCIP database entries and lifecycle carbon documentation given CSRD supply chain disclosure mandates. Monitor ECHA substance evaluation protocol enforcement intensity as the inflection signal distinguishing compliant premium-tier vendors from blocked economy-grade imports.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Norwegian Hydropower Refining | Captive feedstock supply secures margin control as petroleum coke volatility squeezes non-integrated competitors. |
| GaN-SiC Heterogeneous Integration Development | Hybrid module architectures defend RF device share against pure GaN-on-SiN radar substitution threats. |
| Polish Manufacturing Greenfield Expansion | Lower industrial electricity rates attract substrate finishing operations from German corridor concentration. |
| AEC-Q101 Accelerated Qualification Investment | Compressed 14-month automotive timelines favor pre-qualified incumbents over second-source strategies. |
| CSRD Lifecycle Carbon Data Infrastructure | First-mover documentation advantage captures OEM sustainability scorecard procurement consolidation. |
Research Methodology
Trade flow databases, ECHA registration dossiers, and EU industrial electricity consumption statistics formed the secondary backbone, cross-referenced with primary interviews involving Acheson furnace operations managers, Tier 1 power module procurement leads, and automotive platform qualification engineers. Bottom-up substrate shipment tallies from Norwegian refiners were triangulated against top-down automotive inverter content-per-vehicle estimates.
Historical capacity utilization and qualification timeline trends across the analysis window informed projection elasticity assumptions. Segmentation modeling incorporated product type integration depth, end-user cost tier stratification, technology maturity curves, and application geographic clustering. CAGRs were derived from automotive electrification mandate penetration rates and F-Gas Regulation substitution elasticity coefficients.
The model holds under stable ECHA enforcement intensity and Norwegian grid transmission capacity; deviation in REACH substance evaluation protocol stringency or Nordic hydropower output would shift supply availability and pricing tier spreads. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Silicone Solutions for Leather and Textile Market
Specialty Materials
Europe Polyether Ether Ketone (Peek) Market
Specialty Materials
Advanced Green Septa Market
Specialty Materials
Asia-Pacific Reflective Tape Market
Specialty Materials
EVA Interlayer for Photovoltaic Market
Specialty Materials
Global Polybenzimidazoles (PBI) Market
Specialty Materials
ePTFE Electronic Film Market
Specialty Materials
Charge Generation Materials (CGM) Market
Specialty Materials
Global Montan Wax Market
Specialty Materials
Global PE Films Market
Specialty Materials
Polyetherimide (PEI) Market
Specialty Materials
Water Soluble Film Market
Specialty Materials
UV Stabilized Films Market
Specialty Materials
Battery Separator Films Market
Specialty Materials
Global Ajinomoto Build-Up Film Substrate Market
Specialty Materials
Specialty Silicone Market