
 PVB Interlayers Market | 2026-2036
PVB Interlayers Market Size, Share, and Industry Trends Forecast 2026-2036
PVB Interlayers Market Outlook
The gap between acoustic and standard-grade PVB interlayers is rebalancing as automotive OEMs raise sound-dampening specifications for electric vehicles. Eastman Chemical Company leverages its integrated resin-to-film supply chain to sustain cost advantages across premium formulations. Kuraray dominates acoustic PVB development through proprietary polymer architecture, while Sekisui Chemical anchors Asian supply security with multi-site manufacturing in Japan and China.
PVB interlayers are thermoplastic resin films composed of polyvinyl butyral plasticized with plasticizers, typically manufactured through extrusion casting at controlled temperatures to achieve optical clarity and adhesion to glass surfaces. These films bond glass layers under heat and pressure to produce laminated safety glass that retains fragments upon impact, serving critical functions in automotive windshields, architectural facades, and ballistic protection systems. Standard PVB retains volume leadership in mature automotive replacement markets where cost sensitivity limits specification upgrades, yet acoustic PVB captures expanding margin pools as electric vehicle platforms prioritize cabin quietness without added weight. Fire-resistant PVB represents the fastest-growing product category, driven by tightening building codes for high-rise evacuation routes and atrium glazing in commercial developments.
Europe's Construction Products Regulation and the EU Green Deal shape product standards by mandating recycled-content disclosures and fire-performance classifications for facade materials, while China's GB standards for automotive safety glass enforce minimum penetration resistance that elevates interlayer thickness requirements. In the United States, NHTSA Federal Motor Vehicle Safety Standard 205 governs windshield optical properties and impact retention, directly influencing interlayer formulation choices by domestic and import automakers. Stakeholders must monitor evolving carbon-border adjustments and building-embodied-carbon regulations that could redirect procurement toward regionally manufactured interlayers with verified lifecycle data.
Market Dynamics
Automotive electrification and high-rise construction codes are compressing specification cycles for acoustic and fire-resistant interlayers, forcing resin suppliers to requalify formulations faster than traditional automotive program timelines allow.
Growth Catalysts
- EU Green Deal embodied-carbon mandates:Building developers in Germany and France now specify interlayers with verified recycled content and lower lifecycle emissions, pulling demand toward reformulated products.
- China's GB standards for automotive safety glass:Penetration resistance thresholds have elevated minimum interlayer thickness requirements for domestic and export-bound windshields.
- Electric vehicle cabin quietness specifications:Acoustic-grade PVB is displacing standard grades in premium EV platforms where weight-neutral sound dampening commands design priority.
Market Restraints
- Plasticizer cost volatility:Triethylene glycol ester prices fluctuate with petrochemical feedstock markets, compressing margin predictability for film extruders.
- Resin supply concentration:Polyvinyl alcohol feedstock for butyralization concentrates among Asian chemical conglomerates, creating geographic dependency risk.
- Ethylene-vinyl acetate substitution:EVA interlayers capture share in photovoltaic and some architectural applications where optical clarity requirements are less stringent.
Strategic Opportunities
- India's building code modernization:Urban high-rise construction in Mumbai and Bangalore is adopting laminated safety glass faster than local interlayer supply can match.
- Smart glass integration:Suspended particle device and electrochromic layers require specialized interlayer adhesion chemistry that incumbent film producers can extend into.
- Direct-to-processor digital channels:Glass fabricators in China's Jiangsu province are bypassing distributor tiers through platform-based resin procurement.
Industry Challenges
- Multi-standard certification complexity:A single architectural interlayer SKU must simultaneously satisfy CE marking, UL fire ratings, and local seismic codes, extending qualification timelines.
- Extrusion line conversion capex:Shifting between standard, acoustic, and fire-resistant grades requires dedicated die configurations and clean-room protocols that strain mid-capacity producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PVB Interlayers Market |
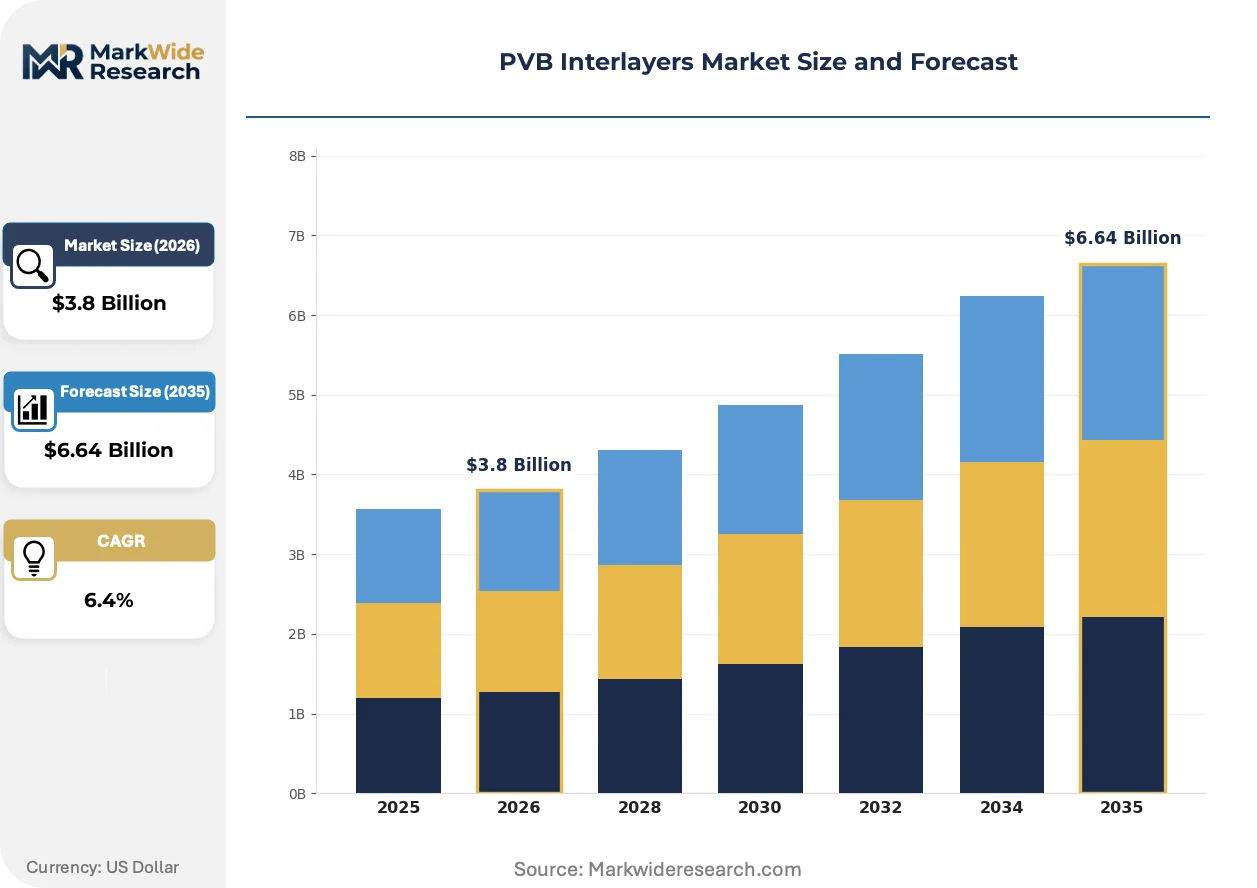
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard PVB, Fire-Resistant PVB, Acoustic PVB, Laminated PVB Application: Automotive Glass, Architectural Glass, Safety Glass, Decorative Glass End User: Automotive Manufacturers, Construction Companies, Glass Processors, Architectural Firms Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesale |
| Companies Covered | Eastman Chemical Company, Kuraray, Sekisui Chemical, Everlam, Saint-Gobain, Chang Chun Group, Huakai Plastic (Chongqing), Genau Manufacturing Company LLP, Guangzhou Aojisi New Material, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PVB Interlayers Market Strategic Shifts
Interlayer functionality is bifurcating toward specialized performance tiers as end-users reject commodity-grade specifications in favor of certified, application-specific films that command measurable safety or comfort outcomes.
Multilayer acoustic PVB is rewriting cabin noise management for electric vehicle platforms. The technology sandwiches damping resins between structural PVB layers to target specific frequency ranges. European luxury automakers have adopted this construction for flagship sedans and SUVs launching between 2024 and 2027. The approach is compressing traditional NVH engineering cycles by integrating acoustic treatment into the glazing stack rather than adding secondary dampening materials.
REACH chemical restriction proposals are forcing reformulation of conventional plasticizer packages. The European Chemicals Agency scrutiny of phthalate alternatives is accelerating migration toward bio-based and non-aromatic plasticizer chemistries. German and Dutch architectural glass processors are now requiring full substance disclosure from interlayer suppliers to preempt downstream compliance liability.
Buyer consortiums among mega-scale glass fabricators are consolidating procurement leverage. Tier-one automotive glazing suppliers and multinational construction material distributors are forming volume-commitment agreements that lock resin allocation and bypass traditional chemical distributor networks. This pattern is most pronounced in China's Yangtze River Delta and Germany's Rhine-Ruhr industrial corridor, where processor scale now rivals interlayer producer bargaining power.
PVB Interlayers Market Segmentation
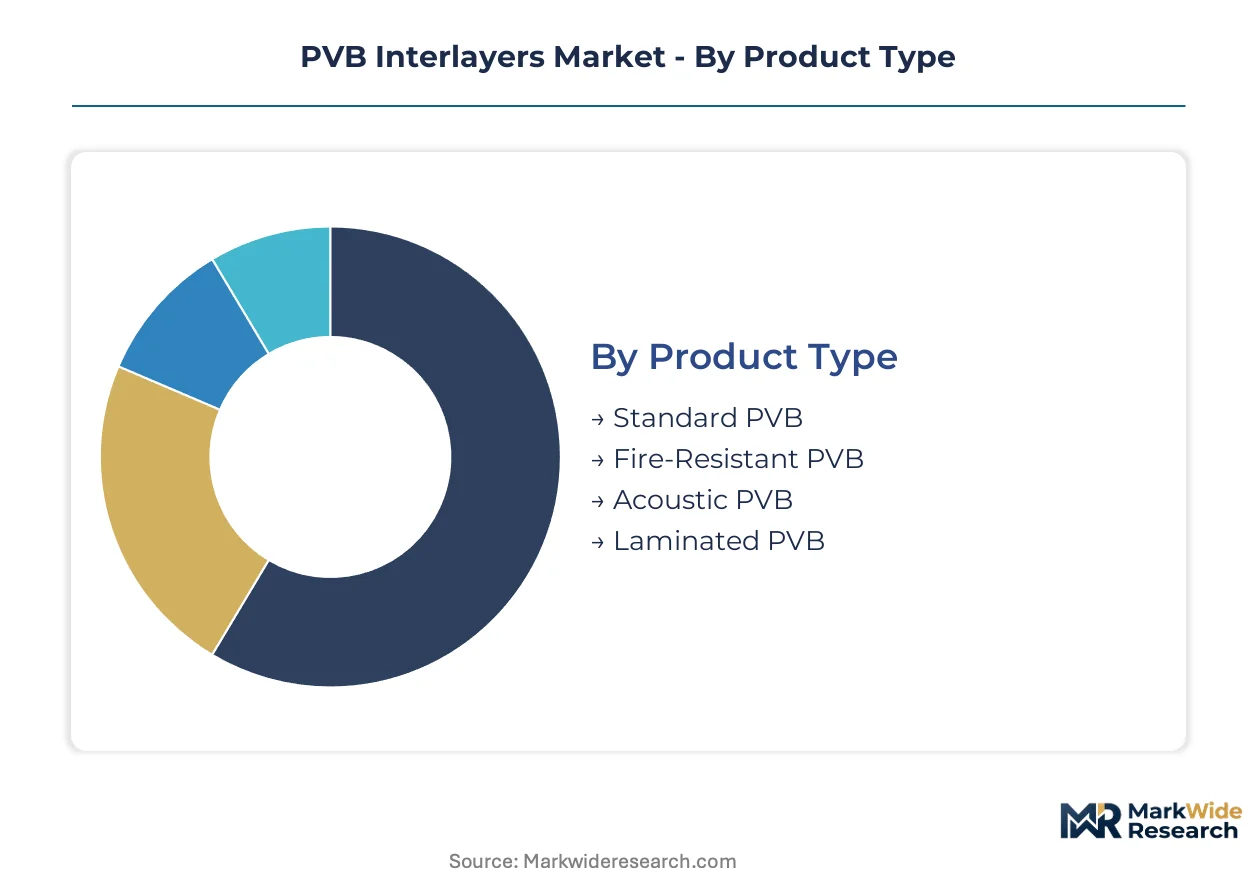
PVB interlayer procurement splits sharply between specification-driven automotive programs and cost-sensitive architectural replacement markets. Buyers evaluate acoustic damping coefficients, fire-resistance ratings, and optical clarity thresholds that vary by end-use certification requirements.
Product Type:
Automotive OEMs and glazing contractors prioritize performance tier over base resin cost when specifying interlayer formulations.
- Standard PVB:Composed of conventional polyvinyl butyral plasticized with triethylene glycol esters for general-purpose optical clarity and glass adhesion. Demand concentrates in mature automotive replacement markets across the United States and Western Europe where cost sensitivity limits specification upgrades.
- Acoustic PVB:Engineered with multilayer constructions that sandwich damping resins between structural PVB layers to target specific frequency ranges. Electric vehicle platforms in Germany and China specify this grade for weight-neutral cabin quietness that displaces secondary dampening materials.
- Fire-Resistant PVB:Incorporates intumescent additives that expand under heat to form insulating char barriers. European high-rise construction under the EU Green Deal and updated Construction Products Regulation mandates this grade for evacuation route glazing.
- Laminated PVB:Pre-bonded multilayer constructions supplied to glass processors for streamlined autoclave processing. Architectural fabricators in China's Jiangsu province specify this format to reduce handling damage and accelerate production cycles.
Volume sits with Standard PVB; growth tilts toward Fire-Resistant PVB.
Application:
End-use certification complexity determines interlayer thickness, optical grade, and supplier qualification requirements.
- Automotive Glass:Windshield and sidelite applications governed by NHTSA Federal Motor Vehicle Safety Standard 205 in the United States and GB standards in China. Penetration resistance thresholds have elevated minimum interlayer thickness requirements for domestic and export-bound production.
- Architectural Glass:Facade and curtain wall installations requiring CE marking under Europe's Construction Products Regulation. German and French developers now specify interlayers with verified recycled content and lower lifecycle emissions.
- Safety Glass:Ballistic and hurricane-resistant glazing for government buildings and critical infrastructure. U.S. federal procurement standards mandate specific interlayer ply counts and adhesion values for blast mitigation.
- Decorative Glass:Colored and patterned interlayers for interior partitions and retail environments. Lower optical clarity tolerances allow processors to utilize edge-trim recycled material in this segment.
Automotive Glass commands the thickest interlayer specifications; Architectural Glass is expanding most quickly under green building mandates.
End User:
Procurement scale and technical specification authority vary dramatically across buyer types.
- Automotive Manufacturers:Direct qualification relationships with resin suppliers for platform-specific acoustic and optical performance. Tier-one glazing suppliers form volume-commitment agreements that lock resin allocation.
- Construction Companies:Project-based procurement responding to local building code enforcement for fire-resistant glazing. Mumbai and Bangalore high-rise developers face supply constraints as laminated safety glass adoption outpaces local interlayer capacity.
- Glass Processors:Mid-scale fabricators purchasing standard grades through distributor networks or direct digital channels. China's Yangtze River Delta processors increasingly bypass distributor tiers through platform-based resin procurement.
- Architectural Firms:Specification influence without direct procurement authority, driving demand for certified performance data and lifecycle transparency. Dutch and German practices now require full substance disclosure from interlayer suppliers.
Glass Processors move the highest tonnage; Automotive Manufacturers drive premium-grade specification.
Distribution Channel:
Channel selection reflects order scale, technical service requirements, and geographic proximity to resin production.
- Direct Sales:Long-term supply contracts between resin producers and tier-one automotive glazing suppliers or multinational construction distributors. Buyer consortiums in Germany's Rhine-Ruhr corridor consolidate procurement leverage.
- Distributors:Regional chemical distributors serving mid-capacity glass processors with standard-grade inventory and technical support. Margin compression from direct digital channels is eroding this channel's share.
- Online Retail:Platform-based procurement for small-batch decorative and replacement-grade interlayers. Limited to non-critical applications where certification documentation requirements are minimal.
- Wholesale:Volume aggregation for export-oriented glass processors in China's coastal manufacturing zones. Price volatility in plasticizer feedstock markets complicates long-term wholesale contracting.
Direct Sales anchors premium-grade volume; platform-based channels are gaining share fastest among mid-scale processors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta anchors interlayer demand as Jiangsu province glass processors scale laminated safety glass capacity for both domestic high-rise construction and export markets.
United States
Automotive OEMs in Detroit and the Southeast are expanding electric vehicle windshield programs with acoustic-grade specifications. NHTSA Federal Motor Vehicle Safety Standard 205 governs optical properties and impact retention, directly influencing interlayer formulation choices. Glass fabricators in the Midwest corridor face margin pressure from plasticizer cost volatility tied to Gulf Coast petrochemical feedstock markets.
Germany
Luxury automakers in Bavaria and Baden-Württemberg specify multilayer acoustic PVB for flagship EV platforms launching through 2027. The EU Green Deal and updated Construction Products Regulation mandate fire-resistant glazing for high-rise evacuation routes. The Rhine-Ruhr industrial corridor hosts buyer consortiums consolidating procurement leverage among mega-scale glass fabricators.
China
Domestic glass processors in Jiangsu and Shandong provinces are scaling capacity for architectural projects and automotive export programs. GB standards enforce minimum penetration resistance that elevates interlayer thickness requirements. Platform-based resin procurement in the Yangtze River Delta is bypassing traditional distributor tiers.
India
Urban high-rise construction in Mumbai and Bangalore is adopting laminated safety glass faster than local interlayer supply can match. The country's national building code modernization is accelerating fire-resistant glazing specifications. Mid-scale glass processors in Gujarat and Maharashtra rely on import channels for certified interlayer grades.
Japan
Automotive glazing suppliers in the Nagoya and Kanto regions maintain direct qualification relationships with resin producers for platform-specific acoustic performance. METI industrial standards shape quality benchmarks for optical clarity and adhesion values. Multi-site manufacturing across Japan and China anchors Asian supply security for regional automakers.
PVB Interlayers Market Competitive Environment
Premium-margin players sit above commodity-margin players across acoustic and fire-resistant formulation tiers, while standard-grade producers compete on resin-to-film conversion efficiency. The vendor base separates into three strategic archetypes: integrated resin-to-film producers controlling captive polyvinyl alcohol supply, specialized acoustic-grade developers with proprietary polymer architectures, and regional extruders serving cost-sensitive replacement markets. Dominant competitive moves include backward integration into polyvinyl alcohol feedstock and multi-site manufacturing expansion to hedge geographic concentration risk.
Within the integrated producer tier, Eastman Chemical Company exemplifies cost advantages sustained across premium formulations through upstream control over resin supply. Kuraray occupies a position representing specialized acoustic development through proprietary multilayer constructions. Sekisui Chemical anchors Asian supply security with manufacturing presence spanning Japan and China.
| Leading Market Players |
|---|
| Eastman Chemical Company |
| Kuraray |
| Sekisui Chemical |
| Everlam |
| Saint-Gobain |
| Chang Chun Group |
| Huakai Plastic (Chongqing) |
| Genau Manufacturing Company LLP |
| Guangzhou Aojisi New Material |
| Others |
Value Chain & Pricing Dynamics
Triethylene glycol ester plasticizer costs cascade from Gulf Coast petrochemical feedstock markets through standard-grade film extruders to automotive replacement distributors, with volatility compressing margin predictability at each conversion tier. Acoustic and fire-resistant formulations command premium spreads by locking resin allocation through volume-commitment agreements that insulate tier-one buyers from spot market swings.
Pricing Analysis
Certified penetration resistance anchors value-based pricing for automotive OEM windshields, with NHTSA and GB compliance tiers separating premium acoustic specifications from commodity replacement grades. Price differentiation tracks certification burden and interlayer thickness requirements, with electric vehicle platforms least sensitive due to cabin quietness prioritization. Cost compression in standard-grade channels intensifies as China's platform-based procurement bypasses distributor markups. Glass processors in mature replacement markets exhibit highest price sensitivity, while tier-one automotive glazing suppliers accept longer-term contracts.
Supply Chain Analysis
Dual-sourcing requirements from German and Japanese automakers mandate multi-site qualification of resin producers across Japan, China, and the United States, fragmenting procurement leverage. Polyvinyl alcohol feedstock for butyralization draws from Asian chemical conglomerates, while triethylene glycol esters hinge on Gulf Coast ethylene oxide capacity. Single-source vulnerability concentrates in specialized acoustic-grade polymer architectures held by proprietary developers. Distribution runs through direct long-term contracts for premium grades and platform-based digital channels for mid-scale architectural processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Resin supply concentration and extrusion line conversion capex constraints prop pricing for qualified suppliers, with fire-resistant formulation capacity particularly bottlenecked by clean-room protocol requirements.
For Market Incumbents: Acquire captive polyvinyl alcohol production assets to hedge feedstock cost volatility and secure margin control across premium formulations. Expand multi-site manufacturing footprint into India's Gujarat and Maharashtra clusters to capture building code modernization demand before local supply catches up. EVA substitution in photovoltaic applications threatens architectural share; counter through certified fire-resistant grade investments that EVA cannot match. For New Entrants and Emerging Players: Enter via India's urban high-rise construction corridor, where laminated safety glass adoption outpaces domestic interlayer capacity and import channels dominate. Target decorative glass segments with colored interlayer formulations that tolerate lower optical clarity and edge-trim recycled inputs. Pursue direct digital procurement relationships with Jiangsu province glass processors bypassing incumbent distributor networks. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale acoustic-grade specialists with proprietary multilayer constructions in Germany's Rhine-Ruhr corridor, where buyer consortiums have compressed distributor margins. Long-term viability centers on reformulation capabilities for REACH-compliant plasticizer packages as ECHA scrutiny tightens. Watch for carbon-border adjustment implementation as the inflection signal redirecting procurement toward regionally manufactured interlayers with verified lifecycle data.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyvinyl Alcohol | Captive resin supply secures cost advantages against feedstock volatility from Asian chemical conglomerates. |
| Multi-Site Manufacturing Expansion | Dual Japan-China presence anchors Asian supply security for automakers requiring geographic risk hedging. |
| Fire-Resistant Formulation Investment | EU Green Deal and Construction Products Regulation mandates create certified-grade demand in high-rise evacuation routes. |
| Platform-Based Direct Procurement | Digital channels capture mid-scale processor volume in China's Yangtze River Delta bypassing distributor tiers. |
| REACH-Compliant Plasticizer Reformulation | Bio-based chemistry investments preempt ECHA restriction proposals and downstream compliance liability for European processors. |
Study Parameters
Multi-period observation of interlayer thickness specifications, plasticizer cost indices, and automotive platform qualification timelines anchored the trend analysis, supplemented by interviews with resin plant managers, automotive glazing procurement leads, architectural glass fabricators, and distribution channel partners. Secondary validation drew from customs and trade data, SEC 10-K filings of integrated chemical producers, European Construction Products Regulation documentation, and China GB standards bulletins. Bottom-up volume builds across product grades and applications triangulated against top-down market sizing from resin production disclosures.
Input-output matrices mapped polyvinyl alcohol feedstock availability through extrusion capacity to end-use demand across automotive, architectural, safety, and decorative segments. Segmentation dimensions modeled include performance tier, application certification requirements, end-user procurement scale, and regional production hub. CAGRs were derived from elasticity-adjusted demand projections and capacity expansion schedules. Industry-specific inputs incorporated electric vehicle platform launch cadences and EU building code enforcement timelines.
Revisions become necessary when carbon-border adjustment mechanisms materialize, plasticizer feedstock markets experience sustained volatility, or EVA substitution accelerates in photovoltaic applications. Deviation in REACH chemical restriction finalization timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
MLCC Silicone Release Film Market
Specialty Materials
Flexible Colored Polyurethane (PU) Foams Market
Specialty Materials
Super Engineering Plastics Market
Specialty Materials
Dura Substitute Market
Specialty Materials
Polyetherimide (PEI) Market
Specialty Materials
Semiconductor O-Rings Market
Specialty Materials
Middle East and Africa Anti-Friction Coatings Market
Specialty Materials
EMI and RFI Shielding Materials Market
Specialty Materials
Cadmium Sulfide Market
Specialty Materials
Dysprosium Oxide Sputtering Target Market
Specialty Materials
Metallic Hot Stamping Foils Market
Specialty Materials
Glass Ionomer Cement Market
Specialty Materials
Eptfe in Spotlight-Poly-Vents Market
Specialty Materials
Adhesion Laminated Surface Protection Films Market
Specialty Materials
Latin America International CEP Market
Specialty Materials
Battery Separator Films Market