
 PCB Prepreg Material Market | 2026-2036
PCB Prepreg Material Market Size, Share, and Industry Trends Forecast 2026-2036
PCB Prepreg Material Market Insights
Taiwan is rewriting regional supply dynamics through dedicated prepreg capacity expansions serving advanced substrate fabrication. Shengyi Technology leverages vertical integration from resin synthesis to laminated sheet production, sustaining cost advantages across high-layer-count boards. Rogers Corporation anchors North American supply for high-frequency applications, competing on dielectric consistency in millimeter-wave radar substrates.
PCB prepreg material comprises resin-impregnated fiberglass fabric that cures under heat and pressure to bond copper-clad laminates into multilayer structures, with glass transition temperatures typically ranging from 130°C to 180°C for standard FR-4 grades and exceeding 200°C for high-performance variants. Its primary commercial purpose is to provide electrical insulation, dimensional stability, and interlayer adhesion in printed circuit board fabrication. FR-4 dominates volume production for consumer electronics and standard computing hardware, while polyimide prepreg commands premium positioning in aerospace and flexible circuit applications where thermal endurance exceeds standard epoxy capabilities. Ultra-thin prepreg layers below 50 micrometers represent the fastest-growing thickness category, driven by smartphone motherboard miniaturization and chiplet-based advanced packaging architectures.
China's NMPA and GB standards enforce halogen-free flame retardancy thresholds, while Taiwan's CNS certifications and the EU REACH framework restrict specific epoxy hardeners and brominated compounds. These regulations are forcing reformulation investments across resin suppliers and laminate manufacturers, elevating compliance costs for exporters serving multiple jurisdictions. Stakeholders must monitor evolving chemical restriction schedules and substrate recycling mandates to anticipate qualification timelines and raw material substitution cycles.
Market Dynamics
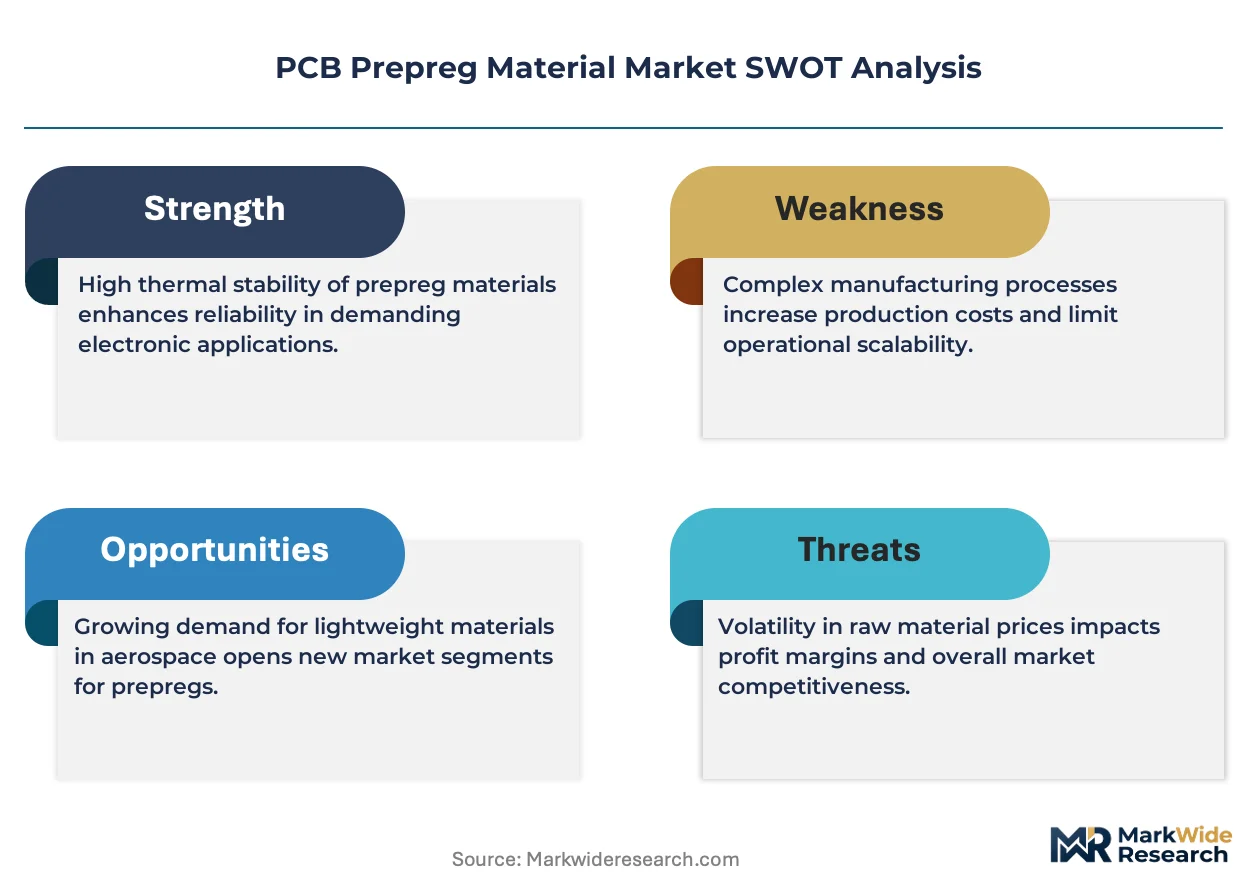
Advanced packaging architectures for chiplet-based processors are compressing prepreg thickness requirements below 50 micrometers, forcing resin suppliers to reformulate for dimensional stability at ultra-thin gauges without sacrificing thermal performance.
Growth Catalysts
- 5G Infrastructure Deployment:Millimeter-wave base station rollouts in telecommunications are consuming high-frequency low-loss prepreg grades for antenna-in-package modules.
- EU REACH Chemical Restrictions:Phasing of brominated flame retardants is accelerating halogen-free epoxy formulations across export-oriented laminate manufacturers.
- Chiplet Advanced Packaging:Heterogeneous integration architectures for AI accelerators are multiplying interposer layer counts and resin-impregnated fabric consumption per substrate.
Market Restraints
- Epoxy Resin Price Volatility:Bisphenol-A and epichlorohydrin feedstock costs swing with crude oil derivatives, compressing formulation margins for mid-tier suppliers.
- Taiwan Supply Concentration:Over 60% of high-layer-count prepreg capacity clusters in earthquake-prone regions, exposing electronics supply chains to single-point disruption.
- Glass Fiber Substitution Limits:Alternative reinforcements like aramid or quartz fabrics remain cost-prohibitive for volume consumer electronics applications.
Strategic Opportunities
- India Electronics Manufacturing:Production-linked incentive schemes for semiconductor packaging are attracting laminate investments to Gujarat and Tamil Nadu corridors.
- Automotive Radar Substrates:77-81 GHz millimeter-wave sensors for adaptive cruise control are specifying ultra-low Df resin systems outside standard FR-4 portfolios.
- Japan METI Carbon Neutrality Roadmap:Biomass-derived epoxy hardener mandates are creating first-mover advantages for bio-based prepreg qualification.
Industry Challenges
- Thin-Film Process Engineering Talent:Coating line operators capable of maintaining sub-50 micrometer resin uniformity across 1,270mm web widths remain scarce in emerging manufacturing regions.
- Multi-Jurisdiction Certification Timelines:Simultaneous UL, NMPA GB, and JIS qualification cycles for new halogen-free grades extend product launch windows by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PCB Prepreg Material Market |
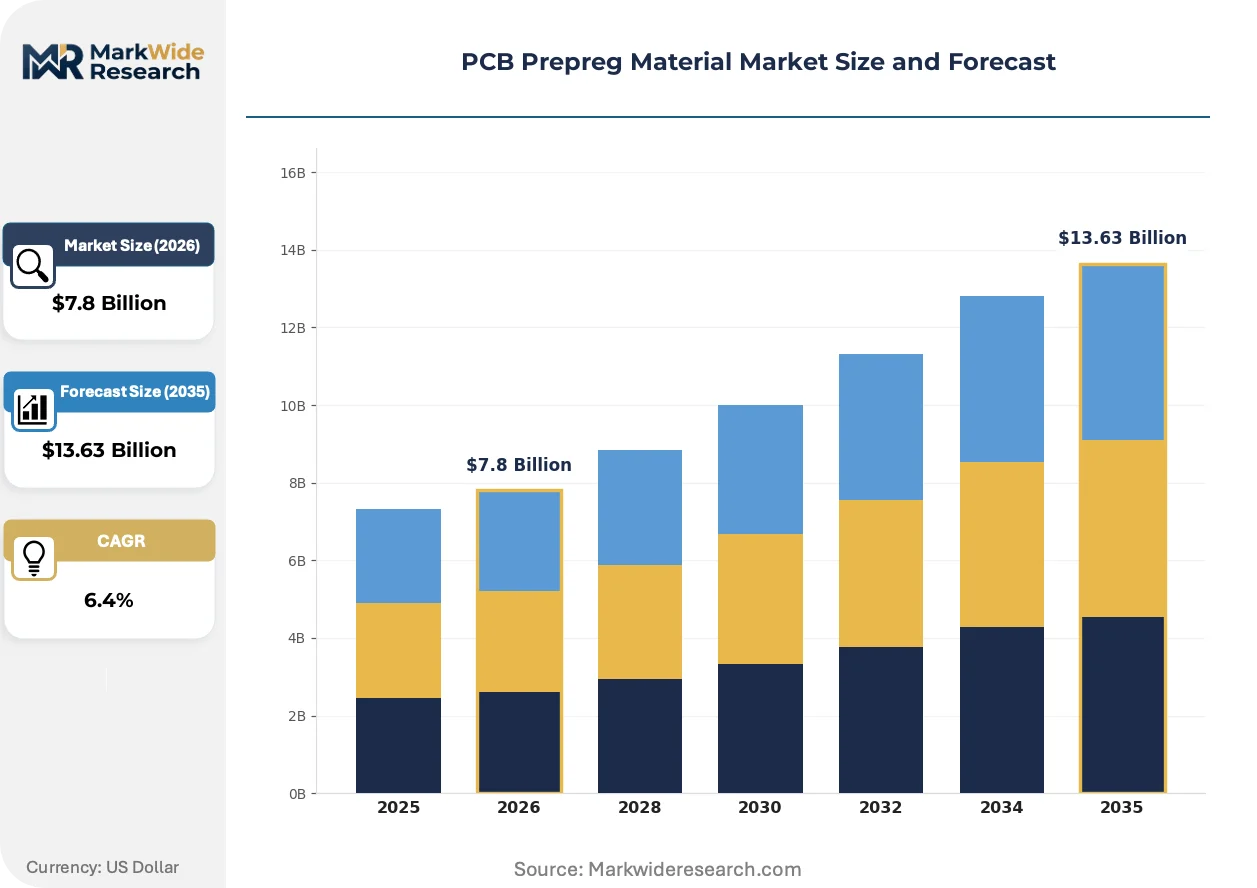
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.63 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: FR-4, Polyimide, PET, Epoxy Manufacturing Process: Hot Pressing, Cold Pressing, Vacuum Bagging, Filament Winding End User: Consumer Electronics, Automotive, Telecommunication, Aerospace Thickness: Thin, Medium, Thick, Ultra-Thin |
| Companies Covered | Elite Material Co. Ltd., Nanya New Material Tech, Taiwan Union Technology Corporation, Rogers Corporation, AGC, Shengyi Technology, ITEQ, Ventec International Group, Isola, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PCB Prepreg Material Market Trends and Innovations
Resin chemistry, reinforcement architecture, and process control systems are converging to enable sub-30 micrometer prepreg production for next-generation substrate miniaturization.
Low-dielectric thermoset resins incorporating hydrocarbon and cyanate ester chemistries are replacing conventional epoxy in high-speed digital substrates. Cloud infrastructure OEMs are qualifying these materials for 112 Gbps PAM4 signal integrity. This substitution is digitizing the material selection process for data center hardware designers.
China's GB/T 4725-2022 standard for printed board base materials tightened glass transition temperature and thermal decomposition thresholds for flame-retardant grades. Domestic laminate producers are accelerating high-Tg epoxy formulations to maintain access to state-funded 5G and supercomputing projects. Exporters serving both China and EU markets face diverging technical specifications requiring parallel product lines.
Substrate fabricators are consolidating procurement volumes with top-tier prepreg suppliers and bypassing regional distributors for direct mill relationships. This disintermediation concentrates price negotiation leverage with buyers possessing 10,000+ ton annual resin commitments. Taiwan's PCB corridor exhibits the most pronounced direct procurement behavior, with advanced packaging foundries qualifying suppliers at resin synthesis stage rather than finished prepreg stage.
PCB Prepreg Material Market Segmentation
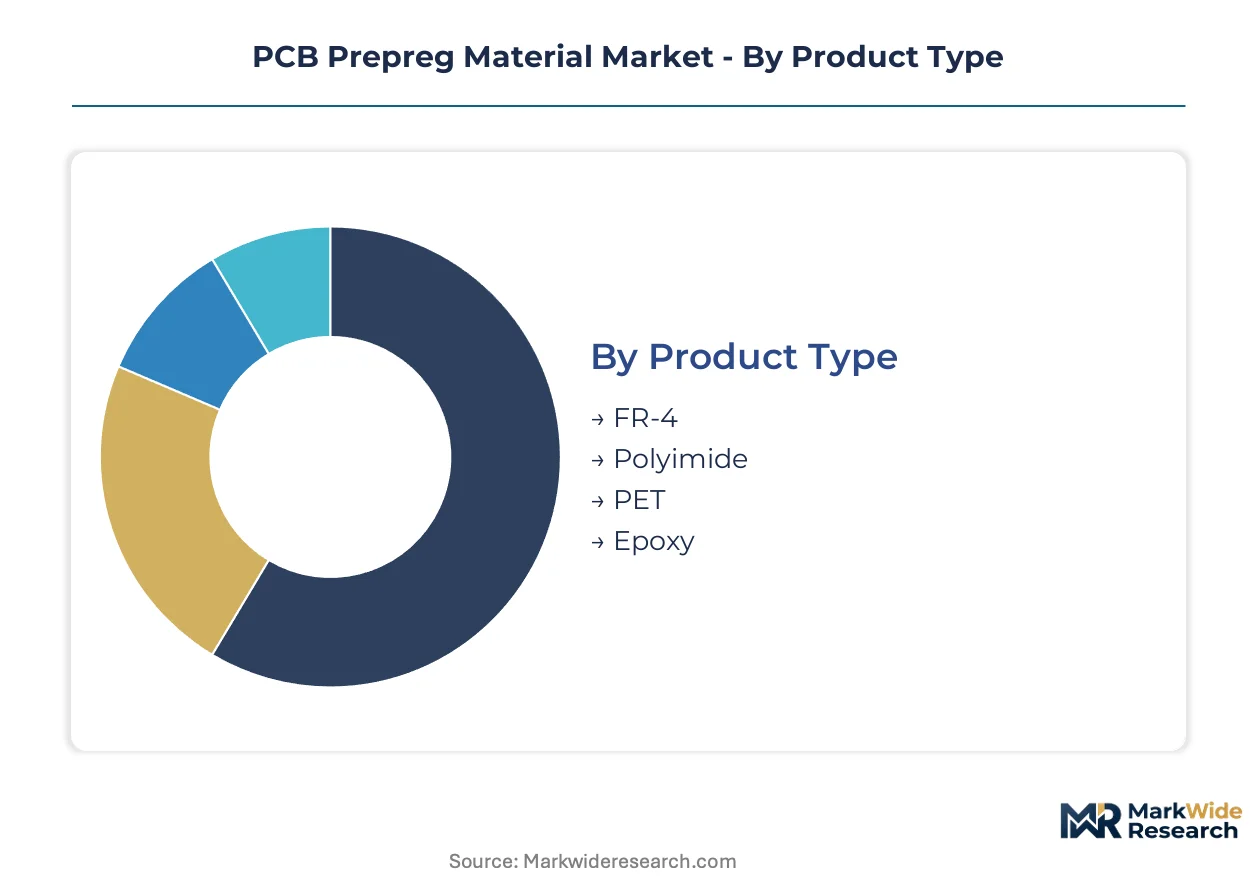
Prepreg specification diversity creates distinct supply chains where resin chemistry, reinforcement architecture, and thickness tolerances determine qualification pathways. Each segmentation dimension carries unique margin profiles and certification barriers that reshape procurement strategies across substrate fabricators.
Product Type:
Cost tier differentiation separates commodity epoxy formulations from premium high-temperature resin systems serving mission-critical applications.
- FR-4:Brominated epoxy-impregnated E-glass fabric dominates volume production with glass transition temperatures between 130°C and 180°C. Smartphone motherboard and standard server PCB demand in Taiwan and China consumes the majority of global FR-4 prepreg output, though halogen-free reformulation under EU REACH and China's GB standards is elevating qualification costs for export-oriented laminate manufacturers.
- Polyimide:Aromatic polymer chemistry delivers thermal endurance exceeding 300°C continuous operation without decomposition. Aerospace flexible circuit fabrication in the US and EU specifies polyimide prepreg for engine control modules and satellite systems where standard epoxy fails, with procurement volumes concentrated through defense contractor qualification programs.
- PET:Polyester resin systems offer cost-sensitive insulation for single-layer and double-layer consumer electronics boards with moderate thermal requirements.
- Epoxy:High-performance modified epoxy variants including cyanate ester and hydrocarbon blends target 112 Gbps signal integrity in data center infrastructure.
FR-4 commands the established base. The steepest expansion runs through high-performance epoxy variants displacing conventional formulations in telecommunications infrastructure.
Manufacturing Process:
Process technology maturity determines throughput rates, thickness uniformity, and capital intensity across prepreg coating operations.
- Hot Pressing:Thermal consolidation under controlled pressure and temperature remains the dominant multilayer lamination method for standard-thickness boards. Taiwan's PCB corridor relies on hot pressing for high-layer-count server motherboards, with process optimization focused on resin flow control to prevent void formation in buried via structures.
- Cold Pressing:Ambient temperature consolidation preserves dimensional stability in temperature-sensitive flexible substrates and ultra-thin gauge materials. Japanese manufacturers employ cold pressing for polyimide-based aerospace laminates where thermal excursion must be minimized to prevent copper foil stress cracking.
- Vacuum Bagging:Atmospheric pressure differential achieves uniform resin distribution in complex geometries and thick-section builds.
- Filament Winding:Automated fiber placement creates anisotropic reinforcement architectures for specialized RF substrate applications requiring controlled dielectric constant directionality.
Hot Pressing retains the volume anchor. Cold Pressing is gaining share fastest in flexible circuit and advanced packaging substrate segments.
End User:
Application-specific performance requirements drive divergent material specifications across terminal markets.
- Consumer Electronics:Smartphone, tablet, and wearable device manufacturers specify ultra-thin prepreg below 50 micrometers for motherboard miniaturization. China's domestic OEMs and Taiwan's contract manufacturers consume the majority of consumer-grade prepreg, with procurement patterns tied to annual flagship device release cycles.
- Automotive:77-81 GHz millimeter-wave radar substrates and battery management systems require ultra-low dissipation factor resin systems. German and Japanese automotive Tier-1 suppliers are qualifying halogen-free high-Tg grades for advanced driver-assistance systems under NHTSA and EU type approval frameworks.
- Telecommunication:5G base station antenna-in-package modules and optical transceivers specify low-loss prepreg for millimeter-wave frequency operation.
- Aerospace:Satellite and avionics applications demand polyimide and cyanate ester prepreg with outgassing certification per NASA and ESA standards.
Consumer Electronics holds the volume base. Automotive radar substrate demand is climbing the fastest as level-3 autonomy deployment accelerates.
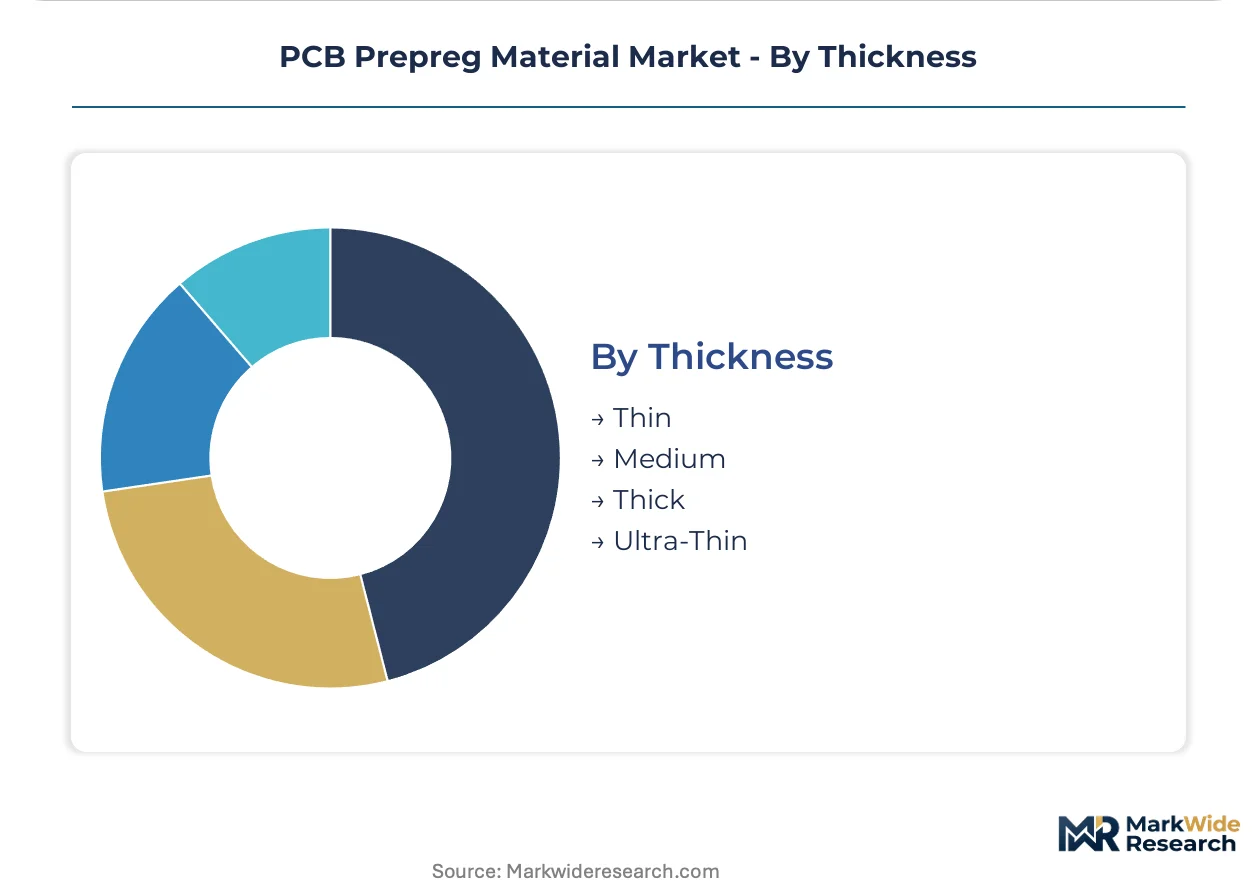
Thickness:
Gauge specification directly determines resin formulation viscosity, reinforcement architecture, and process control requirements.
- Ultra-Thin:Sub-50 micrometer prepreg layers enable chiplet-based advanced packaging and smartphone motherboard density maximization. Taiwan's advanced packaging foundries are driving ultra-thin qualification timelines, with resin suppliers reformulating for dimensional stability at gauges where conventional glass cloth architecture approaches mechanical limits.
- Thin:50-100 micrometer range serves standard multilayer consumer electronics and computing hardware with balanced cost-performance profiles.
- Medium:100-200 micrometer gauges dominate industrial and automotive control board applications requiring structural rigidity.
- Thick:Above 200 micrometer prepreg addresses power electronics, heavy copper designs, and backplane applications where thermal mass and mechanical strength predominate over miniaturization.
Medium thickness retains the installed base. Ultra-Thin is expanding most quickly as heterogeneous integration architectures multiply interposer layer counts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's NMPA and GB standards anchor the dominant geography, tightening flame-retardancy thresholds that reshape formulation requirements across East Asian manufacturing corridors. Taiwan's PCB corridor and South Korea's packaging foundries concentrate advanced substrate demand. India's PLI schemes and Japan's METI carbon mandates are redrawing investment patterns.
China
5G base station rollouts and supercomputing projects consume high-Tg epoxy formulations under GB/T 4725-2022 mandates. The NMPA enforces halogen-free flame retardancy for state-funded infrastructure procurement. Yangtze River Delta laminate producers are accelerating qualification timelines to maintain access to domestic 5G deployment contracts.
Taiwan
Advanced packaging foundries for AI accelerators drive ultra-thin prepreg qualification below 50 micrometers. CNS certifications govern substrate exports to EU and US markets. The PCB corridor from Taoyuan to Tainan concentrates over sixty percent of high-layer-count capacity, exposing supply chains to seismic disruption risks.
South Korea
Memory semiconductor packaging and smartphone motherboard miniaturization multiply interposer layer counts. The MFDS regulates chemical substances in electronics manufacturing under REACH-aligned frameworks. Seoul Capital Area substrate fabricators are consolidating direct mill relationships with top-tier resin suppliers.
Japan
Automotive radar substrates at 77-81 GHz specify ultra-low dissipation factor resin systems. METI's carbon neutrality roadmap mandates biomass-derived epoxy hardeners for qualification advantages. Chubu region automotive Tier-1 suppliers are qualifying halogen-free high-Tg grades under NHTSA and EU type approval frameworks.
United States
Aerospace flexible circuits and satellite systems demand polyimide prepreg with NASA outgassing certification. The EPA regulates brominated flame retardant phase-out under TSCA Section 6. Southern California and Arizona defense contractor clusters concentrate procurement through qualification programs for engine control modules.
PCB Prepreg Material Market Competitive Landscape
Vertically integrated resin-to-laminate producers and specialized high-frequency material suppliers split the market along performance-tier lines. The vendor base concentrates around East Asian manufacturing clusters, with North American and European players occupying niche high-value segments. Three archetypes dominate: captive resin synthesis operations, independent laminate specialists, and RF-focused dielectric engineers. Capacity expansion in India and Southeast Asia is accelerating, while qualification partnerships with advanced packaging foundries are consolidating procurement leverage.
Among Taiwan-based fabricators, Taiwan Union Technology Corporation and Elite Material Co. Ltd. exemplify the vertically integrated archetype controlling resin formulation through laminated sheet production. Rogers Corporation anchors North American supply for high-frequency applications, occupying a position defined by dielectric consistency in millimeter-wave radar substrates. Shengyi Technology represents the scale-driven Chinese competitor with backward integration into resin synthesis.
| Leading Market Players |
|---|
| Elite Material Co. Ltd. |
| Nanya New Material Tech |
| Taiwan Union Technology Corporation |
| Rogers Corporation |
| AGC |
| Shengyi Technology |
| ITEQ |
| Ventec International Group |
| Isola |
| Others |
Pricing and Supply Chain Analysis
Taiwan's PCB corridor from Taoyuan to Tainan concentrates over sixty percent of high-layer-count prepreg capacity, concentrating pricing leverage with substrate fabricators commanding 10,000-plus ton annual resin commitments. Direct mill relationships bypass regional distributors, compressing margins for mid-tier suppliers while premium high-frequency grades retain pricing power through dielectric consistency certification.
Pricing Analysis
Price spreads between Taiwan and China run 12-18 percent for equivalent FR-4 grades, reflecting CNS certification premiums and logistics differentials. Three-tier pricing structure across high-frequency, halogen-free, and standard brominated epoxy levels separates qualification tiers, with EU REACH compliance adding 8-12 percent to export-grade formulations. Cost compression in standard FR-4 intensifies as Yangtze River Delta producers expand output, while automotive radar substrate buyers show least price sensitivity due to NHTSA type approval lock-in effects.
Supply Chain Analysis
Export-control regimes limiting semiconductor packaging equipment flows to China are forcing substrate fabricators to dual-source prepreg across Taiwan, South Korea, and Japan. Bisphenol-A, epichlorohydrin, and E-glass fabric feedstock costs swing with crude oil derivatives, exposing formulation margins to commodity volatility. Single-source vulnerability concentrates in Taiwan's earthquake-prone corridor, where seismic disruption would cascade through AI accelerator and smartphone motherboard supply chains. Distribution runs through direct mill contracts with advanced packaging foundries rather than regional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward advanced packaging foundries consolidating procurement volumes, as Taiwan's substrate fabricators bypass distributors for direct resin synthesis relationships. This concentration demands defensive repositioning from incumbents and targeted white-space entry from challengers.
For Market Incumbents: Insulate margin structures by securing captive epoxy hardener supply through backward integration into resin synthesis, countering feedstock volatility that compresses formulation economics. Accelerate halogen-free qualification under simultaneous UL, NMPA GB, and JIS cycles to defend position against emerging Chinese competitors with state-funded 5G project access. Prioritize sub-50 micrometer coating line talent retention as ultra-thin prepreg qualification becomes the primary technical moat. For New Entrants and Emerging Players: Mid-market automotive radar substrate supply to German and Japanese Tier-1 suppliers represents the most penetrable entry point, as 77-81 GHz millimeter-wave sensor demand outpaces established high-frequency material capacity. India's Gujarat and Tamil Nadu semiconductor packaging corridors offer second-mover advantages under PLI schemes attracting laminate investments absent entrenched supplier relationships. Lead with bio-based epoxy hardener qualification under Japan METI carbon neutrality mandates to differentiate from incumbent petroleum-dependent formulations. For Investors and Strategic Acquirers: Long-term, this sits as a specialty-chemical consolidation play because resin-to-laminate vertical integration determines cost position across thickness tiers and certification levels. Target independent prepreg specialists with qualified sub-50 micrometer production capability and existing advanced packaging foundry relationships rather than commodity FR-4 producers facing margin compression. Monitor NMPA halogen-free mandate enforcement timelines as the inflection signal for Chinese domestic producer market share shifts versus export-oriented Taiwanese competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Synthesis | Captive epichlorohydrin supply locks in margin control against Bisphenol-A price swings. |
| Halogen-Free Formulation Qualification | Parallel UL, NMPA GB, and JIS certification opens EU, China, and Japan procurement channels simultaneously. |
| Ultra-Thin Coating Capacity Expansion | Sub-50 micrometer production capability qualifies suppliers for AI accelerator interposer layers at Taiwan foundries. |
| Direct Mill Relationship Development | Bypassing regional distributors concentrates 10,000-plus ton annual negotiation leverage with substrate fabricators. |
| Bio-Based Hardener R&D Investment | Japan METI carbon neutrality roadmap creates first-mover qualification advantages for biomass-derived epoxy systems. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs/trade data, SEC 10-K filings, and NMPA GB standard documentation to anchor volume estimates in observable production flows. Conversations with laminate plant managers, resin procurement leads at substrate fabricators, technical R&D directors at epoxy suppliers, and distribution channel partners in Taiwan and China provided operational validation. Bottom-up capacity modeling across coating line installations triangulates against top-down consumption estimates derived from PCB layer-count trends and smartphone motherboard unit forecasts.
Forecast inputs incorporate resin chemistry tier, end-use application, thickness specification, and regional manufacturing hub clustering across the projection horizon. Segmentation dimensions span FR-4, polyimide, high-performance epoxy, and PET product types; hot pressing, cold pressing, vacuum bagging, and filament winding processes; consumer electronics, automotive, telecommunications, and aerospace end users; and ultra-thin, thin, medium, and thickness categories. CAGRs derive from regression against historical layer-count multiplication rates in advanced packaging and 5G infrastructure deployment curves.
Practitioners should monitor NMPA enforcement intensity, Taiwan seismic event frequency, and epoxy feedstock price volatility for early signals of forecast deviation. Material shifts in China domestic substitution policy or EU REACH chemical restriction expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Hornbeam Market
Specialty Materials
UV Stabilized Films Market
Specialty Materials
Charge Generation Materials (CGM) Market
Specialty Materials
Global Polybenzimidazoles (PBI) Market
Specialty Materials
Metallic Hot Stamping Foils Market
Specialty Materials
Global Montan Wax Market
Specialty Materials
Asia Pacific Cellulose Acetate Market
Specialty Materials
Special Graphite Market
Specialty Materials
Melamine Foam Market
Specialty Materials
Nanocapsules Market
Specialty Materials
Polyphenylsulfone Market
Specialty Materials
Electrode Paste Market
Specialty Materials
Global PMMA Microspheres Market
Specialty Materials
South America Polyether Ether Ketone (Peek) Market
Specialty Materials
Methyl Silicone Market
Specialty Materials
Mica Sheet Market