
 Halloysite Market | 2026-2036
Halloysite Market Size, Share, and Industry Trends Forecast 2026-2036
Halloysite Market Analysis
The EU Green Deal's nanomaterial sustainability criteria is rebalancing procurement priorities across European industrial clay buyers. Imerys S.A. anchors its halloysite portfolio through captive deposits in France and New Zealand, sustaining long-term feedstock security for pharmaceutical-grade output. Applied Minerals Inc. dominates the North American supply base with its Dragon Mine operation in Utah, leveraging unique geological purity to compete in high-barrier coating applications. Nanoshel LLC specializes in nanotube functionalization, positioning its catalog for researchers in controlled-release and catalysis segments.
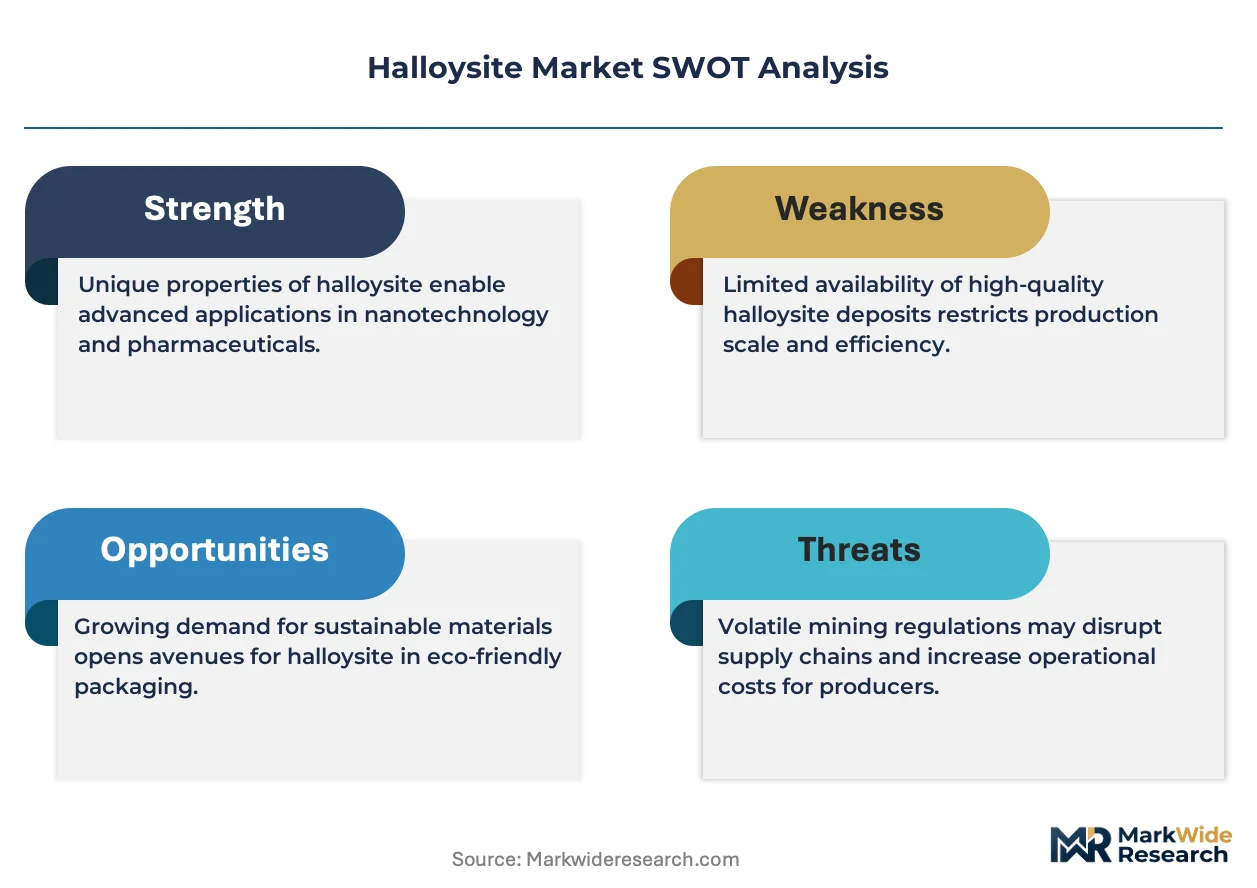
Halloysite is a naturally occurring aluminosilicate clay mineral with a distinctive hollow tubular morphology, typically measuring 1-15 micrometers in length and 10-150 nanometers in diameter, formed through the hydrothermal alteration of volcanic glass or feldspar-rich rocks. Its primary industrial purpose centers on serving as a functional additive where high aspect ratio, internal lumen volume, and surface reactivity deliver reinforcement, encapsulation, or controlled-release performance. Among product types, nanotubes command premium positioning due to their scarcity in natural deposits and the technical complexity of size-classification, while composite additives represent the volume base where processors blend halloysite with polymers and coatings to improve mechanical and barrier properties. The pharmaceutical application segment draws intensifying R&D investment as formulators exploit the mineral's biocompatible lumen structure for active ingredient encapsulation.
EPA oversight of nanoscale materials under the Toxic Substances Control Act shapes how American producers characterize and register halloysite products for commercial distribution. REACH requirements administered by ECHA mandate detailed nanomaterial registration dossiers that filter out under-documented imports into European formulation supply chains. China's GB standards for non-metallic mineral products, enforced by SAMR, establish purity benchmarks that domestic refiners must meet for pharmaceutical and electronics-grade certification. Stakeholders must monitor how evolving nanomaterial classification protocols across these jurisdictions reshape product registration costs and market access timelines.
Market Dynamics
Pharmaceutical formulators are pulling halloysite nanotubes into controlled-release drug delivery systems, creating a demand concentration that outpaces traditional ceramics and coatings applications. This end-use pivot is restructuring procurement priorities across the value chain.
Growth Catalysts
- REACH nanomaterial registration:ECHA's tightening purity disclosure thresholds are filtering out under-documented imports, creating premium positioning for compliant European suppliers.
- China's eastern ceramics corridor:Technical porcelain and advanced refractory producers in this cluster are refining high-grade halloysite, consolidating regional processing expertise.
- Controlled-release encapsulation:Formulation scientists exploit the mineral's biocompatible lumen structure for active ingredient delivery, driving specification intensity in pharmaceutical R&D pipelines.
Market Restraints
- Natural deposit scarcity:Nanotube-grade halloysite occurs in limited geological formations, concentrating upstream supply risk in Utah's Dragon Mine and select New Zealand deposits.
- Size-classification complexity:Technical separation of 10-150 nanometer diameter tubes requires capital-intensive processing, elevating unit economics for premium grades.
- Synthetic clay substitutes:Engineered aluminosilicate alternatives threaten to capture cost-sensitive polymer reinforcement applications where natural morphology is less critical.
Strategic Opportunities
- EU Green Deal nanomaterial criteria:Sustainability-aligned procurement mandates are rebalancing European industrial clay buyer priorities toward verified low-carbon feedstock sources.
- Catalysis research segments:Functionalized nanotube demand from academic and industrial catalysis programs represents an underdeveloped revenue stream beyond encapsulation.
- SAMR pharmaceutical-grade certification:China's GB standard benchmarks for non-metallic mineral products create compliance pathways for domestic refiners targeting electronics and medical applications.
Industry Challenges
- Nanotube functionalization expertise:Surface chemistry modification for specific drug-polymer compatibility requires scarce interdisciplinary talent spanning materials science and pharmaceutical formulation.
- EPA TSCA registration timelines:Nanoscale material characterization dossiers under Toxic Substances Control Act oversight extend commercial distribution approval cycles, compressing revenue realization windows.
- Cross-jurisdictional classification divergence:Inconsistent nanomaterial definitions between EPA, ECHA, and SAMR force redundant testing protocols, inflating compliance overhead for multi-market suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Halloysite Market |
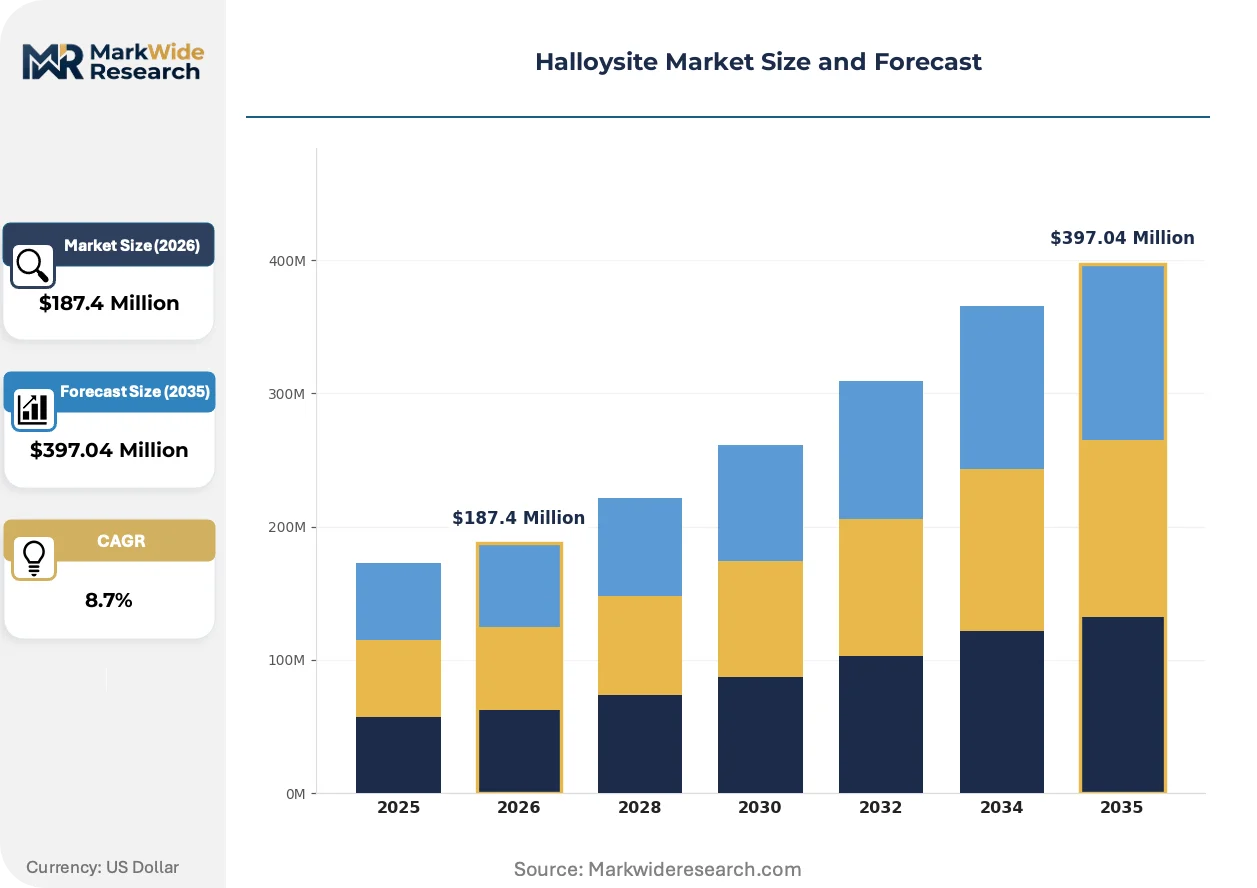
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alumina Silicate, High Purity, Nanotubes, Composite Additives Application: Plastics, Ceramics, Pharmaceuticals, Coatings End Use Industry: Adhesives, Cosmetics, Construction, Electronics Packaging Type: Bulk Bags, Pails, Drums, Sachets |
| Companies Covered | Applied Minerals Inc., Imerys S.A., I-Minerals Inc., Merck KGaA, Nanoshel LLC, Northstar Clay Mines LLC, Otto Chemie Pvt. Ltd., American Elements, Esan, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Halloysite Market Emerging Trajectories
Surface functionalization chemistry is overtaking raw material extraction as the primary value creation layer, with specialized modification protocols commanding premium positioning in pharmaceutical and catalysis segments.
Plasma-assisted surface modification is overtaking conventional wet-chemical functionalization for halloysite nanotubes. Pharmaceutical contract manufacturers in North America and Europe are adopting this dry-process technology to achieve precise lumen chemistry control. The shift is overtaking established solvent-based methods by eliminating aqueous waste streams and enabling tighter batch-to-batch consistency for GMP-compliant production.
REACH registration dossiers administered by ECHA now mandate granular nanomaterial characterization data that exceeds prior aggregate substance thresholds. European formulation supply chains are restructuring procurement relationships to exclude imports lacking compliant documentation. Pharmaceutical-grade halloysite suppliers with pre-existing registration portfolios are capturing specification lock-in as buyer qualification timelines extend.
Specification-driven purchasing is displacing commodity spot-buying in pharmaceutical encapsulation applications. Formulators now require certificate-of-analysis packages tracing tube morphology, surface area, and heavy metal content to batch level. This behavioral shift concentrates supplier relationships among three to five qualified vendors per major pharmaceutical cluster, with qualification costs creating switching friction that favors incumbent relationships.
Halloysite Market Segmentation
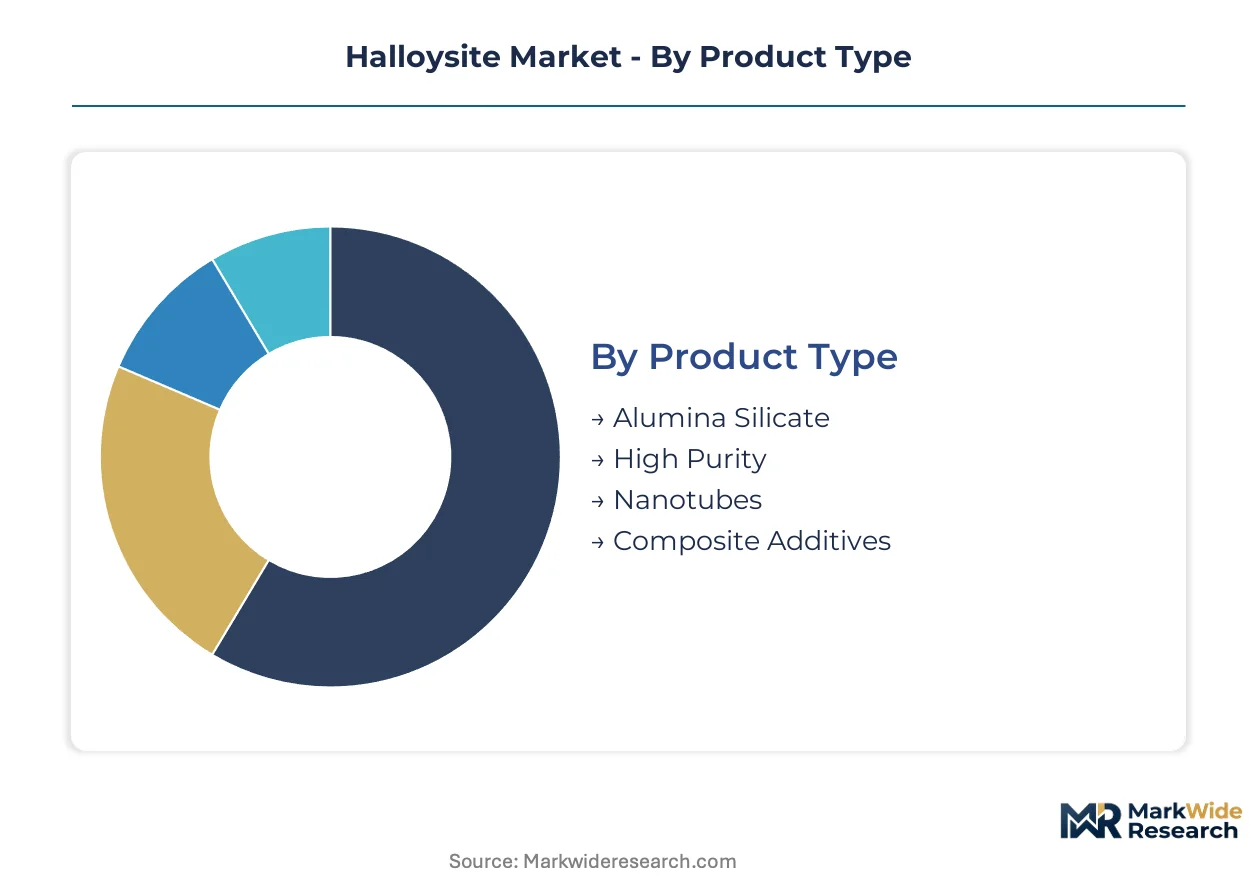
Halloysite's tubular morphology creates natural performance tiers that segment procurement behavior. Buyers sort by purity thresholds and aspect ratio specifications that determine functional value in encapsulation and reinforcement applications.
Product Type:
Volume concentrates in commodity aluminosilicate grades while premium pricing attaches to morphology-controlled nanotube classifications.
- Nanotubes:Hollow cylindrical structures measuring 10-150 nanometers in diameter deliver high aspect ratios for controlled-release pharmaceutical encapsulation. Specification intensity concentrates in North American and European formulation labs where FDA and EMA submission pathways require batch-level morphology certification. Supply scarcity in natural deposits elevates unit economics and concentrates procurement among qualified vendors.
- Composite Additives:Blended halloysite grades serve polymer reinforcement and barrier coating applications where aspect ratio tolerance is wider. Demand clusters in China's eastern ceramics corridor and US Gulf Coast petrochemical complexes where processors integrate functional fillers into high-volume extrusion and coating lines.
- High Purity:Refined grades meeting pharmaceutical and electronics contamination thresholds command certification premiums.
- Alumina Silicate:Base mineral composition represents the foundational feedstock for downstream refinement and functionalization.
Mature deployment sits with composite additives. Newer deployment is concentrated in nanotube functionalization for drug delivery systems.
Application:
Customer type separates specification-driven pharmaceutical buyers from cost-sensitive industrial processors.
- Pharmaceuticals:Formulators exploit biocompatible lumen structures for active ingredient encapsulation in controlled-release tablets and injectables. FDA and EMA nanomaterial characterization requirements extend supplier qualification timelines, creating relationship lock-in among three to five qualified vendors per major cluster.
- Plastics:Polymer compounders blend halloysite into thermoplastics and thermosets to improve tensile strength and thermal stability. Demand concentrates in automotive underhood components and packaging films where mineral reinforcement reduces petroleum-derived resin loading.
- Ceramics:Technical porcelain and advanced refractory producers in China's Jiangsu and Zhejiang provinces refine high-grade halloysite for kiln furniture and electronic substrate applications.
- Coatings:High-barrier film and corrosion-resistant coating formulators leverage platelet alignment for oxygen and moisture resistance.
Procurement maturity is highest in ceramics. The steepest expansion trajectory belongs to pharmaceutical encapsulation.
End Use Industry:
Margin structure separates premium cosmetic and electronics grades from construction commodity tiers.
- Electronics:Printed circuit board substrates and semiconductor packaging materials require ultra-low alkali content and controlled particle size distribution. Japanese and South Korean fabricators specify halloysite for high-frequency dielectric applications where thermal expansion matching is critical.
- Cosmetics:Skincare and color cosmetic formulators incorporate halloysite for texture modification and active ingredient delivery. European Union REACH nanomaterial registration requirements filter out under-documented imports, creating premium positioning for compliant suppliers.
- Adhesives:Structural and pressure-sensitive adhesive compounders use halloysite for rheology control and reinforcement.
- Construction:Cement and concrete admixture producers blend halloysite for workability enhancement and crack resistance in high-performance formulations.
Established supply relationships dominate construction. Emerging specification intensity is concentrated in electronics-grade certification programs.
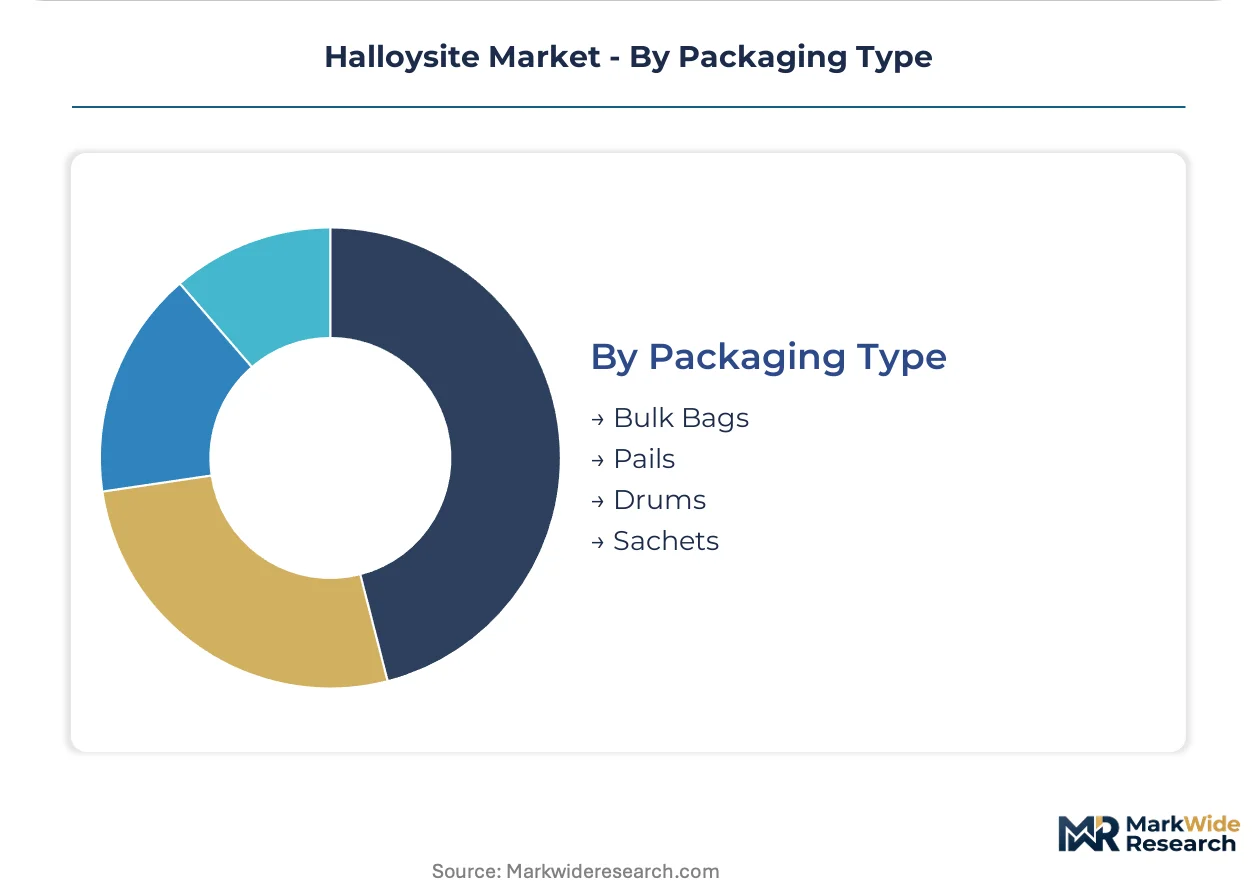
Packaging Type:
Supply chain configuration matches containment requirements to handling economics across volume tiers.
- Bulk Bags:One-ton flexible intermediate bulk containers serve high-volume ceramic and construction processors in China's eastern provinces and US Midwest manufacturing clusters. Rail and bulk truck logistics minimize per-kilogram handling costs for commodity-grade shipments.
- Drums:Steel and fiber drums provide moisture protection and contamination control for pharmaceutical and electronics-grade material. GMP-compliant facilities in New Jersey, Basel, and Shanghai require sealed drum integrity with certificate-of-analysis documentation.
- Pails:Smaller rigid containers serve mid-volume specialty compounders and research-scale buyers.
- Sachets:Pre-weighed aluminum and polymer pouches support laboratory and pilot-scale formulation work.
Volume concentration sits with bulk bags. Precision handling requirements are driving specification growth in drum configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's eastern ceramics corridor, spanning Jiangsu and Zhejiang provinces, concentrates the world's most sophisticated halloysite refining capacity for technical porcelain and advanced refractories.
United States
Pharmaceutical formulators in New Jersey and Massachusetts drive specification intensity for controlled-release encapsulation. EPA nanomaterial oversight under the Toxic Substances Control Act extends registration timelines and concentrates qualified supplier relationships. Utah's Dragon Mine anchors North American feedstock security for high-barrier coating and drug delivery applications.
China
Technical porcelain producers and advanced refractory fabricators in the Yangtze River Delta pull refined halloysite for kiln furniture and electronic substrates. SAMR enforces GB standards for non-metallic mineral purity benchmarks that domestic refiners must meet for pharmaceutical-grade certification. Jiangsu province hosts the densest concentration of halloysite processing infrastructure serving ceramics and electronics supply chains.
France
Cosmetic and pharmaceutical compounders in the Île-de-France region specify halloysite for texture modification and active ingredient delivery systems. REACH nanomaterial registration dossiers administered by ECHA filter out under-documented imports and reward compliant European suppliers. Captive deposits in the Massif Central sustain long-term feedstock security for pharmaceutical-grade output.
Germany
Polymer compounders in North Rhine-Westphalia integrate halloysite into automotive underhood components and high-barrier packaging films. EU Green Deal nanomaterial sustainability criteria rebalancing procurement priorities toward verified low-carbon feedstock sources. The Cologne-Düsseldorf industrial corridor hosts formulation labs driving specification intensity for electronics-grade certification programs.
New Zealand
Specialized nanotube exporters serve North American and European pharmaceutical R&D pipelines from processing facilities near Matauri Bay. The country's national mineral regulator maintains disclosure thresholds for nanomaterial exports that align with ECHA and EPA requirements. Northland region deposits provide geological purity that competes in premium encapsulation and catalysis research segments.
Halloysite Market Vendor Landscape
The competitive structure tilts toward integrated mineral owners with captive geological assets. Upstream concentration in natural nanotube-grade deposits creates supply scarcity that rewards long-term feedstock security. Two strategic archetypes dominate: integrated miners with direct geological control and functionalization specialists commanding premium positioning in pharmaceutical segments. Capacity expansion and strategic partnerships represent the dominant competitive moves as players secure downstream qualification relationships.
Among North American integrated miners, Applied Minerals Inc. exemplifies the geological-asset archetype through its Utah-based operations. Imerys S.A. occupies a position representing European integrated supply security with French and New Zealand deposit control. Nanoshel LLC sits within the functionalization specialist tier, occupying a position in nanotube modification for research and pharmaceutical applications.
| Leading Market Players |
|---|
| Applied Minerals Inc. |
| Imerys S.A. |
| I-Minerals Inc. |
| Merck KGaA |
| Nanoshel LLC |
| Northstar Clay Mines LLC |
| Otto Chemie Pvt. Ltd. |
| American Elements |
| Esan |
| Others |
Supply Flow & Price Mechanics
Energy and logistics costs at Utah's Dragon Mine flow downstream through three distinct pricing tiers for pharmaceutical-grade nanotubes, standard composite additives, and unrefined aluminosilicate feedstock. Buyers in New Jersey formulation labs absorb premium positioning tied to batch-level morphology certification, while China's ceramics corridor negotiates volume-driven contracts for kiln furniture applications.
Pricing Analysis
Yield-linked pricing for controlled-release encapsulation separates pharmaceutical-grade nanotubes from commodity tiers. Certification level—specifically ECHA REACH dossier completeness and FDA Drug Master File status—drives the widest price spreads. Cost compression in standard composite grades intensifies as synthetic aluminosilicate substitutes enter polymer reinforcement applications. Industrial ceramic processors exhibit highest price sensitivity; pharmaceutical formulators show lowest, locked in by qualification timelines and supplier relationship friction.
Supply Chain Analysis
Refurbishment flows for pharmaceutical drum packaging create circular material loops between New Jersey, Basel, and Shanghai GMP facilities. Upstream extraction concentrates in the United States, New Zealand, and France where geological purity supports premium output. Processing draws from volcanic glass deposits, hydrothermal alteration expertise, and nanotube size-classification capital equipment. Single-source vulnerability runs through Utah's Dragon Mine for North American pharmaceutical feedstock. Distribution runs through qualified vendor networks with certificate-of-analysis documentation rather than spot markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The halloysite market functions as a cost-of-compliance story where ECHA REACH nanomaterial registration dossiers erect barrier-to-entry moats favoring incumbents with pre-existing documentation portfolios.
For Market Incumbents: Deploy captive deposit control to secure upstream feedstock against synthetic substitute encroachment. Applied Minerals and Imerys S.A. anchor positioning through Utah and Massif Central geological assets. Surface functionalization chemistry investment protects margin structure as raw material extraction commoditizes. EMA nanomaterial characterization requirements extend relationship lock-in with qualified pharmaceutical formulators. For New Entrants and Emerging Players: The premium-to-economy price gap in pharmaceutical nanotubes opens white-space at mid-tier composite additive positioning. Catalysis research segments remain underpenetrated by specialized functionalization suppliers. China's SAMR pharmaceutical-grade certification pathway offers compliance leverage for domestic refiners targeting electronics applications. Partner with academic labs for specification development before commercial scale-up. For Investors and Strategic Acquirers: Plasma-assisted surface modification adoption by North American contract manufacturers is the leading indicator that dry-process functionalization will displace solvent-based methods. Long-term viability centers on integrated miners with geological control plus functionalization specialists with GMP-compliant modification protocols. Monitor ECHA registration portfolio expansions as inflection signals for specification lock-in capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Deposits | Secures geological purity for pharmaceutical-grade output against synthetic substitute threats. |
| Plasma-Assisted Surface Modification Scale-Up | Eliminates aqueous waste streams for GMP-compliant pharmaceutical production. |
| ECHA REACH Dossier Expansion | Filters under-documented imports and rewards compliant European suppliers with specification lock-in. |
| SAMR Pharmaceutical-Grade Certification | Creates compliance pathways for Chinese refiners targeting medical and electronics applications. |
| Academic Catalysis Research Partnerships | Develops functionalized nanotube demand beyond encapsulation into underdeveloped revenue streams. |
Methodological Framework
Multi-period observation of ECHA registration timelines, SAMR certification pathways, and EPA TSCA approval cycles anchored the trend analysis, supplemented by interviews with pharmaceutical formulation scientists, ceramic plant managers, polymer procurement leads, and nanotube functionalization specialists. Secondary validation drew from ECHA registration databases, FDA Drug Master File listings, Chinese customs trade data, and SEC 10-K filings of integrated mineral owners. Bottom-up demand modeling across application segments triangulated against top-down supply capacity assessments.
Segment-weighting applied morphology grade, end-use industry, and regional regulatory cluster dimensions across the projection horizon. CAGRs were derived from installation base expansion in controlled-release drug delivery, technical porcelain output in Jiangsu province, and barrier coating adoption in automotive underhood components. Forecast inputs incorporated REACH dossier completion rates and plasma-assisted processing equipment deployment patterns.
Inputs from ECHA registration portals and SAMR certification records were available through the study window; gaps in private company functionalization capacity data introduce uncertainty bands around nanotube supply forecasts. Practitioners should monitor EMA nanomaterial guidance document revisions and EPA TSCA Section 5 notice volumes for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Sheath Materials Market
Specialty Materials
Asia-Pacific Reflective Tape Market
Specialty Materials
Europe Green Sic Market
Specialty Materials
Alginate Films Market
Specialty Materials
Metalized Biaxially Oriented Polypropylene Films Market
Specialty Materials
Fumed Silica Market
Specialty Materials
Recyclable Thermosets Market
Specialty Materials
Latin America International CEP Market
Specialty Materials
Flexible Colored Polyurethane (PU) Foams Market
Specialty Materials
Erbium-169 Market
Specialty Materials
Conductive Carbon Black Market
Specialty Materials
Electrode Paste Market
Specialty Materials
Light Diffusion Materials Market
Specialty Materials
Hydrolysis Stable Polyester Films Market
Specialty Materials
UK Lab-Grown Diamonds Market
Specialty Materials
Crusher Backing Materials Market