
 Ball Bearing Market | 2026-2036
Ball Bearing Market Size, Share, and Industry Trends Forecast 2026-2036
Ball Bearing Market Intelligence
High-performance ceramic bearing development is reshaping competitive positioning among manufacturers, creating new value in applications like electric vehicles. SKF Group leverages its extensive industrial and automotive channel access to deploy these advanced solutions. Schaeffler Group specializes in integrated systems for e-mobility and industrial automation. JTEKT Corporation competes through its broad portfolio catering to both automotive and heavy machinery sectors, focusing on reliability and cost-efficiency.
A ball bearing is a rolling-element bearing that uses balls to maintain separation between the bearing races. These components are primarily designed to reduce rotational friction and support both radial and axial loads in mechanical systems. The most common product type, deep groove ball bearings, represents a mature, high-volume category. However, ceramic hybrid bearings are gaining significant traction, especially for high-speed electric motor and machine tool applications where electrical insulation and lower friction are critical.
International Organization for Standardization (ISO) standards dictate the dimensional and quality specifications for ball bearings, ensuring global interoperability. In the automotive sector, regulations from bodies like the US National Highway Traffic Safety Administration (NHTSA) and related European agencies indirectly influence bearing design for safety-critical applications. The selection between traditional chrome steel and advanced ceramic materials will increasingly define the cost, performance, and reliability trade-offs for end-users.
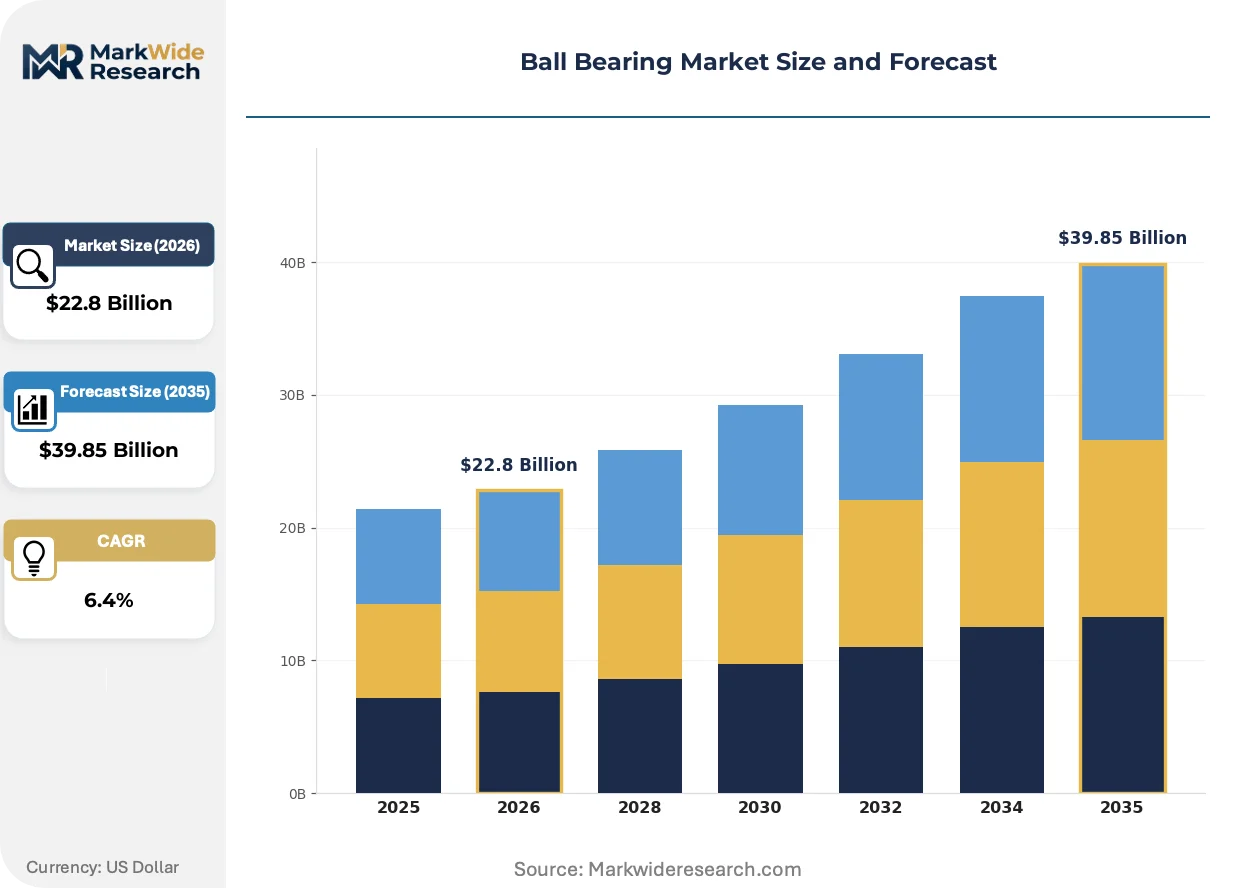
Market Dynamics
The electrification of transportation and industrial machinery is the central force defining the ball bearing market. Demand for higher efficiency, speed, and thermal management in electric motors and drivetrains necessitates a fundamental shift away from commodity steel bearings toward advanced material solutions.
Growth Catalysts
- Electric Vehicle Expansion:The global build-out of electric vehicle production, especially in manufacturing centers like China, creates substantial volume demand for specialized bearings capable of handling high rotational speeds and preventing electrical arcing.
- Renewable Energy Mandates:Policies such as the EU Green Deal and incentives in the US Inflation Reduction Act accelerate the deployment of wind turbines and solar trackers, both of which rely on large-diameter, high-load ball bearings for reliable operation.
- Advanced Material Adoption:The performance benefits of ceramic and hybrid bearings in reducing friction, weight, and heat are driving their adoption in high-value sectors, including aerospace, machine tools, and motorsports, creating new premium segments.
Market Restraints
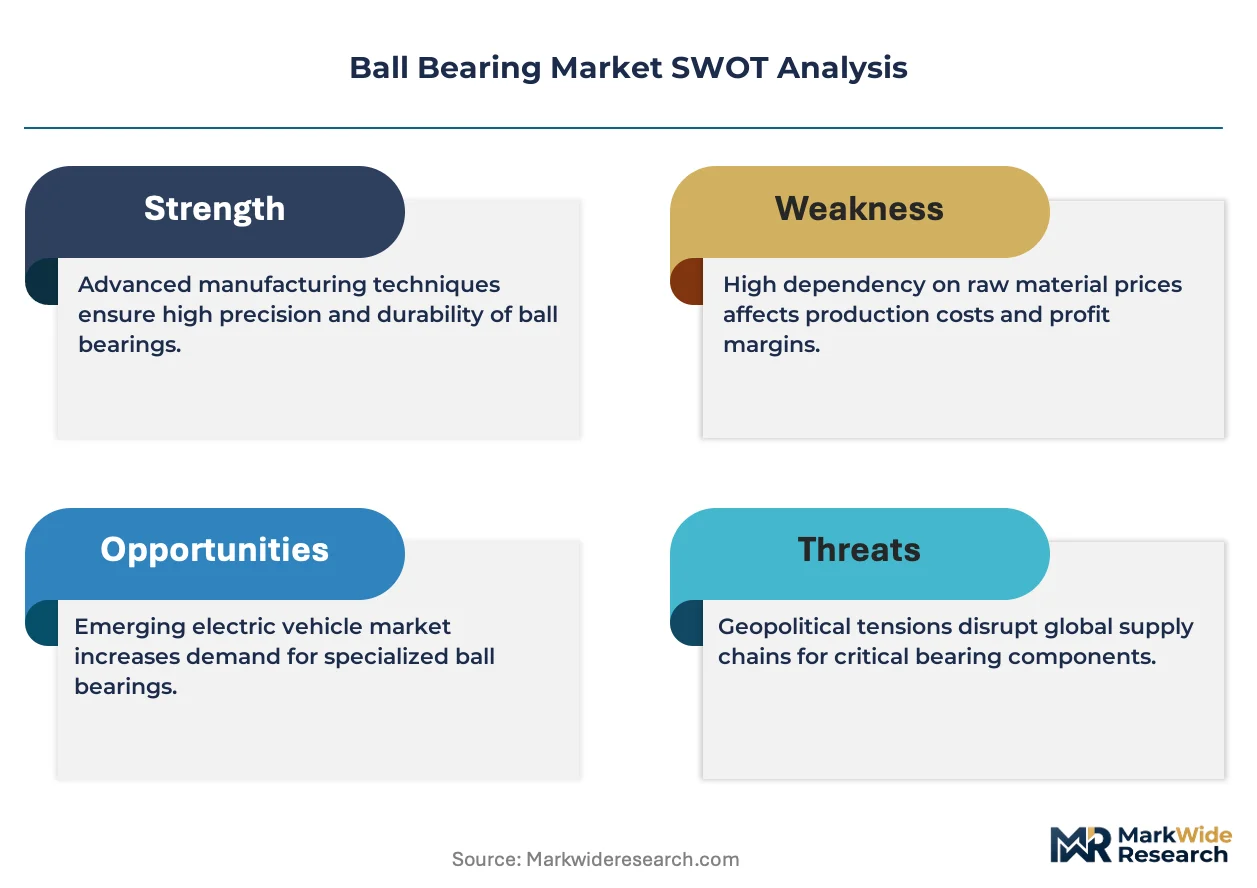
- Raw Material Price Volatility:Fluctuations in the cost of high-purity chrome steel and specialty alloys, key inputs for standard and high-performance bearings, directly impact manufacturer margins and create pricing instability for end-users.
- Technical Limits of Ceramics:While offering superior speed and insulation, full ceramic bearings exhibit lower fracture toughness and shock load capacity compared to steel, restricting their use in heavy-duty applications like mining and construction equipment.
- Substitution from Alternative Technologies:In niche, ultra-high-speed or contaminant-free environments, non-contact solutions like magnetic bearings pose a long-term substitution threat, bypassing the need for traditional rolling-element components entirely.
Strategic Opportunities
- Sensor Integration for IIoT:Embedding sensors directly into bearing assemblies to create "smart bearings" opens new revenue streams from predictive maintenance services, catering to Industry 4.0 demand in automated factories and processing plants.
- Manufacturing Diversification:Establishing production and supply chain hubs in emerging manufacturing economies in Southeast Asia, such as Vietnam and Thailand, offers a strategic alternative to geographic concentration and mitigates supply chain risks.
- Medical and Laboratory Equipment:The growing need for miniature, high-precision, and corrosion-resistant bearings in surgical robots, diagnostic equipment, and laboratory centrifuges presents a high-margin growth vector for specialized manufacturers.
Industry Challenges
- Stringent Aerospace Certification:The lengthy and capital-intensive process of achieving and maintaining certifications for safety-critical aerospace applications creates significant barriers to entry and slows the introduction of new material innovations. *Precision Manufacturing Workforce: A persistent shortage of skilled technicians and engineers with expertise in tribology, metallurgy, and precision grinding constrains the production scale-up of next-generation, high-tolerance bearing products.
- Counterfeit Component Proliferation:The infiltration of low-quality, uncertified counterfeit bearings into industrial and automotive aftermarkets poses a significant risk to equipment reliability, brand reputation, and end-user safety.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ball Bearing Market |
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $39.85 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Deep Groove Ball, Angular Contact, Self-aligning, Thrust, Ceramic Hybrid Material: Chrome Steel, Stainless Steel, Plastic, Ceramic, Brass Application: Electric Motors, Aerospace Equipment, Machine Tools, Wind Turbines, Conveyors End User Industry: Industrial Manufacturing, Renewable Energy, Transportation, Consumer Electronics, Heavy Machinery |
| Companies Covered | Timken Company, JTEKT Corporation, SKF Group, Luoyang LYC Bearing Co., Ltd., NACHI-Fujikoshi Corp., NSK Ltd., Schaeffler Group, Wafangdian Bearing Group Corporation, NTN Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ball Bearing Market Strategic Shifts & Innovations
The evolution of ball bearings from simple mechanical components to integrated mechatronic systems is the dominant theme. This shift is driven by end-user demands for data-driven operational intelligence, higher system-level efficiency, and application-specific performance that commodity products cannot deliver.
Smart bearing technology, which embeds micro-sensors for monitoring vibration, temperature, and load, is a key innovation. Industrial automation and wind energy operators are adopting these components to enable predictive maintenance strategies. This technology is digitizing the entire asset lifecycle management process, moving it from a reactive repair model to a proactive, condition-based framework.
Global standards from the International Organization for Standardization (ISO) continue to govern the dimensional and quality specifications, ensuring worldwide interoperability. These standards provide a baseline that is being elevated by sector-specific safety requirements from bodies like the US NHTSA and Germany's KBA. The automotive sector, in particular, is pushing for tighter manufacturing tolerances and enhanced material traceability in response to these safety mandates.
End-user purchasing behavior is moving toward the acquisition of integrated subsystems over discrete components. Original equipment manufacturers in e-mobility and robotics now frequently source complete bearing units that include seals, encoders, and housings from a single supplier. This trend is most visible in European industrial markets, disrupting traditional distributor channels and favoring suppliers with deep system engineering capabilities.
Ball Bearing Market Segmentation
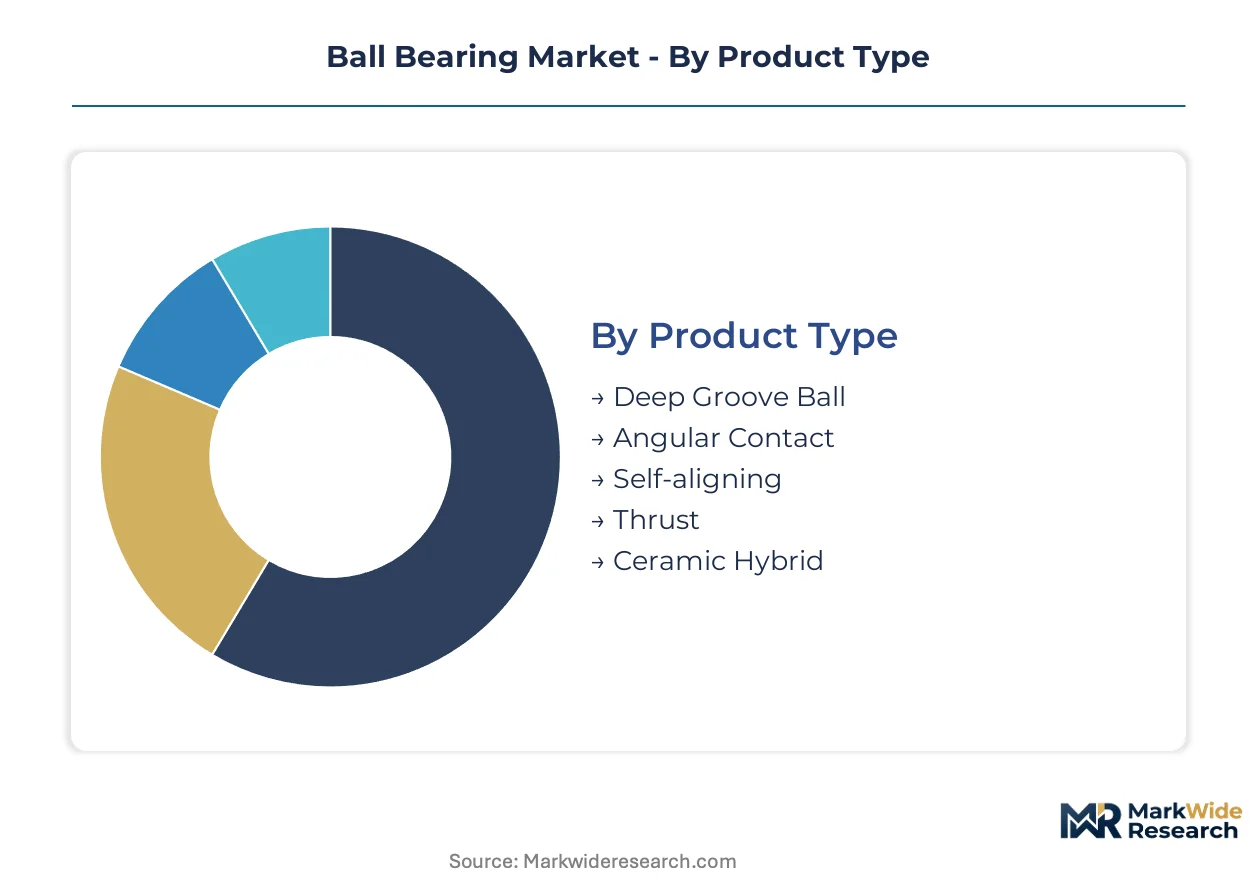
The ball bearing market's structure reflects diverse performance requirements and application lifecycles across various industrial sectors. Understanding these segmentations reveals where innovation is concentrated and where established product lines maintain volume stability.
Product Type:
Product types within the ball bearing market exhibit varying development cycles, from mature designs with long adoption histories to rapidly evolving high-performance solutions. This differentiation impacts manufacturing complexity and market entry barriers for new participants.
- Deep Groove Ball:These versatile bearings feature raceway grooves with radii slightly larger than the balls, allowing for both radial and axial loads. Demand remains consistently high in general industrial machinery and automotive components due to their cost-effectiveness and widespread availability.
- Ceramic Hybrid:Comprising steel rings and ceramic balls, these bearings offer superior speed, electrical insulation, and reduced friction. Adoption is rapidly expanding in electric vehicle drivetrains and high-speed machine tools, particularly in manufacturing hubs like China and Germany.
- Angular Contact:Designed to accommodate both radial and axial loads, these bearings are often used in pairs or sets for precise shaft guidance. Applications include pumps, compressors, and automotive transmissions, where stiffness is critical.
- Self-aligning:Featuring two rows of balls and a common spherical raceway in the outer ring, these bearings compensate for angular misalignment. They are commonly found in agricultural machinery and textile equipment, tolerating shaft deflections.
- Thrust:Primarily designed to handle axial loads, these bearings prevent axial displacement of shafts. They see use in rotary tables, gearboxes, and automotive steering systems, where axial forces are predominant.
Deep Groove Ball bearings anchor the market's volume base, while Ceramic Hybrid bearings gain share at the steepest rate due to electrification trends.
Material:
Material choices for ball bearings directly influence their operational parameters, including load capacity, corrosion resistance, and thermal stability, dictating their suitability for specific cost and performance tiers. Manufacturers balance raw material costs with application demands.
- Chrome Steel:This traditional material, typically AISI 52100, offers high hardness and wear resistance, making it suitable for most general industrial and automotive applications. Its widespread use ensures cost-efficiency and established manufacturing processes.
- Ceramic:Primarily silicon nitride (Si3N4) or zirconium dioxide (ZrO2), these materials provide excellent hardness, low density, and non-magnetic properties. Their adoption is increasing in high-speed spindles and medical equipment, where precision and electrical insulation are paramount.
- Stainless Steel:Offering superior corrosion resistance compared to chrome steel, this material is preferred in environments exposed to moisture or chemicals. Applications include food processing machinery and marine equipment, where hygiene and durability are essential.
- Plastic:Lightweight and corrosion-resistant, plastic bearings are often used in low-load, low-speed applications where lubrication is difficult or contamination is a concern. Consumer electronics and office equipment frequently incorporate these components.
- Brass:Employed for cages in certain bearing designs, brass offers good machinability and anti-friction properties. It is often selected for its non-sparking characteristics in specific industrial settings.
Chrome Steel remains the foundational material, while Ceramic materials are increasingly specified for demanding, high-performance applications.
Application:
The diverse applications of ball bearings range from high-volume, general-purpose uses to highly specialized, performance-critical roles, each presenting distinct demand characteristics and design challenges. This segment's demand profile is heavily influenced by industrial investment cycles.
- Electric Motors:Bearings in electric motors must withstand high rotational speeds and prevent electrical arcing, driving demand for specialized hybrid and insulated solutions. The global surge in electric vehicle production and industrial automation significantly boosts this segment.
- Wind Turbines:Large-diameter, high-load ball bearings are crucial for the reliable operation of wind turbine gearboxes and main shafts. Renewable energy mandates, such as the EU Green Deal, accelerate deployment in countries like Germany and Denmark.
- Aerospace Equipment:Bearings in aircraft engines and control systems require extreme precision, reliability, and lightweight materials. Stringent certifications from bodies like the FAA ensure only qualified components are used in safety-critical systems.
- Machine Tools:High-precision bearings are essential for the accuracy and speed of machine tool spindles and guideways. The adoption of advanced manufacturing techniques in countries like Japan and South Korea drives demand for high-performance solutions.
- Conveyors:Standardized ball bearings are widely used in conveyor systems for material handling across various industries. Their primary role is to ensure smooth, continuous operation under moderate loads, prioritizing durability and cost.
Electric Motors represent a substantial growth vector, while Aerospace Equipment demands the highest levels of material traceability and performance validation.
End User Industry:
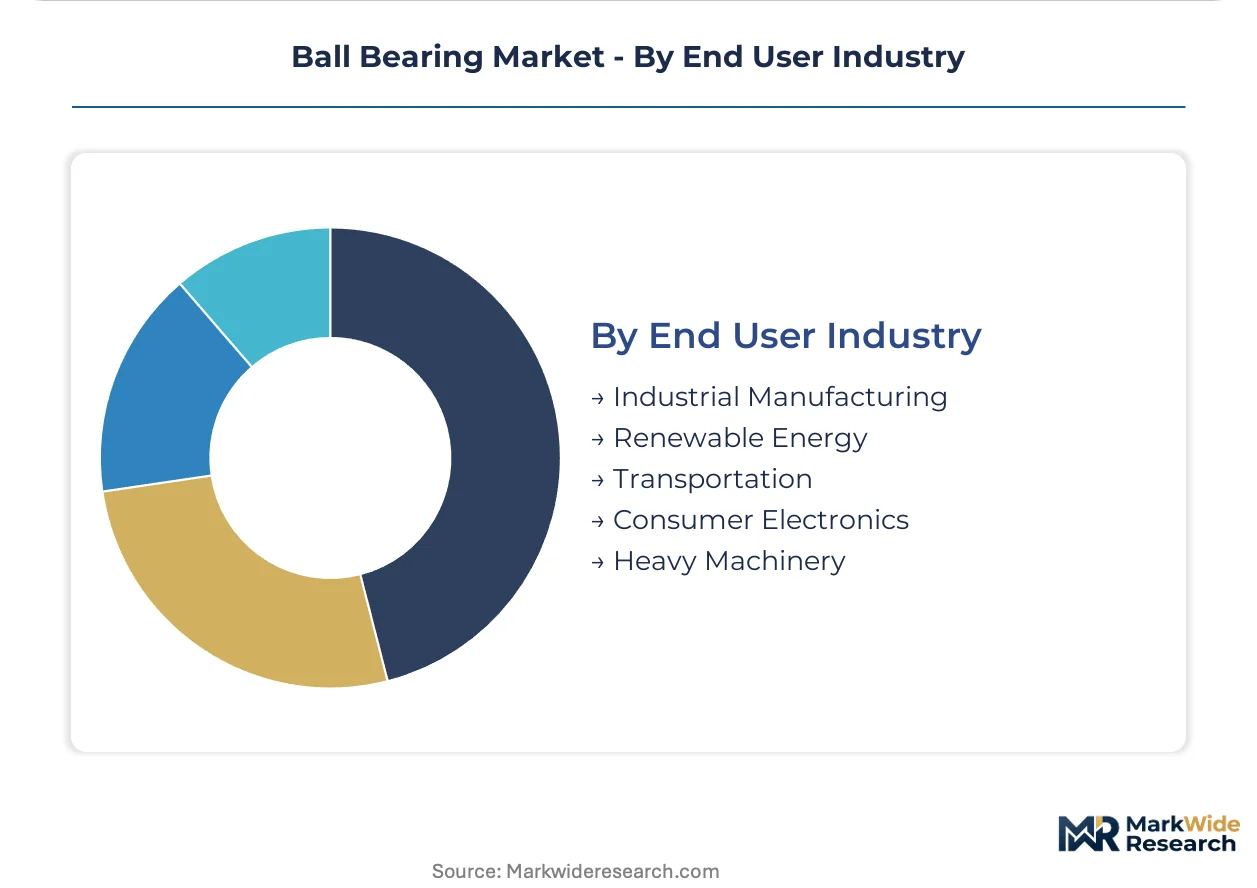
End-user industries dictate the scale, performance requirements, and procurement patterns for ball bearings, influencing manufacturers' strategic focus and product development. Each industry presents unique opportunities and regulatory considerations for suppliers.
- Transportation:This segment includes automotive, rail, and aerospace, requiring bearings for engines, drivetrains, wheels, and control systems. The electrification of vehicles, influenced by regulations from the US NHTSA and Germany's KBA, significantly reshapes bearing demand.
- Renewable Energy:Ball bearings are integral to wind turbines, solar trackers, and hydroelectric generators, demanding robust, long-lasting components. Government incentives like the US Inflation Reduction Act stimulate significant investment in this sector.
- Industrial Manufacturing:This broad sector encompasses machinery for production lines, robotics, and automation, requiring a wide range of bearing types. Smart bearing integration for Industry 4.0 applications drives innovation in automated factories.
- Heavy Machinery:Construction equipment, mining vehicles, and agricultural machinery rely on durable, high-load capacity bearings. These applications prioritize robustness and resistance to harsh operating conditions.
- Consumer Electronics:Miniature and specialized bearings are used in devices like hard drives, cooling fans, and small motors. This segment often prioritizes compact size, low noise, and cost-effectiveness.
The Transportation sector commands substantial volume, with Renewable Energy emerging as a significant long-term investment area for specialized bearing solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for ball bearings varies significantly across applications. Buyers in high-performance sectors like aerospace prioritize reliability and specialized materials over cost. Conversely, general industrial machinery and consumer electronics segments exhibit higher price sensitivity, favoring volume-driven, cost-effective solutions.
China
Electric vehicle production and renewable energy mandates drive substantial volume demand in China. The country's dual carbon goals incentivize advanced bearing solutions for green technologies, particularly in wind turbines and solar trackers. Manufacturing hubs in the Yangtze River Delta actively integrate specialized bearings into new energy vehicle drivetrains and industrial automation equipment.
Germany
Germany's e-mobility sector and advanced industrial automation require high-precision ball bearings. The EU Green Deal accelerates demand for efficient components in sustainable manufacturing. Engineering clusters in Baden-Württemberg lead development of ceramic hybrid bearings for machine tools and electric motors.
United States
United States electric vehicle build-out and wind energy projects create strong demand for specialized bearings. The US Inflation Reduction Act provides incentives for domestic manufacturing and renewable energy deployment. Major automotive production centers in Michigan and wind turbine assembly plants in Texas require high-load capacity solutions.
Japan
Precision machine tools and the automotive sector sustain consistent demand for high-performance bearings in Japan. METI industrial policies support advanced manufacturing initiatives and component innovation. Industrial clusters in Aichi Prefecture integrate sophisticated bearings into robotics and next-generation vehicles.
India
India's expanding automotive manufacturing and industrial growth fuel a robust market for ball bearings. The PLI scheme stimulates domestic production of critical components across various sectors. Industrial hubs in Tamil Nadu and Maharashtra actively procure bearings for vehicle assembly and general machinery applications.
Ball Bearing Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another in the ball bearing market. The landscape features a mix of global diversified industrial conglomerates and specialized component manufacturers. Strategic archetypes include high-performance innovators, volume-driven standard product suppliers, and regional niche players. Companies pursue capacity expansion and strategic partnerships to secure raw material access and broaden application reach.
On the premium-tier vector, SKF Group and Schaeffler Group exemplify global engineering excellence and integrated system solutions. These European-based entities leverage extensive R&D to develop advanced ceramic hybrid bearings for e-mobility, aerospace, and high-speed machine tools. JTEKT Corporation, a Japanese-based manufacturer, also occupies a strong position, offering a broad portfolio for both automotive and heavy machinery sectors. Luoyang LYC Bearing Co., Ltd., a prominent Chinese manufacturer, anchors the volume-driven segment, catering to general industrial and automotive applications with cost-efficient offerings.
| Leading Market Players |
|---|
| Timken Company |
| JTEKT Corporation |
| SKF Group |
| Luoyang LYC Bearing Co., Ltd. |
| NACHI-Fujikoshi Corp. |
| NSK Ltd. |
| Schaeffler Group |
| Wafangdian Bearing Group Corporation |
| NTN Corporation |
| Others |
Cost & Logistics Intelligence
Concentration of high-purity chrome steel and specialty alloy production in specific Asian countries directly influences pricing power, allowing margin pools to accumulate upstream before reaching downstream component integrators.
Pricing Analysis
Predictive maintenance services, enabled by smart bearing technology, drive significant lifetime value for end-users. Pricing for ball bearings often follows a value-based model, particularly for high-performance ceramic hybrid solutions. Price differentiation stems from certification levels required for aerospace applications and the degree of customization for specialized machinery. Cost compression in standard deep groove ball bearings intensifies due to high-volume manufacturing in China, impacting overall market pricing. Buyers in consumer electronics exhibit high price sensitivity, while aerospace and medical equipment sectors prioritize performance over cost.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities are becoming more common to manage working capital across the ball bearing value chain. Geographic supply is concentrated, with China and Japan serving as major manufacturing hubs for both raw materials and finished components. The industry depends on consistent access to chrome steel, silicon nitride, and various specialty alloys. Raw material price volatility represents a primary structural risk for manufacturers. Distribution runs through a dual model, combining direct sales to large OEMs for specialized applications and extensive distributor networks for general industrial and aftermarket segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ball bearing market is increasingly a service-attach opportunity, with predictive maintenance and condition monitoring services expanding faster than traditional hardware sales.
For Market Incumbents: Build certification moats around advanced material applications like aerospace and e-mobility to deter new entrants. Invest heavily in R&D for next-generation ceramic hybrid bearings capable of higher speeds and greater electrical insulation. Leverage existing extensive industrial and automotive channel access to deploy these advanced solutions. This strategy helps mitigate the threat of price erosion in commodity segments.
For New Entrants and Emerging Players: Geographic underpenetration in emerging manufacturing economies, particularly in Southeast Asia, offers significant white-space opportunities. Target high-precision, corrosion-resistant bearings for niche medical equipment and specialized robotics applications. A focused go-to-market angle should emphasize localized production capabilities and application-specific engineering support for regional OEMs.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed firms specializing in advanced material science or sensor integration technologies. The long-term viability of the ball bearing market is anchored by the global electrification of transportation and industrial automation. Target firms with robust intellectual property in ceramic materials or smart bearing technology. The increasing frequency of M&A transactions in specialized bearing segments serves as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Ceramic Hybrids | Increases supply of high-performance components critical for electric vehicles and machine tools. |
| Integration of Smart Bearing Technology | Enables predictive maintenance services, creating new recurring revenue streams for manufacturers. |
| Strategic Partnerships for Material Innovation | Secures access to next-generation alloys and composites, enhancing product performance and differentiation. |
| Diversification of Manufacturing Footprint | Mitigates supply chain risks by establishing production hubs in emerging Southeast Asian economies. |
| Investment in Aerospace Certification Processes | Reinforces market position in high-margin, safety-critical applications with stringent regulatory barriers. |
Research Approach
Cross-validation between primary interviews with industry stakeholders and rigorous secondary data validation anchors the qualitative findings. This study engaged automotive OEM engineers, industrial plant managers, material science R&D directors, and aftermarket distributors. Secondary sources included ISO standards, US NHTSA regulations, Germany's KBA guidelines, company financial reports, and industry association data, ensuring comprehensive bottom-up and top-down triangulation.
The calibration of quantitative models against historical market data informed the forecast framework across the analysis window. Segmentation dimensions modeled included product type, material, application, end-user industry, and regional manufacturing output. Compound annual growth rates were derived from detailed demand drivers such as global electric vehicle production volumes and wind turbine installation capacities, alongside market penetration rates for advanced materials.
The forecast holds incumbent behavior within observed patterns; aggressive moves by disruptive material innovators or large state-backed manufacturers would shift outcomes. Macroeconomic shifts, significant policy changes, or disruptive technological breakthroughs would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Control Arms Market
Automotive Parts
Full Synthetic Motor Oil Market
Automotive Parts
Global Automotive Gasket and Seal Market
Automotive Parts
Colombia Commercial Vehicles Lubricants Market
Automotive Parts
Automotive Electric Vacuum Pump Market
Automotive Parts
Harmonic Gearboxes Market
Automotive Parts
Automotive Electric Water Pump Market
Automotive Parts
Brass Synchronizer Ring Market
Automotive Parts
Automotive Mechanical Control Cable Market
Automotive Parts
US Automotive Airfilters Market
Automotive Parts
Automotive Wiper System Market
Automotive Parts
Automotive Aluminium Extrusion Market
Automotive Parts
Automotive AHSS Market
Automotive Parts
Automotive Oil Pressure Switch Market
Automotive Parts
Thailand Automotive Lubricants Market
Automotive Parts
Industrial Shock Absorbers Market