
 Automotive Mechanical Control Cable Market | 2026-2036
Automotive Mechanical Control Cable Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Mechanical Control Cable Market Insights
Chinese steel wire rope producers are expanding coated-cable capacity to serve brake and clutch assembly lines serving European OEMs. DURA Automotive Systems leverages vertical integration across North American stamping and cable-forming operations to sustain just-in-time delivery contracts with Detroit vehicle assemblers. Suprajit Engineering Ltd. anchors South Asian aftermarket distribution through dedicated dealer networks spanning two dozen Indian states.
Automotive mechanical control cables are tension-transmission devices constructed from stranded steel or polymer-composite cores sheathed in lubricated conduits, engineered to translate pedal or lever displacement into throttle, brake, clutch, or transmission actuation with sub-millimeter travel precision. The throttle cable segment retains volume dominance in internal-combustion vehicle platforms across Latin America and Africa, while composite-material brake cables are gaining specification share in European electric-vehicle architectures where reduced unsprung mass carries range value. OEM end users concentrate procurement through long-term blanket orders that lock in steel pricing, whereas aftermarket providers compete on same-day availability of standardized clutch and transmission cable kits.
The US NHTSA Federal Motor Vehicle Safety Standards govern cable-system integrity under FMVSS 135 brake requirements, while China's GB standards and MIIT homologation rules mandate corrosion resistance and cycle-life testing for on-road mechanical assemblies. India's BIS certification and CDSCO-adjacent automotive component quality protocols create compliance barriers for uncertified imports, redirecting sourcing toward domestic Tier-1 cable formers. Stakeholders must monitor how ECE R90 brake-cable homologation and China's evolving GB/T standards for composite materials reshape supplier qualification timelines and tooling amortization schedules.
Market Dynamics
Steel pricing volatility and India's PLI scheme for automotive components are compressing supplier margins while accelerating localization of clutch and throttle cable production in South Asian industrial corridors.
Growth Catalysts
- ECE R90 brake-system mandates:European homologation requirements are redirecting supplier investment toward certified cable assemblies with enhanced corrosion resistance and cycle-life performance.
- Composite-material advancement:Polymer-composite brake cables are gaining specification share in electric-vehicle architectures where reduced unsprung mass carries range value.
- Tamil Nadu industrial corridor:Tier-1 suppliers are localizing production to serve Maruti Suzuki and Tata Motors procurement programs under domestic content incentives.
Market Restraints
- Steel wire rope input volatility:Raw material price swings compress margin predictability for cable formers locked into long-term blanket order pricing structures.
- Chinese supplier concentration:Coated-cable capacity expansion by domestic producers creates dependency risk for European OEM brake and clutch assembly lines.
- Electronic throttle control substitution:Drive-by-wire systems are displacing mechanical throttle cables in premium vehicle platforms across developed automotive markets.
Strategic Opportunities
- Aftermarket channel digitization:Same-day availability platforms are unbundling traditional dealer networks for standardized clutch and transmission cable kits.
- Maharashtra supplier ecosystem:Industrial cluster development offers co-location advantages for integrated stamping and cable-forming operations.
- GB/T composite standards evolution:China's evolving material certification protocols create qualification windows for certified foreign cable assemblies.
Industry Challenges
- Homologation timeline compression:ECE R90 certification cycles and BIS quality protocol adherence are extending supplier qualification periods for new cable platforms.
- Legacy system integration friction:Mechanical cable architectures must interface with electronic control modules in hybrid drivetrain configurations, complicating engineering validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Mechanical Control Cable Market |
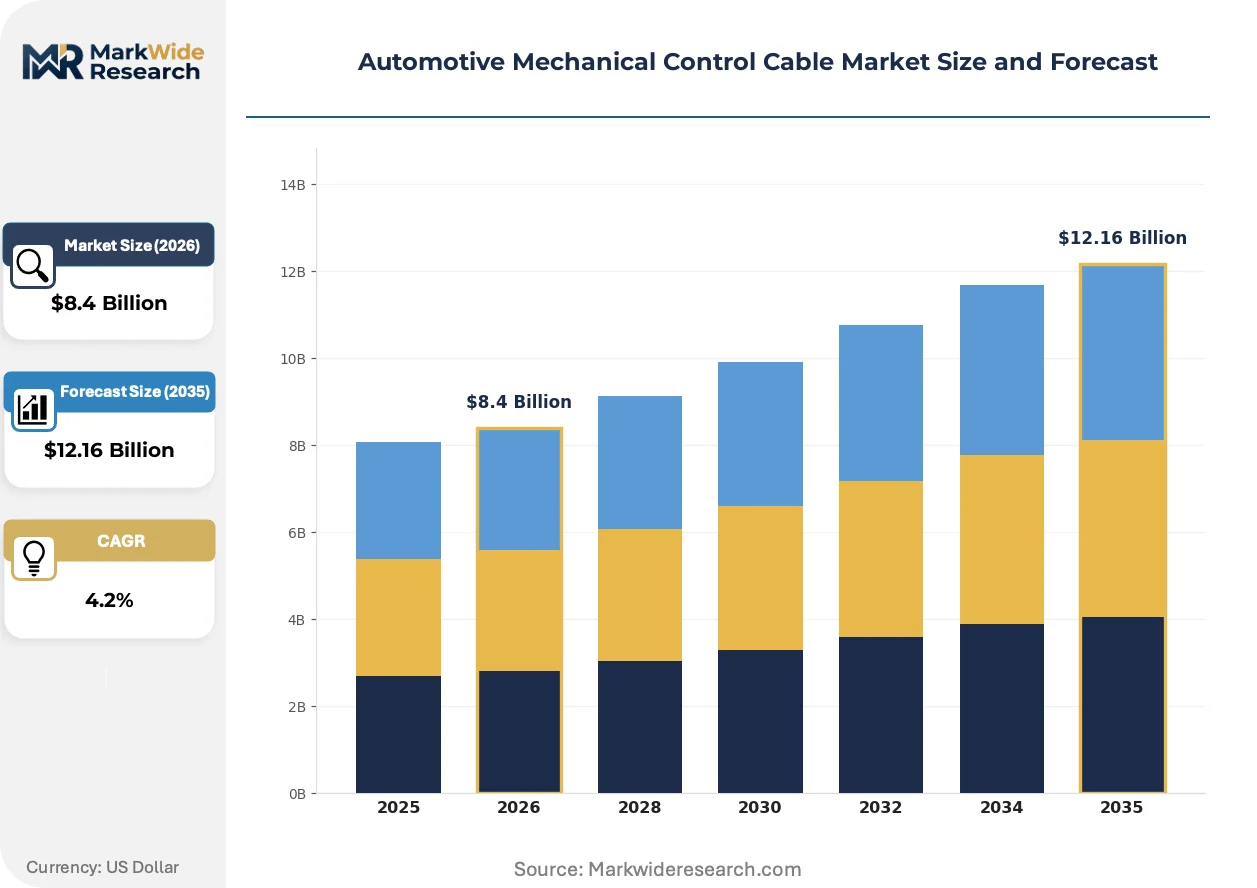
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $12.16 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
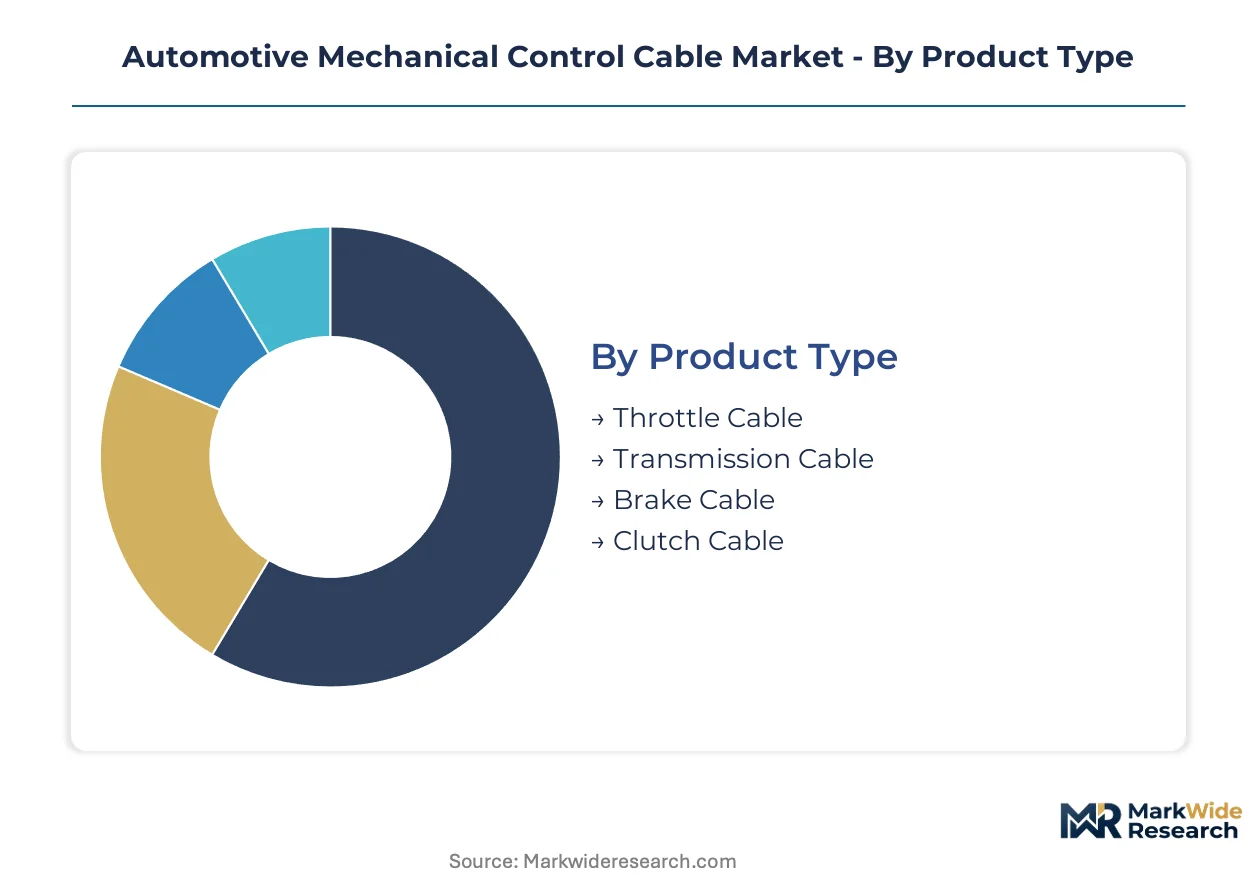
| Segmentation | Product Type: Throttle Cable, Transmission Cable, Brake Cable, Clutch Cable End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Installation Type: On-Road, Off-Road, Heavy-Duty, Light-Duty Material: Steel, Aluminum, Plastic, Composite |
| Companies Covered | DURA Automotive Systems, Suprajit Engineering Ltd., HI-LEX Corporation, Kongsberg Automotive, Grand Rapids Controls, Küster Holding GmbH, Tyler Madison, Cablecraft Motion Controls, Bergen Cable Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Mechanical Control Cable Market Trends and Innovations
Material science advances and regulatory homologation pressures are converging to redefine cable-system specifications across combustion and electric vehicle platforms simultaneously.
Polymer-composite core technology is rewriting brake cable engineering specifications. The material substitutes stranded steel with carbon-fiber reinforced polymer filaments sheathed in lubricated conduits. European electric-vehicle OEMs are specifying these assemblies for unsprung mass reduction. This substitution is compressing traditional steel-core supplier relevance in premium brake system procurement.
REACH substance restrictions and RoHS compliance extensions are tightening coating chemistry requirements for European-market cable assemblies. The regulations mandate elimination of specific heavy-metal lubricants and sheathing compounds. Brake cable suppliers serving German and French OEMs are reformulating conduit materials to maintain homologation status.
Long-term blanket order contracting is consolidating buyer power among Detroit and European vehicle assemblers. Procurement teams are locking in eighteen-to-twenty-four-month steel pricing to hedge commodity volatility. This behavior is visible most acutely in North American transmission cable sourcing, where just-in-time delivery contracts now bundle material cost risk with volume commitments.
Automotive Mechanical Control Cable Market Segmentation
Mechanical control cable procurement splits across fundamentally different buyer logics: OEMs optimize for specification precision and steel-price hedging, while aftermarket channels compete on inventory velocity and same-day fulfillment. Understanding these divergent purchase criteria exposes where margin pools concentrate and which material technologies command premium positioning.
Product Type:
Application severity and actuation precision requirements determine cable specification across vehicle platforms.
- Throttle Cable:Stranded steel-core assemblies with sub-millimeter travel precision translate pedal displacement into engine airflow modulation. Demand concentrates in Latin American and African internal-combustion platforms where electronic throttle control penetration remains limited by cost constraints.
- Brake Cable:Polymer-composite and steel-core variants engineered for ECE R90 homologation requirements are gaining specification share in European electric-vehicle architectures where unsprung mass reduction directly extends driving range.
- Transmission Cable:Heavy-duty steel wire rope constructions manage gear-selector actuation loads in commercial vehicle applications.
- Clutch Cable:Self-adjusting stranded steel assemblies dominate manual transmission platforms across South Asian passenger vehicle production.
Throttle cable leads on scale; brake cable leads on momentum.
End User:
Contracting structure and inventory risk allocation vary sharply across the value chain.
- OEMs:Vehicle manufacturers lock in eighteen-to-twenty-four-month steel pricing through long-term blanket orders that bundle material cost risk with volume commitments, concentrating procurement power among Detroit and European assemblers.
- Aftermarket Providers:Distributors compete on same-day availability of standardized clutch and transmission cable kits, with Suprajit Engineering anchoring South Asian distribution through dedicated dealer networks spanning two dozen Indian states.
- Tier-1 Suppliers:Cable formers in Tamil Nadu and Maharashtra industrial corridors localize production to serve Maruti Suzuki and Tata Motors under domestic content incentives.
- Vehicle Assemblers:Just-in-time delivery contracts with integrated stamping and cable-forming operations sustain lean inventory positions.
OEMs command the largest contract values; aftermarket providers are expanding most quickly through channel digitization.
Installation Type:
Operating environment severity dictates material specification and cycle-life testing protocols.
- On-Road:Passenger and commercial vehicle applications governed by NHTSA FMVSS 135 brake requirements and India's BIS certification protocols.
- Off-Road:Agricultural and construction equipment cables face abrasive contamination and extreme temperature cycling.
- Heavy-Duty:Commercial vehicle transmission and clutch assemblies in India and Southeast Asia absorb high-frequency actuation loads.
- Light-Duty:Compact passenger vehicle platforms prioritize packaging efficiency and reduced actuation effort.
On-road installation dominates volume; heavy-duty applications show steepest expansion trajectory.
Material:
Mass reduction imperatives and regulatory chemistry restrictions are reshaping material qualification.
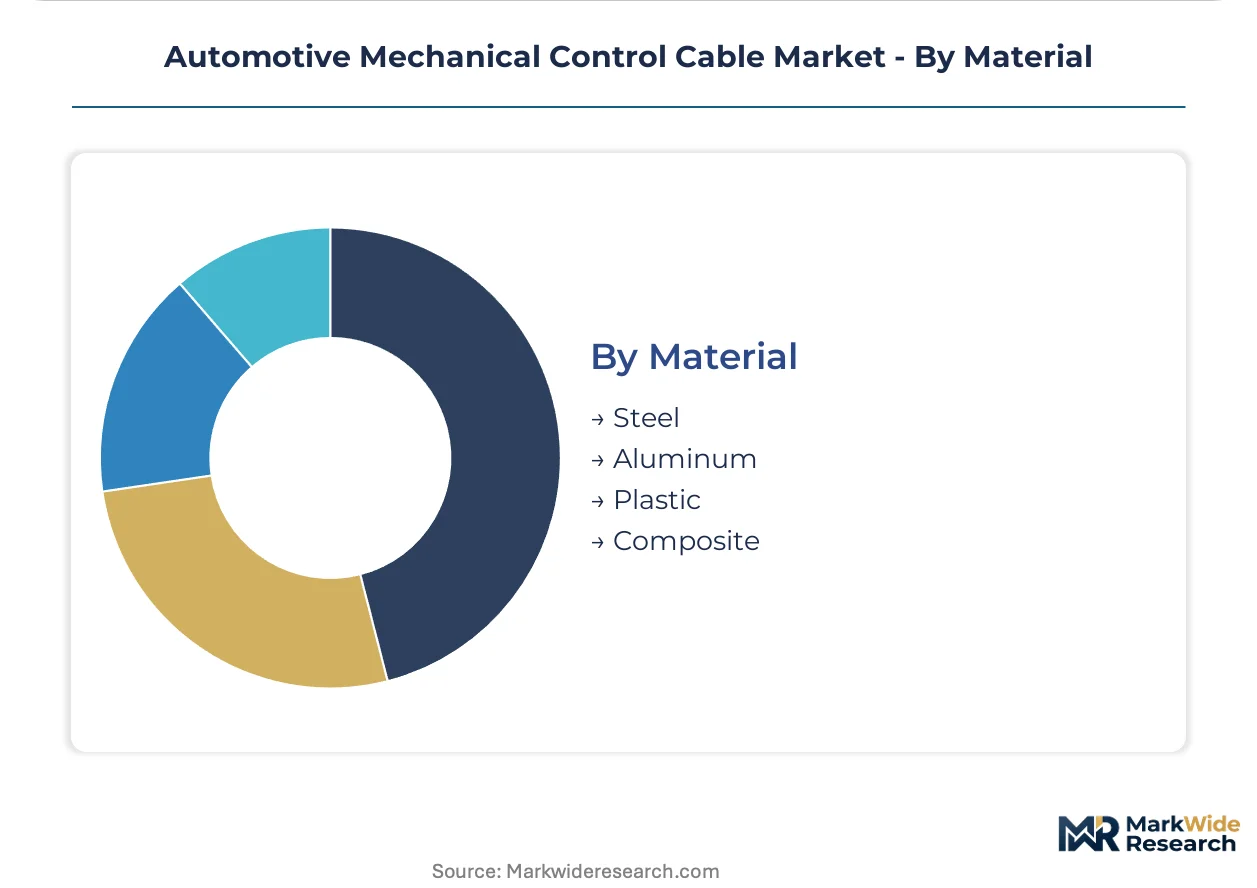
- Steel:Stranded wire rope cores remain the default specification for transmission and clutch applications where tensile strength and fatigue resistance outweigh mass considerations.
- Composite:Carbon-fiber reinforced polymer filaments substitute steel in European electric-vehicle brake systems, compressing traditional supplier relevance as REACH substance restrictions tighten coating chemistry requirements.
- Aluminum:Intermediate density option for throttle linkages where moderate mass reduction justifies material cost premiums.
- Plastic:Sheathing and conduit materials undergoing reformulation to eliminate heavy-metal lubricants under RoHS compliance extensions.
Steel leads on installed base; composite gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's steel wire rope producers scale coated-cable capacity aggressively while India's Tamil Nadu corridor localizes clutch and throttle production for domestic OEMs. Divergent regulatory trajectories in these markets are compressing qualification timelines and redirecting supplier investment toward certified assemblies.
United States
Detroit vehicle assemblers sustain just-in-time delivery contracts through integrated stamping and cable-forming operations. NHTSA FMVSS 135 brake requirements govern cable-system integrity validation. Michigan and Ohio industrial clusters concentrate procurement power through eighteen-to-twenty-four-month steel pricing lock-ins.
Germany
European electric-vehicle OEMs specify polymer-composite brake cables for unsprung mass reduction. ECE R90 homologation mandates redirect supplier investment toward certified assemblies with enhanced corrosion resistance. Baden-Württemberg and Bavaria host Tier-1 formers reformulating conduit materials under REACH substance restrictions.
China
Domestic coated-cable capacity expansion serves brake and clutch assembly lines supplying European OEMs. MIIT homologation rules and evolving GB/T standards for composite materials reshape supplier qualification windows. Yangtze River Delta producers concentrate steel wire rope output for transmission cable exports.
India
Tamil Nadu and Maharashtra industrial corridors localize production to serve Maruti Suzuki and Tata Motors procurement programs. BIS certification and PLI scheme incentives for automotive components create compliance barriers for uncertified imports. Tier-1 suppliers anchor South Asian aftermarket distribution through dedicated dealer networks.
Japan
Precision cable engineering serves hybrid drivetrain configurations where mechanical architectures interface with electronic control modules. METI industrial standards and JIS certification protocols maintain quality benchmarks for export-oriented production. Kansai and Chubu regions concentrate specialized forming operations for premium vehicle platforms.
Automotive Mechanical Control Cable Market Competitive Landscape
North American producers anchor one tier through integrated stamping and cable-forming operations; Asian specialists hold manufacturing scale advantages in steel wire rope output. The vendor base splits between consolidated Detroit-facing assemblers and fragmented regional formers serving aftermarket channels. Three archetypes dominate: vertically integrated OEM contractors, standalone cable formers, and steel-core commodity producers. Competitive moves concentrate on capacity expansion in coated-cable segments and strategic partnerships for composite-material qualification.
Among the integrated OEM contractors, DURA Automotive Systems exemplifies the North American tier through its captive supply structure across stamping and forming operations. Suprajit Engineering Ltd. occupies a position within the Asian specialist tier, representing the distributed aftermarket model spanning dealer networks. HI-LEX Corporation anchors the precision-engineering segment, exemplifying Japanese manufacturing standards for hybrid drivetrain applications. These three entities represent distinct competitive vectors: geographic integration, channel dominance, and technical specification leadership.
| Leading Market Players |
|---|
| DURA Automotive Systems |
| Suprajit Engineering Ltd. |
| HI-LEX Corporation |
| Kongsberg Automotive |
| Grand Rapids Controls |
| Küster Holding GmbH |
| Tyler Madison |
| Cablecraft Motion Controls |
| Bergen Cable Technology |
| Others |
Pricing and Supply Chain Analysis
Polymer-composite brake cable adoption across European electric-vehicle platforms is simultaneously elevating material cost baselines and fragmenting supplier concentration away from traditional steel-core formers toward specialized composite processors. This technology transition concentrates pricing power among certified Tier-1 suppliers capable of ECE R90 homologation while compressing margins for commodity steel-cable producers locked into long-term blanket order structures.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for steel wire rope inputs across global brake and clutch cable procurement. Contract-based long-term offtake dominates OEM procurement, with eighteen-to-twenty-four-month steel pricing lock-ins bundling volume commitments with material cost risk. Price differentiation hinges on ECE R90 certification tier and geographic delivery cost to European assembly plants. Cost compression in standard steel-core segments is intensifying because Chinese producers are scaling coated-cable output aggressively. Aftermarket distributors show highest price sensitivity due to inventory velocity pressures, while OEM platform engineers prioritize specification precision over unit cost.
Supply Chain Analysis
Reverse-logistics flows for remanufactured transmission cables are emerging as a secondary supply channel serving India's commercial vehicle aftermarket through Maharashtra-based refurbishment operations. Primary manufacturing concentrates in China, India, and Germany, with Yangtze River Delta and Tamil Nadu industrial corridors anchoring respective regional output. Raw material dependencies rest on steel wire rope, carbon-fiber reinforced polymer filaments, and REACH-compliant lubricated conduit sheathing. Single-source vulnerability runs through Chinese coated-cable capacity serving European OEM brake assembly lines. Distribution runs through Tier-1 supplier direct contracts with vehicle assemblers and dedicated dealer networks spanning Indian states.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where ECE R90 brake-system mandates are accelerating procurement redirection toward certified cable assemblies with enhanced corrosion resistance and cycle-life performance.
For Market Incumbents: Extend ECE R90 certification coverage across brake cable product lines before qualification windows compress under evolving European homologation timelines. Deepen backward integration into steel wire rope forming to hedge commodity volatility exposure from Chinese supplier concentration. Lock in long-term blanket orders with Detroit and European assemblers to defend margin position against emerging composite-material specialists.
For New Entrants and Emerging Players: Launch via aftermarket digitization platforms targeting same-day availability gaps in India's clutch and transmission cable replacement demand. Target Maharashtra and Tamil Nadu industrial corridor co-location to access Maruti Suzuki and Tata Motors procurement programs under PLI scheme incentives. Penetrate through certified composite brake cable qualification for European electric-vehicle platforms where unsprung mass reduction carries range value.
For Investors and Strategic Acquirers: Valuations sit cheapest among standalone cable formers lacking ECE R90 certification or composite-material qualification capabilities. Long-term viability centers on regulatory compliance moats widening across the analysis window as REACH substance restrictions and BIS protocols tighten. Target acquisition archetypes include Tier-1 suppliers with captive OEM relationships and demonstrated homologation track records. Monitor GB/T composite standards evolution in China as an inflection signal for qualified foreign cable assembly market entry.
| Strategic Initiative | Industry Significance |
|---|---|
| Composite Material Qualification | ECE R90-certified polymer brake cables unlock European electric-vehicle procurement specifications. |
| Backward Integration into Steel Forming | Captive wire rope production hedges Chinese supplier concentration risk for North American OEM contracts. |
| Aftermarket Channel Digitization | Same-day availability platforms disintermediate traditional dealer networks across Indian state markets. |
| PLI Scheme Co-location | Tamil Nadu and Maharashtra cluster proximity secures Maruti Suzuki and Tata Motors volume commitments. |
| REACH Compliance Reformulation | Conduit material chemistry adjustments maintain European homologation status under tightening substance restrictions. |
Research Methodology
Bottom-up vehicle production modeling reconciled against top-down steel wire rope consumption tracking forms the analytical core of this study. Primary interviews with Tier-1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and dealership operations managers were combined with secondary validation from vehicle production databases, IHS Markit registration data, SEC filings of listed automotive component suppliers, and customs trade records. This triangulation approach ensures demand-side estimates align with supply-side capacity disclosures across the analysis window.
Input-output matrices map cable content per vehicle across propulsion architecture, vehicle class, and regional production cluster dimensions. CAGRs were derived through segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs incorporate ECE R90 homologation timeline assumptions, PLI scheme incentive disbursement patterns, and composite-material substitution curves in European electric-vehicle platforms throughout the projection horizon.
Forecast precision tightens around the base case; tail outcomes carry wider variance under steel price volatility spikes and accelerated electronic throttle control substitution in premium platforms. Practitioners should monitor MIIT homologation rule changes and BIS certification protocol amendments for early signals of supplier qualification barrier shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
US Automotive Parts Magnesium Die Casting Market
Automotive Parts
Tire Mold Market
Automotive Parts
France Automotive Parts Aluminium Die Casting Market
Automotive Parts
Europe Motorcycle Parts and Accessories Market
Automotive Parts
Automotive Electric Parking Brakes Market
Automotive Parts
Automotive Propeller Shaft Market
Automotive Parts
Automotive Air Compressor Market
Automotive Parts
Automotive Electric Water Pump Market
Automotive Parts
Uae Passenger Vehicles Lubricants Market
Automotive Parts
Car Phone Holder Market
Automotive Parts
Australia Automotive Parts Magnesium Die Casting Market
Automotive Parts
Automotive Common Rail System Market
Automotive Parts
Automatic Gearbox Valves Market
Automotive Parts
Automotive Belts Market
Automotive Parts
Indonesia Commercial Vehicles Lubricants Market
Automotive Parts
Automotive Wiping Systems Market