
 US Automotive Airfilters Market | 2026-2036
US Automotive Airfilters Market Size, Share, and Industry Trends Forecast 2026-2036
US Automotive Airfilters Market Analytics
Modular filter cartridge systems are pivoting how fleet buyers configure maintenance contracts, unbundling traditional bundled service packages into component-level procurement. MANN+HUMMEL leverages its captive media manufacturing to control cost positions across OEM channels. Donaldson Company, Inc. anchors its position in heavy-duty truck applications with proprietary nanofiber layering technology. K&N Engineering, Inc. differentiates through washable performance filters that compete on lifetime cost rather than replacement frequency.
Automotive airfilters are pleated fibrous media devices engineered to remove particulate matter from intake air streams, typically constructed from cellulose, synthetic blends, or glass microfibers with MERV efficiency ratings calibrated to engine protection requirements. Their primary function is preventing abrasive wear of cylinder walls, turbocharger vanes, and fuel injection components while maintaining optimal air-to-fuel ratios. Engine air intake filtration dominates value capture given higher unit costs and stricter OEM specification requirements, while cabin filtration segments sustain faster growth trajectories as consumer awareness of interior air quality intensifies. Aftermarket installation channels occupy concentrated margin pools due to recurring replacement demand and lower price transparency compared to OEM captive supply agreements.
EPA tailpipe and emissions regulations shape filter efficiency mandates, compelling manufacturers to engineer higher particulate capture rates without restricting airflow profiles that degrade fuel economy. NHTSA corporate average fuel economy standards indirectly pressure filter designs toward lower pressure-drop configurations. California Air Resources Board zero-emission vehicle pathways create divergent demand signals as internal combustion filter requirements persist alongside emerging battery thermal management filtration needs. Stakeholders must monitor how powertrain electrification timelines reshape aftermarket inventory strategies and manufacturing capacity allocation across filtration product families.
Market Dynamics
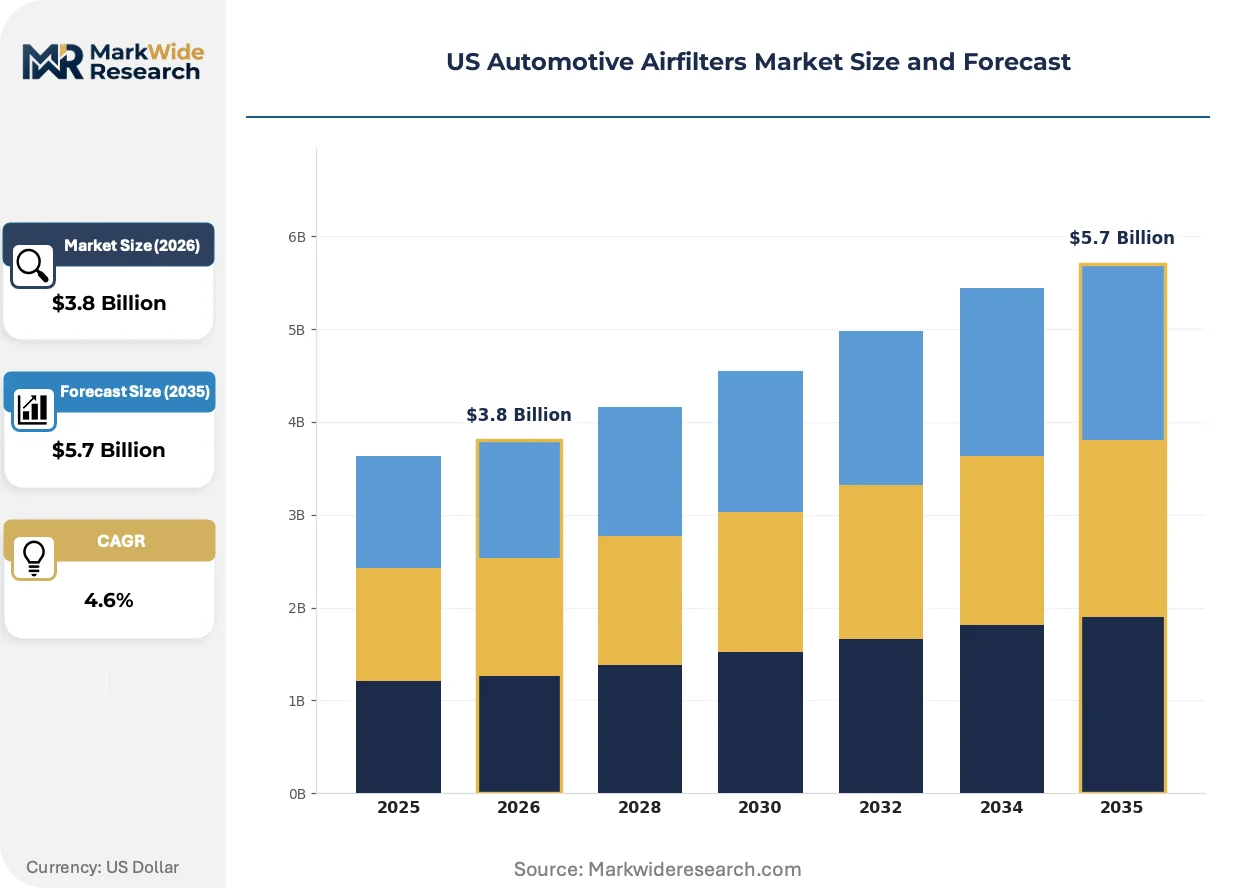
EPA emissions compliance timelines are compressing replacement cycles for commercial fleet operators while nanofiber media investments reshape upstream manufacturing economics across the Midwest corridor.
Growth Catalysts
- EPA Phase 3 Greenhouse Gas Standards:Heavy-duty truck fleets face stricter particulate capture mandates, forcing filter media upgrades ahead of 2027 implementation deadlines.
- Battery thermal management filtration:Electric vehicle battery pack cooling systems require specialized filtration media, creating parallel demand streams alongside internal combustion engine requirements.
- Ohio-Indiana manufacturing cluster:Concentrated OEM assembly operations generate captive demand for just-in-time filter supply contracts with localized logistics advantages.
Market Restraints
- Cellulose pulp price volatility:Raw material input costs for traditional filter media fluctuate with packaging industry demand cycles and forestry supply constraints.
- Single-source nanofiber substrate dependence:Proprietary electrospinning equipment and process IP concentrates critical supply among limited domestic equipment vendors.
- California Air Resources Board divergence:State-level zero-emission vehicle mandates create inventory complexity for national aftermarket distributors managing SKU proliferation.
Strategic Opportunities
- Texas Gulf Coast petrochemical logistics hubs:Underdeveloped independent service networks for heavy-duty fleets create whitespace for regional maintenance contract providers.
- Washable performance filter aftermarket:Lifetime-cost positioning targets enthusiast and commercial segments seeking reduced replacement frequency and waste disposal burden.
- IRA clean vehicle tax credits:Fleet electrification incentives accelerate hybrid vehicle adoption, sustaining dual-track filter demand for internal combustion range extenders.
Industry Challenges
- Electrospinning technician scarcity:Specialized nanofiber production requires process engineers with polymer chemistry and high-voltage equipment expertise that outpaces vocational training pipeline output.
- California-EPA regulatory reconciliation:Divergent certification timelines for 50-state compliance force duplicate testing protocols and extended product launch schedules.
- Legacy fleet management software integration:Predictive maintenance algorithms for filter replacement scheduling require API connectivity with entrenched telematics platforms resistant to third-party data sharing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Automotive Airfilters Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Filter Type: HEPA, Cabin, Engine, Universal Material: Fiberglass, Polyester, Foam, Cellulose Vehicle Type: Passenger Cars, Trucks, SUVs, Vans Installation Type: OEM, Aftermarket, Custom, Standard |
| Companies Covered | MANN+HUMMEL, Donaldson Company, Inc., Robert Bosch GmbH, MAHLE GmbH, Denso Corporation, Cummins Filtration, Freudenberg Filtration Technologies, K&N Engineering, Inc., ACDelco, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Automotive Airfilters Market Evolving Landscape
Filter architecture is fragmenting from monolithic designs toward serviceable sub-assemblies, while regulatory pressure and fleet procurement rationalization reshape competitive positioning across supply tiers.
Nanofiber layering technology is modularizing engine air intake systems by enabling discrete pre-filter and final-stage cartridges that fleets replace independently. Long-haul trucking operators with centralized maintenance depots are standardizing on cartridge-based platforms to reduce per-service labor hours. This architecture is modularizing supplier relationships, allowing fleet buyers to unbundle media sourcing from housing hardware and capture component-level pricing transparency.
NHTSA corporate average fuel economy standards are pressuring filter designs toward lower pressure-drop configurations that minimize engine pumping losses. Manufacturers are optimizing pleat geometry and media density to balance particulate capture efficiency against airflow restriction metrics. Heavy-duty diesel applications face the steepest engineering trade-offs, driving adoption of computational fluid dynamics simulation tools to validate designs before physical prototyping.
Fleet procurement offices are consolidating supplier relationships through multi-year maintenance contracts that bundle filter replacement with fluid services and inspection intervals. Independent repair shops and smaller regional fleets face exclusion from these preferred vendor networks, compressing their parts sourcing flexibility. This concentration is most visible across the I-75 corridor, where integrated logistics providers anchor contract structures that marginalize traditional jobber distribution channels.
US Automotive Airfilters Market Segmentation
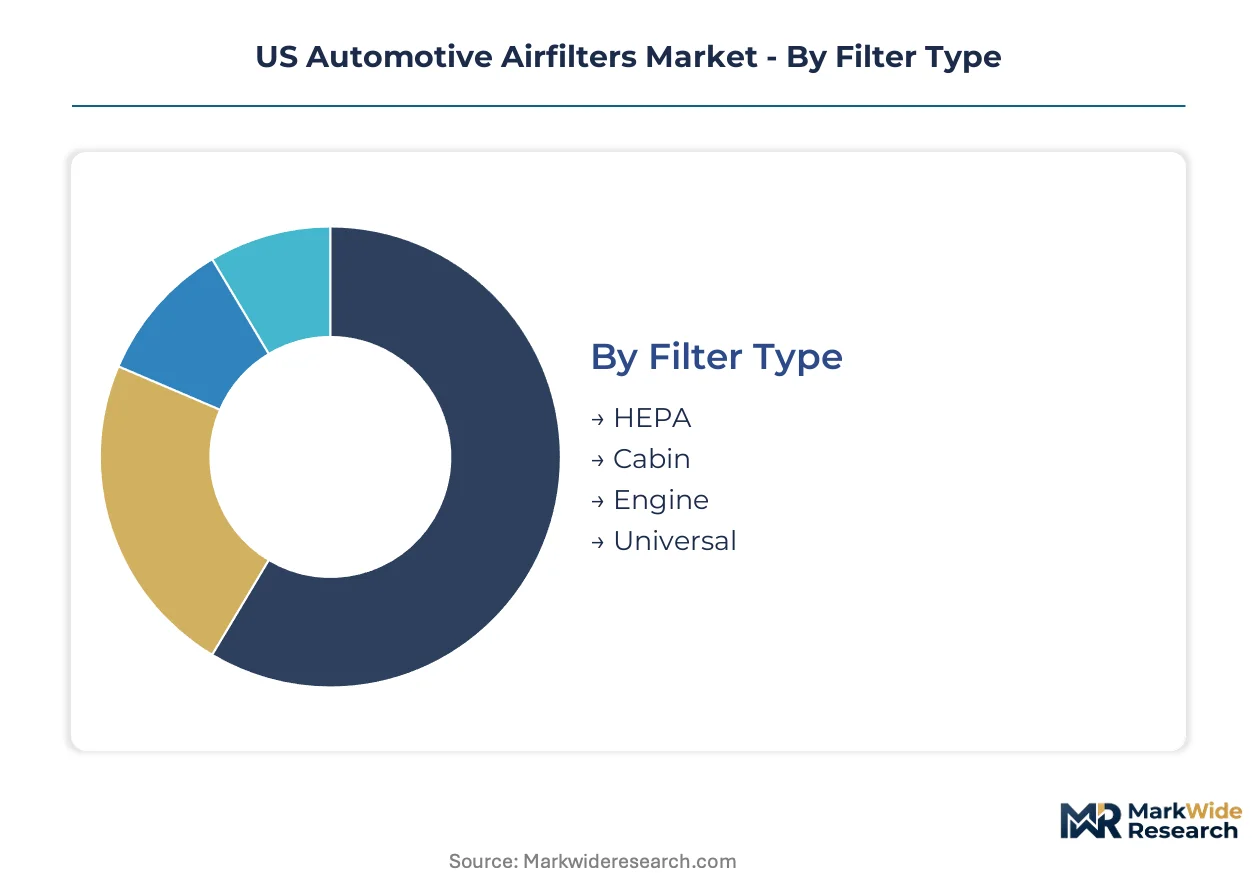
Segmentation in the US automotive airfilters market reveals divergent margin structures and replacement cadences across application types. Fleet procurement offices, OEM specification engineers, and aftermarket distributors each prioritize different performance thresholds and cost positions when selecting filtration solutions.
Filter Type:
Buyers in this category separate by contamination sensitivity and regulatory exposure rather than absolute price tolerance.
- HEPA:High-efficiency particulate air filters employ dense glass microfiber matrices certified to capture particles as small as 0.3 microns. Demand concentrates in premium cabin air applications across California and Northeast corridors where consumer awareness of interior air quality drives specification upgrades.
- Cabin:Pleated synthetic or cellulose media designed for HVAC intake filtration, typically rated MERV 6-13. Fleet operators in the Midwest automotive corridor are expanding replacement schedules as EPA emissions standards tighten, creating recurring revenue concentration for service contract providers.
- Engine:Robust cellulose-synthetic composite media engineered for high-temperature intake air streams with pressure-drop tolerances calibrated to fuel economy targets.
- Universal:Trim-to-fit media sheets serving legacy vehicle populations and specialty equipment where application-specific SKUs lack economic justification.
Volume sits with Engine filtration; growth tilts toward Cabin as consumer specification awareness climbs.
Material:
Raw material selection tracks directly against the pressure-drop versus efficiency trade-off mandated by NHTSA fuel economy standards.
- Fiberglass:Borosilicate glass microfibers spun into dense mats deliver sub-micron capture efficiency for HEPA-tier applications. Heavy-duty diesel operators facing EPA Phase 3 compliance deadlines are standardizing on fiberglass final-stage cartridges despite unit cost premiums.
- Polyester:Thermoplastic synthetic fibers offering moisture resistance and dimensional stability across temperature cycling. Aftermarket distributors in the Ohio-Indiana manufacturing cluster favor polyester blends for inventory flexibility given cellulose pulp price volatility.
- Foam:Open-cell polyurethane structures serving pre-filter and coarse particulate applications where washability and low restriction outweigh fine capture requirements.
- Cellulose:Wood pulp-based media with established OEM specification heritage, dominant in high-volume engine air applications where cost position governs contract awards.
Cellulose commands the volume base; fiberglass gains share fastest on regulatory efficiency mandates.
Vehicle Type:
Vehicle classification determines duty cycle severity and the economic viability of extended-life filter technologies.
- Passenger Cars:Light-duty applications with standardized filter geometries and high replacement frequency. The I-75 corridor's concentrated logistics networks favor bundled maintenance contracts integrating passenger car filter swaps with oil change intervals.
- Trucks:Heavy-duty diesel platforms with severe-duty dust exposure and the steepest EPA emissions compliance requirements. Texas Gulf Coast petrochemical logistics hubs present whitespace for regional service providers targeting independent truck fleets outside integrated contract networks.
- SUVs:Mid-duty platforms with cabin filtration specification upgrades driving faster media turnover than engine air segments.
- Vans:Commercial delivery configurations with stop-start duty cycles accelerating filter loading rates versus highway-equivalent mileage.
Trucks anchor revenue concentration; SUVs show the steepest specification upgrade trajectory.
Installation Type:
Channel selection locks in margin structure and determines whether buyers optimize for unit economics or total cost of ownership.
- OEM:Captive supply agreements with vehicle manufacturers requiring qualification to proprietary specification protocols. MANN+HUMMEL and Donaldson anchor positions through just-in-time delivery contracts with Midwest assembly operations.
- Aftermarket:Independent distribution through jobbers, retail chains, and e-commerce platforms serving the replacement cycle. K&N Engineering targets this channel with washable performance filters competing on lifetime cost positioning.
- Custom:Application-engineered solutions for specialty equipment, performance modifications, or severe-environment operating conditions.
- Standard:Catalog-fit replacements conforming to SAE dimensional specifications without vehicle-specific engineering adaptation.
Aftermarket captures replacement volume; OEM locks in specification control and captive margins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters along the Midwest automotive corridor while consumption distributes across coastal logistics hubs and state-level regulatory zones. This geographic split shapes inventory positioning and service network density.
Michigan
Detroit's concentrated OEM assembly operations generate captive demand for just-in-time filter supply contracts. EPA Phase 3 Greenhouse Gas Standards compel heavy-duty truck filter media upgrades ahead of 2027 deadlines. Tier 1 suppliers in the Ann Arbor-Detroit corridor maintain localized logistics advantages for JIT delivery to powertrain plants.
Ohio
Freight corridors along I-70 and I-71 sustain replacement demand from long-haul trucking fleets. NHTSA corporate average fuel economy standards pressure filter designs toward lower pressure-drop configurations. Columbus-based distribution hubs serve as consolidation points for aftermarket inventory flowing to independent repair networks.
Texas
Petrochemical logistics hubs on the Gulf Coast present whitespace for regional maintenance contract providers targeting independent truck fleets. California Air Resources Board divergence creates inventory complexity for distributors managing SKU proliferation for cross-border fleet operations. Houston-Dallas freight lanes concentrate severe-duty dust exposure applications.
Indiana
RV and specialty vehicle manufacturing in the Elkhart-Goshen region sustains demand for universal and custom filter configurations. IRA clean vehicle tax credits accelerate hybrid vehicle adoption in fleet segments, sustaining dual-track filter demand. Indianapolis distribution centers anchor Midwest aftermarket replenishment networks.
California
Zero-emission vehicle mandates from the California Air Resources Board create divergent demand signals alongside persistent internal combustion filter requirements. Premium cabin filtration specification concentrates in Los Angeles and San Francisco metro areas where consumer awareness of interior air quality drives upgrades. Port logistics at Long Beach and Oakland sustain heavy-duty fleet replacement cycles.
US Automotive Airfilters Market Competitive Landscape
The competitive structure tilts toward diversified filtration conglomerates with captive media manufacturing capabilities. Tiered supplier relationships separate OEM captive contracts from aftermarket distribution channels. Two strategic archetypes dominate: integrated manufacturers controlling upstream substrate production, and specialized performance brands competing on lifetime cost positioning. Dominant competitive moves include backward integration into nanofiber substrate production and multi-year fleet maintenance contract consolidation.
Within the diversified conglomerate tier, MANN+HUMMEL and Donaldson Company, Inc. exemplify integrated manufacturing models. K&N Engineering, Inc. occupies a position on the performance-specialist vector, representing the washable filter archetype targeting reduced replacement frequency. These three anchors illustrate how supplier positioning fragments between specification-controlled OEM channels and margin-rich aftermarket segments.
| Leading Market Players |
|---|
| MANN+HUMMEL |
| Donaldson Company, Inc. |
| Robert Bosch GmbH |
| MAHLE GmbH |
| Denso Corporation |
| Cummins Filtration |
| Freudenberg Filtration Technologies |
| K&N Engineering, Inc. |
| ACDelco |
| Others |
Value Network & Pricing Analysis
Cellulose pulp futures volatility cascades through Midwest manufacturing corridors, compressing margin structures for traditional media producers while amplifying pricing power for integrated substrate manufacturers. Fleet procurement offices exploit this asymmetry to unbundle component-level contracts, forcing tiered cost absorption across cellulose-dependent suppliers.
Pricing Analysis
Cost-down pressure on standard cellulose media accelerates because packaging industry demand cycles divert pulp supply toward corrugated packaging. Three-tier pricing structure across premium nanofiber, standard synthetic-blend, and economy cellulose levels separates OEM specification tiers. EPA Phase 3 compliance deadlines intensify pricing pressure on heavy-duty diesel applications. Independent repair shops exhibit highest price sensitivity due to exclusion from consolidated fleet maintenance contracts.
Supply Chain Analysis
SAE qualification protocols and OEM specification certification gate entry into captive supply agreements with Detroit and Indiana assembly operations. Germany, China, and Mexico anchor global media substrate supply, with borosilicate glass microfiber drawing from German specialty chemical producers. Single-source electrospinning equipment dependence creates vulnerability to polymer chemistry technician scarcity. Distribution runs through Columbus and Indianapolis consolidation hubs serving Midwest aftermarket networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US automotive airfilters market sits in a technology-transition phase as nanofiber layering displaces monolithic cellulose designs across heavy-duty fleet applications.
For Market Incumbents: Hedge against powertrain electrification timelines by diversifying into battery thermal management filtration media, while consolidating nanofiber substrate production through backward integration into captive electrospinning capacity. EPA regulatory divergence between federal and California standards threatens inventory obsolescence for non-diversified producers. For New Entrants and Emerging Players: IRA clean vehicle tax credits in the United States open a window for hybrid vehicle filter specialists targeting dual-track internal combustion and battery cooling applications. Texas Gulf Coast petrochemical logistics hubs present the most penetrable whitespace for regional maintenance contract providers outside integrated I-75 corridor networks. A fleet telematics partnership strategy bypasses entrenched jobber distribution channels. For Investors and Strategic Acquirers: Distressed-cycle entries favor Midwest-based electrospinning equipment operators with stranded polymer chemistry process IP. Long-term viability hinges on capacity positioning across both internal combustion range-extender and pure battery electric thermal management filtration demand. Watch nanofiber media adoption rates in heavy-duty diesel pre-filter applications as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nanofiber Substrate Production | Captive electrospinning capacity insulates margin structures from cellulose pulp volatility and single-source equipment dependence. |
| Multi-Year Fleet Maintenance Contract Consolidation | Bundled filter-fluid-inspection agreements lock in recurring revenue concentration across I-75 corridor logistics providers. |
| Battery Thermal Management Filtration Development | Parallel product lines for electric vehicle cooling systems hedge against internal combustion engine filter demand erosion. |
| Texas Gulf Coast Service Network Expansion | Independent heavy-duty fleet whitespace outside integrated contract structures offers regional margin capture opportunities. |
| Wearable Filter Cartridge Platform Standardization | Modular pre-filter and final-stage architectures reduce per-service labor hours for centralized fleet maintenance depots. |
Research Methodology
Document review covered EPA regulatory filings, NHTSA CAFE standard documentation, and vehicle production databases, complemented by interviews with Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distribution channel managers, and fleet maintenance operations heads. Secondary validation drew from SEC 10-K disclosures, customs trade data, and IHS Markit registration statistics. Bottom-up filter unit economics triangulated against top-down automotive production forecasts.
Value outputs across the projection horizon reflect segmentation by filter type, material substrate, vehicle classification, and installation channel, with propulsion architecture as an industry-specific overlay. CAGRs derived from historical replacement cycle analysis, fleet electrification scenario modeling, and regulatory compliance timeline impacts. Cellulose pulp price indices and nanofiber media penetration curves served as key forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for battery electric vehicle thermal management filtration would alter the outlook for traditional engine air filter demand trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Malaysia Brake Pads Market
Automotive Parts
Thailand Automotive Lubricants Market
Automotive Parts
Automotive Slack Adjuster Market
Automotive Parts
Resin Silencer Market
Automotive Parts
France Automotive Lubricants Market
Automotive Parts
Suspension Bump Stopper Market
Automotive Parts
South Africa Automotive Lubricants Market
Automotive Parts
Japan Commercial Vehicles Lubricants Market
Automotive Parts
Motorcycle Aluminum Casting Market
Automotive Parts
Automotive Thermal Management Systems for Electric Vehicles Market
Automotive Parts
Automotive Pinion Gear Market
Automotive Parts
Nigeria Automotive Engine Oils Market
Automotive Parts
Nigeria Passenger Vehicles Lubricants Market
Automotive Parts
Electric Power Steering System (EPS) Market
Automotive Parts
Global Automotive Selective Catalytic Reduction System Market
Automotive Parts
Global Rubber Transmission Belts Market