
 Civil Aircraft Tire Market | 2026-2036
Civil Aircraft Tire Market Size, Share, and Industry Trends Forecast 2026-2036
Civil Aircraft Tire Market Insights
China is narrowing the civil aircraft tire supply gap through domestic capacity expansion for narrowbody programs. Michelin leverages vertical integration across rubber sourcing and retreading networks to sustain its position in OEM channels. Bridgestone Corporation anchors its competitiveness through R&D intensity focused on heat-resistant tread compounds for high-cycle operations.
Civil aircraft tires are reinforced rubber-composite structures designed to withstand extreme landing loads, thermal cycling, and burst pressures exceeding 200 psi while supporting aircraft weights from regional jets to widebodies. Radial tires now lead the product type segment due to superior heat dissipation and extended cycle life on long-haul routes. Bias tires still occupy significant share in regional and cargo fleets where cost sensitivity and retrofit compatibility drive procurement.
FAA certification under Technical Standard Order C62e and EASA's CS-25 airworthiness requirements shape tire performance benchmarks for load rating, speed capability, and hydroplaning resistance. The EU's REACH chemicals framework and emerging sustainability disclosure rules are forcing material transparency across synthetic rubber and aramid fiber supply chains. Stakeholders must monitor regulatory divergence between US and European tire retread standards as dual-certification costs reshape supplier economics.
Market Dynamics
Radial tire architecture is displacing bias-ply designs across narrowbody and widebody fleets as operators prioritize heat dissipation and extended cycle life under FAA Technical Standard Order C62e certification pressure.
Growth Catalysts
- Fleet renewal mandates:Asia-Pacific airlines are accelerating narrowbody replacements to meet EASA CS-25 airworthiness benchmarks for hydroplaning resistance and load rating.
- REACH chemicals framework:The EU's material transparency rules are forcing synthetic rubber and aramid fiber suppliers to document supply chains, advantaging certified tier-one vendors.
- Retread network densification:MRO facilities across India and Southeast Asia are expanding cold-bond retreading capacity to capture cost-sensitive regional carrier demand.
Market Restraints
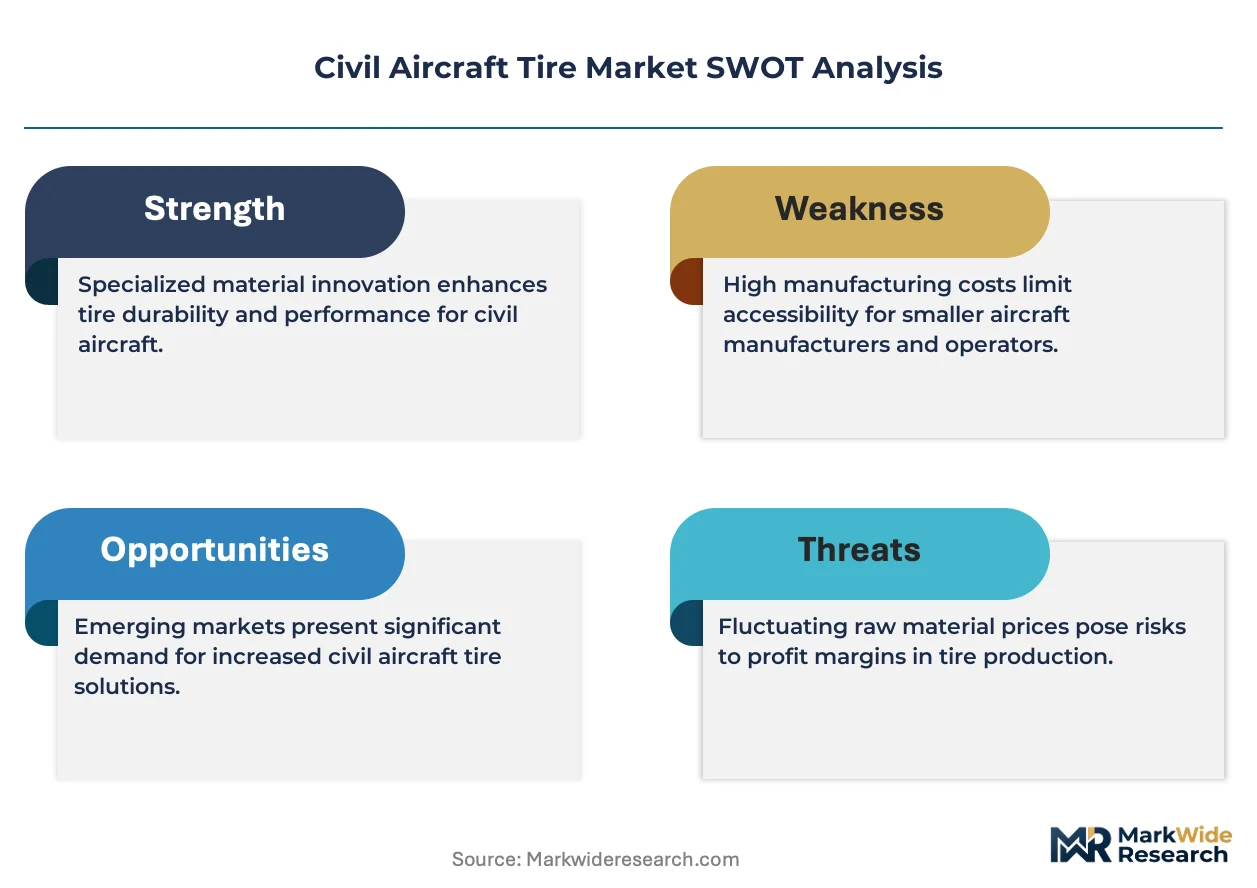
- Natural rubber price volatility:Thai and Indonesian latex supply disruptions transmit directly to tire compound cost structures with limited hedging mechanisms.
- OEM supply concentration:Three integrated rubber-cord-tire producers control the majority of certified narrowbody tire supply, creating single-source risk for airlines.
- Dual-certification friction:Divergent FAA and EASA retread standards force suppliers to maintain parallel testing protocols, elevating compliance overhead.
Strategic Opportunities
- COMAC narrowbody ramp:China's C919 production buildout creates captive demand for domestically certified radial tires with import substitution tailwinds.
- Sustainability-linked procurement:EU CSRD disclosure rules are embedding lifecycle carbon metrics into airline tire sourcing RFPs, favoring retreadable designs.
- Predictive maintenance integration:Tire pressure monitoring systems are converging with fleet IoT platforms to enable condition-based replacement scheduling.
Industry Challenges
- Specialized compound formulation talent:Heat-resistant tread chemistry expertise concentrates among a shrinking cohort of rubber technologists with aviation certification experience.
- Extended airworthiness qualification timelines:FAA TSO-C62e and EASA CS-25 approval cycles stretch 18-24 months for new tire designs, compressing product refresh windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Civil Aircraft Tire Market |
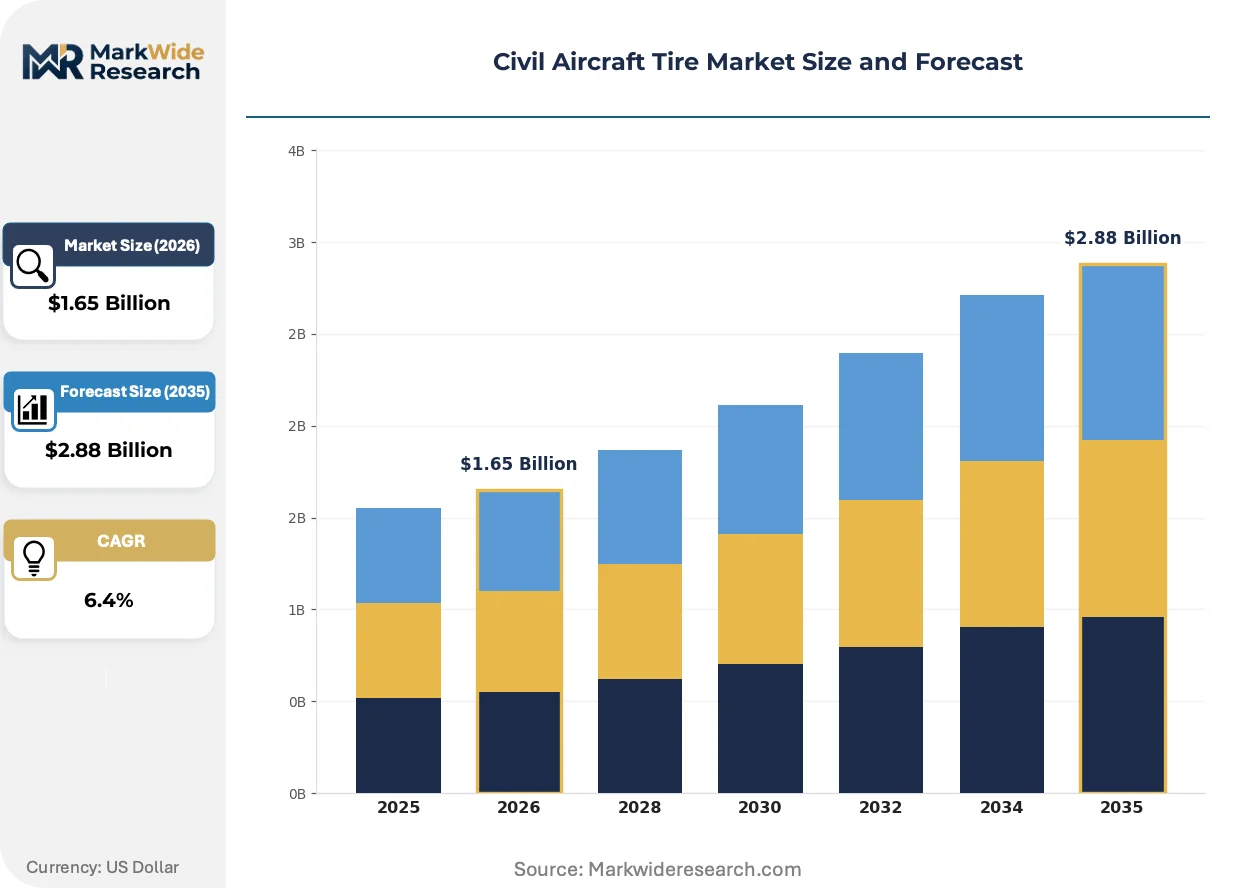
| Market Size in 2026 | $1.65 Billion |
| Market Size in 2035 | $2.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Main Gear Tires, Nose Gear Tires, Radial Tires, Bias Tires Material: Rubber, Composite, Synthetic, Fabric End User: Airlines, Military, Cargo Carriers, Maintenance Providers Size: Small Aircraft Tires, Medium Aircraft Tires, Large Aircraft Tires, Ultra-Large Aircraft Tires |
| Companies Covered | Michelin, Goodyear Tire and Rubber Company, Bridgestone Corporation, Dunlop Aircraft Tyres, Qingdao Sentury Tire, Specialty Tires of America, Wilkerson Company, Aviation Tires and Treads, Petlas Tire Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Civil Aircraft Tire Market Trends and Innovations
Material science advances and regulatory disclosure mandates are restructuring how tires are specified, tracked, and retired across commercial aviation fleets.
Silica-reinforced tread compounds are replacing carbon-black dominant formulations to reduce rolling resistance and thermal buildup during high-cycle operations. Low-cost carriers operating dense narrowbody networks are adopting these compounds fastest to extend tire life between overhauls. The technology is migrating from premium widebody applications into regional and single-aisle segments, compressing the performance gap between tire tiers.
EASA's CS-25 airworthiness requirements are tightening burst pressure and speed rating thresholds for new type certifications. Tire manufacturers must now submit extended fatigue test data under variable thermal loading conditions. Narrowbody OEM tire suppliers face the steepest compliance cost escalation as they serve the highest-volume, most price-sensitive procurement channels.
Airlines are unbundling tire procurement from airframe purchase agreements to capture aftermarket retreading economics. Large fleet operators are establishing direct relationships with retread specialists, bypassing traditional OEM-locked distribution. This pattern is most pronounced among Asia-Pacific low-cost carriers with centralized maintenance operations and high aircraft utilization rates.
Civil Aircraft Tire Market Segmentation
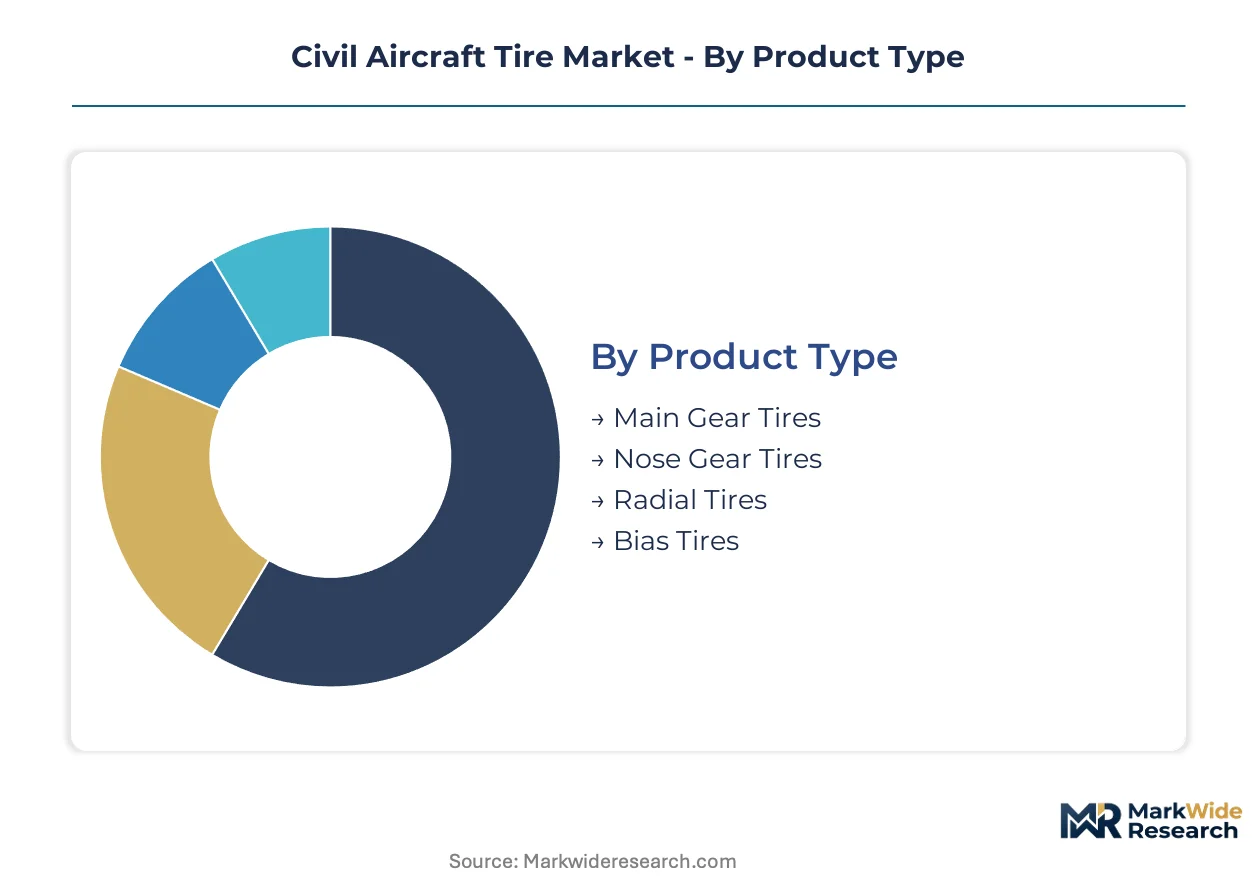
Civil aircraft tire procurement splits across technical specifications, operational profiles, and regulatory tiers. Each segmentation axis reveals distinct margin structures and supplier concentration patterns that shape competitive positioning.
Product Type:
Mature radial architectures now dominate commercial fleets while bias-ply designs persist in specialized applications where retrofit economics override performance premiums.
- Main Gear Tires:These structures absorb maximum landing loads and braking torque on multi-axle truck assemblies. Demand concentrates among narrowbody operators in China and Southeast Asia as COMAC and Airbus A320neo fleets expand. Heat-resistant tread compounds from certified tier-one vendors command procurement preference under FAA TSO-C62e.
- Nose Gear Tires:Smaller diameter specifications prioritize hydroplaning resistance and steering response over pure load capacity. Regional carriers operating high-frequency short-haul networks in India drive replacement volumes through accelerated wear cycles.
- Radial Tires:Steel-belted carcass construction delivers superior heat dissipation for long-haul operations. Adoption accelerates across widebody fleets serving transpacific routes.
- Bias Tires:Cross-ply nylon cord construction retains cost advantage for cargo conversions and legacy fleet extensions. Procurement persists among freight operators in Indonesia and Vietnam.
Main gear tires retain volume leadership; radial tires hold the steepest expansion curve.
Material:
Cost tiers separate commodity rubber formulations from engineered composites requiring specialized curing equipment and aviation certification.
- Rubber:Natural latex and synthetic polybutadiene blends form the base compound matrix. Thai supply disruptions transmit directly to tire manufacturer cost structures with limited hedging mechanisms.
- Composite:Carbon fiber and aramid reinforcement layers reduce weight while maintaining burst pressure ratings. Narrowbody OEM channels in China specify these materials for C919 production ramp.
- Synthetic:Oil-derived polymers enable consistent performance across temperature extremes. EASA REACH documentation requirements favor established European compound suppliers.
- Fabric:Nylon and polyester cord plies provide structural integrity in bias-ply architectures. Demand clusters among regional MRO retreading facilities in Malaysia and Thailand.
Rubber compounds anchor procurement volumes; composite reinforcement claims the fastest share gains.
End User:
Customer type determines certification burden, contract duration, and aftermarket service bundling intensity.
- Airlines:Full-service and low-cost carriers negotiate multi-year tire supply agreements tied to airframe deliveries. Unbundling from OEM packages enables direct retread relationships.
- Military:Defense procurement channels require ITAR compliance and domestic sourcing mandates. Specifications prioritize field repairability over commercial cycle life metrics.
- Cargo Carriers:Dedicated freighter operators maximize tire utilization through aggressive retread policies. Centralized maintenance hubs in Singapore and Dubai optimize turnaround economics.
- Maintenance Providers:Independent MRO facilities capture aftermarket value through cold-bond retreading and pressure monitoring integration. Certification scope limits competitive entry.
Airlines generate the dominant revenue share; cargo carriers are climbing the fastest on e-commerce fleet expansion.
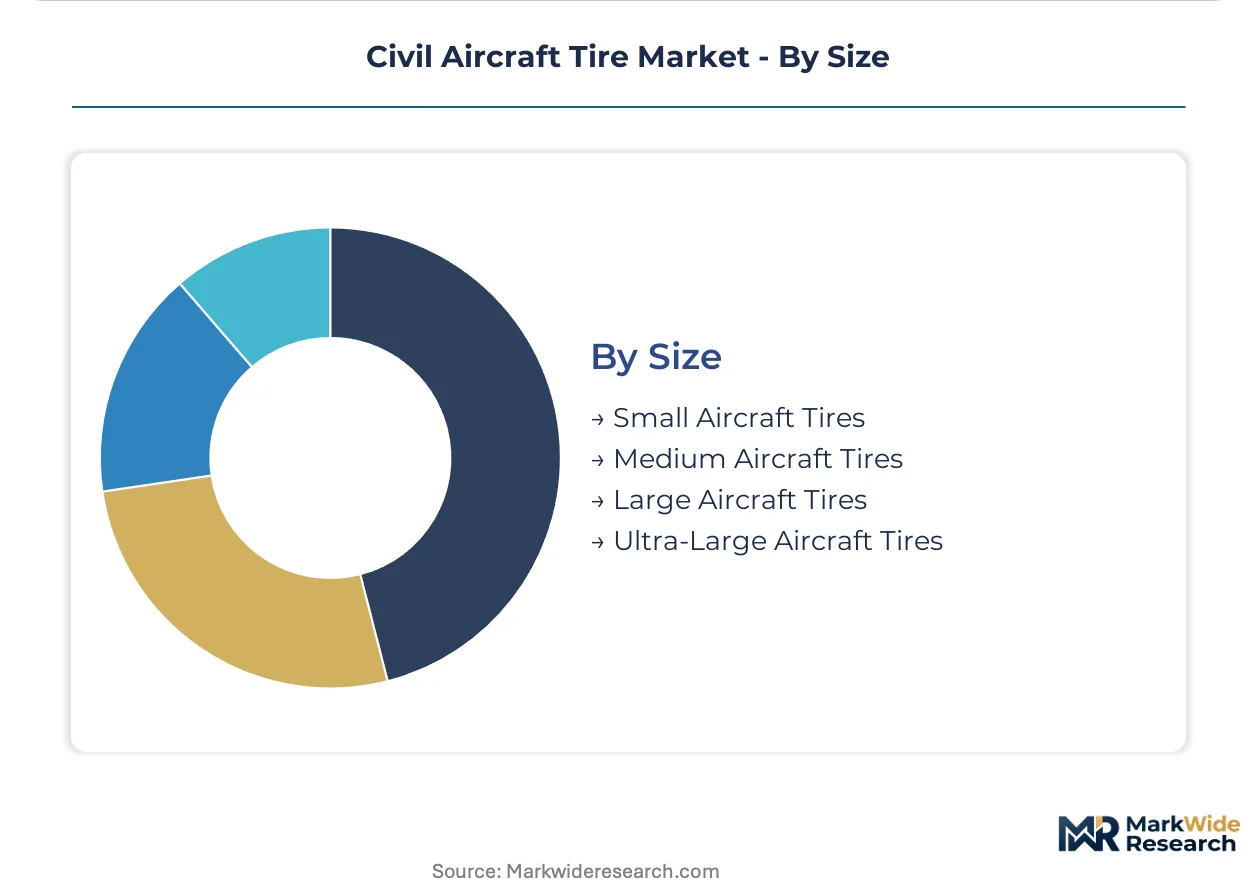
Size:
Application scale dictates mold investment, testing protocol complexity, and supplier qualification barriers.
- Small Aircraft Tires:General aviation and regional turboprop specifications below 24-inch diameter. Procurement fragments across numerous part-number configurations.
- Medium Aircraft Tires:Single-aisle narrowbody main and nose gear dimensions. Volume concentration attracts dedicated production lines from certified manufacturers.
- Large Aircraft Tires:Widebody twin-aisle and long-haul specifications demanding advanced heat dissipation. Boeing 787 and Airbus A350 programs anchor demand.
- Ultra-Large Aircraft Tires:Superjumbo and specialized freighter dimensions above 50-inch diameter. Limited qualified suppliers create concentrated supply risk for A380 and 747-8 operators.
Medium aircraft tires retain volume leadership; ultra-large aircraft tires hold the steepest expansion curve on freighter conversions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Pudong-Shanghai aviation cluster anchors China's tire demand as COMAC scales C919 production. Frankfurt Airport's cargo throughput sustains German MRO retreading density. Dubai International's hub status concentrates Gulf fleet procurement decisions.
United States
Boeing's 737 MAX production recovery drives narrowbody tire demand through Washington and South Carolina assembly lines. FAA TSO-C62e certification timelines stretch supplier qualification windows. The Wichita, Kansas aviation corridor hosts specialized tire distribution infrastructure serving regional carrier networks.
China
COMAC's C919 production ramp generates captive demand for domestically certified radial tires. MIIT domestic content mandates accelerate import substitution across synthetic rubber supply chains. The Pudong-Shanghai cluster concentrates tire testing and certification infrastructure for narrowbody programs.
Germany
Lufthansa Technik's MRO scale sustains European retreading economics through Hamburg and Frankfurt facilities. EASA REACH documentation requirements favor established compound suppliers with full material traceability. The Baden-Württemberg automotive belt supplies specialized curing equipment to aviation tire producers.
India
IndiGo and Air India's narrowbody fleet expansion drives replacement tire volumes through Delhi-Mumbai corridors. DGFT import licensing for aviation-grade natural rubber creates procurement friction for domestic blenders. The Chennai aviation maintenance cluster is expanding cold-bond retreading capacity for regional operators.
Japan
ANA and JAL's widebody operations sustain demand for heat-resistant radial specifications on transpacific routes. METI industrial standards align with EASA burst pressure benchmarks for export compatibility. The Nagoya aerospace corridor integrates tire logistics with Mitsubishi Heavy Industries' regional jet support networks.
Civil Aircraft Tire Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in rubber compounding and cord reinforcement. Three integrated producers control certified narrowbody supply, creating tier-one concentration against a fragmented retread services layer. Archetypes span full-stack rubber-to-tire manufacturers, specialized aviation compounders, and regional MRO service consolidators. Capacity expansion and backward integration into natural rubber sourcing represent the dominant competitive vectors.
Among French and Japanese tire conglomerates, Michelin and Bridgestone Corporation occupy positions exemplifying full-stack integration from rubber cultivation through OEM certification. Dunlop Aircraft Tyres represents the specialist archetype focused exclusively on aviation-grade specifications. These anchors demonstrate how geographic origin and corporate structure shape competitive positioning within a certification-intensive procurement environment.
| Leading Market Players |
|---|
| Michelin |
| Goodyear Tire and Rubber Company |
| Bridgestone Corporation |
| Dunlop Aircraft Tyres |
| Qingdao Sentury Tire |
| Specialty Tires of America |
| Wilkerson Company |
| Aviation Tires and Treads |
| Petlas Tire Corporation |
| Others |
Pricing and Supply Chain Analysis
Thai and Indonesian latex cultivation concentrates upstream supply for natural rubber feedstocks, anchoring margin pools with certified compounders who command tier-one OEM pricing premiums. Aviation-grade aramid fiber production in the United States and Japan further concentrates reinforcement material supply, forcing tire manufacturers to absorb cost volatility or pass through to airline procurement contracts.
Pricing Analysis
FAA TSO-C62e and EASA CS-25 certification tiers dictate the pricing structure across civil aircraft tire procurement. Three-tier pricing stratifies across OEM-certified premium, aftermarket-standard, and retread-economy levels, with certification grade and volume scale as the primary price differentiation drivers. Cost compression in the retread tier is intensifying because regional carriers in Southeast Asia are consolidating maintenance spend. Low-cost carriers operating narrowbody fleets exhibit highest price sensitivity; widebody long-haul operators prioritize cycle life over unit cost.
Supply Chain Analysis
ITAR and dual-use export controls restrict aramid fiber and specialized curing equipment flows between defense-linked suppliers and commercial aviation channels. Geographic supply concentrates in Thailand for natural rubber, China for synthetic polybutadiene, and the United States for aramid reinforcement. Raw material dependencies rest on latex harvest cycles, oil-derived polymer feedstocks, and carbon fiber cord. Single-source vulnerability sits with certified narrowbody tire mold production. Distribution runs through OEM-locked channels for new tires and independent MRO networks for retread services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Domestic Chinese tire certification for COMAC programs presents a substitution threat that incumbent suppliers must navigate through accelerated local partnership structures.
For Market Incumbents: Harden supply security through backward integration into Thai latex processing and captive aramid fiber supply from Japanese partners. Defend OEM channel position by embedding tire pressure monitoring data into airline fleet IoT platforms, creating switching costs against retread specialists. Prioritize dual-certification investment to capture EASA CS-25 and FAA TSO-C62e overlap demand. For New Entrants and Emerging Players: India's cold-bond retread capacity expansion offers the most penetrable white-space entry point, with IndiGo and Air India's centralized maintenance operations creating concentrated demand. Target cargo carrier segments in Indonesia and Vietnam where bias-ply retrofit economics override brand loyalty. Establish direct airline relationships bypassing OEM-locked distribution through sustainability-linked lifecycle carbon metrics. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional MRO consolidators across Southeast Asia holding retread certification scope. Long-term viability hinges on exposure to narrowbody fleet renewal waves and COMAC import substitution tailwinds. Watch for EASA REACH compliance cost escalation as the signal for tier-two supplier distress and consolidation opportunity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Natural Rubber Processing | Captive Thai latex supply insulates compound cost structures from harvest volatility. |
| Dual-Certification Investment for FAA and EASA Alignment | Parallel TSO-C62e and CS-25 approval unlocks airline procurement across regulatory jurisdictions. |
| Retread Network Densification in Southeast Asia | Cold-bond capacity expansion in Chennai and Bangkok captures regional carrier aftermarket spend. |
| Predictive Maintenance Platform Integration | Tire pressure monitoring convergence with fleet IoT enables condition-based replacement scheduling. |
| COMAC C919 Domestic Certification Partnership | MIIT content mandates create captive demand for locally certified radial tire supply. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with airline procurement directors, MRO facility managers, tire compound R&D leads, and aviation regulatory compliance officers. Secondary validation drew from FAA TSO-C62e certification databases, EASA CS-25 airworthiness filings, customs trade records for natural rubber and aramid fiber, and SEC disclosures from integrated tire manufacturers. Bottom-up fleet expansion models and top-down OEM delivery schedules were triangulated to anchor volume estimates.
Calibration against historical certification timelines and production ramp patterns shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, material composition, end-user type, and aircraft size tier. CAGRs were derived from fleet renewal schedules and replacement cycle frequencies. Forecast inputs incorporated COMAC delivery targets, EASA REACH compliance cost trajectories, and retread adoption rates by carrier business model.
Macroeconomic conditions sit as an overlay; deviation in jet fuel prices, air travel demand recovery, and natural rubber futures would shift the trajectory. Forecasts reflect documented assumptions about certification timeline stability and supply chain concentration persistence. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Automotive Retread Tires Market
Tires and Wheels
Automotive Green Tires Market
Tires and Wheels
Europe Aircraft Tires Market
Tires and Wheels
Rechargeable Tires Market
Tires and Wheels
Wheel Spacers and Adapters Market
Tires and Wheels
Automotive Wheel Rims Market
Tires and Wheels
Wheel and Tire Service Equipment Market
Tires and Wheels
Wheel Cover Market
Tires and Wheels
E-Bike Tire Market
Tires and Wheels
Asia-Pacific Alloy Wheels Market
Tires and Wheels
Self-Healing Tire Market
Tires and Wheels
Global Tire Curing Press Market
Tires and Wheels
North America Alloy Wheels Market
Tires and Wheels
Asia Pacific 2-Wheeler Tire Market
Tires and Wheels
Zeropressure Tires Market
Tires and Wheels
Europe Tire Market