
 Automotive Oil Pressure Switch Market | 2026-2036
Automotive Oil Pressure Switch Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Oil Pressure Switch Market Outlook
The automotive oil pressure switch market is recalibrating around a widening gap between premium solid-state units for electrified powertrains and commodity mechanical switches serving internal combustion fleets. Bosch leverages its Tier-1 supplier relationships to dominate integrated sensor modules for European OEM platforms. Standard Motor Products, Inc. anchors the North American aftermarket through extensive channel control and SKU breadth for legacy vehicle parc maintenance.
An automotive oil pressure switch is a sensing device that monitors lubricant pressure within an engine block, typically employing a diaphragm-actuated contact mechanism calibrated between 5 and 100 psi to trigger dashboard warnings or ECU protective shutdowns. Its primary purpose is preventing catastrophic engine damage from oil starvation during cold starts, high-RPM operation, or degraded pump performance. Electrical and digital product types command expanding margin pools as automakers phase out analog gauges in favor of CAN-bus-integrated instrument clusters. Solid-state operating mechanisms are displacing traditional switch-based architectures in premium segments where vibration resistance and million-cycle durability justify unit cost premiums.
The US NHTSA enforces functional safety expectations through FMVSS compliance pathways that pressure sensor suppliers toward ISO 26262-aligned design processes. China's MIIT and GB standards bodies impose localized electromagnetic compatibility and environmental sealing requirements that condition market access for foreign manufacturers. Stakeholders must weigh backward integration into MEMS fabrication against specialized foundry partnerships as transistor-based designs capture share from electromechanical predecessors.
Market Dynamics
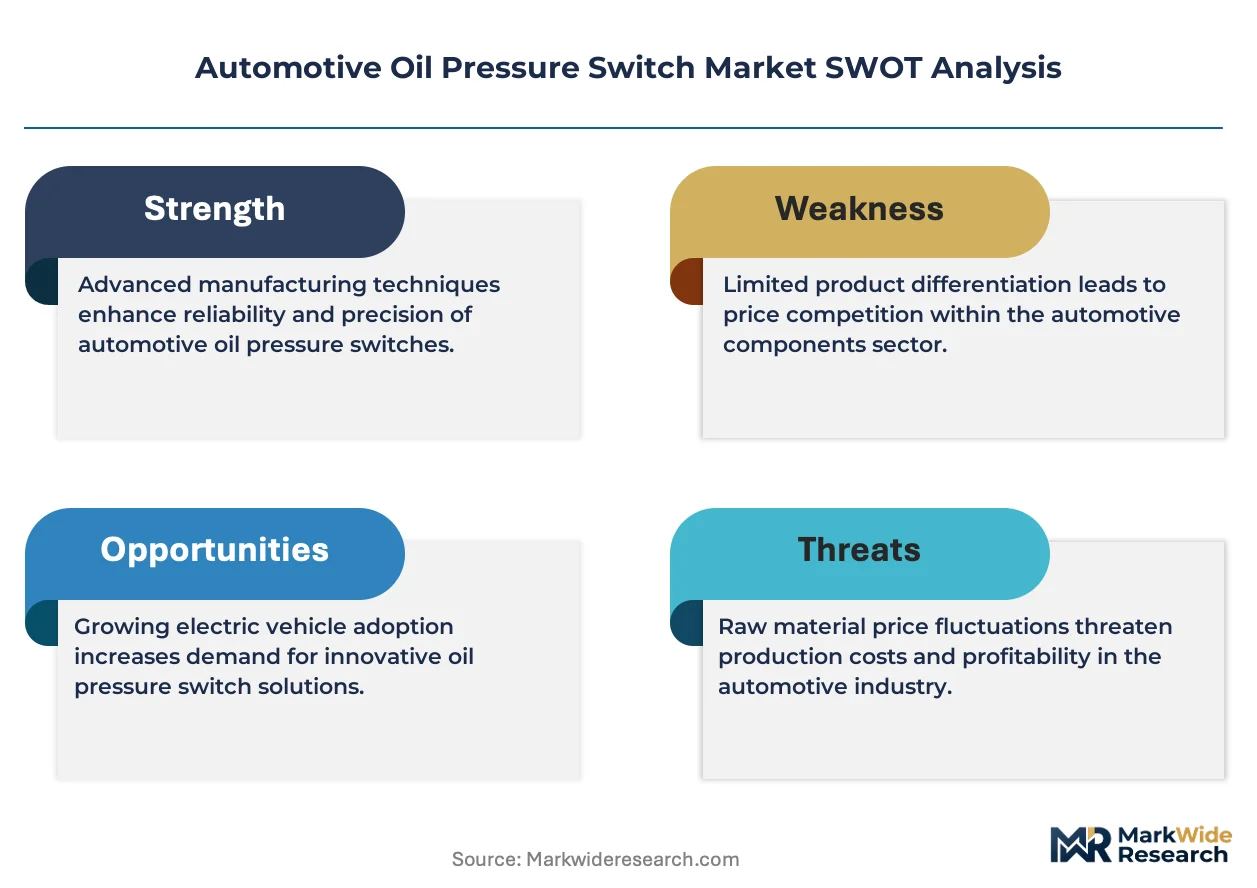
Solid-state MEMS architectures are compressing the addressable market for electromechanical diaphragm switches as powertrain electrification accelerates and thermal management systems demand million-cycle durability thresholds.
Growth Catalysts
- MIIT sensor reliability mandates:China's Ministry of Industry and Information Technology now requires enhanced electromagnetic compatibility and environmental sealing for domestic vehicle platforms, forcing Tier-1 suppliers to upgrade certification portfolios.
- Powertrain electrification:Battery thermal management systems in electric vehicles deploy redundant pressure sensing for coolant loop integrity, creating parallel demand streams alongside traditional engine lubrication monitoring.
- Heavy-duty mechanical switch demand:United States truck and SUV production sustains commodity switch volumes for internal combustion fleets with extended service life requirements.
Market Restraints
- Silicon wafer cost volatility:MEMS fabrication feedstock prices fluctuate with semiconductor cycle dynamics, compressing margins for solid-state switch manufacturers without captive foundry access.
- Electromechanical switch commoditization:Diaphragm-actuated contact mechanisms face price erosion as Chinese domestic suppliers flood aftermarket channels with unbranded alternatives.
- ISO 26262 compliance friction:Functional safety certification for automotive ASIL ratings extends development timelines and diverts engineering resources from feature differentiation.
Strategic Opportunities
- India commercial vehicle electrification:Bureau of Indian Standards is drafting localized sensor specifications for emerging electric bus and logistics truck platforms.
- CAN-bus integration convergence:Digital output switches combining pressure sensing with LIN or CAN transceivers capture value from analog gauge replacement cycles.
- Aftermarket channel consolidation:Specialized distributors with diagnostic tool integration capabilities are displacing traditional jobber networks for sensor replacement demand.
Industry Challenges
- MEMS process engineering talent scarcity:Deep expertise in wafer-level packaging and hermetic sealing for automotive environments concentrates at a handful of specialized foundries and IDMs.
- Legacy ECU integration complexity:Backward compatibility with 1990s-era engine control modules constrains firmware architecture choices for next-generation digital switches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Oil Pressure Switch Market |
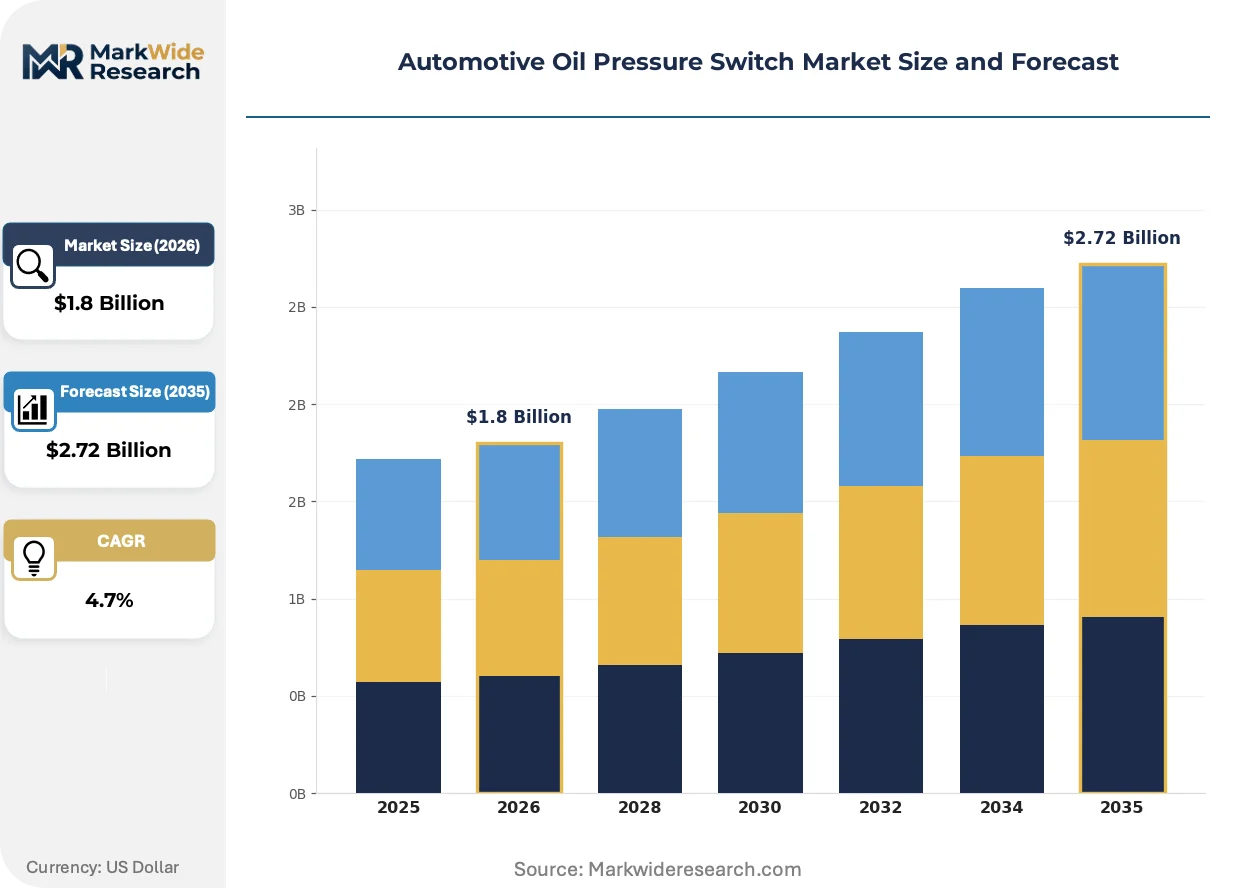
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical, Electrical, Digital, Analog Installation Type: Inline, Integrated, Standalone, Modular End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Operating Mechanism: Transistor-Based, Switch-Based, Relay-Based, Solid-State |
| Companies Covered | Bitron Industrie S.p.A, Standard Motor Products, Inc., Amphenol Advanced Sensors, Tecmark Corporation, Francisco Albero S.A.U., Bosch, HELLA, DENSO Corporation, Delphi Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Oil Pressure Switch Market Strategic Shifts
Automotive oil pressure sensing is bifurcating into premium solid-state modules for electrified platforms and cost-optimized mechanical units for legacy fleet maintenance, with interface standardization and fabrication economics determining competitive outcomes.
Capacitive MEMS pressure transducers are electrifying the sensing layer by eliminating moving parts entirely. European OEMs specify these for battery coolant monitoring and transmission fluid circuits. The technology is electrifying supplier R&D allocation away from diaphragm metallurgy toward wafer-level vacuum sealing and ASIC integration.
China's GB/T standards bodies are tightening electromagnetic compatibility test protocols for automotive sensors. Foreign manufacturers must redesign shielding architectures and submit to localized testing regimens. Solid-state suppliers with existing MIIT certification pipelines capture first-mover advantage against mechanical switch incumbents.
Fleet operators are compressing sensor replacement cycles through predictive maintenance platforms that flag degradation before dashboard illumination. Telematics-integrated service networks in North America now trigger proactive part dispatch based on pressure waveform anomaly detection. This pattern is most visible in long-haul trucking where downtime costs dwarf component replacement expenses.
Automotive Oil Pressure Switch Market Segmentation
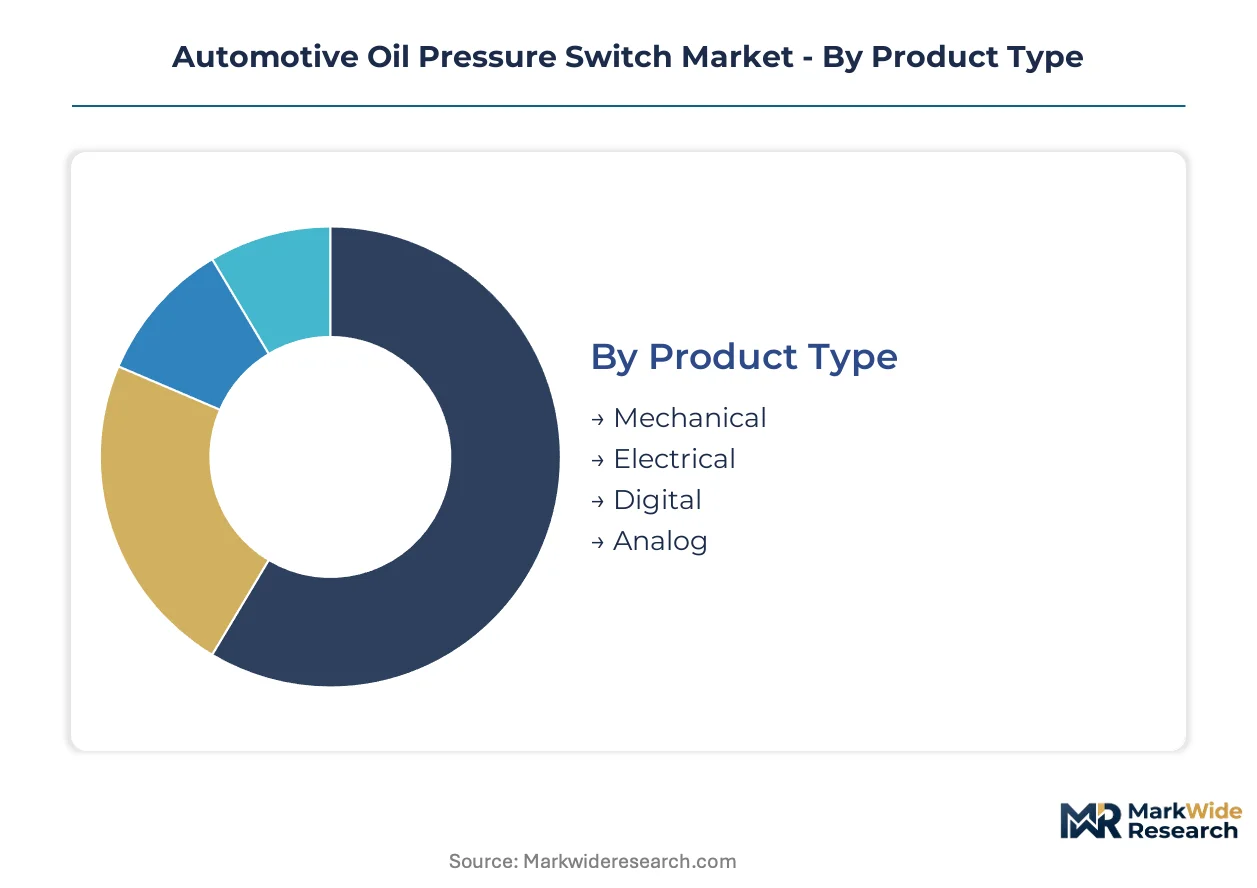
Segmentation in automotive oil pressure switches reveals how powertrain electrification and legacy fleet maintenance create divergent demand profiles. Each axis—product technology, installation architecture, customer type, and operating principle—carries distinct margin structures and certification requirements that reshape supplier positioning.
Product Type:
Solid-state and electromechanical architectures are diverging along powertrain electrification fault lines, with transistor-based designs commanding premium positioning in battery thermal management while diaphragm mechanisms retain cost-sensitive internal combustion applications.
- Mechanical:Diaphragm-actuated contact mechanisms calibrated between 5 and 100 psi dominate legacy truck and SUV production in the United States, where extended service life requirements and price sensitivity preserve commodity volumes. Heavy-duty fleet operators specify these for million-mile durability targets despite slower response times.
- Electrical:Variable resistance output switches bridge analog gauge systems and early ECU architectures, capturing replacement demand in 1990s-2000s vehicle parc maintenance. North American aftermarket distributors stock these for backward compatibility with legacy instrument clusters.
- Digital:CAN-bus-integrated switches with LIN transceiver outputs are displacing analog alternatives as European OEMs mandate unified sensor networks for instrument cluster consolidation.
- Analog:Continuous voltage output devices serve specialized industrial vehicle applications requiring direct gauge drive without microcontroller intermediation.
Mature deployment sits with Mechanical switches. Newer deployment is concentrated in Digital architectures.
Installation Type:
Packaging density and thermal management integration are redefining how pressure sensing modules attach to engine blocks, transmission housings, and battery coolant loops.
- Inline:Threaded port-mounted switches with standardized M10x1 or 1/8 NPT fittings dominate aftermarket replacement cycles due to minimal installation tooling requirements.
- Integrated:Multi-sensor modules combining pressure, temperature, and flow sensing in single housings are expanding most quickly in battery electric vehicle thermal management systems, where space constraints and wiring complexity reduction drive consolidation.
- Standalone:Discrete switches with dedicated electrical connectors persist in commercial vehicle applications requiring field-serviceable component isolation.
- Modular:Swappable sensor cartridges within common housing platforms enable platform-spanning procurement flexibility for multi-powertrain vehicle families.
Standalone architectures anchor legacy fleet maintenance. Integrated modules are gaining share fastest in electrified platform launches.
End User:
Procurement authority is fragmenting across vehicle lifecycle stages, with specification power shifting from assemblers toward Tier-1 module suppliers and predictive maintenance platform operators.
- OEMs:Vehicle manufacturers specify solid-state MEMS switches for new platform development, leveraging ISO 26262 certification requirements to consolidate supplier bases around ASIL-capable vendors.
- Aftermarket Providers:Specialized distributors with diagnostic tool integration capabilities are displacing traditional jobber networks, capturing sensor replacement demand through telematics-triggered proactive dispatch.
- Tier-1 Suppliers:Integrated module manufacturers aggregate pressure sensing with pump control and filtration monitoring, backward integrating into MEMS fabrication to secure margin capture.
- Vehicle Assemblers:Contract manufacturing partners in emerging markets source mechanical switches through localized procurement to satisfy domestic content requirements.
Aftermarket Providers command replacement cycle compression. Tier-1 Suppliers are consolidating specification authority in new vehicle development.
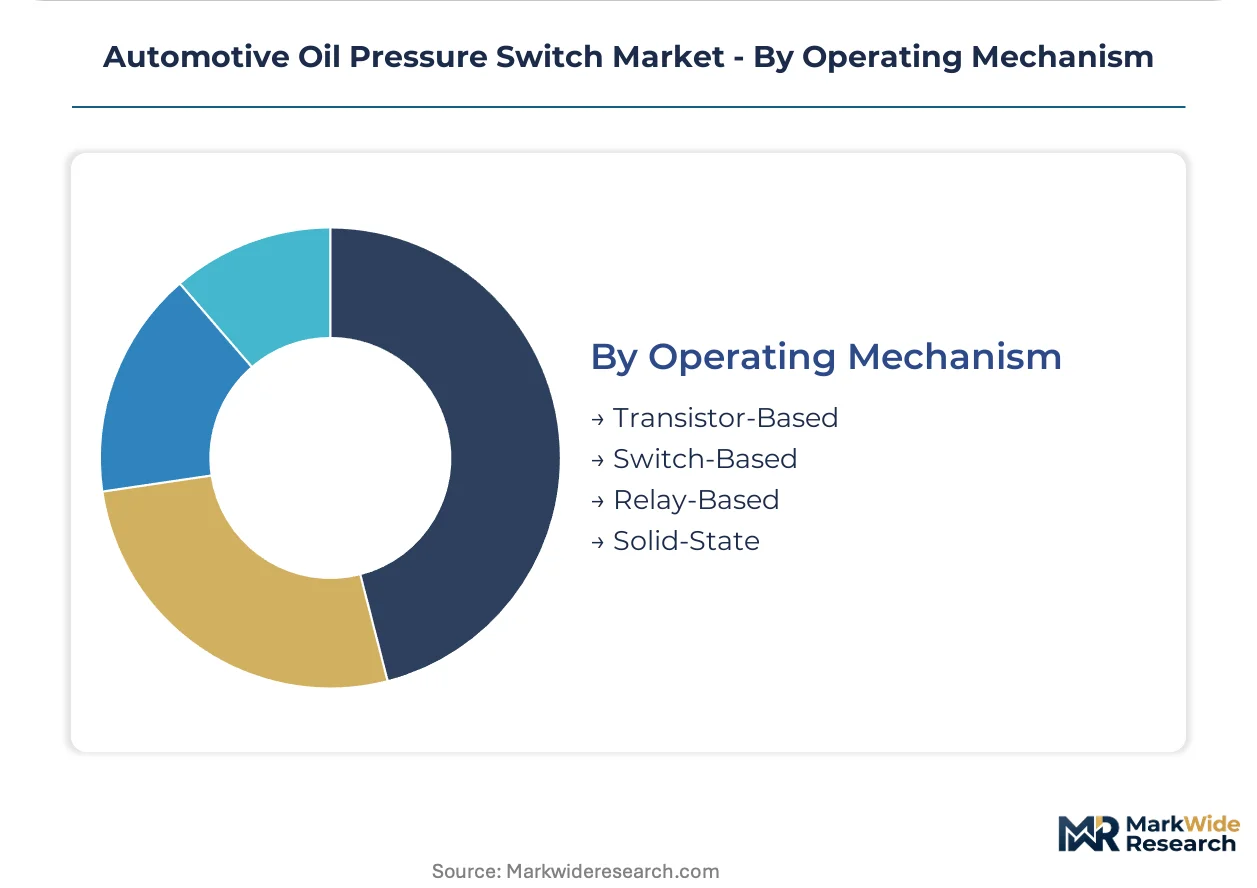
Operating Mechanism:
Physics-based sensing principles are stratifying across durability, response time, and electromagnetic immunity requirements.
- Transistor-Based:Piezoresistive MEMS elements with ASIC signal conditioning achieve million-cycle durability and microsecond response times, justifying unit cost premiums in battery coolant loop monitoring where thermal runaway detection is critical.
- Switch-Based:Bimetallic and diaphragm contact mechanisms face price erosion as Chinese domestic suppliers flood aftermarket channels, though they retain position in high-vibration commercial engine compartments where simplicity equals reliability.
- Relay-Based:Electromechanical isolation switches serve heavy-duty applications requiring galvanic separation between sensing element and high-current warning lamp circuits.
- Solid-State:Capacitive MEMS transducers eliminate moving parts entirely, with European OEMs specifying these for transmission fluid and battery thermal circuits.
Switch-Based mechanisms anchor installed base maintenance. Solid-State designs are climbing the fastest in electrified powertrain specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Detroit's automotive corridor sustains heavy-duty mechanical switch demand as domestic truck and SUV production lines maintain extended service life specifications for internal combustion fleets.
United States
NHTSA functional safety expectations through FMVSS compliance pathways pressure sensor suppliers toward ISO 26262-aligned design processes. The agency's enforcement patterns favor ASIL-capable vendors in procurement cycles. Michigan and Ohio manufacturing clusters concentrate electromechanical switch fabrication for legacy fleet maintenance.
Germany
European OEMs specify capacitive MEMS transducers for transmission fluid and battery thermal circuits as powertrain electrification accelerates. KBA type-approval requirements condition market access for foreign manufacturers. Stuttgart and Munich automotive engineering centers drive solid-state sensor integration into unified CAN-bus networks.
China
MIIT mandates stricter sensor reliability standards for domestic vehicle platforms, forcing Tier-1 suppliers to upgrade certification portfolios. GB/T standards bodies tighten electromagnetic compatibility test protocols for automotive sensors. Shanghai and Guangzhou manufacturing corridors absorb MEMS fabrication investment for localized supply security.
Japan
METI industrial policy directs precision sensor manufacturing toward automotive electrification applications. JIS standards alignment remains prerequisite for Tier-1 supplier qualification. Nagoya and Tokyo-Yokohama industrial zones concentrate piezoresistive MEMS development for million-cycle durability thresholds.
India
Bureau of Indian Standards drafts localized sensor specifications for emerging electric bus and logistics truck platforms. PLI scheme incentives attract component manufacturing investment for domestic content requirements. Pune and Chennai automotive clusters expand procurement of solid-state switches as commercial vehicle electrification intensifies.
Automotive Oil Pressure Switch Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification tier and powertrain integration depth, with ASIL-capable MEMS fabricators commanding specification authority in new platform development while mechanical switch specialists defend aftermarket replacement cycles. The vendor base stratifies into three archetypes: integrated module manufacturers backward integrating into MEMS fabrication, specialized sensor houses with captive foundry partnerships, and commodity mechanical producers serving price-sensitive fleet maintenance. Dominant competitive moves include strategic partnerships for MIIT certification pipeline access and portfolio diversification into battery thermal management sensing.
Among European-integrated module manufacturers, Bosch and HELLA exemplify the premium-tier archetype through Tier-1 supplier relationships and unified sensor network specifications. Standard Motor Products, Inc. anchors the North American aftermarket through extensive channel control and SKU breadth for legacy vehicle parc maintenance.
| Leading Market Players |
|---|
| Bitron Industrie S.p.A |
| Standard Motor Products, Inc. |
| Amphenol Advanced Sensors |
| Tecmark Corporation |
| Francisco Albero S.A.U. |
| Bosch |
| HELLA |
| DENSO Corporation |
| Delphi Technologies |
| Others |
Value Chain & Pricing Dynamics
MEMS process engineering talent concentration in Nagoya and Stuttgart feeds labor-cost differentials that widen pricing-tier spreads between solid-state modules and commodity mechanical switches. Foundry access in Japan and Germany anchors premium-tier cost structures, while diaphragm switch fabrication in lower-cost manufacturing corridors preserves economy-tier positioning.
Pricing Analysis
Uptime-guarantee contracts for fleet operators anchor value-based pricing in the heavy-duty segment, with predictive maintenance integration commanding service premiums atop hardware. Three-tier pricing structure across premium, standard, and economy levels separates ASIL-certified MEMS modules from electrical bridge products and unbranded mechanical alternatives. Cost compression in the mechanical tier is intensifying because Chinese domestic suppliers flood aftermarket channels with unbranded diaphragm switches. Fleet maintenance departments exhibit highest price sensitivity, while OEM platform engineers prioritize certification compliance over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for integrated thermal management modules, while specialized distributors with diagnostic tool integration capture aftermarket replacement cycles. Wafer fabrication concentrates in Japan, Germany, and China, with MEMS foundry capacity tethered to automotive qualification timelines. Silicon wafers, ceramic substrates, and hermetic sealing alloys constitute critical input dependencies. Single-source vulnerability in ASIC signal conditioning chips threatens solid-state switch output consistency. Distribution runs through Tier-1 module manufacturers who aggregate pressure sensing with pump control and filtration monitoring.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solid-state MEMS architectures are displacing electromechanical diaphragm mechanisms across electrified powertrain specifications, compressing the addressable market for legacy switch suppliers. Capacitive transducer technology is replacing contact-based sensing in premium thermal management applications.
For Market Incumbents: Anticipate accelerated share erosion in mechanical switch portfolios as powertrain electrification intensifies and Chinese domestic suppliers commoditize diaphragm-actuated alternatives. Prioritize backward integration into MEMS fabrication to secure captive wafer supply and margin capture. Defend aftermarket position through telematics-integrated distributor partnerships that compress replacement cycle timing.
For New Entrants and Emerging Players: The mid-tier price-point gap between Bosch-HELLA premium modules and unbranded Chinese mechanical switches offers white-space opportunity for ASIL-capable regional suppliers. Target India's Bureau of Indian Standards certification pipeline for emerging electric bus platforms before specification authority consolidates around incumbent Tier-1 relationships. Pursue foundry partnership models rather than capital-intensive fab construction to accelerate MIIT compliance timelines.
For Investors and Strategic Acquirers: The window for entry favors specialized MEMS sensor houses with captive automotive qualification pipelines and existing MIIT certification infrastructure. Long-term viability rests on ASIL-capable design processes that OEMs mandate for new platform development. Watch for inflection when European OEMs accelerate unified CAN-bus network specifications that displace analog gauge architectures entirely.
| Strategic Initiative | Industry Significance |
|---|---|
| MIIT Certification Pipeline Investment | First-mover access to China's domestic vehicle platform specifications accelerates market entry. |
| MEMS Foundry Partnership | Specialized wafer-level packaging expertise concentrates at handful of qualified automotive suppliers. |
| CAN-bus Integration Development | Digital output switches with LIN transceivers capture value from analog gauge replacement cycles. |
| Predictive Maintenance Platform Integration | Telematics-triggered proactive dispatch compresses sensor replacement cycles for fleet operators. |
| Battery Thermal Management Expansion | Coolant loop pressure sensing creates parallel demand streams alongside traditional engine lubrication monitoring. |
Study Parameters
Document review covered vehicle production databases, IHS Markit registration data, and MIIT certification filings, complemented by interviews with Tier-1 supplier procurement leads, OEM platform engineers, aftermarket distributors, and MEMS foundry operations managers. Secondary sources included SEC filings from listed automotive component suppliers, customs and trade flow records, and GB/T standards documentation. Bottom-up segment sizing triangulated against top-down market aggregation to ensure consistency across electrified and internal combustion powertrain forecasts.
Historical shipment patterns cross-referenced against panel input from platform engineering directors informed the analytical framework across the projection horizon. Segmentation dimensions modeled included propulsion architecture, vehicle class, content per vehicle, OEM tier, and regional production cluster. CAGRs were derived from regression analysis of technology adoption curves and regulatory mandate implementation schedules. Forecast inputs incorporated MIIT sensor reliability mandate compliance timelines and European OEM unified sensor network specifications.
Inputs from Tier-1 supplier procurement leads and MEMS foundry operations managers were available through the study window; gaps in emerging market aftermarket channel data introduce uncertainty bands around replacement cycle compression assumptions. Forecasts reflect documented assumptions regarding powertrain electrification penetration rates and regulatory certification timeline adherence. Periodic stress-testing of base assumptions is recommended given silicon wafer cost volatility and ISO 26262 compliance friction risks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Crankcase Additives Market
Automotive Parts
Germany Automotive Hydraulic Actuators Market
Automotive Parts
EV Reduction Gears Market
Automotive Parts
Cam Trigger Kits Market
Automotive Parts
Automotive Winches System (AWS) Market
Automotive Parts
Die Cast Parts for Electric Vehicle Market
Automotive Parts
Road Marking Machine Market
Automotive Parts
Italy Automotive Hydraulic Actuators Market
Automotive Parts
Commercial Vehicles LED Bar Lights Market
Automotive Parts
Middle East Automotive Lubricants Market
Automotive Parts
Full Synthetic Motor Oil Market
Automotive Parts
Plastic Fuel Tanks Market
Automotive Parts
ASEAN Automotive Bearings Market
Automotive Parts
Automotive Timing Chain Market
Automotive Parts
North America Automotive Parts Magnesium Die Casting Market
Automotive Parts
Automotive Roller Bearing Market