
 Thailand Automotive Lubricants Market | 2026-2036
Thailand Automotive Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Thailand Automotive Lubricants Market Analytics
Synthetic formulation technology is tilting production economics toward higher-performance base stocks in Thailand's lubricant blending plants. Shell plc leverages its Rayong manufacturing complex to sustain supply continuity for domestic OEM contracts. PTT Lubricants anchors its position through captive feedstock access from parent refining operations. Bangchak Corporation differentiates via renewable feedstock integration at its Chon Buri facilities.
Thailand automotive lubricants are formulated mixtures of base oils and performance additives engineered to reduce friction, dissipate heat, and prevent wear in powertrain components, with synthetic grades typically achieving viscosity indices above 140 and thermal oxidation stability exceeding mineral alternatives by factor of two to three. Engine oil commands the dominant volume position due to mandatory drain intervals tied to warranty compliance across Thai-assembled vehicles. The aftermarket provider channel captures expanding margin pools as vehicle parc ages beyond manufacturer service periods, while bio-based formulations remain nascent pending cost parity with synthetic alternatives.
Thailand Industrial Standards Institute (TISI) mandates lubricant labeling and performance claims verification, while Department of Industrial Works (DIW) oversees hazardous substance handling in blending operations. The country's national petroleum regulator enforces fuel-economy standards that indirectly tighten lubricant viscosity grade specifications for new vehicle certification. Stakeholders must monitor whether carbon border adjustment mechanisms in Thailand's export destination markets eventually extend compliance obligations to lubricant supply chains serving re-exported vehicle production.
Market Dynamics
Synthetic base stock migration is compressing mineral oil capacity utilization across Thailand's blending infrastructure while tightening viscosity grade specifications for OEM certification. TISI enforcement of labeling standards and DIW hazardous substance protocols are accelerating formulation complexity costs for domestic producers.
Growth Catalysts
- Commercial Fleet Intensification:Logistics operators in Bangkok's manufacturing corridor are extending drain intervals through synthetic adoption to maximize vehicle uptime. Fleet procurement contracts now specify SAE 5W-30 and 0W-20 grades for fuel economy compliance.
- TISI Certification Expansion:Thailand Industrial Standards Institute mandates are elevating quality thresholds for aftermarket lubricants. Mandatory performance verification is filtering substandard imports from neighboring supply sources.
- Eastern Economic Corridor Clustering:Automotive assembly concentration in Rayong and Chon Buri provinces generates captive demand for just-in-time lubricant delivery. Proximity blending reduces inventory carrying costs for OEM service fill operations.
Market Restraints
- Group II/III Base Oil Import Dependency:Thailand lacks domestic hydrocracking capacity for high-viscosity-index feedstocks. Refinery output concentrates in Group I stocks unsuitable for modern OEM specifications.
- Additive Package Concentration:Performance chemical formulations rely on imported detergent-dispersant and anti-wear chemistries from Singapore and South Korea. Supply bottlenecks in friction modifier availability constrain blending schedule flexibility.
- Bio-based Cost Disequilibrium:Renewable ester base stocks remain priced at 40-60% premium to synthetic hydrocarbon alternatives. Fleet operators defer adoption pending total cost of ownership parity with conventional formulations.
Strategic Opportunities
- Used Oil Re-refining Infrastructure:Thailand generates substantial waste lubricant volumes lacking systematic collection and reprocessing. Investment in vacuum distillation and hydrotreating capacity could close circular supply loops.
- Industrial-Automotive Formulation Convergence:Hydraulic and compressor lubricants for Eastern Seaboard manufacturing are adopting automotive-grade additive technologies. Cross-sector formulation expertise transfers reduce R&D duplication.
- Digital Fleet Management Integration:Telematics-enabled oil condition monitoring allows predictive drain scheduling. Lubricant suppliers embedding sensors into packaging capture recurring revenue from monitoring services.
Industry Challenges
- Formulation Chemist Scarcity:Thai universities produce limited graduates specializing in tribology and lubricant additive chemistry. Blending facilities compete with petrochemical and specialty chemical sectors for technical talent.
- OEM Approval Timeline Compression:New viscosity grade introductions require 12-18 month engine test sequences for factory fill authorization. Aftermarket suppliers struggle to synchronize product launches with vehicle model refresh cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thailand Automotive Lubricants Market |
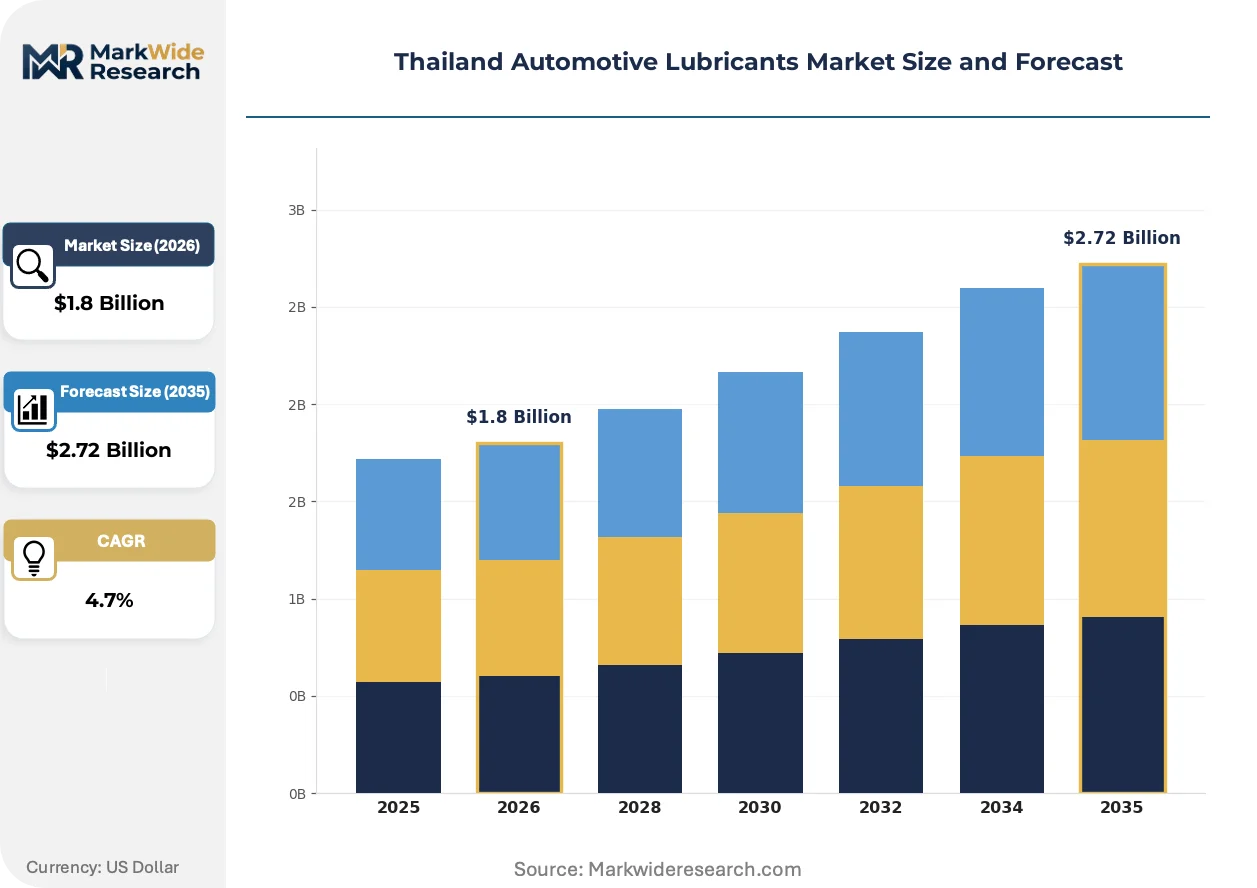
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Transmission Fluid, Gear Oil, Brake Fluid Formulation: Synthetic, Semi-Synthetic, Mineral, Bio-Based End User: OEMs, Aftermarket Providers, Retail Consumers, Fleet Services Packaging Type: Drum, Bottle, Pail, Sachet |
| Companies Covered | PETRONAS Chemicals Group Berhad, Chevron Corporation, Shell plc, TotalEnergies, BP p.l.c., ExxonMobil Corporation, Bangchak Corporation, Idemitsu Kosan, PTT Lubricants, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thailand Automotive Lubricants Market Evolving Landscape
Synthetic formulation architectures are displacing conventional mineral chemistry across Thailand's lubricant value chain. Three interconnected developments are restructuring competitive positioning and procurement patterns.
Polyalphaolefin (PAO) and gas-to-liquids base stocks are migrating from premium passenger car segments into commercial vehicle and industrial applications. Fleet operators in the Eastern Economic Corridor are adopting PAO-blended 10W-40 formulations for extended drain intervals under tropical operating conditions. This migration from mineral-dominant formulations is compressing margins for blenders lacking synthetic blending flexibility.
Thailand Industrial Standards Institute (TISI) labeling enforcement is tightening performance claim substantiation requirements for all marketed lubricants. Mandatory testing documentation and third-party verification are extending product registration timelines. Domestic blenders are responding by consolidating SKU portfolios to focus on certified grades with proven test track records.
Aftermarket service channels are capturing lubricant margin pools as Thailand's vehicle parc ages beyond manufacturer warranty periods. Independent workshops in Bangkok metropolitan and provincial urban centers are displacing dealer service bays for routine maintenance. Channel disintermediation is most pronounced in the 5-10 year vehicle age cohort where owner sensitivity to service cost peaks.
Thailand Automotive Lubricants Market Segmentation
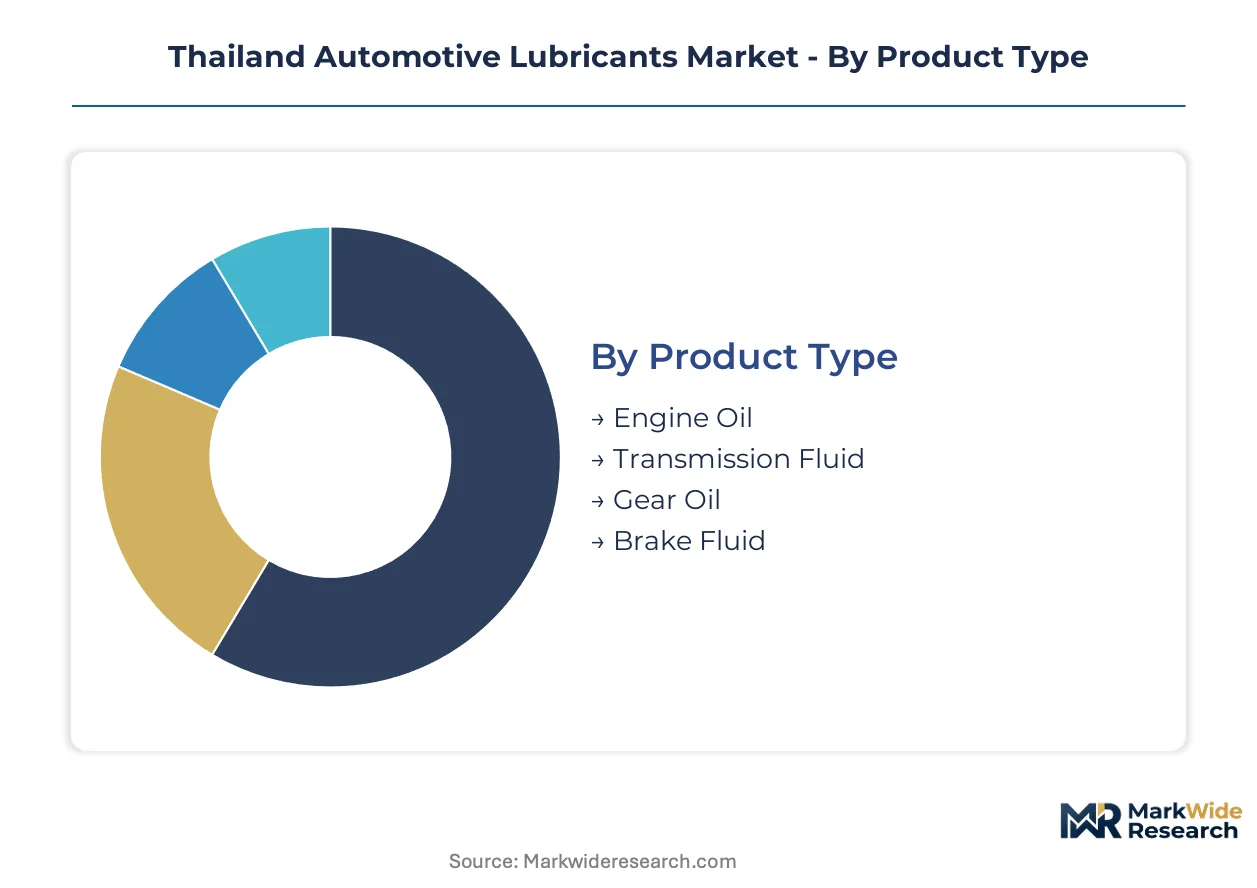
Thailand's automotive lubricant demand fragments across formulation technologies, distribution channels, and vehicle lifecycle stages. Each segment carries distinct margin profiles and regulatory exposure that shape supplier positioning strategies.
Product Type:
Powertrain protection requirements span friction reduction, thermal management, and wear prevention across distinct mechanical systems.
- Engine Oil:Formulated from Group II/III base stocks with detergent-dispersant additive packages to manage combustion byproducts and oxidation. Bangkok's manufacturing corridor and Eastern Economic Corridor assembly plants drive concentrated demand for SAE 5W-30 and 0W-20 grades tied to fuel economy compliance.
- Transmission Fluid:Specialized friction-modified formulations for automatic and continuously variable transmissions requiring precise viscosity retention across tropical temperature ranges. Fleet operators in Rayong and Chon Buri provinces specify extended-drain synthetics to maximize commercial vehicle uptime.
- Gear Oil:Extreme-pressure additive systems protect differentials and manual transmissions under high-torque loading.
- Brake Fluid:Glycol-ether or silicone-based hydraulic fluids meeting DOT 3/4/5.1 specifications for ABS system compatibility.
Established volume favors Engine Oil; emerging adoption favors Transmission Fluid.
Formulation:
Base stock selection determines thermal stability, drain interval extension, and OEM warranty compliance.
- Synthetic:Polyalphaolefin and gas-to-liquids base stocks achieve viscosity indices above 140 with oxidation stability two to three times mineral alternatives. Eastern Economic Corridor fleet procurement now specifies synthetic grades for 15,000+ kilometer drain intervals.
- Semi-Synthetic:Blended formulations balancing performance upgrade against mineral base cost structures. Independent workshops in Bangkok metropolitan area favor these for 5-10 year vehicle age cohorts where owner price sensitivity peaks.
- Mineral:Group I base stocks from domestic refinery output face compression as TISI specifications tighten.
- Bio-Based:Renewable ester chemistry from Bangchak Corporation's Chon Buri facilities remains at 40-60% premium to synthetic hydrocarbons.
Cost discipline favors Mineral; performance specification favors Synthetic.
End User:
Channel structure determines pricing power, technical service requirements, and inventory velocity.
- OEMs:Factory fill contracts require 12-18 month engine test sequences for viscosity grade authorization. Rayong and Chon Buri assembly clusters demand just-in-time delivery with captive blending proximity.
- Aftermarket Providers:Independent service channels capture margin pools as Thailand's vehicle parc ages beyond manufacturer warranty periods. Bangkok provincial urban centers show pronounced dealer displacement for routine maintenance.
- Retail Consumers:Do-it-yourself purchasers through automotive parts retailers and convenience channels.
- Fleet Services:Logistics operators specifying bulk procurement contracts with telematics-enabled oil condition monitoring for predictive drain scheduling.
Margin concentration favors Aftermarket Providers; volume scale favors Fleet Services.
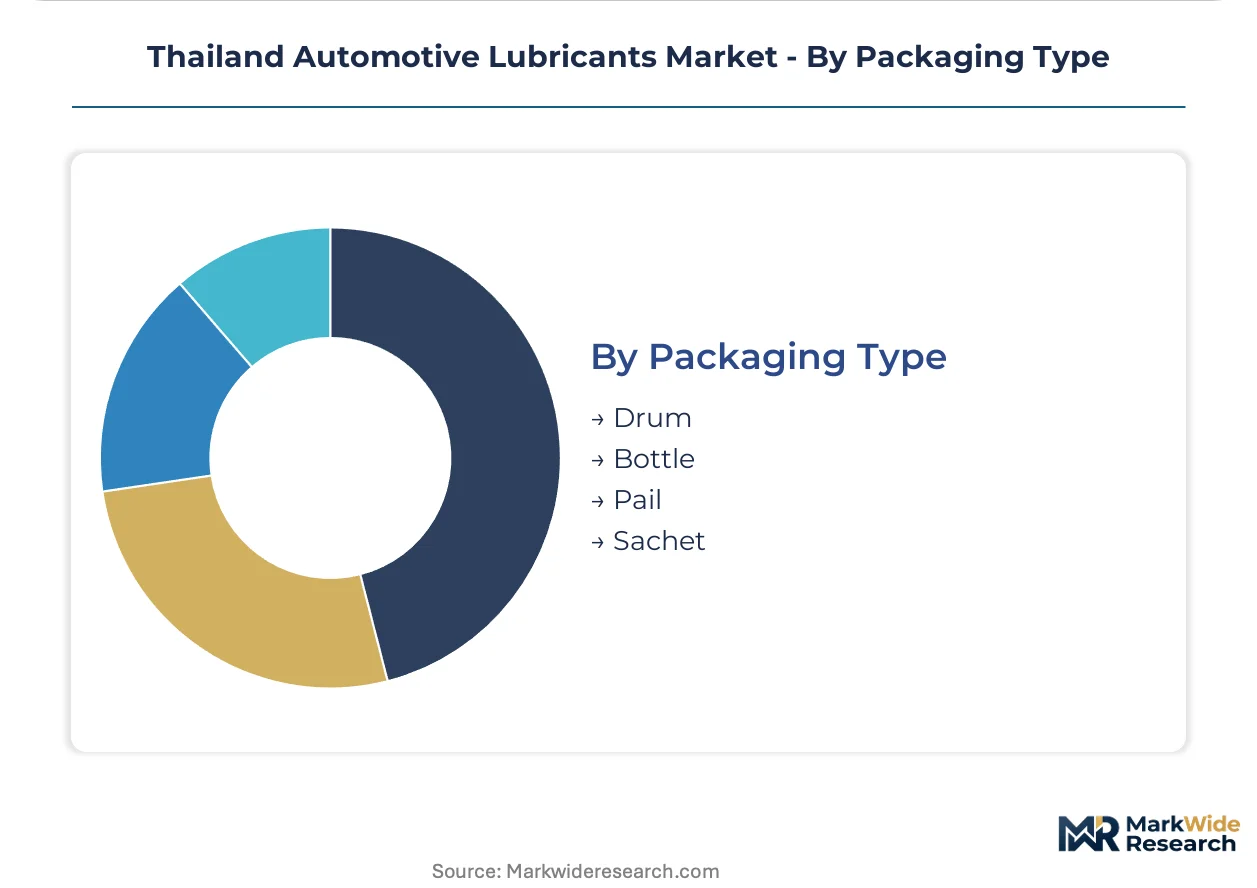
Packaging Type:
Container format aligns with consumption scale, handling infrastructure, and point-of-use accessibility.
- Drum:200-liter steel containers for industrial and fleet bulk consumption. Eastern Economic Corridor manufacturing clusters specify drum delivery to centralized lube bays.
- Bottle:1-5 liter retail formats for passenger car top-up and independent workshop dispensing. Bangkok metropolitan distribution centers manage high-SKU complexity for this channel.
- Pail:18-20 liter plastic containers bridging retail and small commercial demand.
- Sachet:Single-use 100-500ml pouches for two-wheeler roadside service and rural market penetration.
Logistics efficiency favors Drum; accessibility breadth favors Bottle.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet operators and automotive assemblers anchor demand concentration across Thailand's manufacturing belt. Bangkok's logistics corridors and the Eastern Economic Corridor provinces generate the dominant procurement volumes. Industrial standards enforcement tightens quality thresholds nationwide.
Bangkok Metropolitan Region
Commercial fleet intensification drives synthetic lubricant procurement across Greater Bangkok's logistics networks. Thailand Industrial Standards Institute mandates filter substandard aftermarket imports from neighboring supply sources. Samut Prakan and Pathum Thani provinces host dense concentrations of distribution centers specifying SAE 5W-30 grades for fuel economy compliance.
Eastern Economic Corridor
Automotive assembly clustering in Rayong and Chon Buri provinces generates captive demand for just-in-time lubricant delivery. Department of Industrial Works oversees hazardous substance handling protocols at blending facilities throughout the corridor. Proximity blending operations reduce inventory carrying costs for OEM service fill contracts at assembly plants.
Central Plains Manufacturing Belt
Agricultural machinery and light commercial vehicle fleets sustain mineral oil demand in Ayutthaya and Saraburi provinces. TISI certification requirements elevate formulation standards for aftermarket products serving this price-sensitive segment. Regional distributors consolidate procurement to meet tightening quality verification timelines.
Northern Industrial Zone
Chiang Mai and Lamphun provinces anchor aftermarket service channel expansion as vehicle parc ages beyond warranty periods. Independent workshops displace dealer service bays for routine maintenance in this cohort. Parts retailers manage high-SKU complexity for passenger car top-up demand across urban centers.
Southern Seaboard
Songkhla and Surat Thani provinces concentrate commercial marine and fishing fleet lubricant consumption alongside automotive applications. Port logistics operators specify extended-drain synthetics to maximize vessel and vehicle uptime simultaneously. Regional blending depots serve cross-sector demand from centralized lube bay infrastructure.
Thailand Automotive Lubricants Market Competitive Landscape
Channel-controlling players compete with product-specialist players across Thailand's lubricant value chain. The market structure consolidates around integrated energy majors with captive feedstock access and independent blenders serving niche specification requirements. Two strategic archetypes dominate: refinery-integrated suppliers leveraging upstream hydrocarbon control, and additive-technology specialists importing performance chemical packages. Competitive dynamics center on formulation certification speed and OEM factory fill authorization timelines.
Within the integrated energy major tier, Shell plc and PTT Lubricants exemplify contrasting feedstock strategies. Shell plc occupies a position anchored to its Rayong manufacturing complex sustaining supply continuity for domestic OEM contracts. PTT Lubricants represents refinery-integrated supply architecture through captive feedstock access from parent refining operations. Bangchak Corporation sits within the renewable feedstock specialist archetype at its Chon Buri facilities, differentiating via bio-based formulation development pending cost parity achievement.
| Leading Market Players |
|---|
| PETRONAS Chemicals Group Berhad |
| Chevron Corporation |
| Shell plc |
| TotalEnergies |
| BP p.l.c. |
| ExxonMobil Corporation |
| Bangchak Corporation |
| Idemitsu Kosan |
| PTT Lubricants |
| Others |
Value Network & Pricing Analysis
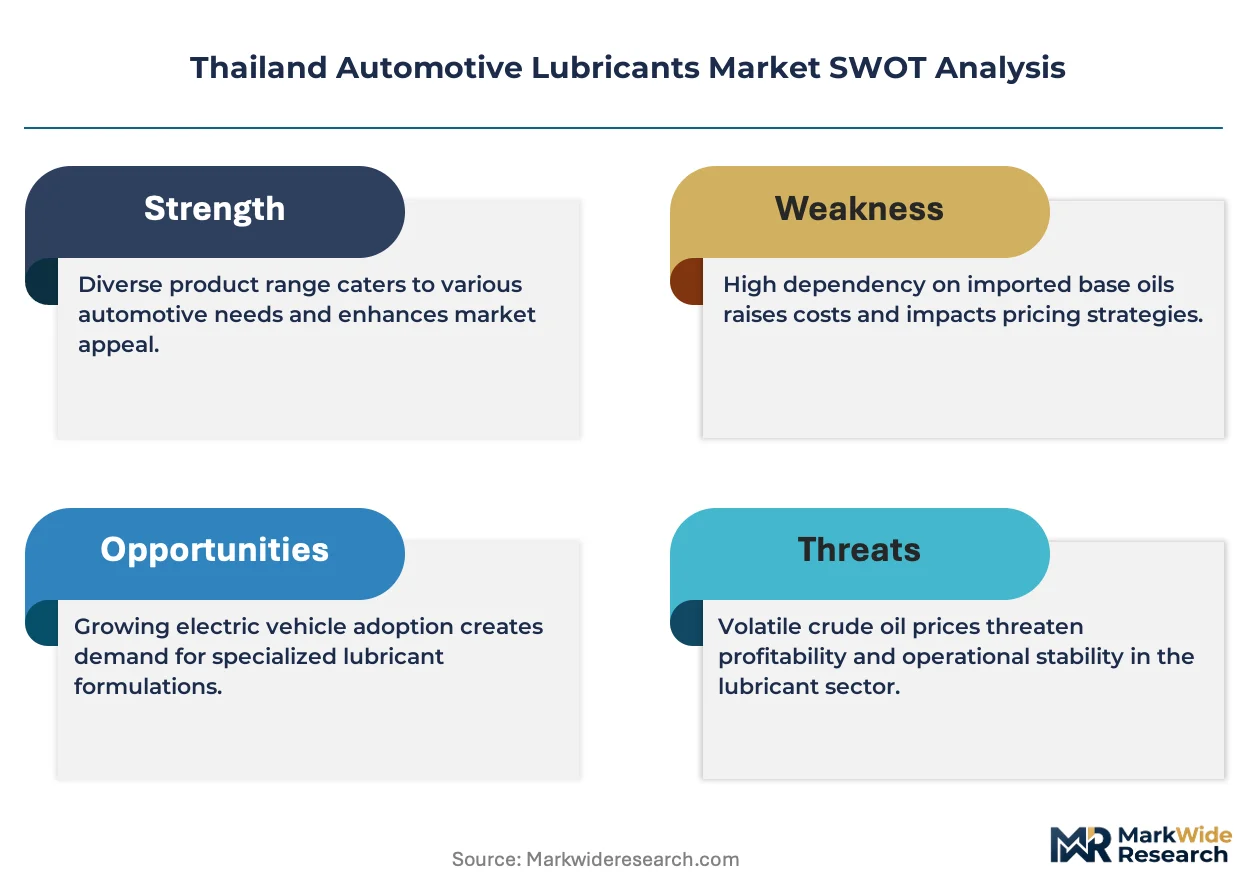
Group II/III base oil import dependency determines both the three-tier pricing structure across premium, standard, and economy levels and the regional clustering of Thailand's blending infrastructure. This feedstock bottleneck compresses margins for domestic producers while concentrating formulation expertise near Rayong and Chon Buri assembly corridors.
Pricing Analysis
Cost-plus contracts with Singapore and South Korean additive suppliers index to regional aromatics benchmarks and freight differentials. Price differentiation separates TISI-certified synthetic grades from uncertified mineral alternatives, with fleet operators showing lowest sensitivity due to uptime value capture. Pricing pressure stems from bio-based ester premiums running 40-60% above synthetic hydrocarbons, forcing cost compression in the mineral tier where Bangkok independent workshops dominate procurement.
Supply Chain Analysis
Contract manufacturing concentrates at Shell's Rayong complex, PTT Lubricants' refinery-integrated facilities, and Bangchak Corporation's Chon Buri renewable feedstock operations. Feedstock draws from Singapore, South Korea, and Japan for high-viscosity-index base stocks and friction modifier chemistries. Single-source vulnerability sits with detergent-dispersant additive packages from Singaporean chemical specialists. Distribution runs through drum and bulk tanker networks serving Eastern Economic Corridor OEMs, with bottle and sachet formats penetrating Bangkok metropolitan aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thailand's automotive lubricant sector sits at a platform-economics inflection where telematics-enabled oil condition monitoring creates recurring revenue interoperability between hardware sensors and predictive maintenance software ecosystems.
For Market Incumbents: Pre-empt independent workshop channel capture by embedding IoT sensors into drum and pail packaging, converting transactional lubricant sales into subscription monitoring revenue. Secure backward integration into used oil re-refining infrastructure before circular supply chain mandates tighten. Defend against bio-based entrants by accelerating synthetic-to-semi-synthetic grade migration in fleet procurement contracts. For New Entrants and Emerging Players: Build out digital fleet management integration capabilities targeting logistics operators in Samut Prakan and Pathum Thani provinces where telematics penetration lags OEM service bays. White-space opportunity concentrates in predictive drain scheduling for 5-10 year vehicle age cohorts where owner price sensitivity peaks. Go-to-market angle: partner with regional parts retailers for sensor-enabled packaging pilot programs. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors additive-technology specialists with TISI certification speed and OEM factory fill authorization track records. Long-term viability over the projection horizon hinges on formulation chemist scarcity resolution and re-refining infrastructure buildout. Signal to watch: Thailand Industrial Standards Institute expansion of mandatory performance verification to bio-based categories.| Strategic Initiative | Industry Significance |
|---|---|
| Used Oil Re-refining Infrastructure | Vacuum distillation capacity closes circular supply loops for waste lubricant volumes. |
| Telematics-Enabled Packaging Integration | Sensor embedding converts transactional sales into recurring monitoring service revenue. |
| TISI Certification Acceleration | Fast-track performance verification filters substandard imports from neighboring supply sources. |
| Synthetic Formulation Portfolio Migration | Group III base stock adoption captures extended-drain fleet procurement specifications. |
| Renewable Feedstock Cost Parity Investment | Bangchak Corporation's Chon Buri facilities anchor bio-based premium positioning. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, TISI certification registries, and Department of Industrial Works hazardous substance filings. Interviews with lubricant blending plant managers, OEM procurement leads at Rayong assembly facilities, aftermarket distributor channel heads, and fleet logistics operators in Bangkok's manufacturing corridor informed demand segmentation. Secondary validation drew from petroleum refinery output disclosures, additive package import records, and vehicle parc aging databases. Bottom-up volume builds triangulated against top-down sector value estimates.
Forecast inputs incorporate formulation technology migration curves, TISI enforcement intensity scenarios, and fleet telematics adoption rates across the analysis window. Segmentation dimensions span product type, base stock chemistry, end-user channel, and packaging format. CAGRs derive from elasticity modeling against commercial vehicle utilization trends and synthetic grade penetration thresholds. Industry-specific inputs include drain interval extension coefficients under tropical operating conditions and OEM factory fill authorization timeline distributions.
Stress conditions across base oil import tariff regimes, friction modifier supply bottlenecks, and carbon border adjustment mechanism extensions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding TISI certification expansion pace and Eastern Economic Corridor assembly cluster growth. Quarterly review of fleet telematics penetration rates and re-refining infrastructure investment announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
North America Automotive AHSS Market
Automotive Parts
Electric Vehicle Brake Pad Market
Automotive Parts
South Africa Automotive Parts Aluminium Die Casting Market
Automotive Parts
Ceramic Matrix Composite Disc Brakes (CMC Brake Disc) Market
Automotive Parts
Global Automotive Plain Carbon ERW Tubes Market
Automotive Parts
Connecting Rods Market
Automotive Parts
Canada Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Central Lubrication System Market
Automotive Parts
Automotive Propeller Shaft Market
Automotive Parts
North America Automotive Parts Aluminum Die Casting Market
Automotive Parts
Canada Automotive Parts Zinc Die Casting Market
Automotive Parts
Automotive Brake Friction Products Market
Automotive Parts
Automotive OEM Brake Friction Material Market
Automotive Parts
Bulgaria Automotive Lubricants Market
Automotive Parts
Argentina Automotive Lubricants Market
Automotive Parts
X-Arm Type Window Regulator Market