
 Automotive Control Arms Market | 2026-2036
Automotive Control Arms Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Control Arms Market Analytics
Aluminum-intensive vehicle architectures is narrowing the performance gap between stamped steel and forged aluminum control arms across mass-market segments. ZF Friedrichshafen AG leverages its integrated chassis systems portfolio to anchor premium OEM contracts in Europe. Magna International Inc. sustains manufacturing scale across multiple North American assembly corridors. Hyundai Mobis Co., Ltd. competes through captive supply relationships within the Hyundai Motor Group.
Automotive control arms are suspension linkage components that connect the wheel hub to the vehicle frame, typically manufactured through forging or stamping processes with specified ball joint interfaces to manage camber, caster, and toe alignment under dynamic loads. Their primary purpose is maintaining tire contact patch geometry while isolating road-induced forces from the passenger compartment. Lower control arms carry greater load burdens in modern multilink suspensions, positioning this product category as the dominant volume segment where margin pools concentrate around forged aluminum variants. Steel control arms retain cost advantages in commercial vehicle applications where duty cycles prioritize durability over unsprung mass reduction.
NHTSA Federal Motor Vehicle Safety Standards govern structural integrity and corrosion resistance requirements for suspension components sold in the United States. EPA Corporate Average Fuel Economy mandates indirectly shape control arm specifications by incentivizing lightweight materials that reduce vehicle mass. EU REACH regulations and the F-Gas Regulation constrain surface treatment chemistries and manufacturing processes for suppliers serving European OEM assembly networks. Stakeholders must monitor how evolving battery-electric vehicle platform architectures alter load path distributions and attachment point geometries in ways that could obsolete legacy control arm designs.
Market Dynamics
Platform electrification is redistributing suspension load paths away from traditional engine-bay anchor points toward battery-pack perimeter frames, forcing control arm suppliers to revalidate attachment geometries and material specifications for EV-dedicated architectures.
Growth Catalysts
- EPA Corporate Average Fuel Economy mandates:These standards intensify OEM pressure to reduce unsprung mass, accelerating aluminum-forged control arm penetration into mid-market vehicle segments previously served by stamped steel.
- German premium automaker procurement concentration:High-specification forged assemblies from Baden-Württemberg and Bavaria supplier clusters anchor technology diffusion across European OEM specification sheets.
- Hollow-casting aluminum processes:Advanced manufacturing techniques enable wall-thickness optimization that preserves structural integrity while achieving mass reductions competitive with solid forgings.
Market Restraints
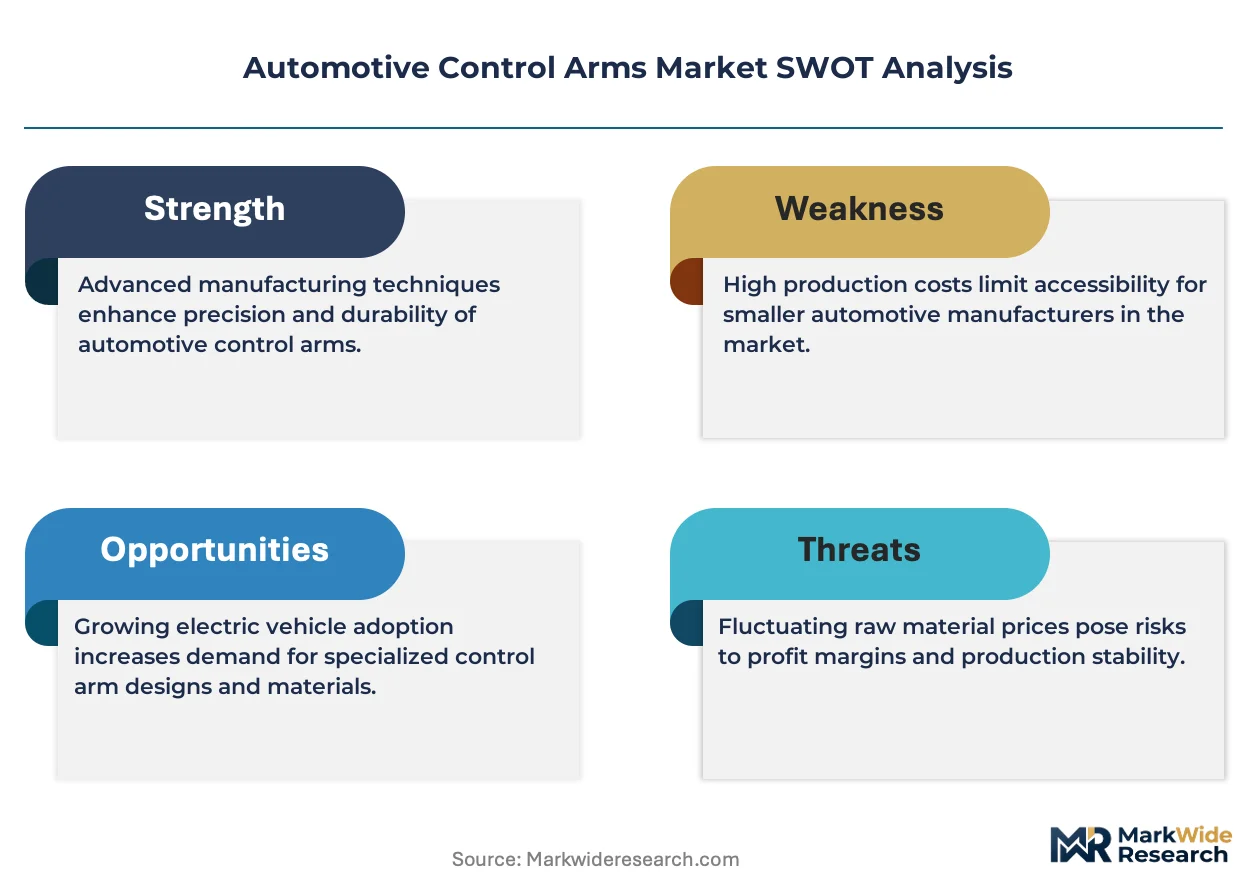
- Primary aluminum price volatility:LME aluminum contract fluctuations compress margin predictability for suppliers committed to long-term OEM pricing agreements.
- Chinese semi-finished billet concentration:Geographic concentration of aluminum alloy feedstock creates supply vulnerability for European and North American forging operations.
- Steel cost-performance floor:High-strength stamped steel retains cost advantages in commercial vehicle duty cycles where durability specifications outweigh mass reduction targets.
Strategic Opportunities
- Indian passenger vehicle electrification:PLI scheme incentives for domestic EV manufacturing create localized demand for lightweight suspension components as Tata Motors and Mahindra expand electric platforms.
- EU Green Deal industrial policy:Carbon border adjustment mechanisms and green aluminum certification requirements favor suppliers with verified low-carbon primary metal sourcing.
- Additive manufacturing topology optimization:Convergence of generative design software and selective laser melting enables complex lattice structures that reduce mass beyond conventional forging limits.
Industry Challenges
- Multiphysics simulation expertise scarcity:Control arm suppliers struggle to recruit engineers capable of integrating crash, fatigue, and NVH modeling for EV-specific load cases.
- OEM platform validation timelines:Extended homologation cycles for new suspension architectures delay revenue recognition and tie up engineering resources across multiple model-year programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Control Arms Market |
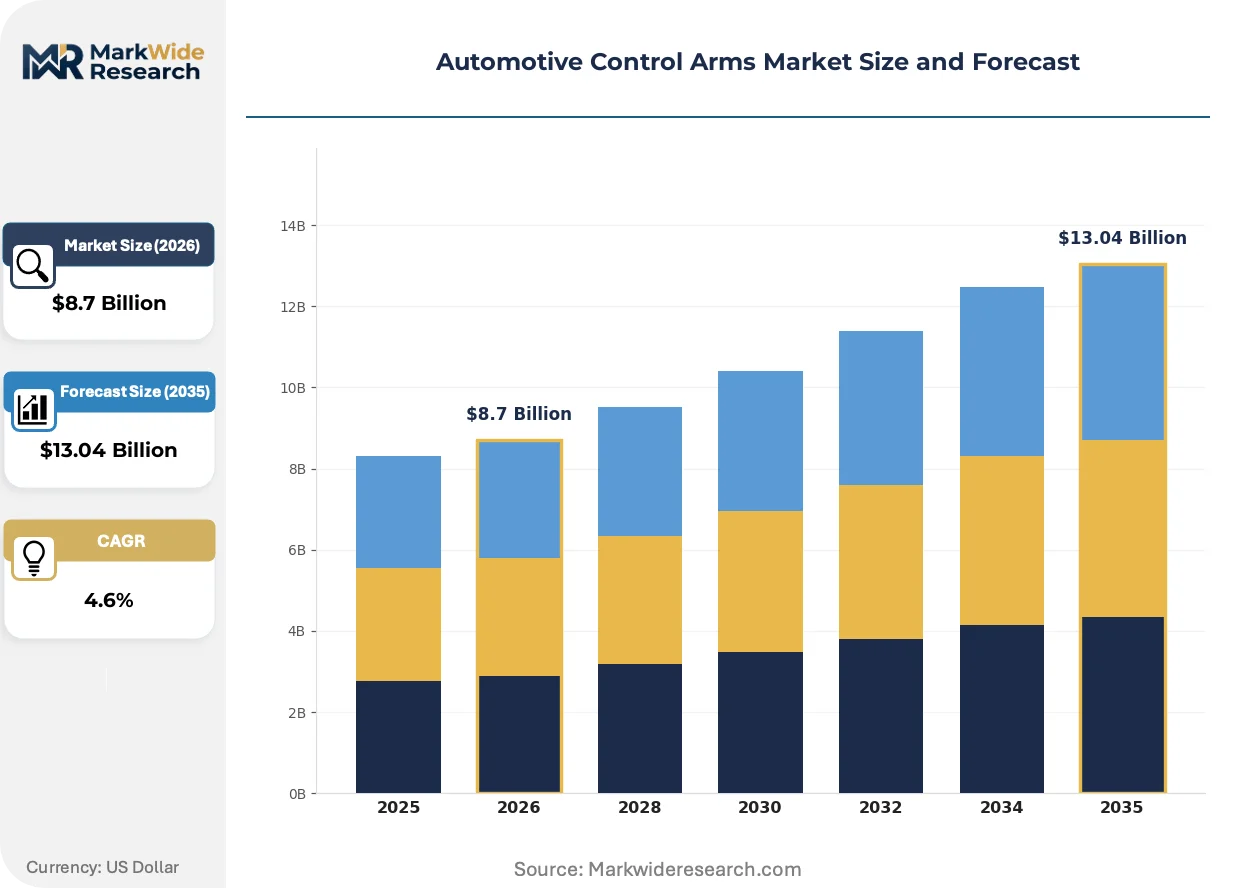
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Upper Control Arms, Lower Control Arms, Adjustable Control Arms, OEM Control Arms Material: Aluminum, Steel, Carbon Fiber, Composite End User: Passenger Vehicles, Commercial Vehicles, Motorsports, Aftermarket Distribution Channel: Online Retail, Specialty Stores, Distributors, Direct Sales |
| Companies Covered | Mando Corporation, DRiV Incorporated, ZF Friedrichshafen AG, Aisin Seiki Co., Ltd., Aludyne, Magna International Inc., Tenneco Inc., Mevotech Inc., Hyundai Mobis Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Control Arms Market Evolving Landscape
Digital thread integration is collapsing the traditional separation between design simulation and production quality assurance, enabling real-time specification adjustments that compress development cycles for platform-specific control arm variants.
Topology-optimized aluminum forgings is digitizing the trade-off between structural performance and mass reduction that previously required iterative physical prototyping. Tier-1 suppliers serving Volkswagen Group MEB and Hyundai-Kia E-GMP platforms are deploying these tools to deliver EV-specific lower control arms within compressed platform development windows. The technology is digitizing how OEM chassis engineers validate crash-energy management paths without multiple hardware build iterations.
EU REACH Annex XVII restrictions on hexavalent chromium surface treatments are forcing conversion to trivalent passivation and zirconium-based pretreatment chemistries for corrosion protection. Suppliers serving Stellantis and Renault assembly networks must requalify coating adhesion and salt-spray performance under these constrained chemical palettes. German forging specialists in the Neckar-Alb region are investing in closed-loop process water systems to maintain compliance while preserving throughput.
Fleet procurement centralization through mobility-service operators is fragmenting traditional OEM-aftermarket channel structures for control arm replacement. Leasing companies and ride-hail fleet managers in California and Texas are negotiating direct service contracts with remanufacturing specialists rather than franchised dealer networks. This channel shift concentrates volume with suppliers capable of certified refurbished assemblies rather than new-part-only manufacturers.
Automotive Control Arms Market Segmentation
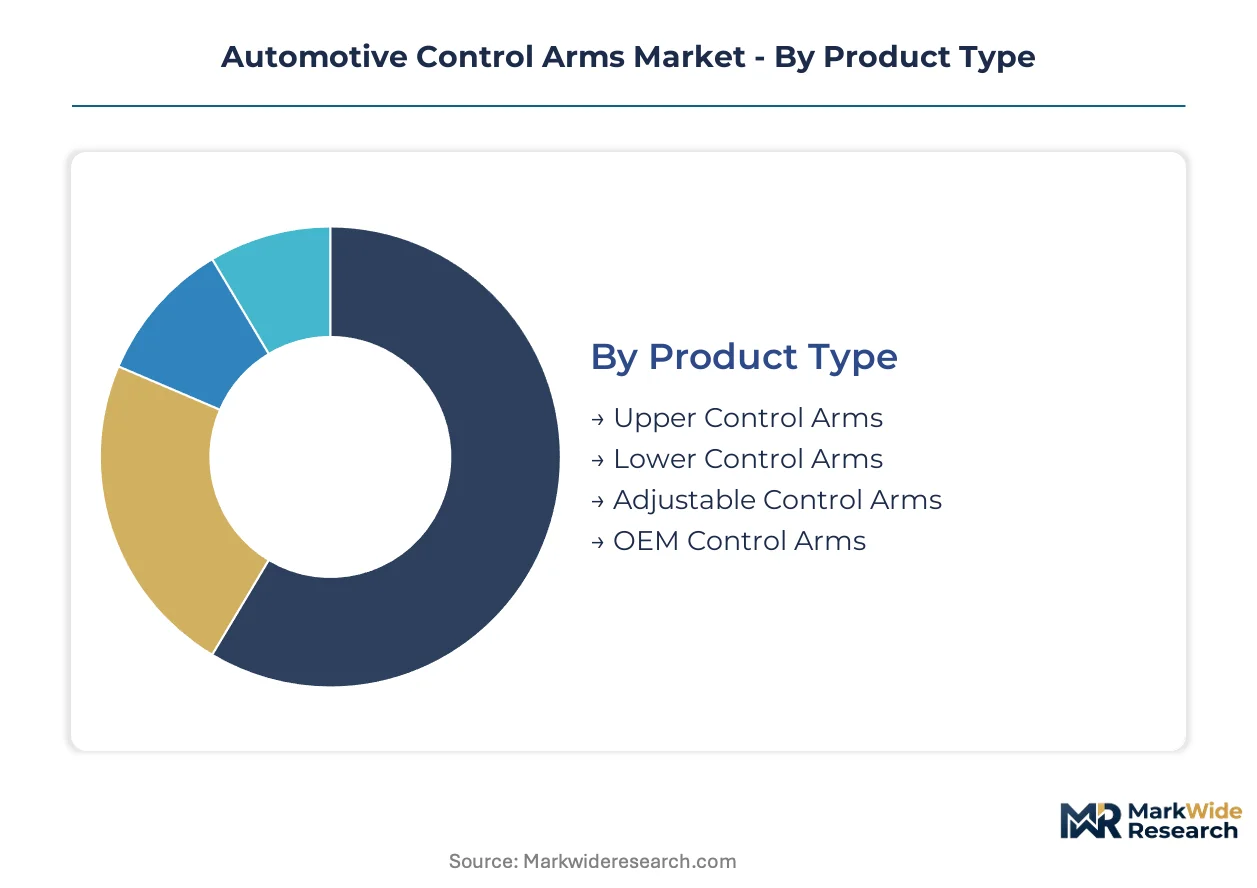
Control arm procurement cycles vary dramatically across segments, with motorsports and aftermarket channels demanding rapid design iterations while OEM programs lock specifications for multi-year platform lifespans. Understanding these velocity differentials helps suppliers calibrate inventory strategies and engineering resource allocation.
Product Type:
Lower control arms turn over fastest due to wear-prone ball joint interfaces and load-bearing fatigue, while adjustable variants cycle slowest given their niche motorsports application and extended validation requirements.
- Lower Control Arms:These components shoulder the primary vertical and lateral loads in multilink suspensions, typically manufactured as forged aluminum or stamped steel assemblies with integrated ball joint housings. Demand concentrates in German premium OEM procurement from Baden-Württemberg supplier clusters, where EPA fuel-economy mandates are accelerating aluminum-forged penetration into mid-market segments previously served by steel.
- Upper Control Arms:Positioned above the wheel centerline, these arms manage camber geometry with reduced load burden compared to lower counterparts, often utilizing hollow-casting aluminum processes to optimize mass. Procurement from Hyundai-Kia E-GMP platform programs in South Korea is expanding fastest as electric vehicle architectures redistribute suspension load paths toward battery-pack perimeter frames.
- Adjustable Control Arms:Motorsports and off-road aftermarket applications requiring camber and caster fine-tuning dominate this segment, with extended replacement cycles reflecting specialized use cases.
- OEM Control Arms:Platform-locked specifications with 5-7 year design lifespans characterize this segment, tied to vehicle model-year programs and extended homologation timelines.
Lower control arms dominate installed base volume given their universal application across vehicle architectures. Adjustable control arms are where expansion concentrates as off-road and track-day enthusiast markets deepen penetration.
Material:
Cost tiers separate these segments sharply, with carbon fiber commanding 8-12x multiples over stamped steel and aluminum occupying the strategic middle ground where fuel-economy regulations drive substitution.
- Aluminum:Forged and hollow-cast variants deliver the mass reduction OEMs require for CAFE compliance, with primary aluminum price volatility compressing margin predictability for suppliers locked into long-term pricing agreements. German forging operations in the Neckar-Alb region anchor European supply, though Chinese semi-finished billet concentration creates feedstock vulnerability.
- Steel:High-strength stamped grades retain cost-performance advantages in commercial vehicle duty cycles where durability specifications outweigh unsprung mass targets, with Indian and Brazilian heavy-truck assembly plants representing concentrated demand.
- Carbon Fiber:Motorsports and ultra-premium EV applications exploit its exceptional stiffness-to-weight ratio, constrained by cycle time and cost barriers to mass-market penetration.
- Composite:Glass-fiber reinforced polymers serve select NVH-critical applications, with limited thermal tolerance restricting deployment near brake assemblies.
Steel dominates installed base given legacy fleet composition and commercial vehicle durability requirements. Aluminum is where expansion concentrates as EPA mandates intensify lightweighting pressure across passenger vehicle segments.
End User:
Volume concentration versus margin capture defines this segmentation, with passenger vehicles delivering scale and motorsports yielding premium pricing despite fractional volume.
- Passenger Vehicles:OEM assembly networks account for the overwhelming share of control arm consumption, with electric platform proliferation from Volkswagen Group MEB and Hyundai-Kia E-GMP architectures forcing revalidation of attachment geometries and material specifications. Indian PLI scheme incentives for domestic EV manufacturing are creating localized demand growth as Tata Motors and Mahindra expand electric platforms.
- Commercial Vehicles:Duty cycles prioritizing durability over mass reduction sustain steel-intensive procurement, with fleet procurement centralization through leasing companies fragmenting traditional aftermarket channel structures.
- Motorsports:Rapid design iteration and custom geometry requirements characterize this segment, with topology-optimized forgings and additive manufacturing enabling complex lattice structures beyond conventional forging limits.
- Aftermarket:Ride-hail fleet managers in California and Texas negotiate direct service contracts with remanufacturing specialists, concentrating volume with suppliers capable of certified refurbished assemblies.
Passenger vehicles dominate installed base across global vehicle parc. Motorsports is where expansion concentrates as track-day participation and amateur racing series proliferate.
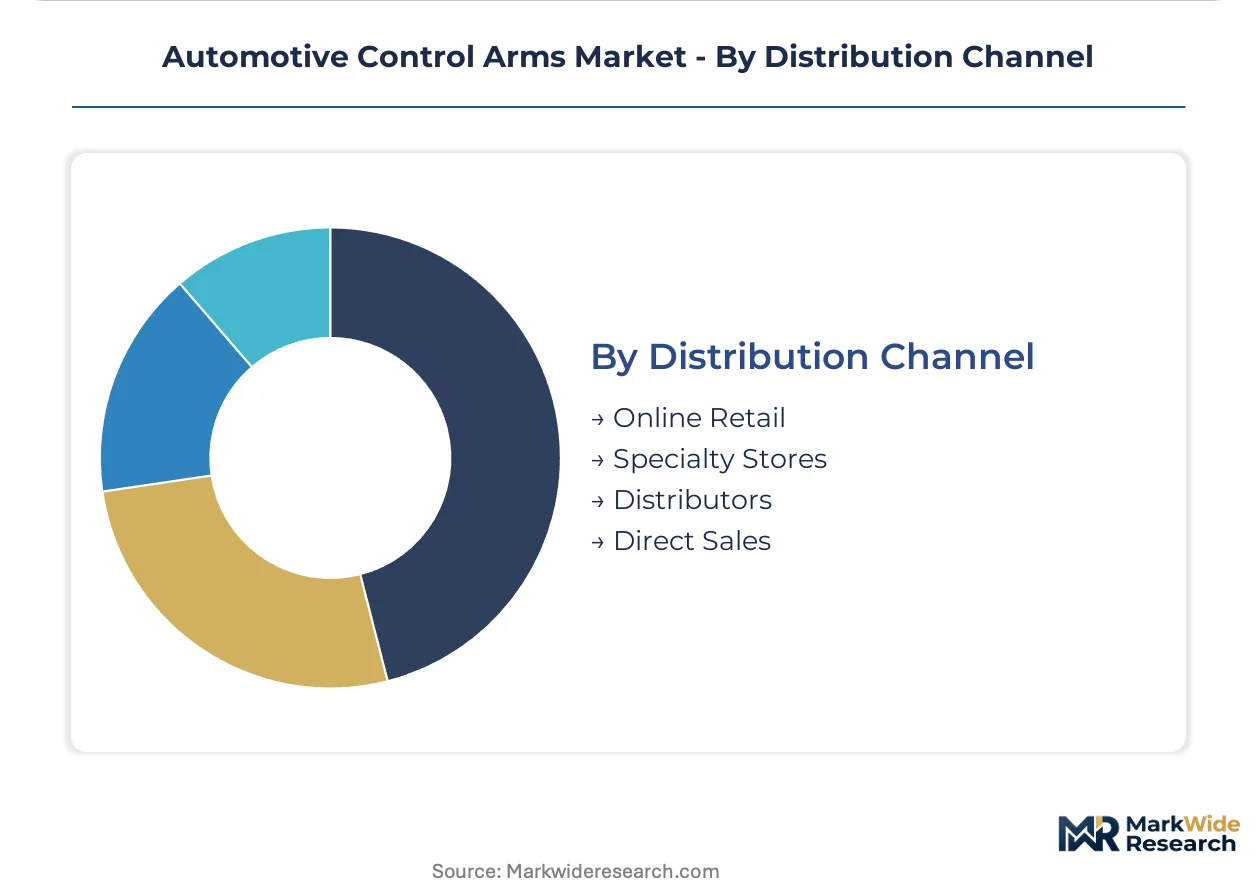
Distribution Channel:
Customer type and order velocity separate these channels, with direct sales locking in multi-year OEM commitments while online retail serves fragmented individual demand.
- Direct Sales:Tier-1 suppliers anchor premium OEM contracts through integrated chassis systems portfolios, with ZF Friedrichshafen AG and Magna International sustaining manufacturing scale across European and North American assembly corridors respectively. Extended platform validation timelines delay revenue recognition but secure multi-year volume commitments.
- Distributors:Independent aftermarket channels serve collision repair and general maintenance demand, with inventory positioning in regional logistics hubs determining competitive access.
- Specialty Stores:Performance-oriented retail serves enthusiast upgrade demand, with suspension tuning expertise differentiating competitive positioning.
- Online Retail:E-commerce penetration accelerates price transparency and SKU proliferation, with Amazon and RockAuto capturing share in routine replacement applications.
Direct sales dominate installed base value given OEM contract concentration. Online retail is where expansion concentrates as digital-native consumers age into vehicle ownership and maintenance decision-making.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in automotive control arms tilt toward net importing positions in mature Western markets while Asian manufacturing hubs consolidate export capacity. The United States absorbs substantial volumes of finished assemblies from Mexican maquiladora operations under USMCA provisions. Germany maintains surplus positions in high-specification forged aluminum components destined for premium OEM assembly networks across Europe and North America.
United States
NHTSA Federal Motor Vehicle Safety Standards govern structural integrity requirements for suspension components, with California and Texas ride-hail fleet managers negotiating direct service contracts with remanufacturing specialists. The EPA Corporate Average Fuel Economy mandate intensifies pressure to reduce unsprung mass, accelerating aluminum-forged control arm penetration into mid-market segments. Manufacturing corridors in Michigan and Ohio anchor domestic stamping and forging capacity serving Detroit Three assembly networks.
Germany
Baden-Württemberg and Bavaria supplier clusters anchor European demand for high-specification forged control arm assemblies, with EU REACH Annex XVII restrictions forcing conversion from hexavalent chromium to trivalent passivation chemistries. The EU Green Deal carbon border adjustment mechanism favors suppliers with verified low-carbon primary aluminum sourcing. Neckar-Alb region forging specialists are investing in closed-loop process water systems to maintain compliance while preserving throughput.
China
Domestic electric vehicle platform proliferation from BYD and NIO is redistributing suspension load paths toward battery-pack perimeter frames, forcing control arm suppliers to revalidate attachment geometries. GB standards and MIIT regulations shape local content requirements and technical specifications for chassis components. Yangtze River Delta manufacturing bases concentrate semi-finished aluminum billet production, creating feedstock leverage for regional forging operations.
India
PLI scheme incentives for domestic EV manufacturing create localized demand growth as Tata Motors and Mahindra expand electric platforms, with BIS certification requirements governing structural performance specifications. Steel-intensive procurement sustains cost advantages in commercial vehicle duty cycles where durability outweighs mass reduction. Tamil Nadu and Maharashtra assembly corridors concentrate OEM demand from Maruti Suzuki and Hyundai Motor India operations.
South Korea
Hyundai-Kia E-GMP platform programs are expanding fastest as electric vehicle architectures redistribute suspension load paths, with MFDS and KSA standards governing component quality assurance. Seoul Capital Area engineering centers deploy topology-optimized aluminum forgings within compressed platform development windows. Busan-Ulsan industrial complexes anchor export-oriented forging capacity serving Hyundai Motor Group captive supply relationships.
Automotive Control Arms Market Competitive Landscape
On the supply side, the industry is consolidating around integrated chassis systems portfolios that lock in multi-year OEM contracts through technical specification leadership. Tier-1 suppliers with captive aluminum forging and hollow-casting capabilities command premium positions in electrified platform procurement, while mid-scale specialists compete on aftermarket remanufacturing certifications. Strategic archetypes include integrated chassis module suppliers, aluminum forging specialists, and steel stamping scale players. Competitive dynamics center on backward integration into primary aluminum sourcing and geographic expansion to anchor regional OEM assembly corridors.
Within the integrated systems tier, ZF Friedrichshafen AG and Magna International Inc. exemplify the chassis module bundling strategy that secures platform-locked specifications across extended model-year programs. Hyundai Mobis Co., Ltd. occupies a distinctive position through captive supply relationships within the Hyundai Motor Group, representing the vertical integration archetype that insulates volume from external procurement competition. These three anchors illustrate how supplier structure—whether independent tier-1, diversified multinational, or captive affiliate—shapes competitive access to electrified platform development windows.
| Leading Market Players |
|---|
| Mando Corporation |
| DRiV Incorporated |
| ZF Friedrichshafen AG |
| Aisin Seiki Co., Ltd. |
| Aludyne |
| Magna International Inc. |
| Tenneco Inc. |
| Mevotech Inc. |
| Hyundai Mobis Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Yangtze River Delta port congestion feeds directly into landed cost spreads between Chinese semi-finished billet and European forged aluminum control arms, compressing margin pools for suppliers locked into long-term OEM contracts while amplifying price differentiation across premium and standard tiers.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure that stratifies across premium forged aluminum, standard hollow-cast variants, and economy stamped steel tiers. Price differentiation rests on certification grade alignment with EPA fuel-economy mandates and volume scale commitments across platform-locked programs. Cost compression in mid-market aluminum segments is intensifying because primary aluminum LME volatility transfers unpredictably through billet supply agreements. Fleet procurement managers represent the most price-sensitive buyer archetype, while German premium OEM platform engineers exhibit lowest sensitivity given specification-locked technical requirements.
Supply Chain Analysis
Extended payment terms from European OEMs now stretch 90-120 days, forcing Tier-1 suppliers toward supply-chain finance facilities anchored by receivables from Volkswagen Group and Stellantis procurement divisions. Geographic supply concentrates in China for semi-finished aluminum billet, Germany for high-specification forging operations, and Mexico for USMCA-compliant finished assembly export. Raw material dependencies draw from primary aluminum smelters, high-strength steel coil, and zirconium-based pretreatment chemistries constrained by EU REACH Annex XVII. Single-source vulnerability around Chinese billet concentration threatens European forging throughput. Distribution runs through direct OEM supply contracts, with aftermarket channels fragmenting toward remanufacturing specialists serving ride-hail fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through fleet procurement centralization by mobility-service operators, consolidating volume negotiation leverage away from traditional franchised dealer networks and toward direct Tier-1 contracting.
For Market Incumbents: Pre-empt margin erosion from hollow-casting aluminum process diffusion by deepening captive supply relationships with Hyundai Motor Group and Volkswagen Group platform programs. Anchor defensive positioning through backward integration into verified low-carbon primary aluminum sourcing that satisfies EU Green Deal carbon border adjustment requirements. Reinforce specification lock-in by embedding topology-optimized forging expertise within compressed EV platform validation timelines.
For New Entrants and Emerging Players: Indian passenger vehicle electrification presents the most penetrable white-space opportunity, with PLI scheme incentives creating localized demand for lightweight suspension components as Tata Motors and Mahindra expand electric platforms. Target aftermarket remanufacturing certification capabilities to capture fleet procurement contracts from California and Texas ride-hail operators bypassing traditional dealer channels. Pursue a go-to-market angle built on additive manufacturing topology optimization for motorsports and off-road adjustable control arm applications.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with non-core automotive chassis component divisions lacking EV-specific engineering capabilities. Long-term viability favors suppliers with demonstrated multiphysics simulation expertise integrating crash, fatigue, and NVH modeling for battery-electric load cases. Monitor OEM platform validation timeline compression as the critical inflection signal—accelerated homologation cycles favor agile specialists over legacy forging operations with extended development windows.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Volkswagen Group MEB and Hyundai-Kia E-GMP architectures lock in multi-year volume commitments for approved suppliers. |
| Backward Integration into Primary Aluminum | Verified low-carbon sourcing secures preferential positioning under EU Green Deal carbon border adjustment mechanisms. |
| Geographic Manufacturing Footprint | Mexican maquiladora capacity anchors USMCA-compliant supply to Detroit Three assembly networks in Michigan and Ohio. |
| Software-Defined Vehicle Investment | Digital thread integration between design simulation and production quality assurance compresses development cycles for EV-specific variants. |
| Remanufacturing Certification Program | Certified refurbished assembly capabilities capture fleet procurement contracts from mobility-service operators in California and Texas. |
Research Methodology
Desk research of vehicle production databases, IHS Markit registration data, and SEC filings from Tier-1 suppliers preceded structured interviews with OEM platform engineers, Tier-1 procurement directors, aftermarket distributors, and fleet operations managers at mobility-service providers. Primary fieldwork captured specification requirements for EV-dedicated architectures and validation timeline pressures across German, North American, and South Korean assembly corridors. Secondary validation drew from EPA fuel-economy mandate documentation, EU REACH regulatory filings, and PLI scheme incentive structures. Bottom-up segment sizing triangulated against top-down OEM production forecasts.
Assumptions held fixed include prevailing NHTSA safety standards, EU Green Deal carbon border adjustment implementation timelines, and observed OEM platform electrification commitments across the analysis window. Variable conditions encompassed primary aluminum price trajectory, Chinese billet export policy shifts, and Indian domestic EV manufacturing scale. Segmentation dimensions modeled vehicle class, propulsion architecture, material specification tier, and regional production cluster. CAGRs derived from regression analysis of historical OEM procurement volumes against projected electric platform penetration rates. Industry-specific inputs included content-per-vehicle estimates for multilink suspension architectures and hollow-casting aluminum process yield improvements.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese forging operations or accelerated additive manufacturing adoption by motorsports specialists would shift outcomes. Macroeconomic deviation in primary aluminum pricing, regulatory relaxation of EPA fuel-economy mandates, or technological breakthrough in carbon fiber composite stamping would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Europe Automotive Lubricants Market
Automotive Parts
Saudi Arabia Vehicle Exhaust Hose Market
Automotive Parts
Global Automotive Dynamic Chassis Control System Market
Automotive Parts
Automotive Pinion Gear Market
Automotive Parts
Engine Fogging Oil Market
Automotive Parts
Europe Automotive Engine Oils Market
Automotive Parts
Daytime Running Lights Market
Automotive Parts
AWD Coupling System Market
Automotive Parts
Automotive Antifreeze Market
Automotive Parts
Mexico Automotive Actuators Market
Automotive Parts
Automotive AC Compressor Market
Automotive Parts
North America Automotive Airfilters Market
Automotive Parts
Needle Roller Bearings Market
Automotive Parts
France Automotive Lubricants Market
Automotive Parts
Middle East Automotive Lubricants Market
Automotive Parts
United States Automotive Parts Die Casting Market