
 Industrial Shock Absorbers Market | 2026-2036
Industrial Shock Absorbers Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Shock Absorbers Market Foresight
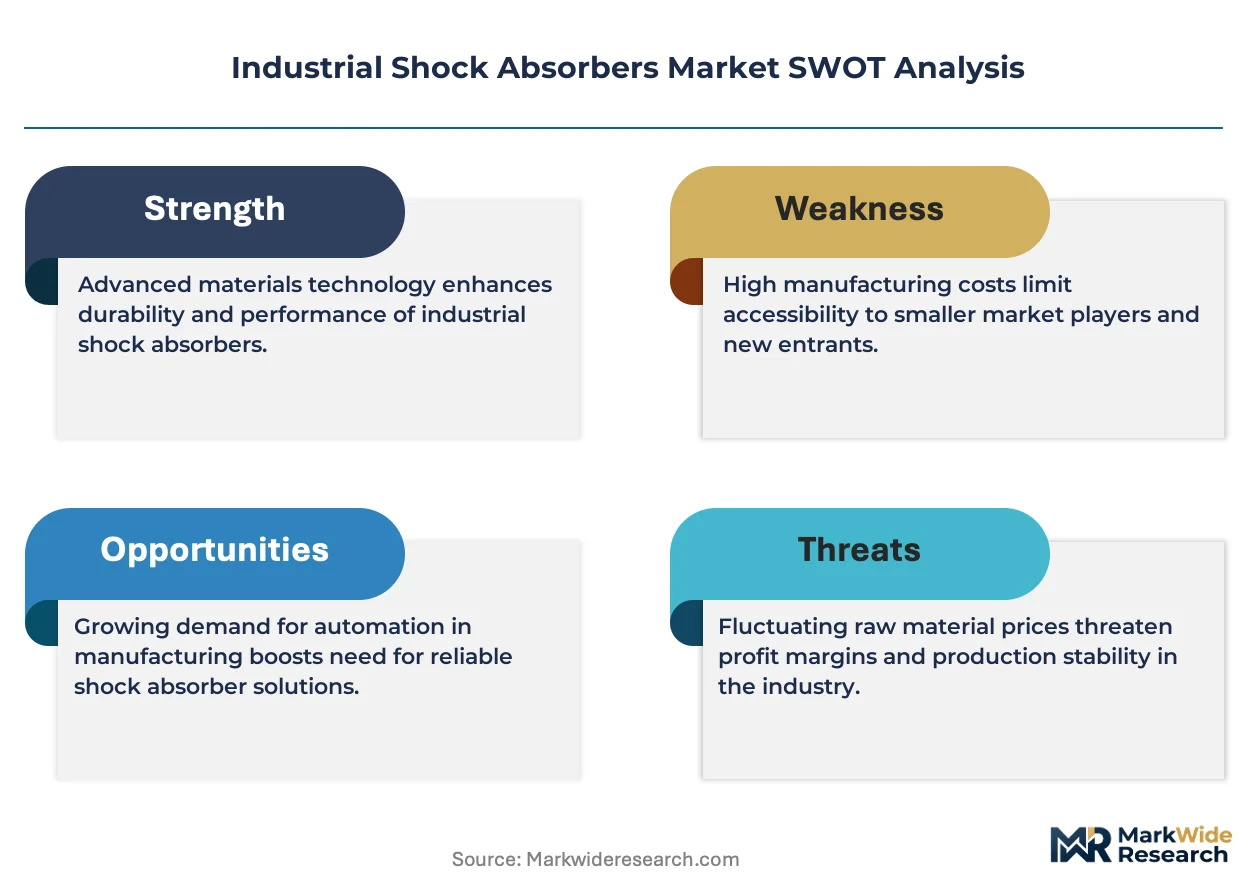
German industrial component manufacturing is restructuring capacity to serve precision automation demand across Europe. KYB Corporation leverages its automotive heritage to anchor hydraulic shock absorber supply for robotic material handling systems. ACE Controls Inc. specializes in adjustable damping solutions that dominate North American semiconductor fabrication equipment. Weforma Dämpfungstechnik GmbH sustains its position through captive polymer compounding and rapid custom prototyping for German machine builders.
Industrial shock absorbers are kinetic energy dissipation devices that convert impact momentum into thermal energy through fluid displacement, gas compression, or material deformation, typically rated for stroke lengths between 25 mm and 300 mm and operating temperatures from minus 30°C to 80°C. Their primary purpose is protecting mechanical structures, improving cycle rates, and reducing noise in automated production environments. Hydraulic products lead unit volume due to proven reliability in heavy machinery applications, while electromagnetic technology captures expanding margin pools in semiconductor and electronics manufacturing where programmable damping profiles enable precision positioning. Passive technology still occupies the majority of installed base across automotive stamping and aerospace assembly lines, though semi-active systems are gaining traction in defense and transportation infrastructure where load conditions vary unpredictably.
OSHA machine guarding standards and EU Machinery Directive 2006/42/EC enforcement compel OEMs to specify certified shock absorption in automated equipment, directly shaping product testing protocols and market access requirements. EPA spill containment rules and REACH substance restrictions further constrain hydraulic fluid formulations, pushing suppliers toward bio-based alternatives and sealed pneumatic designs. Stakeholders must monitor how IEC functional safety standards evolve for collaborative robots, as this will determine certification burdens and component specification power across the supply chain.
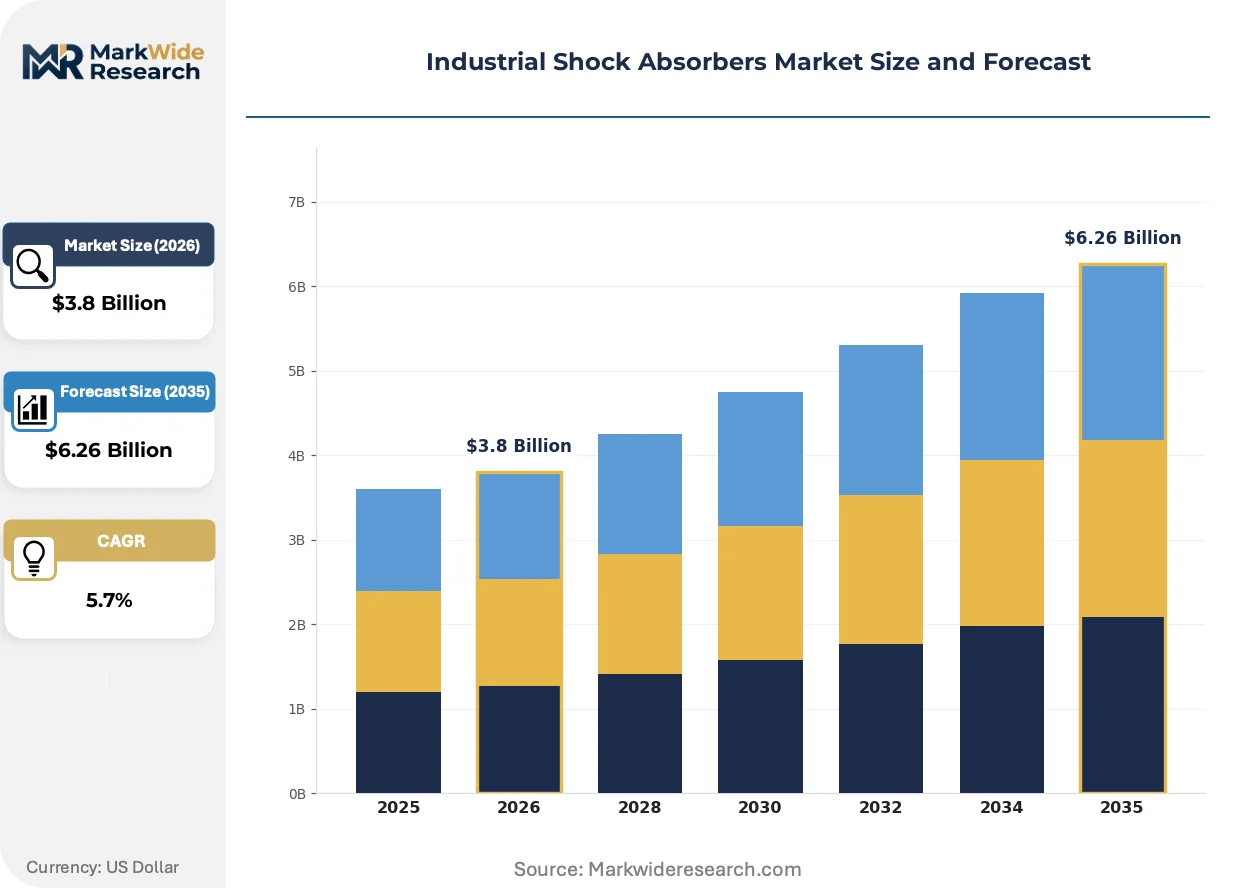
Market Dynamics
REACH substance restrictions and OSHA machine guarding standards are compressing formulation flexibility while mandating certified damping solutions across automated production lines. Suppliers now face simultaneous pressure to eliminate hazardous hydraulic fluids and prove functional safety compliance for collaborative robot integration.
Growth Catalysts
- EU Machinery Directive 2006/42/EC:Enforcement compels OEMs to specify certified shock absorption in automated equipment, directly expanding addressable demand for tested and validated damping products.
- Automotive assembly automation:End-use buyers in vehicle manufacturing are expanding capital expenditure on robotic material handling systems that require precision kinetic energy management.
- Stuttgart-Dortmund machinery cluster:Concentration of German machine builders generates dense demand for rapid custom prototyping and captive polymer compounding capabilities.
Market Restraints
- Specialized elastomer supply concentration:High-performance polymer formulations depend on a limited supplier base concentrated in Central Europe, creating input vulnerability.
- REACH Annex XVII substance restrictions:Regulatory friction limits hydraulic fluid formulation options, forcing costly reformulation cycles and inventory transitions.
- Electromagnetic actuation substitution:Programmable damping systems threaten conventional hydraulic unit margins in semiconductor and electronics manufacturing applications.
Strategic Opportunities
- Collaborative robot safety standards:IEC functional safety evolution for cobots creates certification-driven specification power for compliant component suppliers.
- Defense and transportation infrastructure:Semi-active damping systems address unpredictable load conditions in military and heavy civil applications where passive technology underperforms.
- Sealed pneumatic architectures:Bio-based fluid alternatives and closed-loop gas compression designs bypass EPA spill containment exposure while meeting sustainability procurement criteria.
Industry Challenges
- Functional safety engineering talent:Shortage of professionals versed in IEC 61508 and machinery directive compliance extends product validation timelines.
- Legacy hydraulic system integration:Retrofitting programmable damping profiles into existing automotive stamping and aerospace assembly lines demands complex control architecture reconciliation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Shock Absorbers Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic, Pneumatic, Mechanical, Electromagnetic Application: Automotive, Aerospace, Machinery, Electronics End User: Manufacturing, Construction, Transportation, Defense Technology: Passive, Active, Semi-Active, Variable Stiffness |
| Companies Covered | KYB Corporation, ACE Controls Inc., ZIMMER GROUP, Weforma Dämpfungstechnik GmbH, Parker Hannifin Corporation, Pennar Industries Limited, Universal Power Conversion, Inc, Slam Proof Ltd., BIBUS AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Shock Absorbers Market Shifts & Advancements
Programmable damping and sustainable material science are actively displacing fixed-parameter hydraulic systems across precision manufacturing verticals. Three concurrent developments are compressing traditional product lifecycles and reshaping supplier capability requirements.
Magnetorheological fluid technology is rewriting competitive positioning in semiconductor fabrication equipment. Wafer handling system OEMs in South Korea and Taiwan are adopting electromagnetic damping for sub-micron positioning accuracy. This capability compression is eliminating price premiums previously commanded by precision hydraulic units in cleanroom environments.
EPA spill containment rules and REACH bio-based substance mandates are forcing hydraulic fluid formulation changes. Suppliers must certify bio-degradable alternatives or pivot to sealed gas-spring architectures. German machinery OEMs are responding fastest, driven by ECHA enforcement timelines and customer sustainability scorecards.
Buyer consolidation among automotive Tier-1 integrators is compressing supplier negotiation cycles. Procurement teams now demand outcome-based performance guarantees rather than component specifications. This shift is most visible in Stuttgart's automotive supply cluster, where damping suppliers must assume lifecycle liability for integrated motion control systems.
Industrial Shock Absorbers Market Segmentation
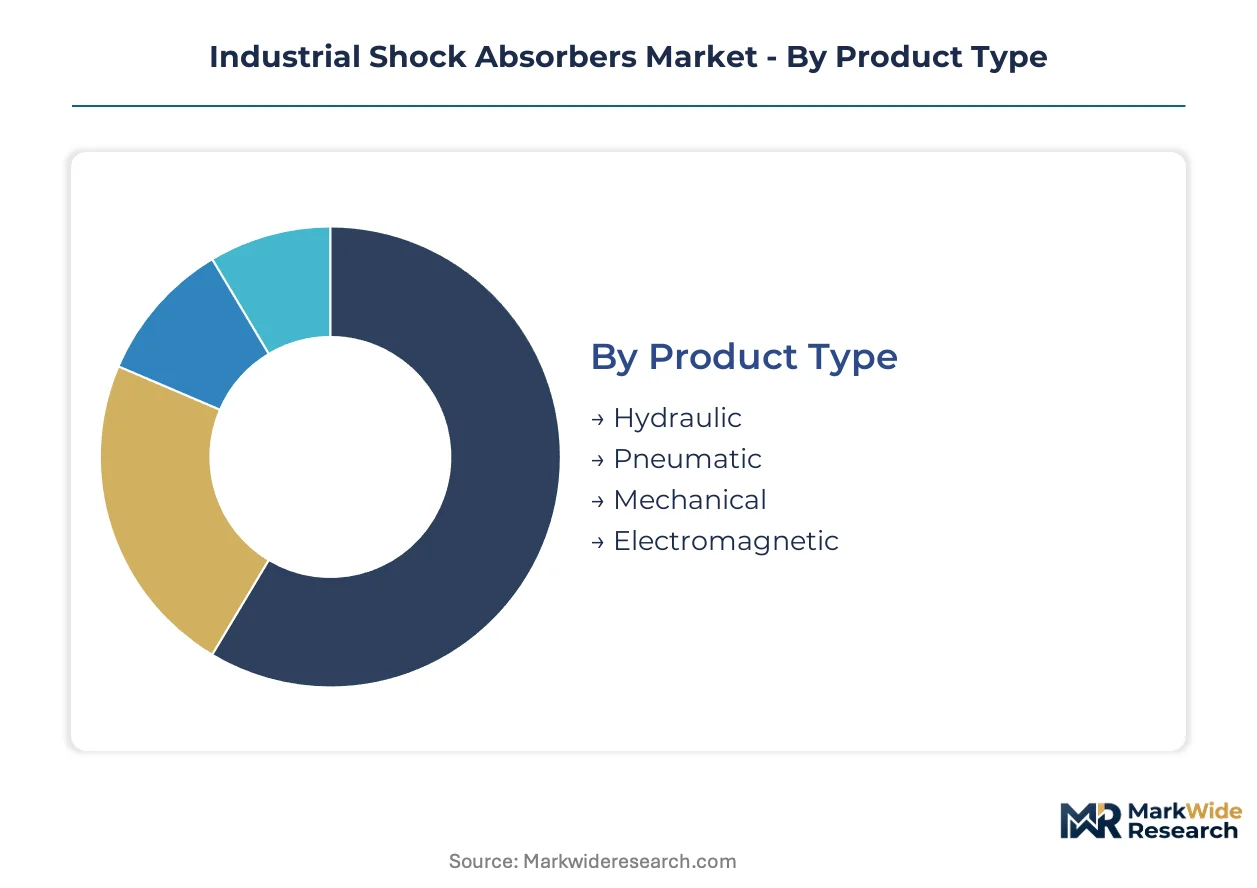
Industrial shock absorber procurement decisions hinge on certification requirements that vary sharply across product architectures and end-use environments. Suppliers must align testing protocols with machinery directive mandates, OSHA guarding standards, and semiconductor cleanroom specifications to secure specification approval.
Product Type:
Hydraulic units carry the heaviest certification burden under EPA spill containment and REACH fluid formulation rules, while electromagnetic designs face IEC functional safety scrutiny for collaborative robot integration.
- Hydraulic:Fluid-filled cylinders dissipate kinetic energy through orifice-controlled oil displacement, rated for strokes up to 300 mm and loads exceeding 50 kN. German automotive stamping lines in Stuttgart and Dortmund specify these for heavy-press protection, though REACH Annex XVII is forcing bio-based fluid transitions that extend validation timelines.
- Pneumatic:Compressed gas chambers provide adjustable damping through regulated air displacement, eliminating hydraulic leak risks in food processing and clean manufacturing. South Korean semiconductor fabs are specifying sealed pneumatic architectures to bypass EPA containment exposure while meeting sustainability procurement scorecards.
- Mechanical:Spring and elastomer compression systems deliver fixed-rate energy absorption without fluid maintenance. These dominate legacy aerospace assembly jigs where programmable profiles offer limited incremental value.
- Electromagnetic:Magnetorheological fluid technology enables real-time damping adjustment through magnetic field modulation. Wafer handling OEMs in Taiwan are adopting these for sub-micron positioning accuracy, compressing margins previously commanded by precision hydraulic units.
Hydraulic sits at the top of the volume ranking, with electromagnetic climbing the fastest.
Application:
Cost stratification across application verticals separates premium-certified precision systems from standard industrial grades.
- Automotive:Robotic material handling systems on vehicle assembly lines require kinetic energy management for cycle rate optimization and collision protection. Tier-1 integrators in Germany's industrial belt now demand outcome-based performance guarantees rather than component specifications.
- Aerospace:Assembly line fixtures and landing gear test rigs specify high-reliability damping for structural load management. Defense procurement is driving semi-active system trials for unpredictable load conditions.
- Machinery:General industrial equipment represents the broadest installed base, spanning stamping presses, conveyor systems, and automated storage retrieval. Price competition is intense among regional suppliers serving mid-volume OEMs.
- Electronics:Semiconductor fabrication and PCB assembly demand ultra-clean damping solutions with programmable positioning profiles. This vertical captures expanding margin pools as electromagnetic substitution accelerates.
Machinery commands the largest revenue base, with electronics gaining share fastest on precision manufacturing automation.
End User:
Customer type determines procurement sophistication, with defense and transportation infrastructure buyers driving semi-active technology trials while construction remains price-sensitive.
- Manufacturing:Automated production environments across automotive, electronics, and consumer goods represent core demand. OSHA machine guarding standards compel certified shock absorption specification, directly expanding addressable demand for tested products.
- Construction:Heavy equipment and infrastructure applications favor passive hydraulic systems for reliability under harsh conditions. Procurement emphasizes initial cost over lifecycle performance.
- Transportation:Rail, heavy truck, and material handling equipment OEMs are testing semi-active damping for variable load adaptation. German machinery builders are responding fastest to ECHA enforcement timelines.
- Defense:Military vehicle and weapons platform programs specify ruggedized damping for unpredictable terrain and recoil management. These applications are gaining traction where passive technology underperforms.
Manufacturing dominates unit volume, with defense showing the steepest expansion trajectory on semi-active system adoption.
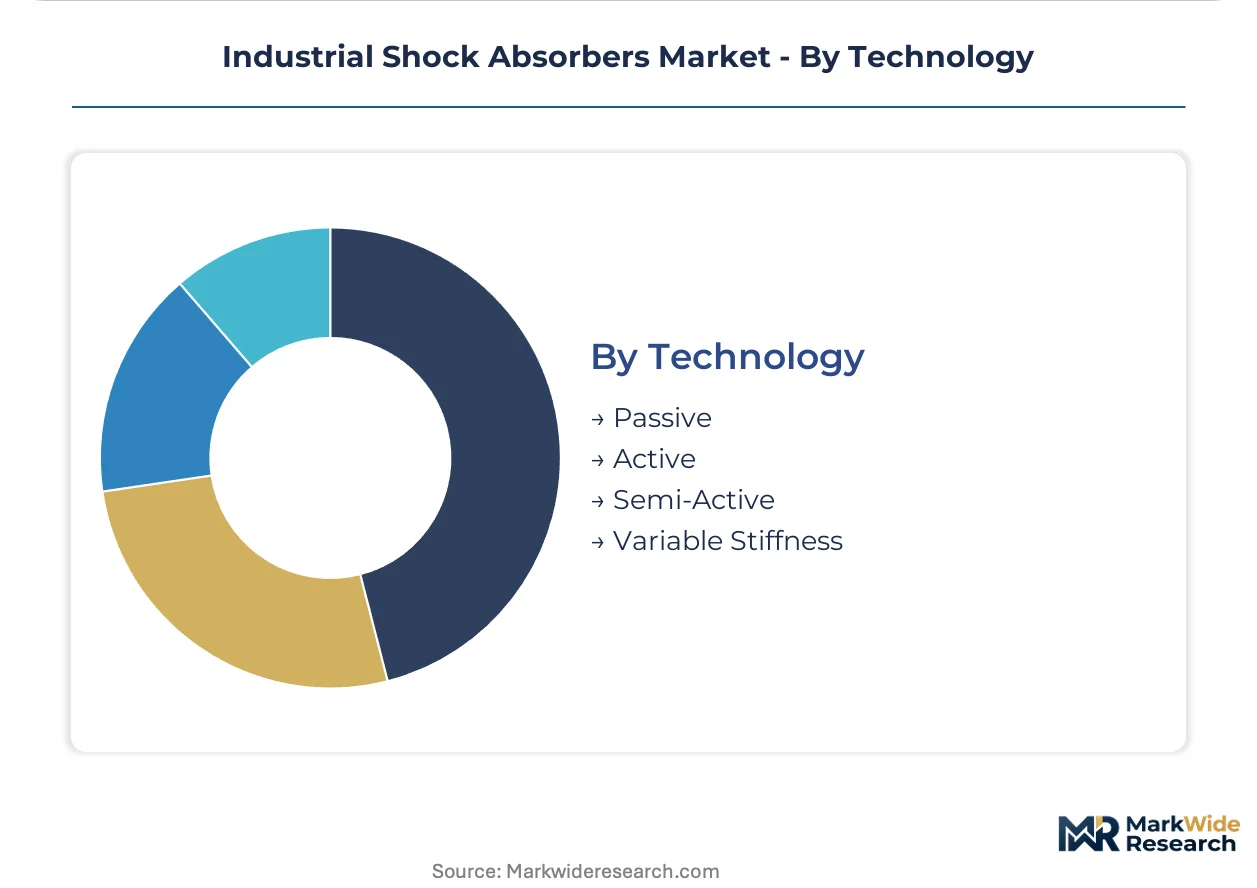
Technology:
Technology maturity separates established passive architectures from emerging programmable systems that require control engineering integration.
- Passive:Fixed-parameter hydraulic and mechanical designs occupy the majority of installed base across automotive stamping and aerospace assembly lines. These systems offer proven reliability but lack adaptability to varying load conditions.
- Active:Externally powered actuation with sensor feedback enables precise force control, though complexity limits adoption to specialized test equipment and research applications.
- Semi-Active:Magnetorheological and electrorheological systems adjust damping in milliseconds without external power for force generation. Defense and transportation infrastructure buyers are specifying these for unpredictable load environments.
- Variable Stiffness:Emerging architectures modulate structural compliance through mechanical or material means, targeting collaborative robot safety applications where IEC standards are still evolving.
Passive retains the largest installed base, with semi-active expanding most quickly on programmable damping demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as manufacturers migrate capacity toward jurisdictions with REACH-aligned but less burdensome enforcement timelines. ECHA compliance costs in Western Europe now exceed bio-based fluid reformulation expenses in North American and select Asian facilities.
Germany
Automotive stamping press OEMs and robotic integrators in Stuttgart and Dortmund drive precision damping procurement. ECHA enforces REACH Annex XVII substance restrictions with accelerating inspection frequency. Baden-Württemberg's machinery cluster demands rapid custom prototyping capabilities from captive polymer compounders.
United States
Semiconductor fabrication equipment builders and aerospace assembly line operators specify certified shock absorption for OSHA machine guarding compliance. EPA spill containment rules under the Clean Water Act constrain hydraulic fluid storage architectures. Michigan's automotive corridor and Arizona's chip fabrication zones concentrate demand for programmable damping systems.
China
Electric vehicle battery assembly automation and electronics manufacturing expand precision kinetic energy management procurement. SAMR enforces GB standards for machinery safety with increasing alignment to IEC functional safety protocols. Yangtze River Delta industrial zones host dense concentrations of robotic material handling system integrators.
South Korea
Wafer handling equipment OEMs and display panel automation lines adopt electromagnetic damping for sub-micron positioning requirements. MFDS and METI-coordinated standards govern collaborative robot safety component certification. Gyeonggi Province semiconductor clusters source magnetorheological units for cleanroom environments.
Japan
Precision automation equipment exports and domestic automotive assembly modernization sustain hydraulic and electromagnetic damping demand. METI administers JIS standards for industrial machinery safety with particular scrutiny on collaborative robot integration. Nagoya's industrial corridor and Osaka's electronics manufacturing belt concentrate specification authority.
Industrial Shock Absorbers Market Competitive Landscape
German producers anchor the premium-tier certification vector; Japanese and American specialists hold scale positions in automotive and semiconductor verticals. The vendor base separates into three functional tiers: integrated motion control providers, captive polymer compounders with rapid prototyping capabilities, and regional hydraulic component fabricators. Dominant competitive moves include backward integration into high-performance elastomer formulation and technology licensing partnerships for magnetorheological fluid architectures.
Among Germany-based specialists, Weforma Dämpfungstechnik GmbH and ZIMMER GROUP exemplify the captive compounding archetype serving machinery OEMs with accelerated custom development cycles. KYB Corporation and ACE Controls Inc. occupy positions spanning automotive heritage adaptation and precision damping specification for robotic material handling. Parker Hannifin Corporation represents the integrated industrial conglomerate model with cross-divisional motion control portfolio breadth.
| Leading Market Players |
|---|
| KYB Corporation |
| ACE Controls Inc. |
| ZIMMER GROUP |
| Weforma Dämpfungstechnik GmbH |
| Parker Hannifin Corporation |
| Pennar Industries Limited |
| Universal Power Conversion, Inc |
| Slam Proof Ltd. |
| BIBUS AG |
| Others |
Supply & Pricing Matrix
Captive polymer compounding in Germany's industrial belt anchors both supply security and pricing power for precision damping suppliers serving Stuttgart's automotive machinery cluster. REACH Annex XVII compliance costs and bio-based fluid reformulation expenses now exceed alternative sourcing economics, compressing margins for non-integrated competitors while reinforcing tiered pricing stratification across certification grades.
Pricing Analysis
Distributor margins of 15-25% separate hydraulic component fabricators from direct-to-OEM suppliers serving Tier-1 automotive integrators. Three-tier pricing structure across certified precision, standard industrial, and economy grades reflects ISO 13849 functional safety tiering and REACH fluid formulation compliance status. Cost compression in economy hydraulic units is intensifying because electromagnetic substitution threatens conventional product lines in semiconductor fabrication. Construction equipment buyers exhibit highest price sensitivity, while electronics manufacturing procurement teams prioritize programmable damping accuracy over unit cost.
Supply Chain Analysis
Domestic-content mandates in South Korea's semiconductor equipment sector and China's electric vehicle battery automation are reshaping sourcing patterns for magnetorheological fluid architectures. Manufacturing concentration rests on Germany, China, and Japan, with high-performance elastomer formulation drawing from specialized Central European compounders. Supply chain vulnerability centers on single-source magnetorheological fluid suppliers concentrated in East Asia. Distribution runs through authorized industrial distributors serving regional machinery OEMs, with direct OEM relationships dominating high-volume automotive and electronics verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Automotive assembly automation is shifting procurement specifications toward certified precision systems with lifecycle performance guarantees rather than component-level sourcing.
For Market Incumbents: Acquire captive elastomer compounding capabilities to secure input cost control against REACH-driven formulation volatility. Consolidate testing and certification infrastructure to compress validation timelines for collaborative robot safety compliance. Electromagnetic substitution in semiconductor wafer handling represents the primary technology threat requiring defensive R&D repositioning. For New Entrants and Emerging Players: Magnetorheological fluid system engineering offers technology-first entry into electronics manufacturing verticals where incumbent hydraulic suppliers lack programmable positioning expertise. Target South Korean and Taiwanese semiconductor equipment OEMs with sub-micron accuracy specifications underserved by legacy damping architectures. Partner with regional system integrators for cleanroom qualification and aftermarket service coverage rather than building direct sales infrastructure. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap captive compounders with rapid prototyping capabilities because machinery OEM procurement consolidation is compressing supplier counts to preferred partners with integrated motion control portfolios. Five-to-ten-year viability hinges on electromagnetic technology transition timing and functional safety certification moat durability. Monitor IEC 62061 collaborative robot safety standard finalization as the critical inflection signal for specification power redistribution.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Elastomer Compounding | Captive polymer formulation secures REACH-compliant supply for German machinery OEMs. |
| Electromagnetic Technology Licensing | Magnetorheological fluid partnerships enable entry into semiconductor wafer handling systems. |
| Functional Safety Certification Investment | IEC 61508 compliance creates specification barriers for collaborative robot integration applications. |
| Sealed Pneumatic Architecture Development | Bio-based fluid alternatives bypass EPA spill containment exposure in food processing equipment. |
| Outcome-Based Performance Contracting | Lifecycle liability assumption aligns with Stuttgart automotive Tier-1 procurement consolidation trends. |
Research Methodology
Bottom-up automotive and electronics manufacturing modeling reconciled against top-down hydraulic and electromagnetic component production tracking forms the analytical core. Primary interviews with plant engineers at German automotive stamping facilities, OEM procurement teams in Stuttgart and Dortmund, semiconductor equipment builders in South Korea and Taiwan, and aftermarket service heads at regional distributors were validated against secondary sources including ECHA substance restriction databases, OSHA machine guarding enforcement records, IEC functional safety standard drafts, and SEC filings from publicly traded motion control conglomerates.
Input-output matrices mapped energy dissipation device shipments across product architecture, application vertical, end-user category, and technology maturity segments throughout the forecast period. CAGRs were derived from regression analysis of capital expenditure patterns in vehicle assembly automation and electronics manufacturing precision equipment. Industry-specific forecast inputs included collaborative robot deployment trajectories, REACH Annex XVII enforcement timelines, and magnetorheological fluid patent expiration schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to electromagnetic substitution velocity and ECHA bio-based substance mandate acceleration. Forecasts reflect documented assumptions regarding machinery OEM procurement consolidation pace and functional safety standard adoption curves. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Electric Power Steering Market
Automotive Parts
Global Automotive Plastics Market
Automotive Parts
Automotive Lifts Market
Automotive Parts
Thin-Section Ball Bearings Market
Automotive Parts
Nigeria Commercial Vehicles Lubricants Market
Automotive Parts
Global Automotive Closure Market
Automotive Parts
Automotive Fuel Supply System Market
Automotive Parts
Vehicle Jump Starter Market
Automotive Parts
Mexico Automotive Parts Aluminum Die Casting Market
Automotive Parts
Steel Cords for Radial Tyres Market
Automotive Parts
Transfer Case Market
Automotive Parts
Engine Fogging Oil Market
Automotive Parts
Canada Automotive Actuators Market
Automotive Parts
France Automotive Actuators Market
Automotive Parts
Engine Oil Pan Market
Automotive Parts
Latin America Electric Power Steering Market