
 Advanced Traffic Management System (ATMS) Market | 2026-2036
Advanced Traffic Management System (ATMS) Market Size, Share, and Industry Trends Forecast 2026-2036
Advanced Traffic Management System (ATMS) Market Intelligence
Aftermarket service revenue is narrowing toward software subscription and data analytics tiers as hardware commoditization pressures legacy business models. Siemens Mobility leverages its European installed base to sustain recurring maintenance contracts across urban corridor networks. Swarco anchors Nordic and Central European markets through specialized signal controller manufacturing. Hitachi competes in Asia-Pacific rail-integrated traffic systems, extending its mobility platform beyond standalone road management.
An Advanced Traffic Management System orchestrates real-time traffic flow through sensor networks, adaptive signal algorithms, and centralized command platforms operating at sub-second latency thresholds, primarily serving municipal and highway operators seeking congestion mitigation and incident response automation. The component dimension shows traffic sensors and control devices carrying established margin pools while communication networks absorb disproportionate capital allocation as fiber and 5G backhaul expand. Cloud computing within the technology dimension is displacing on-premise data management systems fastest among mid-sized municipal agencies seeking scalable analytics without dedicated IT infrastructure.
The US Federal Highway Administration coordinates state-level deployment standards through MUTCD guidelines, while the EU Green Deal and F-Gas Regulation shape European procurement toward energy-efficient control equipment and reduced sensor network emissions. India's Ministry of Road Transport and Highways mandates ITS integration under NHAI smart corridor initiatives, tightening compliance for foreign equipment suppliers. Stakeholders must weigh interoperability standards against proprietary platform lock-in as procurement shifts from discrete hardware bids to integrated system-of-systems contracts.
Market Dynamics
Cloud computing integration is redirecting vendor investment toward software-centric revenue models, compressing traditional hardware margins while expanding recurring service income pools across municipal procurement channels.
Growth Catalysts
- Adaptive Signal Algorithms:Real-time corridor optimization reduces intersection delay metrics by 15-30% in deployed urban networks. Municipal agencies prioritize these systems under federal infrastructure modernization frameworks.
- EU Green Deal Procurement Mandates:European corridor management contracts now require energy-efficient control equipment and reduced sensor network emissions, redirecting capital toward compliant system architectures.
- 5G Backhaul Expansion:Fiber and cellular infrastructure investment enables sub-second latency for centralized command platforms, unlocking scalable deployment across mid-sized urban jurisdictions.
Market Restraints
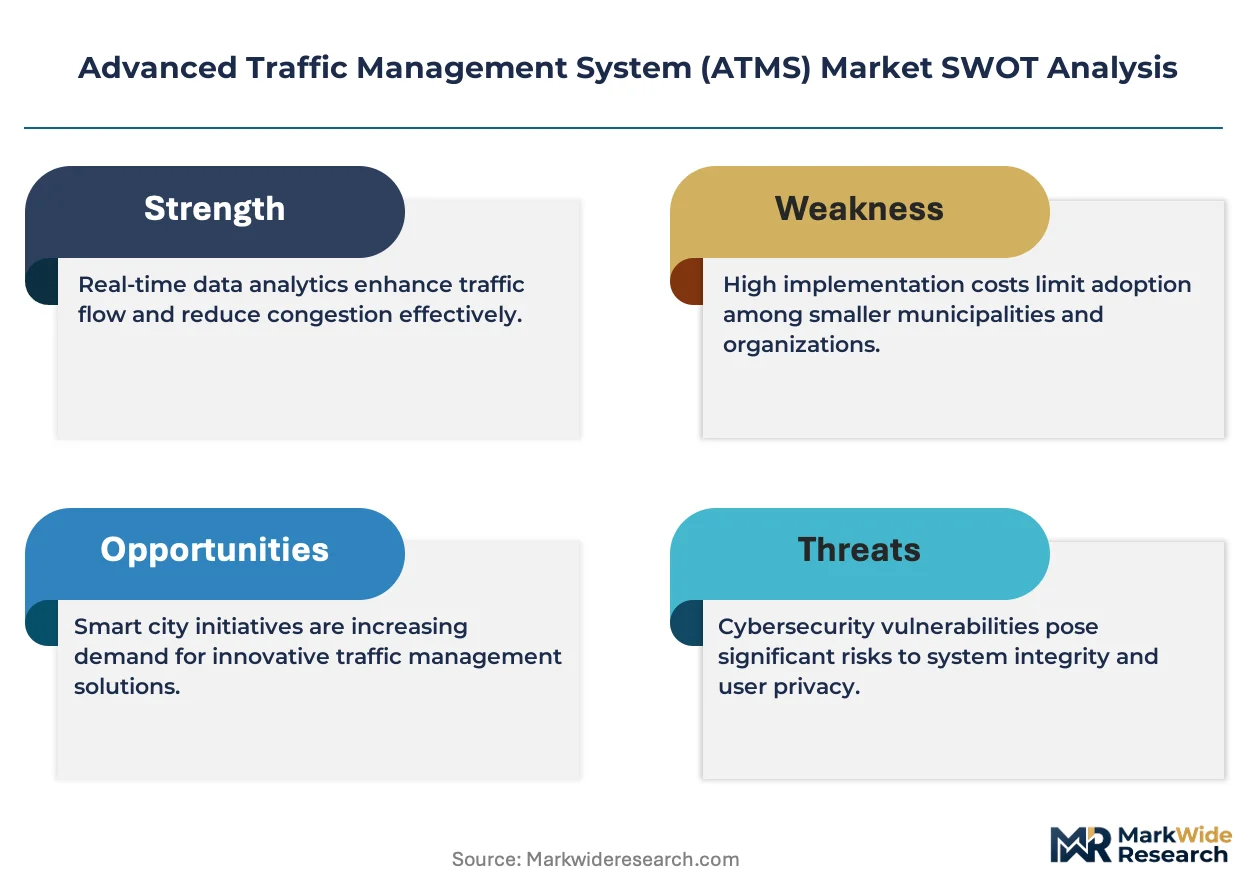
- Copper and Semiconductor Input Volatility:Traffic sensor manufacturing faces margin pressure from commodity price swings in specialized electronic components and wiring harness materials.
- Proprietary Platform Lock-in:Integrated system-of-systems contracts create switching costs that deter competitive displacement, entrenching incumbent vendor positions in established corridors.
- Legacy On-Premise Infrastructure:Dedicated IT infrastructure requirements in large metropolitan agencies slow cloud migration timelines and fragment standardization efforts.
Strategic Opportunities
- Rail-Integrated Traffic Systems:Convergence of road management with transit signaling platforms creates cross-modal optimization demand in dense Asian and European urban clusters.
- India NHAI Smart Corridors:National highway authority mandates for ITS integration under tightening compliance frameworks open procurement channels for foreign equipment suppliers meeting BIS certification requirements.
- Edge Computing Convergence:Distributed processing at signal controller nodes reduces backhaul bandwidth requirements while enabling real-time anomaly detection without centralized latency.
Industry Challenges
- Interoperability Standardization Delays:Fragmented communication protocols between sensor networks and central platforms force costly middleware development and extend integration timelines.
- Cybersecurity Skill Gaps:Municipal agencies lack specialized talent to harden connected infrastructure against intrusion, creating liability exposure and insurance cost escalation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Advanced Traffic Management System (ATMS) Market |
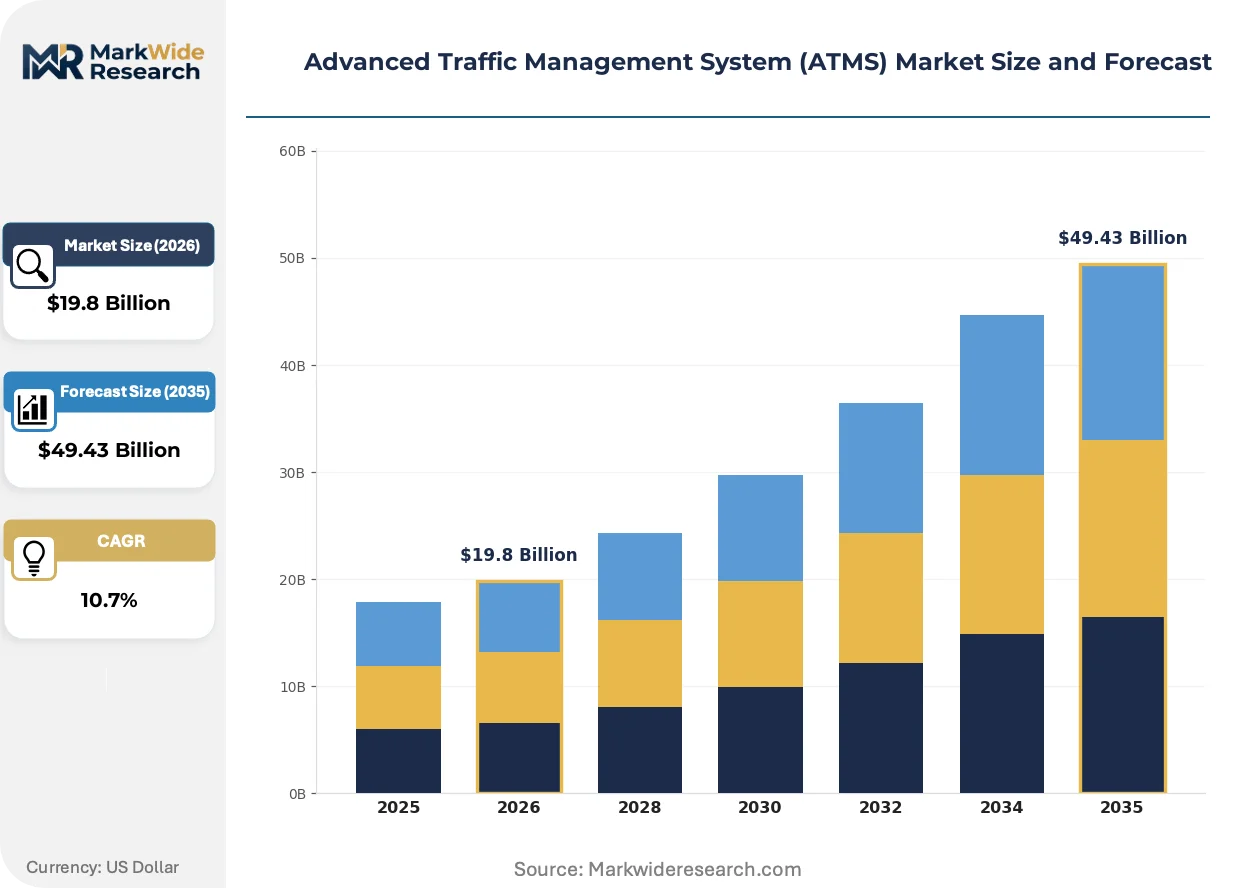
| Market Size in 2026 | $19.8 Billion |
| Market Size in 2035 | $49.43 Billion |
| CAGR (2026 – 2036) | 10.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component: Traffic Sensors, Control Devices, Communication Networks, User Interfaces, Data Management Systems Technology: Vehicle Detection, Adaptive Signal Control, Video Analytics, Incident Detection, Cloud Computing Application: Congestion Management, Incident Management, Parking Management, Public Transit Management, Emergency Response End User: Traffic Authorities, Municipal Agencies, Highway Operators, Transport Consultants, Infrastructure Providers |
| Companies Covered | Watsoo, Kent ITS, Siemens Mobility, Technova Systems, Metro Infrasys, Swarco, Comvision, Ador, Hitachi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Advanced Traffic Management System (ATMS) Market Strategic Shifts & Innovations
Software-defined traffic infrastructure is compressing hardware differentiation while elevating data analytics and predictive modeling as primary competitive battlegrounds. Vendors now compete on algorithm performance rather than controller specifications.
Edge AI processing at signal controller nodes is digitizing intersection decision-making, shifting computation from centralized servers to distributed hardware. Mid-sized municipal agencies in Germany and the Netherlands deploy these architectures fastest, avoiding dedicated data center capital while achieving real-time adaptive response. This compression of the compute stack is digitizing procurement evaluation criteria toward software benchmarks.
EU F-Gas Regulation phase-down mandates are accelerating replacement of conventional sensor cooling systems with solid-state alternatives in European corridor deployments. Equipment suppliers must redesign thermal management architectures to maintain measurement precision without fluorinated refrigerants. Nordic and Central European markets exhibit the steepest compliance-driven replacement cycles.
Performance-based service contracting is displacing discrete hardware procurement in North American municipal budgets. Agencies now purchase congestion reduction outcomes rather than signal controllers, transferring operational risk to vendors. This model concentrates fastest in US states with MUTCD guideline alignment and available federal infrastructure funding streams.
Advanced Traffic Management System (ATMS) Market Segmentation
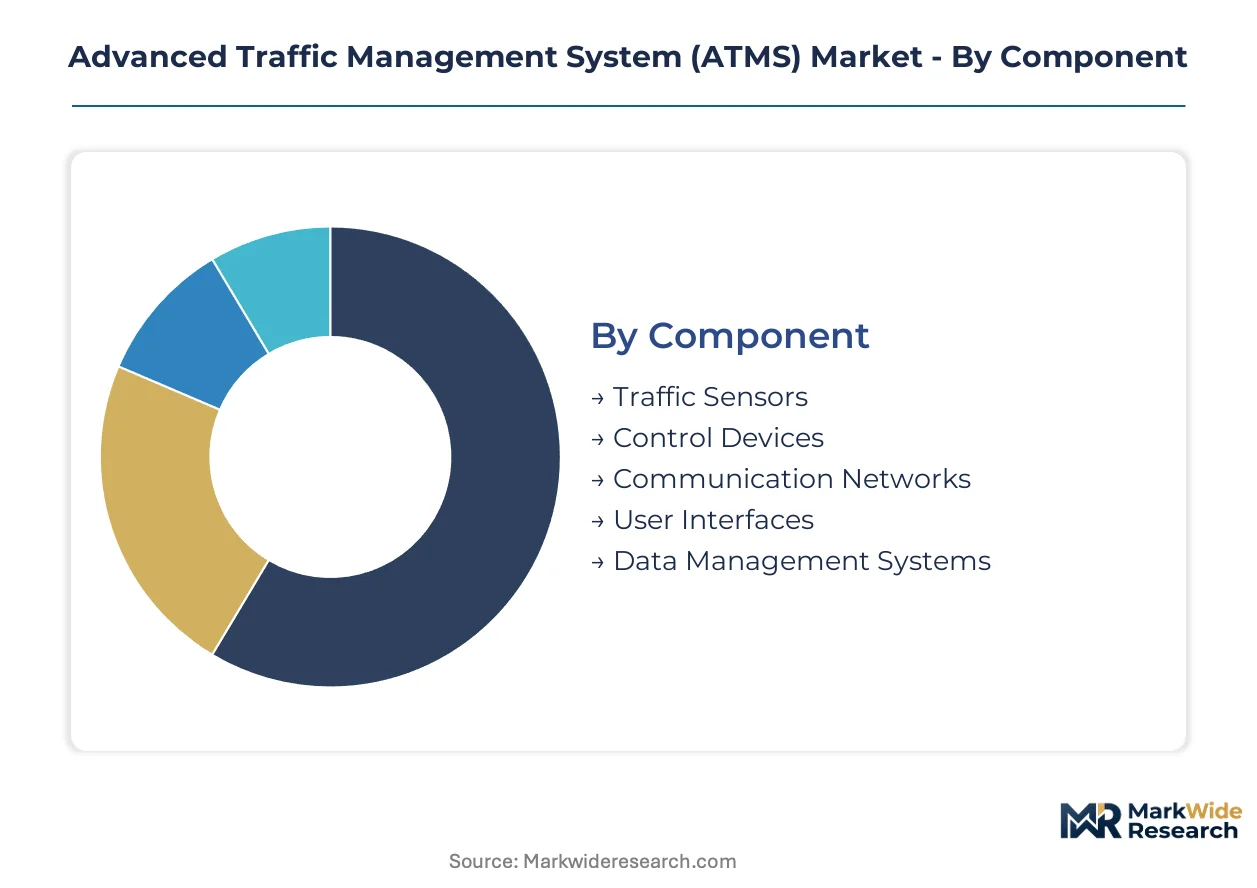
ATMS procurement patterns diverge sharply between legacy infrastructure retrofits and greenfield smart city deployments. Municipal buyers prioritize component modularity to preserve interoperability across vendor generations. Technology selection increasingly hinges on latency specifications and cloud-readiness rather than hardware durability metrics.
Component:
Deployment scale spans single-intersection retrofits to thousand-node regional networks, driving divergent unit economics and integration complexity.
- Traffic Sensors:Inductive loops, radar units, and lidar arrays capture vehicle presence and classification data at millisecond resolution. German corridor networks under KBA safety mandates anchor European demand for multi-modal detection arrays.
- Control Devices:Signal controllers and variable message signs execute algorithmic commands with hard real-time constraints. US state DOTs under MUTCD guidelines concentrate procurement of NTCIP-compliant controllers for arterial corridor upgrades.
- Communication Networks:Fiber backhaul and 5G private networks transport telemetry between field devices and command centers.
- User Interfaces:Touchscreen consoles and mobile dashboards present operators with situational awareness overlays.
- Data Management Systems:On-premise servers and hybrid cloud architectures store historical traffic patterns for predictive modeling.
Established volume favors control devices; emerging adoption favors data management systems.
Technology:
Algorithm sophistication separates premium deployments from baseline compliance-driven installations.
- Vehicle Detection:Computer vision and magnetic sensing identify vehicle presence, speed, and classification. Video analytics platforms in Dutch urban networks leverage edge AI to reduce centralized processing loads.
- Adaptive Signal Control:Real-time optimization algorithms adjust signal timing based on upstream traffic conditions. Indian NHAI smart corridors under BIS certification requirements drive fastest adoption in Asian markets.
- Video Analytics:Automated incident recognition and license plate extraction from CCTV feeds.
- Incident Detection:Automated collision identification and emergency service dispatch triggering.
- Cloud Computing:Scalable data lakes and API-first architectures replace on-premise server farms.
Mature deployments emphasize adaptive signal control; greenfield installations prioritize cloud computing architectures.
Application:
Functional priorities shift between congestion reduction mandates and safety-critical emergency response capabilities.
- Congestion Management:Arterial optimization and corridor synchronization reduce travel time variability. California municipal agencies under SB 743 vehicle miles traveled regulations deploy these systems for compliance-driven network balancing.
- Incident Management:Automated collision detection and dynamic lane control accelerate clearance times. Tokyo Metropolitan Police Department specifications shape Japanese procurement for tunnel and expressway safety systems.
- Parking Management:Guidance systems directing drivers to available spaces via dynamic signage.
- Public Transit Management:Signal priority and dwell time optimization for bus and light rail networks.
- Emergency Response:Preemption systems clearing intersections for ambulances and fire apparatus.
Congestion management commands current capital allocation; incident management claims steepest expansion trajectory.
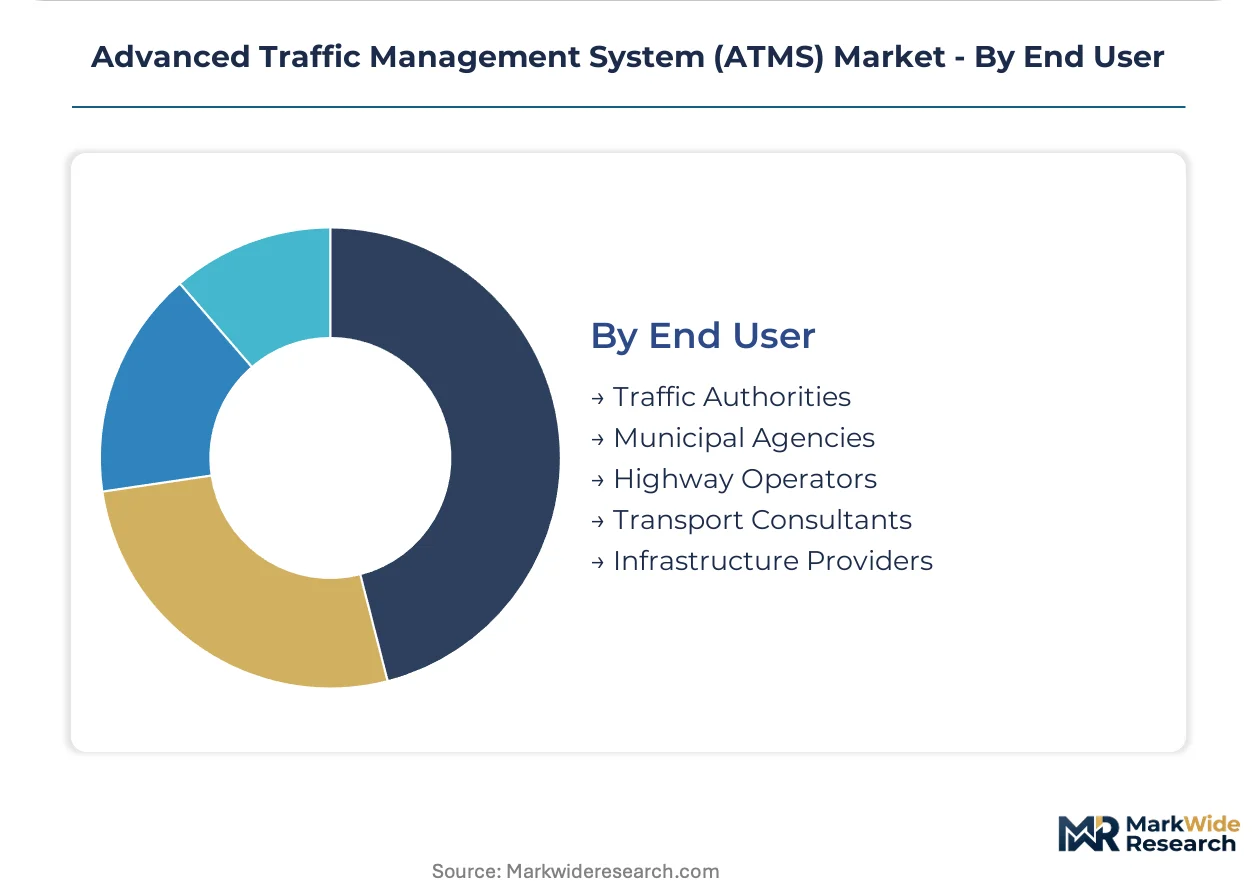
End User:
Budget authority and technical staffing determine procurement sophistication and vendor relationship models.
- Traffic Authorities:Regional agencies managing multi-jurisdiction signal coordination and corridor optimization. Transport for London specifications influence procurement standards across UK urban networks.
- Municipal Agencies:City departments operating localized intersection control with limited integration scope. Mid-sized US cities under IIJA funding streams represent fastest-scaling customer segment.
- Highway Operators:Toll road concessionaires and state turnpike authorities managing high-speed corridor networks.
- Transport Consultants:Engineering firms designing systems on behalf of public agency clients.
- Infrastructure Providers:Private developers integrating traffic systems into commercial and residential projects.
Traffic authorities dominate contract value; municipal agencies drive unit volume expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between geographies: European agencies prioritize energy-efficient corridor retrofits under environmental mandates, while Asian markets emphasize rail-integrated systems and North American procurement centers on adaptive signal algorithms for congestion mitigation.
United States
Federal infrastructure funding streams through the IIJA accelerate municipal adoption of adaptive signal control systems. The Federal Highway Administration's MUTCD guidelines standardize procurement specifications across state DOTs. California agencies under SB 743 vehicle miles traveled regulations deploy corridor optimization networks fastest, with Los Angeles and San Francisco metropolitan areas anchoring western deployment.
Germany
KBA safety mandates drive multi-modal detection array procurement for autobahn and urban corridor networks. The EU Green Deal and F-Gas Regulation redirect capital toward solid-state sensor cooling systems and reduced-emission control equipment. Swarco anchors Nordic and Central European supply through specialized signal controller manufacturing concentrated in the Stuttgart industrial corridor.
India
NHAI smart corridor initiatives mandate ITS integration under tightening BIS certification requirements for foreign equipment suppliers. The Ministry of Road Transport and Highways enforces compliance frameworks that accelerate procurement of adaptive traffic systems. Mumbai-Delhi industrial corridors and Bangalore's tech hub concentrate deployment of video analytics and incident detection platforms.
Japan
Tokyo Metropolitan Police Department specifications shape procurement for tunnel and expressway safety systems with sub-second latency requirements. METI standards govern rail-integrated traffic platform convergence in dense urban clusters. Osaka-Kobe and Nagoya manufacturing belts anchor deployment of edge AI processing at signal controller nodes.
United Kingdom
Transport for London specifications influence procurement standards across UK urban networks prioritizing congestion management outcomes. The Department for Transport coordinates national deployment frameworks aligned with EU-derived environmental standards. Manchester and Birmingham metropolitan regions lead regional corridor management system upgrades outside the capital.
Advanced Traffic Management System (ATMS) Market Key Industry Players
Capability concentration sits with specialized signal controller and sensor manufacturers; scale advantage sits with diversified mobility platform providers spanning rail and road integration. The vendor base organizes around three strategic archetypes: European corridor system specialists, Asia-Pacific rail-integrated platform builders, and North American adaptive algorithm developers. Consolidation pressures favor integrated system-of-systems contracts over discrete hardware procurement. Dominant competitive moves include strategic partnerships for cloud platform integration and geographic expansion through compliance certification in regulated procurement markets.
Within the European specialist tier, Siemens Mobility and Swarco occupy anchor positions leveraging regional installed bases. Siemens Mobility exemplifies the diversified platform archetype with recurring maintenance contract structures across urban corridor networks. Swarco represents the specialized controller manufacturing segment with concentrated presence in Nordic and Central European markets. Hitachi sits within the Asia-Pacific rail-integrated systems archetype, extending mobility platforms beyond standalone road management into multimodal optimization. These three company structures illustrate the competitive divergence between software-centric recurring revenue models and hardware-anchored system integration approaches.
| Leading Market Players |
|---|
| Watsoo |
| Kent ITS |
| Siemens Mobility |
| Technova Systems |
| Metro Infrasys |
| Swarco |
| Comvision |
| Ador |
| Hitachi |
| Others |
Cost & Logistics Intelligence
The Rotterdam-Antwerp freight corridor's volatile container rates compress hardware margins while amplifying software subscription premiums across ATMS procurement tiers. Supply concentration in German controller manufacturing and Taiwanese semiconductor fabrication feeds directly into three-tier pricing stratification across premium adaptive systems, standard corridor management, and economy retrofit configurations.
Pricing Analysis
Long-term service contracts dominate municipal procurement, displacing discrete hardware transactions with outcome-based congestion reduction agreements. Price differentiation rests on algorithm performance benchmarks and NTCIP certification tiers, with California DOT specifications commanding premiums over baseline MUTCD compliance. Pricing pressure stems from copper and semiconductor input volatility squeezing sensor manufacturing margins. Mid-sized municipal agencies under IIJA funding streams exhibit highest price sensitivity; large metropolitan traffic authorities prioritize latency specifications over unit cost.
Supply Chain Analysis
Tariff exposure between China and the United States disrupts lidar array and edge processor supply continuity for North American deployments. Manufacturing concentrates in Germany for signal controllers, Taiwan for AI accelerators, and South Korea for 5G modems. Raw material dependencies span rare earth elements for magnetic sensors, high-purity silicon for solid-state lidar, and fluorinated alternatives for EU F-Gas compliant thermal management. Distribution runs through systems integrators bundling hardware, software, and maintenance into unified municipal contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ATMS procurement is crossing into platform economics as interoperability standards fragment proprietary vendor ecosystems. The shift from hardware-centric to software-defined infrastructure rewards ecosystem orchestrators over component specialists.
For Market Incumbents: Build switching-cost moats through deep integration of adaptive algorithms with municipal data lakes, entrenching position against cloud-native challengers. Siemens Mobility's maintenance contract structures across urban corridor networks illustrate defensive bundling of hardware, software, and analytics. Prioritize backward integration into edge AI processor supply to offset semiconductor cost volatility and secure sub-second latency guarantees. For New Entrants and Emerging Players: Build out white-space presence in Indian NHAI smart corridors where BIS certification requirements have slowed foreign incumbent penetration. Target mid-sized US cities under IIJA funding streams lacking dedicated IT infrastructure for cloud-native adaptive signal platforms. Lead with API-first architectures enabling rapid interoperability with legacy NTCIP controller installations, reducing municipal switching friction. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underoptimized traffic management divisions lacking software-centric recurring revenue models. Five-to-ten year viability favors vendors with established cloud platform integration and performance-based contracting capabilities. Monitor MUTCD guideline revision cycles as inflection signals for accelerated municipal replacement spending.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Cloud-native architectures displace on-premise data centers in German municipal deployments. |
| Strategic Partnership | 5G private network alliances with carriers unlock sub-second latency for corridor optimization. |
| Acquisition of Specialist Firm | Edge AI controller startups accelerate real-time anomaly detection without centralized servers. |
| Geographic Expansion | BIS certification investment opens procurement channels under Indian NHAI compliance frameworks. |
| Product Launch | Solid-state sensor cooling systems address EU F-Gas Regulation mandates in Nordic markets. |
Research Approach
Desk research of municipal procurement databases, FHWA MUTCD guideline documentation, and EU Green Deal regulatory filings preceded structured interviews with traffic authority operations directors, state DOT procurement officers, and systems integration engineers. Primary fieldwork validated secondary findings against operating deployment timelines and vendor contract structures. Bottom-up unit economics across sensor, controller, and software tiers were triangulated with top-down infrastructure spending forecasts from federal and state budget appropriations.
Assumptions held IIJA funding continuity and EU environmental mandate enforcement fixed across the projection horizon, while cloud migration velocity and edge AI adoption rates were varied under sensitivity scenarios. Segmentation modeling spanned component type, technology sophistication, application priority, and end-user budget authority. CAGRs were derived from deployment pipeline analysis and vendor revenue mix disclosures. Forecast inputs incorporated 5G backhaul expansion timelines and adaptive algorithm performance benchmarks from deployed urban networks.
Sensitivities concentrate around federal infrastructure funding reauthorization cycles and semiconductor supply normalization trajectories. Forecasts reflect assumptions about municipal procurement standardization and interoperability protocol convergence that may shift with regulatory guidance revisions. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Contactless Ticketing Market
Smart Transportation Solutions
Fleet Health Monitoring and Diagnostic Analytics Systems Market
Smart Transportation Solutions
Bike Sharing Market
Smart Transportation Solutions
New Energy Vehicle Sweeper Market
Smart Transportation Solutions
Thailand Ride Hailing Market
Smart Transportation Solutions
Global V2X Market
Smart Transportation Solutions
Rail Internet of Things (IoT) Market
Smart Transportation Solutions
Global Electric Public Transport Market
Smart Transportation Solutions
Global Smart Highway Market
Smart Transportation Solutions
Smart Transportation Solution Market
Smart Transportation Solutions
Automated Robotic Parking System Market
Smart Transportation Solutions
Real-Time Parking System Market
Smart Transportation Solutions
Smart Logistic Market
Smart Transportation Solutions
Europe Car Parking Market
Smart Transportation Solutions
Smart Ports Market
Smart Transportation Solutions
Rail Freight Digital Transformation Market