
 Germany Electric Bus Battery Pack Market | 2026-2036
Germany Electric Bus Battery Pack Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Electric Bus Battery Pack Market Insights
Urban public transport operators is decoupling from diesel procurement cycles as battery-electric bus mandates tighten across German metropolitan transit authorities. CATL leverages its European manufacturing footprint to supply high-volume lithium-ion cell contracts for depot-fleet operators. Akasol AG anchors its position through specialized pack integration tailored to German OEM chassis specifications. Northvolt AB competes on proximity advantages from its planned German gigafactory operations.
Germany electric bus battery packs are electrochemical energy storage systems engineered from lithium-ion or solid-state cell arrays, typically configured in 300-500 kWh capacities to deliver 200-400 kilometer daily range cycles for heavy-duty urban transit duty. Their primary commercial purpose is to replace internal combustion powertrains with zero-emission alternatives while maintaining route flexibility and passenger load capacity. Lithium-ion chemistry dominates current procurement volumes due to mature supply chains and established recycling protocols through Germany's dual collection system. Solid-state technology is gaining R&D investment intensity as manufacturers target higher energy density thresholds for extended-range intercity applications. Fast charging infrastructure is concentrating margin pools around grid-balancing services and peak-demand management contracts with municipal utilities.
KBA type-approval requirements and EU Battery Regulation traceability mandates are reshaping cell sourcing obligations for pack assemblers serving German operators. Germany's Federal Emission Control Act (BImSchG) transit exemptions and EU Green Deal fleet decarbonization targets are synchronizing procurement timelines across state-level transport associations. Stakeholders must monitor domestic cell manufacturing scale-up against import dependency ratios as carbon border adjustments tighten supply chain disclosure requirements.
Market Dynamics
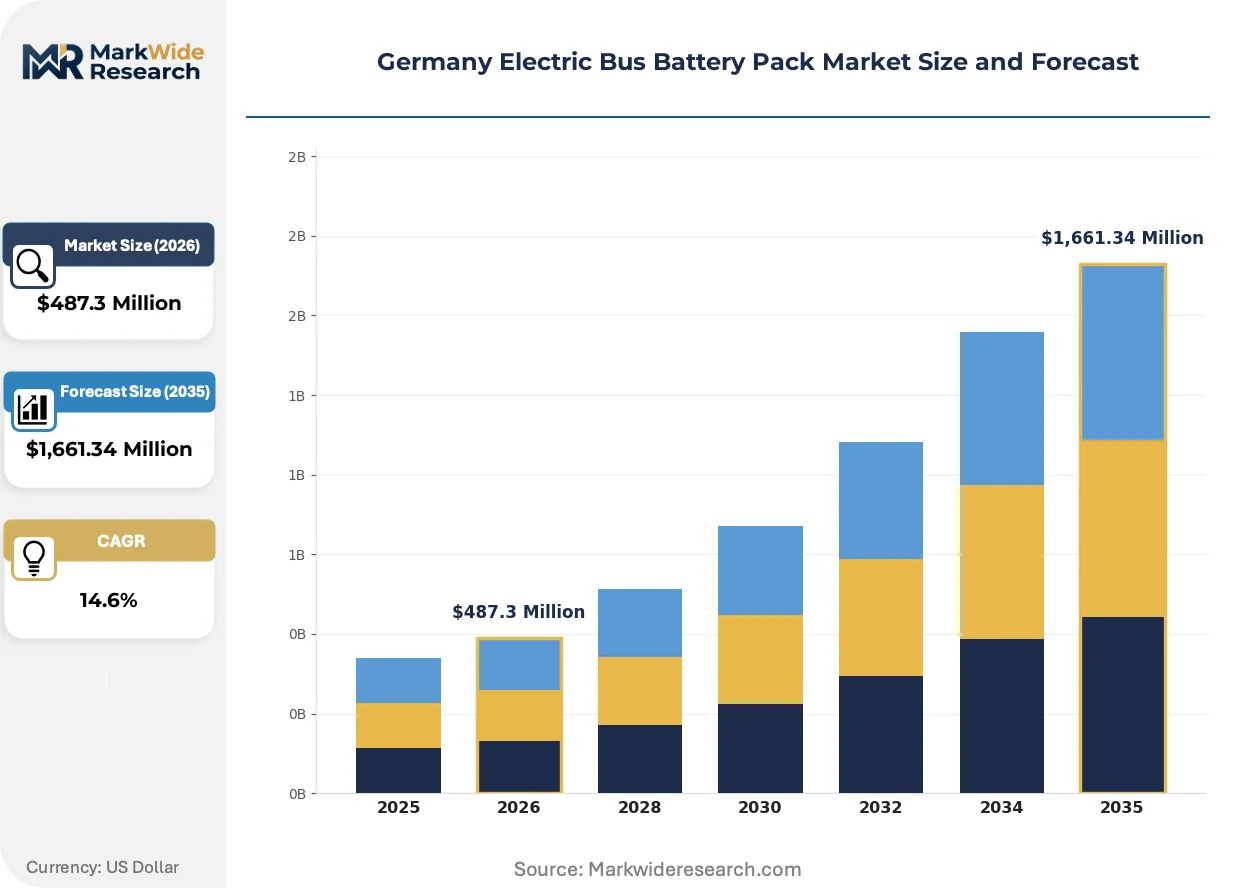
Fleet electrification timelines across German metropolitan transit authorities are compressing procurement cycles as KBA type-approval requirements and EU Battery Regulation mandates synchronize cell sourcing obligations with domestic manufacturing scale-up efforts.
Growth Catalysts
- BMWK Funding Directives:The National Hydrogen and Battery Strategy redirects municipal procurement budgets toward domestic cell sourcing, accelerating depot-fleet electrification across Bavaria and North Rhine-Westphalia transit agencies.
- EU Green Deal Fleet Decarbonization Targets:Binding emission reduction mandates synchronize state-level transport association procurement timelines, eliminating diesel bus replacement options for urban operators.
- Depot Charging Infrastructure Scaling:Grid-balancing service contracts with municipal utilities in Berlin-Brandenburg and Stuttgart corridors create revenue streams that offset battery pack capital expenditure.
Market Restraints
- Lithium-Ion Cell Import Dependency:Germany's domestic cell manufacturing capacity lags behind procurement volume requirements, exposing pack assemblers to carbon border adjustment disclosure risks and supply chain volatility.
- 300-500 kWh Pack Cost Structure:High nickel-content cathode materials and thermal management system complexity maintain capital intensity barriers for smaller municipal operators.
- Solid-State Technical Limitations:Current solid-state electrolyte manufacturing yields and interface stability challenges delay commercial deployment for extended-range intercity applications.
Strategic Opportunities
- North Rhine-Westphalia Corridor Expansion:Underpenetrated mid-sized city transit networks in the Ruhr region present volume growth potential as federal co-funding programs extend beyond metropolitan tier-one operators.
- Second-Life Stationary Storage Convergence:Retired electric bus battery packs are integrating with municipal grid stabilization infrastructure, creating circular economy revenue streams through Germany's dual collection system.
- Fast-Charging Infrastructure Innovation:Opportunity charging pantograph systems at route terminals enable smaller pack configurations, opening procurement to route-flexible mid-capacity operators previously excluded from electrification.
Industry Challenges
- BImSchG Transit Exemption Coordination:Navigating Federal Emission Control Act compliance timelines across sixteen state transport associations creates fragmented certification requirements for pack assemblers serving multi-state operators.
- EU Battery Regulation Traceability Systems:Real-time cell provenance documentation and recycling content verification impose data infrastructure capex burdens on mid-tier pack integrators.
- Depot Grid Integration Complexity:Simultaneous high-power charging of 50+ vehicle fleets demands utility coordination for transformer upgrades and peak demand management protocol development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Electric Bus Battery Pack Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,661.34 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Nickel-metal Hydride, Solid State, Others Capacity: 200 kWh, 300 kWh, 400 kWh, 500 kWh Charging Type: Fast Charging, Regular Charging, Wireless Charging, Opportunity Charging End User: Public Transport Operators, Private Bus Operators, Educational Institutions, Fleet Operators |
| Companies Covered | Contemporary Amperex Technology Co. Ltd. (CATL), BYD Company Ltd., LG Energy Solution Ltd., Samsung SDI Co. Ltd., Northvolt AB, Akasol AG, BMZ Group, VARTA AG, LEAPENERGY, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Electric Bus Battery Pack Market Trends and Innovations
Cell chemistry evolution and regulatory traceability mandates are restructuring competitive positioning around domestic manufacturing proximity and circular economy infrastructure ownership.
Solid-state battery technology is integrating silicon-anode architectures with sulfide-based electrolytes to achieve energy density thresholds exceeding 400 Wh/kg. Stuttgart-based OEM chassis manufacturers are pilot-testing these configurations for 400-kilometer intercity route applications. This chemistry transition is compressing lithium-ion pack lifecycle expectations as operators delay replacement cycles awaiting solid-state commercialization.
The EU Battery Regulation mandatory carbon footprint declarations and recycled content thresholds are reshaping cell sourcing obligations for German pack assemblers. Industrial consequence includes binding due diligence requirements for cobalt, lithium, and nickel supply chains entering the European Economic Area. Pack integrators serving Berlin-Brandenburg municipal operators are responding by securing long-term offtake agreements from Nordic cell producers with verified low-carbon hydroelectric power supply.
Service-unbundling from hardware procurement is restructuring municipal transit authority contracting models. German operators are separating battery pack ownership from vehicle chassis acquisition through third-party energy service agreements. This financial structure is concentrating in North Rhine-Westphalia, where Verkehrsverbund associations aggregate demand across multiple municipal fleets to achieve scale pricing from independent battery asset managers.
Germany Electric Bus Battery Pack Market Segmentation
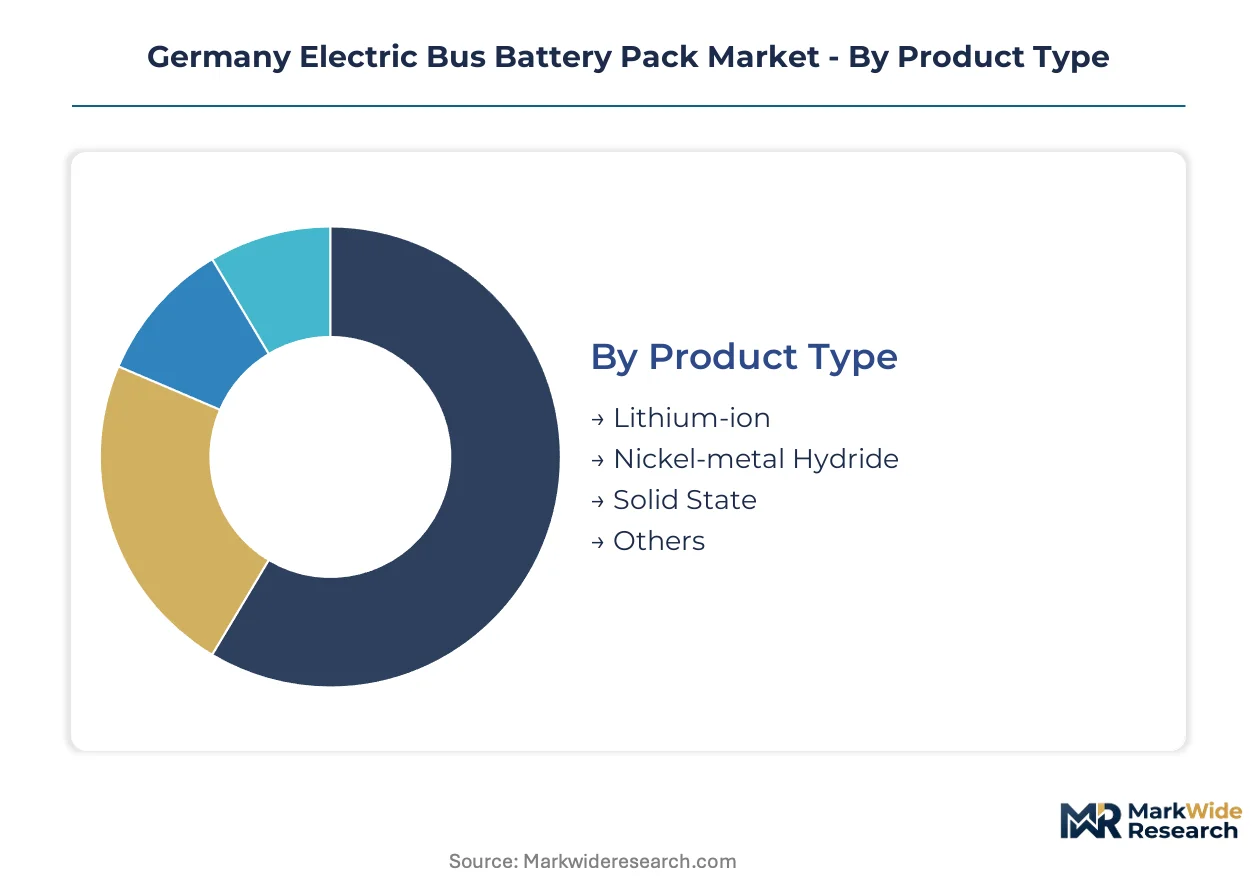
Segmentation in the Germany electric bus battery pack market reveals how capital deployment, route requirements, and procurement structures fragment demand across distinct technical configurations. Each dimension carries specific implications for pack assemblers negotiating with municipal transit authorities and private fleet managers.
Product Type:
Capital intensity varies sharply across chemistries, with solid-state manufacturing demanding multibillion-euro fabrication investments while lithium-ion leverages depreciated European cell capacity.
- Lithium-ion:Nickel-manganese-cobalt and lithium-iron-phosphate cell configurations dominate current procurement, leveraging CATL's Erfurt manufacturing base and established recycling pathways through Germany's dual collection system. Bavarian depot-fleet operators concentrate orders here due to proven KBA type-approval pathways and supply chain traceability compliance with EU Battery Regulation mandates.
- Solid State:Sulfide-based electrolyte architectures with silicon-anode designs target energy density thresholds exceeding 400 Wh/kg for extended-range intercity applications. Stuttgart-based OEM chassis manufacturers pilot-test these configurations, though manufacturing yield challenges and interface stability issues delay commercial deployment beyond metropolitan demonstration corridors.
- Nickel-metal Hydride:Mature chemistry retains niche presence in retrofit applications and legacy fleet extensions where thermal management simplicity outweighs energy density requirements.
- Others:Sodium-ion and lithium-sulfur experimental chemistries occupy pre-commercial R&D phases within BMWK-funded research consortia.
Lithium-ion absorbs the bulk of installed capacity; solid-state is expanding most quickly among next-generation procurement specifications.
Capacity:
Route distance requirements and depot infrastructure constraints segment demand into discrete energy storage tiers, with higher capacities commanding disproportionate thermal management system complexity.
- 300 kWh:Standard configuration for Berlin-Brandenburg urban depot fleets achieves 200-250 kilometer daily range cycles with overnight charging protocols. North Rhine-Westphalia Verkehrsverbund associations aggregate procurement across municipal operators at this tier, optimizing pack ownership economics through third-party energy service agreements.
- 400 kWh:Extended-range specification serves Stuttgart metropolitan corridor routes with inter-suburban segments, requiring enhanced battery management systems and active cooling architectures that elevate capital expenditure thresholds.
- 200 kWh:Compact packs enable route-flexible deployment where opportunity charging infrastructure at terminal stations supplements depot charging cycles.
- 500 kWh:Maximum capacity tier targets 12-meter articulated bus configurations and cold-climate operations where heating loads degrade effective range.
300 kWh configurations anchor procurement volumes; 400 kWh specifications are climbing the fastest as route electrification extends beyond core urban networks.
Charging Type:
Grid integration requirements and fleet utilization patterns differentiate infrastructure investment profiles, with fast-charging systems demanding utility coordination for transformer upgrades.
- Fast Charging:150-350 kW DC systems enable midday range extension for high-frequency routes, concentrating in Berlin-Brandenburg where municipal utility contracts incorporate grid-balancing service revenue streams.
- Opportunity Charging:Pantograph systems at route terminals permit smaller pack configurations, opening procurement to mid-capacity operators previously excluded from electrification by overnight depot constraints.
- Regular Charging:Standard AC overnight protocols dominate Bavarian depot-fleet operations where extended dwell times accommodate slower charge cycles.
- Wireless Charging:Inductive pad systems remain pilot-phase deployments in Mannheim and Brunswick demonstration corridors, constrained by efficiency losses and infrastructure capital intensity.
Fast charging captures the dominant share of new infrastructure deployment; opportunity charging is gaining share fastest as route-terminal electrification accelerates.
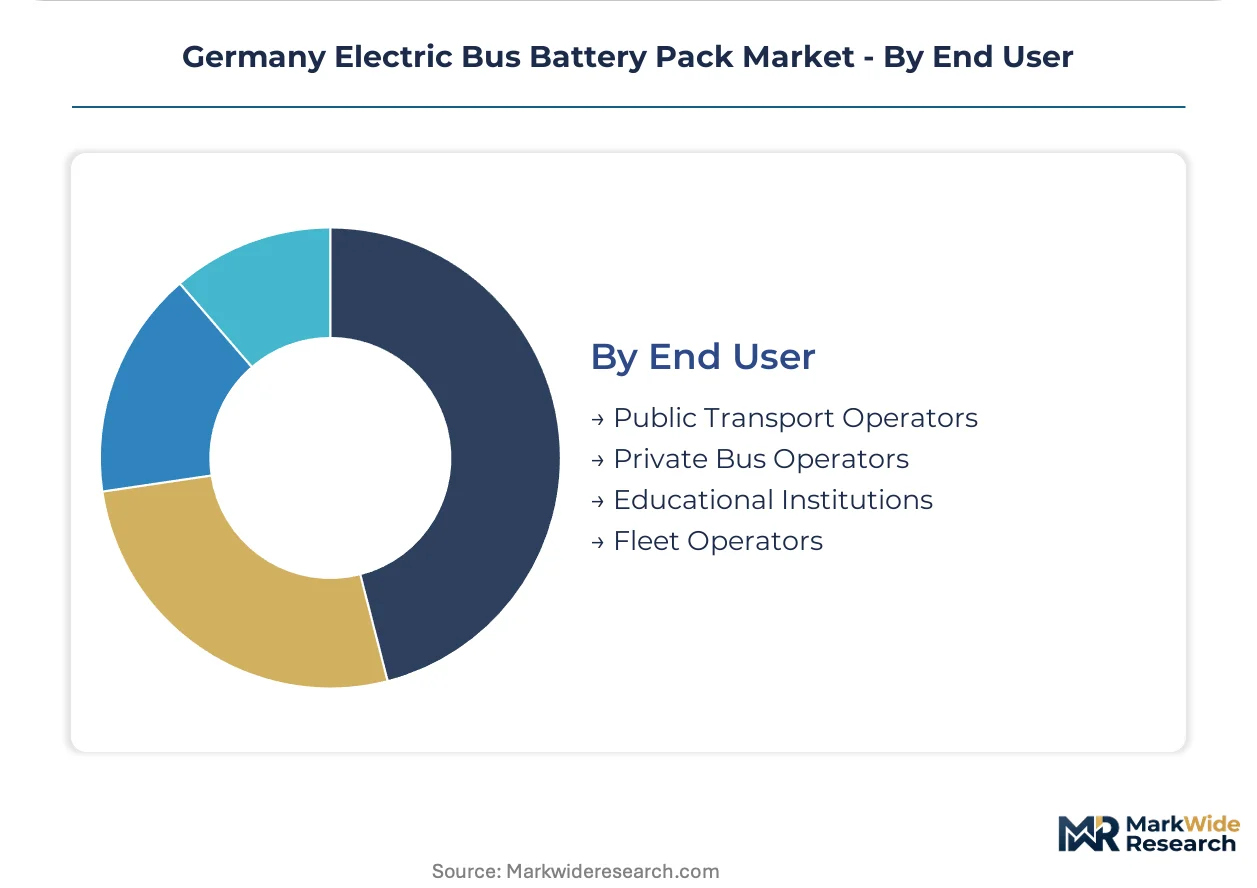
End User:
Procurement scale and financing sophistication fragment demand across public and private ownership structures, with public transport operators leveraging federal co-funding unavailable to commercial counterparts.
- Public Transport Operators:Municipal transit authorities in Bavaria and North Rhine-Westphalia drive procurement volumes through BMWK-funded fleet electrification mandates, aggregating demand via state transport associations to achieve scale pricing.
- Fleet Operators:Private logistics and corporate shuttle providers represent emerging demand concentration, particularly for airport and industrial park circulation services where route predictability supports battery-electric economics.
- Private Bus Operators:Commercial intercity and tour bus companies face capital intensity barriers without federal co-funding access, delaying electrification beyond regulatory minimums.
- Educational Institutions:University and school district fleets constitute fragmented, price-sensitive demand with limited procurement sophistication.
Public transport operators command the preponderance of installed base; fleet operators are expanding most quickly as private electrification mandates tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Berlin-Brandenburg's special economic zones for clean technology manufacturing concentrate federal co-funding and municipal procurement aggregation. Bavaria and North Rhine-Westphalia anchor electrification timelines through state transport association mandates.
Bavaria
Munich's metropolitan transit authority drives 300 kWh pack procurement through depot-fleet overnight charging protocols. BMWK funding directives under the National Hydrogen and Battery Strategy redirect municipal budgets toward domestic cell sourcing. The Munich-Augsburg corridor hosts CATL's Erfurt manufacturing base supplying nickel-manganese-cobalt configurations.
North Rhine-Westphalia
Verkehrsverbund associations aggregate demand across Ruhr region municipal operators for scale pricing from independent battery asset managers. EU Battery Regulation traceability mandates synchronize procurement timelines with KBA type-approval requirements. The Cologne-Düsseldorf corridor scales fast-charging infrastructure through municipal utility grid-balancing contracts.
Baden-Württemberg
Stuttgart-based OEM chassis manufacturers pilot-test solid-state configurations with silicon-anode architectures for 400-kilometer intercity applications. The Federal Emission Control Act transit exemptions coordinate fleet replacement cycles across state transport associations. The Stuttgart metropolitan corridor deploys 400 kWh extended-range specifications with enhanced thermal management systems.
Berlin-Brandenburg
Municipal transit operators compress procurement cycles as binding EU Green Deal fleet decarbonization targets eliminate diesel bus replacement options. KBA type-approval requirements reshape cell sourcing obligations for pack assemblers serving multi-state operators. The Berlin-Brandenburg metropolitan region concentrates depot charging infrastructure scaling with 150-350 kW DC fast-charging systems.
Lower Saxony
Hanover's transport authority leverages federal co-funding programs extending beyond metropolitan tier-one operators to mid-sized city networks. BImSchG compliance timelines create fragmented certification requirements across sixteen state transport associations. The Hanover-Brunswick corridor hosts wireless charging pilot-phase deployments with inductive pad systems at demonstration terminals.
Germany Electric Bus Battery Pack Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with cell producers and pack integrators occupying distinct margin pools in the value chain. The market structure concentrates around three strategic archetypes: Asian cell giants with European manufacturing footprints, domestic pack integrators with OEM chassis specialization, and Nordic proximity-based producers scaling German gigafactory operations. Dominant competitive moves include securing long-term offtake agreements with verified low-carbon power supply and separating battery pack ownership from vehicle chassis acquisition through third-party energy service agreements.
Among Asian-origin cell producers, Contemporary Amperex Technology Co. Ltd. and BYD Company Ltd. occupy positions leveraging depreciated European manufacturing capacity. Akasol AG exemplifies the domestic pack integrator archetype through specialized integration tailored to German OEM chassis specifications. Northvolt AB represents the Nordic proximity-based producer competing on supply chain advantages from planned German operations. These three anchors illustrate how geography, manufacturing scale, and regulatory compliance capabilities segment competitive positioning.
| Leading Market Players |
|---|
| Contemporary Amperex Technology Co. Ltd. (CATL) |
| BYD Company Ltd. |
| LG Energy Solution Ltd. |
| Samsung SDI Co. Ltd. |
| Northvolt AB |
| Akasol AG |
| BMZ Group |
| VARTA AG |
| LEAPENERGY |
| Others |
Pricing and Supply Chain Analysis
Municipal transit authorities in Bavaria and North Rhine-Westphalia concentrate procurement volumes through state transport association aggregation, anchoring contract-based long-term offtake pricing with volume-scale discounts and KBA type-approval certification premiums. This buyer concentration feeds back into supply chain configuration, as pack assemblers prioritize domestic cell sourcing to meet EU Battery Regulation carbon footprint thresholds and secure municipal utility grid-balancing revenue shares.
Pricing Analysis
Short lead-time premiums apply to lithium-ion pack configurations sourced from CATL's Erfurt manufacturing base, while spot inventory discounts emerge for nickel-metal hydride retrofit applications with depreciated supply chains. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and thermal management system complexity. Cost compression in mid-tier 300 kWh configurations is intensifying because nickel-content cathode material volatility and domestic cell manufacturing scale-up delays squeeze assembler margins. Smaller municipal operators without Verkehrsverbund aggregation show highest price sensitivity; Berlin-Brandenburg metropolitan authorities with federal co-funding access exhibit lowest.
Supply Chain Analysis
Workforce availability constraints in German cell manufacturing and Nordic hydroelectric-powered production sites are compressing capacity expansion timelines for domestic sourcing mandates. Cell supply concentrates in China, South Korea, and emerging German operations from Northvolt AB's planned gigafactory. Raw material dependencies rest on Chilean lithium, Indonesian nickel, and DRC cobalt through established offtake agreements. Single-source vulnerability from Asian cathode active material suppliers exposes pack assemblers to carbon border adjustment disclosure risks. Distribution runs through OEM chassis manufacturer integration partnerships and third-party energy service agreement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where EU Battery Regulation traceability mandates and KBA type-approval requirements erect barrier-to-entry moats favoring pack assemblers with verified low-carbon supply chains and domestic manufacturing proximity.
For Market Incumbents: Anticipate solid-state chemistry transition delays by securing long-term lithium-ion cell offtake from Nordic hydroelectric-powered producers before carbon footprint declarations tighten. Defend position against emerging Nordic proximity-based entrants by deepening backward integration into recycling infrastructure through Germany's dual collection system. Prioritize certification investment in EU Battery Regulation compliance systems to maintain municipal procurement eligibility as traceability mandates harden. For New Entrants and Emerging Players: EU Green Deal fleet decarbonization targets in Germany open a window for opportunity charging pantograph specialists serving mid-sized Ruhr region cities excluded from overnight depot electrification. Target underpenetrated Verkehrsverbund associations in North Rhine-Westphalia aggregating demand across municipal operators lacking procurement sophistication. Pursue go-to-market angle through third-party battery asset management separating pack ownership from chassis acquisition. For Investors and Strategic Acquirers: The window for entry favors domestic pack integrators with OEM chassis specialization and established KBA type-approval pathways over pure cell manufacturing plays facing capital intensity barriers. Acquisition focus should center on mid-tier integrators with circular economy infrastructure ownership and second-life stationary storage convergence capabilities. Monitor domestic cell manufacturing scale-up against import dependency ratios as inflection indicator for supply chain reconfiguration timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cell Manufacturing | Domestic gigafactory operations secure BMWK funding eligibility and carbon footprint compliance for municipal contracts. |
| Circular Economy Infrastructure Investment | Second-life stationary storage convergence with Germany's dual collection system creates recurring revenue from retired bus packs. |
| Opportunity Charging Pantograph Deployment | Route-terminal electrification opens procurement to mid-capacity operators previously excluded by depot constraints. |
| Long-term Supply Agreement with Nordic Producers | Verified low-carbon hydroelectric power supply meets EU Battery Regulation mandatory carbon footprint declarations. |
| Third-party Battery Asset Management Launch | Energy service agreements separate pack ownership from chassis acquisition, concentrating margin pools in North Rhine-Westphalia. |
Research Methodology
Document review covered KBA type-approval filings, EU Battery Regulation implementation guidance, BMWK funding program disclosures, and municipal transit authority procurement records, complemented by interviews with pack integration engineers, OEM chassis procurement leads, state transport association planning officers, and municipal utility grid integration specialists. Secondary validation drew from Federal Network Agency grid connection data, VDV industry association fleet statistics, and customs trade records for cell and cathode material imports. Bottom-up triangulation across operator-level procurement pipelines and top-down reconciliation against federal funding allocation databases anchored volume estimates.
Installed base and revenue outputs across the projection horizon reflect analytical framework segmentation by chemistry type, capacity tier, charging infrastructure configuration, and end-user ownership structure. CAGRs were derived from logistic adoption curve modeling calibrated to fleet replacement cycle timing and federal co-funding program trajectories. Industry-specific forecast inputs incorporated depot charging infrastructure scaling rates and solid-state manufacturing yield improvement assumptions.
The model assumes a particular technology adoption path; alternative pathways for solid-state commercialization would alter the outlook if interface stability challenges resolve faster than baseline projections. Forecasts reflect assumptions regarding BMWK funding continuity, EU Battery Regulation enforcement timelines, and nickel price volatility. Material deviation in domestic cell manufacturing scale-up, carbon border adjustment implementation severity, or solid-state pilot program success warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Pedelec Market
Electric Vehicles
E-Bike Market
Electric Vehicles
Electric Shuttle Market
Electric Vehicles
Electromagnetic and Radio Frequency Interference Coating for Electric Vehicles Market
Electric Vehicles
US Automotive High Performance Electric Vehicle Market
Electric Vehicles
Electric Vehicle Electronic Expansion Valve (EXV) Market
Electric Vehicles
Asia-Pacific Lithium-Ion Battery for Electric Vehicle Market
Electric Vehicles
Electric Vehicle Lithium-Ion Battery Market
Electric Vehicles
Asia Pacific Electric Scooter Market
Electric Vehicles
Electric Motorcycles and Scooters Market
Electric Vehicles
Electric Vehicle NVH Material Market
Electric Vehicles
48V Mild Hybrid Electric Vehicle (MHEV) Market
Electric Vehicles
Global Automotive Inductive Wireless Charging Systems Market
Electric Vehicles
Neighbourhood Electric Vehicle Market
Electric Vehicles
India Solar E-Bike Market
Electric Vehicles
France Solar E-Bike Market