
 Automotive Wiper System Market | 2026-2036
Automotive Wiper System Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Wiper System Market Analysis
The gap between economy-grade and premium-spec wiper systems is collapsing as OEMs mandate aerodynamic beam designs across mid-range trims. Robert Bosch GmbH leverages its sensor integration expertise to bundle rain detection with wiper control modules. Valeo SA anchors European supply through its dominance in factory-installed beam wiper assemblies for French and German OEMs. DENSO Corporation specializes in compact motor architectures that sustain Japanese automakers' packaging constraints for right-hand-drive platforms.
An automotive wiper system comprises a DC motor, linkage mechanism, wiper arm, and blade assembly engineered to clear precipitation across specified sweep angles typically between 70 and 110 degrees, with activation triggered manually or via capacitive rain sensors measuring droplet density on the windshield. Beam wipers lead value generation due to their spring-steel spine construction eliminating traditional bracket joints, while rain sensor technology captures the fastest growth trajectory as OEMs integrate automatic activation with ADAS visibility protocols. The aftermarket installation channel remains structurally fragmented with margin pools concentrating in winter wiper variants featuring synthetic rubber compounds rated below minus forty degrees Celsius.
The EPA enforces motor efficiency standards affecting wiper motor electromagnetic compatibility, while NHTSA Federal Motor Vehicle Safety Standard 103 mandates minimum cleared vision percentages that directly shape blade sweep geometry and motor torque specifications. China's GB 15085 standard governs wiper durability cycles under dust and salt spray conditions, creating divergent testing protocols for suppliers serving multiple regulatory zones. Stakeholders must monitor how ECE R43 amendments on optical distortion interact with emerging camera-housing integration requirements for autonomous driving sensor suites.
Market Dynamics
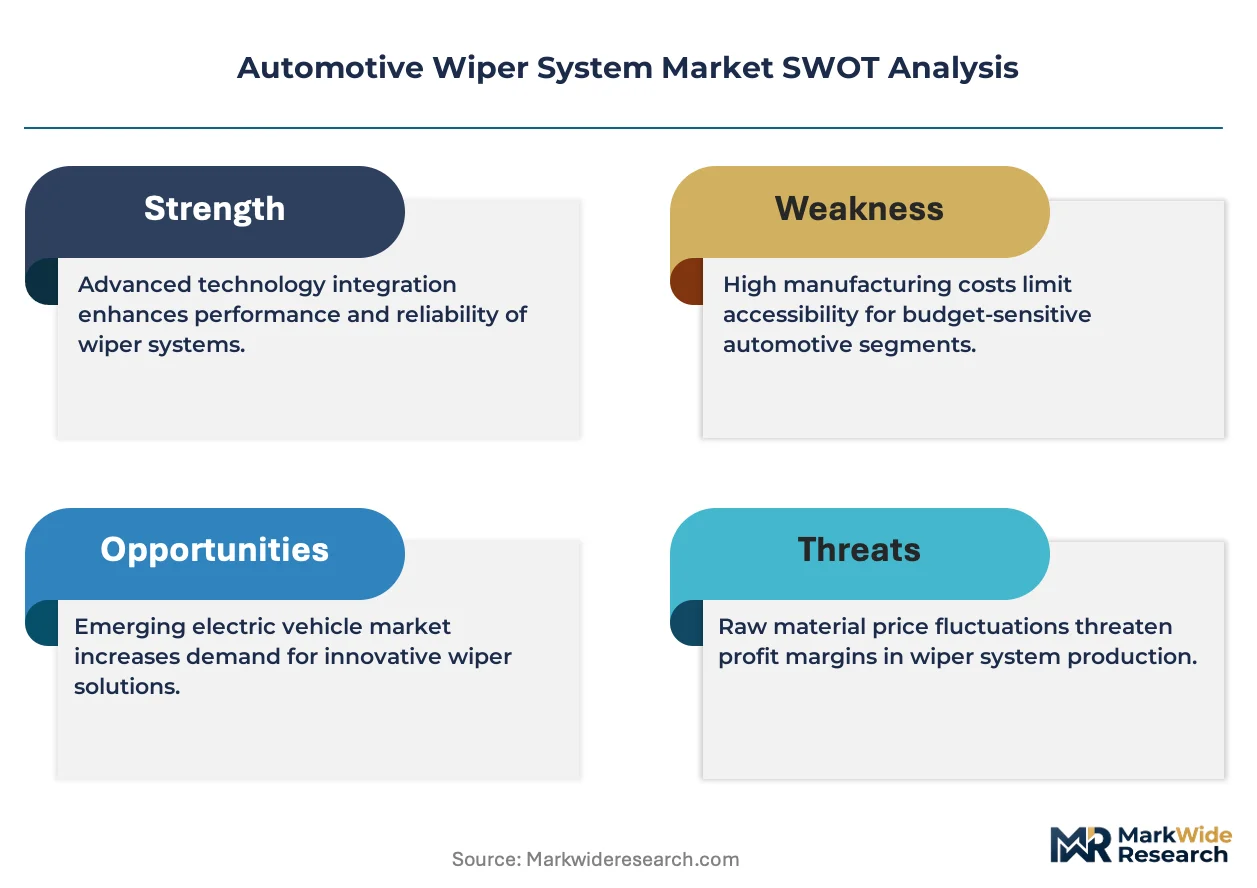
OEM consolidation around aerodynamic beam architectures is compressing the traditional three-tier wiper supply structure into a premium-standard binary, forcing suppliers to absorb bracket-elimination tooling costs while meeting divergent regional durability certifications.
Growth Catalysts
- Rain-sensing ADAS integration:Capacitive droplet detection modules are becoming mandatory visibility-enabling components for Level 2+ autonomous driving protocols, pulling sensor-wiper bundled procurement across German and Japanese OEM platforms.
- China MIIT safety standards:Tightened windshield clearing performance requirements under GB 15085 are accelerating factory-fit automatic wiper penetration in domestic passenger vehicle production.
- Synthetic rubber formulation advances:Fluoropolymer blade compounds rated to minus forty degrees Celsius are extending replacement intervals and capturing winter aftermarket premiumization in Nordic and North American markets.
Market Restraints
- Neodymium magnet cost volatility:Rare-earth price swings in Chinese export markets directly compress DC wiper motor margin structures, particularly for suppliers without long-term offtake agreements.
- Single-source beam steel dependency:Spring-steel spine production concentrates in a narrow band of German and Japanese specialty mills, creating geographic concentration risk for tier-one wiper assembly suppliers.
- ECE R43 optical distortion limits:Windshield glazing curvature specifications constrain maximum wiper sweep angles in European premium vehicle platforms, limiting blade length standardization economies.
Strategic Opportunities
- Camera-housing integration whitespace:Autonomous driving sensor suite placement on windshields is creating demand for precision-milled wiper park positions that avoid optical interference, opening specialized blade assembly contracts.
- India BIS durability certification:Pending mandatory dust-cycle testing under revised automotive component standards will favor suppliers with existing salt-spray validation infrastructure, creating first-mover positioning.
- Direct-to-fleet digital channels:Commercial vehicle operators are bypassing traditional aftermarket distributors through telematics-linked predictive blade replacement platforms, compressing channel margin extraction.
Industry Challenges
- Electromagnetic compatibility engineering:EPA motor efficiency standards require specialized shielding expertise that sits with a thin cohort of automotive electrical system specialists, creating talent acquisition bottlenecks.
- Dual-carbon validation timelines:OEM sustainability scorecards now demand lifecycle carbon documentation for wiper assemblies, forcing suppliers to reconfigure sub-tier material traceability systems within compressed product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Wiper System Market |
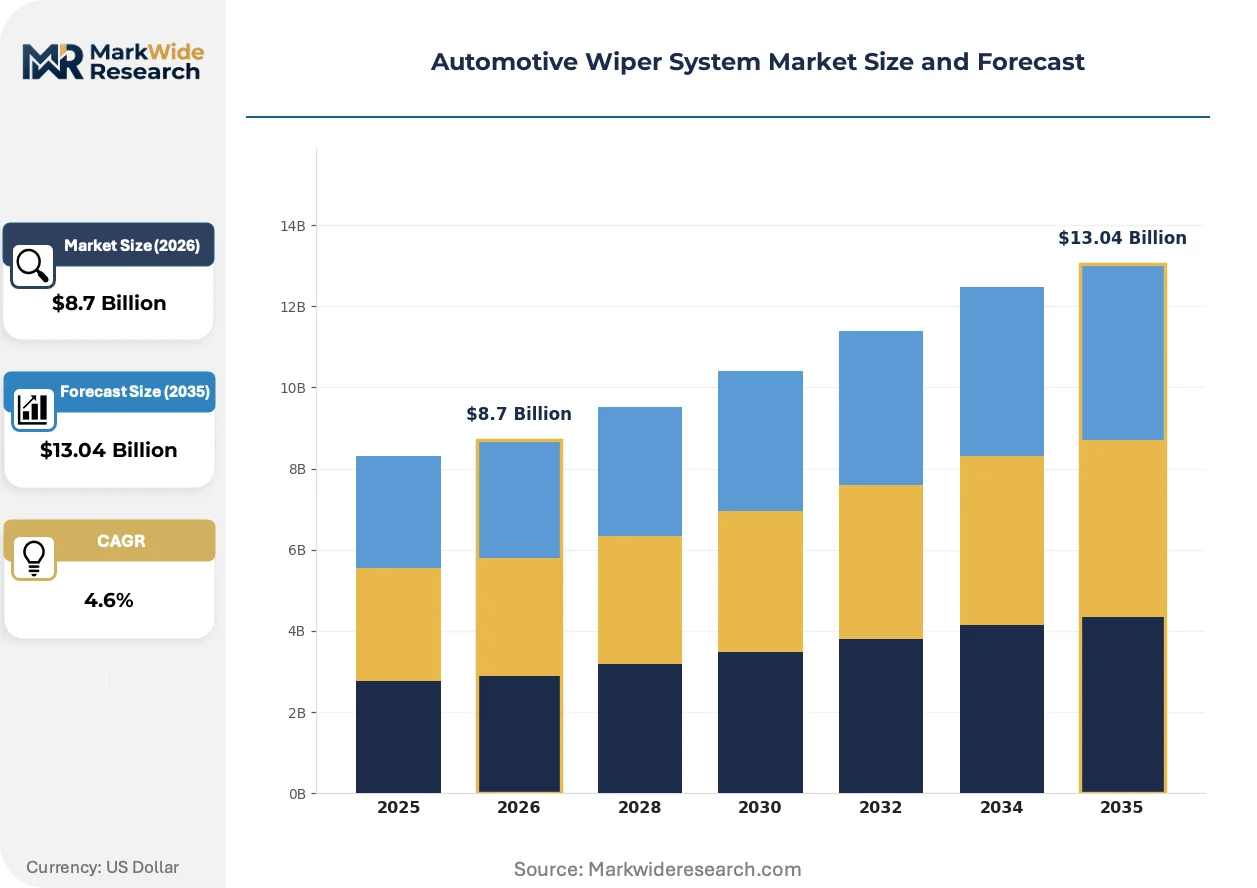
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional Wipers, Beam Wipers, Winter Wipers, Hybrid Wipers End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Automotive Dealerships Technology: Automatic Wipers, Manual Wipers, Infrared Sensors, Rain Sensors Installation: Factory Installed, Aftermarket Installation, DIY Kits, Professional Services |
| Companies Covered | Mitsuba Corporation, HELLA GmbH & Co. KGaA, Robert Bosch GmbH, WAI Global, DOGA, Valeo SA, Trico Products Corporation, Magneti Marelli, DENSO Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Wiper System Market Emerging Trajectories
Active aerodynamics and sensor fusion are rewriting wiper system specifications, collapsing the boundary between visibility hardware and autonomous driving perception infrastructure while fragmenting procurement authority across traditional engineering silos.
Beam wiper architectures with integrated spring-steel spines are displacing conventional bracketed designs across mid-range vehicle trims. Korean and Chinese OEMs have compressed adoption timelines from premium-tier exclusivity to standard-fit deployment within single product cycles. This displacement is eliminating bracket-component supplier tiers and consolidating value capture among integrated beam assembly specialists with in-house steel forming capabilities.
Europe's ECE R43 windshield glazing regulations are tightening optical distortion thresholds for camera-mounting zones, forcing wiper sweep pattern redesigns that avoid sensor sightline interference. The industrial consequence is a new specification layer linking blade trajectory geometry directly to autonomous driving system validation. Premium German OEMs are responding by mandating co-development contracts that bind wiper suppliers into ADAS release-to-production timelines.
Commercial fleet operators are unbundling blade replacement from scheduled maintenance contracts and shifting toward usage-based procurement triggered by telematics-reported sweep degradation. This behavioral pivot disrupts traditional aftermarket distributor relationships and concentrates volume with suppliers capable of API-integrated inventory replenishment. The shift is most visible in North American long-haul trucking and European logistics fleets where downtime cost sensitivity exceeds parts procurement friction.
Automotive Wiper System Market Segmentation
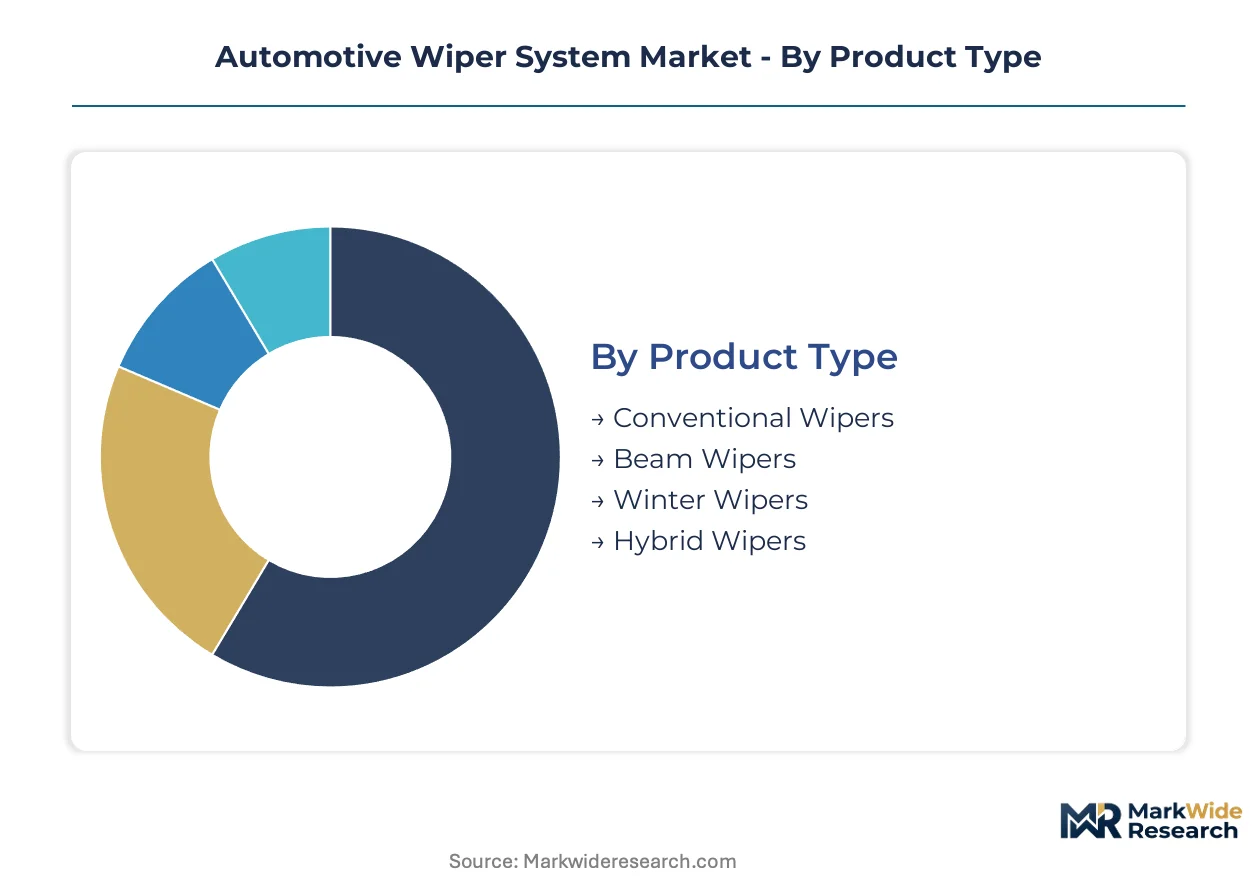
Segmentation in automotive wiper systems reveals how regulatory pressure and autonomous driving integration are reshaping procurement patterns across product tiers and installation channels. Understanding these divides exposes where margin pools are concentrating and which technology transitions suppliers must navigate.
Product Type:
Regulatory differentiation across NHTSA, ECE R43, and China's GB 15085 standards directly shapes which wiper architectures qualify for factory installation versus aftermarket replacement.
- Conventional Wipers:Bracket-supported metal frames with multiple pressure points dominate economy vehicle trims and legacy fleet replacement cycles. Demand concentrates in India's commercial vehicle sector and Southeast Asian markets where cost minimization overrides aerodynamic performance requirements.
- Beam Wipers:Spring-steel spine construction eliminates bracket joints and delivers uniform pressure distribution across curved windshields. German and Japanese OEMs mandate beam architectures across mid-range and premium passenger vehicles to meet ECE R43 optical distortion thresholds.
- Winter Wipers:Synthetic rubber compounds rated below minus forty degrees Celsius with protective boot designs block ice accumulation.
- Hybrid Wipers:Bracketed frames with aerodynamic spoilers bridge cost and performance for regional OEMs in Brazil and Mexico.
Established volume favors Conventional Wipers; emerging adoption favors Beam Wipers.
End User:
Customer type determines specification authority and contract structure, with OEMs wielding design control while aftermarket channels compete on availability and price.
- OEMs:Vehicle manufacturers specify wiper systems during platform development, locking suppliers into multi-year supply agreements with embedded sensor integration requirements. German and Japanese OEMs bundle rain-sensing modules with wiper control electronics.
- Aftermarket Providers:Independent distributors and private-label brands serve replacement demand through retail and e-commerce channels.
- Vehicle Assemblers:Contract manufacturers in China and Mexico install wiper systems under OEM direction with limited specification autonomy.
- Automotive Dealerships:Authorized service networks handle warranty replacements and upsell premium blade upgrades.
Procurement authority concentrates with OEMs; margin extraction favors Aftermarket Providers.
Technology:
Sensor sophistication separates factory-installed systems from replacement hardware, with capacitive detection becoming mandatory for ADAS-equipped vehicles.
- Automatic Wipers:Sensor-activated systems integrate with vehicle CAN bus architectures to trigger wipe cycles without driver intervention. NHTSA visibility standards and Level 2+ autonomous driving protocols accelerate factory penetration in US and German passenger vehicles.
- Rain Sensors:Capacitive droplet detection modules mounted on windshields measure precipitation density and adjust wipe frequency. Japanese OEMs source these from integrated sensor-wiper suppliers to meet METI safety guidelines.
- Manual Wipers:Driver-activated stalk controls persist in commercial vehicles and economy segments.
- Infrared Sensors:Optical precipitation detection offers alternative sensing physics for specialized applications.
Technology deployment splits between Automatic Wipers for new vehicles and Manual Wipers for replacement cycles.
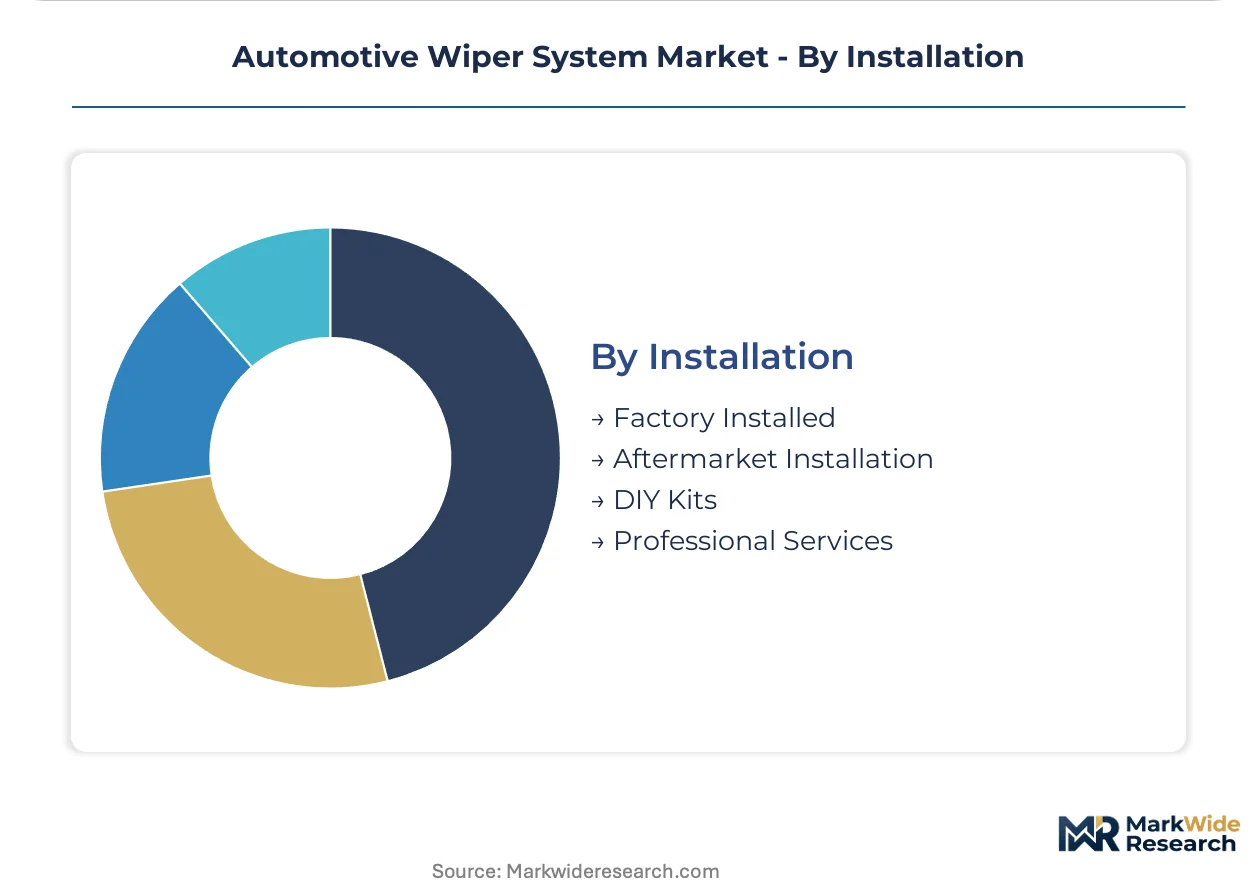
Installation:
Channel structure determines margin capture, with factory installation capturing value through specification lock-in while aftermarket battles for share through convenience and speed.
- Factory Installed:OEM-directed assembly at vehicle production lines integrates wiper systems with windshield glazing and sensor calibration. China's MIIT certification requirements and ECE R43 validation protocols create regulatory barriers for aftermarket alternatives.
- Aftermarket Installation:Professional service bays handle blade replacement and system upgrades with diagnostic equipment.
- DIY Kits:Consumer-packaged blade assemblies with adapter systems target price-sensitive replacement demand.
- Professional Services:Specialized installers address complex integrations including rain sensor recalibration.
Factory Installed commands specification premium; Aftermarket Installation captures volume flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wiper system manufacturing concentrates in automotive production clusters where OEM proximity reduces logistics costs and accelerates design iteration cycles. Germany, Japan, China, and the United States host the dominant supplier ecosystems, each shaped by distinct regulatory frameworks and vehicle specification traditions.
Germany
Premium OEM demand for beam wiper architectures and rain-sensing integration drives specification authority from Stuttgart and Munich headquarters. ECE R43 windshield glazing regulations enforce optical distortion thresholds that constrain wiper sweep geometries and validate supplier engineering capabilities. Baden-Württemberg's supplier corridor around Stuttgart anchors European wiper system development for Mercedes-Benz and Porsche platforms.
Japan
Right-hand-drive packaging constraints and compact motor requirements from Toyota, Honda, and Nissan shape supplier technical priorities. METI safety guidelines mandate automatic wiper penetration for ADAS-equipped vehicles, accelerating sensor-wiper bundled procurement. Toyota City's supplier ring concentrates DENSO Corporation and affiliated tier-one assembly operations serving domestic OEM platforms.
China
Domestic passenger vehicle production expansion under MIIT certification requirements is pulling factory-fit automatic wiper penetration toward international parity levels. GB 15085 durability standards govern dust-cycle and salt-spray validation protocols that diverge from European and North American test regimes. Shanghai and Guangzhou automotive clusters concentrate wiper assembly capacity serving BYD, Geely, and SAIC production lines.
United States
NHTSA Federal Motor Vehicle Safety Standard 103 mandates minimum cleared vision percentages that directly shape blade sweep angles and motor torque specifications for Detroit Three platforms. EPA motor efficiency standards affect wiper motor electromagnetic compatibility engineering requirements. Michigan's automotive corridor retains specification influence despite production diversification toward Southern states.
India
Commercial vehicle cost sensitivity sustains conventional bracketed wiper demand in the aftermarket, though passenger vehicle OEMs are adopting beam architectures for export-compliant platforms. Pending BIS durability certification revisions will mandate dust-cycle testing that favors suppliers with existing salt-spray validation infrastructure. Tamil Nadu's Sriperumbudur automotive belt concentrates assembly operations for Hyundai, Kia, and Renault-Nissan sourcing.
Automotive Wiper System Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated sensor-wiper suppliers commanding specification influence while scale manufacturers compete on bracket elimination and steel forming efficiency. The market structure tiers into three supplier categories: multinational integrated system architects with ADAS co-development contracts, regional beam assembly specialists with captive steel forming, and aftermarket-focused blade manufacturers competing on compound formulation and adapter universality. Dominant competitive moves include backward integration into spring-steel spine production and strategic partnerships with rain sensor module suppliers.
Among Japanese integrated suppliers, Mitsuba Corporation and DENSO Corporation exemplify the sensor-wiper bundled procurement archetype that METI guidelines accelerate. European system architects are represented by Valeo SA, which anchors factory-installed beam wiper penetration for French and German OEM platforms. Robert Bosch GmbH occupies a position spanning both sensor integration and motor control module supply, reflecting German engineering depth in automotive electrical systems.
| Leading Market Players |
|---|
| Mitsuba Corporation |
| HELLA GmbH & Co. KGaA |
| Robert Bosch GmbH |
| WAI Global |
| DOGA |
| Valeo SA |
| Trico Products Corporation |
| Magneti Marelli |
| DENSO Corporation |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements for neodymium magnets lock in both DC motor supply access and price visibility for tier-one wiper assembly suppliers serving German and Japanese OEM platforms. These contracts insulate margin structures from Chinese rare-earth export volatility while committing buyers to minimum volume thresholds that constrain sourcing flexibility.
Pricing Analysis
ECE R43 dictates the pricing tier structure across European factory-installed wiper systems, with optical distortion certification grades separating premium beam assemblies from standard bracketed alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects GB 15085 durability validation tiers in China and NHTSA FMVSS 103 compliance grades in the United States. Cost compression in economy-tier conventional wipers is intensifying because Korean and Chinese OEMs have compressed beam adoption timelines to single product cycles. Commercial fleet operators exhibit highest price sensitivity through telematics-linked usage-based procurement, while premium German OEMs demonstrate lowest sensitivity due to ADAS co-development contract bundling.
Supply Chain Analysis
Inventory buffers for spring-steel spines extend lead times beyond twelve weeks as German and Japanese specialty mills operate at capacity constraints. Geographic supply concentration centers on China for rare-earth magnet processing, Germany for precision steel forming, and Japan for compact motor architectures. Raw material dependencies draw from neodymium-iron-boron magnet alloys, fluoropolymer rubber compounds, and high-tensile spring steel. Single-source vulnerability sits with the narrow band of specialty mills producing beam-grade steel, creating geographic concentration risk for tier-one assembly suppliers. Distribution runs through OEM-directed tier-one supply agreements for factory installation, with aftermarket channels fragmenting across independent distributors and telematics-integrated fleet platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive wiper system demand follows vehicle production cycles, with OEM platform refreshes and ADAS penetration rates serving as the primary cyclical recovery driver. Suppliers must align capacity planning with these platform timelines to capture specification windows.
For Market Incumbents: Secure captive supply agreements for spring-steel spine production to defend against single-source mill dependency. Invest in electromagnetic compatibility engineering talent acquisition to meet EPA motor efficiency standards before compliance deadlines tighten. Backward integration into neodymium magnet sourcing mitigates rare-earth price volatility threatening DC motor margin structures.
For New Entrants and Emerging Players: Predictive blade replacement platforms for commercial fleets represent a service-layer gap where incumbents under-serve with traditional distributor relationships. Target North American long-haul trucking and European logistics operators through API-integrated inventory replenishment systems. Camera-housing integration contracts for autonomous driving sensor suites offer the most penetrable entry point given co-development timeline fragmentation among established suppliers.
For Investors and Strategic Acquirers: Regional beam assembly specialists with in-house steel forming capabilities present acquisition targets with durable competitive positioning. Long-term viability over the next decade rests on ADAS integration depth rather than replacement cycle volume. Monitor ECE R43 amendment timelines on optical distortion thresholds as the signal to watch for inflection in specification authority toward sensor-wiper bundled suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Spring-Steel Production | Captive spine manufacturing eliminates bracket-elimination tooling cost absorption and secures ECE R43 validation capacity. |
| Rain Sensor-Wiper Control Module Bundling | Integrated procurement packages capture METI guideline acceleration and Level 2+ ADAS specification authority. |
| Telematics-Linked Fleet Replacement Platforms | API-integrated inventory systems compress aftermarket distributor margins and concentrate volume with direct suppliers. |
| GB 15085 Salt-Spray Validation Infrastructure | First-mover positioning under pending India BIS durability certification favors existing dust-cycle testing capability. |
| Dual-Carbon Lifecycle Documentation Systems | OEM sustainability scorecards now mandate material traceability reconfiguration within compressed product development cycles. |
Methodological Framework
Desk research of vehicle production databases, IHS Markit registration data, and regulatory filing repositories preceded structured interviews with OEM platform engineers, tier-one supplier procurement leads, aftermarket distributors, and dealership operations managers. Primary fieldwork captured specification authority shifts and procurement pattern evolution across German, Japanese, and Chinese automotive clusters. Secondary validation drew from NHTSA FMVSS submissions, ECE R43 technical documentation, and MIIT certification records. Bottom-up volume modeling triangulated against top-down OEM production forecasts to align segmentation outputs.
Variance decomposition across product type, technology tier, installation channel, and regional production cluster shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional regulatory cluster. CAGRs derived from regression analysis of historical penetration rates against ADAS deployment curves and platform refresh cycles. Industry-specific forecast inputs incorporated beam wiper adoption velocity and rain sensor bundling ratios by OEM headquarters location.
Underlying assumptions cover sustained ADAS penetration, stable rare-earth export regimes, and OEM platform timeline execution, with deviation risk concentrated in ECE R43 amendment timing and China MIIT enforcement intensity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Trailing Arm Bushing Market
Automotive Parts
Automotive Electric Parking Brakes Market
Automotive Parts
Industrial Roller Chain Drives Market
Automotive Parts
Engine Oil Market
Automotive Parts
Full Synthetic Motor Oil Market
Automotive Parts
Die Cast Parts for Electric Vehicle Market
Automotive Parts
Global Automotive Ignition Market
Automotive Parts
Electro Hydraulic Power Steering Market
Automotive Parts
Global Automotive Damper Market
Automotive Parts
Russia Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Vents Market
Automotive Parts
Splined Sleeves Market
Automotive Parts
Automotive Canister Market
Automotive Parts
China Automotive Lubricants Market
Automotive Parts
Automotive Canister Purge Valve Market
Automotive Parts
Automotive Steel Market