
 Full Synthetic Motor Oil Market | 2026-2036
Full Synthetic Motor Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Full Synthetic Motor Oil Market Insights
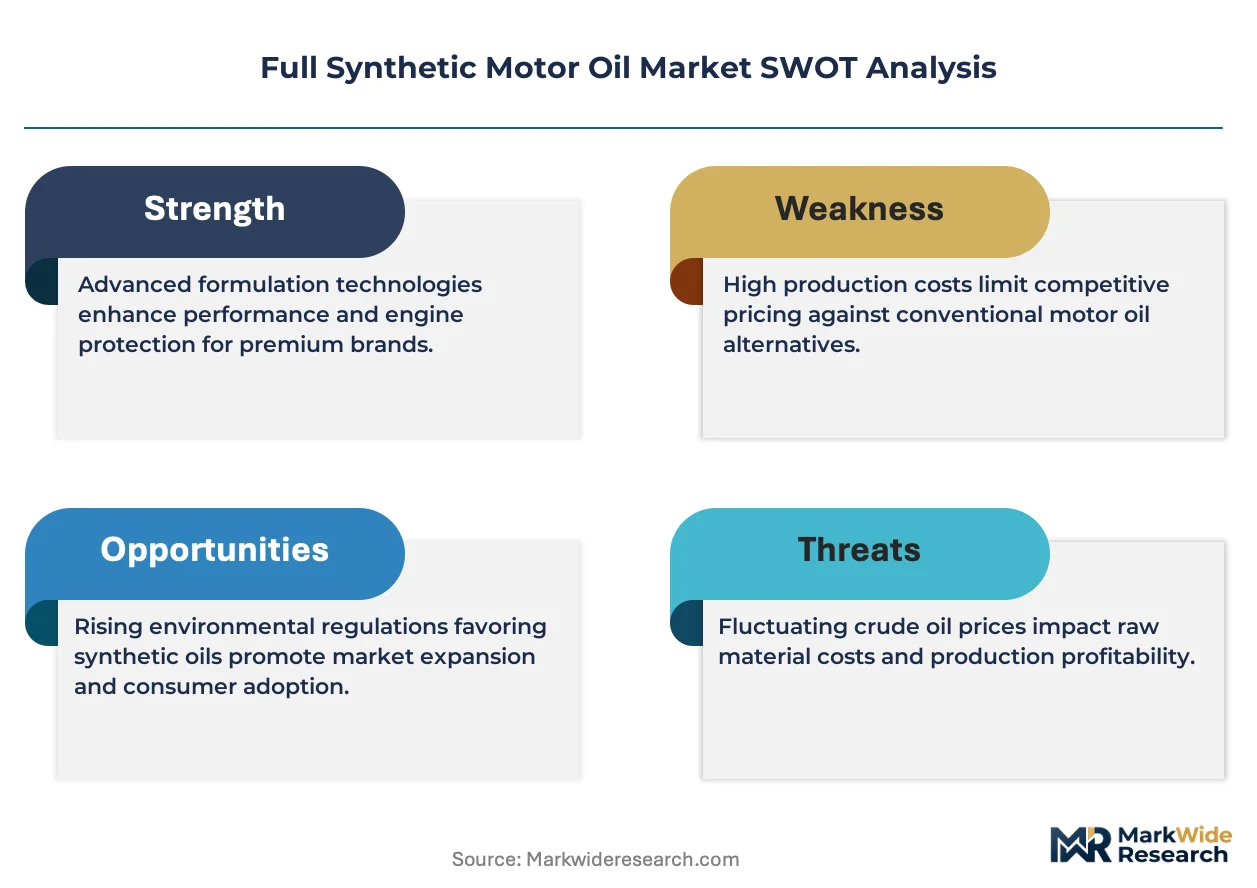
The capital-intensity divergence between integrated refiners and independent blenders is unwinding competitive stability in the full synthetic motor oil sector. ExxonMobil Corporation leverages captive base-oil production to control input costs across premium grades. Valvoline Inc. competes through specialized quick-lube channel dominance in North American aftermarket service. AMSOIL Inc. differentiates via direct-to-consumer subscription models targeting enthusiast segments with extended-drain formulations.
Full synthetic motor oil consists of chemically engineered base stocks, typically poly-alpha-olefins (PAO) or Group III hydrocracked oils, blended with detergent, dispersant, and anti-wear additive packages to achieve thermal stability beyond mineral alternatives. Its primary purpose is lubrication of internal combustion engines under extreme temperature cycling and extended service intervals. High-performance formulations command premium positioning as OEMs specify lower viscosity grades for fuel economy compliance. The 0W-20 and 5W-30 viscosity grades capture expanding share as turbocharged direct-injection engines proliferate. Passenger vehicles remain the anchor end-user segment, though heavy-duty trucks are transitioning toward synthetic blends under fleet total-cost-of-ownership pressure.
API certification requirements in the US, REACH chemical registration in Europe, and China's GB standards collectively dictate additive chemistry choices and product registration timelines for market access. The US EPA coordinates with OEMs through ILSAC to align oil specifications with corporate average fuel economy mandates. Stakeholders must monitor divergence between OEM-specific approvals and industry blanket certifications as electrification reshapes lubricant demand profiles.
Market Dynamics
OEM drain interval extension programs and turbocharged direct-injection engine proliferation are compressing demand for conventional lubricants while elevating premium synthetic specifications. Fleet operators now specify 15,000-mile service intervals as baseline, forcing reformulation investments across the supply base.
Growth Catalysts
- API SP and ILSAC GF-6 compliance mandates:US EPA coordination with OEMs on corporate average fuel economy standards requires lower viscosity grades. Formulators must certify 0W-16 and 0W-20 products to access US passenger vehicle channels.
- China's domestic OEM specification divergence:GB standards and proprietary approvals from SAIC, Geely, and BYD are creating dedicated demand for synthetic formulations tuned to local engine architectures and fuel quality profiles.
- Poly-alpha-olefin thermal stability thresholds:PAO base stocks withstand turbocharger outlet temperatures exceeding 150°C. This material performance enables 10,000-mile-plus drain intervals in European and North American passenger fleets.
Market Restraints
- Group III+ base oil supply concentration:Hydrocracked feedstock availability clusters in South Korea, Qatar, and US Gulf Coast refineries. Blend dependent on these inputs face freight cost volatility and geopolitical sourcing risk.
- Additive package cost structure:Molybdenum dithiocarbamate and boron ester chemistries constitute 35-45% of finished lubricant raw material costs. Mining output fluctuations in Chile and Turkey transmit directly to blender margins.
- Electric powertrain substitution trajectory:Battery electric vehicles eliminate crankcase lubrication entirely. OEM electrification roadmaps from Volkswagen, Stellantis, and General Motors threaten addressable volume in passenger segments by 2035.
Strategic Opportunities
- India's BIS lubricant standard upgrades:The Bureau of Indian Standards is phasing IS 13656:2002 specifications toward synthetic-equivalent performance tiers. Early certification investments unlock access to Maruti Suzuki and Tata Motors factory fill contracts.
- Heavy-duty fleet synthetic blend conversion:Class 8 truck operators in the US and Germany are transitioning from mineral 15W-40 to synthetic 5W-30 under total-cost-of-ownership pressure from fuel economy regulations and extended drain economics.
- Direct-to-consumer subscription channels:Enthusiast vehicle owners and track-day participants seek extended-drain formulations delivered on predictive replacement schedules. This bypasses traditional quick-lube and retail auto parts intermediaries.
Industry Challenges
- OEM-specific approval timeline compression:Volkswagen 508.00/509.00, BMW LL-17 FE+, and Mercedes-Benz 229.71 certifications require 18-24 month test cycles. Formulators must parallel-process multiple OEM protocols to secure factory fill positions.
- Additive chemistry skill scarcity:Formulation chemists with expertise in friction modifier synergy and dispersant polymer architecture command premium compensation. Independent blenders struggle to recruit against integrated refiner compensation structures.
- REACH registration synchronization:ECHA chemical substance database updates require reformulation when additive components face SVHC candidate listing. European market access demands continuous regulatory monitoring and reformulation agility.
Report Scope
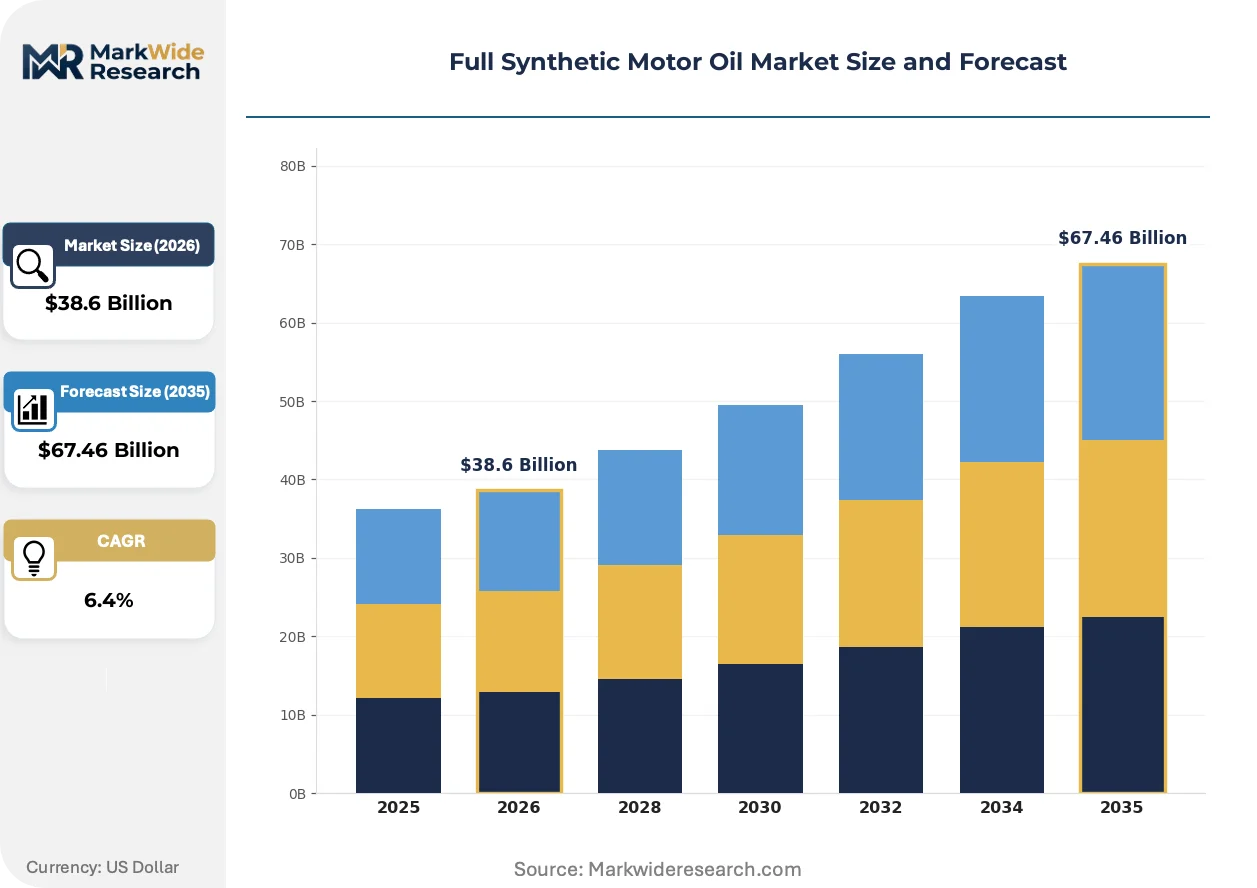
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Full Synthetic Motor Oil Market |
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $67.46 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Performance, Fuel Economy, Standard, Racing Viscosity Grade: 0W-20, 5W-30, 10W-40, 5W-20 End User: Passenger Vehicles, Commercial Vehicles, Heavy-Duty Trucks, Motorcycles Distribution Channel: Online Retail, Auto Parts Stores, Service Stations, Distributors |
| Companies Covered | ExxonMobil Corporation, Shell plc, Chevron Corporation, TotalEnergies SE, Valvoline Inc., Phillips 66 Company, AMSOIL Inc., Castrol, Pennzoil, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Full Synthetic Motor Oil Market Trends and Innovations
Formulation chemistry is pivoting toward lower viscosity grades and electrification-compatible thermal management fluids. These shifts compress traditional mineral oil demand while opening adjacent lubricant categories for synthetic base stock redeployment.
Gas-to-liquids base stock technology is decomposing the historical PAO-Group III quality hierarchy. Shell's Pearl and Oryx facilities in Qatar and Nigeria produce ultra-clean paraffinic feedstocks indistinguishable from synthetic performance. European and Asian blenders are adopting GTL stocks for mid-tier synthetic positioning. This feedstock flexibility is decomposing premium pricing power for traditional PAO suppliers.
EU F-Gas Regulation phase-down schedules are constraining fluorinated polymer use in lubricant additive packages. ECHA restrictions on per- and polyfluoroalkyl substances force reformulation of friction modifiers and anti-wear compounds. Passenger vehicle OEMs in Germany and France are accelerating approval timelines for PFAS-free factory fill specifications.
Fleet procurement departments are consolidating lubricant supplier rosters under outcome-based performance contracts. US Class 8 truck operators now specify guaranteed fuel economy improvement and extended drain interval validation rather than product brand. This specification shift concentrates volume with formulators capable of field trial documentation and telematics integration.
Full Synthetic Motor Oil Market Segmentation
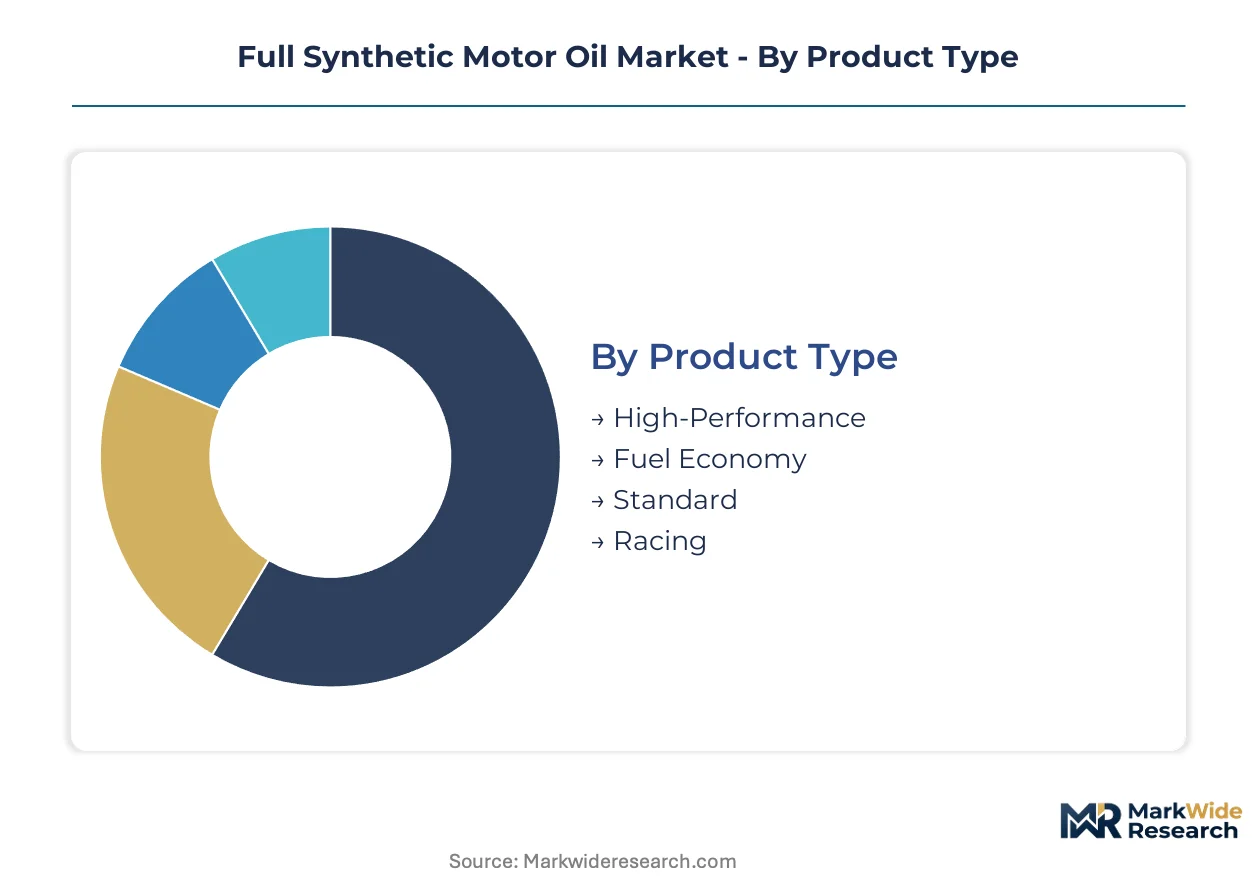
Full synthetic motor oil demand fragments across performance tiers, viscosity specifications, and channel economics that reward distinct formulation investments. Each segmentation axis carries divergent margin profiles and certification barriers that shape competitive positioning.
Product Type:
Premium positioning and OEM factory fill approvals concentrate margin pools in performance-differentiated tiers rather than commodity segments.
- High-Performance:Formulations carry BMW LL-17 FE+, Mercedes-Benz 229.71, or Volkswagen 508.00/509.00 approvals. Turbocharged direct-injection engines in German and US passenger vehicles specify these grades for thermal stability beyond standard synthetics.
- Fuel Economy:Ultra-low viscosity 0W-16 and 0W-20 grades serve EPA-coordinated CAFE compliance mandates. Japanese and US OEMs specify these formulations to meet corporate average fuel economy thresholds without engine redesign.
- Standard:API SP and ILSAC GF-6 certified products for mainstream drain interval extension.
- Racing:Track-day and competition formulations with elevated ZDDP content for extreme load protection.
The dominant share belongs to Fuel Economy, while High-Performance is closing the gap fastest.
Viscosity Grade:
Volume concentration tracks OEM engine architecture shifts toward lower viscosity for thermal efficiency gains.
- 0W-20:Cold-crank viscosity enables turbocharger bearing protection at sub-zero startup. US and Japanese passenger vehicle OEMs specify this grade across light truck and crossover platforms to satisfy CAFE mandates without hybridization.
- 5W-30:The workhorse specification spans European and North American fleets with balanced high-temperature shear stability and fuel economy. German OEMs retain this grade for performance variants where 0W-20 thermal margins prove insufficient.
- 10W-40:Legacy grade for older European and Latin American vehicle populations.
- 5W-20:Ford and Honda factory fill specification for mid-size passenger car platforms.
5W-30 retains the largest installed base, though 0W-20 is expanding most quickly.
End User:
Fleet procurement centralization and total-cost-of-ownership modeling reshape volume allocation across vehicle categories.
- Passenger Vehicles:Turbocharged direct-injection engine proliferation drives synthetic conversion from mineral baselines. Chinese, US, and German OEMs specify full synthetic for factory fill on new platforms.
- Commercial Vehicles:Class 3-6 delivery and utility fleets in the US and Germany specify synthetic blends under outcome-based performance contracts with guaranteed fuel economy improvement.
- Heavy-Duty Trucks:Class 8 operators transition from 15W-40 mineral to 5W-30 synthetic under extended drain economics.
- Motorcycles:Wet clutch compatibility requirements drive specialized JASO MA2 certified formulations.
Passenger Vehicles command the dominant volume position, while Heavy-Duty Trucks show the steepest conversion trajectory.
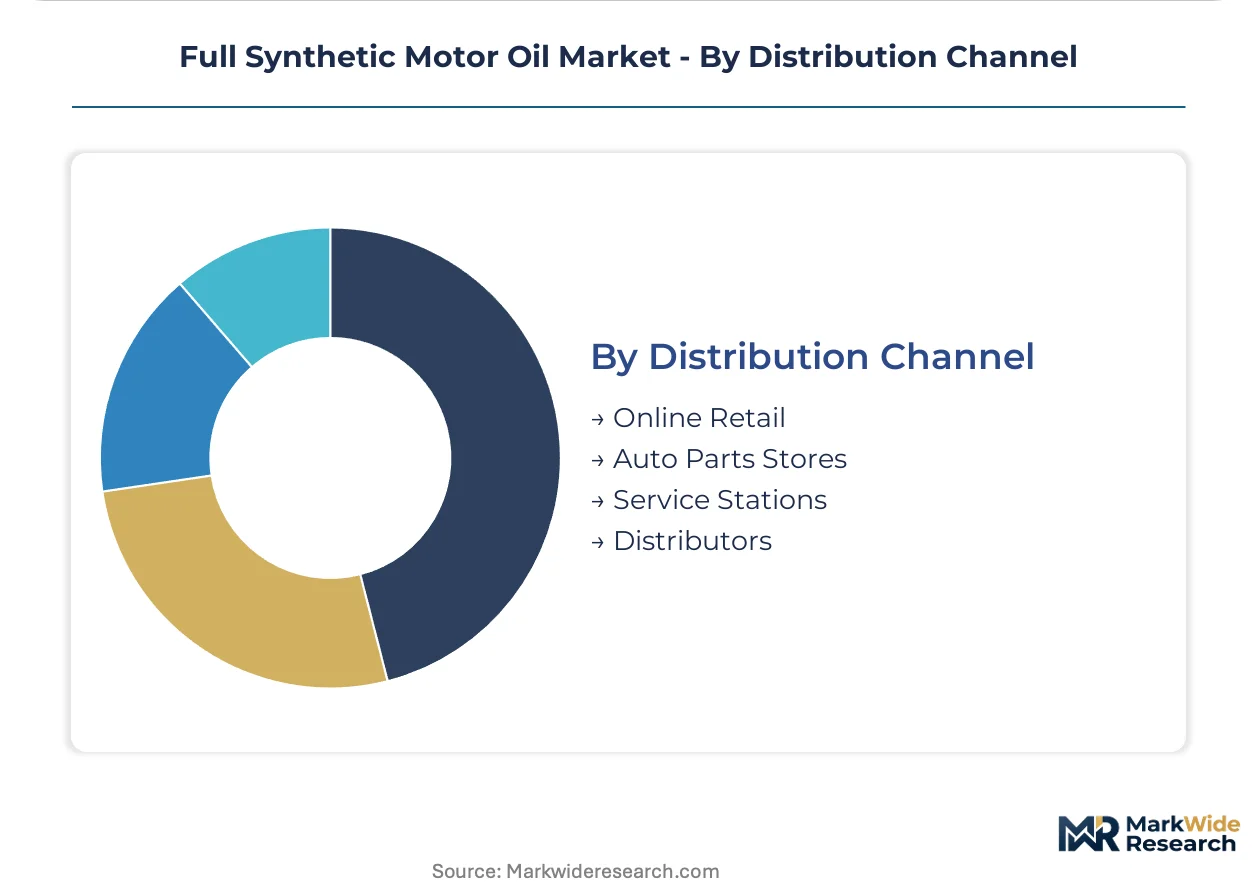
Distribution Channel:
Channel control determines pricing realization and customer data access for predictive replacement scheduling.
- Online Retail:Direct-to-consumer subscription models capture enthusiast segments with extended-drain formulations delivered on predictive schedules. This bypasses traditional quick-lube intermediaries and captures margin otherwise lost to service bay operators.
- Auto Parts Stores:Retail shelf space competition concentrates with brands holding DIY consumer recognition and volume rebate programs.
- Service Stations:Quick-lube channel dominance in North America rewards specialized service bay equipment and bulk supply contracts.
- Distributors:Independent jobbers serve secondary markets and rural service facilities with mixed-brand portfolios.
Service Stations retain the largest transaction volume, though Online Retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity for full synthetic motor oil varies sharply by geography. Fleet operators in Germany and the United States absorb premium pricing under total-cost-of-ownership contracts, while price-sensitive buyers in India and Brazil prioritize certified synthetics at entry-tier price points.
United States
Class 8 truck fleets specify 15,000-mile drain intervals as baseline, converting from mineral 15W-40 to synthetic 5W-30 under EPA-coordinated fuel economy mandates. The EPA coordinates with OEMs through ILSAC to align oil specifications with corporate average fuel economy standards. Houston-Gulf Coast refineries cluster captive base-oil production for integrated formulators serving North American aftermarket channels.
Germany
Volkswagen, BMW, and Mercedes-Benz factory fill positions require 18-24 month OEM-specific approval cycles for 508.00/509.00 and LL-17 FE+ certifications. The ECHA enforces REACH registration synchronization and SVHC candidate listing updates that force additive reformulation. The Ruhr industrial corridor hosts lubricant blending facilities supplying German OEM factory fill and European aftermarket distribution.
China
Domestic OEMs including SAIC, Geely, and BYD specify proprietary synthetic formulations tuned to local engine architectures and fuel quality profiles. The MIIT administers GB standards that diverge from legacy North American API specifications. The Yangtze River Delta concentration of automotive manufacturing drives demand for synthetic factory fill as domestic production scales.
India
Maruti Suzuki and Tata Motors factory fill contracts are unlocking to early movers certifying synthetic-equivalent performance under BIS lubricant standard upgrades. The Bureau of Indian Standards is phasing IS 13656:2002 specifications toward synthetic-equivalent tiers. The Gujarat industrial corridor hosts blending capacity expansion targeting domestic OEM supply and export positioning.
South Korea
Group III+ hydrocracked base oil supply concentrates in Ulsan and Yeosu refinery complexes, creating feedstock cost advantages for integrated formulators. The MFDS coordinates chemical substance registration parallel to REACH alignment for export market access. The Seoul Capital Area automotive cluster specifies synthetic factory fill for Hyundai-Kia platforms targeting European and North American export compliance.
Full Synthetic Motor Oil Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in full synthetic motor oil supply. Integrated refiners control captive base-oil production and additive blending, while independent formulators compete through channel specialization and enthusiast segment targeting. Two strategic archetypes dominate: backward-integrated petroleum majors with refinery-to-retail control, and independent blenders with quick-lube or direct-to-consumer channel dominance. Competitive moves concentrate on OEM approval timeline compression and subscription-based customer lock-in.
Within the integrated petroleum major tier, ExxonMobil Corporation and Shell plc exemplify backward-integrated positioning through captive base-oil production. Valvoline Inc. occupies a position within the independent blender archetype, competing through specialized service channel dominance. AMSOIL Inc. anchors the direct-to-consumer subscription segment, targeting enthusiast buyers with extended-drain formulations delivered on predictive replacement schedules.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| Shell plc |
| Chevron Corporation |
| TotalEnergies SE |
| Valvoline Inc. |
| Phillips 66 Company |
| AMSOIL Inc. |
| Castrol |
| Pennzoil |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts between integrated refiners and fleet operators lock in both Group III+ base oil supply access and price visibility across multi-year service intervals. These arrangements insulate blenders from spot market volatility in hydrocracked feedstocks while committing buyers to synthetic conversion volumes under total-cost-of-ownership frameworks.
Pricing Analysis
After-sales service revenue from extended-drain interval programs drives lifetime value for formulators serving fleet operators. Three-tier pricing structure across premium, standard, and economy levels separates OEM-certified factory fill formulations from API SP-certified aftermarket products and entry-tier synthetic blends. Cost compression in the standard tier is intensifying because Group III+ supply expansion from South Korean and Qatari refineries is eroding historical PAO premiums. Fleet procurement departments show the lowest price sensitivity due to fuel economy guarantee contracts, while independent quick-lube operators remain the most price-sensitive buyer segment.
Supply Chain Analysis
Inventory cycles for additive packages now stretch 12-16 weeks as formulators buffer against molybdenum dithiocarbamate supply disruptions from Chilean mining output. Base oil production concentrates in South Korea, Qatar, and the US Gulf Coast, where hydrocracking capacity expansion is outpacing blender demand growth. Finished lubricant formulation draws from poly-alpha-olefin, detergent polymer, and friction modifier chemistries that face ECHA SVHC screening risk under REACH updates. Distribution runs through captive refiner networks, independent jobber systems, and direct-to-consumer subscription platforms serving enthusiast segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market fragments across OEM-specific approval requirements, creating niche opportunities for specialized formulators as electrification eliminates commoditized mineral oil demand. Divergence between Chinese GB standards and legacy API specifications is spawning dedicated supply chains for domestic OEM factory fill.
For Market Incumbents: Secure Volkswagen 508.00/509.00 and BMW LL-17 FE+ certifications ahead of competing blenders to lock in German OEM factory fill positions. Defend margin structures by backward integration into Group III+ base oil production through offtake agreements with Ulsan and Yeosu refinery operators. Channel control through quick-lube bay equipment placement remains essential against direct-to-consumer subscription encroachment.
For New Entrants and Emerging Players: Lead with JASO MA2-certified motorcycle formulations targeting Southeast Asian wet-clutch compatibility requirements where incumbent presence remains thin. India's BIS synthetic-equivalent standard upgrade creates immediate certification arbitrage for early movers securing Maruti Suzuki and Tata Motors contracts. A direct-to-consumer subscription model bypassing traditional distributor markups captures enthusiast segments with predictive replacement scheduling.
For Investors and Strategic Acquirers: Capital is best deployed toward independent blenders holding quick-lube channel dominance in North American aftermarket service. Long-term viability hinges on formulation chemistry capabilities surviving electrification transition through adjacent thermal management fluid development. Monitor OEM electrification roadmap acceleration from Volkswagen, Stellantis, and General Motors as the primary volume inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| OEM-Specific Certification Investment | Volkswagen 508.00/509.00 approval unlocks German factory fill positions against commodity competitors. |
| Backward Integration into Base Oil Supply | Captive Group III+ production from Ulsan refineries insulates margin from hydrocracked feedstock volatility. |
| Direct-to-Consumer Channel Development | Subscription models bypass quick-lube intermediaries and capture enthusiast segment lifetime value. |
| PFAS-Free Formulation Transition | ECHA restrictions on fluorinated polymers force friction modifier chemistry redevelopment for EU market access. |
| Heavy-Duty Fleet Synthetic Conversion | Class 8 truck operators adopting 5W-30 synthetic under EPA fuel economy mandates expand addressable volume. |
Research Methodology
Desk research of customs trade data, API certification registries, and OEM factory fill specifications preceded structured interviews with lubricant formulation chemists, fleet procurement managers, quick-lube channel operators, and base oil refinery planners. Secondary validation drew from SEC 10-K filings of integrated petroleum majors, ECHA REACH substance databases, and MIIT GB standard documentation. Bottom-up volume modeling triangulated against top-down market sizing across the projection horizon.
Variance decomposition across viscosity grade, performance tier, and end-use segment shaped the analytical framework throughout the forecast period. CAGRs derived from segment-level volume trajectories weighted by regional production cluster intensity and OEM platform rollout schedules. Modeled inputs included turbocharged direct-injection engine penetration rates and electrification substitution curves by vehicle class.
The analysis sits within stated boundaries; outcomes outside sustained OEM drain interval extension or accelerated battery electric vehicle adoption would require recalibration. Forecasts reflect assumptions on additive chemistry cost trajectories and regulatory synchronization timelines. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Crank Trigger System Market
Automotive Parts
Automotive Oil and Air Filters Market
Automotive Parts
Automotive Intercooler Market
Automotive Parts
Diesel Common Rail Injection System Market
Automotive Parts
Global Motorcycle Carbon Ceramic Brake Rotors Market
Automotive Parts
Automotive Canister Purge Valve Market
Automotive Parts
Engine Piston Ring Set Market
Automotive Parts
Europe Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Coolant Market
Automotive Parts
Garage Body Shop Equipment Market
Automotive Parts
Saudi Arabia Vehicle Exhaust Hose Market
Automotive Parts
Industrial V Belt Market
Automotive Parts
Colombia Automotive Lubricants Market
Automotive Parts
Saudi Arabia Passenger Vehicles Lubricants Market
Automotive Parts
Passenger Car Wiper Blade Market
Automotive Parts
Camshaft Lifters Market