
 North America Road Freight Transportation Market | 2026-2036
North America Road Freight Transportation Market Size, Share, and Industry Trends Forecast 2026-2036
North America Road Freight Transportation Market Insights
The EPA Phase 3 greenhouse gas standards for heavy-duty vehicles is recalibrating fleet procurement priorities across North American carriers. United Parcel Service Inc. leverages its integrated network density to sustain last-mile economics while electrifying urban delivery routes. J B Hunt Transport Services Inc. anchors intermodal-road hybrid offerings that dominate cross-border freight between the United States and Mexico. FedEx Corp. differentiates through time-definite express infrastructure that controls premium segment access across the continent.
Road freight transportation encompasses the movement of goods via motor vehicles over public highway networks, utilizing power units ranging from Class 8 tractor trailers exceeding 33,000 pounds GVWR to light commercial delivery vans, with cargo secured in dry van, refrigerated, flatbed, or tank configurations depending on commodity requirements. The primary industrial purpose is to provide flexible, door-to-door logistics connectivity for supply chains where rail or air alternatives lack terminal density or cost efficiency. Full Truckload services command the largest revenue pool due to shipper preferences for dedicated capacity and reduced handling, while Refrigerated freight under Load Type captures expanding margin pools as temperature-sensitive pharmaceutical and fresh food volumes rise. Less Than Truckload competes on consolidation economics but faces structural pressure from e-commerce parcel networks that specialize in smaller shipment profiles.
The Federal Motor Carrier Safety Administration governs driver hours-of-service limits and electronic logging device mandates that constrain effective capacity and shape carrier hiring cycles across the United States. Transport Canada enforces comparable commercial vehicle operator registration and safety fitness standards that harmonize cross-border fleet compliance under the Canada-United States-Mexico Agreement framework. California Air Resources Board regulations on zero-emission medium- and heavy-duty vehicles are forcing early fleet turnover decisions for operators with exposure to the state's freight corridors. Stakeholders must monitor how divergent federal and state-level emissions timelines reshape capital deployment between diesel replacement cycles and electrification infrastructure commitments.
Market Dynamics
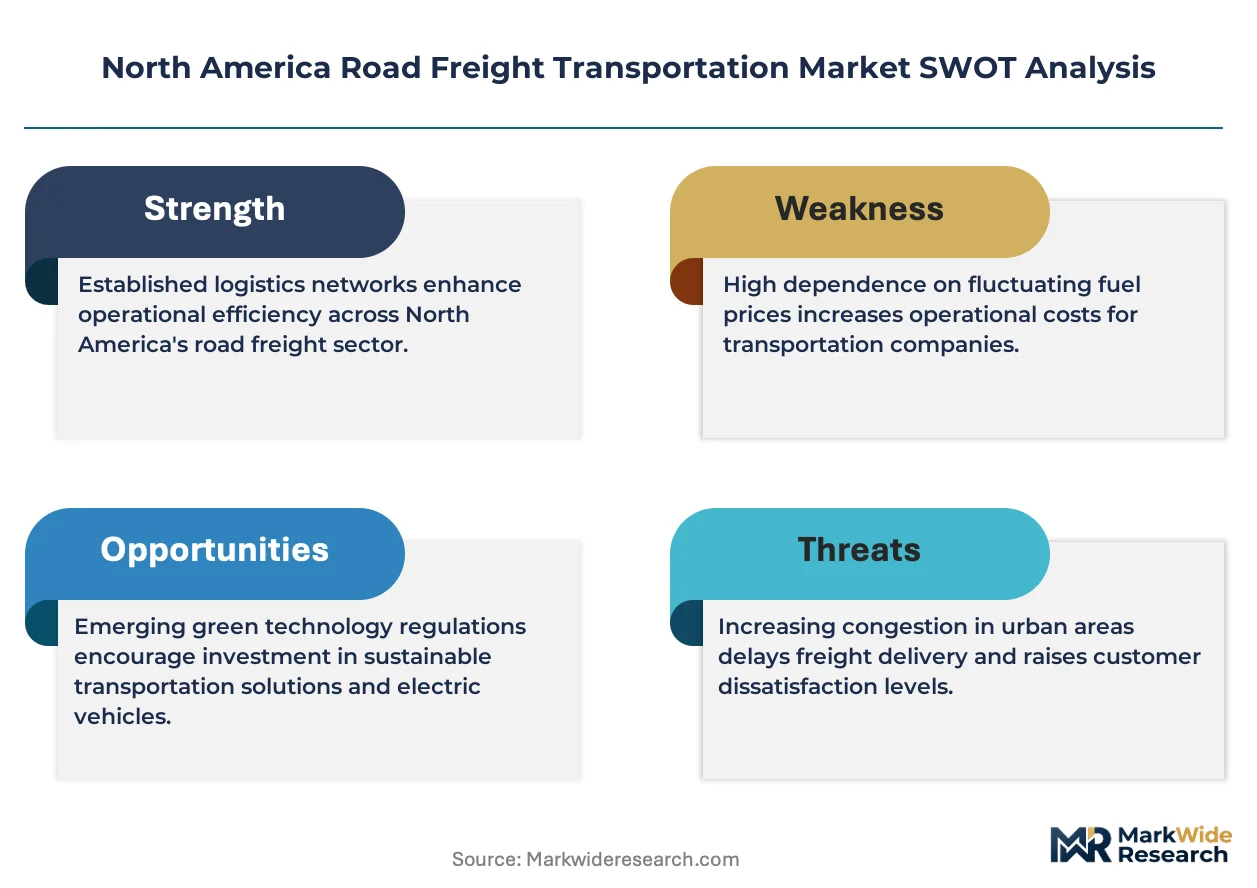
EPA Phase 3 greenhouse gas standards are forcing carriers across the United States, Canada, and Mexico to accelerate fleet turnover timelines while simultaneously managing electrification capital deployment against compressed diesel replacement cycles.
Growth Catalysts
- E-commerce fulfillment density:Refrigerated and dedicated freight services are expanding along the United States-Mexico-Canada corridor to serve temperature-sensitive pharmaceutical and fresh food distribution networks.
- Canada-United States-Mexico Agreement harmonization:Cross-border regulatory alignment is reducing customs friction and accelerating intermodal-road hybrid service deployment between Mexican manufacturing clusters and United States consumer markets.
- California Air Resources Board zero-emission mandates:Early fleet turnover requirements for medium- and heavy-duty vehicles operating in California freight corridors are stimulating charging infrastructure investment and electric tractor pre-orders.
Market Restraints
- Driver hours-of-service constraints:Federal Motor Carrier Safety Administration electronic logging device mandates limit effective capacity utilization and compress asset turns during peak shipping seasons.
- Battery supply concentration:Lithium-ion cell production for electric heavy-duty tractors concentrates in Asian manufacturing hubs, exposing North American carriers to raw material cost volatility and extended equipment delivery timelines.
- Intermodal substitution economics:Rail container services on the Texas-California corridor and Great Lakes manufacturing belt capture bulk commodity flows that erode full truckload rate premiums for non-time-sensitive cargo.
Strategic Opportunities
- Mexican nearshoring manufacturing expansion:Automotive and electronics production relocation from Asia to Monterrey and Guadalajara is generating dedicated cross-border fleet demand with long-term contract visibility.
- Pharmaceutical cold chain specialization:Temperature-controlled last-mile services for biologics and vaccines offer margin expansion potential as healthcare distribution networks regionalize inventory positioning.
- United States Inflation Reduction Act commercial vehicle credits:Federal tax incentives for zero-emission heavy-duty vehicle purchases are improving total cost of ownership calculations for fleet electrification programs.
Industry Challenges
- Technician skill scarcity:Maintenance networks lack sufficient trained personnel to service high-voltage electric drivetrains and advanced driver-assistance systems across dispersed terminal locations.
- Charging infrastructure capex intensity:Depot electrification requires substantial capital for megawatt-scale grid connections, on-site battery storage, and utility demand charge management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Road Freight Transportation Market |
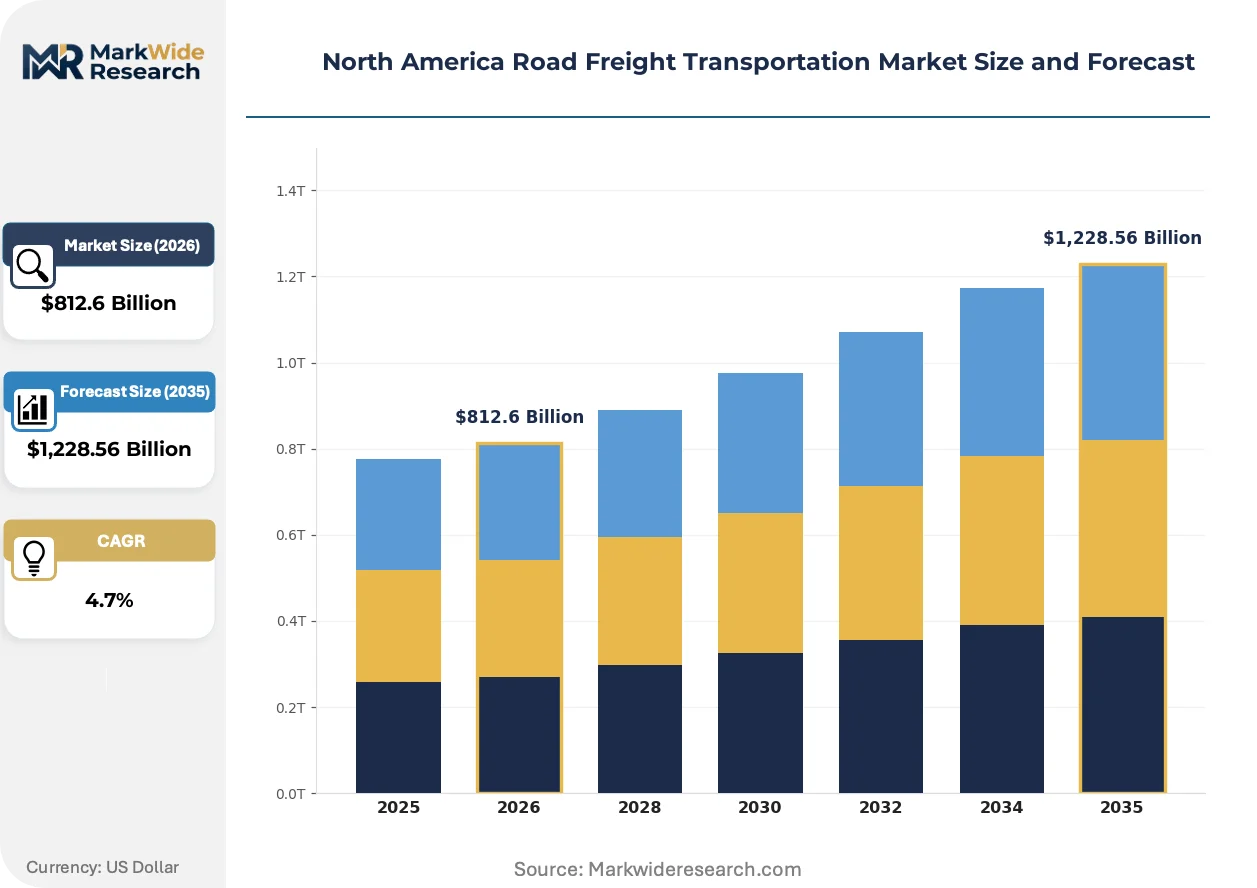
| Market Size in 2026 | $812.6 Billion |
| Market Size in 2035 | $1,228.56 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Full Truckload, Less Than Truckload, Dedicated Freight, Expedited Shipping Vehicle Type: Tractor Trailers, Box Trucks, Flatbed Trucks, Delivery Vans End User: Retail, Manufacturing, Food & Beverage, Construction Load Type: Dry Van, Refrigerated, Hazardous Materials, Bulk |
| Companies Covered | United Parcel Service Inc., FedEx Corp., XPO Inc., J B Hunt Transport Services Inc., Knight Swift Transportation Holdings Inc., Old Dominion Freight Line Inc., Schneider National Inc., Ryder System Inc., ArcBest Corp., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Road Freight Transportation Market Trends and Innovations
Telematics and predictive analytics platforms are restructuring how carriers optimize asset utilization, route planning, and maintenance scheduling across fragmented shipper networks. These digital layers are compressing information asymmetries that historically protected incumbent broker relationships.
Autonomous trucking software stacks are decentralizing long-haul freight planning away from human dispatcher networks toward algorithmic load matching and dynamic pricing engines. Large shippers in the retail and automotive sectors are piloting driver-out highway segments between Dallas and Houston, with autonomous middle-mile operations expanding to the Phoenix-Tucson corridor by asset-light technology providers. This decentralization is compressing spot market broker margins and forcing traditional dispatch operations toward exception-handling roles.
Transport Canada and the United States Environmental Protection Agency are converging on harmonized heavy-duty vehicle emissions testing protocols under the Canada-United States-Mexico Agreement framework. This regulatory alignment reduces certification burden for cross-border equipment operators and accelerates unified powertrain development cycles for engine manufacturers serving both markets. The harmonization most directly affects refrigerated fleet operators running transcontinental routes between Ontario and California.
Shippers are consolidating freight procurement onto digital freight matching platforms that disintermediate traditional asset-based carrier sales relationships. Food and beverage manufacturers in the Midwest are migrating from annual contract tenders to dynamic spot market participation with pre-qualified carrier pools, compressing pricing cycles from quarterly to weekly adjustments. This behavioral shift is most visible in the Chicago distribution hub, where refrigerated capacity now trades on platform-based auctions with real-time rate transparency.
North America Road Freight Transportation Market Segmentation
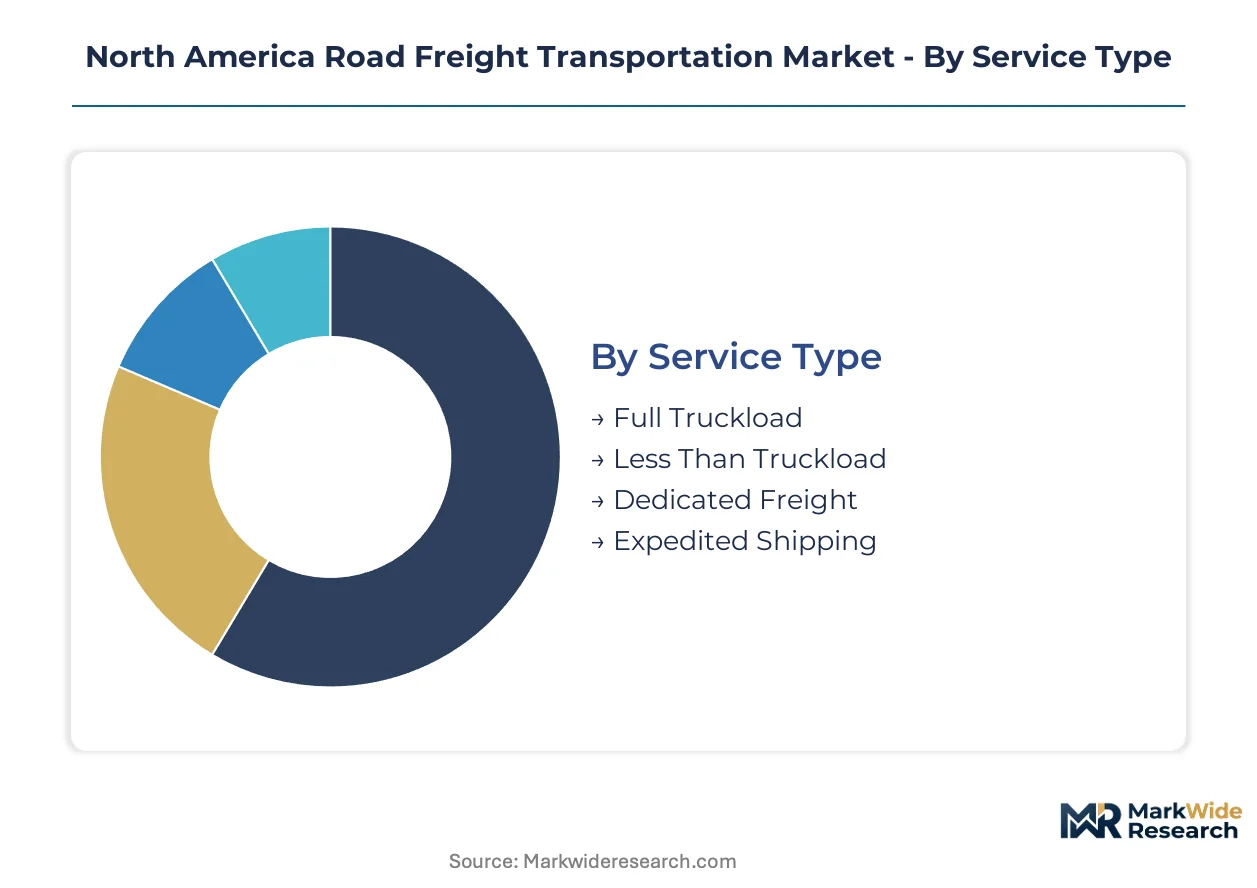
Road freight segmentation in North America reflects divergent capital intensity and regulatory exposure across service models. Carrier fleet strategies and shipper procurement patterns map directly to how these categories partition risk, margin, and compliance burden.
Service Type:
Full Truckload and Dedicated Freight require minimal incremental certification beyond standard operating authority, while Expedited Shipping triggers TSA Known Shipper protocols and Less Than Truckload demands hazmat handling endorsements for consolidated loads.
- Full Truckload:Dedicated tractor-trailer capacity moving single-shipper cargo from origin to destination without intermediate handling. Demand concentrates along the Texas-California corridor where automotive and energy shippers prioritize transit time reliability over rail economics.
- Less Than Truckload:Consolidated freight from multiple shippers loaded onto common equipment with hub-and-spoke terminal sorting. Volume clusters in Chicago and Dallas distribution hubs where e-commerce return logistics and mid-market manufacturers seek freight cost sharing.
- Dedicated Freight:Exclusive equipment and driver assignment under multi-year contracts with guaranteed capacity commitments. Food and beverage manufacturers in the Great Lakes belt contract dedicated refrigerated fleets to secure cold chain integrity.
- Expedited Shipping:Time-critical ground transport with team drivers or air-ride equipment for high-value, deadline-sensitive cargo. Aerospace suppliers in Wichita and medical device manufacturers in Minneapolis drive premium rate acceptance.
Full Truckload sits at the top of the volume ranking, with Dedicated Freight climbing the fastest as shippers trade spot market volatility for contract stability.
Vehicle Type:
Capital deployment and operating cost tiers separate these equipment categories, with tractor trailers commanding the highest per-unit investment and delivery vans offering the lowest barrier to fleet entry.
- Tractor Trailers:Class 8 power units exceeding 33,000 pounds GVWR paired with 53-foot dry van, refrigerated, or flatbed trailers. Long-haul carriers running the United States-Mexico-Canada corridor depend on sleeper-cab configurations for driver utilization efficiency.
- Box Trucks:Straight trucks with integrated cargo bodies typically ranging 16-26 feet in length. Regional distributors in California urban freight corridors deploy these for final-mile pallet deliveries where tractor-trailer maneuverability is constrained.
- Flatbed Trucks:Open-deck equipment with no fixed enclosure, secured by chains and tarps for oversized or irregular cargo. Steel and construction materials shippers in Houston and Pittsburgh specify flatbed for loading flexibility at mills and job sites.
- Delivery Vans:Light commercial vehicles under 10,000 pounds GVWR for parcel and small-package distribution. E-commerce fulfillment networks in Phoenix and Atlanta scale electric van deployments to satisfy California Air Resources Board zero-emission mandates.
Tractor Trailers generate the highest revenue per asset, though Delivery Vans are expanding most quickly as last-mile electrification accelerates fleet turnover.
End User:
Shipper industry concentration determines lane density and rate negotiation leverage, with retail and food and beverage offering the most predictable demand profiles.
- Retail:Big-box and e-commerce distribution requiring high-velocity replenishment of regional fulfillment centers. Seasonal surge patterns around port gateways in Los Angeles and Savannah strain capacity availability.
- Manufacturing:Just-in-time component delivery and finished goods distribution for automotive, electronics, and industrial equipment. Mexican maquiladora operations in Monterrey generate dedicated cross-border lanes to Texas and Michigan assembly plants.
- Food & Beverage:Temperature-controlled and dry supply chain management from production through retail shelf. Refrigerated carriers serving California Central Valley agriculture and Midwest protein processing face strict FDA Food Safety Modernization Act compliance.
- Construction:Project-based freight for building materials, heavy equipment, and aggregate movement. Infrastructure spending in Texas and Florida drives flatbed and specialized heavy-haul demand with volatile seasonal patterns.
Retail commands the largest freight spend, with Food & Beverage gaining share fastest as cold chain regionalization intensifies.
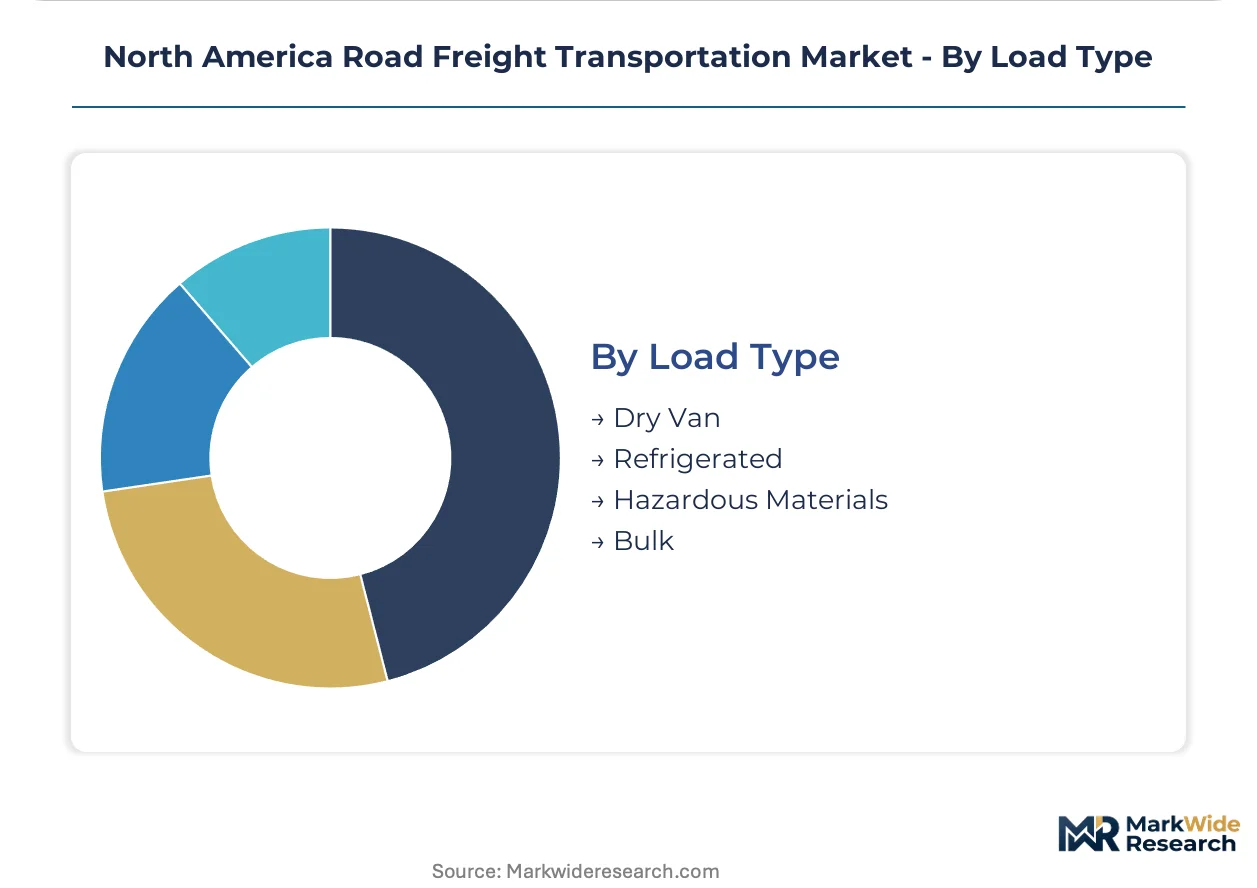
Load Type:
Hazardous materials and refrigerated shipments impose specialized equipment and driver certification requirements that limit carrier pool availability and sustain rate premiums.
- Dry Van:Enclosed box trailers for non-temperature-sensitive general freight representing the baseline equipment configuration. Consumer packaged goods manufacturers in Ohio and Pennsylvania move the majority of dry van volume through Chicago and Atlanta hubs.
- Refrigerated:Insulated trailers with integrated refrigeration units maintaining precise temperature bands for perishables and pharmaceuticals. Biologics distribution networks are expanding temperature-validated capacity between Indianapolis and Miami.
- Hazardous Materials:Tank trailers and specialized van equipment for chemicals, fuels, and regulated substances requiring placarding. EPA and Transport Canada dangerous goods regulations restrict driver eligibility and routing options.
- Bulk:Open-hopper or pneumatic tank equipment for unpackaged commodities including grain, minerals, and liquids. Agricultural shippers in Iowa and Kansas depend on bulk trucking for elevator-to-port movements.
Dry Van leads by shipment count, with Refrigerated expanding most steeply as pharmaceutical cold chain requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North American road freight industry traces its modern scale to the post-Interstate Highway System era of the 1950s-1960s, when the United States built the backbone infrastructure that enabled long-haul trucking to displace rail for time-sensitive cargo. This foundation expanded through the Canada-United States Free Trade Agreement and NAFTA, embedding cross-border trucking into continental supply chains.
United States
Texas-California freight lanes and the Great Lakes manufacturing belt generate the highest truckload volumes, driven by automotive assembly plants and energy sector equipment movements. EPA Phase 3 greenhouse gas standards are accelerating fleet electrification investments among carriers operating in California freight corridors. The Los Angeles-Long Beach port complex anchors transcontinental drayage networks that feed inland distribution hubs in Phoenix and Dallas.
Canada
Ontario's automotive manufacturing cluster in Windsor-Toronto generates dedicated cross-border lanes to Michigan and Ohio assembly plants. Transport Canada harmonizes commercial vehicle safety fitness standards with the United States under the Canada-United States-Mexico Agreement framework. The Highway 401 corridor between Toronto and Montreal carries the densest freight traffic concentration in the country.
Mexico
Monterrey and Guadalajara manufacturing clusters are expanding dedicated fleet demand as automotive and electronics production relocates from Asia. Mexican federal trucking regulations align with cross-border safety protocols under the Canada-United States-Mexico Agreement. The Nuevo León-Texas border crossing at Laredo processes the highest commercial truck volume between the two countries.
North America Road Freight Transportation Market Competitive Landscape
Capital-heavy asset-based carriers compete with asset-light freight brokers and digital matching platforms for control of shipper relationships. The market structure concentrates around integrated parcel networks, intermodal-road hybrids, and specialized trucking operators with distinct equipment configurations. Three archetypes dominate: integrated express carriers with last-mile density, asset-based truckload specialists with dedicated contract portfolios, and technology-enabled brokers with algorithmic pricing engines. Competitive dynamics center on electrification infrastructure partnerships and cross-border service integration under harmonized regulatory frameworks.
Within the integrated express tier, United Parcel Service Inc. and FedEx Corp. occupy positions defined by continental network density and time-definite service capabilities. J B Hunt Transport Services Inc. anchors the intermodal-road hybrid archetype, exemplifying carriers that leverage rail partnerships for long-haul economics while retaining trucking flexibility for first and final miles. These three entities represent distinct strategic postures: parcel integration, express premium positioning, and intermodal optimization.
| Leading Market Players |
|---|
| United Parcel Service Inc. |
| FedEx Corp. |
| XPO Inc. |
| J B Hunt Transport Services Inc. |
| Knight Swift Transportation Holdings Inc. |
| Old Dominion Freight Line Inc. |
| Schneider National Inc. |
| Ryder System Inc. |
| ArcBest Corp. |
| Others |
Pricing and Supply Chain Analysis
Captive fleet ownership among Tier 1 asset-based carriers anchors both supply security and rate-setting leverage across the United States-Mexico-Canada corridor. This vertical integration insulates dedicated contract pricing from spot market volatility while exposing operators to concentrated equipment procurement cycles and driver wage inflation.
Pricing Analysis
Contract-based long-term offtage dominates pricing structures across full truckload and dedicated segments, with premium-mid-economy pricing differentiation separating guaranteed capacity commitments from transactional spot purchases. Price differentiation hinges on equipment specialization—refrigerated and hazmat-certified fleets command sustained premiums—and geographic delivery cost differentials across California Air Resources Board-regulated corridors versus unrestricted interstate lanes. Cost compression in standard dry van services is intensifying because digital freight platforms compress broker margins and accelerate rate transparency. Small and mid-market shippers exhibit highest price sensitivity, while pharmaceutical and aerospace manufacturers accept premium rates for temperature-validated and expedited services.
Supply Chain Analysis
Diesel engine and electric drivetrain supply rests on concentrated manufacturing footprints in the United States, Mexico, and Germany, with lithium-ion cell production drawing from South Korean and Chinese chemical processing networks. Critical component dependencies span semiconductor chips for telematics and advanced driver-assistance systems, high-strength steel for trailer fabrication, and specialized refrigerants for temperature-controlled units. Single-source vulnerability in battery cell supply exposes North American carriers to raw material cost volatility and extended equipment delivery timelines. Distribution runs through original equipment manufacturer dealer networks and direct fleet sales channels, with aftermarket parts flowing through regional parts distributors and captive service centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America road freight transportation market functions as a regulatory compounder where EPA Phase 3 greenhouse gas standards and California Air Resources Board zero-emission mandates are restructuring capital deployment priorities and accelerating fleet turnover timelines.
For Market Incumbents: Anchor intermodal-road hybrid service density along the Texas-California corridor to defend against rail substitution economics and autonomous trucking displacement. Deepen vertical integration into charging infrastructure partnerships and electric vehicle service technician training networks to secure first-mover positioning under compressed diesel replacement cycles. Lock in multi-year dedicated contracts with food and beverage manufacturers in the Great Lakes belt to insulate revenue from spot market volatility. For New Entrants and Emerging Players: Autonomous trucking software licensing offers a technology-first wedge into long-haul freight planning between Dallas and Houston, where pilot programs already operate driver-out highway segments. Target pharmaceutical cold chain specialization as the most penetrable segment, leveraging temperature-validated last-mile services for biologics distribution between Indianapolis and Miami. Pursue asset-light partnership models with established carriers rather than competing for tractor-trailer fleet capital. For Investors and Strategic Acquirers: Roll-up economics work for regional refrigerated carriers because FDA Food Safety Modernization Act compliance requirements and specialized equipment certification create barriers that favor scale players with consolidated maintenance networks. Focus acquisition screening on dedicated contract portfolios with food and beverage exposure and cross-border Mexico-United States lane density. Monitor electric tractor pre-order backlogs and megawatt-scale charging infrastructure deployment timelines as the signal to watch for fleet electrification inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Fleet Conversion Program | EPA Phase 3 compliance secures California corridor access and unlocks IRA commercial vehicle tax credits. |
| Cross-Border Customs Technology Partnership | Canada-United States-Mexico Agreement harmonization reduces dwell time at Laredo and accelerates intermodal-road hybrid deployment. |
| Refrigerated Capacity Expansion | Biologics distribution networks between Indianapolis and Miami demand temperature-validated pharmaceutical cold chain infrastructure. |
| Autonomous Trucking Pilot Expansion | Driver-out highway segments on Dallas-Houston and Phoenix-Tucson corridors compress labor cost exposure and extend asset utilization. |
| Technician Training Network Buildout | High-voltage electric drivetrain service capability addresses critical maintenance skill scarcity across dispersed terminal locations. |
Research Methodology
Bottom-up freight volume modeling reconciled against top-down carrier capacity tracking forms the analytical core of this study. Primary interviews with fleet operations directors, shipper procurement managers, intermodal rail partnership leads, and commercial vehicle dealership principals combine with secondary validation from FMCSA carrier census data, Transport Canada commercial vehicle registration records, EPA emissions certification filings, and customs trade flow databases. Triangulation across these sources ensures segmentation integrity across service type, vehicle configuration, and end-use industry dimensions.
Historical trendline analysis of truckload rate indices, fuel cost pass-through coefficients, and equipment order backlogs informs the projection framework. Segmentation dimensions modeled span service type, vehicle class, end-use industry, load configuration, and regulatory exposure cluster. CAGRs derive from equipment replacement cycle analysis, e-commerce fulfillment network expansion trajectories, and cross-border manufacturing relocation patterns. Forecast inputs incorporate driver hours-of-service constraint impacts, battery supply chain lead times, and charging infrastructure deployment schedules.
The model holds under sustained regulatory enforcement of EPA Phase 3 and California Air Resources Board mandates; deviation in federal-state emissions timeline alignment or lithium raw material supply disruption would shift fleet turnover assumptions. A small set of named triggers—autonomous trucking regulatory approval velocity, Mexico nearshoring manufacturing contract visibility, and electric vehicle total cost of ownership crossover timing—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
Reverse Logistics Market
Transportation & Logistics
Europe Cross Border Road Freight Transport Market
Transportation & Logistics
Parcel Delivery Market
Transportation & Logistics
Indonesia Refrigerated Trailer Market
Transportation & Logistics
Malaysia Domestic CEP Market
Transportation & Logistics
India Direct-To-Consumer (D2C) Logistics Market
Transportation & Logistics
Germany Cold Chain Logistics Market
Transportation & Logistics
Global Automotive 3PL Market
Transportation & Logistics
Romania Road Freight Transport Market
Transportation & Logistics
Poland Road Freight Transport Market
Transportation & Logistics
GCC International Express Service Market
Transportation & Logistics
Europe Refrigerated Transport Market
Transportation & Logistics
United States less than-Truck-Load (LTL) Market
Transportation & Logistics
Spain Cold Chain Logistics Market
Transportation & Logistics
ASEAN Road Freight Transport Market
Transportation & Logistics
Europe Customs Brokerage Market